
 Mexico Smart TV Market | 2026-2036
Mexico Smart TV Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Smart TV Market Intelligence
Federal Telecommunications Institute (IFT) spectrum reallocation is recalibrating the cost-of-entry calculus for manufacturers without digital-ready product portfolios. Samsung Electronics Co Ltd leverages its Tizen ecosystem to sustain premium positioning in Mexico City and Guadalajara retail channels. LG Electronics Inc anchors mid-tier volume through WebOS-integrated sets distributed via Elektra and Liverpool store networks. Hisense Home Appliances Group Co Ltd competes aggressively on price in the 32-inch and 43-inch segments through Coppel and Walmart Mexico placements.
A Smart TV integrates internet connectivity, streaming application support, and digital broadcast reception into a flat-panel display unit, typically employing LED-backlit LCD or self-emissive OLED panels with 4K resolution as the baseline specification for new Mexican retail stock. The device serves primary commercial purposes in residential living rooms, hotel guest accommodations, and corporate meeting environments where over-the-top content delivery replaces traditional cable distribution. LED product type occupies the dominant volume position due to manufacturing scale and price accessibility for Mexican middle-income households. Android TV technology leads platform share among value-oriented brands, while WebOS and Tizen concentrate in premium tiers where interface responsiveness and app ecosystem breadth command higher retail prices.
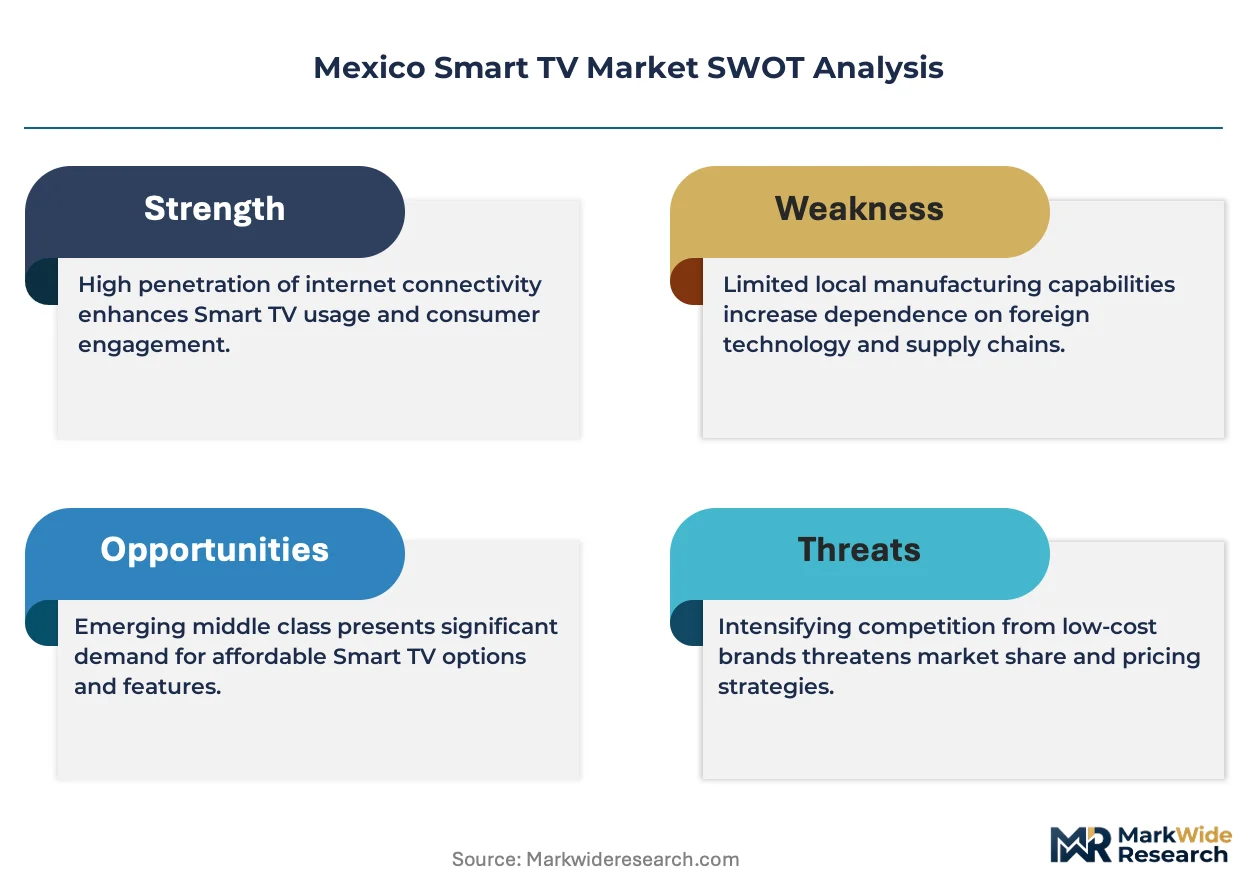
IFT digital television standards, NOM-001-SCFI electrical safety certifications, and PROFECO consumer protection mandates collectively shape product compliance burdens and warranty obligations for importers and domestic assemblers. NOM energy efficiency labeling requirements from CONUEE are tightening standby power thresholds, forcing chipset and power supply redesigns across the supplier base. Stakeholders must monitor forthcoming IFT 5G spectrum auctions and their implications for broadcast-to-broadband convergence features in next-generation set designs.
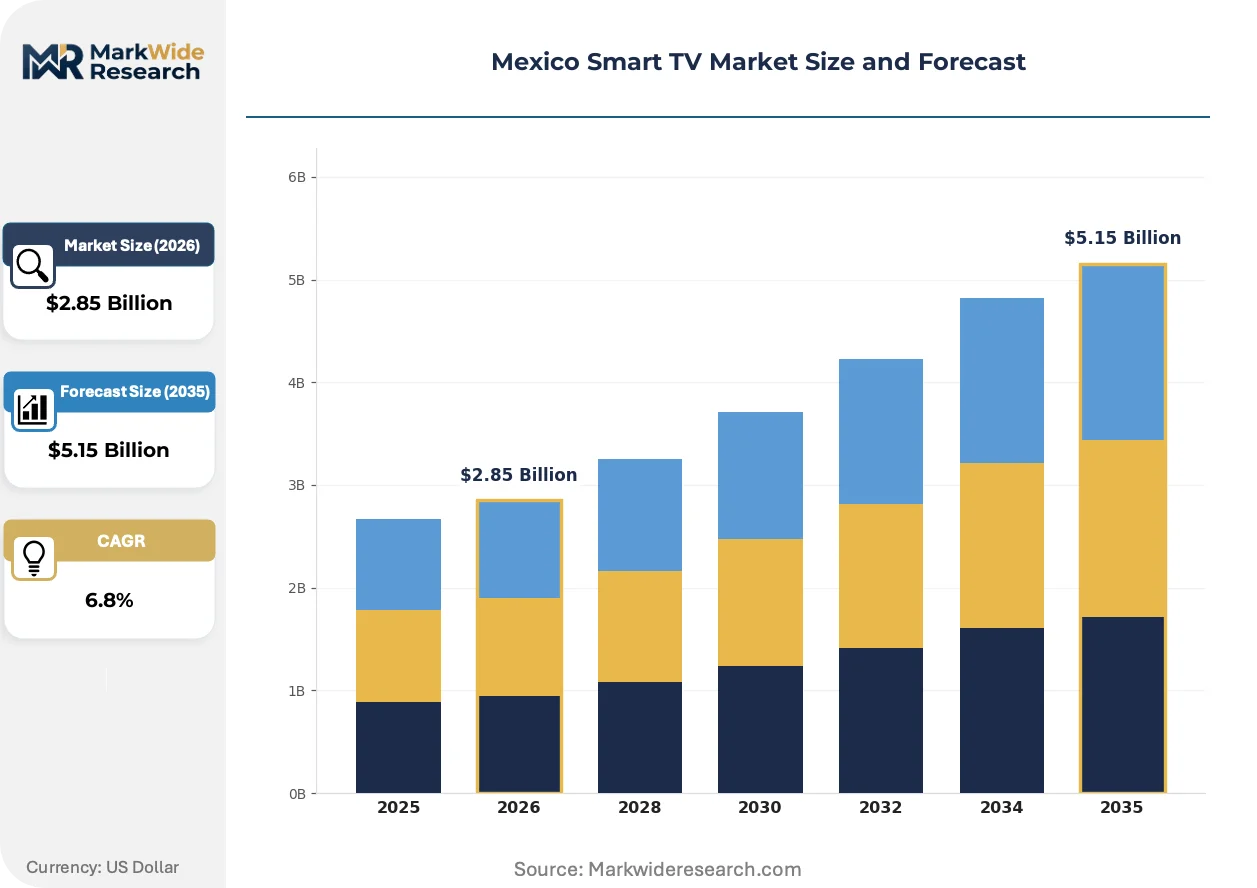
Market Dynamics
Federal Telecommunications Institute spectrum reallocation is compressing analog-to-digital transition timelines, forcing manufacturers to accelerate digital-ready portfolio overhauls while hospitality chains in Cancún and Mexico City compress replacement cycles for in-room entertainment systems.
Growth Catalysts
- NOM Energy Efficiency Mandates:CONUEE standby power thresholds are forcing chipset and power supply redesigns that favor newer, more efficient Smart TV architectures over legacy inventory.
- Hospitality Sector Modernization:Hotel chains in Cancún and Mexico City are accelerating in-room entertainment replacement cycles, creating concentrated demand for commercial-grade Smart TV deployments.
- Bajío Manufacturing Corridor Scale:Assembly plants in Guanajuato and Querétaro serve both domestic retail and North American export channels, generating procurement volume efficiencies for component suppliers.
Market Restraints
- Panel Input Cost Volatility:LCD glass substrate and driver IC pricing fluctuates with semiconductor foundry capacity constraints in East Asia, compressing assembler margins.
- Import Concentration Risk:Mexico relies on concentrated display panel supply from Korean and Chinese manufacturers, exposing assemblers to shipping cost spikes and currency mismatches.
- Substitution from Streaming Devices:Low-cost HDMI dongles and set-top boxes extend the functional life of non-smart displays, delaying replacement demand in price-sensitive households.
Strategic Opportunities
- Southeastern Tourism Corridors:Riviera Maya and Los Cabos hospitality developments are underpenetrated for premium in-room entertainment relative to Cancún and Mexico City saturation.
- 5G-Broadcast Convergence:Forthcoming IFT 5G spectrum auctions enable hybrid broadcast-broadband service models that differentiate next-generation set designs from WiFi-only competitors.
- Direct-to-Installer Channels:Commercial integrators serving corporate meeting environments represent an emerging bypass of traditional retail distribution for enterprise-grade deployments.
Industry Challenges
- Embedded Software Talent Scarcity:Android TV and WebOS customization for Mexican market requirements demands firmware engineering capabilities concentrated in Mexico City and Guadalajara, creating hiring bottlenecks for Bajío assemblers.
- NOM-001-SCFI Certification Timelines:Electrical safety testing backlog at approved laboratories extends product launch windows, compressing selling seasons for seasonal retail cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Smart TV Market |
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $5.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OLED, QLED, LED, LCD Technology: Android TV, WebOS, Tizen, Roku Screen Size: 32-Inch, 43-Inch, 55-Inch, 65-Inch Connectivity: Wi-Fi, Ethernet, Bluetooth, USB |
| Companies Covered | Hisense Home Appliances Group Co Ltd, Koninklijke Philips NV, Samsung Electronics Co Ltd, Haier Smart Home Co Ltd, Panasonic Holdings Corp, LG Electronics Inc, TCL Technology, Sharp Corporation, Sony Group Corp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Smart TV Market Strategic Shifts & Innovations
Display architecture and content delivery models are fragmenting across price tiers, with modular hardware designs and regulatory energy mandates forcing divergent technical roadmaps for premium versus value-positioned product lines.
System-on-chip architecture is modularizing across Mexican assembler portfolios. MediaTek and Amlogic reference designs now separate processing, connectivity, and tuner subsystems into swappable board configurations. Bajío manufacturing plants are adopting these platforms to serve multiple retail channels from common chassis tooling. This modularity is compressing SKU proliferation costs while enabling rapid regional feature customization for Coppel versus Liverpool retail placements.
IFT digital television standards implementation is tightening interoperability requirements for integrated tuners. The regulator's compressed transition timeline forces importers to certify dual-standard ATSC/ISDB-T reception capabilities ahead of analog switch-off deadlines. Mid-tier volume players distributing through Elektra networks face the steepest compliance cost escalation, accelerating consolidation toward assemblers with captive certification resources.
Commercial procurement patterns are fragmenting across hospitality verticals. Boutique properties in Mexico City's Roma and Condesa districts specify aesthetic-integrated displays with custom framing, displacing standardized black-bezel bulk purchases. Procurement teams at these properties negotiate directly with LG and Samsung commercial divisions, bypassing traditional electronics distributors. This channel compression is most visible in the Distrito Federal luxury accommodation segment, where design differentiation commands premium positioning.
Mexico Smart TV Market Segmentation
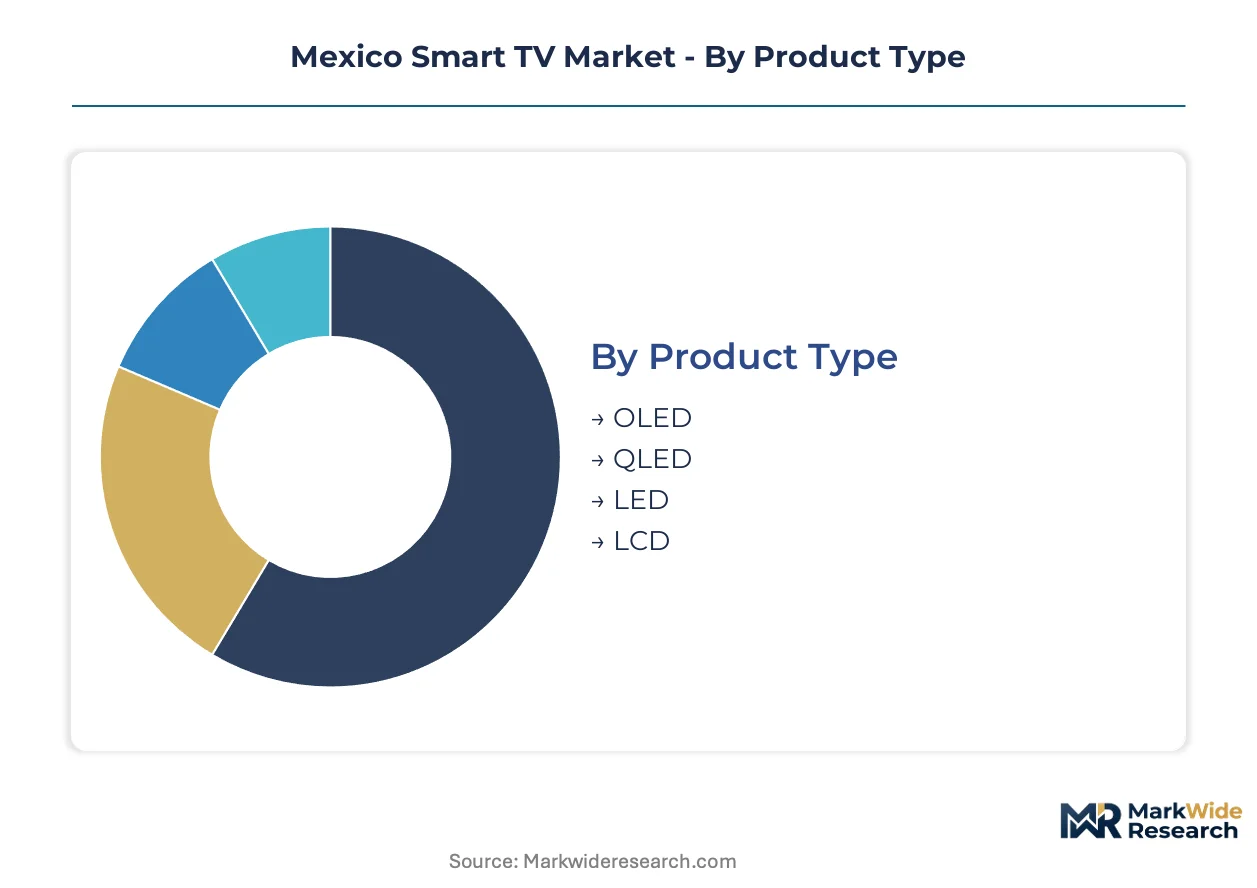
Mexico's Smart TV market fragments across technical specifications that align with distinct household income tiers and commercial deployment contexts. Procurement patterns in the Bajío manufacturing corridor and hospitality clusters in Cancún demonstrate how segment selection directly correlates with end-use requirements and NOM compliance burdens.
Product Type:
Panel technology selection dominates buyer calculus, with purchase decisions anchored to brightness requirements, viewing environment constraints, and energy efficiency mandates from CONUEE.
- LED:Backlit LCD architecture employing edge-lit or direct-lit LED arrays delivers the luminance stability required for high-ambient Mexican residential environments. Bajío assembly plants prioritize LED SKUs for Coppel and Walmart Mexico channels where price accessibility governs volume procurement.
- LCD:Legacy cold-cathode and basic LED-backlit configurations persist in commercial hospitality bulk purchasing where replacement cycle compression favors lowest acquisition cost over premium display performance.
- QLED:Quantum dot-enhanced LED systems from Samsung leverage Tizen integration for premium positioning in Mexico City and Guadalajara retail channels.
- OLED:Self-emissive pixel architecture eliminates backlight layers, enabling the thin profiles and infinite contrast ratios specified by luxury hotel properties in Polanco and Santa Fe districts.
LED leads on scale; OLED leads on momentum in the Distrito Federal luxury accommodation segment.
Technology:
Operating platform selection determines app ecosystem breadth, interface responsiveness, and firmware customization requirements for Mexican market compliance.
- Android TV:Google's open-source foundation enables rapid OEM customization for value-tier brands distributing through Elektra networks, though embedded software talent scarcity in Bajío assemblers constrains differentiation.
- WebOS:LG's proprietary stack anchors mid-tier volume through Liverpool store placements, with streamlined navigation commanding retail price premiums over Android TV equivalents.
- Tizen:Samsung's closed ecosystem sustains premium positioning through proprietary app curation and hardware-software optimization.
- Roku:Lightweight OS architecture reduces memory and processing requirements, enabling competitive positioning in 32-inch entry-level segments.
Android TV dominates unit volume; WebOS captures margin concentration in multi-brand retail environments.
Screen Size:
Display diagonal selection correlates with household living room dimensions, mounting infrastructure, and streaming content consumption intensity.
- 43-Inch:The dimensional sweet spot for Mexican middle-income apartment layouts, balancing immersive viewing with furniture integration constraints in Guadalajara and Monterrey residential developments.
- 55-Inch:Emerging baseline for new household formation in Mexico City condominiums, where over-the-top content consumption justifies larger display investment.
- 32-Inch:Kitchen and secondary bedroom deployments, plus hospitality standardization for limited-service properties in Cancún's hotel zone.
- 65-Inch:Premium residential and corporate meeting environment specifications, concentrated in Polanco, Santa Fe, and San Pedro Garza García high-income districts.
43-Inch leads on scale; 55-Inch climbs the fastest as 4K content availability expands.
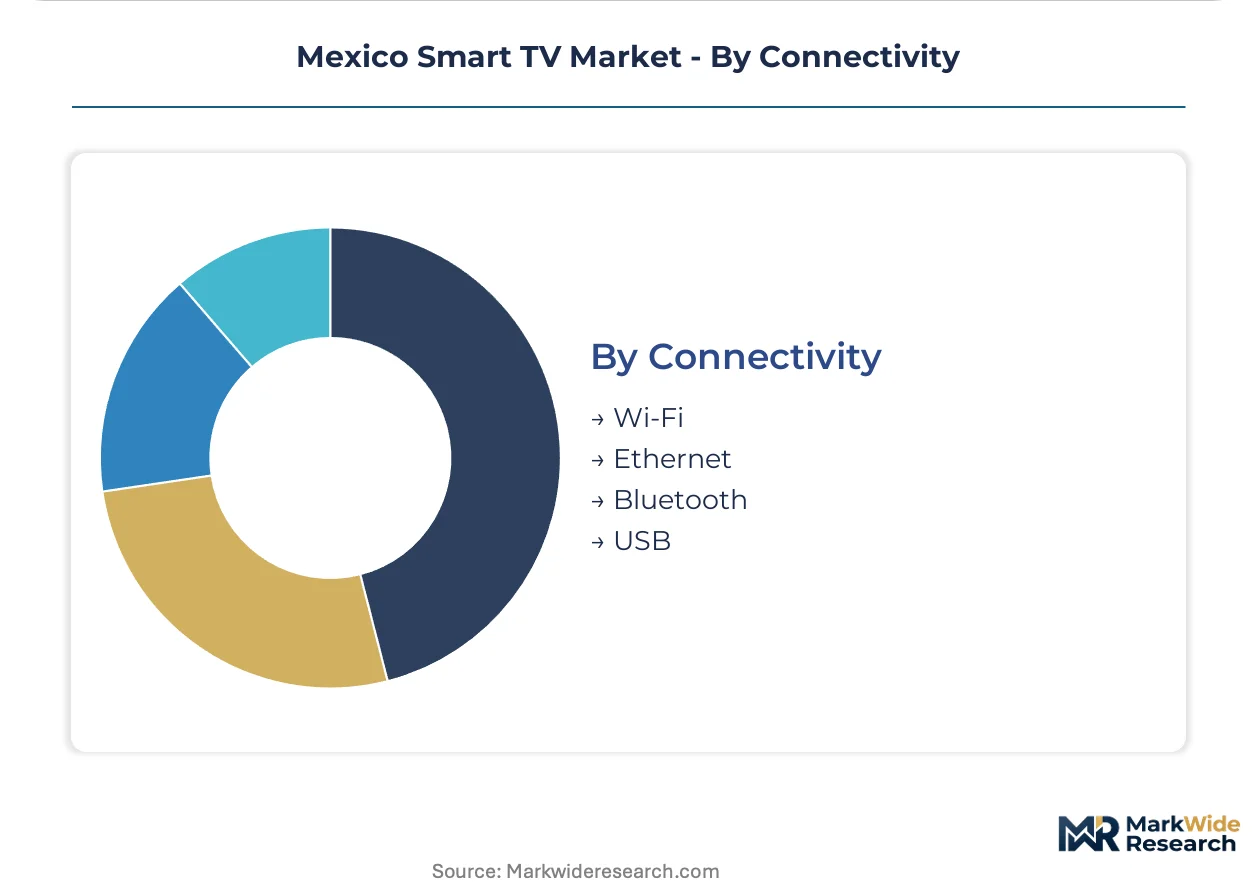
Connectivity:
Interface configuration determines network reliability, peripheral integration, and future-proofing against IFT 5G spectrum auction outcomes.
- Wi-Fi:Dual-band 802.11ac and Wi-Fi 6 implementations dominate residential installations where Ethernet infrastructure is absent, though congestion in multi-dwelling units creates reliability constraints.
- Ethernet:Wired connectivity anchors commercial hospitality deployments in Cancún and Mexico City where guaranteed bandwidth for in-room streaming services is contractually mandated.
- Bluetooth:Peripheral pairing capability for soundbars and wireless headphones, increasingly standard across all price tiers.
- USB:Media playback and firmware update interface, with USB 3.0 differentiation emerging in premium tiers.
Wi-Fi leads on scale; Ethernet leads on reliability premiums in commercial procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded software engineers cluster in Mexico City and Guadalajara, creating talent scarcity for Bajío assemblers seeking Android TV and WebOS customization capabilities.
Mexico City Metro
Luxury hospitality developments in Polanco and Santa Fe drive premium OLED procurement for aesthetic-integrated guest room displays. IFT spectrum reallocation mandates accelerate digital-ready tuner certification timelines for importers serving this corridor. Samsung and LG commercial divisions negotiate directly with boutique properties in Roma and Condesa, bypassing traditional electronics distributors.
Bajío Region
Guanajuato and Querétaro assembly plants generate procurement volume efficiencies for component suppliers serving both domestic retail and North American export channels. CONUEE NOM energy efficiency labeling requirements tighten standby power thresholds, forcing chipset and power supply redesigns across the supplier base. System-on-chip modularization from MediaTek and Amlogic enables rapid regional feature customization for Coppel versus Liverpool retail placements.
Jalisco
Guadalajara's middle-income residential developments concentrate 43-inch LED demand as the dimensional sweet spot for apartment living room layouts. PROFECO consumer protection mandates shape warranty obligations for importers distributing through Elektra and Walmart Mexico channels. The metropolitan area anchors WebOS-integrated set distribution for mid-tier volume through Liverpool store networks.
Nuevo León
San Pedro Garza García high-income districts specify 65-inch displays for premium residential and corporate meeting environments. NOM-001-SCFI electrical safety certification backlogs at approved laboratories extend product launch windows for seasonal retail cycles. Monterrey's industrial base supports direct-to-installer channels serving enterprise-grade commercial integrators.
Yucatán Peninsula
Riviera Maya hospitality developments remain underpenetrated for premium in-room entertainment relative to Cancún saturation. Hotel chains in Cancún's hotel zone compress replacement cycles for in-room entertainment systems, creating concentrated demand for commercial-grade deployments. The region's limited-service properties standardize on 32-inch displays for cost-optimized bulk purchasing.
Mexico Smart TV Market Key Industry Players
The competitive structure tilts toward diversified electronics conglomerates with captive display panel supply and proprietary operating system ecosystems. Korean and Chinese manufacturing groups anchor volume positions through scale economies in component procurement. Three archetypes dominate: integrated platform owners with semiconductor fabrication capabilities, brand licensors leveraging third-party ODM assembly, and retail-private-label specialists optimizing for channel-specific price positioning. Competitive moves concentrate on firmware ecosystem lock-in and certification resource capture.
Within the integrated platform tier, Samsung Electronics Co Ltd and LG Electronics Inc exemplify closed-ecosystem positioning through Tizen and WebOS respectively. Hisense Home Appliances Group Co Ltd represents the value-tier archetype competing aggressively on price in entry-level screen sizes through mass retail channel placements. These three anchors illustrate how divergent technical roadmaps for premium versus value-positioned product lines fragment competitive dynamics across Mexican retail and commercial procurement segments.
| Leading Market Players |
|---|
| Hisense Home Appliances Group Co Ltd |
| Koninklijke Philips NV |
| Samsung Electronics Co Ltd |
| Haier Smart Home Co Ltd |
| Panasonic Holdings Corp |
| LG Electronics Inc |
| TCL Technology |
| Sharp Corporation |
| Sony Group Corp |
| Others |
Cost & Logistics Intelligence
LCD glass substrate pricing volatility cascades through Mexican assembler margins into three distinct retail pricing tiers, with CONUEE energy efficiency mandates layering compliance premiums atop component cost fluctuations.
Pricing Analysis
Platform-bundled content licensing versus unbundled hardware-only procurement splits the market into divergent margin structures. Three-tier pricing structure across premium, standard, and economy levels stratifies by operating system ecosystem and panel architecture, with Tizen and WebOS commanding retail premiums over Android TV equivalents. Cost compression in the 32-inch economy tier is intensifying because HDMI dongle substitution extends legacy display lifecycles. Coppel and Walmart Mexico channel buyers exhibit acute price sensitivity, while direct-to-installer commercial procurement tolerates higher acquisition costs for guaranteed bandwidth specifications.
Supply Chain Analysis
Single-source vulnerability sits with Korean and Chinese display panel manufacturers, exposing Bajío assemblers to shipping cost spikes and currency mismatches. Mexico's supplier base draws from Taiwan for semiconductor foundry services, China for LCD glass substrates, and South Korea for OLED emitter materials. Tariff exposure compounds margin pressure through concentrated import dependencies on East Asian component flows. Distribution runs through Coppel, Liverpool, and Walmart Mexico retail networks for residential volume, with Elektra anchoring mid-tier reach and commercial integrators emerging as a direct channel for enterprise deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's Smart TV market functions as a geographic-arbitrage play where Bajío assembly labor costs and USMCA tariff preferences attract North American-bound production, offsetting East Asian panel import dependencies.
For Market Incumbents: Deploy certification resource capture as the primary lever. Samsung and LG should deepen captive laboratory relationships to compress NOM-001-SCFI testing timelines ahead of seasonal retail cycles. Hisense must accelerate backward integration into MediaTek reference design partnerships to reduce firmware customization bottlenecks caused by embedded software talent scarcity in Guanajuato. For New Entrants and Emerging Players: Commercial integrators serving corporate meeting environments represent the most penetrable channel bypass. Boutique hospitality properties in Riviera Maya and Los Cabos offer underexploited white-space for aesthetic-integrated display specifications. New entrants should anchor go-to-market strategy on direct procurement relationships with Distrito Federal luxury accommodation developers. For Investors and Strategic Acquirers: Asymmetric upside sits with Bajío assemblers possessing modular system-on-chip platforms and captive certification resources. Long-term viability hinges on 5G-broadcast convergence feature integration capability. Investors should monitor IFT spectrum auction timelines as the critical inflection signal for hybrid broadcast-broadband service model differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Modular SoC Platform Adoption | MediaTek and Amlogic reference designs enable rapid SKU customization for Coppel versus Liverpool channel requirements. |
| Captive Certification Investment | In-house NOM-001-SCFI testing resources compress product launch windows against seasonal retail cycles. |
| Direct-to-Installer Channel Development | Commercial integrators bypass traditional electronics distributors for enterprise-grade hospitality and corporate deployments. |
| 5G-Broadcast Convergence R&D | IFT spectrum auction outcomes will differentiate next-generation tuner architectures from WiFi-only competitors. |
| Energy Efficiency Redesign | CONUEE standby power threshold compliance forces chipset and power supply architecture overhauls across portfolios. |
Research Approach
Bottom-up hospitality and residential procurement modeling reconciled against top-down display panel import tracking forms the analytical core of this study. Primary interviews with Bajío plant managers, Coppel category buyers, IFT regulatory affairs specialists, and CONUEE certification officers combined with secondary validation from Mexican customs records, PROFECO consumer complaint databases, and IFT spectrum allocation filings. Triangulation between assembler production schedules and retail channel inventory data anchors volume estimates.
Input-output matrices map panel technology, operating platform, screen size, and connectivity specifications against end-use segments across the projection horizon. Segmentation dimensions include product type, technology architecture, display diagonal, and interface configuration, with regional adoption patterns modeled separately. CAGRs derive from logistic diffusion curves fitted to replacement cycle data and household formation projections. Forecast inputs incorporate IFT digital transition timelines and CONUEE energy mandate phase-in schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor foundry capacity constraints and peso-dollar exchange rate volatility. Forecasts reflect documented assumptions about hospitality sector modernization pace and analog switch-off compliance rates. Panel price volatility, regulatory testing backlogs, and streaming device substitution rates constitute primary revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Smart Headphones Market
Consumer Electronics
Global Office and Contact Center Headset Market
Consumer Electronics
Middle East Radio Headset Market
Consumer Electronics
Asia-Pacific Mobile Phone Accessories Market
Consumer Electronics
Global Bluetooth Mono Earpieces Market
Consumer Electronics
Waterproof Headphones Market
Consumer Electronics
Ultra HD Action Camera Market
Consumer Electronics
Global Automated Laundromat Services Market
Consumer Electronics
Vape Cartridge Market
Consumer Electronics
Global Speaker Market
Consumer Electronics
Smart Audio Devices Market
Consumer Electronics
US Knife Sharpening Service Market
Consumer Electronics
Stylus Pen Market
Consumer Electronics
Consumer Electronic Biometrics Market
Consumer Electronics
HiFi Electronics Market
Consumer Electronics
US Mobile Phone Accessories Market