
 UAE Consumer Electronics Market | 2026-2036
UAE Consumer Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Consumer Electronics Market Insights
Multi-source component procurement is restructuring supply relationships across the UAE consumer electronics sector. Samsung Electronics Co Ltd anchors its Gulf operations through dedicated regional distribution hubs. Apple Inc competes via controlled retail environments and premium channel positioning. Jumbo Electronics leverages its long-standing local presence to sustain shelf dominance in brick-and-mortar formats.
Consumer electronics encompass semiconductor-powered devices designed for personal computing, communication, audiovisual consumption, and connected home management, typically operating on 110-240V universal voltage with wireless connectivity protocols including Wi-Fi 6E and Bluetooth 5.3. Smartphones command the largest revenue pool within product type segments, while online retail channels capture the fastest growth trajectory as logistics infrastructure matures. Premium price tiers concentrate margin pools among brand-loyal demographics, whereas budget tiers drive volume through mass merchant foot traffic.
MOHAP enforces electromagnetic compatibility and product safety standards for all imported electronics, while the UAE's TRAI-aligned telecommunications authority certifies wireless transmission equipment before market entry. ESMA's conformity assessment requirements create compliance barriers for uncertified manufacturers. Stakeholders must monitor evolving e-waste regulations and circular economy mandates that will reshape post-sale obligations and refurbishment economics.
Market Dynamics
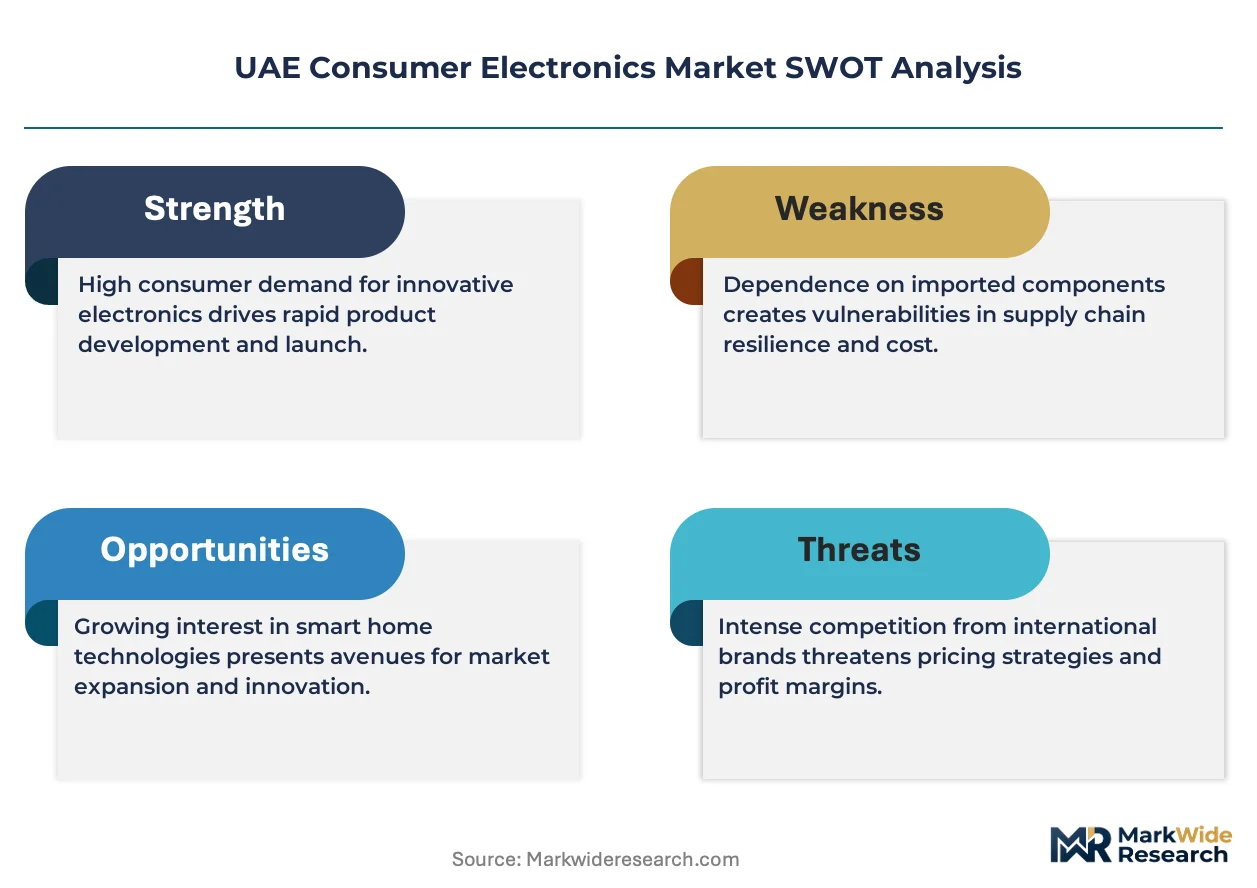
MOHAP's tightening electromagnetic compatibility mandates are forcing distributors to restructure import certification workflows, while smart home device proliferation pulls semiconductor procurement toward specialized IoT chipsets. This dual pressure compresses margins for uncertified suppliers and rewards pre-certified ecosystem partners.
Growth Catalysts
- Smart Home Device Proliferation:Residential buyers across Dubai's villa compounds and Abu Dhabi's high-rise districts are installing connected climate control and security systems. This pulls demand for interoperable hubs and sensors.
- ESMA Conformity Streamlining:The Emirates Authority for Standardization and Metrology has digitized its product registration portal. Faster certification turnaround reduces inventory holding periods for distributors.
- Logistics Infrastructure Maturation:Same-day fulfillment networks now cover Sharjah and Ras Al Khaimah. Electronics retailers are expanding online channel penetration beyond Dubai's core corridors.
Market Restraints
- Semiconductor Input Cost Volatility:Memory and processor wafer prices fluctuate with foundry capacity constraints. UAE distributors lack long-term foundry relationships to hedge exposure.
- Supply Concentration Risk:Component sourcing clusters in East Asian assembly hubs. Geopolitical friction or shipping disruption cascades directly into UAE retail stockouts.
- Regulatory Friction:MOHAP's product safety documentation requirements demand Arabic labeling and technical file translation. Smaller importers face compliance cost barriers.
Strategic Opportunities
- Underpenetrated Northern Emirates:Fujairah and Umm Al Quwain retail corridors lack dedicated consumer electronics flagship presence. First-mover retailers can capture emerging middle-income households.
- Refurbishment and Circular Economy:Dubai's impending e-waste mandates will create regulated secondary markets. Certified refurbishment operations can monetize trade-in flows.
- Wi-Fi 6E and Matter Protocol Convergence:Interoperability standards eliminate ecosystem lock-in. Neutral platform providers can aggregate device management across competing brands.
Industry Challenges
- Certification Timeline Compression:MOHAP's expedited review windows demand parallel regulatory and logistics planning. Distributors must pre-position documentation before cargo departure.
- Integration Complexity with Legacy Building Infrastructure:Older residential towers in Deira and Bur Dubai lack neutral wiring for smart device retrofits. Installers face site-specific engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Consumer Electronics Market |
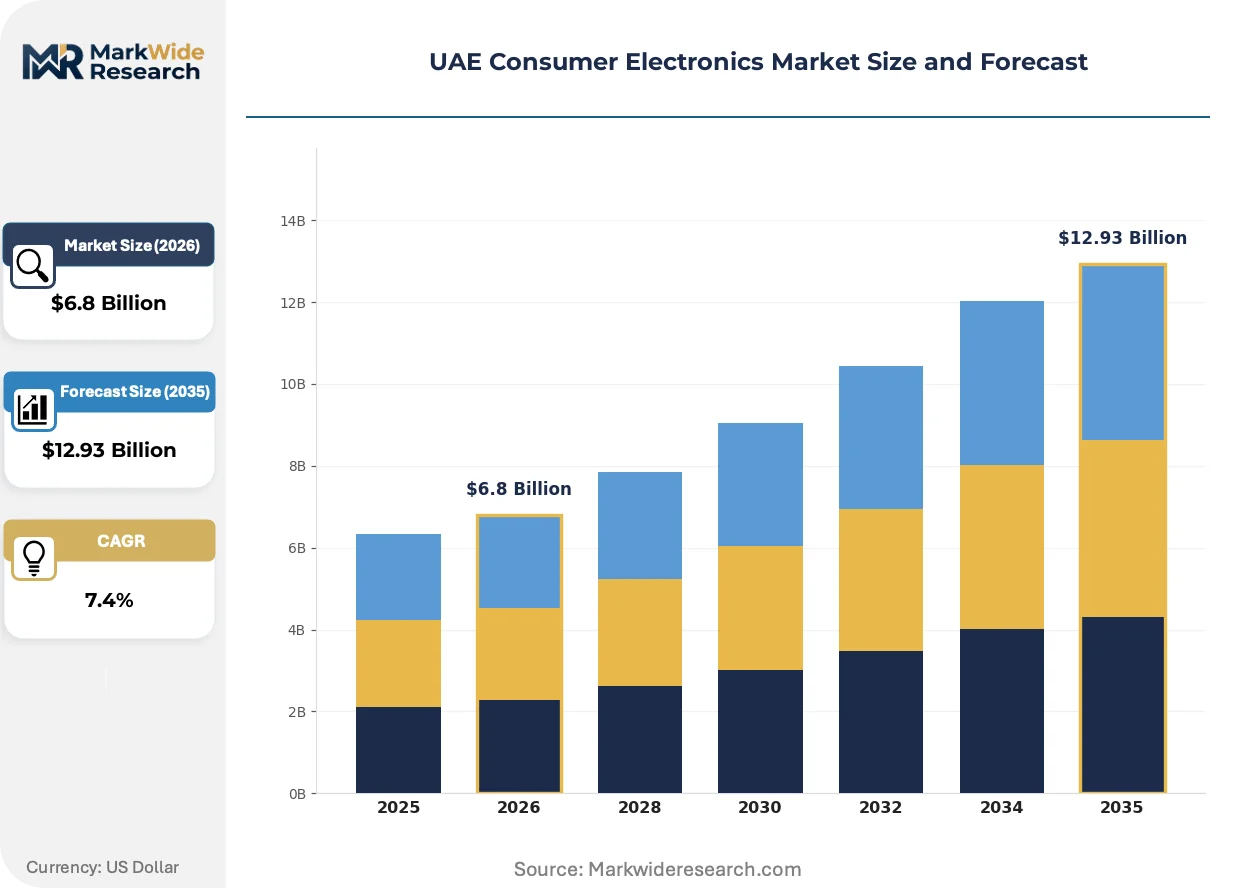
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Laptops, Tablets, Televisions Price Tier: Premium, Mid-Range, Budget, Discount Distribution Channel: Online Retail, Direct Sales, Specialty Stores, Mass Merchants Customer Type: Consumers, Businesses, Educational Institutions, Government |
| Companies Covered | Sony Group Corp, Huawei Technologies, Samsung Electronics Co Ltd, Dell Technologies Inc Ordinary Shares - Class C, HP Inc, Apple Inc, Lenovo Group Ltd, Jumbo Electronics, LG Electronics Inc ADR, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Consumer Electronics Market Trends and Innovations
Connectivity protocol standardization and retail channel digitization are restructuring how UAE consumers discover, purchase, and integrate electronics. These shifts compress traditional distribution hierarchies and elevate service bundling as a differentiation mechanism.
Matter-compatible smart home ecosystems are overtaking proprietary platform silos. Developers in Dubai's new residential towers specify interoperable lighting and climate systems. This protocol convergence compresses hardware margin pools while expanding software and installation service revenue for system integrators.
MOHAP's electromagnetic compatibility testing requirements now align with IEC 61000 series standards. Importers must submit third-party lab reports before customs clearance. Premium audio and gaming peripheral categories face the longest certification queues, prompting distributors to pre-stage inventory during Ramadan lulls.
Subscription-based device upgrade programs are displacing outright purchase cycles among affluent Emirati households. Retailers in Abu Dhabi's Yas Mall and Dubai Mall anchor stores bundle annual refresh rights with insurance and technical support. This model concentrates in smartphone and wearable categories where obsolescence anxiety runs highest.
UAE Consumer Electronics Market Segmentation
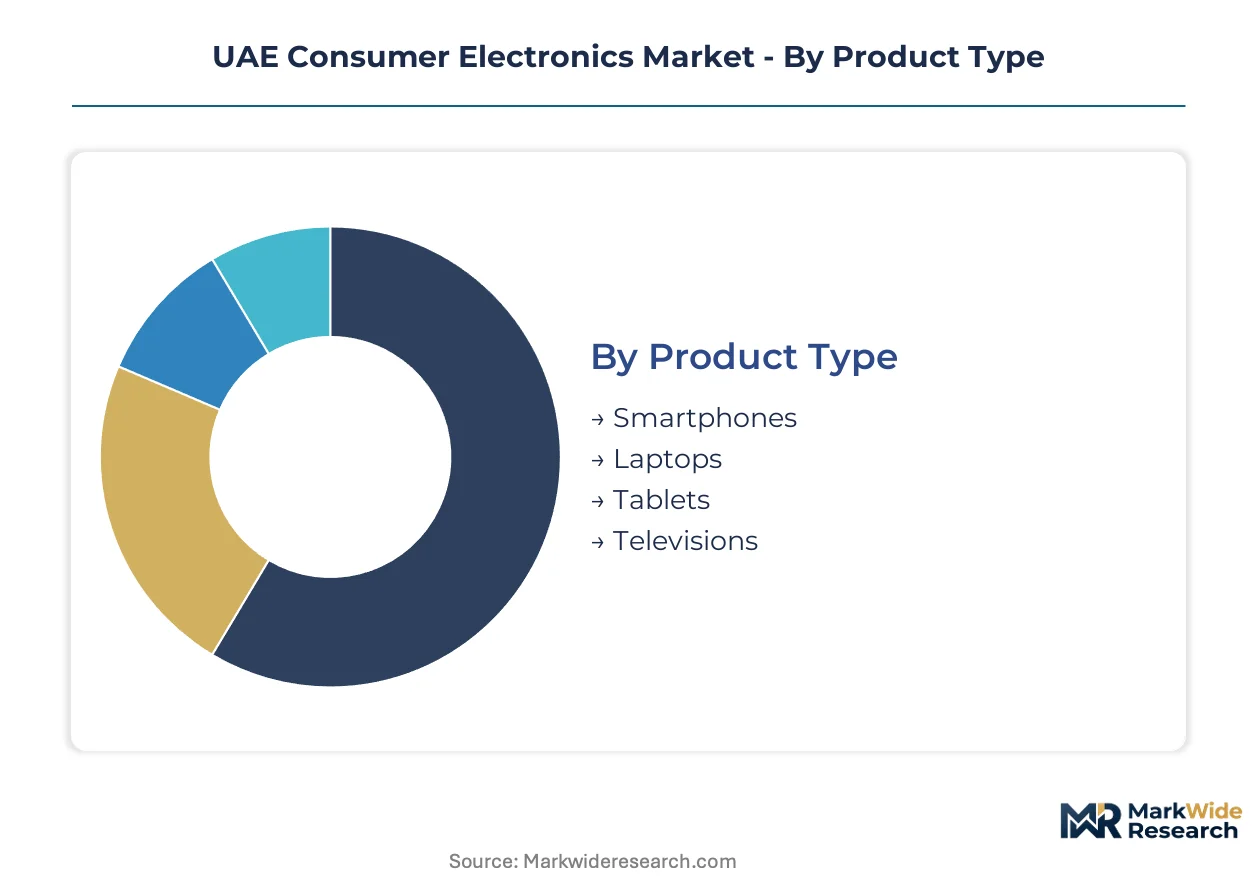
Segmentation in the UAE consumer electronics market reveals how procurement patterns diverge across technical specifications, budget thresholds, and fulfillment preferences. These divisions expose where margin pools concentrate and which channels are capturing shifting purchase behaviors.
Product Type:
Semiconductor architecture and connectivity protocol requirements differentiate hardware categories, with implications for certification complexity and replacement cycles.
- Smartphones:ARM-based SoCs with integrated 5G modems dominate bill-of-materials costs. Demand clusters among Dubai's professional services workforce and Abu Dhabi's government employees, driven by carrier-subsidized upgrade programs and mobile wallet integration requirements.
- Laptops:x86 and ARM compute platforms now split the commercial segment, with Thunderbolt 4 and USB4 connectivity becoming standard for enterprise fleet procurement. UAE free zone headquarters drive bulk orders with three-year refresh cycles.
- Tablets:Media consumption and field service applications sustain demand across education and logistics verticals. Apple iPadOS and Android ecosystems compete for stylus-enabled productivity use cases.
- Televisions:QD-OLED and Mini LED backlight technologies command living room upgrades in villa compounds. Screen size preferences skew larger in Sharjah and Ras Al Khaimah residential developments.
Smartphones lead on scale; laptops lead on momentum.
Price Tier:
Purchase thresholds segment buyers by payment method preference and brand loyalty intensity, with direct effects on retail format selection.
- Premium:Flagship devices above AED 3,500 with titanium enclosures and satellite connectivity. Emirates NBD and FAB offer zero-interest installment plans that sustain volume in Dubai Mall and Yas Mall flagship locations.
- Mid-Range:Performance-optimized chipsets with compromised camera arrays or storage tiers. South Asian expatriate households in Deira and Bur Dubai prioritize this bracket for family handset procurement.
- Budget:Sub-AED 1,000 devices with MediaTek Dimensity or Qualcomm Snapdragon 4-series processors. Mass merchant foot traffic in Sharjah's Mega Mall and Ajman City Centre sustains this tier.
- Discount:Previous-generation flagships and carrier-locked inventory. Gray market operators in Dubai's Al Ain Centre move volume through cash transactions outside VAT documentation.
Premium tier leads on margin extraction; budget tier leads on unit velocity.
Distribution Channel:
Fulfillment infrastructure maturity and purchase occasion urgency determine channel selection, with logistics coverage expanding beyond traditional retail corridors.
- Online Retail:Same-day delivery networks now cover all seven emirates. Noon and Amazon.ae compete on electronics assortment depth, with return policies influencing high-consideration purchases.
- Direct Sales:Manufacturer-owned stores and corporate B2B contracts. Apple and Samsung operate experience centers in Dubai Mall where technical support bundling justifies price premiums.
- Specialty Stores:Jumbo Electronics and Sharaf DG maintain destination electronics retail with installation service attachments. Gaming peripheral and high-fidelity audio categories concentrate here.
- Mass Merchants:Carrefour and Lulu Hypermarket capture impulse and gift purchases. Seasonal promotions around Ramadan and Eid drive traffic spikes in this channel.
Mass merchants lead on foot traffic; online retail leads on expansion trajectory.
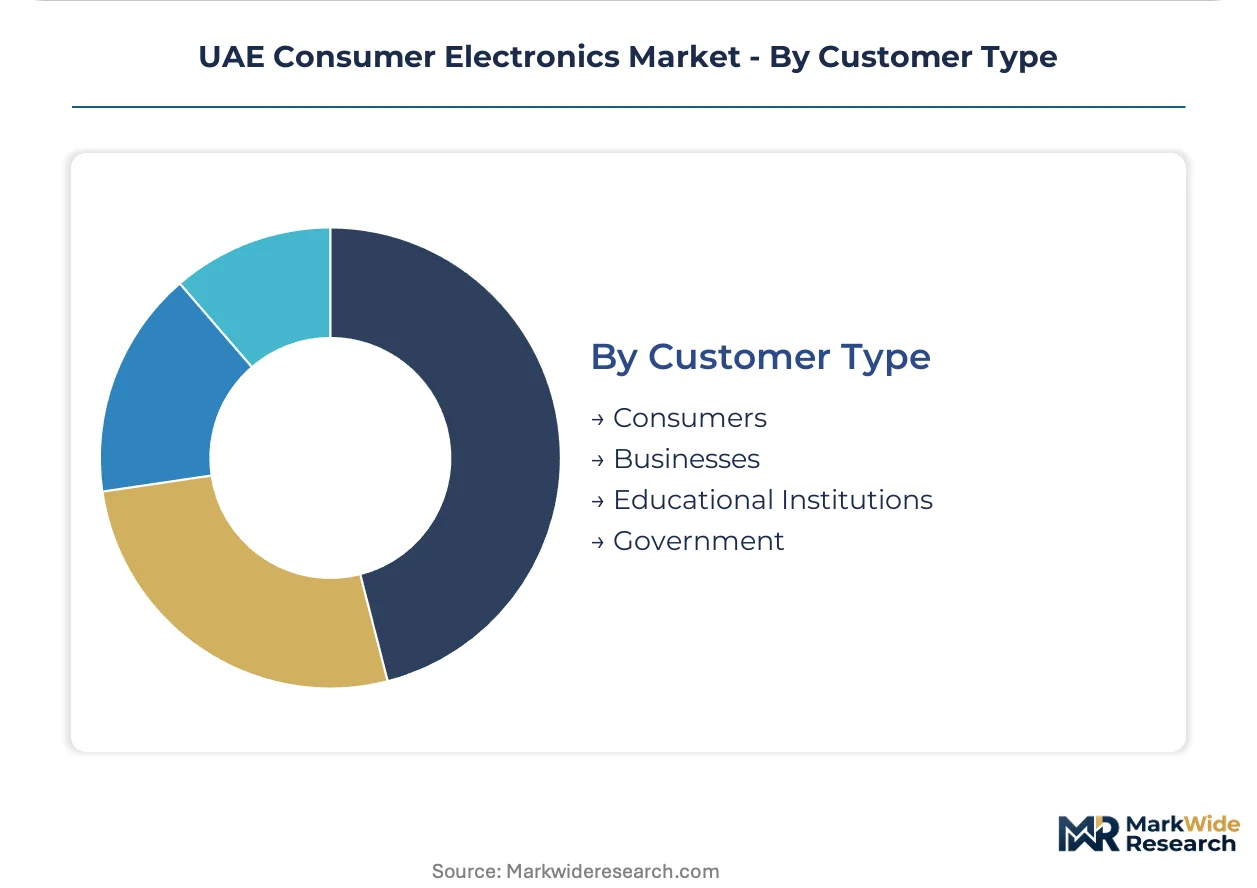
Customer Type:
Procurement governance structures and budget authority patterns create distinct sales cycle lengths and technical specification requirements.
- Consumers:Individual households making discretionary replacement decisions. Social media influence and peer recommendation dominate discovery, with unboxing content driving brand consideration.
- Businesses:Corporate IT departments managing fleet deployments. ADNOC, Emirates Group, and Etisalat drive large-volume tenders with security certification requirements and multi-year support contracts.
- Educational Institutions:K-12 schools and universities procuring student device programs. MOE-approved specifications limit vendor eligibility, with ChromeOS and iPadOS dominating tablet deployments.
- Government:Federal and emirate-level entities with sovereign procurement frameworks. Tawazun and ADQ-related entities enforce data residency and local support presence requirements.
Consumer segment leads on transaction frequency; government segment leads on contract value concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping electronics distribution across the Gulf, with MOHAP's streamlined certification processes attracting regional headquarters migration from jurisdictions with heavier compliance burdens. This cost-of-compliance gap concentrates procurement authority in Dubai and Abu Dhabi while pulling satellite operations into Sharjah's logistics corridors.
Dubai
Dubai Mall and Mall of the Emirates anchor premium electronics retail, with Emirates NBD installment plans sustaining flagship device turnover among professional services households. MOHAP's digitized product registration portal enables faster customs clearance through Jebel Ali Free Zone. Dubai Silicon Oasis hosts regional distribution hubs for multinational vendors serving the broader GCC market.
Abu Dhabi
Yas Mall and Al Wahda Mall concentrate government employee procurement clusters, with sovereign wealth-related entities driving enterprise fleet tenders. Tawazun procurement frameworks enforce data residency requirements for federal contracts. Masdar City's smart building specifications pull demand for interoperable climate and security systems into specification pipelines.
Sharjah
Sharjah's Mega Mall and City Centre Sharjah capture mid-range and budget-tier volume from South Asian expatriate households. The emirate's industrial zones host third-party logistics providers feeding same-day delivery networks into Dubai's northern corridors. Hamriyah Free Zone attracts warehousing operations seeking lower occupancy costs than Jebel Ali.
Northern Emirates
Fujairah and Ras Al Khaimah retail corridors remain underpenetrated by dedicated electronics flagships, creating first-mover opportunities for mass merchant expansion. Ajman City Centre sustains budget-tier foot traffic through seasonal Ramadan promotions. Umm Al Quwain's emerging middle-income households represent untapped demand for entry-level smartphones and connected home devices.
UAE Consumer Electronics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in refurbishment services and neutral platform aggregation. The vendor base splits between vertically integrated multinationals with captive Gulf distribution and regional specialists leveraging local regulatory fluency. Three archetypes dominate: ecosystem-locked premium brands, multi-brand retail aggregators, and component-agnostic system integrators. Competitive moves concentrate on certification pre-positioning and installation service bundling.
Within the multinational tier, Samsung Electronics Co Ltd and Apple Inc anchor premium positioning through controlled retail environments and technical support bundling. Jumbo Electronics exemplifies the regional specialist archetype, sustaining shelf dominance in brick-and-mortar formats through long-standing local presence and installation service attachments. These three occupy positions spanning manufacturing origin, retail format control, and regulatory navigation capability.
| Leading Market Players |
|---|
| Sony Group Corp |
| Huawei Technologies |
| Samsung Electronics Co Ltd |
| Dell Technologies Inc Ordinary Shares - Class C |
| HP Inc |
| Apple Inc |
| Lenovo Group Ltd |
| Jumbo Electronics |
| LG Electronics Inc ADR |
| Others |
Pricing and Supply Chain Analysis
MOHAP's e-waste compliance mandates and circular economy directives gate qualified supplier access and premium-tier pricing power, as certified refurbishment capabilities become prerequisites for flagship retail placement and enterprise contract eligibility. This environmental qualification layer concentrates margin pools among distributors with pre-staged compliance infrastructure while compressing pricing flexibility for uncertified gray-market operators.
Pricing Analysis
Input-cost pass-through from semiconductor wafer volatility flows unevenly across product tiers, with ARM-based SoC and memory module fluctuations absorbed faster in premium smartphone SKUs than in budget MediaTek configurations. Price differentiation rests on ESMA certification tier and installation service bundling, where pre-certified ecosystem partners command AED 200-400 attach premiums. Cost compression in mid-range laptops intensifies because Thunderbolt 4 controller shortages force chipset downgrades. Mass merchant buyers in Sharjah and Ajman exhibit highest price sensitivity, while sovereign wealth-linked enterprises in Abu Dhabi prioritize data residency over unit cost.
Supply Chain Analysis
ESMA conformity assessment and MOHAP electromagnetic compatibility documentation gate customs clearance, filtering supplier eligibility before cargo reaches Jebel Ali. Component sourcing draws from Taiwan, South Korea, and Vietnam, with foundry capacity for 5G modems and OLED display drivers concentrated in Taichung and Gumi. Single-source vulnerability runs through specialized IoT chipset suppliers serving Dubai's smart building specifications. Distribution runs through Dubai Silicon Oasis regional hubs feeding Sharjah logistics corridors and Northern Emirates retail expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE consumer electronics market functions as a geographic-arbitrage play, with MOHAP's digitized certification portal offering faster turnaround than Saudi SFDA or Indian BIS pathways, lowering compliance carrying costs for regional headquarters migration.
For Market Incumbents: Lock in pre-certified inventory positions before Ramadan demand surges compress available lab testing slots. Deepen backward integration into refurbishment operations to capture Dubai's impending e-waste mandate trade-in flows. Neutral platform aggregation poses substitution risk to proprietary ecosystem lock-in; defend by accelerating Matter protocol certification across hub and sensor portfolios.
For New Entrants and Emerging Players: ESMA's digitized product registration portal in the UAE opens a window for white-label smart home device penetration where interoperability certification substitutes for brand equity. Fujairah and Umm Al Quwain retail corridors offer lowest competitive density for mass merchant partnerships. Pursue certified refurbishment licensing as a service-layer entry point rather than hardware manufacturing.
For Investors and Strategic Acquirers: Roll-up economics work for regional specialty retailers with installation service attachments because post-sale technical support contracts generate recurring revenue streams immune to semiconductor price cycles. Mid-cap distributors with MOHAP pre-certification relationships and Northern Emirates logistics coverage represent priority acquisition archetypes. Watch for e-waste mandate enforcement timelines as inflection indicator for refurbishment asset valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Eliminates ecosystem lock-in for Jumbo Electronics and Sharaf DG integration services. |
| Refurbishment Operation Licensing | Positions distributors to monetize Dubai e-waste mandate trade-in flows. |
| Same-Day Delivery Network Expansion | Extends Noon and Amazon.ae coverage into Fujairah and Ras Al Khaimah corridors. |
| Backward Integration into IoT Chipset Sourcing | Reduces foundry capacity exposure for smart home hub manufacturers. |
| Corporate B2B Fleet Tender Positioning | Captures ADNOC and Emirates Group refresh cycles with data residency compliance. |
Research Methodology
Coverage spans Dubai, Abu Dhabi, Sharjah, and the Northern Emirates, with primary inputs from each emirate's distinct procurement clusters. Primary interviews with MOHAP compliance officers, Jebel Ali Free Zone logistics managers, Jumbo Electronics category buyers, and Etisalat enterprise procurement leads combined with secondary validation from ESMA registration databases, UAE customs electronics import records, and SEC 10-K filings of listed component suppliers. Bottom-up smartphone and laptop shipment estimates triangulated against top-down retail audit data from mall operators.
Granularity-level modeling tracked product type, price tier, distribution channel, and customer type dimensions across the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market value expansion. Forecast inputs incorporated foundry capacity utilization reports from Taiwan and South Korea, plus MOHAP certification queue length data as leading indicators of inventory availability.
Revisions become necessary when semiconductor foundry capacity constraints intensify, shipping disruption cascades through Jebel Ali, or e-waste mandate enforcement timelines accelerate beyond current guidance. Forecasts reflect assumptions about ESMA portal processing speeds and Matter protocol adoption curves among Dubai developers. A model refresh is warranted upon material change in MOHAP electromagnetic compatibility testing alignment with IEC standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Zipline Kits Market
Consumer Electronics
North America Gaming Accessories Market
Consumer Electronics
Smart Connected TV Market
Consumer Electronics
Latin America Consumer Electronics Market
Consumer Electronics
Global Smart Earbuds Market
Consumer Electronics
Instant Camera Market
Consumer Electronics
Bluetooth Headphones Market
Consumer Electronics
Japan Gaming Peripherals Market
Consumer Electronics
Mobile Phone Accessories Market
Consumer Electronics
Europe Smart TV Market
Consumer Electronics
Computing Mouse Market
Consumer Electronics
Portable Media Player Market
Consumer Electronics
Smart Speaker Market
Consumer Electronics
Wet Wipes Market
Consumer Electronics
Handheld Device Accessories Market
Consumer Electronics
Vape Market