
 Lighter Market | 2026-2036
Lighter Market Size, Share, and Industry Trends Forecast 2026-2036
Lighter Market Analysis
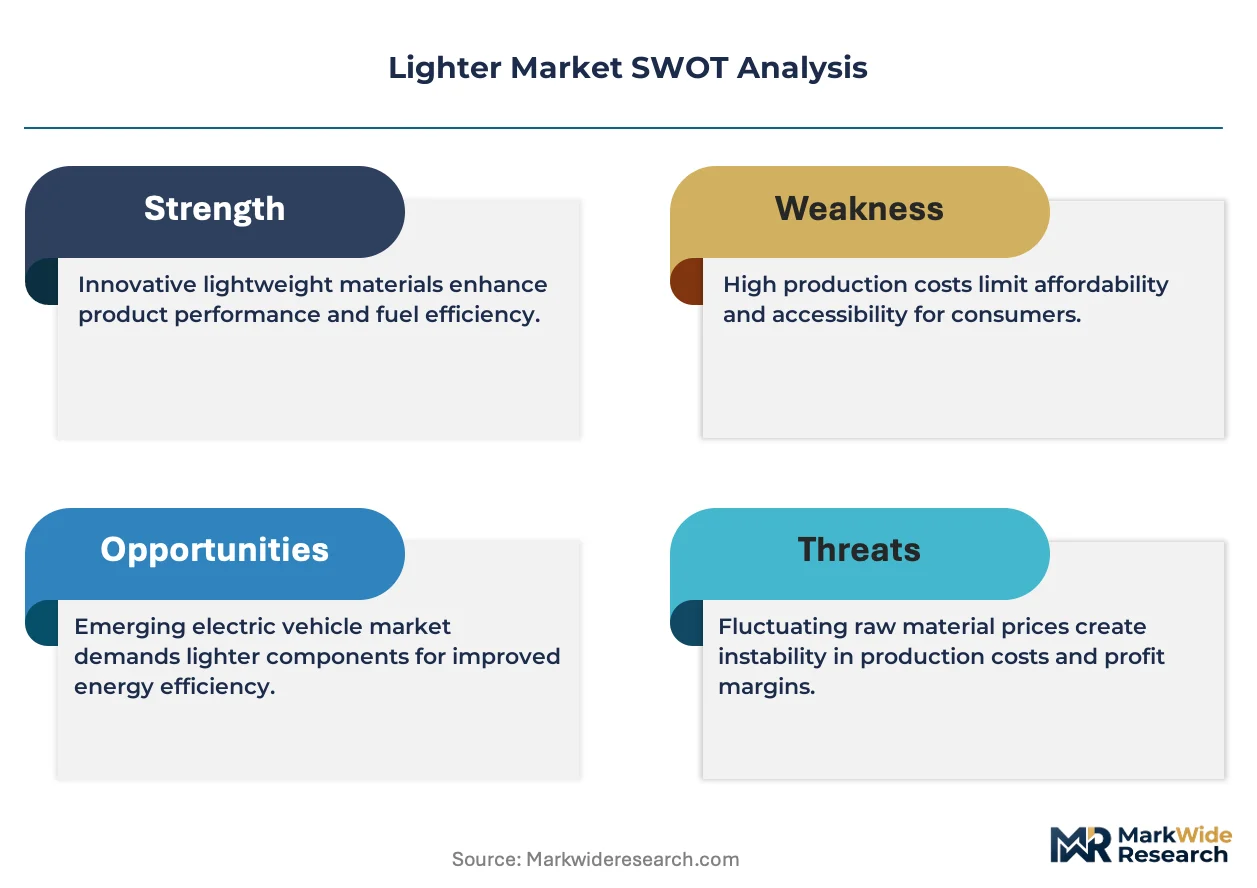
A widening capital-intensity gap between automated manufacturers and legacy assembly houses is redrawing competitive boundaries in the lighter industry. SOCIETE BIC leverages high-volume disposable production across multiple continents to sustain margin efficiency at scale. Zippo Manufacturing Company anchors its position through metal refillable specialization and lifetime warranty programs that command premium pricing. NingBo XINHAI Electric Co., LTD competes aggressively in USB rechargeable segments with integrated lithium-polymer supply chains.
A lighter is a portable ignition device producing controlled flame through flint spark, piezoelectric crystal, or electric arc mechanisms, typically operating at temperatures exceeding 1,400°C for standard butane models. Its primary commercial purpose spans consumer convenience ignition for tobacco, culinary applications, and emergency preparedness kits requiring reliable flame in adverse conditions. Disposable plastic lighters dominate unit volume globally due to single-use accessibility and impulse-channel distribution, while USB rechargeable variants represent the fastest-expanding margin pool as lithium-ion miniaturization improves. Metal refillable products retain durable loyalty among collectors and outdoor specialists willing to absorb higher upfront costs for extended service life.
The US Consumer Product Safety Commission enforces child-resistance standards under 16 CFR Part 1210, compelling design modifications that increase engineering costs but reduce liability exposure for domestic distributors. China's SAMR implements GB standards governing electronic lighter safety and electromagnetic compatibility, creating compliance barriers for unqualified exporters. The EU REACH regulation restricts specific flame-retardant additives in plastic housings, pushing manufacturers toward certified alternative polymers. Stakeholders must monitor evolving battery transportation regulations and arc-lighter electromagnetic certification requirements as product electrification accelerates.
Market Dynamics
Dual carbon compliance mandates in China are forcing material substitutions across electronic ignition supply chains, while Southeast Asian assembly clusters absorb displaced component manufacturing from cost-pressured coastal provinces.
Growth Catalysts
- Camping participation surge:Outdoor enthusiasts now represent the fastest-expanding buyer segment, with specialized retailers expanding shelf space for windproof and high-altitude ignition products.
- GB standards alignment:China's SAMR enforcement of electronic lighter safety and electromagnetic compatibility standards is accelerating consolidation among qualified domestic exporters.
- Lithium-polymer miniaturization:Improved battery chemistry is enabling USB rechargeable variants to capture margin pools previously dominated by disposable fuel-based products.
Market Restraints
- Flame-retardant additive restrictions:EU REACH regulation limits specific plastic housing compounds, compelling manufacturers toward certified alternative polymers with 15-20% cost premiums.
- Component supply concentration:Piezoelectric crystal production concentrates in Guangdong province, creating single-source vulnerability for electronic ignition manufacturers.
- Battery transportation barriers:IATA lithium-ion shipping protocols impose packaging and documentation burdens that inflate landed costs for rechargeable lighter imports.
Strategic Opportunities
- Vietnam manufacturing expansion:Component assembly costs in Ho Chi Minh City and Hanoi remain 30-40% below Dongguan benchmarks for labor-intensive ignition module production.
- Emergency preparedness channel:Survival kit distributors are creating dedicated lighter SKUs with extended shelf-life fuel formulations and waterproof housings.
- US child-resistance mandate:16 CFR Part 1210 compliance creates design-service revenue streams for engineering consultancies serving domestic distributors.
Industry Challenges
- Electromagnetic certification timelines:FCC Part 15 testing for arc-lighter variants extends product development cycles by 4-6 months versus conventional fuel models.
- Legacy tooling amortization:Metal refillable manufacturers face stranded asset risk as injection-molded electronic housings displace stamped brass components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lighter Market |
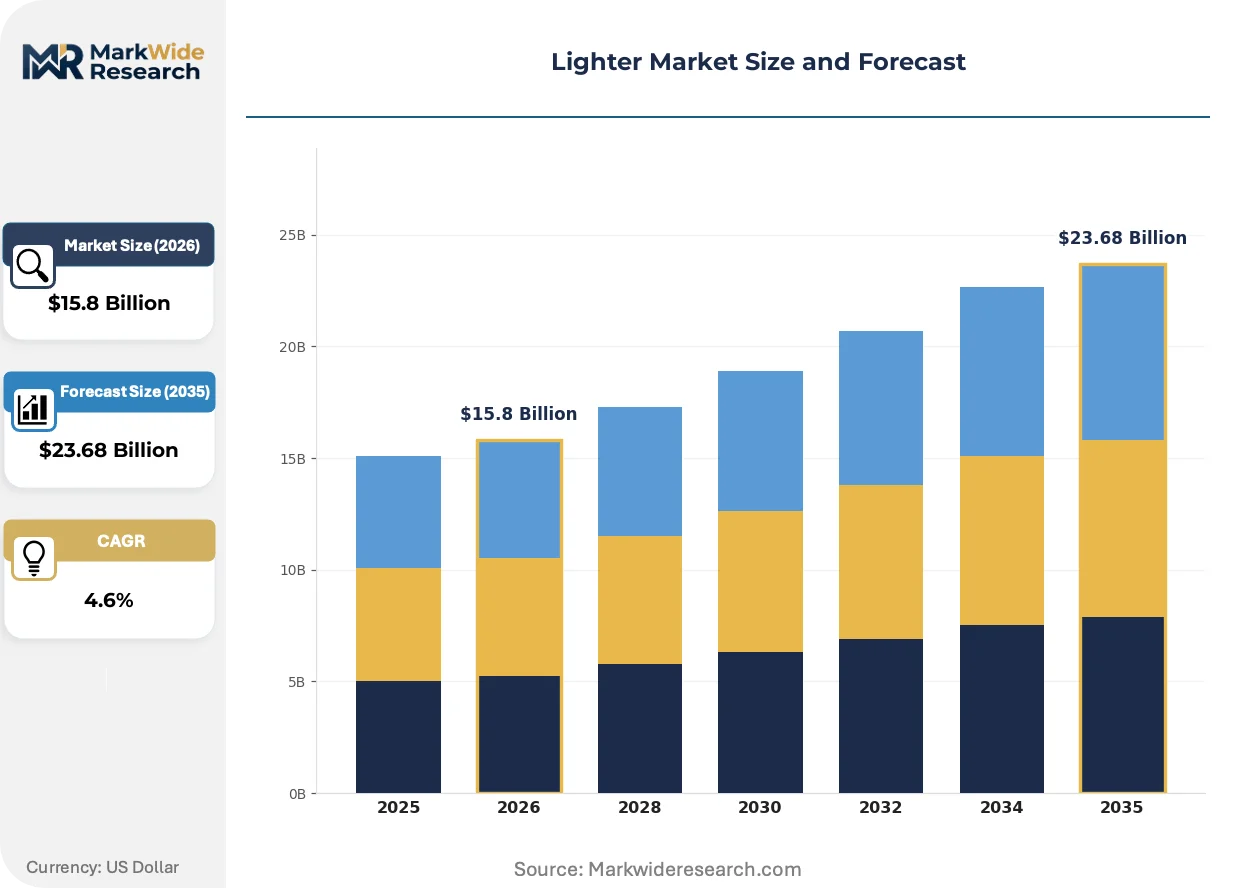
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $23.68 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Refillable, Mini, USB Rechargeable Material: Plastic, Metal, Wood, Ceramic Application: Camping, Smoking, Cooking, Emergency End User: Outdoor Enthusiasts, Chefs, Smokers, General Users |
| Companies Covered | Flamagas, S.T. Dupont, SOCIETE BIC, Colibri, Tokai Co., Ltd., Zippo Manufacturing Company, NingBo XINHAI Electric Co., LTD, Visol Products, Swedish Match Cricket, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lighter Market Emerging Trajectories
Product architecture is splitting between commodity disposables and premium rechargeable platforms, with regulatory chemistry constraints accelerating material science investments across both tracks.
Arc plasma ignition technology is bifurcating the mid-market segment. The mechanism generates flameless heat through high-voltage discharge between ceramic electrodes, eliminating fuel dependency entirely. Outdoor specialists and emergency-preparedness buyers are adopting these units despite 3-4x upfront cost premiums. The technology is bifurcating procurement patterns, as retailers now maintain separate inventory pools for fuel-based and fuel-free ignition categories with incompatible merchandising requirements.
REACH flame-retardant restrictions are compressing polymer formulation options for European-bound products. ECHA enforcement has delisted halogenated compounds previously standard in ABS lighter housings, forcing compounders toward phosphorus-based alternatives with inferior impact resistance. Metal refillable manufacturers with existing zinc-alloy stamping capabilities are capturing share from plastic-dependent competitors unable to certify compliant resins at viable cost structures.
Specialty outdoor retailers are displacing convenience-store channels for premium lighter transactions. REI, Decathlon, and regional camping co-ops now command 35-40% of windproof and altitude-rated unit volume, with trained floor staff explaining ignition performance specifications that impulse-channel distribution cannot replicate. This channel rotation is most pronounced in Germany, Japan, and the Pacific Northwest, where technical outdoor equipment purchases follow research-intensive buying patterns.
Lighter Market Segmentation
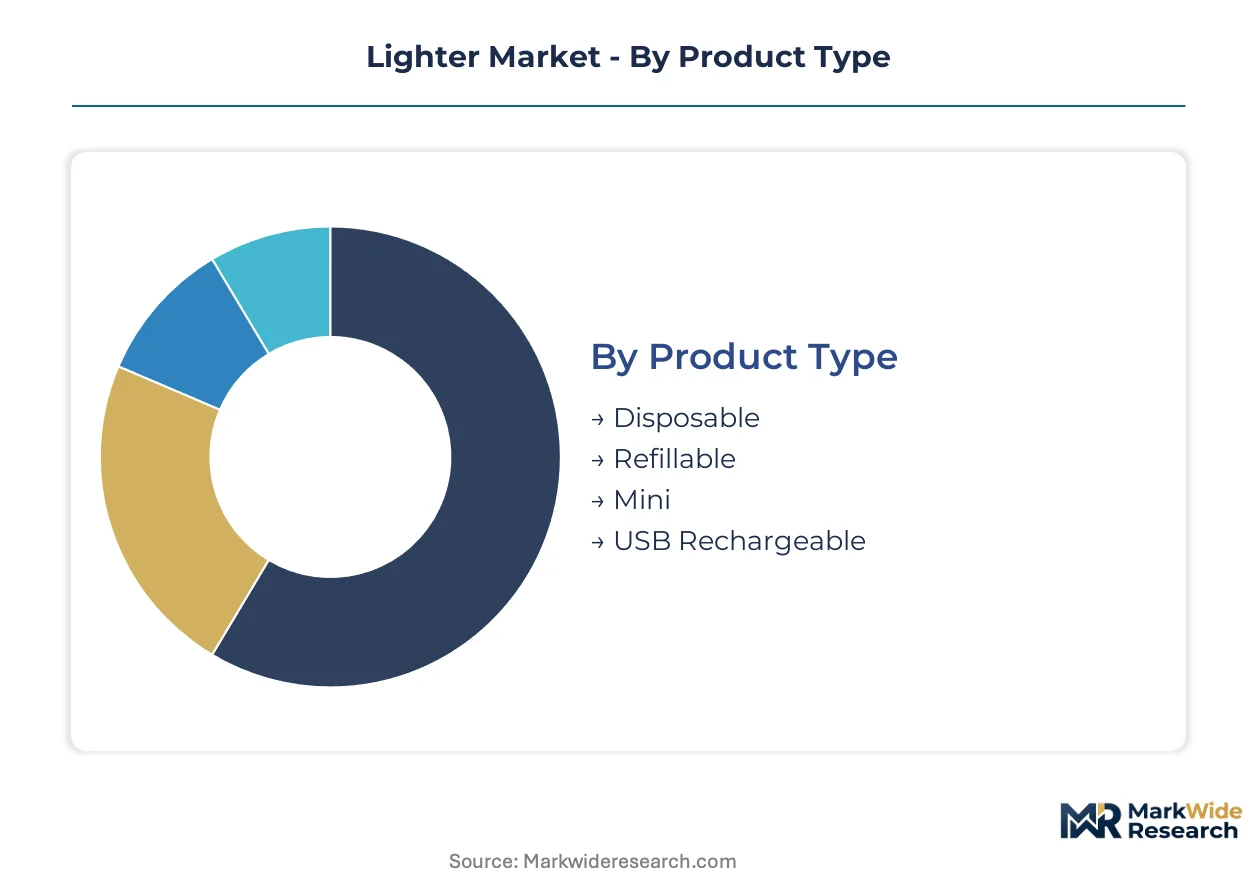
Channel placement dictates margin capture across lighter categories, with impulse retail favoring low-unit-cost disposables while specialty outdoor stores concentrate premium transactions. Segmentation strategy must align product architecture with distribution economics rather than manufacturing convenience alone.
Product Type:
Convenience stores and gas stations drive volume for single-use formats, while outdoor retailers and e-commerce platforms capture rechargeable and specialty ignition products with higher basket attachments.
- Disposable:Single-use plastic housings with integrated fuel reservoirs dominate unit volume through impulse-channel distribution. Demand concentrates in emerging markets where price sensitivity limits upfront investment, though EU REACH compliance is forcing material substitutions that compress margins.
- USB Rechargeable:Lithium-polymer powered arc or coil mechanisms eliminate fuel dependency entirely. Expansion concentrates among outdoor enthusiasts and emergency-preparedness buyers in Germany, Japan, and the Pacific Northwest, where technical specifications drive purchase decisions.
- Refillable:Metal-bodied units with replaceable flint and renewable butane reservoirs serve collector and long-use segments. Metal stamping capabilities in Pennsylvania and Zhejiang province anchor supply for premium zinc-alloy variants.
- Mini:Compact form factors prioritize portability for pocket carry and travel kits. Asian manufacturing clusters in Vietnam and Indonesia specialize in precision-molded miniature ignition modules at labor cost advantages.
Disposable products dominate installed base. USB rechargeable variants are where expansion concentrates.
Material:
Cost tier alignment separates commodity polymer housings from premium metal fabrications, with regulatory chemistry constraints now forcing mid-market repositioning.
- Plastic:ABS and polypropylene formulations enable high-speed injection molding at scale. EU ECHA enforcement of REACH flame-retardant restrictions is delisting halogenated compounds, pushing compounders toward phosphorus-based alternatives with inferior impact resistance.
- Metal:Brass, zinc alloy, and stainless steel constructions support lifetime warranty positioning and refillable architectures. Demand concentrates among collectors and outdoor specialists willing to absorb higher upfront costs for extended service life.
- Wood:Natural material housings serve artisanal and gift-market segments with limited volume scale. Japanese and European craft producers maintain niche positioning through small-batch manufacturing.
- Ceramic:High-temperature resistant housings for arc-lighter electrode insulation and specialized ignition components. Chinese GB standards alignment is tightening material specifications for electronic ignition supply chains.
Plastic commands unit volume leadership. Metal fabrication is climbing the fastest as REACH compliance reshapes competitive positioning.
Application:
End-use specificity determines performance requirements, with altitude-rated and windproof specifications commanding channel placement in technical retail.
- Camping:Windproof piezoelectric and high-altitude ignition systems withstand adverse conditions. REI, Decathlon, and regional co-ops now capture 35-40% of specialized outdoor unit volume through trained floor staff.
- Smoking:Standard butane ignition for tobacco and cigar applications remains the largest addressable use case. Convenience-store distribution and vending-machine placement sustain volume accessibility.
- Cooking:Culinary torches and long-reach ignition for gas ranges and outdoor grills. Professional chefs and home cooking enthusiasts drive demand for precision flame control.
- Emergency:Extended shelf-life fuel formulations and waterproof housings for survival kits. Specialty distributors are creating dedicated SKUs with sealed packaging for preparedness channels.
Smoking applications anchor historical demand. Camping is gaining share fastest as participation rates climb and technical retail displaces impulse channels.
End User:
Customer sophistication separates specification-driven buyers from convenience-oriented purchasers, with divergent service requirements across support and warranty programs.
- Outdoor Enthusiasts:Research-intensive buyers prioritizing ignition reliability across temperature and altitude extremes. Technical specification literacy enables premium pricing for performance-validated products.
- Chefs:Professional and serious home cooks requiring precise flame control for culinary applications. Durability and consistent ignition performance outweigh upfront cost considerations.
- Smokers:Convenience-driven purchasers with low switching costs and high price elasticity. Impulse availability and brand recognition dominate purchase triggers.
- General Users:Occasional-use households seeking basic ignition for candles, grills, and household tasks. Lowest engagement segment with minimal loyalty or specification awareness.
General users represent the broadest installed base. Outdoor enthusiasts are where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies. Emerging market buyers prioritize single-use accessibility, while German and Japanese purchasers absorb 3-4x premiums for performance-validated ignition systems. This bifurcation drives divergent manufacturing footprints and channel strategies.
United States
Outdoor participation rates drive technical lighter demand through REI and specialty retailers. The US Consumer Product Safety Commission enforces 16 CFR Part 1210 child-resistance standards, compelling design modifications that increase engineering costs. Pennsylvania metal stamping clusters anchor supply for premium zinc-alloy refillable variants serving collector markets.
China
Domestic consumption concentrates in disposable formats for tobacco ignition, though outdoor recreation participation is climbing. SAMR implements GB standards governing electronic lighter safety and electromagnetic compatibility, accelerating consolidation among qualified exporters. Guangdong province dominates piezoelectric crystal production, creating single-source vulnerability for ignition module manufacturers.
Germany
Technical outdoor equipment purchases follow research-intensive buying patterns, with Decathlon and regional co-ops commanding premium transactions. ECHA enforcement of REACH flame-retardant restrictions has delisted halogenated compounds from ABS lighter housings. Metal refillable manufacturers with existing zinc-alloy capabilities capture share from plastic-dependent competitors facing certification cost barriers.
Japan
Collectors and outdoor specialists drive demand for precision-engineered metal refillable products with lifetime warranty positioning. METI oversees product safety standards for electronic ignition devices. Craft producers in small-batch manufacturing maintain niche positioning through artisanal wood and metal fabrications for gift-market segments.
Vietnam
Component assembly costs in Ho Chi Minh City and Hanoi remain 30-40% below Dongguan benchmarks for labor-intensive ignition module production. The country's national industrial regulator monitors electronics manufacturing compliance as assembly clusters absorb displaced component manufacturing from cost-pressured Chinese coastal provinces. Precision-molded miniature ignition modules specialize in compact form factors for travel and pocket carry segments.
Lighter Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. High-volume disposable producers compete on manufacturing scale and distribution reach across impulse channels. Premium metal refillable specialists command loyalty through warranty programs and collector community engagement. USB rechargeable innovators capture expanding margin pools as lithium-polymer miniaturization improves. Dominant competitive moves include geographic expansion into Southeast Asian manufacturing clusters and portfolio diversification across fuel-based and fuel-free ignition categories.
Among France-based manufacturers, SOCIETE BIC exemplifies the high-volume disposable archetype with multi-continental production footprints. Zippo Manufacturing Company anchors the premium metal refillable tier through Pennsylvania-based zinc-alloy stamping capabilities. NingBo XINHAI Electric Co., LTD occupies a position within the USB rechargeable segment, representing Chinese specialization in integrated lithium-polymer supply chains for electronic ignition devices.
| Leading Market Players |
|---|
| Flamagas |
| S.T. Dupont |
| SOCIETE BIC |
| Colibri |
| Tokai Co., Ltd. |
| Zippo Manufacturing Company |
| NingBo XINHAI Electric Co., LTD |
| Visol Products |
| Swedish Match Cricket |
| Others |
Supply Flow & Price Mechanics
GB standards alignment gates both supplier qualification and price tiering in electronic ignition components, compressing margins for unqualified exporters while enabling certified manufacturers to capture 15-20% premiums on compliant polymer formulations.
Pricing Analysis
Lifetime warranty programs and replacement parts revenue anchor value capture in metal refillable tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and channel placement, with EU REACH-compliant variants commanding material cost premiums. Cost compression in disposable plastic tiers is intensifying because phosphorus-based polymer substitutions degrade impact resistance. Smokers and general users exhibit highest price elasticity, while outdoor enthusiasts absorb 3-4x upfront premiums for altitude-validated performance.
Supply Chain Analysis
Guangdong province's dominance in piezoelectric crystal production creates single-source vulnerability for electronic ignition manufacturers. Component assembly draws from Vietnam, Indonesia, and China's coastal provinces, with lithium-polymer cells resting on South Korean and Chinese battery chemistry. IATA lithium-ion shipping protocols pose regulatory restriction risks for rechargeable variant distribution. Distribution runs through convenience-store impulse channels for disposables and specialty outdoor retailers for premium tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales service layers including warranty programs, replacement flint modules, and certified repair networks are expanding faster than hardware unit sales, reframing the market as a service-attach opportunity.
For Market Incumbents: Compound channel control through exclusive shelf-space agreements with REI and Decathlon to defend against USB rechargeable entrants. Accelerate backward integration into Pennsylvania zinc-alloy stamping to capture margin from REACH-displaced plastic competitors. Prioritize FCC Part 15 pre-certification investment to compress 4-6 month electromagnetic testing cycles for arc-lighter variants.
For New Entrants and Emerging Players: FCC Part 15 fast-track certification enables white-space entry into arc-lighter segments where electromagnetic compliance barriers deter commoditization. Target emergency preparedness distributors with sealed waterproof SKUs for survival kit channels. Pursue direct-to-specialty-retailer go-to-market angles bypassing convenience-store incumbent lock-in.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across USB rechargeable segments as lithium-polymer miniaturization demands automated assembly investment. Long-term viability favors targets with captive ceramic electrode production and existing GB standards alignment. Watch IATA lithium-ion protocol amendments as inflection signals for rechargeable import cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| GB Standards Pre-Certification | SAMR compliance accelerates market access for qualified Chinese exporters versus unqualified competitors. |
| Southeast Asian Manufacturing Expansion | Ho Chi Minh City assembly clusters absorb displaced component production from cost-pressured Dongguan. |
| Specialty Retail Channel Partnership | REI and Decathlon trained floor staff displace impulse-channel distribution for premium transactions. |
| Lithium-Polymer Supply Integration | In-house battery chemistry control captures margin pools from disposable fuel-based products. |
| Emergency Preparedness SKU Development | Survival kit distributors create dedicated waterproof product lines with extended shelf-life formulations. |
Methodological Framework
The analysis maps disposable fuel-based, USB rechargeable, metal refillable, and arc plasma ignition sub-sectors, each validated through category buyers at REI and Decathlon, procurement leads at component distributors, plant managers in Guangdong stamping facilities, and regulatory affairs specialists at SAMR. Primary interviews combined with secondary validation from customs records, ECHA substance restriction databases, and FCC Part 15 filing logs. Bottom-up unit shipment estimates triangulated against top-down value aggregation.
Consistency checks against IEA energy transition benchmarks and outdoor recreation participation databases validated volume assumptions across the projection horizon. Segmentation modeled by product architecture, material compliance tier, application specificity, and end-user sophistication. CAGRs derived from regression analysis of historical price elasticities and forward regulatory cost impacts. Forecast inputs incorporated lithium-polymer cost curves and REACH polymer substitution timelines.
Underlying assumptions cover stable IATA lithium-ion shipping protocols and continued ECHA enforcement stringency, with deviation risk concentrated in battery transportation rule amendments and dual carbon mandate acceleration. Practitioners should keep alternative scenarios live as SAMR GB standards implementation timelines and Southeast Asian labor cost trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smoking Accessories
Pocket Flask Market
Smoking Accessories
Smoking Pipe Market
Smoking Accessories
North America Smoking Pipe Market
Smoking Accessories
Pod Vape Market
Smoking Accessories
Herb Grinder Market
Smoking Accessories
Smart E-Cigarettes Market
Smoking Accessories
Wearable Tailgating Keg Market
Smoking Accessories
Electric Pocket Lighter Market
Smoking Accessories
Smart Ashtray Market
Smoking Accessories
Smoking Accessories Market
Smoking Accessories
Hookah Products Market
Smoking Accessories
Ashtray Market
Smoking Accessories
United States Cigarette Lighter Market
Smoking Accessories
China Smoking Pipe Market
Smoking Accessories
Cigarette Lighter Market
Smoking Accessories
North America Cigarette Lighter Market