
 Ultra-Portable Speakers Market | 2026-2036
Ultra-Portable Speakers Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra-Portable Speakers Market Outlook
Modular accessory bundling is repositioning how consumers evaluate ultra-portable speakers, shifting purchase criteria from standalone audio quality to ecosystem compatibility. JBL leverages its waterproof IP67-rated portfolio to dominate beach and hiking retail channels. Sony sustains premium positioning through proprietary spatial audio codecs and high-resolution Bluetooth streaming.
Ultra-portable speakers are compact, battery-operated audio reproduction devices typically weighing under 500 grams, employing neodymium drivers and lithium-polymer cells to deliver 5–20 watts of output for personal or small-group listening in mobile environments. Bluetooth speakers anchor the volume base due to universal smartphone compatibility and declining component costs. Smart speakers represent the fastest-expanding margin pool as voice-assistant integration commands price premiums. Solar-powered speakers remain nascent but attract sustainability-focused outdoor buyers seeking off-grid functionality.
FCC certification requirements govern wireless transmission standards in the United States, while CE marking and the EU RoHS directive restrict hazardous substances in European-sold electronics. Japan's METI enforces energy-efficiency benchmarks that shape battery and charging circuit design for export-bound manufacturers. Stakeholders must monitor evolving right-to-repair legislation across multiple jurisdictions as durability and serviceability become competitive differentiators.
Market Dynamics
The EU Green Deal's right-to-repair mandates are forcing manufacturers to redesign chassis architectures for battery accessibility and component modularity, fundamentally altering cost structures and supplier relationships across the ultra-portable speaker value chain.
Growth Catalysts
- Outdoor recreation participation:Hiking, camping, and beach activities in the United States, China, and Germany are pulling demand for IP67-rated waterproof units with extended battery life.
- RoHS directive compliance:European hazardous substance restrictions are accelerating lead-free solder and recycled plastic adoption, creating first-mover advantages for compliant suppliers.
- Bluetooth Low Energy 5.3:Reduced power draw and improved range are enabling smaller form factors without sacrificing playback duration, opening new wearable and clip-on categories.
Market Restraints
- Lithium-polymer cell concentration:Cathode material sourcing bottlenecks in China create input cost volatility and supply security exposure for non-integrated assemblers.
- Neodymium magnet dependence:Rare earth processing concentration in Inner Mongolia generates price instability and geopolitical risk for driver manufacturers.
- FCC certification timelines:Radio frequency testing backlogs in the United States extend product launch windows by 8-14 weeks, compressing seasonal selling periods.
Strategic Opportunities
- India's PLI scheme:Electronics manufacturing incentives are attracting assembly capacity to Gujarat and Tamil Nadu, creating export hubs for Middle East and African markets.
- Solar-integrated off-grid units:Photovoltaic panel miniaturization converging with power management ICs is opening wilderness expedition and emergency preparedness applications.
- Voice-assistant licensing:Alexa and Google Assistant integration protocols are enabling premium pricing in smart speaker sub-segments without proprietary R&D investment.
Industry Challenges
- Acoustic engineering talent scarcity:Compact enclosure design expertise for neodymium driver optimization concentrates in Denmark, Japan, and California, constraining new entrant capability building.
- IP codec licensing complexity:Sony LDAC, Qualcomm aptX, and AAC patent pools create royalty stacking and regional compatibility fragmentation for streaming protocol support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra-Portable Speakers Market |
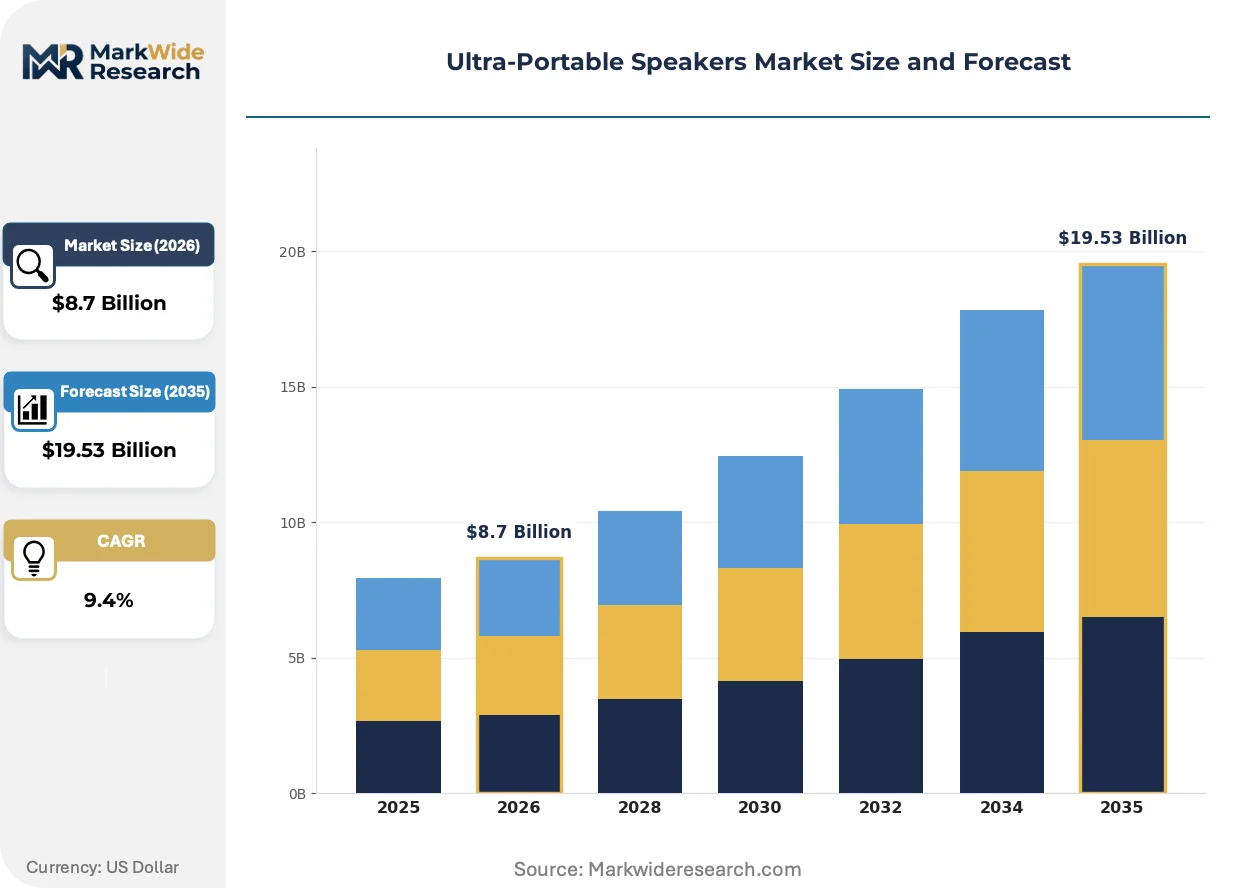
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bluetooth Speakers, Wired Speakers, Smart Speakers, Solar-Powered Speakers Use Case: Outdoor Activities, Home Use, Travel, Events Power Source: Battery-Powered, USB-C, Solar, AC Adapter Connectivity: Bluetooth, NFC, Wi-Fi, AUX |
| Companies Covered | Sony, Marshall, JBL, Bowers & Wilkins, Sonos, Ultimate Ears, Anker Soundcore, PartyBox, Bose, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra-Portable Speakers Market Strategic Shifts
Spatial audio rendering algorithms and AI-driven adaptive equalization are compressing the performance gap between compact portable units and larger stationary systems, redefining consumer quality expectations at sub-500-gram weights.
Spatial audio codecs are expanding into mainstream ultra-portable speaker firmware as a differentiator against basic stereo competitors. Outdoor enthusiasts and remote workers are adopting head-tracking-enabled models for immersive conferencing and entertainment. This capability is expanding into mid-tier price bands previously reserved for basic Bluetooth streaming, compressing premium positioning windows for legacy brands.
The EU Green Deal's right-to-repair legislation is mandating standardized screw patterns, battery connector accessibility, and spare parts availability for seven-year minimum lifespans. Manufacturers serving European distribution channels are redesigning unibody enclosures into modular sub-assemblies with user-replaceable lithium-polymer cells. This regulatory pressure is expanding into voluntary durability certifications in Germany and France, influencing product development roadmaps eighteen to twenty-four months ahead of formal enforcement dates.
Specialty audio retailers are losing share to direct-to-consumer brand sites and Amazon storefronts as warranty registration and firmware update ecosystems build stickier manufacturer-customer relationships. Younger buyers in the United States and China research IP ratings and codec support tables online before store visits, collapsing the traditional demonstration-driven purchase funnel. This channel compression is most visible in urban coastal markets where same-day delivery logistics outperform mall-based electronics chains for impulse outdoor gear purchases.
Ultra-Portable Speakers Market Segmentation
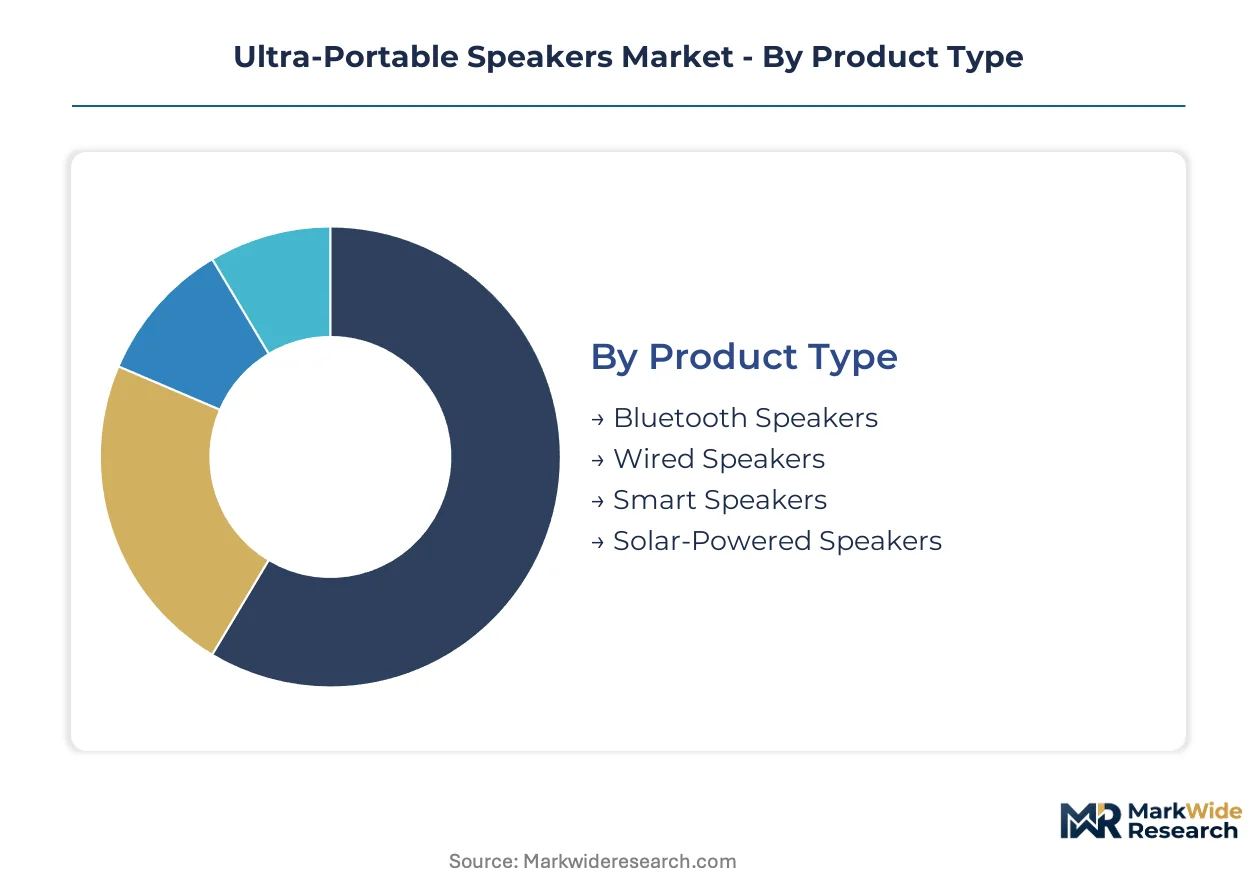
Segmentation in ultra-portable speakers reveals distinct engineering trade-offs between standalone functionality and ecosystem integration. Each dimension—product architecture, use environment, power delivery, and connectivity protocol—creates divergent margin profiles and supplier requirements.
Product Type:
Bluetooth speakers anchor the volume base as standalone units requiring no companion infrastructure, while smart speakers embed voice-assistant modules demanding persistent cloud connectivity.
- Bluetooth Speakers:These units leverage universal smartphone compatibility and declining component costs to dominate mass-market channels. IP67-rated waterproof variants pull demand from hiking and beach activities in the United States and Germany.
- Smart Speakers:Voice-assistant integration commands price premiums through Alexa and Google Assistant licensing protocols. Firmware update ecosystems build stickier manufacturer-customer relationships than basic audio hardware.
- Wired Speakers:AUX-dependent units serve latency-sensitive applications and budget-conscious buyers in emerging markets.
- Solar-Powered Speakers:Photovoltaic panel miniaturization attracts sustainability-focused outdoor buyers seeking off-grid functionality for wilderness expeditions.
Bluetooth speakers lead volumes today; smart speakers are climbing the fastest.
Use Case:
Cost-tier stratification separates premium positioning for stationary home environments from ruggedized designs for mobile outdoor deployment.
- Outdoor Activities:Hiking, camping, and beach recreation in China and Germany pull demand for neodymium-driver units with extended lithium-polymer battery life. FCC certification timelines for radio frequency testing compress seasonal selling periods for United States-bound inventory.
- Home Use:Spatial audio rendering algorithms and AI-driven adaptive equalization compress the performance gap between compact units and larger stationary systems.
- Travel:Sub-500-gram form factors with clip-on accessories target business travelers and digital nomads in urban coastal markets.
- Events:Daisy-chain capable units serve small-group gatherings where multiple speaker synchronization replaces single high-wattage systems.
Outdoor activities command the highest ASPs; home use generates the largest absolute revenue pool.
Power Source:
Maturity gradients separate established lithium-polymer architectures from emerging solar-integrated designs requiring power management IC innovation.
- Battery-Powered:Lithium-polymer cells deliver 5–20 watts of output through neodymium drivers, though cathode material sourcing bottlenecks in China create input cost volatility.
- USB-C:Unified charging standards reduce cable fragmentation and enable faster replenishment cycles for mobile users.
- Solar:Photovoltaic miniaturization converges with efficient power management to open emergency preparedness applications.
- AC Adapter:Tethered designs persist in price-sensitive segments where battery cost elimination outweighs portability loss.
Battery-powered configurations dominate unit economics; solar integration shows the steepest expansion trajectory.
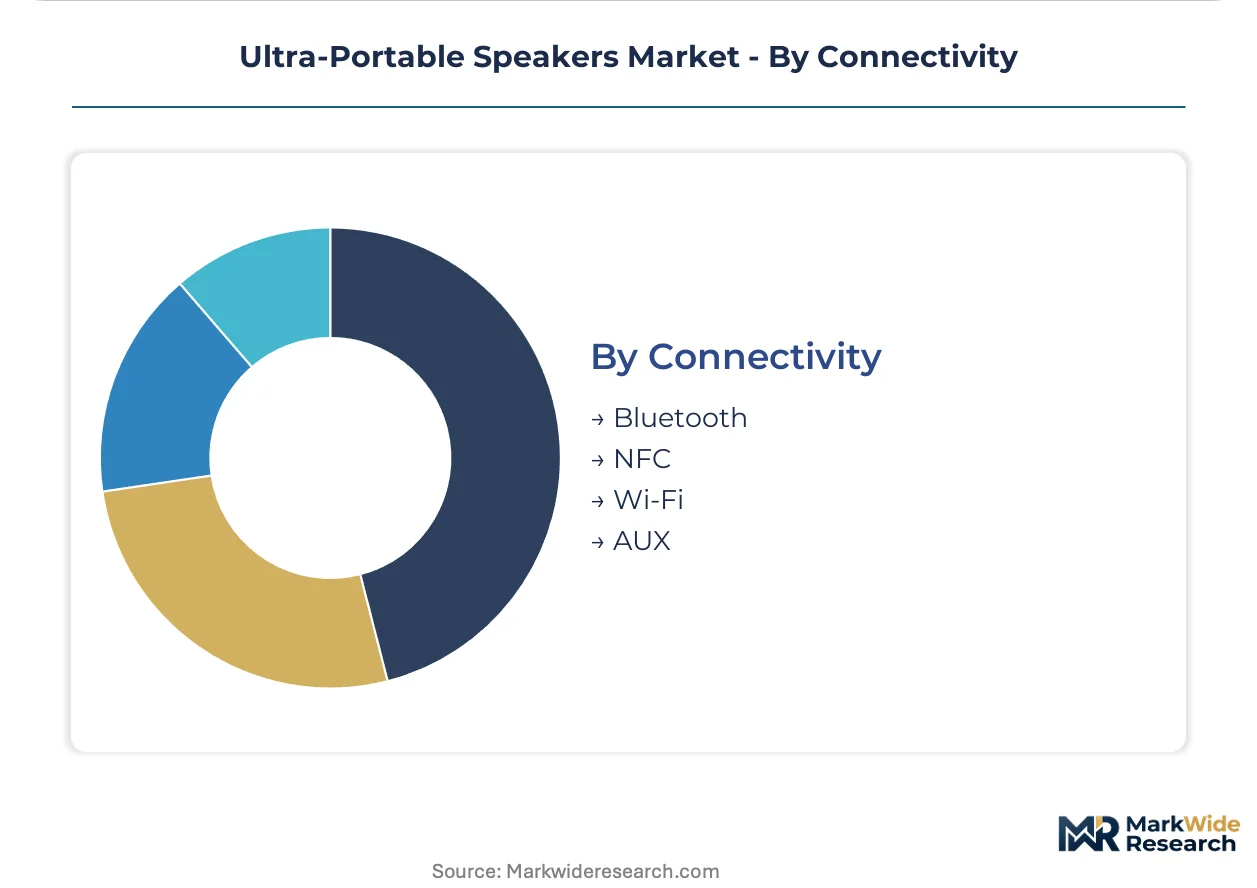
Connectivity:
Protocol selection determines codec licensing burdens and regional compatibility fragmentation for streaming support.
- Bluetooth:Bluetooth Low Energy 5.3 reduces power draw and improves range, enabling smaller form factors without sacrificing playback duration. Sony LDAC, Qualcomm aptX, and AAC patent pools create royalty stacking complexity.
- Wi-Fi:Higher bandwidth protocols support high-resolution streaming and multi-room synchronization for home network environments.
- NFC:Tap-to-pair functionality streamlines initial setup for non-technical users in premium tier positioning.
- AUX:Analog fallback ensures compatibility with legacy source devices and eliminates wireless interference concerns.
Bluetooth anchors universal adoption; Wi-Fi connectivity is gaining share fastest in premium tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portable audio manufacturing scaled through Japanese precision electronics in the 1980s before Korean and Chinese firms captured mass-market assembly. Today's demand geography reflects outdoor recreation participation, right-to-repair regulatory exposure, and voice-assistant ecosystem penetration across distinct national markets.
United States
Hiking and beach recreation drive IP67-rated waterproof unit demand across California and Florida coastal markets. FCC certification timelines for radio frequency testing extend product launch windows by 8-14 weeks, compressing seasonal selling periods. Austin and Seattle host firmware development clusters for voice-assistant integration protocols.
Germany
EU Green Deal right-to-repair mandates force chassis redesign for battery accessibility and seven-year spare parts availability. Berlin and Munich engineering centers concentrate acoustic optimization talent for neodymium driver enclosures. Voluntary durability certifications in France and Germany influence product roadmaps eighteen to twenty-four months ahead of formal enforcement.
China
Domestic outdoor recreation participation and export manufacturing capacity coexist in Shenzhen and Dongguan electronics corridors. MIIT enforces GB standards for wireless transmission and battery safety that shape designs for Middle East and African export markets. Cathode material sourcing bottlenecks for lithium-polymer cells create input cost volatility for non-integrated assemblers.
India
PLI scheme electronics manufacturing incentives attract assembly capacity to Gujarat and Tamil Nadu for Middle East and African export hubs. BIS certification requirements govern wireless product safety and electromagnetic compatibility. Mumbai and Bangalore retail channels show channel compression toward direct-to-consumer brand sites and Amazon storefronts.
Japan
METI energy-efficiency benchmarks shape battery and charging circuit design for export-bound manufacturers. Kanto region acoustic engineering expertise concentrates compact enclosure design capability for neodymium driver optimization. Spatial audio rendering algorithms and head-tracking-enabled models command premium positioning in domestic and Asian export markets.
Ultra-Portable Speakers Market Competitive Environment
Premium-margin players sit above commodity-margin players across codec licensing and spatial audio capability. The vendor base stratifies into three tiers: heritage audio houses with proprietary driver technology, consumer electronics conglomerates leveraging ecosystem integration, and direct-to-consumer challengers optimizing Amazon storefront algorithms. Consolidation pressure operates through voice-assistant licensing protocols rather than manufacturing scale. Dominant competitive moves include M&A for acoustic engineering talent and strategic partnerships for solar-integrated power management ICs.
Within the heritage audio tier, Sony and Bowers & Wilkins exemplify proprietary codec differentiation. Marshall occupies a position linking lifestyle branding with premium-tier positioning. JBL represents the consumer electronics conglomerate archetype through waterproof IP67 portfolio breadth and beach-hiking retail channel dominance. Anker Soundcore anchors the direct-to-consumer challenger model. Ultimate Ears and Bose sit within specialist outdoor-audio positioning. Sonos exemplifies ecosystem-integrated smart speaker architecture.
| Leading Market Players |
|---|
| Sony |
| Marshall |
| JBL |
| Bowers & Wilkins |
| Sonos |
| Ultimate Ears |
| Anker Soundcore |
| PartyBox |
| Bose |
| Others |
Value Chain & Pricing Dynamics
Certification-grade stratification between IP67-rated outdoor units and basic indoor speakers splits both pricing power and sourcing configurations across the ultra-portable speaker market. Premium tiers command margin buffers through neodymium driver optimization and proprietary codec licensing, while commodity tiers compete on lithium-polymer cell cost and Shenzhen assembly velocity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels anchors the competitive landscape. Premium positioning draws from Sony LDAC and Qualcomm aptX codec licensing alongside spatial audio firmware, while economy tiers sacrifice waterproof certification and battery cycle ratings. Pricing pressure stems from cathode material volatility in Chinese lithium-polymer supply chains, compressing assembler margins. Outdoor recreation buyers in Germany and the United States show lowest price sensitivity, prioritizing IP67 ratings and extended playback duration over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Los Angeles, and Singapore orchestrate hub-and-spoke fulfillment for seasonal outdoor retail surges. Manufacturing concentrates in Shenzhen and Dongguan for PCB assembly, with neodymium magnet sourcing tethered to Inner Mongolia rare earth processing. Cathode material bottlenecks in Chinese lithium-polymer production create single-source vulnerability for non-integrated brands. Distribution runs through direct-to-consumer brand sites and Amazon storefronts, collapsing traditional electronics retail margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ultra-portable speaker market functions as a regulatory compounder where EU Green Deal right-to-repair mandates are restructuring product architecture roadmaps and supplier qualification requirements eighteen to twenty-four months ahead of enforcement.
For Market Incumbents: To counter direct-to-consumer challengers eroding beach-hiking retail channels, JBL and Sony should deepen firmware update ecosystem stickiness through voice-assistant licensing partnerships. Backward integration into neodymium driver enclosure design in Denmark and California acoustic engineering clusters protects premium positioning against codec royalty stacking. For New Entrants and Emerging Players: The $40-80 price-point gap between premium smart speakers and economy Bluetooth units offers white-space entry through solar-integrated off-grid designs targeting wilderness expedition buyers. India's PLI scheme assembly incentives in Gujarat create manufacturing footprint for Middle East and African export markets. Go-to-market traction depends on Amazon storefront algorithm optimization for IP67 and codec specification search terms. For Investors and Strategic Acquirers: Consolidation pressure builds where voice-assistant licensing protocols concentrate margin capture among Alexa and Google Assistant ecosystem partners. Long-term viability favors acoustic engineering talent pools in Kanto and Copenhagen over pure assembly capacity. Watch solar-integrated power management IC partnerships as inflection signals for off-grid category expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Voice-Assistant Licensing Agreement | Alexa and Google Assistant protocols enable premium pricing without proprietary R&D investment. |
| Acoustic Engineering Talent Acquisition | Denmark and Japan expertise in neodymium driver optimization constrains new entrant capability building. |
| Solar-Integrated Product Line Launch | Photovoltaic miniaturization opens wilderness expedition and emergency preparedness applications. |
| Right-to-Repair Design Transition | EU Green Deal mandates modular chassis redesign for seven-year battery accessibility. |
| Direct-to-Consumer Channel Expansion | Amazon storefront algorithms outperform mall-based electronics chains for impulse outdoor gear purchases. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with acoustic engineering directors, lithium-polymer procurement leads, outdoor retail category managers, and FCC certification consultants with secondary validation. Customs records, CE marking databases, RoHS compliance filings, and Bluetooth SIG certification registries anchored supply-side triangulation. Bottom-up assembly capacity estimates and top-down retail audit data converged for volume reconciliation.
Comparable historical periods anchored the forecast window to pre-pandemic outdoor recreation participation baselines and post-regulatory announcement product development cycles. Segmentation dimensions spanned product architecture, use environment, power delivery, and connectivity protocol, with codec licensing burden and waterproof certification tier as industry-specific variables. CAGRs derived from shipment trajectory modeling against lithium-polymer cell cost curves and voice-assistant penetration assumptions.
Caveats apply where cathode material sourcing disruptions or FCC certification timeline extensions could materially shift the outlook. Forecasts reflect documented assumptions around right-to-repair enforcement calendars and Bluetooth Low Energy adoption velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Stress Ball Market
Consumer Electronics
Portable Speaker Market
Consumer Electronics
Gaming Laptops and Desktops Market
Consumer Electronics
Learning Remote Controls Market
Consumer Electronics
Foldable Phone Market
Consumer Electronics
Waterproof Bathroom TV Market
Consumer Electronics
Global Automated Laundromat Services Market
Consumer Electronics
Consumer Electronics Repair and Maintenance Market
Consumer Electronics
Screen Privacy Protectors Market
Consumer Electronics
Global Home Audio System Market
Consumer Electronics
Asia-Pacific Refurbished and Used Mobile Phones Market
Consumer Electronics
Consumer Electronics Market
Consumer Electronics
Global Bluetooth Mono Earpieces Market
Consumer Electronics
Smart Home Projector Market
Consumer Electronics
Portable Media Player Market
Consumer Electronics
Headphones Market