
 Vaporizer Market | 2026-2036
Vaporizer Market Size, Share, and Industry Trends Forecast 2026-2036
Vaporizer Market Analysis
The EU Green Deal is realigning material sourcing requirements across inhalation device supply chains. Pax Labs Inc. leverages ceramic heating element R&D to sustain compliance with evolving emissions standards. Storz & Bickel GmbH & Co. KG anchors the medical-grade segment through German pharmacy distribution channels. Greenlane Holdings Inc. competes on North American wholesale scale while navigating state-level packaging and testing mandates.
A vaporizer is an electronic or thermal device engineered to heat plant material, concentrates, or formulated liquids to temperatures sufficient for active compound release without combustion, typically operating between 150°C and 230°C with precision thermocouple or convection-based temperature control. Portable units dominate unit volume due to battery miniaturization and discreet form factors, while desktop systems command margin pools in connoisseur and clinical settings where power stability and vapor density are prioritized. Concentrates-compatible hardware is the fastest-growing material configuration as extraction technology improves resin purity and consumer preference shifts toward higher-potency formats.
The FDA regulates tobacco-derived vapor products through premarket tobacco product application requirements, while the EU Tobacco Products Directive mandates nicotine concentration limits and emissions disclosure for cross-border sales. Germany's BfArM oversees medical cannabis vaporizer registration as Class I medical devices, creating a dual-track compliance burden for manufacturers serving both wellness and clinical channels. Stakeholders must monitor how state-level THC potency caps and flavor restrictions in jurisdictions like Colorado and Massachusetts reshape product development roadmaps and channel eligibility.
Market Dynamics
The EU Tobacco Products Directive revision is consolidating emissions testing protocols while medical cannabis frameworks in Germany and Australia expand the addressable patient base for clinical-grade hardware. Battery miniaturization and ceramic heating element advances are compressing the performance gap between portable and desktop form factors.
Growth Catalysts
- Medical cannabis program expansion:Germany's BfArM registration pathway for Class I medical devices creates pharmacy distribution access for precision temperature-control units. Patient enrollment growth drives clinical-grade hardware procurement.
- EU Green Deal material mandates:REACH-aligned sourcing requirements for heating elements and battery housings are accelerating supply chain reconfiguration toward compliant ceramic and stainless steel suppliers.
- Concentrate extraction technology:Improved resin purity from hydrocarbon and solventless methods is expanding demand for compatible hardware configurations across California's regulated dispensary network.
Market Restraints
- Lithium-ion battery cost volatility:Raw material price swings for cobalt and nickel feed directly into portable unit bill-of-materials, compressing margin pools for mid-tier manufacturers without captive cell supply.
- Dual-track compliance burden:Hardware serving both wellness and medical channels must satisfy FDA premarket tobacco product application requirements alongside BfArM medical device registration, extending time-to-market.
- Desktop unit substitution pressure:Battery technology improvements and convection heating advances in portable form factors are eroding the power stability advantage of plug-in systems for connoisseur segments.
Strategic Opportunities
- Australian medical cannabis access expansion:TGA regulatory streamlining for unapproved therapeutic goods is opening pharmacy and specialist clinic channels for prescription vaporizer distribution.
- EU Tobacco Products Directive emissions disclosure:Mandated testing and reporting requirements create competitive differentiation for manufacturers with existing laboratory infrastructure and ceramic heating expertise.
- Subscription-based hardware models:Device-plus-consumable bundling through direct-to-patient platforms in Germany's pharmacy network locks in recurring revenue and reduces price sensitivity.
Industry Challenges
- Thermocouple calibration expertise scarcity:Precision temperature control engineering for medical-grade applications requires specialized skill sets concentrated among German and Swiss component suppliers.
- Cross-border testing documentation:Harmonizing emissions data across FDA, BfArM, and TGA submission requirements demands redundant laboratory validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vaporizer Market |
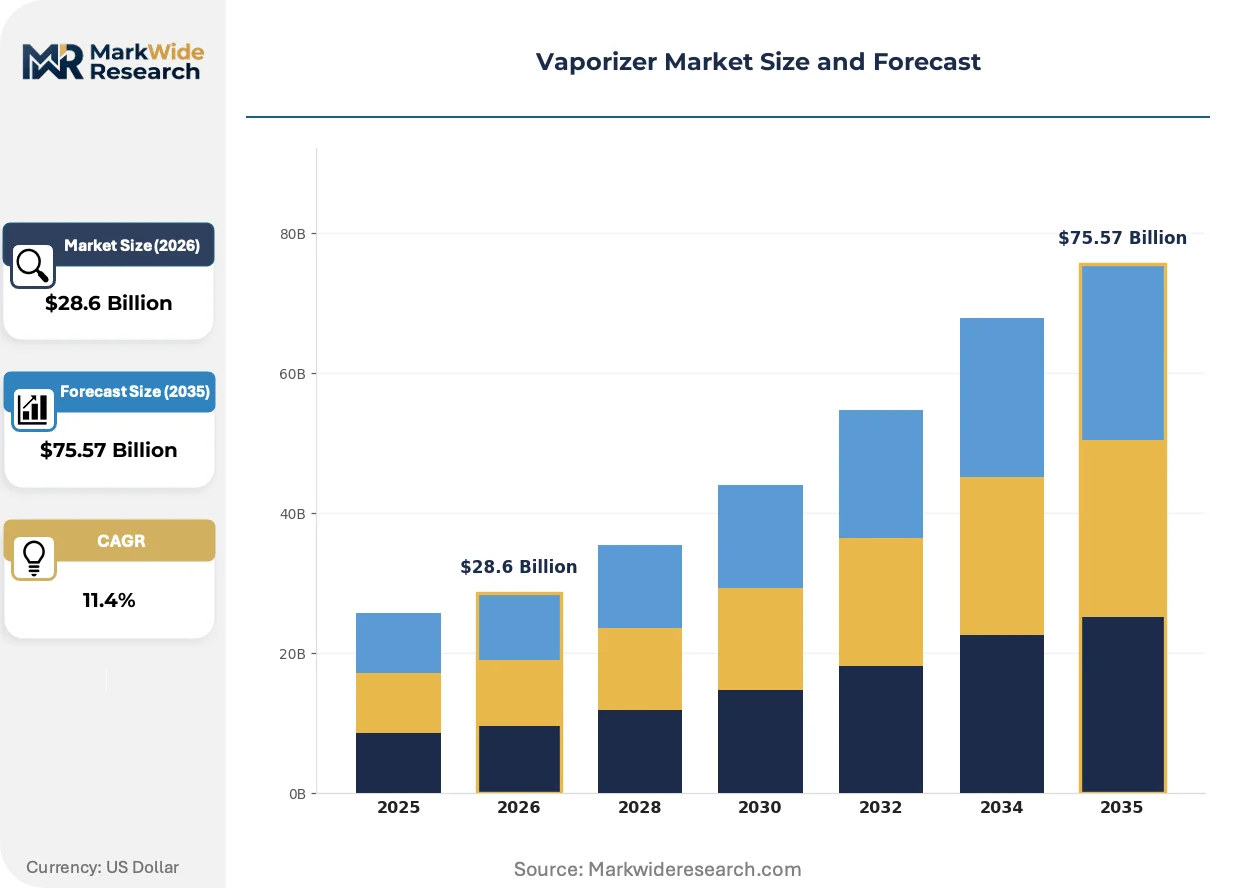
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Desktop, Pen, Pod Material: Dry Herb, Concentrates, E-Liquid, Wax End User: Adult Consumers, Medical Users, Recreational Users, Retailers Distribution Channel: Online Retail, Specialty Stores, Dispensaries, Supermarkets |
| Companies Covered | Firefly Vapor LLC, Greenlane Holdings Inc., Vuber Technologies, Dip Devices Inc., Chief Botanicals Inc., Pax Labs Inc., Storz & Bickel GmbH & Co. KG, Vivant Inc., Dr. Dabber Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vaporizer Market Emerging Trajectories
Ceramic heating element architectures are displacing traditional metal coil designs as manufacturers prioritize emissions compliance and thermal efficiency. Convection-based temperature control systems are consolidating market share across both wellness and clinical segments.
Alumina ceramic heating chambers are consolidating as the dominant thermal management solution for medical-grade hardware. German pharmacy distributors specify ceramic components to satisfy BfArM emissions thresholds for Class I device registration. This material shift is consolidating supplier relationships around REACH-certified ceramic foundries with existing pharmaceutical equipment track records.
The EU Tobacco Products Directive revision mandates standardized emissions testing and nicotine concentration disclosure for cross-border sales of electronic inhalation devices. Manufacturers must submit aerosol constituent data to national competent authorities before market placement. Portable concentrate-compatible units face the steepest compliance burden due to higher thermal output and variable resin formulations.
Patient acquisition through licensed pharmacy channels is displacing direct-to-consumer wellness marketing in Germany's medical cannabis framework. Prescription validation requirements and insurance reimbursement pathways favor hardware vendors with BfArM-registered devices and established pharmacy distribution contracts. This channel consolidation is most visible in North Rhine-Westphalia and Bavaria, where dispensary density supports localized patient education and device fitting services.
Vaporizer Market Segmentation
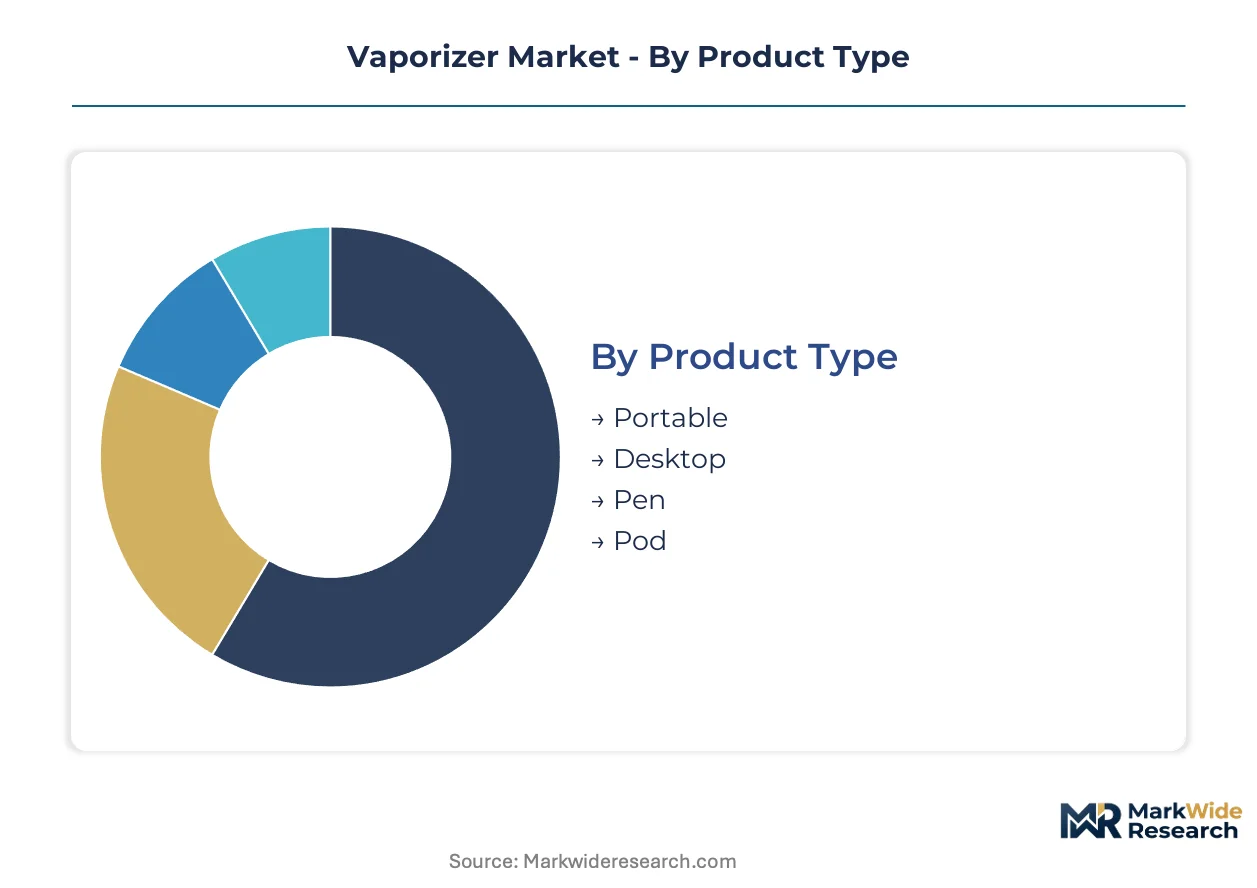
Segmentation in the vaporizer market reflects divergent compliance burdens and thermal engineering requirements across wellness, clinical, and adult-use channels. Manufacturers configure heating element architectures, battery specifications, and temperature control precision differently depending on whether devices target pharmacy distribution, dispensary retail, or direct-to-consumer e-commerce.
Product Type:
Buyers differentiate primarily by power stability needs versus portability constraints, with battery miniaturization narrowing the performance gap between mobile and stationary formats.
- Portable:Battery-powered units with ceramic heating chambers and precision thermocouple control dominate unit volume. Demand concentrates in California's regulated dispensary network where discreet form factors and session customization drive turnover among adult-use consumers.
- Desktop:Plug-in systems with convection heating and power-optimized vapor density command premium positioning in connoisseur and clinical settings. German pharmacy channels prioritize these units for patient home-use prescriptions requiring consistent temperature stability.
- Pen:Slim cylindrical designs with integrated batteries target concentrate compatibility and ultra-portability. Ease of concealment supports adoption across recreational markets with strict public consumption restrictions.
- Pod:Closed-system cartridges with proprietary battery interfaces emphasize convenience and dosing consistency. Pre-filled formats align with medical user preferences for standardized cannabinoid delivery.
Volume sits with Portable; growth tilts toward Pod configurations as pharmacy channels standardize prescription formats.
Material:
Material selection determines heating chamber engineering, emissions profiles, and regulatory classification pathways for manufacturers.
- Dry Herb:Whole-flower vaporization requires convection or conduction heating between 180°C and 210°C with grind-size optimization. German medical cannabis programs specify dry herb compatibility for insurance-reimbursed devices.
- Concentrates:Resin and extract vaporization demands higher thermal output and specialized chamber geometries. Australia's expanding TGA framework drives clinical-grade concentrate hardware procurement for chronic pain management protocols.
- E-Liquid:Nicotine and non-nicotine formulations utilize wick-based coil systems subject to EU Tobacco Products Directive emissions disclosure. Cross-border sales require standardized aerosol constituent testing.
- Wax:Semi-solid extract formats necessitate dab-tool loading and quartz or ceramic nail configurations. California dispensary density supports specialized accessory ecosystems for wax-compatible hardware.
Revenue concentrates in Dry Herb; steepest expansion trajectory belongs to Concentrates as extraction purity advances.
End User:
End user categories reflect fundamentally different purchasing authorization requirements, reimbursement pathways, and device performance expectations.
- Adult Consumers:Wellness-oriented buyers seeking controlled compound delivery without combustion. California and Colorado state regulations shape product availability and potency disclosure requirements.
- Medical Users:Prescription-validated patients requiring BfArM-registered Class I devices with documented temperature precision. Germany's pharmacy network provides the primary procurement channel with insurance reimbursement for qualifying conditions.
- Recreational Users:Adult-use purchasers in regulated markets prioritizing discretion, session control, and social consumption compatibility. State-level flavor and potency restrictions in Massachusetts and Colorado constrain hardware configuration options.
- Retailers:Dispensary and specialty store operators procuring inventory for resale, with compliance documentation requirements varying by jurisdiction. German pharmacy distributors demand batch-level emissions testing certificates.
Procurement volume clusters with Adult Consumers; margin expansion favors Medical Users through device-plus-consumable subscription models.
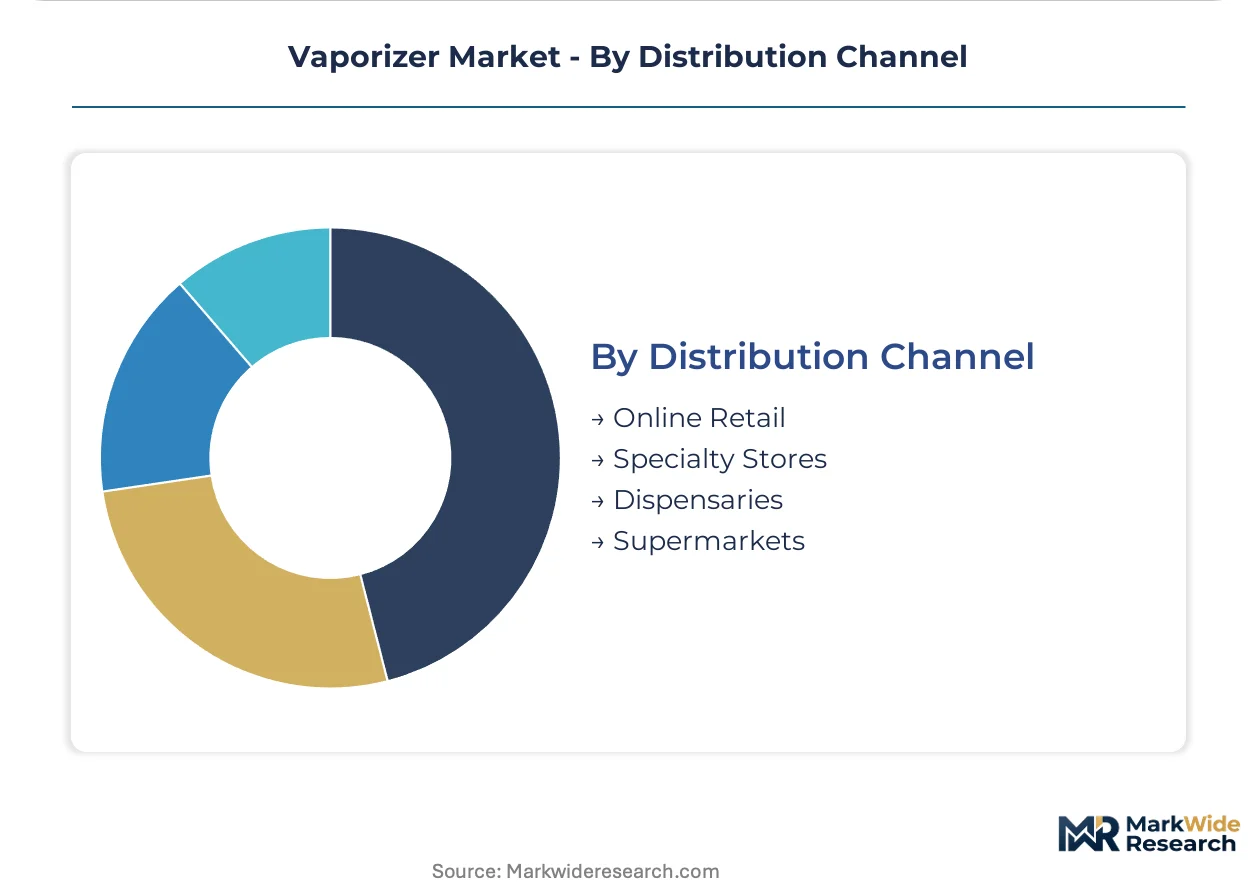
Distribution Channel:
Channel selection determines regulatory exposure, customer education requirements, and inventory turnover velocity for hardware manufacturers.
- Online Retail:Direct-to-consumer and marketplace platforms enabling geographic reach with age verification and shipping compliance burdens. EU cross-border sales require national competent authority notification under Tobacco Products Directive protocols.
- Specialty Stores:Head shops and wellness retailers providing hands-on demonstration and accessory bundling. Staff training requirements concentrate in jurisdictions with complex product classification rules.
- Dispensaries:Licensed cannabis retailers in California, Colorado, and Massachusetts offering regulated product adjacencies. Channel density in Los Angeles and San Francisco supports premium portable unit placement.
- Supermarkets:Mass-market retail for nicotine vapor products with standardized packaging and placement restrictions. Limited penetration for cannabis-compatible hardware due to federal scheduling conflicts.
Turnover velocity peaks in Dispensaries; regulatory compliance investment concentrates in Online Retail for multi-jurisdiction operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates medical-grade device production while the United States absorbs the largest volume of adult-use portable units. Australia's patient enrollment expansion and California's dispensary density create divergent demand profiles across wellness and clinical channels.
United States
California's regulated dispensary network and Colorado's potency disclosure mandates drive premium portable turnover. FDA premarket tobacco product application requirements filter hardware serving nicotine-adjacent channels. Los Angeles and San Francisco cluster channel density that supports discreet form factor adoption among adult-use consumers.
Germany
BfArM Class I medical device registration creates pharmacy distribution access for precision temperature-control hardware. Insurance reimbursement pathways for qualifying conditions anchor procurement through licensed pharmacy networks. North Rhine-Westphalia and Bavaria concentrate patient education and device fitting services.
Australia
TGA regulatory streamlining for unapproved therapeutic goods expands specialist clinic channels for prescription vaporizer distribution. Chronic pain management protocols drive clinical-grade concentrate hardware procurement. Sydney and Melbourne anchor pharmacy network expansion for patient acquisition.
Canada
Health Canada oversight of cannabis vapor products shapes emissions documentation requirements for cross-provincial distribution. Provincial retail monopolies and private dispensary licensing create channel fragmentation. Ontario and British Columbia concentrate distribution infrastructure for both medical and adult-use segments.
United Kingdom
MHRA medical device registration and evolving CBD regulatory clarity shape hardware import and distribution pathways. Pharmacy channel access remains constrained by prescription cannabis availability limits. London concentrates wellness-oriented retail and specialist clinic presence for device demonstration.
Vaporizer Market Vendor Landscape
The competitive structure tilts toward specialized medical-grade manufacturers with ceramic heating expertise. Consolidation pressure concentrates among mid-tier portable producers facing lithium-ion cost volatility and dual-track compliance burdens. Three archetypes dominate: German-engineered clinical specialists, California-rooted wellness brands, and North American wholesale distributors. Capacity expansion and strategic pharmacy distribution partnerships represent the primary competitive moves.
Among German-engineered clinical specialists, Storz & Bickel GmbH & Co. KG exemplifies the medical-grade archetype through pharmacy channel anchoring. Pax Labs Inc. occupies a position within the wellness-oriented portable segment. Greenlane Holdings Inc. represents the wholesale scale archetype navigating state-level compliance mandates.
| Leading Market Players |
|---|
| Firefly Vapor LLC |
| Greenlane Holdings Inc. |
| Vuber Technologies |
| Dip Devices Inc. |
| Chief Botanicals Inc. |
| Pax Labs Inc. |
| Storz & Bickel GmbH & Co. KG |
| Vivant Inc. |
| Dr. Dabber Inc. |
| Others |
Supply Flow & Price Mechanics
Thermocouple calibration engineers concentrated in southern Germany and the Swiss cantons of Zurich and Basel-Stadt command wage premiums that cascade into medical-grade device pricing spreads. Labor-cost differentials between these precision-temperature clusters and Asian electronics manufacturing regions sustain a three-tier pricing structure across premium, standard, and economy levels.
Pricing Analysis
Margin tightening in mid-tier portable units reflects lithium-ion battery cost volatility and dual-track compliance burdens for FDA and BfArM submissions. Pricing stratifies across premium, standard, and economy tiers based on ceramic heating element certification grade and pharmacy channel access. Cost compression accelerates in standard-tier hardware as cobalt and nickel feedstock swings compress bill-of-materials predictability. Adult consumers in California dispensaries exhibit highest price sensitivity; German medical users with insurance reimbursement pathways show lowest sensitivity.
Supply Chain Analysis
REACH-certified ceramic foundry qualification gates supplier relationships for medical-grade heating chambers. Component sourcing concentrates in Germany, China, and Switzerland for precision thermocouples, battery cells, and alumina ceramics respectively. Raw material dependencies include cobalt-nickel cathode formulations, high-purity alumina powder, and medical-grade stainless steel housings. Single-source vulnerability sits with Swiss-German thermocouple calibration expertise. Distribution runs through pharmacy networks in Germany, licensed dispensaries in California and Colorado, and direct-to-consumer platforms with age-gating infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in this market hinges on vertical-integration races upstream into ceramic heating element production and downstream into pharmacy distribution contracts. Players securing captive supply of REACH-certified alumina and BfArM registration pathways are consolidating margin pools.
For Market Incumbents: Extend ceramic heating element R&D capabilities to satisfy tightening EU Tobacco Products Directive emissions thresholds. Deepen pharmacy distribution partnerships in North Rhine-Westphalia and Bavaria to lock in patient acquisition channels. Battery cost volatility and portable unit substitution pressure threaten mid-tier positioning without upstream ceramic supply control. For New Entrants and Emerging Players: Convection-based temperature control algorithms offer a technology-first wedge against established conduction-dominant portfolios. Target Australia's TGA-streamlined specialist clinic channels where patient enrollment expansion outpaces incumbent pharmacy coverage. Pursue direct-to-patient subscription models with device-plus-consumable bundling to bypass dispensary slotting fee barriers. For Investors and Strategic Acquirers: The window for entry favors German-engineered clinical specialists with existing BfArM registrations and ceramic foundry relationships. Long-term viability rests on dual-track compliance infrastructure spanning FDA premarket tobacco pathways and EU medical device frameworks. Watch TGA regulatory streamlining velocity as inflection indicator for Asia-Pacific clinical-grade hardware demand.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Heating Element Backward Integration | Captive alumina supply secures REACH compliance and BfArM emissions thresholds for medical-grade registration. |
| Pharmacy Distribution Partnership Expansion | Licensed pharmacy access in Germany anchors insurance-reimbursed patient acquisition and recurring revenue. |
| Dual-Track Regulatory Submission Investment | Parallel FDA and BfArM pathways extend addressable market across wellness and clinical channels simultaneously. |
| Convection Temperature Control R&D | Advanced thermal management erodes desktop unit power stability advantages and commands portable premium positioning. |
| Subscription-Based Hardware Models | Device-plus-consumable bundling through direct-to-patient platforms reduces price sensitivity and locks recurring revenue. |
Methodological Framework
Independent corroboration across device manufacturer executives, German pharmacy procurement managers, and Australian TGA regulatory consultants underwrites the qualitative findings. Primary interviews with ceramic heating element suppliers, battery cell procurement leads, and California dispensary operators combined with secondary validation from FDA 510(k) filings, BfArM medical device registrations, and EU Tobacco Products Directive submission databases. Bottom-up unit shipment estimates and top-down market value triangulation anchored the sizing framework.
Historical reference periods spanning medical cannabis program launches in Germany and Australia anchored the forecast window calibration. The analytical framework modeled segmentation dimensions including product type, material configuration, end-user category, and distribution channel across the projection horizon. CAGRs derived from patient enrollment trajectories, battery technology cost curves, and regulatory pathway timelines. Ceramic heating element adoption rates and concentrate-compatible hardware penetration served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including sudden lithium-ion raw material export restrictions, unanticipated EU Tobacco Products Directive enforcement delays, and state-level THC potency cap revisions in US jurisdictions. Forecasts reflect documented assumptions regarding patient enrollment growth and ceramic supplier capacity expansion. A model refresh is warranted upon material change in BfArM registration processing timelines or TGA therapeutic goods approval velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Global Office and Contact Center Headset Market
Consumer Electronics
HiFi Electronics Market
Consumer Electronics
Shoe Shining Machine Market
Consumer Electronics
Mobile Phone Accessories Market
Consumer Electronics
Consumer Electronics Repair and Maintenance Market
Consumer Electronics
Smart Headphones Market
Consumer Electronics
Earbuds Market
Consumer Electronics
Gaming Mouse Market
Consumer Electronics
Latin America Consumer Electronics Market
Consumer Electronics
Global Earphones and Headphones Market
Consumer Electronics
Global Laptop Market
Consumer Electronics
Wireless Mouse Market
Consumer Electronics
Wireless Earphone Market
Consumer Electronics
Camera Case Market
Consumer Electronics
North America Wireless Anc Headphone Market
Consumer Electronics
Global Home Audio System Market