
 Alternate Current (AC) Drives Market | 2026-2036
Alternate Current (AC) Drives Market Size, Share, and Industry Trends Forecast 2026-2036
Alternate Current (AC) Drives Market Outlook
Aftermarket service revenue is reshaping profit pools away from hardware shipments toward lifecycle contracts and remote diagnostics. ABB leverages its digital platform architecture to capture recurring software subscriptions. Siemens sustains competitive position through deep integration of drives with its PLC and automation ecosystems. Yaskawa Electric dominates precision motion applications where servo drive performance commands premium positioning.
Alternate Current (AC) Drives are power conversion systems that modulate voltage and frequency to control AC motor speed, typically operating between 0.4 kW and multi-megawatt outputs with switching frequencies from 2 to 16 kHz depending on application requirements. Their primary purpose is to reduce mechanical load energy consumption and enable precise process control across industrial machinery. Variable frequency drives occupy the largest installed base due to universal applicability in fan and pump systems where throttling losses otherwise dominate operating costs. Servo drives represent the fastest-expanding category as packaging machinery and robotics demand nanometer-level positioning accuracy. Multi-axis controllers concentrate margin pools in semiconductor fabrication and advanced material handling where coordinated motion complexity justifies system-level pricing.
The EU Ecodesign Directive and IEC 61800-9 efficiency standards compel manufacturers to redesign power stages and thermal management systems to meet mandatory loss thresholds. The US Department of Energy motor efficiency regulations and China's GB 18613 standards create parallel compliance burdens that favor suppliers with modular platform architectures spanning multiple efficiency tiers. Stakeholders must monitor how carbon border adjustment mechanisms reshape total cost of ownership calculations for energy-intensive industries sourcing drives across jurisdictions.
Market Dynamics
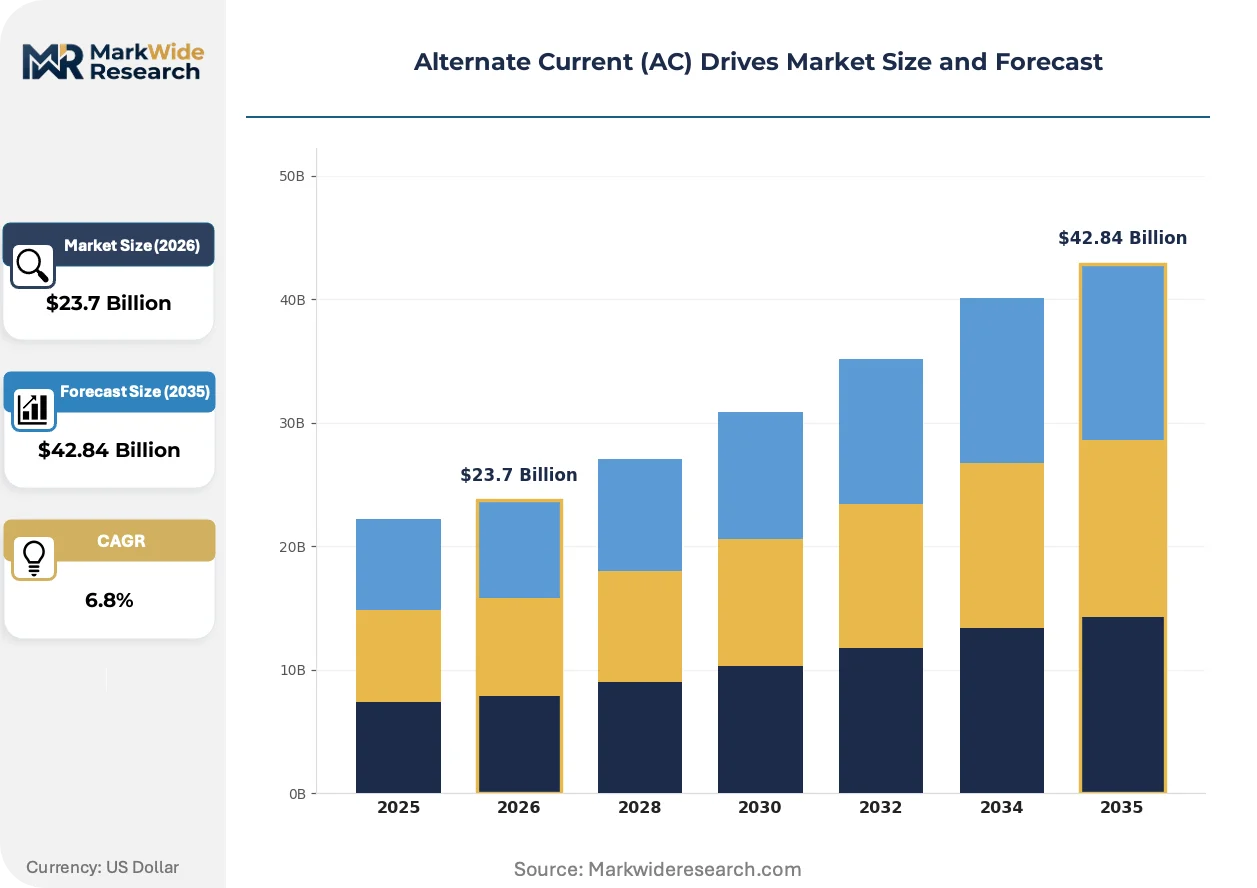
Aftermarket service revenue is compressing hardware margins while IEC 61800-9 efficiency mandates force power stage redesigns across supplier portfolios. This dual pressure is restructuring competitive economics toward lifecycle contracts and platform modularity.
Growth Catalysts
- EU Ecodesign Directive:Mandatory motor system efficiency thresholds in Europe accelerate variable frequency drive replacement cycles across industrial pump and fan installations.
- Water treatment infrastructure:Municipal and industrial facilities deploy drives for energy-efficient pump control, reducing throttling losses in filtration and distribution systems.
- China's GB 18613 standards:State-mandated energy conservation targets in manufacturing clusters drive adoption of premium efficiency drive platforms.
Market Restraints
- IGBT and SiC semiconductor supply:Power module sourcing concentrates among Asian foundries, creating input cost volatility and allocation risk for drive manufacturers.
- Technical integration complexity:Legacy motor fleets require rewinding or replacement to achieve rated efficiency with modern drives, extending payback periods.
- Skilled commissioning shortage:Proper drive parameterization demands certified technicians, limiting deployment velocity in underpenetrated industrial regions.
Strategic Opportunities
- India's industrial corridors:PLI scheme incentives and CEA efficiency mandates create white space for drive vendors in automotive and textile manufacturing clusters.
- Servo-motion convergence:Packaging machinery and robotics applications demand nanometer-level positioning, expanding addressable market beyond traditional VFD segments.
- Remote diagnostics platforms:Cloud-based condition monitoring enables subscription revenue models that decouple service income from hardware shipment cycles.
Industry Challenges
- Multi-jurisdiction certification timelines:Parallel UL, CE, and CCC approval processes delay product launches and fragment R&D resource allocation.
- Thermal management engineering scarcity:Power density improvements require specialized magnetics and cooling design expertise that outpaces vocational training pipelines.
- Legacy automation integration:Fieldbus protocol fragmentation across installed PLC bases complicates seamless drive commissioning in brownfield facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alternate Current (AC) Drives Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Variable Frequency Drives, Soft Starters, Servo Drives, Multi-Axis Controllers Technology: PWM, Scalar Control, Direct Torque Control, Vector Control End User: Manufacturing, Water Treatment, HVAC, Renewable Energy Application: Conveyor Systems, Pumps, Fans, Compressors |
| Companies Covered | Yaskawa Electric, Schneider Electric, ABB, Fuji Electric, Mitsubishi Electric, Siemens, Rockwell Automation, WEG, Danfoss, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alternate Current (AC) Drives Market Strategic Shifts
Digital twin architectures and wide-bandgap semiconductors are compressing physical prototyping cycles while elevating power density benchmarks. These shifts are redrawing R&D economics and supplier capability requirements across the sector.
Silicon carbide (SiC) MOSFETs enable higher switching frequencies with reduced thermal losses, shrinking drive enclosure volumes by thirty to fifty percent compared to silicon IGBT platforms. Automotive test stand and semiconductor fabrication buyers are adopting SiC-based drives fastest, prioritizing footprint reduction over unit cost. This transition is virtualizing thermal simulation workflows, allowing vendors to validate cooling designs digitally before metal cutting.
REACH substance restrictions and F-Gas Regulation phase-downs in Europe compel elimination of specific thermal interface materials and refrigerants from drive manufacturing. Suppliers must reformulate potting compounds and redesign heat exchangers to maintain IP ratings without restricted substances. Servo drive portfolios face the steepest compliance burden due to their precision thermal tolerances and sealed enclosures.
Buying committees now unbundle hardware procurement from long-term service agreements, forcing vendors to price maintenance and software upgrades separately. System integrators and large industrial end-users in Germany and Japan lead this disintermediation, using competitive tendering for each contract element. Drive OEMs respond with modular software licensing that decouples feature access from initial hardware purchase scope.
Alternate Current (AC) Drives Market Segmentation
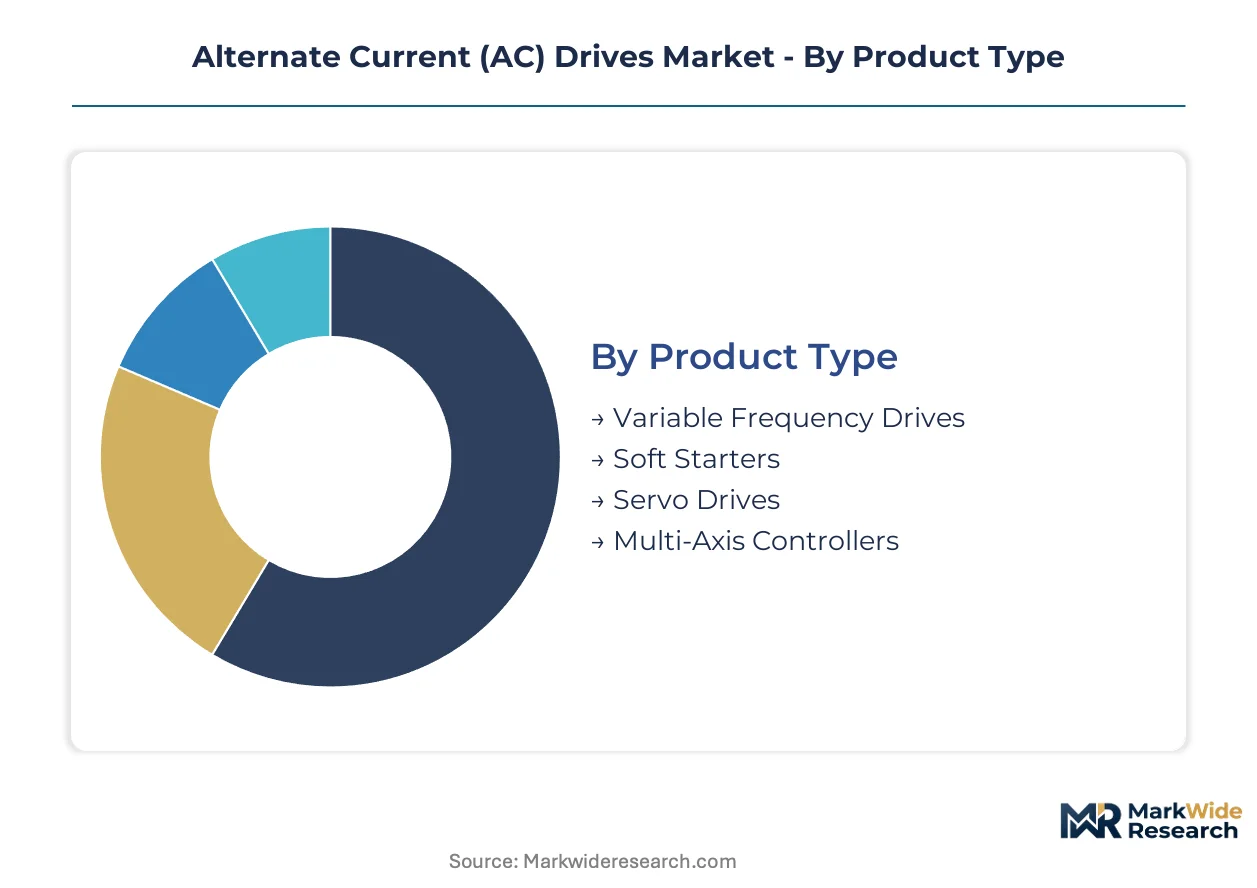
AC drive segmentation reflects divergent engineering priorities across power density, precision, and integration depth. Each category captures distinct margin structures and competitive dynamics that reshape supplier portfolio strategies.
Product Type:
Mature variable frequency drives dominate installed base economics while emerging servo architectures capture premium positioning in precision automation.
- Variable Frequency Drives:These units modulate voltage and frequency to control AC induction motor speed across 0.4 kW to multi-megawatt ranges. Water treatment facilities in China deploy them for energy-efficient pump control, driven by GB 18613 efficiency mandates and state conservation targets.
- Servo Drives:Closed-loop systems deliver nanometer-level positioning accuracy through high-bandwidth current control. Packaging machinery and robotics applications in Germany and Japan concentrate demand, where IEC 61800-9 compliance and coordinated motion complexity justify system-level pricing.
- Soft Starters:Reduced-voltage starting devices limit inrush current for fixed-speed applications requiring gentle mechanical engagement.
- Multi-Axis Controllers:Coordinated motion platforms synchronize multiple servo axes for semiconductor fabrication and advanced material handling.
Variable Frequency Drives retain volume leadership; Servo Drives hold the steepest expansion curve.
Technology:
Cost tier stratification separates commodity PWM implementations from premium vector architectures commanding specialized commissioning services.
- PWM:Pulse-width modulation dominates mainstream applications through insulated-gate bipolar transistor switching at 2-16 kHz frequencies. Fan and pump systems across US municipal infrastructure standardize on this cost-optimized approach, though IGBT supply concentration among Asian foundries creates input volatility.
- Vector Control:Field-oriented algorithms decouple torque and flux components for dynamic response matching DC motor performance. Machine tool and crane applications in Japan and South Korea adopt these platforms where METI efficiency guidelines and precision load handling converge.
- Scalar Control:Volts-per-hertz schemes provide basic speed regulation without rotor position feedback for undemanding constant-torque loads.
- Direct Torque Control:Hysteresis-based switching tables eliminate current loop latency for high-inertia mineral processing drives.
PWM retains volume leadership; Vector Control holds the steepest expansion curve.
End User:
Application concentration varies by capital intensity and regulatory exposure, with manufacturing absorbing standard platforms and renewable energy demanding grid-code compliance.
- Manufacturing:Discrete and process industries deploy drives across material handling, machining, and assembly lines. Automotive and textile clusters in India expand adoption under PLI scheme incentives and CEA efficiency mandates.
- Water Treatment:Municipal and industrial filtration facilities prioritize energy recovery in pumping operations. European utilities accelerate replacement cycles under EU Ecodesign Directive thresholds for motor-driven systems.
- HVAC:Building automation systems modulate chiller and air handling unit capacity against variable thermal loads.
- Renewable Energy:Solar inverters and wind turbine converters require grid-synchronization capabilities and fault ride-through functionality.
Manufacturing retains volume leadership; Water Treatment holds the steepest expansion curve.
Application:
Customer type differentiation separates OEM machinery builders seeking embedded integration from end-user facilities prioritizing retrofit compatibility.
- Pumps:Centrifugal and positive displacement pump control represents the largest addressable application by unit volume. Throttling loss elimination drives payback calculations across US water utilities facing EPA energy performance benchmarking.
- Fans:Aerodynamic load profiling enables significant energy reduction versus damper control in ventilation and combustion air systems. Cement and steel plants in China integrate these drives to meet dual carbon goals and provincial emissions targets.
- Conveyor Systems:Bulk material handling and parcel sorting require coordinated multi-motor synchronization.
- Compressors:Rotary and reciprocating air compression benefits from load-unload optimization and pressure band tightening.
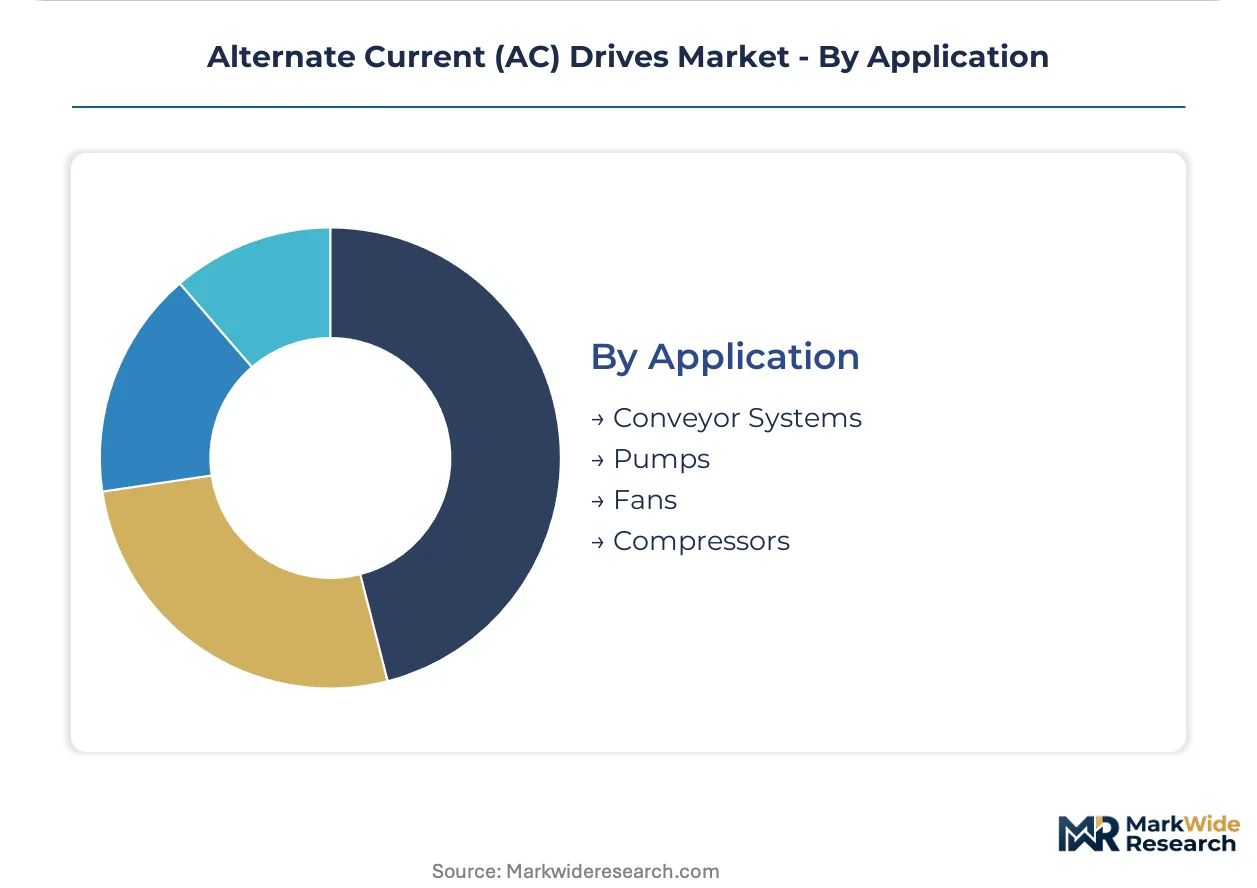
Pumps retain volume leadership; Fans hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Buyers in Germany absorb premium pricing for IEC 61800-9-compliant systems, while procurement committees in India negotiate aggressively on hardware costs despite lifecycle efficiency gains.
China
State-mandated energy conservation targets and GB 18613 efficiency standards accelerate drive replacement in manufacturing clusters. Provincial emissions enforcement tightens operational requirements for cement and steel plants. The Yangtze River Delta absorbs volume leadership as automotive and electronics OEMs electrify production lines.
Germany
Machine tool builders and packaging machinery OEMs prioritize nanometer-level positioning accuracy. The EU Ecodesign Directive and F-Gas Regulation compel thermal management redesigns. Industrial automation corridors in Baden-Württemberg concentrate servo drive demand for coordinated motion applications.
United States
EPA energy performance benchmarking drives pump system retrofits across municipal water utilities. DOE motor efficiency regulations extend compliance burdens to legacy installations. Texas and California industrial facilities absorb premium vector control platforms for dynamic load handling.
India
PLI scheme incentives and CEA efficiency mandates create white space in automotive and textile manufacturing. Price-sensitive procurement delays premium adoption despite proven payback periods. Maharashtra and Gujarat industrial corridors expand variable frequency drive deployment under state conservation programs.
Japan
METI efficiency guidelines and precision manufacturing culture sustain premium positioning for servo architectures. Robotics and semiconductor fabrication demand multi-axis coordination. The Chubu region around Nagoya anchors machine tool builder demand for field-oriented control systems.
Alternate Current (AC) Drives Market Competitive Environment
Capability concentration sits with precision motion specialists; scale advantage sits with diversified automation conglomerates. The vendor base stratifies across three tiers: integrated platform providers capturing lifecycle contracts, component specialists dominating narrow performance bands, and regional fabricators competing on hardware cost. Strategic moves center on modular software licensing and cloud-based condition monitoring subscriptions that decouple service revenue from shipment cycles.
Within the integrated platform tier, ABB, Siemens, and Yaskawa Electric exemplify divergent competitive positioning. The Swiss-Swedish conglomerate anchors digital service architectures. The German industrial group occupies deep PLC ecosystem integration. The Japanese precision specialist represents nanometer-level motion control premiumization. Each archetype defends distinct margin pools against encroachment from modular competitors.
| Leading Market Players |
|---|
| Yaskawa Electric |
| Schneider Electric |
| ABB |
| Fuji Electric |
| Mitsubishi Electric |
| Siemens |
| Rockwell Automation |
| WEG |
| Danfoss |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor carries power module cargo whose freight cost volatility feeds directly into tiered hardware pricing and aftermarket service bundling across European drive deployments.
Pricing Analysis
Lifecycle service contracts now drive lifetime value more than initial hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61800-9-certified platforms from basic PWM implementations. Cost compression in economy-tier hardware is intensifying because Asian IGBT foundries concentrate supply. Municipal water utilities in the United States show highest price sensitivity; semiconductor fabricators in Japan absorb premium servo platforms without negotiation.
Supply Chain Analysis
Export-control restrictions on wide-bandgap semiconductor manufacturing equipment limit SiC substrate flows from United States and Japanese suppliers to Chinese packaging facilities. Power module assembly concentrates in China, South Korea, and Malaysia. Raw material dependencies include silicon carbide wafers, copper magnet wire, and aluminum heatsink extrusions. Single-source vulnerability sits with epitaxial SiC wafer suppliers. Distribution runs through authorized industrial distributors and direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capital equipment procurement cycles in manufacturing signal cyclical recovery as industrial electrification mandates accelerate replacement demand across Chinese and European facilities.
For Market Incumbents: Entrench platform modularity to defend against modular software competitors unbundling hardware from service revenue. Deepen backward integration into SiC power module design to secure supply allocation. Lock in certified technician training networks to limit commissioning bottlenecks that delay customer deployments.
For New Entrants and Emerging Players: India's automotive and textile manufacturing clusters under PLI scheme incentives represent the most penetrable entry point for standard variable frequency drive platforms. Municipal water treatment facilities in Southeast Asia offer secondary white space with less entrenched supplier relationships. Lead with remote diagnostics subscriptions to bypass established service infrastructure.
For Investors and Strategic Acquirers: The EU Ecodesign Directive's tightening efficiency thresholds reshape the acquisition landscape toward vendors with pre-certified IEC 61800-9 platforms. Long-term viability centers on software-defined service revenue decoupled from hardware shipment volatility. Target precision motion specialists with multi-axis controller portfolios. Watch carbon border adjustment mechanism proposals as the critical inflection signal for energy-intensive industry sourcing decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Software Licensing | Decouples feature access from initial hardware purchase scope, enabling recurring revenue streams. |
| SiC Power Stage Transition | Shrinks enclosure volumes thirty to fifty percent for automotive test stand and semiconductor fabrication buyers. |
| Remote Diagnostics Platform | Cloud-based condition monitoring enables subscription models independent of shipment cycles. |
| Certified Technician Network Expansion | Addresses skilled commissioning shortages limiting deployment velocity in underpenetrated industrial regions. |
| REACH-Compliant Thermal Redesign | Eliminates restricted substances from potting compounds and heat exchangers for European market access. |
Study Parameters
Two parallel data streams informed the analysis: structured interviews with drive OEM product managers, plant engineers at water treatment facilities, automation system integrators, and aftermarket service heads; and secondary validation through IEC standard documentation, SEC filings of listed automation conglomerates, customs trade data for power module imports, and EIA industrial energy consumption surveys. Bottom-up unit economics triangulated against top-down market sizing.
Forecast inputs span product type, technology architecture, end-user industry, and application intensity across the analysis window. Segmentation dimensions modeled include power density tier, precision requirement, and integration depth. CAGRs derived from historical replacement cycle analysis, regulatory mandate timelines, and efficiency standard adoption curves. Specific inputs include GB 18613 implementation pace and EU Ecodesign Directive revision schedules.
Practitioners should monitor semiconductor export control expansions and carbon border adjustment mechanism enactment for early signals. Forecasts reflect assumptions about regulatory enforcement continuity and foundry capacity expansion. Material shifts in wide-bandgap substrate supply availability or efficiency standard acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Latin America Hazardous Location Motor Starters Market
Electrical Power Equipment
HV Bushing Market
Electrical Power Equipment
South America Air Insulated Switchgear Market
Electrical Power Equipment
Battery Charger Market
Electrical Power Equipment
Global Air Insulated Switchgear Market
Electrical Power Equipment
Alternators Market
Electrical Power Equipment
Protective Relay Market
Electrical Power Equipment
Middle East and Africa High Voltage Switchgear Market
Electrical Power Equipment
Global Electric Power Substation Automation Market
Electrical Power Equipment
Power Line Filters Market
Electrical Power Equipment
Hollow Core Insulator Market
Electrical Power Equipment
Utility Poles Market
Electrical Power Equipment
Magnetic Optical Current Transformer Market
Electrical Power Equipment
South America Medium Voltage Switchgear Market
Electrical Power Equipment
Portable Space Heater Market
Electrical Power Equipment
Power Over Ethernet Lighting Market