
 Europe Prebiotic Ingredient Market | 2026-2036
Europe Prebiotic Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Prebiotic Ingredient Market Foresight
Multi-source sourcing of chicory root and Jerusalem artichoke raw material is broadening supply security across the European prebiotic ingredient value chain. Beneo leverages captive beet sugar processing infrastructure to sustain inulin production scale from its Belgian operations. Kerry Group anchors its competitive position through specialized extraction and formulation capabilities serving branded food manufacturers. Cosucra Groupe Warcoing differentiates via pea-derived prebiotic innovation, occupying a distinct plant-protein adjacency.
Prebiotic ingredients comprise non-digestible oligosaccharides—primarily inulin, oligofructose, and galacto-oligosaccharides—that resist upper-gastrointestinal hydrolysis and selectively ferment beneficial colonic microbiota, typically requiring minimum purity thresholds and specified degrees of polymerization for functional efficacy. Inulin and oligofructose derived from chicory root dominate current volume flows, reflecting mature extraction infrastructure and established cost curves across Belgian and Dutch processing hubs. Galacto-oligosaccharides represent the fastest-expanding product category, propelled by infant formula fortification trends and dairy processor backward integration into value-added ingredient streams.
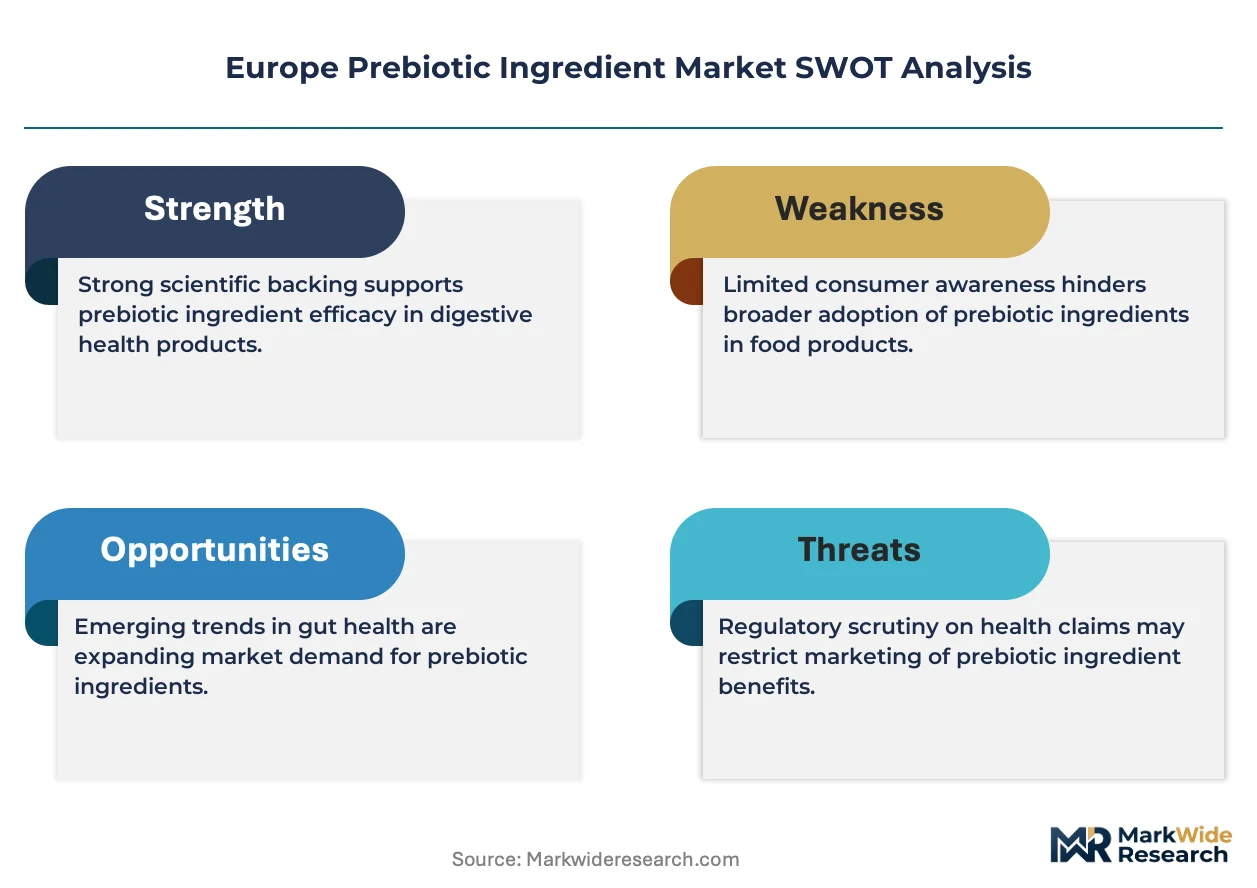
EFSA novel food evaluations and EU Health Claims Regulation substantiation requirements shape product development timelines and label permissibility across member states, while REACH chemical safety protocols govern synthetic prebiotic manufacturing pathways. France's ANSM and Germany's BfR provide complementary national oversight on specific application categories, creating layered compliance obligations for cross-border suppliers. Stakeholders must monitor evolving EFSA opinions on gut microbiome-related health claims, as pending determinations will directly influence permissible marketing architectures and premium positioning strategies.
Market Dynamics
EFSA novel food approval pathways and EU Health Claims Regulation substantiation requirements are compressing product development timelines while simultaneously validating premium positioning for substantiated prebiotic ingredients across member states.
Growth Catalysts
- EFSA novel food frameworks:Streamlined evaluation procedures for chicory-derived inulin and galacto-oligosaccharides are accelerating time-to-market for functional ingredient developers seeking label-compliant positioning.
- Infant formula fortification:Dairy processors across Germany and the Netherlands are integrating galacto-oligosaccharide production into whey processing streams, creating captive supply for early-life nutrition manufacturers.
- Digestive wellness consumer familiarity:Established markets in Belgium and France demonstrate sustained pull for gut microbiome-targeted formulations across yogurt, beverage, and bakery applications.
Market Restraints
- Chicory root supply concentration:Belgian and Dutch processing clusters dominate raw material flows, creating geographic vulnerability to weather-induced harvest variability and input cost volatility.
- EFSA health claims substantiation:Pending determinations on gut microbiome-related claims impose regulatory friction, limiting permissible marketing language for products lacking completed dossier reviews.
- Synthetic prebiotic pathways:REACH chemical safety protocols govern non-plant-derived production routes, elevating compliance burdens relative to established extraction-based alternatives.
Strategic Opportunities
- Eastern European market development:Poland and Romania present underpenetrated demand for digestive wellness products, with retail infrastructure maturing for functional food positioning.
- Pea-derived prebiotic innovation:Pulse protein processing residues offer emerging feedstock streams for novel oligosaccharide extraction, converging with plant-protein formulation trends.
- EU Green Deal bioeconomy incentives:Circular economy funding mechanisms support agricultural residue valorization projects, reducing feedstock costs for regional processors.
Industry Challenges
- Specialized fermentation expertise scarcity:Galacto-oligosaccharide production requires enzymatic biocatalysis capabilities that outpace current technical workforce availability across continental processing facilities.
- Cross-border compliance fragmentation:France's ANSM and Germany's BfR maintain divergent national oversight on specific application categories, multiplying certification timelines for pan-European suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Prebiotic Ingredient Market |
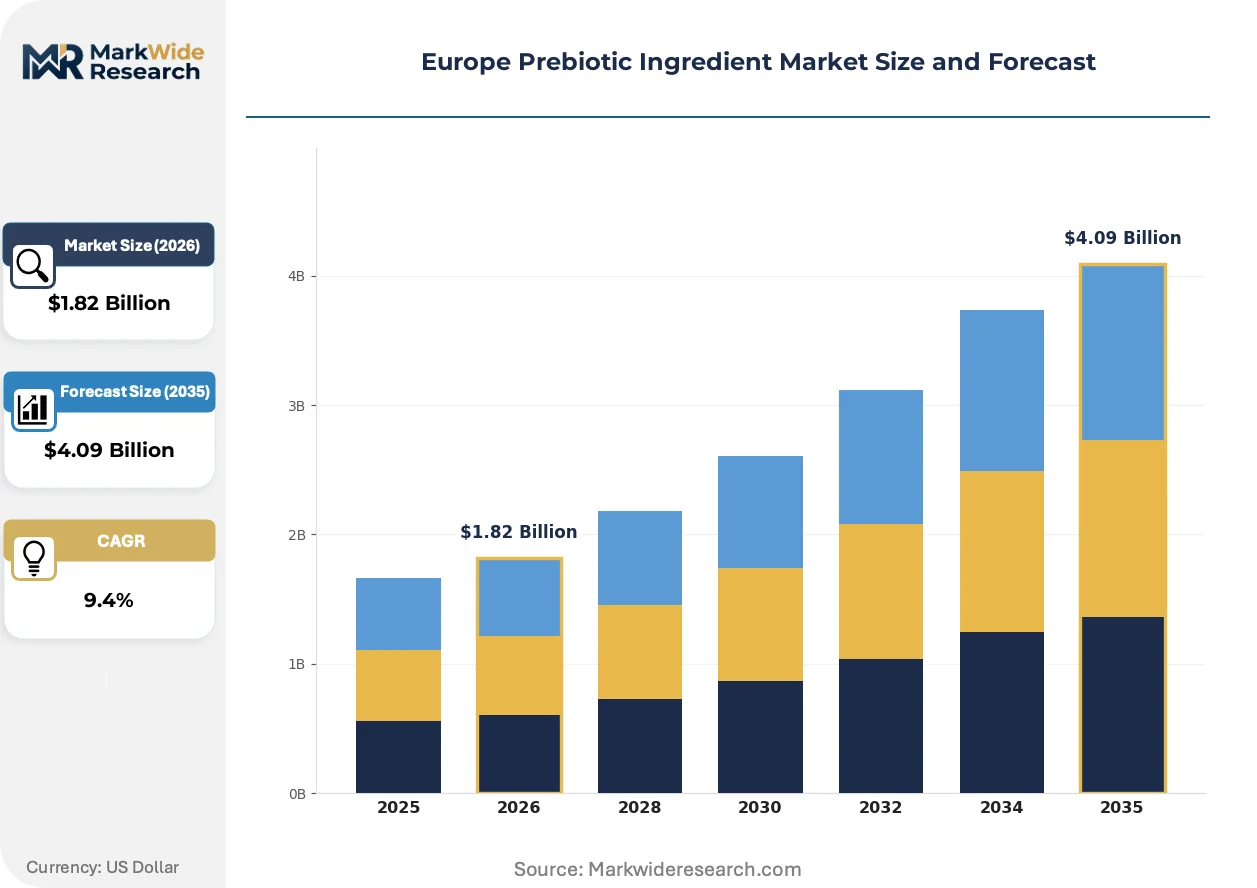
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $4.09 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inulin, Oligofructose, Galacto-oligosaccharides, Xylo-oligosaccharides End Use Industry: Food & Beverages, Dietary Supplements, Pharmaceuticals, Animal Feed Source: Plant-based, Dairy-based, Synthetic, Others Application: Gut Health, Immune Support, Nutraceuticals, Functional Foods |
| Companies Covered | Ingredion Inc., Kerry Group, Nestlé, Cosucra Groupe Warcoing, Cargill Inc., Danone, Archer Daniels Midland Company, Beneo (Süddeutsche Zuckerrübenverwertungs-Genossenschaft eG), Tereos Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Prebiotic Ingredient Market Shifts & Advancements
Continuous chromatographic purification and enzymatic synthesis platforms are compressing production economics while expanding molecular specificity for targeted microbiome modulation applications.
Membrane filtration coupled with simulated moving bed chromatography is automating the separation of specific degrees of polymerization from chicory root extracts. Specialized ingredient houses serving branded dairy and beverage manufacturers are deploying these systems at commercial scale. This automation is compressing batch-to-batch variability and enabling certificate-of-analysis specifications that match infant formula and clinical nutrition requirements.
REACH chemical safety protocols are tightening disclosure requirements for synthetic prebiotic manufacturing pathways, elevating documentation burdens for non-plant-derived producers. The regulation is diverting capital toward extraction-based and fermentation-derived alternatives with established safety dossiers. Synthetic pathway developers are responding by accelerating green chemistry substitutions to preempt authorization restrictions.
Ingredient procurement from dairy and bakery manufacturers is consolidating toward suppliers offering combined prebiotic-probiotic synbiotic formulations. This specification shift is displacing standalone oligosaccharide sourcing for premium positioned finished goods. The behavior is most visible in German and French markets, where finished goods marketers seek simplified supplier relationships and coordinated stability testing.
Europe Prebiotic Ingredient Market Segmentation
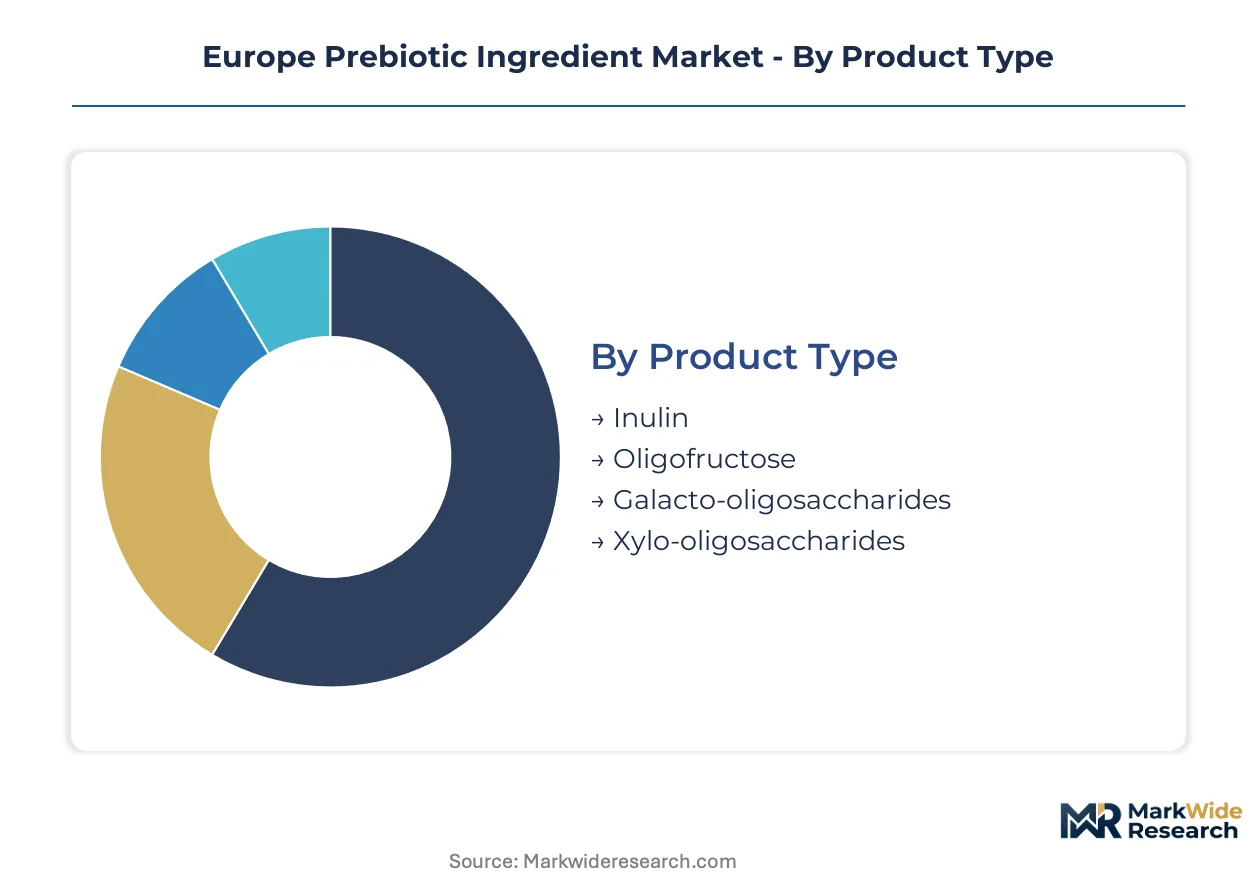
Prebiotic ingredient procurement decisions in Europe hinge on three interlocking filters: regulatory substantiation pathways for label claims, formulation compatibility with existing processing infrastructure, and supply security from concentrated raw material geographies. Buyers across dairy, bakery, and early-life nutrition segments weight these factors differently, fragmenting demand patterns across the value chain.
Product Type:
Buyers prioritize degree-of-polymerization specifications and EFSA novel food dossier status when selecting oligosaccharide grades for commercial formulations.
- Inulin:Long-chain fructan with degrees of polymerization exceeding 10, extracted primarily from chicory root through hot water diffusion. Belgian and Dutch dairy processors anchor European demand, leveraging established extraction infrastructure and validated health claim substantiation for digestive wellness positioning.
- Galacto-oligosaccharides:Disaccharide to hexasaccharide structures synthesized from lactose via β-galactosidase biocatalysis. German and Netherlands-based infant formula manufacturers drive fastest-expanding demand, integrating captive GOS production into whey processing streams to secure early-life nutrition supply chains.
- Oligofructose:Shorter-chain fructan fraction with enhanced solubility and sweetness profile versus inulin.
- Xylo-oligosaccharides:Hemicellulose-derived pentose oligomers emerging from agricultural residue valorization projects under EU Green Deal funding mechanisms.
Volume sits with inulin; growth tilts toward galacto-oligosaccharides.
End Use Industry:
Application-specific purity thresholds and stability requirements divide procurement specifications across downstream sectors.
- Food & Beverages:Largest volume sink encompassing yogurt fortification, bakery fiber enrichment, and beverage formulation. French and German branded manufacturers dominate demand, requiring certificate-of-analysis consistency for high-throughput production lines and EFSA-compliant label positioning.
- Dietary Supplements:Capsule, powder, and sachet formats targeting adult digestive wellness and metabolic health. Premium pricing tolerance here exceeds food applications, rewarding suppliers with clinical trial substantiation and specialized delivery system capabilities.
- Pharmaceuticals:Clinical nutrition and medical food applications demanding pharmacopeial-grade specifications.
- Animal Feed:Gut microbiome modulation for poultry and swine production, primarily in Netherlands and Denmark.
Revenue concentrates in food and beverages; margin expansion favors dietary supplements.
Source:
Feedstock provenance determines REACH compliance burden and circular economy credential eligibility for European buyers.
- Plant-based:Chicory root, Jerusalem artichoke, and pulse protein processing residues dominate extraction-based supply. Belgian processors leverage captive beet sugar infrastructure for integrated inulin production, while French and Dutch operators experiment with pea-derived oligosaccharide streams.
- Dairy-based:Lactose feedstock streams from whey processing support GOS enzymatic synthesis. Netherlands-based dairy cooperatives have achieved backward integration into this value-added ingredient tier, reducing third-party procurement exposure.
- Synthetic:Chemical synthesis pathways for specific oligosaccharide structures face tightening ECHA disclosure requirements.
- Others:Fermentation-derived and enzymatic routes from novel microbial platforms.
Plant-based sources command volume leadership; dairy-based pathways scale most rapidly.
Application:
Health claim substantiation status and target consumer demographic shape specification intensity across functional positioning strategies.
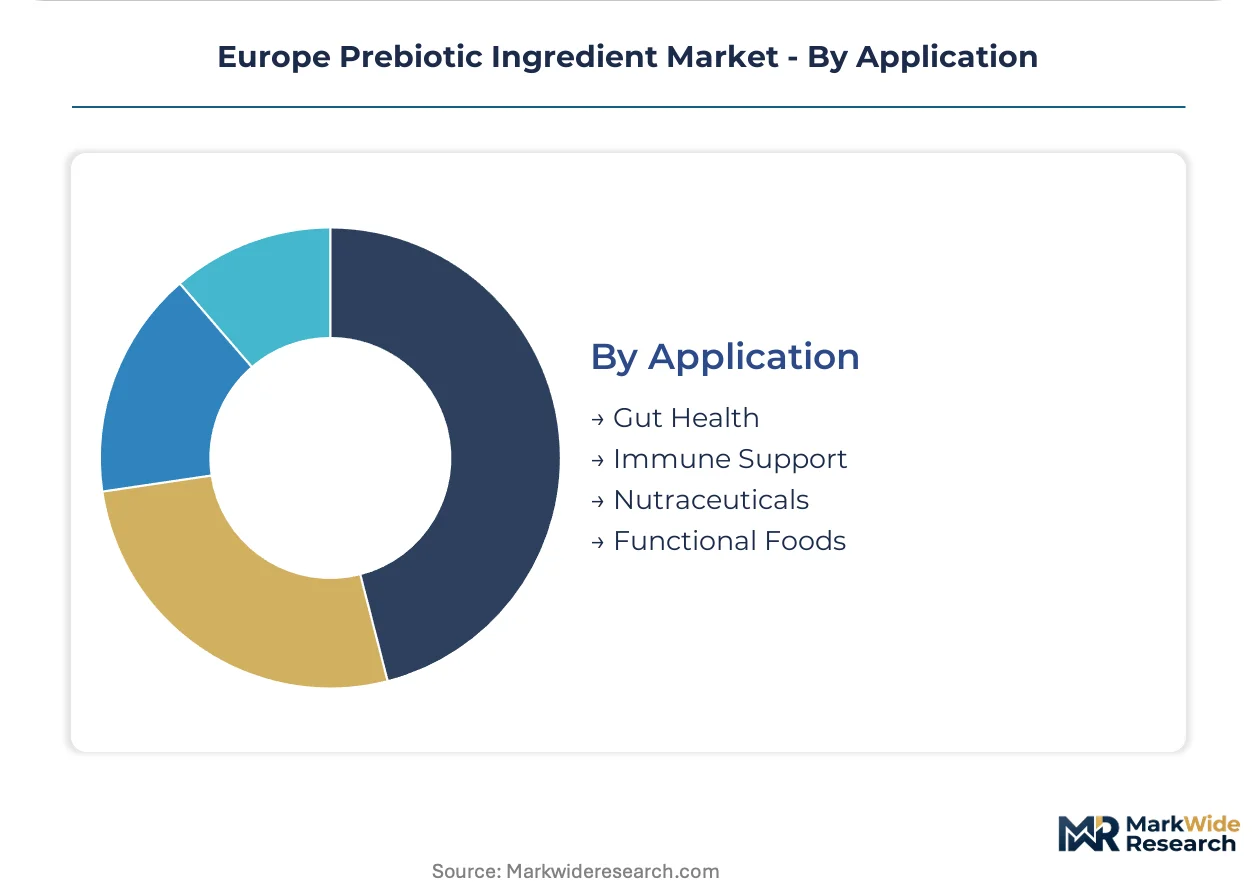
- Gut Health:Core application leveraging selective fermentation by beneficial colonic microbiota. EFSA opinions on gut microbiome-related claims pending determination will directly influence permissible marketing architectures for this segment across member states.
- Immune Support:Emerging positioning requiring clinical trial investment beyond digestive endpoints. German and French supplement manufacturers are advancing dossier development for this adjacent claim category.
- Nutraceuticals:Metabolic health, mineral absorption, and satiety applications in specialized delivery formats.
- Functional Foods:Mainstream integration into everyday consumption occasions without explicit health claim reliance.
Established positioning centers on gut health; immune support applications attract development investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicory root cultivation belts across Belgium and northern France anchor European prebiotic ingredient supply, with processing infrastructure radiating from the Franco-Belgian border into Dutch and German industrial corridors.
Germany
Infant formula manufacturers in Bavaria and North Rhine-Westphalia drive galacto-oligosaccharide demand through captive whey processing integration. BfR oversight on novel food applications shapes dossier preparation timelines for early-life nutrition suppliers. The Frankfurt-Rhine-Main corridor hosts specialized extraction equipment providers serving dairy processors scaling GOS enzymatic synthesis capacity.
France
ANSM regulations on medical food classifications influence pharmaceutical-grade prebiotic procurement specifications for clinical nutrition applications. The Hauts-de-France region concentrates chicory root processing infrastructure inherited from historical beet sugar cooperatives. Paris-based branded manufacturers anchor demand for EFSA-substantiated digestive wellness positioning in yogurt and beverage formulations.
Netherlands
Dairy cooperatives in Friesland and Gelderland have achieved backward integration into galacto-oligosaccharide production from lactose streams. EU Green Deal circular economy funding supports agricultural residue valorization pilots in the Randstad region. Wageningen University research clusters accelerate enzymatic biocatalysis development for next-generation oligosaccharide synthesis platforms.
Belgium
Beneo leverages captive beet sugar processing infrastructure in Wallonia to sustain integrated inulin extraction at commercial scale. EFSA novel food evaluation procedures for chicory-derived ingredients streamline regulatory pathways for regional exporters. The Flanders region hosts specialized chromatographic purification equipment serving certificate-of-analysis requirements for infant formula manufacturers.
Poland
Retail infrastructure maturation in Warsaw and Kraków creates underpenetrated demand for digestive wellness product positioning. National adaptation of EU Health Claims Regulation creates compliance lag versus western member states, delaying premium pricing capture. Poznań-based food processors experiment with pulse protein residue streams for novel xylo-oligosaccharide extraction under bioeconomy development programs.
Europe Prebiotic Ingredient Market Competitive Landscape
Capacity expansion dominates the current landscape as established processors scale chromatographic purification infrastructure to capture infant formula and clinical nutrition contracts. The vendor base stratifies across three tiers: integrated agribusiness conglomerates with captive feedstock control, specialized ingredient houses with formulation expertise, and regional extraction specialists serving commodity dairy applications. Strategic archetypes include backward-integrated dairy processors, beet sugar cooperative derivatives, and pulse protein innovators. M&A activity and enzymatic synthesis technology licensing represent the dominant competitive moves reshaping participant positioning.
Among Belgian and Dutch processing specialists, Beneo and Cosucra Groupe Warcoing exemplify divergent feedstock strategies—one leveraging beet sugar infrastructure for inulin scale, the other pioneering pea-derived oligosaccharide innovation from pulse protein residues. Kerry Group occupies a position bridging extraction capabilities and formulation services for branded food manufacturers seeking synbiotic integration. These three anchors illustrate how geographic proximity to raw material belts combines with regulatory dossier expertise to determine competitive viability.
| Leading Market Players |
|---|
| Ingredion Inc. |
| Kerry Group |
| Nestlé |
| Cosucra Groupe Warcoing |
| Cargill Inc. |
| Danone |
| Archer Daniels Midland Company |
| Beneo (Süddeutsche Zuckerrübenverwertungs-Genossenschaft eG) |
| Tereos Group |
| Others |
Supply & Pricing Matrix
Chicory root spot prices on the Liège commodity exchange cascade through three distinct pricing tiers as Belgian processors pass harvest volatility downstream to infant formula manufacturers, dietary supplement houses, and commodity dairy blenders with divergent certificate-of-analysis requirements.
Pricing Analysis
Service bundling separates contract prebiotic supply from spot-market transactions. Premium tiers wrap EFSA novel food dossier support, stability testing, and synbiotic formulation assistance into long-term offtake agreements. Standard tiers strip out regulatory consulting and technical services. Price differentiation hinges on purity thresholds and REACH documentation depth. Pricing pressure stems from dairy processor backward integration into GOS production. Commodity dairy blenders exhibit highest price sensitivity; clinical nutrition manufacturers tolerate premium positioning.
Supply Chain Analysis
Single-source vulnerability sits with Belgian chicory root cultivation belts concentrated within 150 kilometers of the Franco-Belgian border. The supply chain draws from chicory root, Jerusalem artichoke, and lactose whey permeate as primary feedstocks. Tariff exposure looms for non-EU feedstock imports under evolving EU agricultural policy. Distribution runs through specialized ingredient houses serving branded manufacturers rather than direct processor-to-finished-goods linkages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA novel food approval costs erect a cost-of-compliance moat that protects incumbent positions while forcing new entrants to absorb multi-year dossier preparation timelines before capturing premium pricing.
For Market Incumbents: Deepen chromatographic purification capabilities in Flanders to defend certificate-of-analysis consistency against emerging enzymatic synthesis competitors. Expand captive beet sugar infrastructure integration to buffer chicory root harvest volatility. Prioritize synbiotic formulation partnerships to lock in branded manufacturer switching costs. For New Entrants and Emerging Players: Enzymatic biocatalysis platforms offer entry pathways into GOS production without Belgian chicory belt dependency. Target Polish retail infrastructure maturation for digestive wellness product positioning. Pursue EU Green Deal bioeconomy funding to subsidize agricultural residue valorization feedstock costs. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap extraction specialists with EFSA-approved dossiers in the Netherlands. Five-to-ten year viability hinges on microbiome health claim substantiation trajectories. Monitor EFSA opinions on gut microbiome-related claims as the decisive inflection signal for premium positioning permissibility.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Investment | Regulatory approval unlocks label-compliant positioning for infant formula manufacturers across member states. |
| Chromatographic Purification Scale-Up | Automation compresses batch variability to meet pharmacopeial-grade specifications for clinical nutrition. |
| Backward Integration into Whey Processing | Dairy cooperatives in Friesland capture GOS supply chain margins previously flowing to third-party ingredient houses. |
| Pea-Derived Oligosaccharide R&D | Pulse protein residue valorization converges with plant-protein formulation trends in bakery and beverage applications. |
| Synbiotic Formulation Partnerships | Combined prebiotic-probiotic offerings displace standalone oligosaccharide sourcing for German and French branded manufacturers. |
Research Methodology
EFSA novel food registers, EU customs trade databases, and REACH authorization filings formed the secondary backbone for supply chain mapping and regulatory timeline reconstruction. Primary interviews with extraction plant managers, infant formula procurement leads, dairy cooperative technical directors, and dietary supplement brand managers validated capacity expansion plans and pricing dynamics. Bottom-up and top-down triangulation reconciled processor capacity announcements with downstream demand aggregation across food, supplement, and pharmaceutical segments.
Bottom-up modeling anchored volume projections to named facility expansions and enzymatic synthesis capacity additions, while top-down approaches cross-checked against EU functional food market trajectories. Segmentation dimensions spanned product type, end-use industry, source provenance, and application positioning. CAGRs were derived from slope analysis of segment-specific demand curves calibrated to EFSA approval timelines and dairy processor integration patterns.
Several conditions sit outside the modeled scope, including pending EFSA determinations on microbiome health claims, weather-induced chicory root harvest shocks, and synthetic prebiotic pathway authorization restrictions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Italy Protein Market
Functional Food & Ingredients
Europe Omega-3 PUFA Market
Functional Food & Ingredients
Functional Food Ingredients Market
Functional Food & Ingredients
Global Medical Foods Market
Functional Food & Ingredients
Prebiotic Ingredients Market
Functional Food & Ingredients
Asia-Pacific Omega3 PUFA Market
Functional Food & Ingredients
Brazil Flavored and Functional Water Market
Functional Food & Ingredients
Prickly Pear Fruit Metabolic Health Ingredients Market
Functional Food & Ingredients
Protein Cookie Market
Functional Food & Ingredients
Global Whole Grain and High Fiber Food Market
Functional Food & Ingredients
Refined Functional Carbohydrates Market
Functional Food & Ingredients
Mediterranean Cognitive-First Ingredient Systems Market
Functional Food & Ingredients
Poultry Probiotic Ingredients Market
Functional Food & Ingredients
Banana Leaf Extract Market
Functional Food & Ingredients
Global Probiotic Ingredients Market
Functional Food & Ingredients
Vegan DHA Market