
 Flash Calling Authentication Market | 2026-2036
Flash Calling Authentication Market Size, Share, and Industry Trends Forecast 2026-2036
Flash Calling Authentication Market Foresight
Enterprise buyer concentration in financial services is consolidating around tier-one mobile banking platforms that demand carrier-grade flash calling reliability. Deutsche Telekom leverages its integrated telecom infrastructure to deliver network-layer authentication directly to European banks. Meta competes through WhatsApp Business API integrations that embed flash calling into merchant onboarding flows. Apple differentiates by binding flash call verification to its device-native security enclaves, creating hardware-trust dependencies that standard SMS cannot replicate.
Flash calling authentication transmits a brief, unanswered voice call to verify user identity through caller-ID matching rather than message delivery, typically completing in under three seconds with lower latency than SMS-based one-time passcodes. The technology's primary commercial purpose is to reduce operational authentication costs while bypassing SMS interception vulnerabilities in high-fraud environments. One-time passcode alternatives still dominate transaction volumes but behavioral biometrics represents the fastest-expanding segment as financial institutions layer silent risk signals beneath the flash call event. Cloud-based deployment models anchor new implementations, though hybrid architectures persist among regulated financial institutions requiring data residency controls.
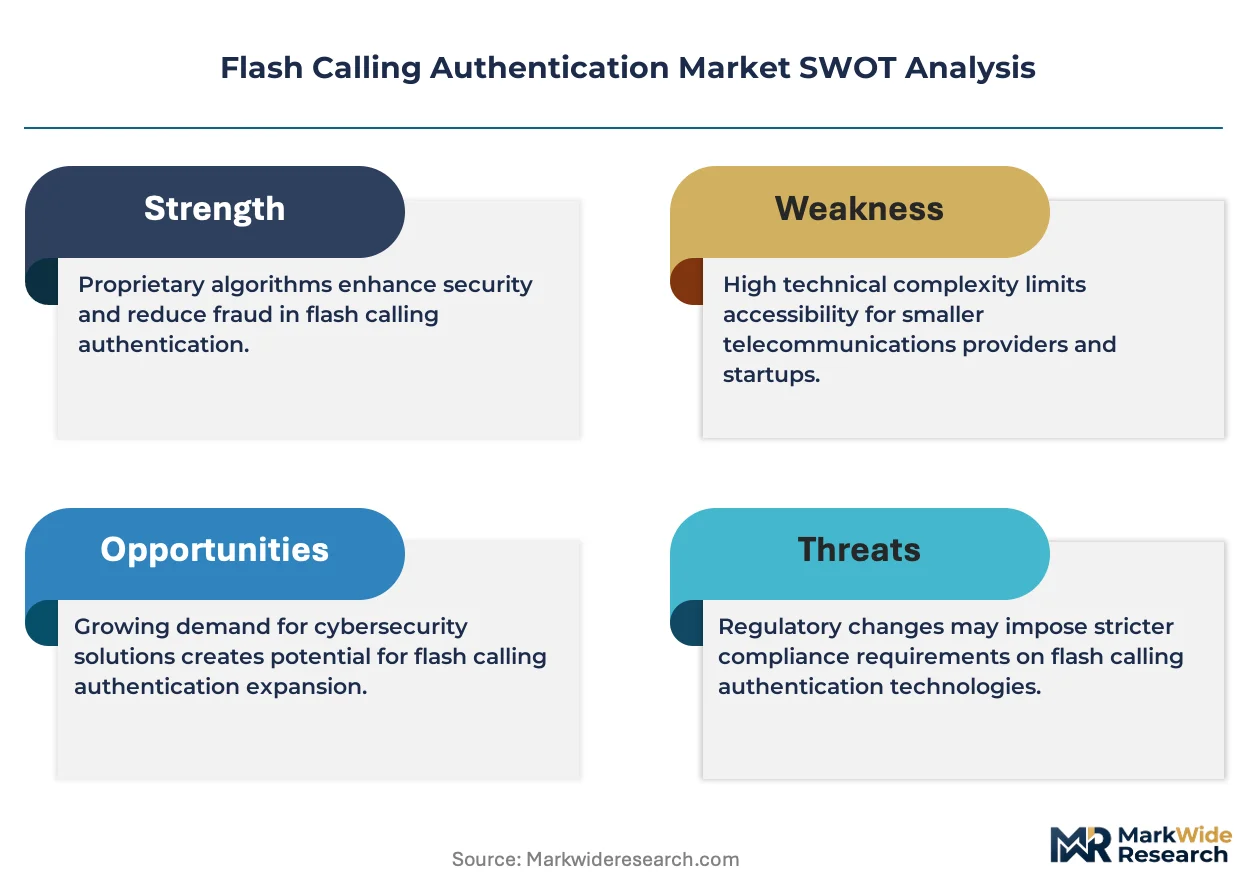
FCC rules on caller-ID authentication under STIR/SHAKEN frameworks compel US telecom operators to upgrade signaling infrastructure, directly expanding addressable flash calling capacity. ETSI standards in Europe and India's TRAI anti-spam mandates create parallel compliance-driven procurement cycles across three continents. Stakeholders must monitor whether carrier billing disputes over unanswered call classification will reshape unit economics before authentication volumes scale.
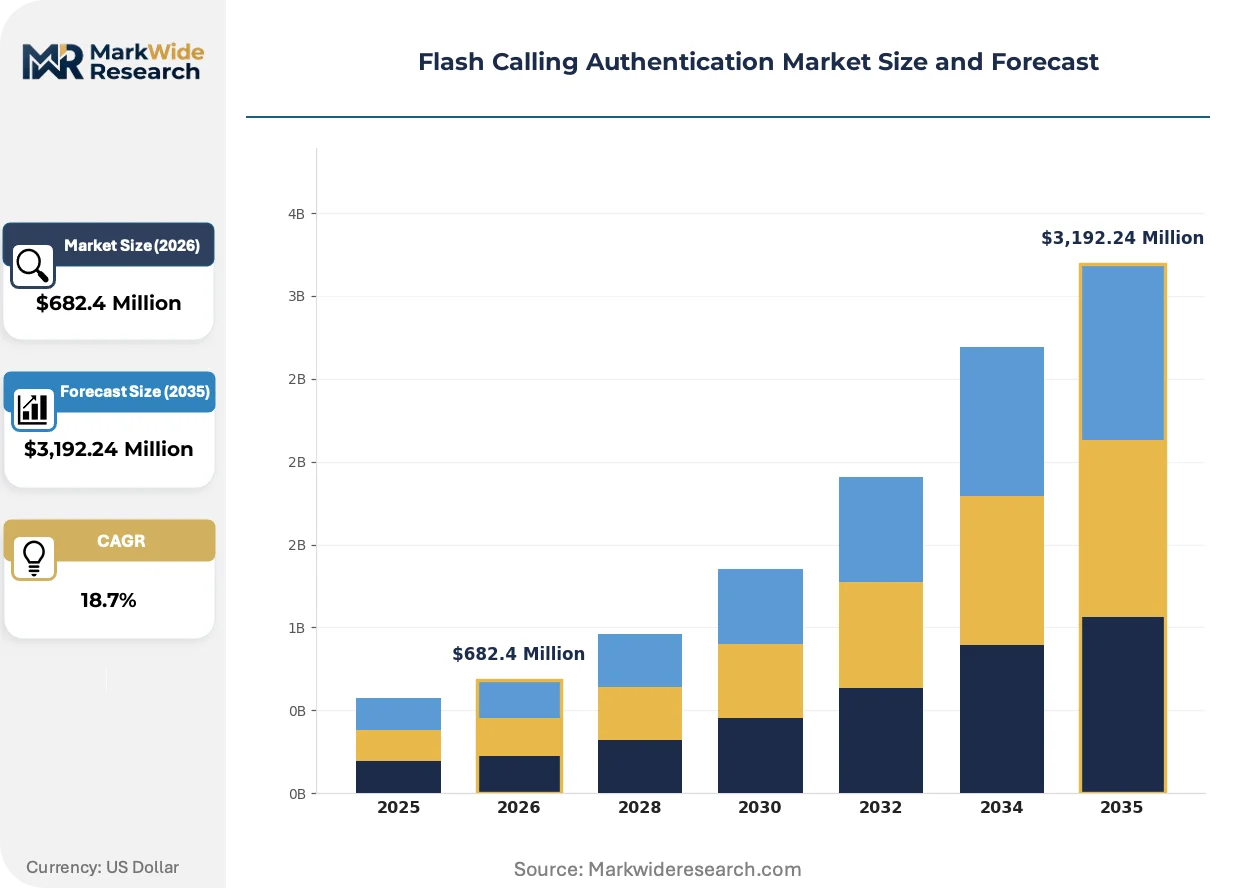
Market Dynamics
Carrier billing disputes over unanswered call classification are compressing unit economics while authentication volumes scale, forcing operators and banks to renegotiate revenue-sharing frameworks before flash calling reaches mass deployment.
Growth Catalysts
- SMS vulnerability bypass:Financial institutions in high-fraud corridors are abandoning intercept-prone text messages for caller-ID matching that completes verification in under three seconds.
- TRAI anti-spam mandates:India's telecom regulator compels operators to deploy authenticated caller-ID infrastructure, directly expanding flash calling capacity for UPI-linked account verification.
- Behavioral biometrics layering:Silent risk signals embedded beneath flash call events allow banks to score transaction risk without adding user friction.
Market Restraints
- Interconnect fee ambiguity:Unanswered call classification disputes between originating and terminating carriers create unpredictable cost structures that erode authentication margins.
- Device fragmentation:Inconsistent caller-ID display implementations across Android OEMs and legacy feature phones degrade verification reliability in price-sensitive markets.
- STIR/SHAKEN compliance costs:FCC-mandated signaling infrastructure upgrades require capital expenditure that smaller regional carriers cannot absorb without tariff increases.
Strategic Opportunities
- EU AI Act alignment:Telecom operators can architect privacy-preserving authentication protocols that satisfy GDPR and emerging AI governance requirements simultaneously.
- Merchant onboarding automation:Embedded flash calling within messaging platform business APIs reduces KYC abandonment rates for micro-merchant enrollment.
- Hardware-trust binding:Device-native security enclaves create differentiation opportunities that standard network-layer verification cannot replicate.
Industry Challenges
- Legacy core banking integration:Decades-old authentication middleware at tier-two financial institutions requires expensive API refactoring to accept caller-ID tokens.
- Cross-border signaling interoperability:Incompatible national implementations of caller-ID authentication standards fragment addressable markets for multinational banking groups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flash Calling Authentication Market |
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $3,192.24 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Authentication Method: One-Time Passcode, Biometric Verification, Knowledge-Based Authentication, Token-Based Validation, Behavioral Biometrics, Confidence Scoring Application: Mobile Banking, Digital Payments, Account Registration, Fraud Detection, Telecom Network Access, E-Government Services End User: Financial Institutions, Telecom Operators, E-Commerce Platforms, Government Agencies, Insurance Providers, Media Companies Deployment Model: Cloud-Based, On-Premises, Hybrid, Managed Services, API Integration, Software as a Service |
| Companies Covered | Deutsche Telekom, Imo, Apple, Meta, Kakao Talk, BBK, Huawei, Samsung, Bell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flash Calling Authentication Market Shifts & Advancements
Silent risk scoring beneath authentication events is reshaping how financial institutions balance security friction against conversion optimization, embedding invisible fraud detection into sub-three-second verification flows.
Behavioral biometrics is overtaking static device fingerprinting as the dominant silent authentication layer. The technology captures micro-interactions—typing cadence, swipe pressure, gyroscopic tilt—during flash call receipt. Tier-one mobile banking platforms are deploying these signals at scale. This convergence is compressing the addressable market for standalone fraud detection vendors that lack carrier integration.
ETSI standards for caller-ID authentication are compelling European operators to harmonize signaling protocols across national borders. The framework mandates attestation levels for voice calls that flash calling providers must map to authentication confidence scores. German and French banking consortia are negotiating unified technical specifications that will reduce fragmentation costs for cross-border payment verification.
Merchant aggregators now demand authentication cost absorption rather than per-transaction fees. Payment service providers are responding with bundled verification pricing that masks flash calling economics behind platform subscription tiers. This shift is most visible in India's digital payments corridor, where UPI volume growth has compressed merchant tolerance for variable authentication charges.
Flash Calling Authentication Market Segmentation
Flash calling authentication segments diverge sharply between standalone verification layers and embedded banking infrastructure, with integration depth determining carrier billing models and API complexity. Financial institutions prioritize segments that minimize core system refactoring while telecom operators favor deployment models that monetize network-layer identity assets.
Authentication Method:
Integration depth varies from standalone verification events to silent risk signals embedded within broader authentication flows, with carrier-grade implementations demanding tighter coupling to signaling infrastructure.
- One-Time Passcode:Flash calling transmits caller-ID tokens as numeric strings displayed on incoming call screens, bypassing SMS interception vulnerabilities. Demand concentrates in India's UPI corridor where TRAI mandates have expanded authenticated caller-ID capacity for account verification.
- Behavioral Biometrics:Micro-interaction capture—typing cadence, gyroscopic tilt, swipe pressure—occurs during the sub-three-second flash call window without adding user friction. Tier-one mobile banking platforms in Southeast Asia deploy these silent signals at scale to score transaction risk beneath visible authentication events.
- Biometric Verification:Voiceprint matching layered atop flash calling creates multi-factor assurance for high-value transfers.
- Knowledge-Based Authentication:Static challenge questions supplement caller-ID matching in legacy core banking environments requiring minimal API change.
- Token-Based Validation:Cryptographic tokens bound to device hardware security modules resist replay attacks in regulated financial services.
- Confidence Scoring:Machine-learned risk aggregation from multiple signals enables step-up authentication only when thresholds breach.
One-Time Passcode leads volumes today; Behavioral Biometrics is gaining share fastest.
Application:
Application segments stratify by transaction value density and regulatory exposure, with high-frequency low-value payments demanding cost-minimized verification and cross-border corridors requiring attestation-grade assurance.
- Mobile Banking:Tier-one platforms demand carrier-grade reliability with sub-three-second completion and network-layer attestation mapped to authentication confidence scores. Deutsche Telekom delivers this directly to European banks through integrated infrastructure, while Indian banks leverage TRAI-mandated caller-ID expansion for UPI-linked verification.
- Digital Payments:Merchant aggregators now insist on cost absorption rather than per-transaction fees, compressing authentication economics behind platform subscription tiers. India's payment service providers respond with bundled pricing as volume growth erodes tolerance for variable charges.
- Account Registration:KYC abandonment reduction drives WhatsApp Business API integrations that embed flash calling into merchant onboarding flows.
- Fraud Detection:Silent risk scoring beneath visible authentication events enables real-time transaction blocking without user-visible friction.
- Telecom Network Access:Subscriber identity verification for SIM swaps and porting requests leverages native signaling infrastructure.
- E-Government Services:Citizen identity binding for benefit distribution requires compliance with national data residency mandates.
Mobile Banking commands the largest revenue pool; Digital Payments is expanding most quickly.
End User:
End user concentration reflects procurement sophistication, with regulated financial institutions demanding hybrid architectures for data residency and technology platforms seeking cloud-native API consumption.
- Financial Institutions:Tier-one mobile banking platforms consolidate around carrier-grade flash calling with behavioral biometrics layering, while tier-two institutions struggle with decades-old authentication middleware requiring expensive API refactoring. EU AI Act and GDPR compliance are reshaping how these buyers architect caller-ID protocols.
- Telecom Operators:Network-layer identity monetization requires STIR/SHAKEN or ETSI-compliant signaling upgrades that expand addressable flash calling capacity. FCC rules compel US operators to upgrade infrastructure, while European harmonization reduces fragmentation costs.
- E-Commerce Platforms:Checkout friction reduction drives merchant onboarding automation with embedded verification.
- Government Agencies:Citizen service delivery mandates data residency controls that favor on-premises or hybrid deployment.
- Insurance Providers:Policyholder verification for claims processing demands audit trails meeting sector-specific compliance.
- Media Companies:Subscription account sharing detection employs device fingerprinting combined with caller-ID matching.
Financial Institutions dominate procurement value; Telecom Operators show the steepest expansion trajectory.
Deployment Model:
Deployment choice reflects data sovereignty requirements and capital constraint trade-offs, with regulated entities accepting higher operational burden for control and technology platforms prioritizing speed-to-market.
- Cloud-Based:API-first consumption models anchor new implementations, enabling rapid merchant onboarding and automatic scaling with UPI volume surges. Indian payment providers leverage this for cost absorption strategies that mask authentication economics behind subscription tiers.
- Hybrid:Regulated financial institutions requiring data residency controls split sensitive processing between cloud orchestration and on-premises token generation. EU AI Act alignment demands are accelerating this architecture for privacy-preserving protocols.
- On-Premises:Legacy core banking integration at tier-two institutions maintains authentication middleware unchanged.
- Managed Services:Outsourced operations reduce staffing requirements for specialized signaling expertise.
- API Integration:Embedded delivery through messaging platform business APIs reduces KYC abandonment.
- Software as a Service:Subscription pricing aligns merchant aggregator preferences for predictable cost structures.
Cloud-Based deployments lead new implementations; Hybrid architectures are climbing the fastest among regulated sectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's UPI-linked verification volumes are compressing authentication economics faster than Germany's ETSI-mandated infrastructure buildouts, creating divergent deployment timelines across high-growth and mature corridors.
United States
STIR/SHAKEN framework compliance is compelling tier-one carriers to upgrade signaling infrastructure, directly expanding flash calling capacity for mobile banking verification. FCC rules mandate attestation-grade caller-ID authentication that financial institutions map to confidence scores. New York and San Francisco financial technology clusters are piloting behavioral biometrics layering beneath sub-three-second verification events.
Germany
ETSI standards harmonization is reducing cross-border fragmentation costs for authentication protocols serving multinational banking groups. EU AI Act and GDPR compliance requirements are reshaping how Deutsche Telekom architects privacy-preserving caller-ID systems. Frankfurt's banking consortium is negotiating unified technical specifications for attestation-level voice call verification.
India
TRAI anti-spam mandates are expanding authenticated caller-ID infrastructure capacity for UPI-linked account registration at unprecedented scale. Payment service providers are absorbing authentication costs behind subscription tiers as merchant tolerance for variable charges erodes. Mumbai and Bangalore digital payments corridors are deploying cloud-native flash calling APIs for micro-merchant onboarding automation.
Singapore
Southeast Asian financial institutions are consolidating procurement around carrier-grade flash calling reliability for mobile banking platforms. The country's national telecom regulator enforces caller-ID authentication standards that align with regional cross-border payment verification needs. Singapore's fintech hub is integrating silent risk scoring beneath visible authentication events for transaction friction reduction.
Brazil
Merchant aggregators in Latin America's largest digital payments market are demanding cost absorption models that mirror India's compressed economics. ANVISA and central bank data residency requirements favor hybrid deployment architectures for regulated financial institutions. São Paulo's banking technology cluster is refactoring decades-old authentication middleware to accept caller-ID tokens.
Flash Calling Authentication Market Competitive Landscape
European telecom operators anchor one tier; Asian technology platforms hold another through messaging ecosystem integration. Market structure consolidates around network-layer identity monetization versus embedded API consumption models. Three archetypes dominate: integrated carriers with signaling infrastructure, device-native security enclave binders, and messaging platform embedders. Competitive moves center on carrier billing renegotiation and behavioral biometrics acquisition.
Within the integrated carrier tier, Deutsche Telekom exemplifies network-layer authentication delivery directly to banking consortia. Among device-native security specialists, Apple and Samsung occupy positions that hardware-trust dependencies create against standard network verification. Meta represents the messaging platform embedder archetype through WhatsApp Business API integrations that reduce KYC abandonment.
| Leading Market Players |
|---|
| Deutsche Telekom |
| Imo |
| Apple |
| Meta |
| Kakao Talk |
| BBK |
| Huawei |
| Samsung |
| Bell |
| Others |
Supply & Pricing Matrix
Signaling infrastructure capex in Germany and India flows through carrier-grade authentication tiers, compressing per-transaction economics for financial institutions while elevating hardware-trust premiums for device-native security enclaves.
Pricing Analysis
Capacity additions in India are reshaping price floors for cloud-native flash calling APIs as TRAI-mandated infrastructure expansion floods the UPI corridor with authenticated caller-ID capacity. Authentication economics stratify across premium carrier-grade attestation, standard API-tier verification, and economy bundled-subscription models. Cost compression in the standard tier intensifies because merchant aggregators now demand cost absorption rather than per-transaction fees. Tier-two financial institutions in Latin America exhibit highest price sensitivity; tier-one mobile banking platforms in Southeast Asia prioritize reliability over unit cost.
Supply Chain Analysis
Direct-to-bank channels handle hyperscale financial institution demand for network-layer authentication, while API marketplaces distribute embedded verification to merchant aggregators. Core supply concentrates in Germany, India, and Singapore, where carrier infrastructure and regulatory mandates converge. Critical inputs include STIR/SHAKEN-compliant signaling hardware, ETSI-standard attestation protocols, and behavioral biometrics SDKs. Single-source vulnerability around carrier-grade signaling infrastructure creates concentration risk for multinational banking groups. Distribution runs through telecom operator direct sales for tier-one banks and platform API ecosystems for micro-merchant onboarding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flash calling authentication functions as a geographic-arbitrage play between India's cost-compressed UPI corridor and Germany's premium ETSI-compliant infrastructure tier.
For Market Incumbents: To counter merchant aggregator demands for cost absorption, Deutsche Telekom and integrated carriers should deepen backward integration into behavioral biometrics acquisition, while simultaneously lobbying for ETSI attestation-level mandates that preserve premium pricing against API commoditization. For New Entrants and Emerging Players: Begin with hybrid deployment architectures targeting tier-two Latin American banks struggling with legacy core banking middleware refactoring, using managed services wrappers to mask API complexity and bypass direct carrier negotiations. For Investors and Strategic Acquirers: Consolidation pressure builds where carrier billing disputes over unanswered call classification erode authentication margins, signaling acquisition opportunities among regional signaling specialists with STIR/SHAKEN-ready infrastructure. Watch for TRAI-style mandate adoption in additional high-volume payment corridors as inflection indicator for capacity-driven price floor shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Behavioral Biometrics Acquisition | Silent risk scoring layers differentiate carrier offerings against API commoditization in India's UPI corridor. |
| ETSI Attestation Compliance Investment | German banking consortia demand unified technical specifications for cross-border payment verification assurance. |
| WhatsApp Business API Integration | Embedded flash calling reduces KYC abandonment for micro-merchant onboarding in Southeast Asian markets. |
| Hybrid Deployment Architecture Launch | EU AI Act alignment accelerates privacy-preserving protocols for regulated financial institutions requiring data residency. |
| Carrier Billing Renegotiation | Unanswered call classification disputes force revenue-sharing framework resets before mass deployment scales. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with telecom network engineers, financial institution authentication architects, regulatory compliance officers at tier-one mobile banking platforms, and merchant aggregator product leads. Secondary validation draws from FCC STIR/SHAKEN implementation filings, TRAI anti-spam mandate documentation, ETSI standards publications, and central bank payment system reports. Bottom-up authentication volume modeling triangulates against top-down carrier infrastructure capex disclosures.
Rate-of-change decomposition separates volume growth from unit price compression across the projection horizon. Segmentation dimensions include authentication method, application type, deployment model, and regional regulatory framework cluster. CAGRs derive from carrier infrastructure buildout timelines mapped to financial institution procurement cycles, with UPI volume trajectories and ETSI harmonization schedules as key industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including potential reclassification of unanswered calls under interconnect fee regimes and unforeseen device fragmentation in emerging markets. Forecasts reflect assumptions about regulatory mandate adoption timelines and carrier billing dispute resolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Europe Enterprise Biometrics Market
Biometrics & Identity Management
Europe Biometrics in Government Market
Biometrics & Identity Management
Biometric Point-Of-Sale Terminals Market
Biometrics & Identity Management
Global Behavioral Biometrics Market
Biometrics & Identity Management
Europe Decentralized Identity Market
Biometrics & Identity Management
North America Enterprise Biometrics Market
Biometrics & Identity Management
Biometric Data Encryption Device Market
Biometrics & Identity Management
Global Voice Biometrics Market
Biometrics & Identity Management
China Mobile Biometrics Market
Biometrics & Identity Management
Biometric ATM Market
Biometrics & Identity Management
Middle East and Africa Biometrics in Government Market
Biometrics & Identity Management
Identity Theft Protection Services Market
Biometrics & Identity Management
Global Biometric Identification Market
Biometrics & Identity Management
Multi-Factor Authentication (MFA) Market
Biometrics & Identity Management
Global Biometric Authentication Identification Market
Biometrics & Identity Management
IRIS Biometrics Market