
 United Kingdom Bath Fitting Market | 2026-2036
United Kingdom Bath Fitting Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Bath Fitting Market Analytics
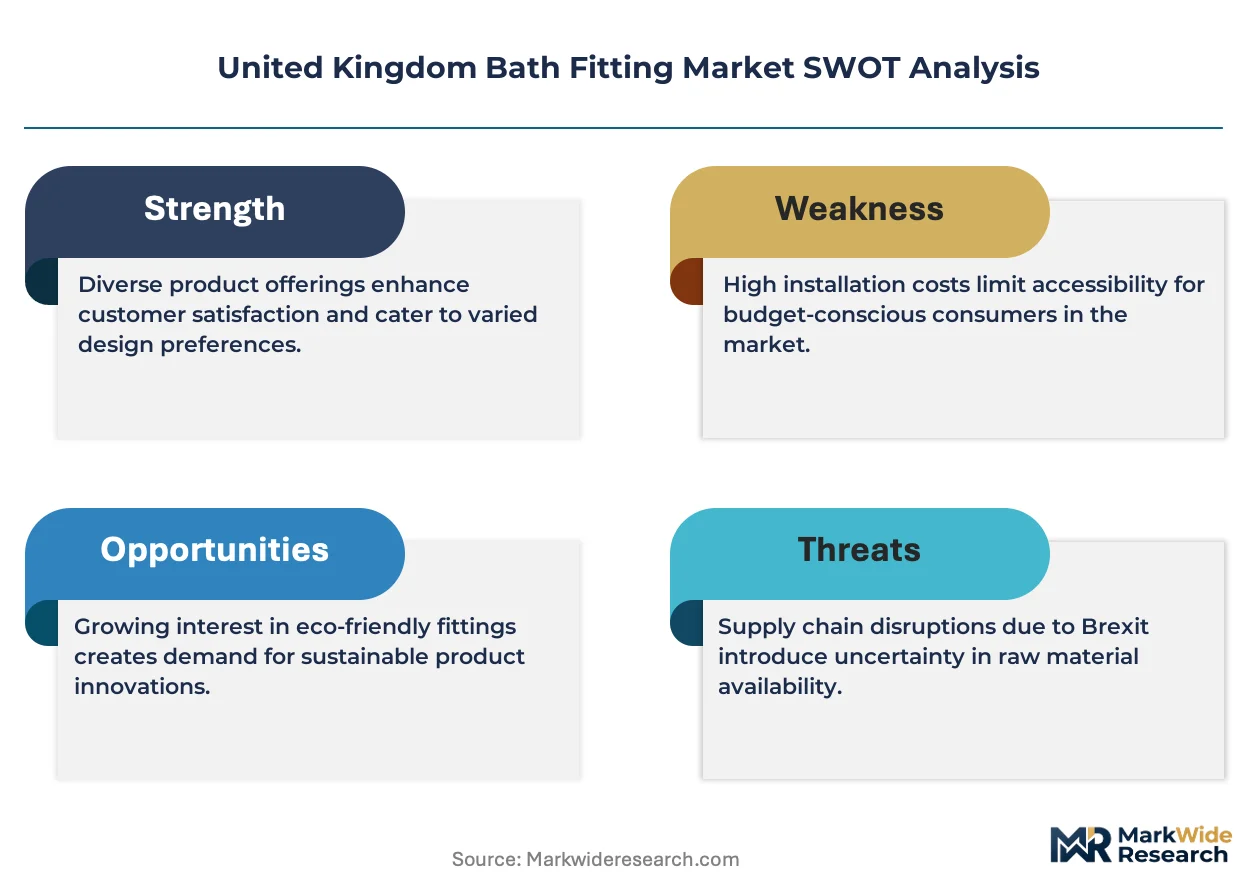
Acrylic is broadening its share in United Kingdom bath fitting production as manufacturers substitute heavier cast-iron and steel vessels. Kohler leverages its vertical manufacturing footprint to control acrylic sheet supply and finished goods distribution across British retail channels. Victorian Plumbing sustains a digitally native model that bypasses traditional merchant networks and captures direct consumer traffic. Burlington Bathrooms anchors its competitive position through heritage-design specialization that commands price premiums in period-property renovations.
United Kingdom bath fittings encompass plumbed fixtures and sanitary ware installed in residential, commercial, and institutional wash environments, typically rated for pressure compatibility between 0.1 and 5 bar and manufactured through thermoforming, casting, or CNC machining processes to deliver water containment, temperature control, and drainage functions. The residential end-user segment dominates volume throughput while the hospitality application generates disproportionate margin contribution through specification-grade durability requirements. Contemporary design styling leads new-build specifications though traditional styling retains defensive margin pools in heritage conservation zones and upscale rural developments.
The UK's Building Regulations Part G and the Water Supply (Water Fittings) Regulations 1999 govern installation standards and water efficiency thresholds, with the Environment Agency enforcing compliance on commercial projects exceeding certain scale thresholds. British Standards Institution (BSI) kitemark certification and WRAS (Water Regulations Advisory Scheme) approval create mandatory gating for product market access in both public procurement and insurance-backed installations. Stakeholders must monitor impending amendments to Part G efficiency targets and the trajectory of UKCA marking convergence with European sanitary ware standards.
Market Dynamics
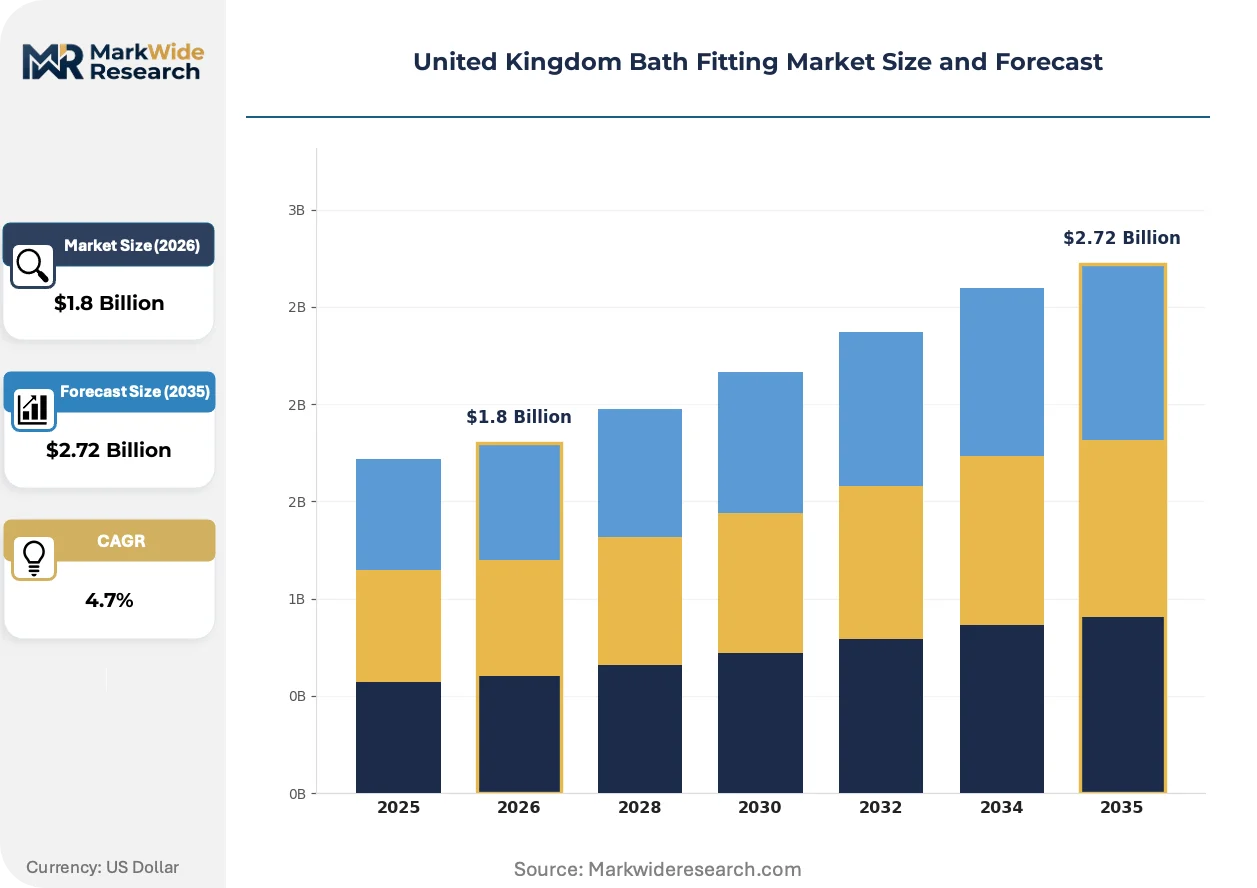
Water efficiency mandates under the UK's Building Regulations Part G are compressing fixture specifications toward low-flow designs while acrylic substitution accelerates material cost restructuring across British manufacturing.
Growth Catalysts
- Part G efficiency thresholds:The UK's Building Regulations Part G mandates maximum flow rates for taps and showers, forcing specification upgrades across new-build and renovation projects.
- Residential renovation intensity:Housing stock turnover in Greater London and the South East generates sustained replacement demand for premium bathroom suites.
- Acrylic thermoforming:Lighter weight and design flexibility in acrylic sheet production enable manufacturers to reduce logistics costs and expand SKU breadth.
Market Restraints
- Brass and copper input volatility:Foundry-grade metal price swings compress margin predictability for tap and mixer manufacturers dependent on alloy feedstock.
- East Asian ceramic supply concentration:Basin and toilet bowl production clusters in Guangdong and Fujian provinces expose British distributors to shipping cost spikes and tariff friction.
- WRAS approval timelines:Water Regulations Advisory Scheme certification requires extended testing cycles that delay product launches by six to twelve months.
Strategic Opportunities
- Scotland's retrofit acceleration:Scottish Government energy efficiency programs fund bathroom upgrades in social housing, creating volume contracts for compliant fixture suppliers.
- Smart shower convergence:Digital thermostatic controls paired with app-based water monitoring appeal to tech-forward renovators in urban centers.
- Direct-to-installer platforms:Digital procurement channels bypass traditional merchant markups and capture trade buyer loyalty through project quoting tools.
Industry Challenges
- Skilled installer scarcity:Qualified plumbing contractors in England face capacity constraints that extend project timelines and inflate labor costs.
- UKCA marking transition:Convergence with European sanitary ware standards creates documentation burdens for manufacturers maintaining dual certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Bath Fitting Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bathtubs, Showers, Faucets, Vanities Material: Ceramic, Acrylic, Metal, Glass Design Style: Contemporary, Traditional, Minimalist, Rustic End User: Residential, Commercial, Hospitality, Institutional |
| Companies Covered | Kohler, TOTO, ROCA, Hansgrohe, Delta Faucets, Victorian Plumbing, Jaquar Group, Villeroy & Boch, Burlington Bathrooms, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Bath Fitting Market Evolving Landscape
Digital control systems and sustainable material substitution are compressing traditional specification patterns while regulatory pressure accelerates compliance-driven product redesign across British supply chains.
Smart thermostatic mixing technology is integrating Bluetooth-enabled temperature control and water usage tracking into shower systems. High-end residential developers in London and Manchester specify these units at accelerating rates. The technology is integrating water efficiency compliance with premium positioning, allowing manufacturers to capture margin premiums while meeting Part G thresholds.
The UK's Building Regulations Part G amendments tighten maximum flow rates for sanitary fittings in new dwellings. Manufacturers must redesign cartridge and aerator configurations to maintain user experience within constrained hydraulic performance bands. Social housing providers and volume housebuilders face the steepest compliance burden, driving specification consolidation toward pre-certified product families.
Trade buyers increasingly consolidate procurement through digital platforms that aggregate stock availability across multiple suppliers. Independent plumbers and small contractors in the Midlands and North West bypass traditional merchant branches for next-day delivery services. This channel shift concentrates purchasing power with platform operators and compresses distributor margins while rewarding inventory visibility and logistics speed.
United Kingdom Bath Fitting Market Segmentation
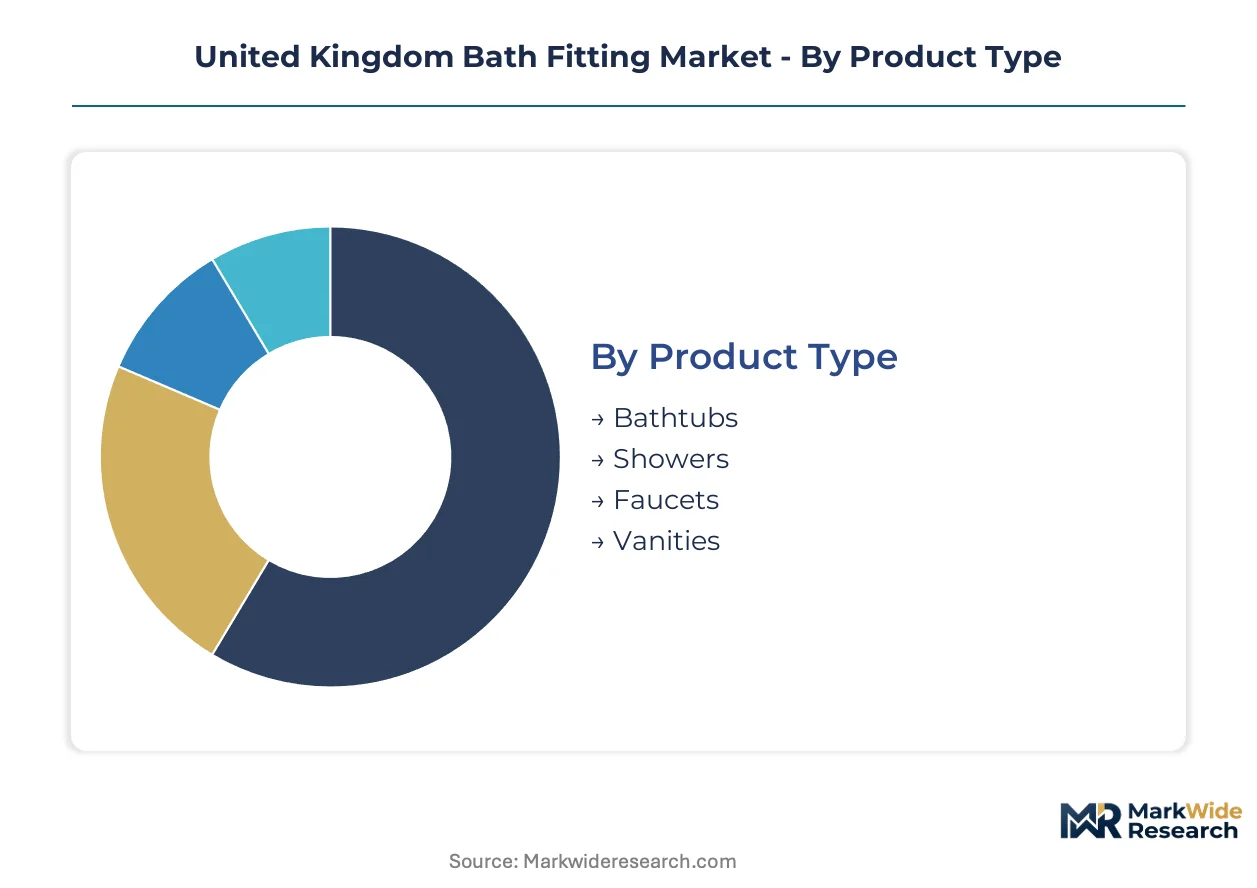
Segmentation in the United Kingdom bath fitting market reveals how upgrade cycles, regulatory compliance, and regional housing stock conditions concentrate demand across distinct product configurations. Understanding these divisions enables suppliers to align inventory depth with replacement intensity in Greater London's premium renovation corridors and Scotland's social housing retrofit programs.
Product Type:
Replacement cycles vary dramatically by fixture category, with full-suite renovations driving bundled purchases while single-item upgrades dominate maintenance workflows.
- Bathtubs:Acrylic thermoformed vessels dominate new specifications due to weight advantages in multi-story residential retrofits. Demand clusters in period-property renovations across England's conservation zones where freestanding designs command specification preference.
- Showers:Digital thermostatic mixer systems integrate Part G compliance with app-based water monitoring. Installers in Manchester and Birmingham specify these units at accelerating rates for tech-forward residential developers seeking efficiency certification.
- Faucets:Brass-bodied mixer cartridges face margin pressure from alloy feedstock volatility.
- Vanities:Modular cabinet systems with integrated basin support speed installation in high-turnover rental refurbishment.
Bathtubs sit at the top of the volume ranking, with showers climbing the fastest.
Material:
Cost tier differentiation separates specification-grade durability from economy retrofit solutions.
- Ceramic:Vitreous china basins and toilet bowls manufactured in East Asian clusters expose British distributors to shipping cost spikes. WRAS approval timelines extend six to twelve months for imported ceramic ware.
- Acrylic:Thermoformed sheet production enables design flexibility and logistics cost reduction. Manufacturers with captive acrylic supply chains control finished goods distribution across British retail channels.
- Metal:Foundry-grade brass and copper price swings compress margin predictability for tap manufacturers.
- Glass:Tempered vessel basins occupy niche positioning in premium urban residential specifications.
Acrylic dominates volume throughput, with glass gaining share fastest in high-end segments.
Design Style:
Customer type and property age dictate styling preferences across renovation versus new-build contexts.
- Contemporary:Clean-line fixtures with concealed fixings lead new-build specifications in London and the South East. Developers specify these units to accelerate sales velocity in competitive prime residential markets.
- Traditional:Heritage-design specialization commands price premiums in period-property renovations. Burlington Bathrooms anchors competitive position through Edwardian and Victorian reproduction lines.
- Minimalist:Wall-hung sanitary ware with integrated cisterns maximizes spatial efficiency in compact urban apartments.
- Rustic:Textured finishes and exposed brassware target rural upscale developments in the Cotswolds and Lake District.
Contemporary styling leads volume, with traditional designs defending the strongest margin pools.
End User:
Application-specific durability requirements create divergent margin structures across installation environments.
- Residential:Private homeowner renovations generate sustained replacement demand across Greater London and the South East. Housing stock turnover outpaces national averages in these regions.
- Commercial:Office washroom fit-outs prioritize vandal-resistant specifications with extended warranty terms.
- Hospitality:Boutique hotels and serviced apartments in Edinburgh and Manchester drive disproportionate margin contribution through specification-grade durability requirements.
- Institutional:Scottish Government energy efficiency programs fund bathroom upgrades in social housing, creating volume contracts for compliant fixture suppliers.
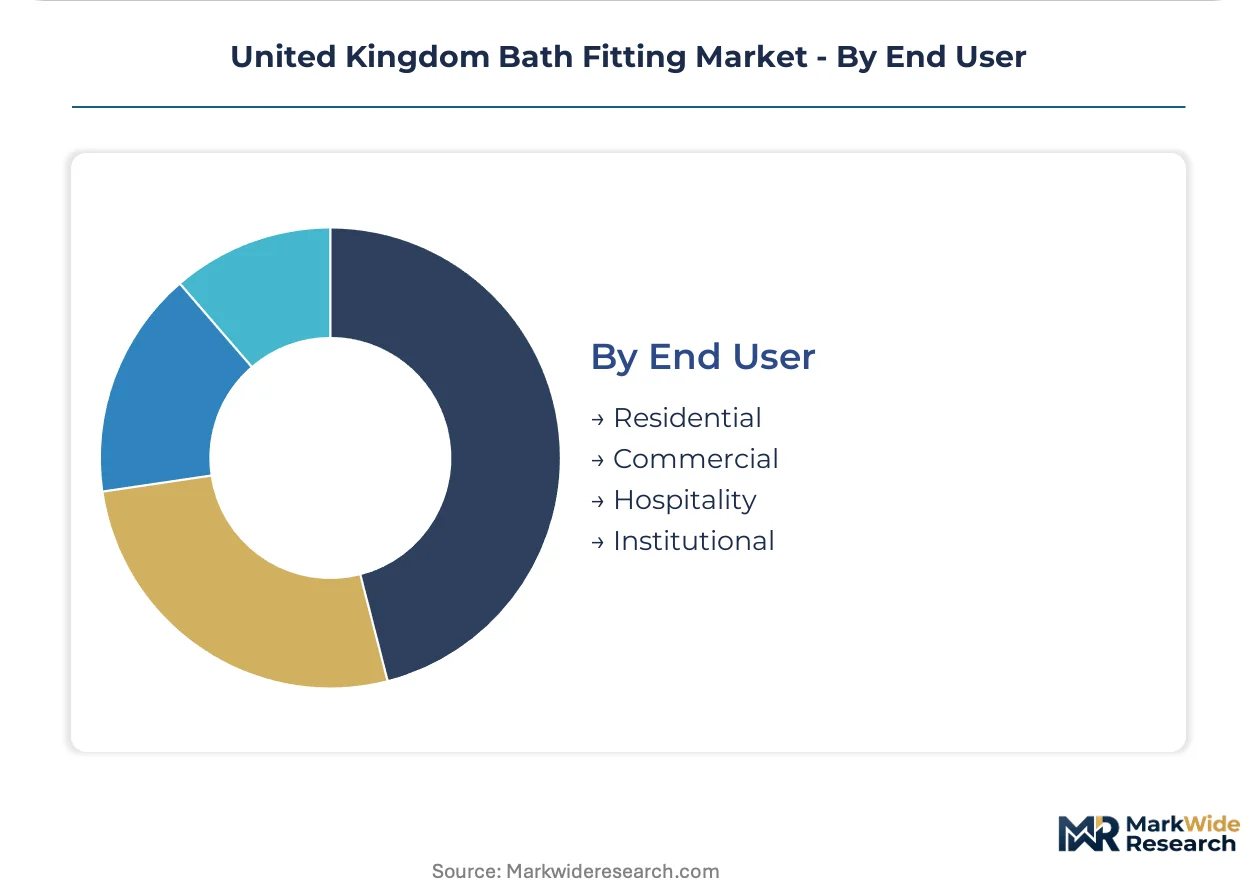
Residential anchors volume throughput, with institutional expanding most quickly through retrofit program funding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater London and the South East concentrate the United Kingdom's bath fitting demand through premium housing turnover and accelerated renovation cycles. England's regulatory environment and Scotland's retrofit funding programs create divergent specification pathways across British sub-regions.
London and the South East
Housing stock turnover in Greater London outpaces national averages, generating sustained replacement demand for specification-grade bathroom suites. The Environment Agency enforces Building Regulations Part G compliance on commercial projects exceeding scale thresholds. High-end residential developers in Kensington and Chelsea specify digital thermostatic systems at accelerating rates.
Midlands
Independent plumbing contractors in Birmingham and the West Midlands bypass traditional merchant branches for digital procurement platforms with next-day delivery. WRAS approval timelines extend product launch cycles for imported ceramic ware entering this distribution corridor. Trade buyer consolidation concentrates purchasing power with platform operators.
North England
Manchester anchors specification demand for tech-forward residential developments integrating smart shower convergence with Part G efficiency certification. Heritage-design reproduction lines command price premiums in period-property renovations across Yorkshire conservation zones. Brass-bodied mixer manufacturers face margin pressure from alloy feedstock volatility.
Scotland
Scottish Government energy efficiency programs fund bathroom upgrades in social housing, creating volume contracts for low-flow fixture suppliers. The Scottish Environment Protection Agency coordinates with building control on Part G enforcement across commercial installations. Edinburgh's boutique hotel sector drives disproportionate margin contribution through durability specifications.
Wales and Northern Ireland
Rural upscale developments in the Welsh Marches and Lake District periphery sustain demand for textured finishes and exposed brassware in rustic styling configurations. Local authority procurement in Belfast prioritizes WRAS-approved pre-certified product families for public housing refurbishment. Distribution logistics face cost premiums serving these peripheral markets.
United Kingdom Bath Fitting Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers balance heritage-design specialization against smart technology integration. The vendor base stratifies across three tiers: multinational plumbing conglomerates with captive acrylic supply chains, digitally native direct-to-consumer platforms, and heritage-design specialists commanding price premiums in conservation zones. Two strategic archetypes define competitive positioning: vertically integrated material controllers and digitally optimized channel bypassers. M&A activity concentrates on acquiring WRAS certification capabilities, while capacity expansion focuses on thermoforming facilities for acrylic sheet production.
Among heritage-design specialists, Burlington Bathrooms anchors the traditional-styling tier through Edwardian and Victorian reproduction lines. Kohler exemplifies the vertically integrated archetype with captive acrylic sheet supply and finished goods distribution across British retail channels. Victorian Plumbing occupies the digitally native position, bypassing traditional merchant networks to capture direct consumer traffic through project quoting tools.
| Leading Market Players |
|---|
| Kohler |
| TOTO |
| ROCA |
| Hansgrohe |
| Delta Faucets |
| Victorian Plumbing |
| Jaquar Group |
| Villeroy & Boch |
| Burlington Bathrooms |
| Others |
Value Network & Pricing Analysis
Foundry-grade brass and copper price indices cascade through British tap manufacturing, compressing margin predictability for alloy-dependent producers while acrylic thermoforming economics enable cost restructuring across lighter-weight fixture categories. Input-cost volatility concentrates pricing power with vertically integrated manufacturers controlling captive sheet supply, leaving merchant-dependent distributors exposed to margin erosion.
Pricing Analysis
Input-cost pass-through from alloy feedstock volatility separates pricing power across three-tier structures spanning premium, standard, and economy levels. WRAS certification tier and brand heritage command differentiation premiums in specification-grade segments. Pricing pressure intensifies in economy basins sourced from East Asian ceramic clusters due to shipping cost spikes and tariff exposure. Volume housebuilders exhibit highest price sensitivity, while heritage-property renovators in conservation zones demonstrate lowest.
Supply Chain Analysis
Workforce availability constraints in England's qualified plumbing contractor pool extend project timelines and inflate labor costs across installation-dependent segments. Manufacturing concentrates in China's Guangdong and Fujian provinces for ceramic ware, with British acrylic thermoforming anchored in domestic facilities. Brass alloy and copper feedstock dependencies expose tap manufacturers to commodity price swings. Single-source vulnerability runs through East Asian ceramic production clusters. Distribution runs through digital procurement platforms consolidating trade buyer purchasing power.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom bath fitting market functions as a geographic-arbitrage play between Scotland's retrofit-funded volume contracts and Greater London's premium renovation corridors, with Part G compliance thresholds creating divergent specification economics across sub-regions.
For Market Incumbents: Anchor defensive positioning through backward integration into acrylic sheet supply chains and WRAS certification capacity expansion. Digital-native platforms threaten traditional merchant networks through direct-to-installer procurement channels. Capacity addition in thermoforming facilities secures cost control against alloy-dependent competitors. For New Entrants and Emerging Players: Part G amendments in England open a window for low-flow fixture specialists capturing social housing retrofit volume. White-space targets include Scotland's institutional procurement corridors and Manchester's tech-forward residential developer segment. Direct-to-installer platforms with project quoting tools offer the most penetrable go-to-market angle for bypassing established merchant markups. For Investors and Strategic Acquirers: Asymmetric upside sits with digitally optimized channel bypassers and heritage-design specialists commanding conservation-zone premiums. Long-term viability centers on regulatory compliance capabilities converging with sustainability positioning. Acquisition target archetype: WRAS-certified manufacturers with captive acrylic supply. Signal to watch: Part G enforcement intensity on commercial scale thresholds as volume inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Sheet Production | Captive supply chains insulate Kohler and peers from logistics cost spikes and enable SKU breadth expansion. |
| WRAS Certification Capacity Expansion | Accelerated approval timelines compress six-to-twelve month launch delays for compliant fixture suppliers. |
| Direct-to-Installer Platform Launch | Victorian Plumbing's digitally native model demonstrates trade buyer loyalty capture through project quoting tools. |
| Heritage-Design Specialization | Burlington Bathrooms anchors Edwardian and Victorian reproduction lines commanding price premiums in period-property renovations. |
| Smart Thermostatic Control Integration | Digital shower systems merge Part G compliance with app-based water monitoring for tech-forward urban developers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with bath fitting manufacturers, merchant branch managers, independent plumbing contractors, and social housing procurement officers with secondary validation against WRAS approval databases, Building Regulations Part G amendment documentation, and Environment Agency enforcement records. Customs data on ceramic ware imports and British Standards Institution kitemark registries anchored supply-side triangulation. Bottom-up fixture shipment analysis and top-down construction spend modeling converged on volume estimates.
Segment-weighting across product type, material composition, design styling, and end-user application dimensions structured the analytical framework across the projection horizon. Residential renovation intensity in Greater London and Scotland's retrofit program funding trajectories informed regional demand allocation. CAGRs derived from housing stock turnover rates, regulatory compliance phase-in schedules, and material substitution elasticity parameters.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt Part G threshold revisions or East Asian supply chain disruptions. Assumptions reflect documented regulatory trajectories and trade flow patterns. Material deviation in brass alloy price volatility or WRAS approval timeline extensions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
India Steam Rooms Market
Bathroom Fixtures and Accessories
Vietnam Sanitary Ware & Bathroom Accessories Market
Bathroom Fixtures and Accessories
New Zealand Bathroom Products Market
Bathroom Fixtures and Accessories
Bathroom Accessories Market
Bathroom Fixtures and Accessories
Shower Tray Market
Bathroom Fixtures and Accessories
Bathroom Sink Market
Bathroom Fixtures and Accessories
Shower Chairs Market
Bathroom Fixtures and Accessories
Europe Bath Fitting Market
Bathroom Fixtures and Accessories
United States Bath Fitting Market
Bathroom Fixtures and Accessories
Water Sink Market
Bathroom Fixtures and Accessories
Sanitary Ware and Bathroom Accessories Market
Bathroom Fixtures and Accessories
Europe Bath and Shower Products Market
Bathroom Fixtures and Accessories
Germany Bathroom Furniture Market
Bathroom Fixtures and Accessories
Luxury Plumbing Fixtures Market
Bathroom Fixtures and Accessories
North America Traditional Toilet Seat Market
Bathroom Fixtures and Accessories
India Shower Cubicle Market