
 Global Car GPS Navigation System Market | 2026-2036
Global Car GPS Navigation System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Car GPS Navigation System Market Analysis
South Korean component manufacturers is consolidating output of multi-frequency GNSS receivers for Tier-1 automotive suppliers. Garmin Ltd. leverages its aviation-grade positioning algorithms to differentiate in premium aftermarket segments. TomTom International BV anchors European map database licensing through long-term OEM partnerships with German and French automakers. Continental AG sustains embedded system dominance through backward integration into antenna module production.
A car GPS navigation system comprises a satellite signal receiver, digital map database, route calculation processor, and display interface, typically operating on L1/L2/L5 frequency bands with real-time kinematic correction for sub-meter accuracy. Its commercial purpose centers on dynamic route optimization, traffic-aware guidance, and fleet telematics integration for logistics operators. Embedded systems command the highest margin pools due to automaker certification cycles and proprietary software stacks, while smartphone applications compete aggressively on zero-hardware-cost models. Cloud computing layers represent the fastest-expanding technology segment as over-the-air map updates replace physical storage.
The Federal Communications Commission in the United States governs spectrum allocation for GPS augmentation services, while the European Union's Radio Equipment Directive mandates cybersecurity standards for connected navigation hardware. Japan's Ministry of Economy, Trade and Industry coordinates QZSS constellation integration with domestic automakers through JIS certification pathways. Stakeholders must monitor regulatory divergence between regional satellite constellations and data localization requirements as they evaluate platform standardization versus market-specific customization.
Market Dynamics
Cloud computing layers are displacing physical map storage across automotive navigation platforms, forcing hardware suppliers to restructure margin capture around software subscription models rather than one-time component sales.
Growth Catalysts
- EU AI Act compliance mandates:German and French automakers must certify embedded navigation systems for algorithmic transparency, creating guaranteed demand for compliant platform upgrades across European production lines.
- Fleet telematics integration:Commercial logistics operators in the United States are mandating real-time vehicle tracking for route optimization and fuel efficiency monitoring.
- Multi-frequency GNSS receiver proliferation:South Korean component manufacturers are scaling L1/L2/L5 band reception modules to serve Tier-1 automotive suppliers with sub-meter accuracy requirements.
Market Restraints
- Semiconductor input volatility:Advanced GNSS receiver chipsets depend on specialized silicon foundry capacity concentrated in Taiwan, exposing supply chains to geopolitical disruption risk.
- Smartphone navigation substitution:Zero-hardware-cost mobile applications are compressing aftermarket device pricing power and eroding standalone PND unit volumes.
- Data localization requirements:China's cross-border data transfer restrictions force foreign navigation providers to establish domestic cloud infrastructure, raising operational complexity.
Strategic Opportunities
- India's connected vehicle mandate:The country's automotive regulator is preparing telematics requirements for commercial fleets, opening embedded system penetration in a historically underpenetrated market.
- QZSS-METI convergence:Japan's Ministry of Economy, Trade and Industry is coordinating centimeter-level augmentation service integration with domestic automakers for autonomous driving readiness.
- Over-the-air update channel expansion:Automakers are unbundling map refresh cycles from vehicle purchase, creating recurring revenue streams through direct-to-vehicle software distribution.
Industry Challenges
- Cybersecurity certification timelines:The European Union's Radio Equipment Directive mandates extended hardware validation cycles that delay product launches by 12-18 months.
- Legacy antenna integration complexity:Embedded navigation suppliers must engineer backward-compatible modules for automaker platforms spanning multiple electrical architectures.
- Real-time kinematic skill scarcity:Positioning algorithm development requires rare expertise combining satellite geodesy with automotive-grade software engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Car GPS Navigation System Market |
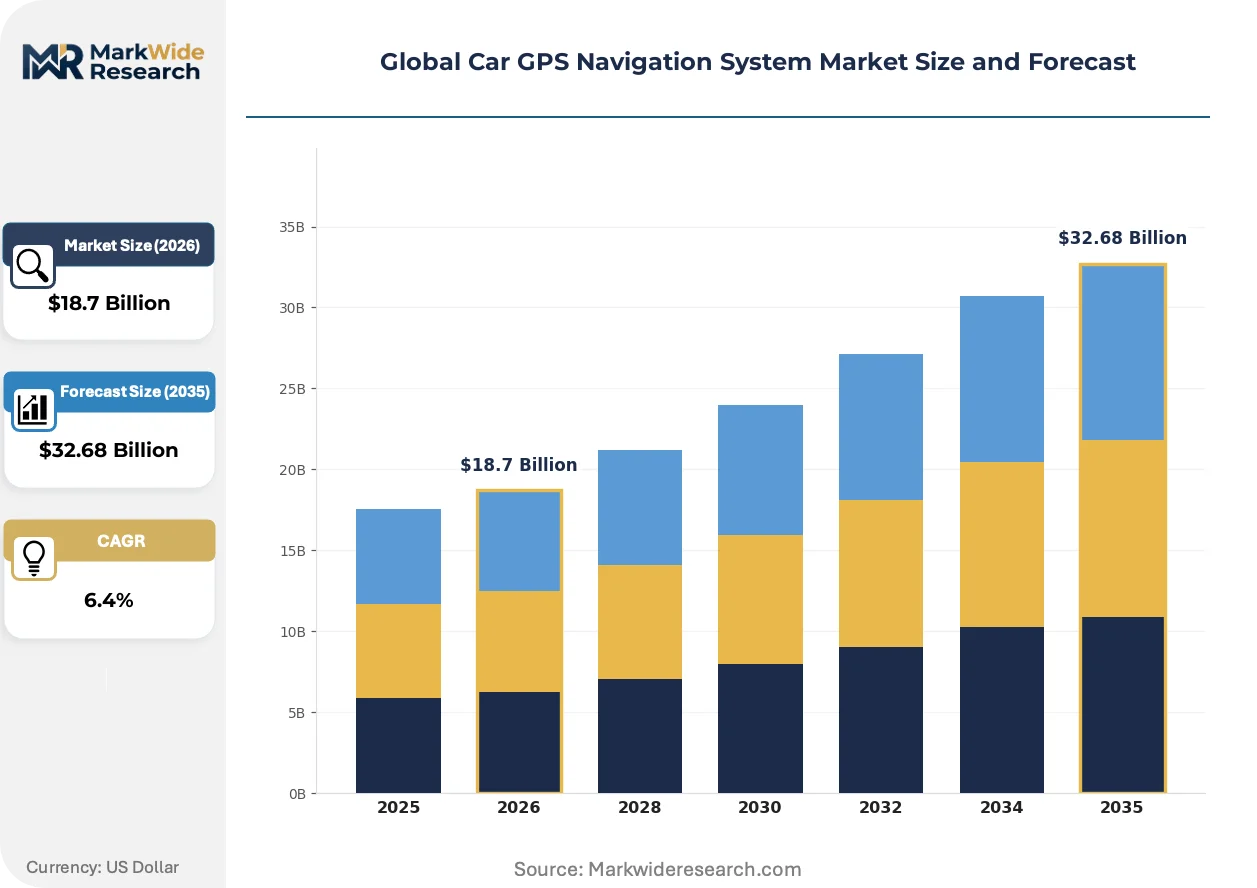
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Embedded Systems, Smartphone Applications, Wearable Devices Technology: Satellite-Based, Map Database, Cloud Computing, Digital Signal Processing End User: Commercial Fleets, Individual Consumers, Transportation Services, Emergency Services Distribution Channel: Online Retail, Offline Retail, Direct Sales, Third-Party Resellers |
| Companies Covered | Garmin Ltd., TomTom International BV, Continental AG, Robert Bosch GmbH, Denso Corporation, Alpine Electronics, Pioneer Corporation, Panasonic Corporation, JVCKENWOOD Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Car GPS Navigation System Market Emerging Trajectories
Satellite positioning hardware is fusing with cloud-native software architectures, compressing traditional boundaries between embedded automotive electronics and consumer mobile platforms.
Multi-constellation GNSS receivers are converging with edge computing modules to enable real-time sensor fusion for lane-level navigation accuracy. German luxury automakers are adopting these integrated platforms for highway pilot systems. This convergence is collapsing the historical separation between positioning hardware suppliers and autonomous driving software developers.
The EU AI Act's algorithmic accountability requirements are mandating explainable route calculation logic in embedded navigation systems. Automotive suppliers must document decision pathways for dynamic rerouting algorithms. European OEM partnerships with map database licensors are restructuring to include audit rights and transparency clauses.
Fleet procurement departments are consolidating vendor relationships around integrated telematics-navigation bundles rather than standalone GPS devices. Third-party logistics operators in the United States are demanding unified platforms combining routing, driver behavior monitoring, and fuel consumption analytics. This consolidation favors suppliers with captive software development capabilities over pure hardware manufacturers.
Global Car GPS Navigation System Market Segmentation
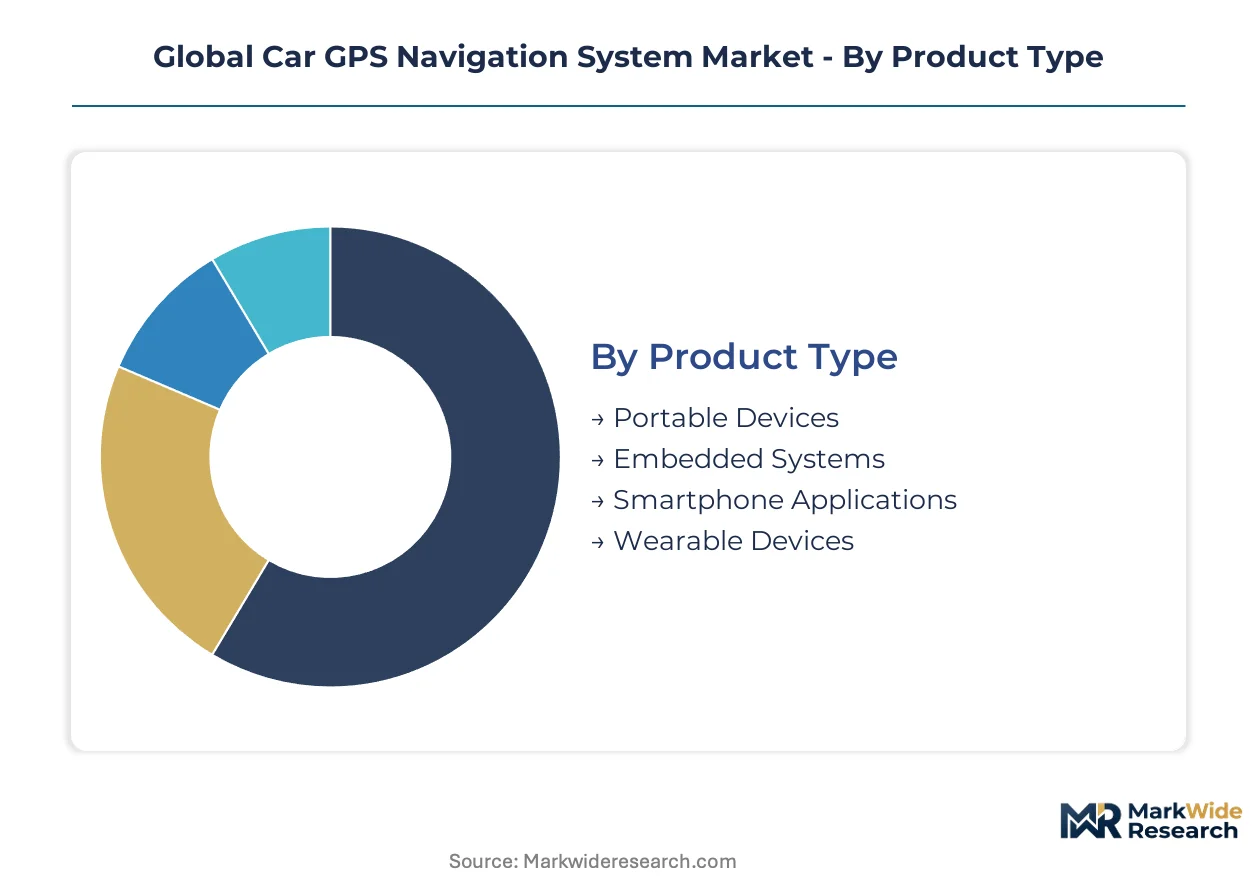
Segmentation in the car GPS navigation system market reveals divergent margin architectures across hardware, software, and service layers. Product type splits expose the tension between automaker-controlled embedded platforms and zero-cost smartphone substitutes. Technology and end-user dimensions further fragment competitive positioning between precision-demanding commercial operators and price-sensitive individual buyers.
Product Type:
The volume versus premium divide separates one-time hardware sales from recurring software revenue pools.
- Embedded Systems:Factory-integrated navigation modules operate on proprietary automotive-grade software stacks with multi-year certification cycles. German and French automakers anchor demand through EU AI Act compliance mandates for algorithmic transparency in route calculation logic. These systems command the highest margin pools due to backward integration into antenna module production and exclusive OEM partnerships.
- Smartphone Applications:Zero-hardware-cost mobile platforms leverage cloud-native map databases with over-the-air update distribution. Individual consumers in China and the United States drive volume through substitution effects that compress aftermarket device pricing power and erode standalone portable unit demand.
- Portable Devices:Standalone navigation hardware with dedicated GNSS receivers serves aftermarket retrofit demand from vehicle owners lacking factory-installed systems.
- Wearable Devices:Wrist-mounted or head-up display formats target motorcycle operators and specialty vehicle segments requiring minimal installation footprint.
Today's leader: Embedded Systems. Tomorrow's challenger: Smartphone Applications.
Technology:
Supply concentration in semiconductor foundries shapes which technology layers capture value.
- Cloud Computing:Distributed software architectures enable real-time traffic fusion, over-the-air map refreshes, and subscription-based revenue models. Commercial fleets in the United States demand these platforms for unified telematics integration combining routing, driver behavior monitoring, and fuel consumption analytics. Cloud layers are displacing physical storage and expanding most quickly as automakers unbundle map refresh cycles from vehicle purchase.
- Satellite-Based:Multi-frequency GNSS receivers operating on L1/L2/L5 bands with real-time kinematic correction deliver sub-meter positioning accuracy. South Korean component manufacturers are scaling production of these modules for Tier-1 automotive suppliers serving autonomous driving readiness programs in Japan and Germany.
- Map Database:Licensed geographic information systems with centimeter-level road geometry and point-of-interest metadata form the foundational content layer for all navigation platforms.
- Digital Signal Processing:Specialized chipsets filter multipath interference and atmospheric distortion to maintain lock in urban canyon environments.
Cloud Computing is climbing the fastest. Map Database licensing retains the most defensive moat.
End User:
Procurement sophistication separates enterprise buyers with technical specifications from individual purchasers prioritizing convenience.
- Commercial Fleets:Logistics operators and transportation services mandate real-time vehicle tracking, route optimization, and regulatory compliance documentation. The FCC governs spectrum allocation for GPS augmentation services supporting these deployments in the United States, while India's connected vehicle mandate is preparing telematics requirements that will open embedded system penetration.
- Emergency Services:Police, fire, and ambulance fleets require mission-critical positioning with guaranteed availability and integration into computer-aided dispatch systems.
- Individual Consumers:Private vehicle owners select navigation solutions based on upfront cost, interface familiarity, and smartphone ecosystem integration.
- Transportation Services:Ride-hailing and delivery platforms optimize driver routing algorithms against dynamic pricing and customer wait-time constraints.
Commercial Fleets dominate current procurement volume. Emergency Services present the steepest certification barrier.
Distribution Channel:
Channel selection reflects the hardware-software boundary and customer technical competence.
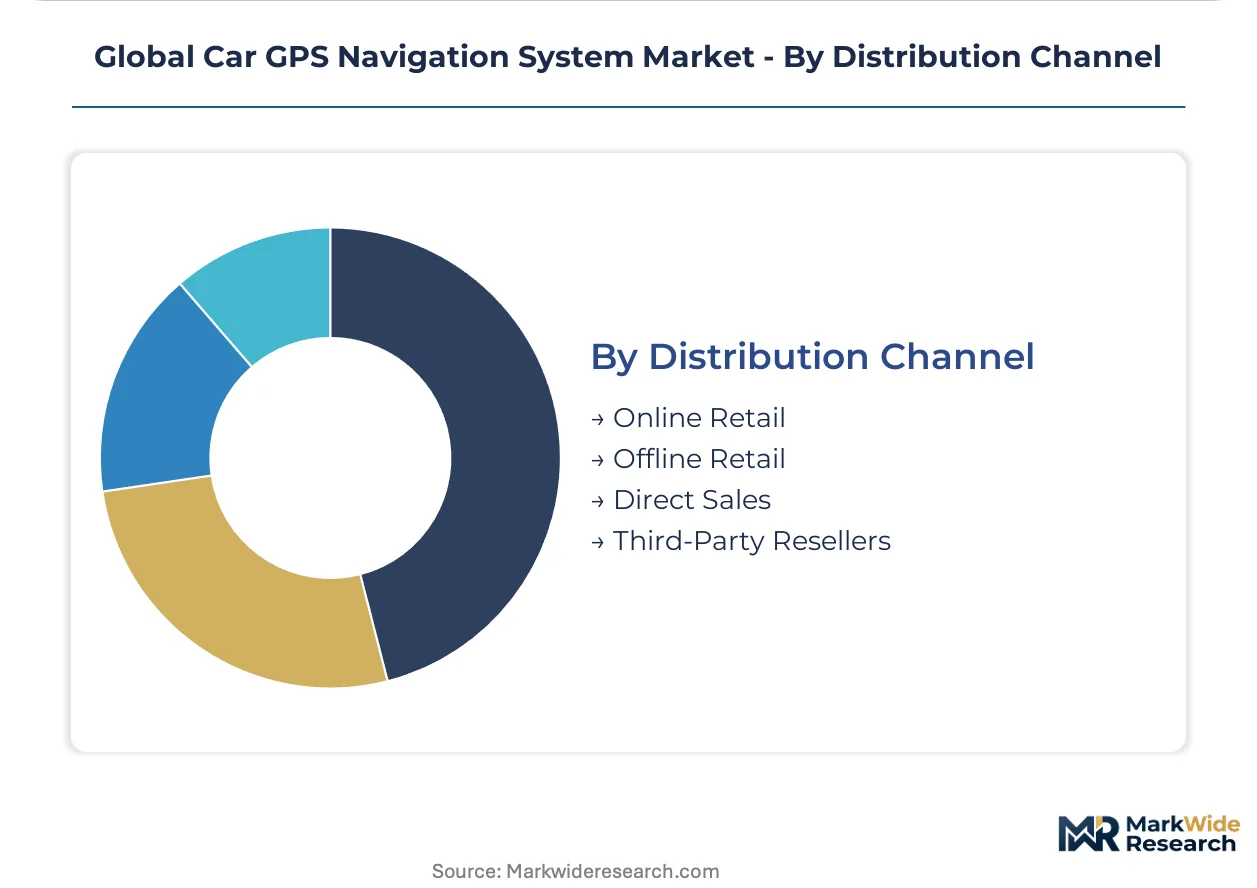
- Direct Sales:Automakers and Tier-1 suppliers distribute embedded navigation systems through captive vehicle configuration pipelines with multi-year contractual lock-in.
- Online Retail:E-commerce platforms serve aftermarket portable device demand and software subscription acquisition with comparison shopping transparency.
- Offline Retail:Electronics retailers and automotive specialty stores provide hands-on evaluation for consumers prioritizing physical product inspection.
- Third-Party Resellers:Independent distributors aggregate fragmented demand from smaller fleet operators and regional transportation services lacking direct OEM relationships.
Direct Sales secures the longest contract duration. Online Retail is gaining share fastest in aftermarket segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting embedded navigation system production toward jurisdictions with streamlined certification pathways, as EU AI Act compliance costs reshape supplier location decisions across the automotive electronics value chain.
United States
Commercial fleet operators in the United States are mandating unified telematics-navigation platforms for route optimization and fuel efficiency monitoring. The FCC governs spectrum allocation for GPS augmentation services supporting these deployments. Detroit-Warren-Dearborn anchors embedded system integration for domestic automakers pursuing over-the-air update capabilities.
Germany
German luxury automakers are adopting multi-constellation GNSS receivers with edge computing modules for highway pilot systems. The KBA coordinates type approval for connected navigation hardware under EU cybersecurity mandates. Stuttgart metropolitan area concentrates Tier-1 supplier engineering centers for real-time kinematic algorithm development.
China
Domestic automakers in China are integrating satellite-based navigation with cloud computing layers for dynamic traffic fusion. Cross-border data transfer restrictions under national cybersecurity law force foreign providers to establish domestic cloud infrastructure. Yangtze River Delta clusters host the principal manufacturing bases for multi-frequency GNSS receiver modules.
Japan
Japanese automakers are coordinating with METI on QZSS constellation integration for centimeter-level augmentation services. JIS certification pathways govern embedded navigation hardware validation for autonomous driving readiness. Nagoya metropolitan area anchors the production of automotive-grade antenna modules with backward-compatible electrical architectures.
South Korea
South Korean component manufacturers are scaling output of L1/L2/L5 band reception modules for sub-meter accuracy requirements. The country's national automotive regulator aligns connected-vehicle mandates with international cybersecurity standards. Seoul Capital Area concentrates foundry-adjacent packaging facilities for specialized GNSS receiver chipsets.
Global Car GPS Navigation System Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native software overlays and subscription revenue models. The supplier base stratifies across three tiers: vertically integrated automotive electronics conglomerates, specialized positioning technology developers, and mobile platform operators leveraging zero-hardware-cost distribution. Two dominant competitive moves are reshaping positioning: strategic partnerships between map database licensors and automakers for exclusive OEM access, and backward integration into antenna module production to capture margin pools from hardware-software convergence.
Within the specialized positioning tier, Garmin Ltd. and TomTom International BV exemplify divergent strategic archetypes. Garmin Ltd. anchors aviation-grade algorithm expertise repurposed for premium aftermarket segments. TomTom International BV occupies a position centered on European map database licensing through long-term contractual frameworks. Continental AG represents the integrated conglomerate model, with in-house production of antenna modules sustaining embedded system dominance across German and French automaker supply chains.
| Leading Market Players |
|---|
| Garmin Ltd. |
| TomTom International BV |
| Continental AG |
| Robert Bosch GmbH |
| Denso Corporation |
| Alpine Electronics |
| Pioneer Corporation |
| Panasonic Corporation |
| JVCKENWOOD Corporation |
| Others |
Supply Flow & Price Mechanics
Backward integration into antenna module production anchors Continental AG's supply position and secures premium pricing power for embedded navigation platforms serving German automakers. This captive manufacturing model insulates margin capture from semiconductor foundry volatility while enabling exclusive OEM partnerships.
Pricing Analysis
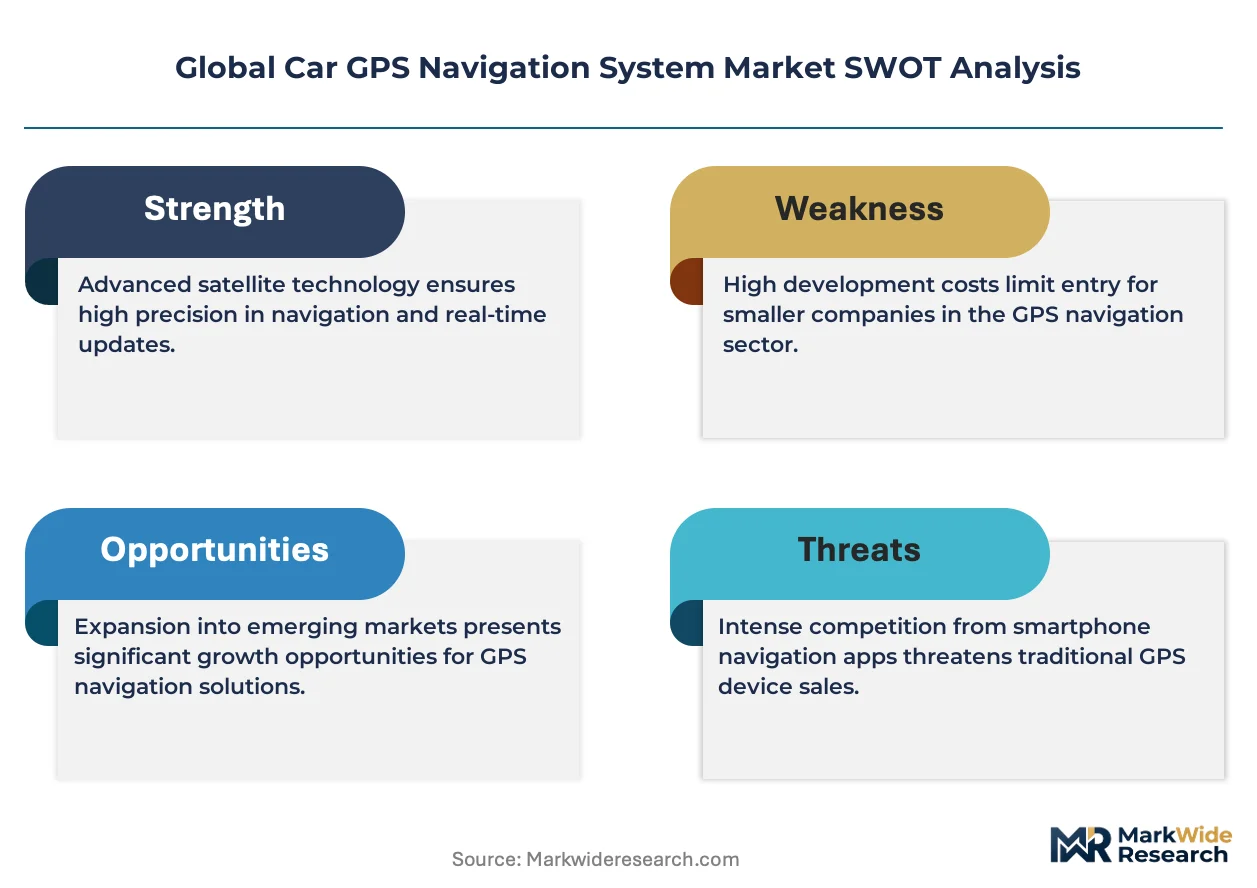
Distributor margin layers in aftermarket portable devices face compression as smartphone applications eliminate hardware attach entirely. Three-tier pricing structure across embedded automotive, aftermarket premium, and economy portable levels separates automaker-certified systems from consumer substitutes. Price differentiation rests on EU AI Act certification grade and real-time kinematic accuracy tier. Cost compression in standalone PND units is intensifying because zero-hardware-cost mobile platforms erode addressable volume. Commercial fleet buyers exhibit lowest price sensitivity due to telematics bundling requirements.
Supply Chain Analysis
Workforce availability constraints in Taiwan and South Korea concentrate specialized GNSS receiver chipset production around Hsinchu and Seoul Capital Area foundry-adjacent packaging facilities. Raw material dependencies draw from gallium arsenide substrates, precision ceramic filters, and automotive-grade substrate materials. Single-source vulnerability in Taiwan-based silicon foundry capacity exposes Tier-1 suppliers to geopolitical disruption risk. Distribution runs through direct automaker configuration pipelines for embedded systems and online retail channels for aftermarket segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU AI Act compliance costs in Germany and France diverge from streamlined certification pathways in South Korea and Japan, creating relocation incentives for embedded system production.
For Market Incumbents: Deploy certification investment as the priority lever. Automakers must document algorithmic transparency for dynamic rerouting logic under EU mandates, creating defensive moats against software-only entrants. Strengthen backward integration into multi-frequency GNSS receiver production to capture margin pools from hardware-software convergence and offset smartphone substitution threats.
For New Entrants and Emerging Players: Cloud-native over-the-air update platforms offer entry wedge into recurring revenue streams as automakers unbundle map refresh cycles from vehicle purchase. India's connected vehicle mandate presents the most penetrable geography for embedded system penetration. Target third-party logistics operators with unified telematics-navigation bundles combining routing and fuel analytics.
For Investors and Strategic Acquirers: Roll-up economics work for specialized positioning algorithm developers because real-time kinematic expertise combining satellite geodesy with automotive software engineering remains scarce and non-replicable. Long-term viability centers on software-defined vehicle integration over the coming decade. Watch QZSS-METI centimeter-level augmentation deployment as inflection indicator for autonomous driving readiness premiumization.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces validation cycles for German automakers facing EU AI Act algorithmic transparency mandates. |
| Software-Defined Vehicle Investment | Enables Continental AG and Bosch to capture recurring revenue through over-the-air navigation updates. |
| Geographic Manufacturing Footprint | Relocates production to South Korea and Japan for streamlined cybersecurity certification timelines. |
| Strategic Partnership | TomTom's European map database licensing secures exclusive OEM access through audit-right contracts. |
| Acquisition of Specialist Firm | Garmin leverages aviation-grade algorithm expertise repurposed for premium aftermarket navigation segments. |
Methodological Framework
Multiple input streams — primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, and aftermarket distributors; secondary validation through vehicle production databases, IHS Markit registration data, FCC spectrum allocation filings, and EU regulatory directives — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, technology layer, end-user category, and regional production cluster segmentation dimensions produced volume and value outputs over the projection horizon. CAGRs were derived from modeled adoption curves for cloud computing layers and multi-frequency GNSS receiver penetration. Forecast inputs incorporated EU AI Act compliance timelines and QZSS-METI augmentation service deployment schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor foundry capacity constraints, cross-border data localization enforcement in China, and smartphone navigation substitution acceleration. Forecasts reflect documented assumptions around regulatory implementation pacing and automaker platform refresh cycles. Material deviation in EU cybersecurity certification timelines or Taiwan supply chain stability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Europe Commercial Telematics Market
Telematics and Infotainment
North America Commercial Vehicle Telematics Market
Telematics and Infotainment
Car DVR Market
Telematics and Infotainment
Next Generation in-Vehicle Networking (IVN) Market
Telematics and Infotainment
Smart Telematics Gateway Market
Telematics and Infotainment
Boat and Ship Telematics Market
Telematics and Infotainment
Global Car Digital Cockpit Market
Telematics and Infotainment
Asia Pacific Automotive Navigation System Market
Telematics and Infotainment
Edge Computing in Automotive Market
Telematics and Infotainment
Automotive Dashboard Camera Market
Telematics and Infotainment
Consumer Telematics Market
Telematics and Infotainment
APAC Telematics Market
Telematics and Infotainment
In-Car Infotainment Market
Telematics and Infotainment
Global Taxi-Sharing Software Market
Telematics and Infotainment
Internet of Cars Market
Telematics and Infotainment
United States Commercial Telematics Market