
 Automotive Advanced Shifter System Market | 2026-2036
Automotive Advanced Shifter System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Advanced Shifter System Market Analysis
Mechatronics engineering talent is bifurcating the competitive landscape, with suppliers who retain in-house electromechanical design capability pulling ahead of pure-play electronic integrators. ZF Friedrichshafen leverages its integrated actuator manufacturing to control the premium electromechanical segment. Continental AG anchors European OEM relationships through localized R&D centers in Germany and Romania. BorgWarner Inc. competes on manufacturing scale, sustaining cost advantages across high-volume automatic shifter programs.
Automotive advanced shifter systems comprise electromechanical, hydraulic, and cable-actuated mechanisms that translate driver input into transmission gear selection, with electronic variants employing Hall-effect sensors and CAN bus communication to achieve sub-100-millisecond shift confirmation. Their primary purpose centers on eliminating mechanical linkage mass while enabling cockpit design flexibility and software-defined shift logic. Electronic shifters lead product type revenue due to electric vehicle platform proliferation, while electromechanical technology captures the fastest expansion as hybrid architectures demand dual-mode mechanical-electronic redundancy. OEM end users concentrate margin pools through long-term platform contracts, whereas aftermarket providers occupy fragmented, price-sensitive service channels.
NHTSA Federal Motor Vehicle Safety Standards govern shift interlock and unintended-movement prevention in the United States, compelling electromechanical architectures with redundant position sensing. ECE R79 in Europe mandates steering-column and dashboard shifter compliance protocols that favor sensor-based electronic solutions over cable-operated legacy designs. China's MIIT New Energy Vehicle准入 rules require localized electromechanical component certification, shaping supplier plant location decisions. Stakeholders must monitor regulatory divergence between brake-transmission shift interlock mandates and autonomous vehicle-ready shift-by-wire exemptions as platforms converge toward software-defined drivetrains.
Market Dynamics
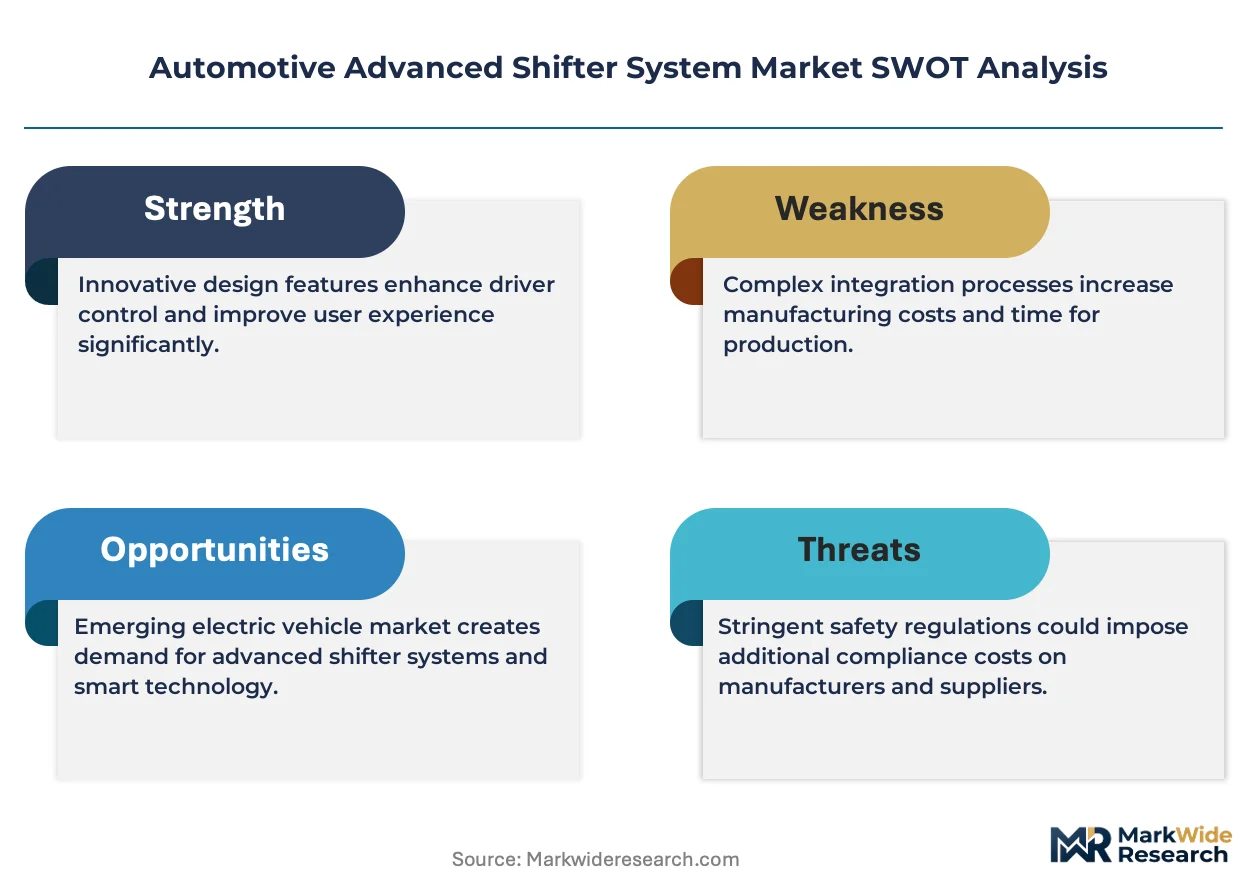
Electrification of vehicle architectures is compressing mechanical linkage demand while forcing suppliers to reengineer around CAN bus integration and redundant position sensing for fail-operational safety.
Growth Catalysts
- EPA fuel economy standards:United States OEMs pursue electromechanical shifters to reduce mass and improve efficiency ratings across light-duty fleets.
- Electric vehicle platforms:Battery-electric architectures eliminate mechanical transmission linkages entirely, creating pull for electronic shift-by-wire modules.
- China MIIT certification:Localized electromechanical component approval requirements accelerate supplier plant investment in Jiangsu and Zhejiang provinces.
Market Restraints
- Rare earth magnet volatility:Neodymium price swings destabilize Hall-effect sensor and actuator cost structures for electronic shifter manufacturers.
- German supplier concentration:ZF Friedrichshafen and Continental AG control premium electromechanical module capacity, creating single-source risk for European OEMs.
- Cable-actuated legacy substitution:Low-cost manual transmission programs in emerging markets resist electronic upgrade cycles.
Strategic Opportunities
- India automotive electrification:PLI scheme incentives for advanced automotive components create entry paths for electronic shifter suppliers.
- Autonomous vehicle shift-by-wire exemptions:NHTSA regulatory pathways for self-driving platforms enable software-defined drivetrain architectures without mechanical backups.
- Japan METI carbon neutrality roadmap:Hybrid vehicle subsidies sustain dual-mode electromechanical shifter demand through 2030.
Industry Challenges
- Mechatronics engineering scarcity:Electromechanical design capability gaps separate integrated suppliers from pure-play electronic integrators.
- ISO 26262 functional safety certification:ASIL-D compliance timelines for shift interlock systems extend product development cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Advanced Shifter System Market |
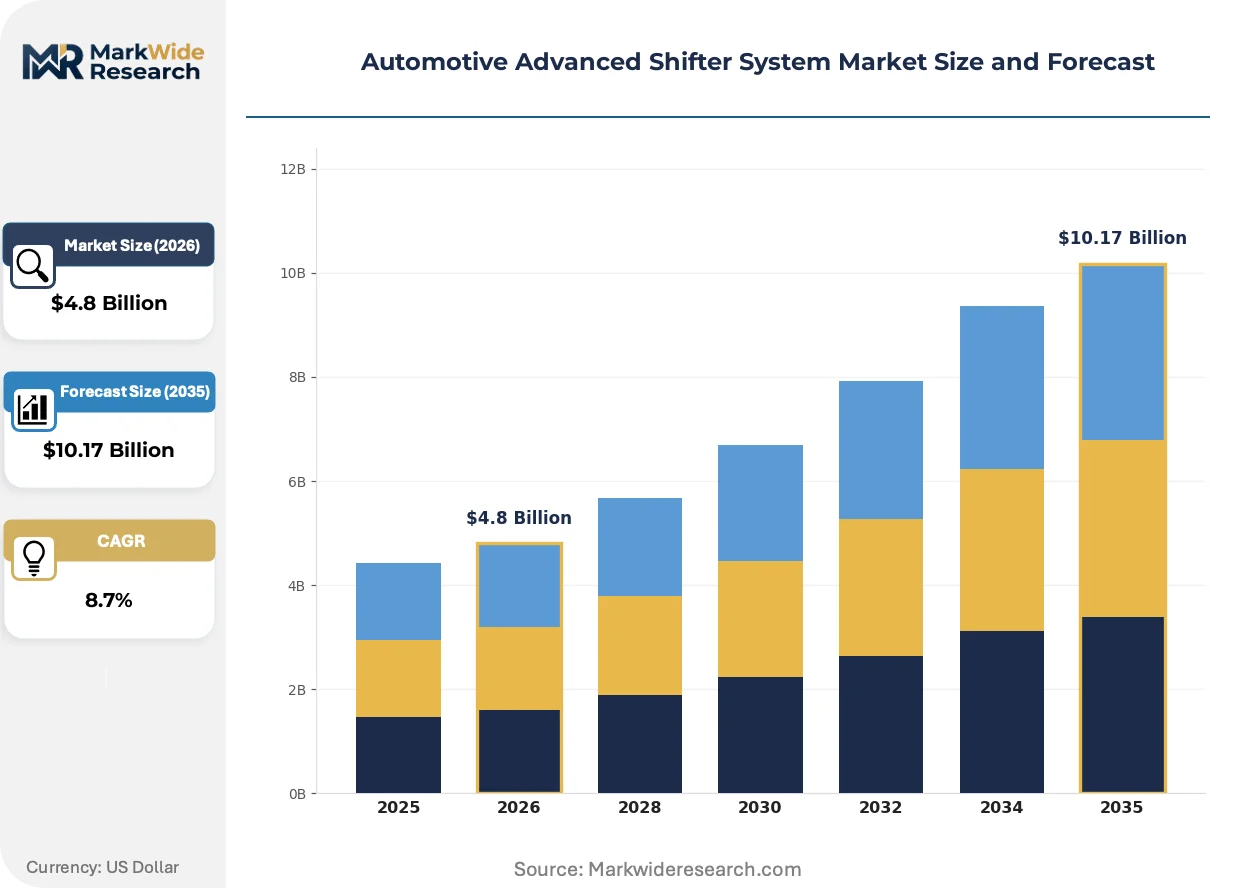
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Shifters, Manual Shifters, Automatic Shifters, Sequential Shifters Technology: Sensor-Based, Cable-Operated, Hydraulic, Electromechanical End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Electric Vehicles |
| Companies Covered | ZF Friedrichshafen AG, Continental AG, BorgWarner Inc., Robert Bosch GmbH, Denso Corporation, Aisin Seiki Co., Ltd., Hyundai Mobis, Kongsberg Automotive, Leopold Kostal GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Advanced Shifter System Market Emerging Trajectories
Software-defined drivetrains are collapsing the boundary between mechanical hardware and electronic control, forcing suppliers to restructure around firmware competency and cybersecurity validation.
Magnetostrictive torque sensors are bifurcating the high-precision actuator segment. Tier-1 suppliers integrate these solid-state position detectors into electromechanical shifter modules for sub-50-millisecond feedback loops. The technology is bifurcating competitive positioning between integrated mechatronics houses and semiconductor-dependent integrators.
EU F-Gas Regulation phase-down mandates are accelerating refrigerant-free thermal management in electronic control modules. Electromechanical shifter suppliers redesign actuator housings to eliminate climate-controlled enclosures. German OEMs push hardest on this specification, cascading requirements through Romanian and Hungarian supply bases.
Fleet procurement consolidation is compressing supplier negotiation cycles. Large rental and mobility operators bundle shifter module specifications into platform-wide transmission contracts, bypassing traditional aftermarket channels. North American commercial fleets lead this aggregation, pressuring Tier-1s toward volume pricing frameworks.
Automotive Advanced Shifter System Market Segmentation
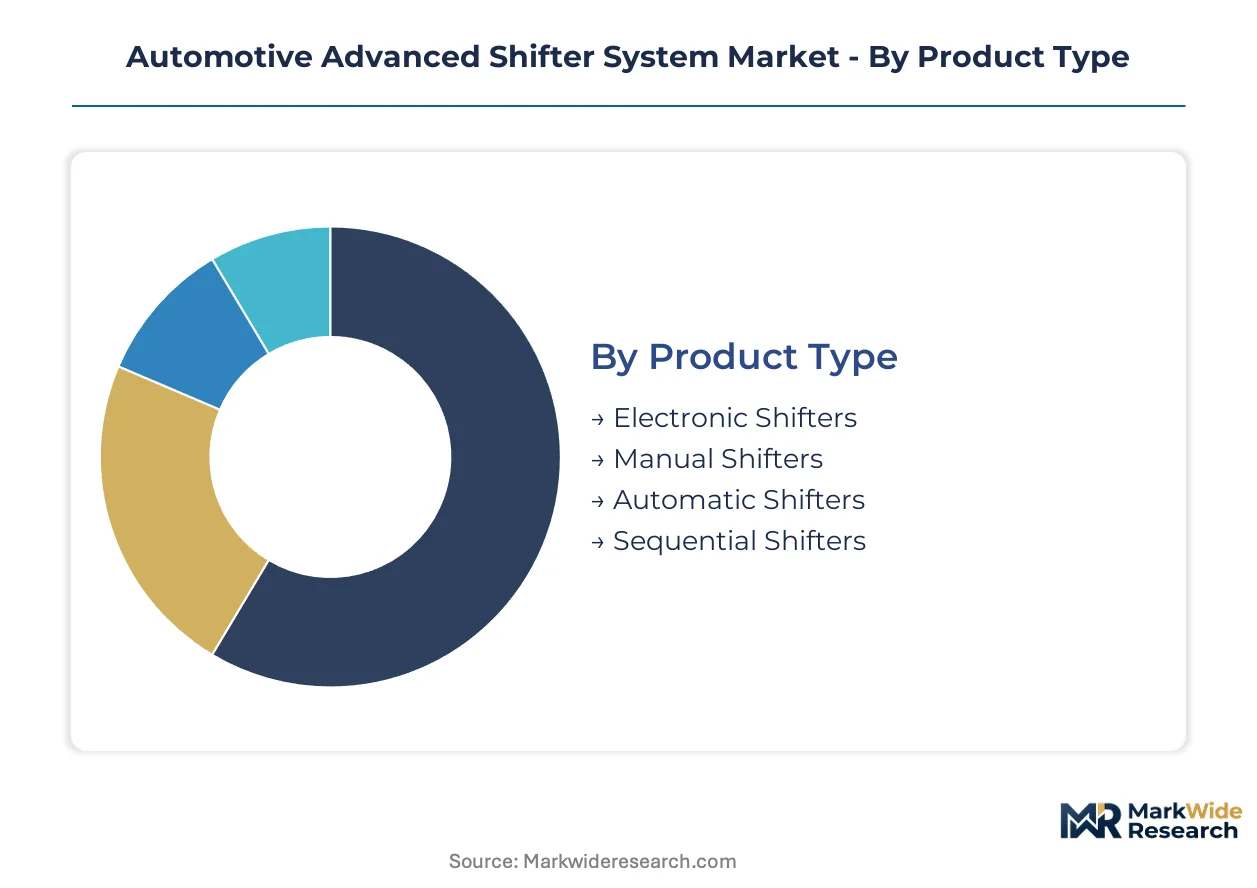
Segmentation in advanced shifter systems reveals how technology choices, customer types, and vehicle applications concentrate margin pools differently. Suppliers must align R&D investment with the segments where electronic architectures and regulatory compliance create pricing power.
Product Type:
Electronic shifters and automatic shifters command premium pricing due to CAN bus integration requirements and NHTSA safety mandates, while manual variants compete on cost efficiency.
- Electronic Shifters:Hall-effect sensor arrays and shift-by-wire logic eliminate mechanical linkages entirely. Demand concentrates in battery-electric platforms across Germany, Japan, and the United States where cockpit design flexibility commands OEM premium allocation.
- Automatic Shifters:Electromechanical actuators with redundant position sensing dominate hybrid architectures. ZF Friedrichshafen and BorgWarner Inc. anchor supply contracts for high-volume light-duty programs in North America.
- Manual Shifters:Cable-actuated mechanisms persist in emerging market cost-sensitive segments.
- Sequential Shifters:Motorsport-derived designs serve niche performance applications with limited volume scale.
Electronic shifters hold installed capacity. Automatic shifters are rotating up the share rankings.
Technology:
Technology choice determines supplier capability requirements, with electromechanical and sensor-based architectures demanding integrated mechatronics expertise that pure-play integrators cannot replicate.
- Electromechanical:Dual-mode mechanical-electronic redundancy serves hybrid platforms requiring fail-operational safety. Japan METI carbon neutrality subsidies sustain demand through dual-mode architectures.
- Sensor-Based:Solid-state Hall-effect and magnetostrictive detectors enable sub-50-millisecond feedback loops. European OEMs in Germany push hardest on EU F-Gas Regulation-compliant thermal management specifications.
- Hydraulic:Fluid-actuated systems retain niche applications in heavy-duty commercial segments.
- Cable-Operated:Legacy mechanical linkages face substitution pressure from EPA fuel economy standards.
Electromechanical systems anchor supplier R&D budgets. Sensor-based architectures are climbing the fastest.
End User:
OEMs and Tier-1 suppliers capture margin through long-term platform contracts, while aftermarket providers operate in fragmented, price-sensitive service channels with limited pricing power.
- OEMs:Original equipment manufacturers consolidate procurement through multi-year platform agreements. NHTSA Federal Motor Vehicle Safety Standards compel electromechanical architectures with redundant sensing in United States light-duty fleets.
- Tier-1 Suppliers:Integrated mechatronics houses control premium module capacity. China MIIT New Energy Vehicle准入 rules require localized electromechanical component certification, shaping plant location decisions in Jiangsu and Zhejiang.
- Aftermarket Providers:Service channel fragmentation limits margin expansion.
- Vehicle Assemblers:Contract manufacturing arrangements concentrate volume pricing pressure.
OEMs dominate contract value. Tier-1 suppliers are rotating up the share rankings.
Application:
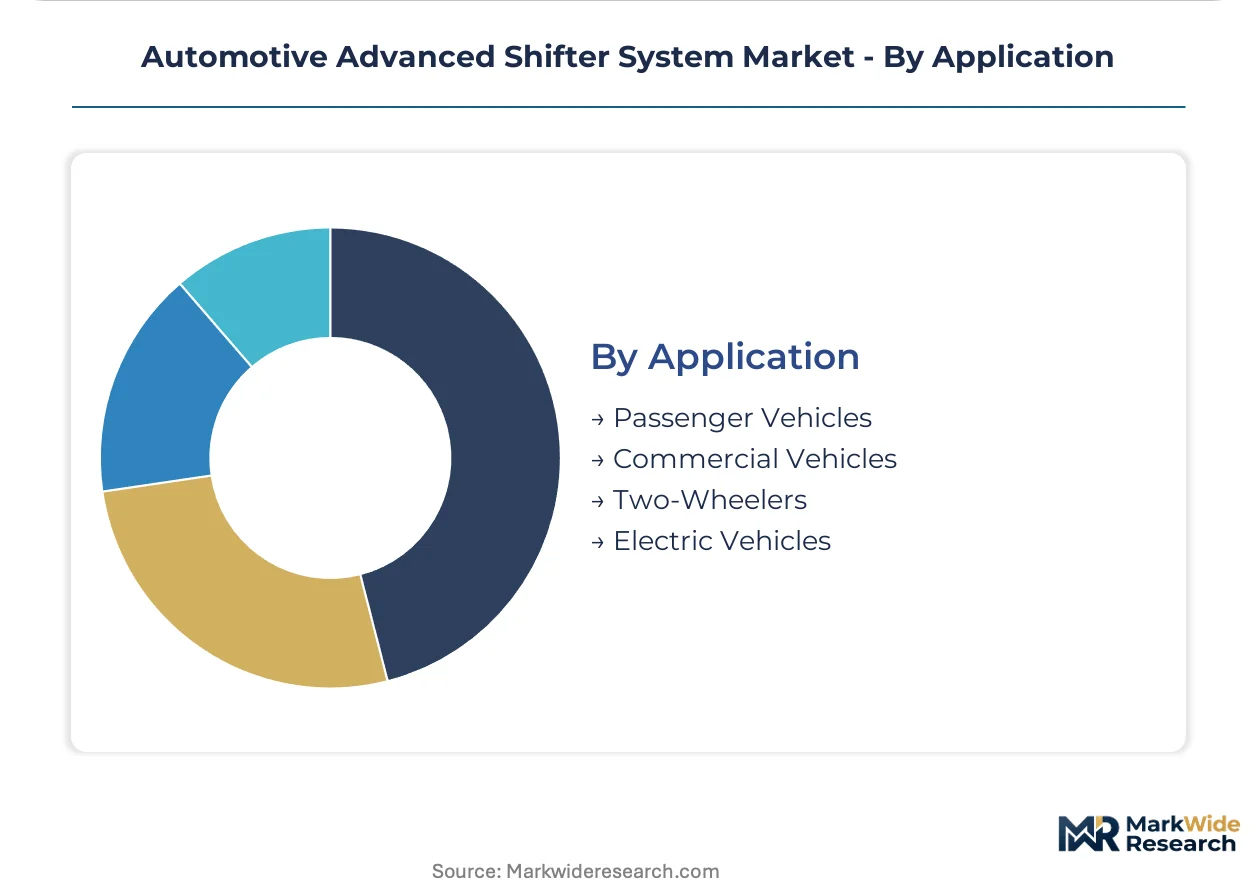
Electric vehicle and passenger vehicle applications drive technology roadmaps, while commercial vehicle segments impose durability requirements that extend validation cycles.
- Electric Vehicles:Battery-electric architectures eliminate mechanical transmission linkages entirely, creating pull for electronic shift-by-wire modules. China, Germany, and Japan concentrate supplier demand for advanced shifter modules.
- Passenger Vehicles:Light-duty fleets pursue electromechanical shifters to reduce mass and improve EPA efficiency ratings. Fleet procurement consolidation in North America compresses supplier negotiation cycles.
- Commercial Vehicles:Heavy-duty duty cycles demand extended durability validation.
- Two-Wheelers:Cost constraints limit electronic architecture penetration.
Passenger vehicles hold installed capacity. Electric vehicles are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA Federal Motor Vehicle Safety Standards in the United States anchor the regulatory framework for shift interlock and unintended-movement prevention, compelling electromechanical architectures with redundant position sensing across major automotive markets.
United States
EPA fuel economy standards drive OEM adoption of electromechanical shifters to reduce mass and improve efficiency ratings across light-duty fleets. NHTSA mandates brake-transmission shift interlock systems with fail-operational redundancy. Michigan and Ohio manufacturing clusters concentrate Tier-1 supplier engineering centers serving Detroit-based OEM platform contracts.
Germany
EU F-Gas Regulation phase-down mandates accelerate refrigerant-free thermal management in electronic control modules. KBA type-approval requirements enforce steering-column and dashboard shifter compliance protocols favoring sensor-based solutions. Bavaria and Baden-Württemberg host integrated mechatronics R&D facilities supplying premium European OEM programs.
China
MIIT New Energy Vehicle准入 rules require localized electromechanical component certification for battery-electric platforms. Dual carbon goals under MEE policy accelerate shift-by-wire module demand. Jiangsu and Zhejiang provinces concentrate supplier plant investment to satisfy domestic OEM procurement requirements.
Japan
METI carbon neutrality roadmap sustains hybrid vehicle subsidies through 2030, preserving dual-mode electromechanical shifter demand. JIS standards govern electronic actuator performance specifications. Kanto and Chubu industrial corridors anchor precision sensor manufacturing for domestic and export programs.
India
PLI scheme incentives for advanced automotive components create entry paths for electronic shifter suppliers targeting electrification programs. BIS certification requirements shape component validation timelines. Maharashtra and Tamil Nadu automotive clusters attract Tier-1 module assembly investments for domestic OEM and export markets.
Automotive Advanced Shifter System Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the Automotive Advanced Shifter System Market, with consolidated capacity concentrated among German and Japanese mechatronics houses. The competitive structure bifurcates between full-system integrators controlling actuator manufacturing and semiconductor-dependent module assemblers. Three strategic archetypes dominate: integrated electromechanical designers, scale-driven automatic transmission suppliers, and sensor-specialist component providers. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure long-term platform contracts.
Within the integrated electromechanical tier, ZF Friedrichshafen AG and Continental AG exemplify full-system capability spanning actuator manufacturing to CAN bus integration. BorgWarner Inc. occupies a position emphasizing manufacturing scale across high-volume automatic shifter programs. These three entities represent the archetype spectrum from premium module integration to cost-optimized volume supply.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Continental AG |
| BorgWarner Inc. |
| Robert Bosch GmbH |
| Denso Corporation |
| Aisin Seiki Co., Ltd. |
| Hyundai Mobis |
| Kongsberg Automotive |
| Leopold Kostal GmbH & Co. KG |
| Others |
Supply Flow & Price Mechanics
NHTSA Federal Motor Vehicle Safety Standards gate both supplier qualification and price differentiation in the Automotive Advanced Shifter System Market, compelling redundant electromechanical architectures that separate certified Tier-1 integrators from commodity cable-actuated providers. ISO 26262 ASIL-D compliance timelines extend product development cycles, concentrating pricing power among mechatronics houses with captive functional safety expertise while compressing margins for semiconductor-dependent module assemblers.
Pricing Analysis
Price spreads between German electromechanical modules and Asian cable-actuated alternatives span three performance tiers across premium, standard, and economy levels. Certification grade under ISO 26262 and volume scale through multi-year OEM platform contracts drive price differentiation, with brake-transmission shift interlock mandates intensifying cost compression in the cable-actuated tier. Fleet procurement consolidation in North America renders commercial vehicle buyers most price-sensitive, while premium European OEMs exhibit lowest sensitivity to module cost given cockpit design flexibility premiums.
Supply Chain Analysis
Inventory buffers for Hall-effect sensors and neodymium magnets extend lead times beyond electromechanical actuator production cycles. Manufacturing concentrates in Germany, China, and Japan, with rare earth magnet supply drawing from Chinese processing facilities and Taiwanese semiconductor foundries. Single-source vulnerability in neodymium pricing destabilizes electronic shifter cost structures. Distribution runs through Tier-1 module assembly plants co-located with OEM vehicle production clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechatronics engineering scarcity constrains supplier expansion, with electromechanical design capability gaps separating integrated actuator manufacturers from pure-play electronic integrators. The market rewards firms controlling in-house firmware development and redundant position sensing validation.
For Market Incumbents: Compound defensive positioning through backward integration into Hall-effect sensor manufacturing and captive magnetostrictive torque sensor production. Add certified capacity in Jiangsu province to satisfy China MIIT localization mandates. ISO 26262 ASIL-D certification investment represents the critical lever against semiconductor-dependent challengers. For New Entrants and Emerging Players: Lead with software-defined shift logic development targeting India's PLI scheme incentives for advanced automotive components. The aftermarket service channel offers most penetrable white-space given fragmented pricing and limited incumbent R&D attention. Pursue vehicle assembler contract manufacturing arrangements as initial go-to-market path. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electromechanical module manufacturing due to redundant sensing architecture requirements. Five-to-ten year viability favors integrated mechatronics houses with captive actuator production and functional safety certification depth. Monitor neodymium price volatility as inflection indicator for electronic shifter manufacturer margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | OEM consolidation around common shift-by-wire architectures reduces supplier validation burden across vehicle programs. |
| Battery Supply Agreement | Electric vehicle platform proliferation pulls electronic shifter demand through dedicated module supply contracts. |
| Software-Defined Vehicle Investment | Firmware competency separates integrated mechatronics houses from hardware-dependent assemblers in shift logic development. |
| Geographic Manufacturing Footprint | Jiangsu and Zhejiang plant placement satisfies China MIIT certification requirements for domestic OEM procurement. |
| Charging Infrastructure Partnership | Fleet procurement consolidation creates bundled specification opportunities across mobility platform contracts. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across OEM platform engineering, Tier-1 supplier procurement, aftermarket distribution, and vehicle assembly operations. Primary interviews with electromechanical design leads, functional safety engineers, and fleet procurement managers combined with secondary validation from NHTSA Federal Motor Vehicle Safety Standards filings, EPA fuel economy compliance databases, China MIIT New Energy Vehicle准入 records, and vehicle production registration data. Bottom-up module shipment estimates triangulated against top-down OEM platform content analysis.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derived from fitted growth curves applied to technology substitution rates and regulatory compliance phase-ins. Forecast inputs incorporated electric vehicle platform rollout schedules and hybrid vehicle subsidy duration under Japan METI policy.
Underlying assumptions cover technology adoption curves and regulatory enforcement intensity, with deviation risk concentrated in rare earth magnet price volatility and autonomous vehicle shift-by-wire exemption timing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Middle East and Africa Automotive LED Lighting Market
Automotive Circuit Systems
Automotive Touch Screen Control Systems Market
Automotive Circuit Systems
Global Automotive Intelligent Dashboard System Market
Automotive Circuit Systems
Automotive Grade Inductors Market
Automotive Circuit Systems
Steering Thermal Systems Market
Automotive Circuit Systems
Dual Circuit Brakes System Market
Automotive Circuit Systems
Automotive Launch Control System Market
Automotive Circuit Systems
Automotive Throttle Position Sensor Market
Automotive Circuit Systems
Automotive Ethernet Switches Market
Automotive Circuit Systems
Automotive Idle Air Control Valve Market
Automotive Circuit Systems
Automotive Digital Instrument Cluster Market
Automotive Circuit Systems
Global Automotive Side Turn Indicator Market
Automotive Circuit Systems
Automotive V2X Antenna Market
Automotive Circuit Systems
In-Vehicle Computer System Market
Automotive Circuit Systems
Automotive 48V System Market
Automotive Circuit Systems
Automotive Steer-by-Wire Actuator Market