
 Nanorobots in Healthcare Market | 2026-2036
Nanorobots in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Nanorobots in Healthcare Market Insights
The United States is fragmenting its nanorobot manufacturing base across Boston, San Francisco, and Research Triangle Park clusters. Bionano Robotics leverages its DNA origami fabrication platform to anchor early-stage therapeutic programs. MagnetoNano Systems sustains competitive differentiation through magnetic control systems for targeted drug delivery. Acuity Nanomedicine specializes in optical control architectures for diagnostic imaging applications.
Nanorobots in healthcare are engineered devices typically measuring 1-100 nanometers, constructed from biocompatible materials such as DNA origami, magnetic nanoparticles, or synthetic peptides, and designed to navigate physiological environments for targeted therapeutic intervention. Their primary commercial purpose centers on precision medicine—delivering payloads to specific cellular targets while minimizing systemic toxicity. Active nanorobots dominate current revenue pools due to their autonomous navigation capabilities, while swarm robotics represents the fastest-growing category as researchers demonstrate collective behavior for complex tissue penetration. Magnetic control technology leads installed base metrics, though chemical control approaches are gaining traction in pharmaceutical company pilot programs for enzymatic trigger mechanisms.
The FDA maintains evolving guidance for nanotechnology-based medical products, while the EMA's Committee for Medicinal Products for Human Use assesses nanorobot biocompatibility through centralized procedures. Japan's PMDA has established accelerated review pathways for regenerative medicine products incorporating nanoscale delivery systems, creating regulatory arbitrage opportunities for first movers. Stakeholders must monitor how FDA-EMA convergence on characterization standards reshapes preclinical data requirements and manufacturing quality benchmarks.
Market Dynamics
DNA origami fabrication platforms are compressing development timelines for therapeutic nanorobots while magnetic control systems anchor near-term commercial viability. Pharmaceutical companies now prioritize enzymatic trigger mechanisms over passive delivery architectures.
Growth Catalysts
- FDA Nanotechnology Guidance:The FDA's evolving framework for nanotechnology-based medical products accelerates Investigational New Drug pathways for targeted drug delivery applications.
- Japan PMDA Accelerated Review:Japan's PMDA has established expedited approval channels for regenerative medicine products incorporating nanoscale delivery systems.
- DNA Origami Maturation:Advances in DNA origami fabrication enable programmable nanorobot architectures with precise spatial control over therapeutic payload release.
Market Restraints
- Biocompatibility Characterization Costs:EMA centralized assessment procedures impose extensive preclinical data requirements that inflate development budgets for nanorobot platforms.
- Magnetic Nanoparticle Supply Concentration:Rare earth element processing for magnetic control systems concentrates in limited geographic clusters, creating input vulnerability.
- Enzymatic Degradation Uncertainty:Physiological enzymatic activity in liver and spleen tissues degrades unshielded nanorobot structures before target tissue penetration.
Strategic Opportunities
- Germany Nanomedicine Infrastructure:German research clusters in Munich and Heidelberg offer underexploited partnership channels for clinical translation programs.
- Swarm Robotics Convergence:Collective behavior algorithms combined with synthetic peptide construction enable complex tissue penetration for oncology applications.
- Optical Control Channel Expansion:Near-infrared responsive nanorobots open diagnostic imaging distribution through radiology equipment vendors.
Industry Challenges
- Multidisciplinary Talent Scarcity:The intersection of molecular biology, robotics engineering, and clinical medicine creates acute recruitment pressure for nanorobot development teams.
- ISO Standardization Delays:Absence of harmonized ISO characterization protocols for nanoscale medical devices forces redundant testing across FDA and EMA submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanorobots in Healthcare Market |
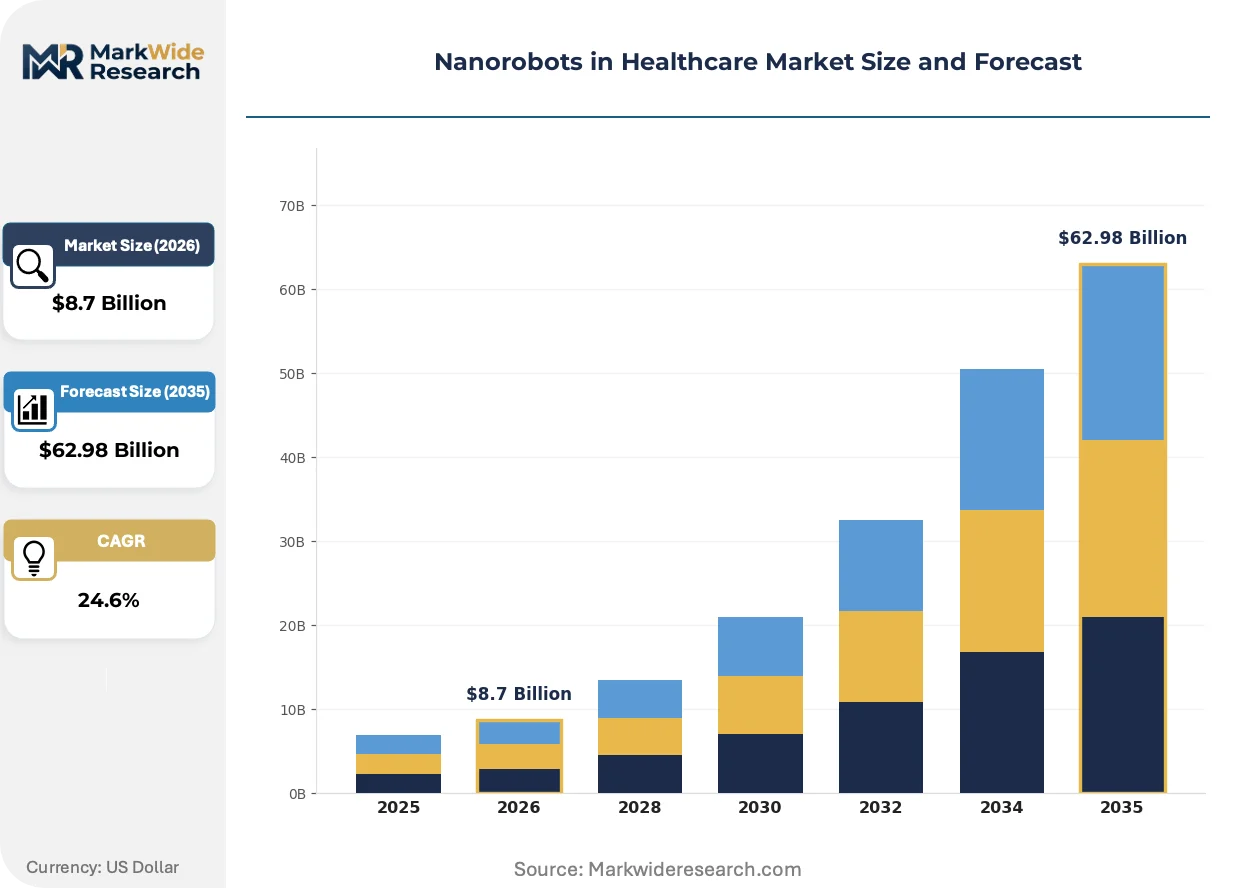
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Nanorobots, Passive Nanorobots, Hybrid Nanorobots, Swarm Robotics Application: Targeted Drug Delivery, Diagnostics, Imaging, Surgical Procedures Technology: Magnetic Control, Optical Control, Thermal Control, Chemical Control End User: Hospitals, Research Institutions, Pharmaceutical Companies, Diagnostic Labs |
| Companies Covered | Bionano Robotics, MagnetoNano Systems, Acuity Nanomedicine, Nanobio Robotics Inc., MicronRobotics, Advanced Nanotech Solutions, DNA Origami Labs, Precision NanoHealth, Aethon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanorobots in Healthcare Market Trends and Innovations
Synthetic peptide construction methods are displacing earlier polymer-based approaches as the dominant nanorobot chassis material. Regulatory convergence between FDA and EMA on characterization standards is compressing preclinical data requirements.
DNA origami technology is hybridizing with magnetic nanoparticle cores to create dual-mode nanorobots capable of both autonomous navigation and external positional control. Oncology therapeutic developers in Boston and San Francisco clusters are adopting these hybrid architectures at accelerated pace. The structural consequence is compression of pure magnetic-control product development pipelines as hybrid platforms capture early-stage funding.
REACH nanomaterial registration requirements in Europe are forcing reformulation of surface coating chemistries for nanorobot platforms intended for EU market entry. Industrial consequence includes migration toward biologically derived coating materials that qualify for simplified registration pathways. Diagnostic imaging applications face the steepest compliance burden, with developers prioritizing US-Japan dual-market launches ahead of European authorization.
Hospital procurement departments are consolidating nanomedicine vendor relationships through centralized nanotechnology evaluation committees. Academic medical centers in the United States are displacing decentralized purchasing with system-level technology assessment protocols. This concentration is most visible in Research Triangle Park adjacent health systems, where Duke and UNC Health coordinate joint pilot program evaluations.
Nanorobots in Healthcare Market Segmentation
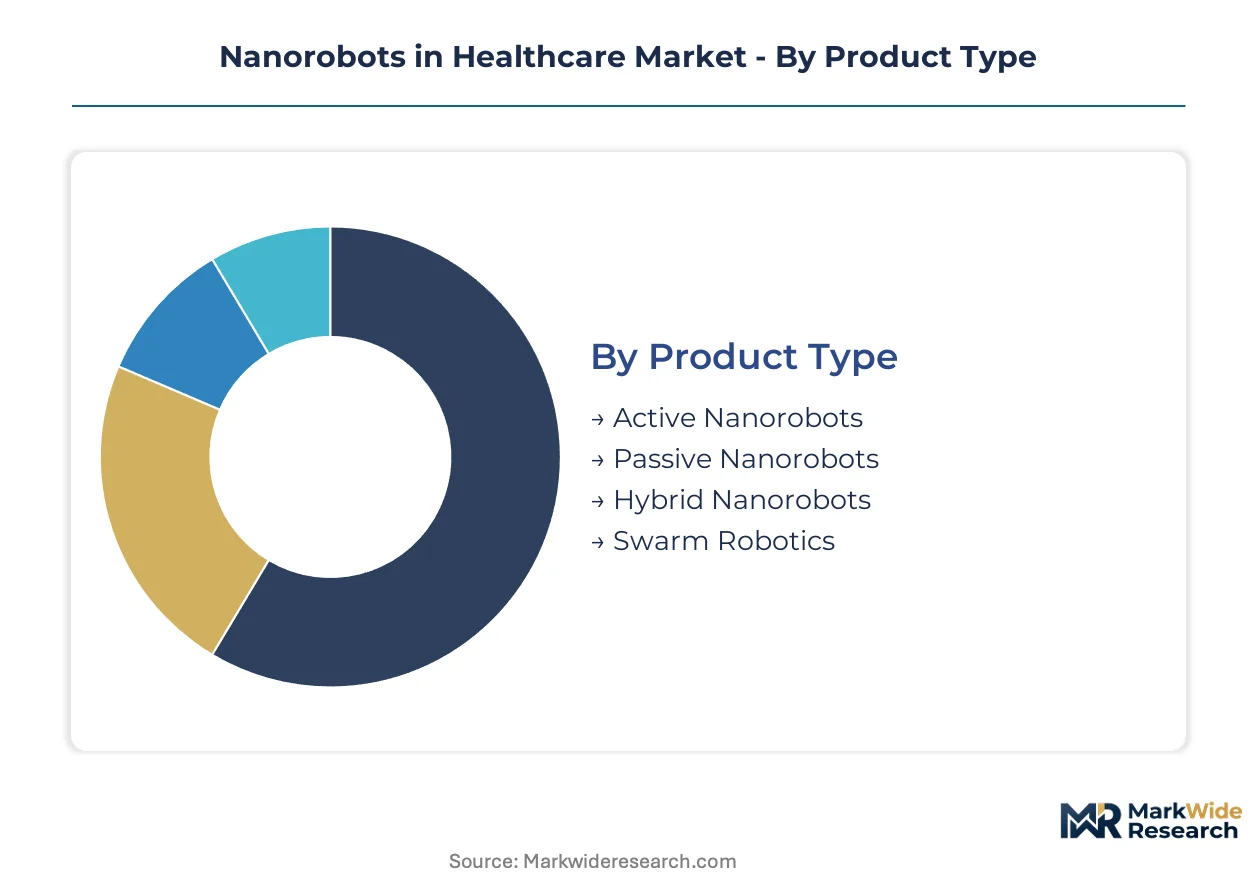
Segmentation in nanorobotics reveals divergent commercialization velocities. Active navigation systems command premium valuations while passive architectures compete on manufacturing scale. Understanding these velocity differentials guides capital allocation across development pipelines.
Product Type:
Cycle times vary dramatically across product categories. Active nanorobots require extended regulatory validation periods. Swarm robotics platforms iterate fastest through preclinical proof-of-concept stages.
- Active Nanorobots:Autonomous navigation capabilities powered by onboard energy harvesting or external field responsiveness. Demand concentrates among pharmaceutical companies in Boston and Research Triangle Park pursuing precision oncology applications, constrained by FDA Investigational New Drug pathway complexity.
- Swarm Robotics:Collective behavior algorithms enabling coordinated tissue penetration through synthetic peptide chassis architectures. Expansion concentrates in Munich and Heidelberg research clusters where German nanomedicine infrastructure supports complex systems validation.
- Passive Nanorobots:Diffusion-dependent payload delivery without autonomous control mechanisms.
- Hybrid Nanorobots:Dual-mode architectures combining DNA origami with magnetic nanoparticle cores for both autonomous and external positional control.
Active Nanorobots dominate installed base. Swarm Robotics is where expansion concentrates.
Application:
Margin structures diverge sharply across therapeutic versus diagnostic deployment. Surgical applications carry the highest reimbursement complexity. Imaging platforms achieve fastest regulatory clearance cycles.
- Targeted Drug Delivery:Precision payload release at cellular targets using enzymatic or magnetic trigger mechanisms. Demand concentrates among pharmaceutical companies prioritizing oncology pipelines, driven by FDA nanotechnology guidance accelerating clinical translation pathways.
- Diagnostics:Biomarker detection and pathogen identification through optical signal amplification. Expansion concentrates in Research Triangle Park adjacent health systems where Duke and UNC Health coordinate joint pilot program evaluations.
- Imaging:Contrast enhancement and real-time physiological visualization.
- Surgical Procedures:Minimally invasive intervention through nanoscale instrument manipulation.
Targeted Drug Delivery dominates installed base. Diagnostics is where expansion concentrates.
Technology:
Supply concentration shapes competitive access. Magnetic control systems depend on rare earth element processing clusters. Chemical control approaches face enzymatic degradation uncertainty in physiological environments.
- Magnetic Control:External field guidance using iron oxide or rare earth nanoparticle cores. Demand concentrates in pharmaceutical company pilot programs, constrained by supply concentration of neodymium and dysprosium processing in limited geographic clusters.
- Chemical Control:pH-responsive or enzymatic trigger mechanisms for payload release. Expansion concentrates in EMA centralized assessment jurisdictions where biocompatibility characterization costs filter out undercapitalized developers.
- Optical Control:Near-infrared responsive architectures for diagnostic imaging applications.
- Thermal Control:Temperature-sensitive material phase transitions for localized therapeutic activation.
Magnetic Control dominates installed base. Chemical Control is where expansion concentrates.
End User:
Procurement authority centralization is reshaping vendor relationships. Hospital systems consolidate through nanotechnology evaluation committees. Research institutions maintain fragmented purchasing with principal investigator autonomy.
- Pharmaceutical Companies:Therapeutic development programs integrating nanorobot platforms into clinical pipelines. Demand concentrates among oncology-focused developers in San Francisco and Boston clusters, driven by Japan PMDA accelerated review pathways for regenerative medicine products.
- Hospitals:Clinical deployment through academic medical center procurement consolidation. Expansion concentrates in United States health systems where centralized technology assessment protocols displace decentralized purchasing.
- Research Institutions:Preclinical investigation and platform validation studies.
- Diagnostic Labs:Commercial testing services incorporating nanoscale detection systems.
Pharmaceutical Companies dominate installed base. Hospitals is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth element processing for magnetic nanoparticle cores concentrates in limited geographic clusters, creating input vulnerability that shapes competitive positioning across therapeutic nanorobot manufacturing.
United States
Pharmaceutical companies in Boston and San Francisco clusters prioritize precision oncology applications, driving demand for DNA origami fabrication platforms. FDA nanotechnology guidance accelerates Investigational New Drug pathways for targeted drug delivery. Research Triangle Park anchors early-stage therapeutic programs where Duke and UNC Health coordinate joint pilot evaluations.
Germany
Munich and Heidelberg research clusters support complex systems validation for swarm robotics platforms using synthetic peptide chassis architectures. EMA centralized assessment procedures impose extensive preclinical data requirements that filter undercapitalized developers. German nanomedicine infrastructure offers underexploited partnership channels for clinical translation programs.
Japan
PMDA accelerated review pathways for regenerative medicine products create regulatory arbitrage opportunities for first movers in nanoscale delivery systems. METI funding supports magnetic control system development for therapeutic applications. Tokyo and Osaka metropolitan areas concentrate pharmaceutical company pilot programs prioritizing enzymatic trigger mechanisms.
Switzerland
Swissmedic maintains stringent biocompatibility characterization standards that align with EMA procedures while offering expedited timelines for breakthrough nanomedicine designs. Basel and Zurich clusters host precision nanohealth developers targeting diagnostic imaging applications. The regulatory environment favors optical control architectures for near-infrared responsive platforms.
United Kingdom
London and Cambridge concentrations focus on hybrid nanorobot architectures combining autonomous navigation with external positional control. The Medicines and Healthcare products Regulatory Agency coordinates with FDA on characterization standard convergence. Academic medical centers displace decentralized purchasing with system-level technology assessment protocols.
Nanorobots in Healthcare Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying magnetic nanoparticle cores and DNA origami substrates. The vendor base organizes around three strategic archetypes: fabrication platform owners, control system developers, and therapeutic application specialists. Consolidation pressures concentrate among magnetic control providers facing rare earth supply constraints. Competitive moves center on strategic partnerships for clinical translation access and technology licensing for enzymatic trigger mechanisms.
Within the fabrication platform tier, Bionano Robotics and DNA Origami Labs exemplify chassis technology providers. MagnetoNano Systems anchors the control system segment. Acuity Nanomedicine occupies a position among optical control specialists targeting diagnostic imaging distribution through radiology equipment vendors.
| Leading Market Players |
|---|
| Bionano Robotics |
| MagnetoNano Systems |
| Acuity Nanomedicine |
| Nanobio Robotics Inc. |
| MicronRobotics |
| Advanced Nanotech Solutions |
| DNA Origami Labs |
| Precision NanoHealth |
| Aethon Inc. |
| Others |
Pricing and Supply Chain Analysis
Rare earth element processing concentration in limited geographic clusters determines both pricing tier spreads and supply chain shape for magnetic nanoparticle-dependent nanorobot platforms. Single-source dependency on neodymium and dysprosium refining creates asymmetric cost pass-through power that stratifies final product pricing across therapeutic application tiers.
Pricing Analysis
EMA centralized assessment procedures dictate the pricing tier structure for nanorobot platforms entering European markets. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared oncology applications from CE-marked diagnostics and unregulated research-grade components. Cost compression in standard-tier enzymatic trigger systems is intensifying because REACH nanomaterial registration forces coating reformulation. Hospital procurement committees demonstrate highest price sensitivity, while pharmaceutical companies in Boston and San Francisco clusters absorb premium pricing for DNA origami fabrication platforms.
Supply Chain Analysis
Contract manufacturing for magnetic nanoparticle cores concentrates among specialized foundries in China, Germany, and Japan with rare earth processing capabilities. DNA origami substrate production draws from synthetic biology foundries in the United States and Switzerland. Supply chain risk centers on single-source vulnerability for dysprosium oxide feedstock. Distribution runs through pharmaceutical company pilot program channels and academic medical center procurement consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across control technology architectures creates white-space opportunities as enzymatic trigger mechanisms displace pure magnetic systems in pharmaceutical development pipelines.
For Market Incumbents: Pre-empt hybrid platform commoditization by securing exclusive DNA origami fabrication partnerships in Research Triangle Park and Munich clusters. Anchor competitive differentiation through backward integration into magnetic nanoparticle core production before rare earth supply constraints tighten. FDA-EMA convergence on characterization standards threatens to erase certification-based pricing premiums for pure-play magnetic control providers. For New Entrants and Emerging Players: German nanomedicine infrastructure in Heidelberg and Munich offers underpenetrated partnership channels for clinical translation programs. Synthetic peptide swarm robotics platforms face lower biocompatibility characterization barriers than DNA origami competitors. Target hospital system procurement consolidation in United States academic medical centers through joint pilot program proposals with Duke and UNC Health evaluation committees. For Investors and Strategic Acquirers: Optical control specialists with near-infrared responsive architectures represent the most defensible acquisition target archetype for diagnostic imaging distribution. Long-term viability hinges on regulatory sandbox access rather than manufacturing scale. Watch for PMDA accelerated review pathway expansion signals as inflection indicators for regenerative medicine nanorobot demand.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Nanotechnology Guidance Alignment | EMA convergence on characterization standards compresses redundant preclinical data requirements across submission pathways. |
| DNA Origami-Magnetic Hybrid Platform Development | Boston and San Francisco oncology developers capture early-stage funding as pure magnetic-control pipelines compress. |
| Hospital System Procurement Consolidation | Duke and UNC Health joint evaluation committees displace decentralized purchasing in Research Triangle Park adjacent systems. |
| Japan PMDA Accelerated Review Access | Tokyo and Osaka pharmaceutical pilot programs leverage regulatory arbitrage for enzymatic trigger mechanism validation. |
| Rare Earth Supply Chain Securement | Neodymium and dysprosium processing concentration in limited geographic clusters creates input vulnerability for magnetic control providers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with nanomedicine development executives, regulatory affairs leads at EMA and FDA, hospital procurement committee members, and DNA origami fabrication platform engineers. Secondary validation drew from FDA nanotechnology guidance documents, EMA centralized assessment procedures, PMDA accelerated review pathway filings, ClinicalTrials.gov nanorobot protocol registrations, and REACH nanomaterial registration databases. Bottom-up therapeutic pipeline analysis triangulated against top-down market sizing across active, swarm, passive, and hybrid nanorobot categories.
Calibration against historical FDA Investigational New Drug approval velocities for nanotechnology-based products anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include navigation autonomy level, therapeutic versus diagnostic application, control technology architecture, and end-user procurement authority structure. CAGRs were derived from therapeutic pipeline stage-gate progression probabilities weighted by regulatory pathway complexity. Industry-specific forecast inputs incorporated enzymatic degradation rates in physiological environments and rare earth element supply concentration metrics.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese rare earth processors or sudden EMA characterization standard relaxation would shift outcomes beyond modeled ranges. Quarterly review of FDA nanotechnology guidance update releases, PMDA accelerated review pathway admission rates, and hospital system procurement consolidation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Cloud Robotics Market
Robotics and Automation
Canada Cloud Robotics Market
Robotics and Automation
Lab Robotics Market
Robotics and Automation
Robotics and Automation Actuators Market
Robotics and Automation
Europe Automated Liquid Handling Market
Robotics and Automation
Europe Data Center Robotics Market
Robotics and Automation
Consumer and Office Robot Market
Robotics and Automation
Global Machine Vision and Vision Guided Robotics Market
Robotics and Automation
Modular Robotics Market
Robotics and Automation
Agricultural Robots and Mechatronics Market
Robotics and Automation
Smart Curtain Robot Market
Robotics and Automation
Robotic Coffee Bars Market
Robotics and Automation
Global Mobile Robots Market
Robotics and Automation
AGV & AMR in Logistics Market
Robotics and Automation
Europe Robotics and Automation Actuators Market
Robotics and Automation
Asrs and Ruos Market