
 United States Testing, Inspection, and Certification (TIC) Market | 2026-2036
United States Testing, Inspection, and Certification (TIC) Market Size, Share, and Industry Trends Forecast 2026-2036
United States Testing, Inspection, and Certification (TIC) Market Insights
Digital twin integration is tilting quality assurance workflows toward real-time predictive analytics rather than post-production sampling. SGS North America Inc. leverages its Houston laboratory network to anchor petrochemical certification workflows. Intertek USA Inc. competes through specialized automotive electrification testing in Michigan. UL LLC differentiates by controlling safety standards development for emerging battery chemistries.
Testing, Inspection, and Certification encompasses the technical evaluation of materials, components, and systems against defined performance, safety, and regulatory benchmarks using calibrated instrumentation, documented protocols, and accredited laboratory or field conditions. The discipline serves industrial and commercial purposes by mitigating liability exposure, enabling market access, and maintaining operational continuity across supply chains. Product Testing commands the largest service type revenue pool due to mandatory pre-market validation cycles, while Remote Monitoring represents the fastest-expanding technology segment as IoT sensor networks reduce site visit frequency. Software Solutions increasingly capture margin from automated compliance documentation and audit trail management.
FAA airworthiness directives, EPA Clean Air Act enforcement, and OSHA process safety management standards collectively expand mandatory inspection frequency across aerospace, energy, and heavy manufacturing sectors. State environmental agencies in Texas and California layer additional emissions testing requirements that deepen TIC engagement. Stakeholders must weigh capital allocation between laboratory automation and field-based remote sensing capabilities as client expectations shift toward continuous rather than episodic verification.
Market Dynamics
FAA airworthiness directives are compressing inspection cycles for aerospace suppliers while EPA emissions enforcement expands continuous monitoring mandates across the Gulf Coast petrochemical corridor. These regulatory pressures are forcing capital reallocation from episodic laboratory testing toward embedded sensor networks and real-time validation infrastructure.
Growth Catalysts
- OSHA Process Safety Management:Mandatory mechanical integrity programs for high-hazard chemical facilities generate recurring inspection contracts. Third-party auditors verify pressure vessel integrity, relief system functionality, and combustion control systems under 29 CFR 1910.119.
- Texas and California state emissions frameworks:Layered testing requirements for volatile organic compounds and hazardous air pollutants deepen TIC provider engagement beyond federal minimums. Refinery clusters in Houston and Los Angeles basin drive concentrated demand.
- Lithium-ion battery chemistry proliferation:UL 9540A thermal runaway propagation testing becomes mandatory for utility-scale energy storage installations. Electrification across automotive and grid storage verticals multiplies pre-market validation cycles.
Market Restraints
- Accredited laboratory capacity concentration:Gulf Coast and Great Lakes regions host disproportionate share of ISO/IEC 17025 certified facilities. Rural manufacturers face 200+ mile logistics burdens for specialized destructive testing.
- PhD-level materials scientist scarcity:Forensic metallurgy and composite failure analysis require decade-long credential accumulation. Pipeline operators compete with semiconductor fabs for identical talent pools.
- Equipment calibration input volatility:Helium-3 and argon gas supply disruptions inflate mass spectrometry operating costs. Neutron radiography facilities face 40% consumable price swings.
Strategic Opportunities
- Appalachian shale gas processing expansion:Pennsylvania and Ohio cryogenic fractionation plants lack mature third-party inspection infrastructure. Greenfield facilities create first-mover positioning for remote monitoring deployment.
- IRA clean energy manufacturing tax credits:Domestic content bonuses accelerate solar module and electrolyzer factory construction. Production equipment qualification and workforce certification services attach to every facility.
- Digital twin convergence with edge computing:Physics-based simulation models paired with field sensor arrays enable predictive rather than reactive integrity management. Offshore platform operators in the Gulf of Mexico pilot continuous structural health monitoring.
Industry Challenges
- ASME Boiler and Pressure Vessel Code certification timelines:Stamp authorization for new fabrication shops stretches 18-24 months. Backlogged National Board review processes delay market entry for emerging NDT technology providers.
- Legacy SCADA integration with cloud analytics platforms:Decades-old distributed control systems in refineries resist API connectivity. Cybersecurity hardening requirements under TSA pipeline directives compound retrofit complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Testing, Inspection, and Certification (TIC) Market |
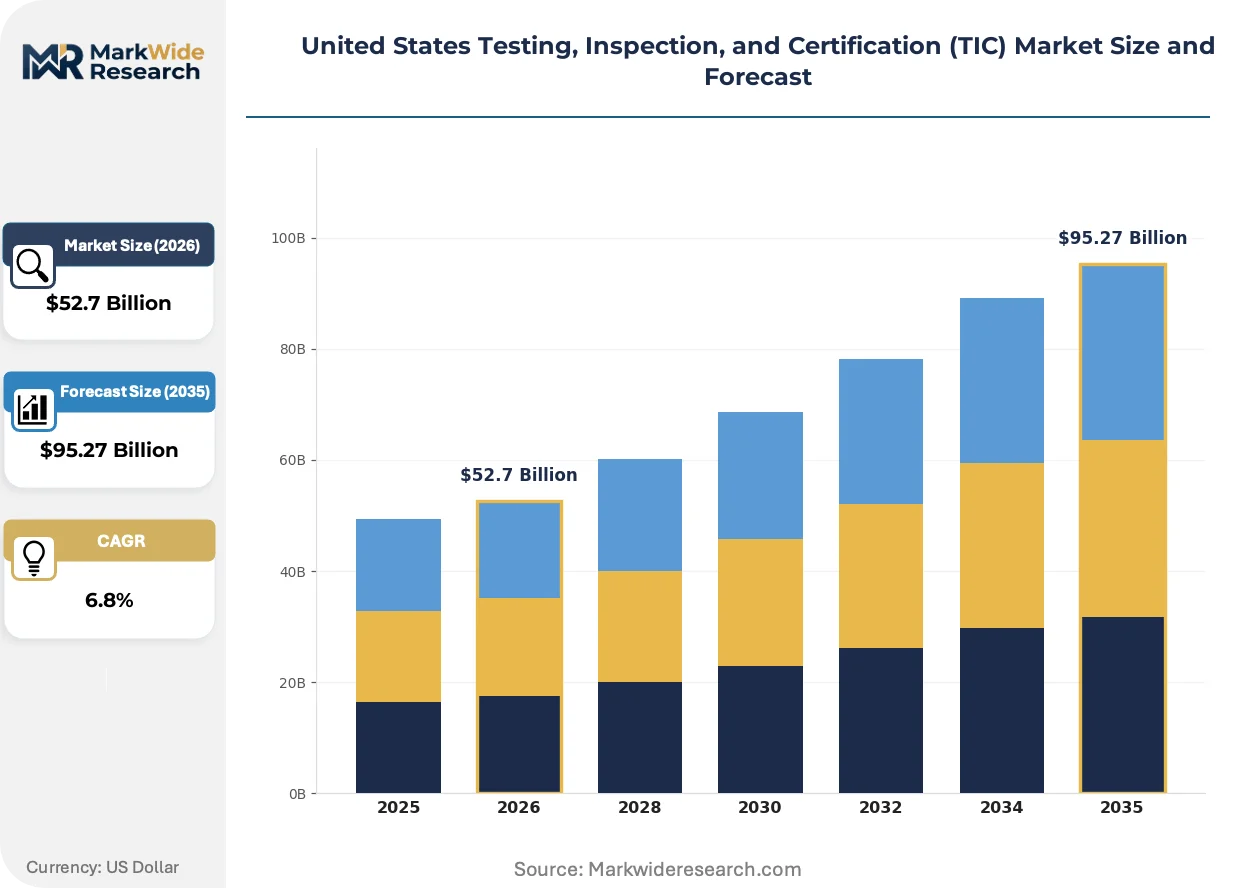
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Product Testing, Quality Assurance, Compliance Verification, Safety Inspection Industry Vertical: Manufacturing, Consumer Goods, Healthcare, Automotive Technology: Laboratory Testing, Field Testing, Remote Monitoring, Software Solutions End User: OEMs, Regulatory Agencies, Research Institutions, Enterprises |
| Companies Covered | SGS North America Inc., Intertek USA Inc., Bureau Veritas North America Inc., UL LLC, Eurofins Scientific Inc., DEKRA, TÜV SÜD, Applus Services, MISTRAS Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Testing, Inspection, and Certification (TIC) Market Trends and Innovations
Real-time sensor networks are displacing scheduled site visits as the dominant verification modality. Predictive analytics platforms now ingest continuous vibration, thermal, and acoustic data streams to flag degradation before catastrophic failure.
Digital twin technology is collapsing the distinction between physical testing and simulation-based validation. Aerospace tier-one suppliers in Wichita and Everett deploy finite element models calibrated against full-scale destructive test results. Boeing and Lockheed Martin procurement teams now accept certificated simulation outputs for design verification, compressing prototype iteration cycles from months to weeks.
EPA Clean Air Act enforcement under the Good Neighbor Plan intensifies fence-line monitoring obligations for petrochemical complexes. Refineries along the Houston Ship Channel deploy open-path Fourier transform infrared spectrometers to detect benzene and 1,3-butadiene leaks in real time. Facility operators in Port Arthur and Baytown renegotiate service contracts to include 24/7 anomaly response rather than quarterly compliance reporting.
Buyer procurement patterns are fragmenting across centralized corporate frameworks and site-level autonomous contracting. Midstream pipeline operators in the Permian Basin negotiate master service agreements with national TIC providers while individual compressor stations retain local specialists for emergency turnaround support. This bifurcation strains vendor management systems and complicates audit trail standardization across enterprise portfolios.
United States Testing, Inspection, and Certification (TIC) Market Segmentation
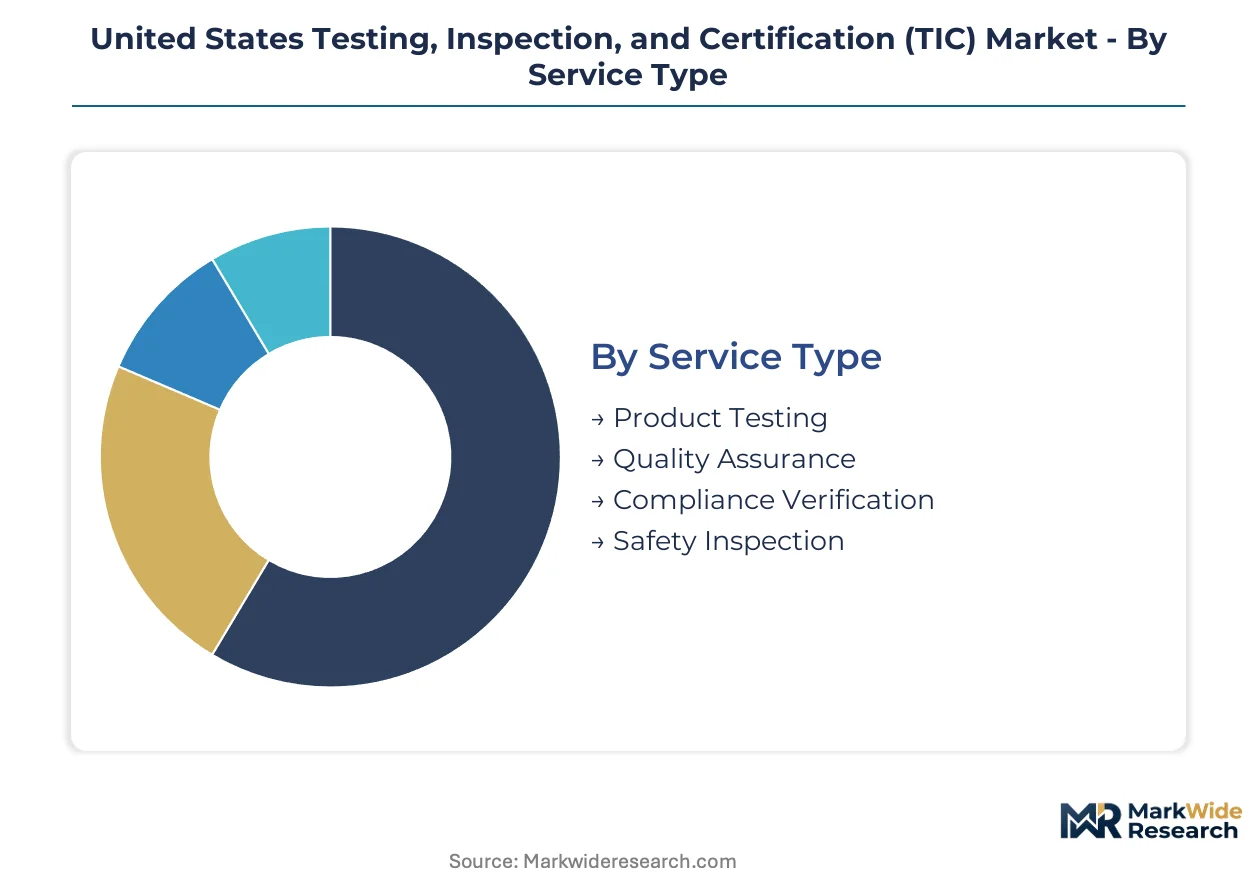
Service differentiation in the United States Testing, Inspection, and Certification (TIC) Market reflects divergent client risk profiles and regulatory exposure. Segmentation reveals where capital-intensive laboratory infrastructure competes against agile field-deployed capabilities.
Service Type:
After-sales service intensity varies dramatically across verification modalities, with recurring audit cycles generating annuity revenue distinct from one-time pre-market validation.
- Product Testing:Pre-market validation of materials, components, and finished goods against ANSI, ASTM, and ISO performance benchmarks. FDA 510(k) submissions and FAA airworthiness certifications drive concentrated demand in Minnesota medical device clusters and Wichita aerospace corridors.
- Quality Assurance:Systematic process auditing and supplier qualification programs embedded throughout production lifecycles. Automotive OEMs in Michigan and Ohio mandate layered QS-9000 and IATF 16949 surveillance, creating multi-year engagement frameworks with tier-one suppliers.
- Compliance Verification:Regulatory conformance assessment against OSHA, EPA, and state environmental mandates.
- Safety Inspection:Hazard identification and risk mitigation verification for operational facilities.
Product Testing holds the largest share; momentum sits with Quality Assurance.
Industry Vertical:
Cost tier stratification separates capital-intensive industrial verification from higher-margin specialized healthcare certification.
- Manufacturing:Foundry, fabrication, and assembly line inspection spanning heavy machinery, metal forming, and industrial equipment. Gulf Coast petrochemical complexes and Great Lakes automotive stamping operations anchor contract volume through ASME pressure vessel and AWS welding certification programs.
- Healthcare:Biocompatibility, sterilization validation, and clinical trial material testing for FDA-regulated devices. Minneapolis-St. Paul and Boston corridor demand concentrates around ISO 10993 cytotoxicity assessments and USP Class VI plastic qualification.
- Consumer Goods:Chemical safety and labeling compliance for CPSC-regulated products.
- Automotive:Electrification-focused battery, motor, and power electronics validation.
Manufacturing dominates contract volume; Healthcare delivers the steepest margin expansion trajectory.
Technology:
Application maturity separates established laboratory modalities from emerging predictive platforms.
- Laboratory Testing:Controlled-environment destructive and non-destructive evaluation using calibrated instrumentation under ISO/IEC 17025 protocols. Houston and Chicago metropolitan areas concentrate accredited capacity for metallography, spectroscopy, and polymer analysis.
- Remote Monitoring:Continuous sensor-based surveillance of operational assets via IoT networks and edge computing architectures. Permian Basin pipeline operators and California refinery fence-line monitors deploy real-time vibration, thermal, and emissions detection to compress inspection intervals.
- Field Testing:On-site non-destructive evaluation using portable ultrasonic, radiographic, and electromagnetic equipment.
- Software Solutions:Automated compliance documentation, audit trail management, and predictive analytics platforms.
Laboratory Testing retains the revenue base; Remote Monitoring is climbing the fastest.
End User:
Customer type determines procurement complexity, with centralized enterprise frameworks diverging from fragmented site-level contracting.
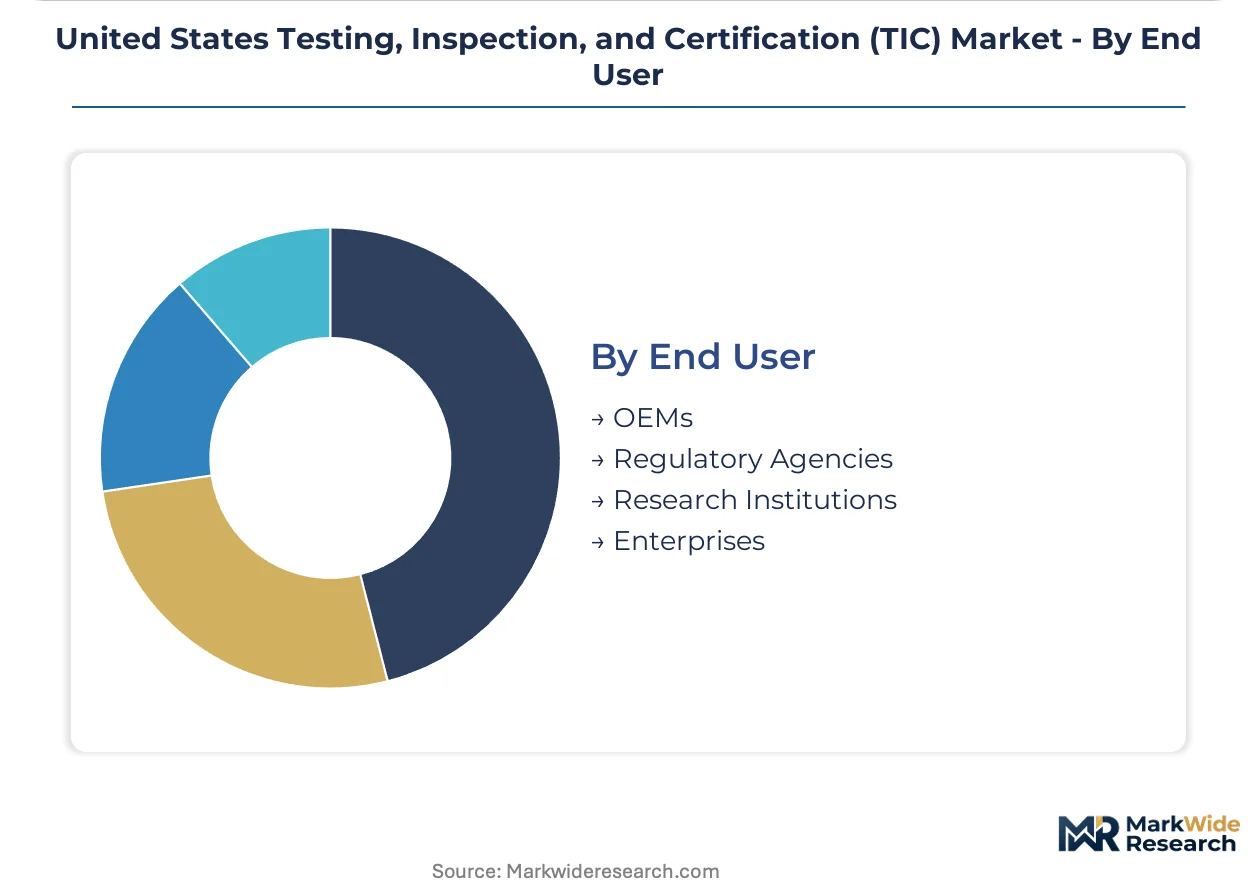
- OEMs:Original equipment manufacturers integrating third-party validation into design verification and production qualification workflows. Boeing in Everett and Lockheed Martin in Fort Worth procure certificated simulation outputs alongside physical test results.
- Regulatory Agencies:Federal and state bodies outsourcing specialized inspection capacity for enforcement support and standards development. EPA regional offices and state environmental agencies in Texas and California contract fence-line monitoring and emissions verification.
- Research Institutions:Universities and national laboratories requiring materials characterization and prototype validation.
- Enterprises:Mid-market manufacturers without captive testing infrastructure.
OEMs anchor premium service tiers; Regulatory Agencies are gaining share fastest through enforcement outsourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers in the United States concentrate TIC procurement around regulatory exposure zones, with petrochemical operators and aerospace manufacturers driving geographic demand clustering. Defense contractors and medical device OEMs anchor secondary demand corridors.
Texas Gulf Coast
Petrochemical complexes in Houston, Baytown, and Port Arthur generate recurring inspection contracts under OSHA Process Safety Management and EPA Clean Air Act enforcement. Refinery operators deploy continuous fence-line monitoring for benzene and 1,3-butadiene detection. The Houston Ship Channel anchors the nation's densest concentration of ASME pressure vessel certification workflows.
California
Aerospace manufacturers in Los Angeles and San Diego counties expand third-party validation contracts as FAA airworthiness directives tighten material traceability. State emissions frameworks layer volatile organic compound testing requirements beyond federal minimums. The Los Angeles basin drives concentrated demand for hazardous air pollutant monitoring services.
Michigan and Ohio
Automotive OEMs mandate layered QS-9000 and IATF 16949 surveillance programs across tier-one supplier networks. Battery electrification testing multiplies pre-market validation cycles for power electronics and motor assemblies. Detroit and Toledo stamping operations anchor contract volume through welding certification programs.
Minnesota Medical Corridor
FDA-regulated device manufacturers in Minneapolis-St. Paul concentrate demand for ISO 10993 cytotoxicity assessments and USP Class VI plastic qualification. Sterilization validation and clinical trial material testing generate premium-margin service contracts. The region hosts specialized biocompatibility laboratory capacity.
Pennsylvania and Ohio Shale Belt
Cryogenic fractionation plants in the Appalachian basin lack mature third-party inspection infrastructure. Greenfield gas processing facilities create first-mover positioning for remote monitoring deployment. Pipeline operators compete with semiconductor fabs for PhD-level materials scientists in forensic metallurgy roles.
United States Testing, Inspection, and Certification (TIC) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. National-scale providers with laboratory networks anchor petrochemical and aerospace certification workflows. Mid-cap specialists concentrate on automotive electrification and medical device validation. Boutique firms capture emergency turnaround and forensic analysis contracts. M&A activity consolidates regional laboratory assets while strategic partnerships embed predictive analytics platforms into client operations.
Within the channel-controlling tier, SGS North America Inc., Intertek USA Inc., and UL LLC occupy positions defined by geographic laboratory density and standards-development influence. SGS leverages Houston infrastructure for Gulf Coast petrochemical workflows. Intertek competes through Michigan-based automotive electrification specialization. UL differentiates by controlling safety standards development for emerging battery chemistries.
| Leading Market Players |
|---|
| SGS North America Inc. |
| Intertek USA Inc. |
| Bureau Veritas North America Inc. |
| UL LLC |
| Eurofins Scientific Inc. |
| DEKRA |
| TÜV SÜD |
| Applus Services |
| MISTRAS Group |
| Others |
Pricing and Supply Chain Analysis
Helium-3 and argon gas supply disruptions determine both pricing tier spreads and supply chain shape across laboratory testing networks. Mass spectrometry operating costs swing with consumable price volatility, compressing margins in analytical services while concentrating accredited capacity in Gulf Coast and Great Lakes metropolitan areas.
Pricing Analysis
Cost-plus contracts with helium and noble gas indexation dominate laboratory testing agreements. Pricing stratifies across ISO/IEC 17025 certified premium tiers, rapid-turnaround standard tiers, and deferred-economy tiers for non-critical validation. Cost compression in economy tiers is intensifying because rural manufacturers face 200-plus mile logistics burdens for specialized destructive testing. Midstream pipeline operators show highest price sensitivity due to commodity margin exposure, while FDA-regulated medical device OEMs accept premium pricing for biocompatibility certification.
Supply Chain Analysis
Export controls on neutron radiography equipment and advanced non-destructive testing systems limit technology flows into domestic laboratory networks. Supply concentrates in Germany, Japan, and the United States for precision instrumentation. Raw material dependencies include helium-3 isotopes, high-purity argon, and specialized scintillation crystals. Single-source vulnerability runs through Russian and Ukrainian noble gas supply channels. Distribution runs through OEM-direct channels for capital equipment and regional service hubs for consumables and calibration gases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to IRA clean energy manufacturing tax credits. Domestic content bonuses accelerate facility construction, attaching production equipment qualification and workforce certification services to every greenfield project.
For Market Incumbents: Insulate core revenue streams by embedding predictive analytics platforms into client operations and securing ASME Boiler and Pressure Vessel Code stamp authorization for new fabrication shops. Vertical integration into remote monitoring sensor manufacturing defends against hardware margin erosion from IoT commoditization. For New Entrants and Emerging Players: Establish a beachhead in Appalachian shale gas processing infrastructure where cryogenic fractionation plants lack mature third-party inspection networks. Pennsylvania and Ohio greenfield facilities offer first-mover positioning for continuous structural health monitoring deployment without incumbent contract lock-in. For Investors and Strategic Acquirers: The market sits at an early-cycle expansion phase that favors specialist laboratory assets with ISO/IEC 17025 accreditation in underserved geographies. Target mid-cap providers with forensic metallurgy and composite failure analysis capabilities. Watch FAA airworthiness directive issuance frequency as inflection indicator for aerospace validation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory Automation Investment | SGS and Intertek deploy robotics in Houston to compress petrochemical testing turnaround times. |
| Remote Monitoring Platform Integration | Permian Basin pipeline operators renegotiate contracts to include 24/7 anomaly response capabilities. |
| Specialist Talent Acquisition | Pipeline operators compete with semiconductor fabs for PhD-level materials scientists in forensic roles. |
| Digital Twin Convergence Partnership | Boeing procurement teams now accept certificated simulation outputs alongside physical test results. |
| Geographic Laboratory Expansion | Backlogged National Board review processes delay market entry for emerging NDT technology providers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with laboratory directors, petrochemical facility maintenance managers, aerospace procurement officers, and EPA regional enforcement coordinators; and secondary validation against FAA airworthiness directive databases, OSHA enforcement records, EPA Clean Air Act compliance filings, and customs trade data for testing equipment imports. Bottom-up service line estimates triangulated against top-down industry spend benchmarks.
Forecast inputs include service type segmentation across product testing, quality assurance, compliance verification, and safety inspection; technology modality splits between laboratory testing, remote monitoring, field testing, and software solutions; and end-user categories spanning OEMs, regulatory agencies, research institutions, and enterprises. CAGRs were derived from regression analysis of historical contract value growth against regulatory enforcement intensity indices and capital expenditure cycles in target verticals. IRA tax credit implementation timelines and FAA directive issuance patterns shaped scenario weightings.
Sensitivities concentrate around helium and noble gas supply disruptions, National Board accreditation backlogs, and shifts in EPA enforcement priorities. Forecasts reflect assumptions regarding regulatory continuity and laboratory capacity expansion rates. Material shifts in export control regimes for radiography equipment or sudden ASME code revision cycles would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Continuous Tablet Manufacturing At-Line Quality Test Systems Market
Testing Services
Staphylococcus Aureus Testing Market
Testing Services
Global Sterility Testing Market
Testing Services
Global Legionella Testing Market
Testing Services
Global Direct-To-Consumer (DTC)Testing Market
Testing Services
Bimetallic Thermometer Market
Testing Services
Lab Screening Test Kit Market
Testing Services
North America and Europe Preclinical Medical Device Testing Services Market
Testing Services
Vials Leak Testing Market
Testing Services
Hemostasis Testing Systems Market
Testing Services
Global Diagnostic Testing Market
Testing Services
Global Urinalysis Test Market
Testing Services
Europe Point-Of-Care-Testing (POCT) Market
Testing Services
Solid Tumor Testing Market
Testing Services
At-Home Celiac Testing Market
Testing Services
Cell Line Authentication and Characterization Tests Market