
 Toxicity Testing Outsourcing Market | 2026-2036
Toxicity Testing Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Toxicity Testing Outsourcing Market Intelligence
In-house toxicology laboratory operations is narrowing as a viable cost center for mid-sized pharmaceutical developers. Eurofins Scientific leverages its global network of GLP-certified sites to anchor multi-regional submission packages for crop protection clients. Catalent, Inc sustains competitive positioning through integrated drug development services that extend from preclinical safety assessment into commercial manufacturing. Charles River Laboratories dominates the North American in vivo testing segment with extensive capacity in large-molecule safety evaluation.
Toxicity testing outsourcing encompasses the delegation of safety pharmacology, genotoxicity, carcinogenicity, and environmental risk assessment studies to specialized contract research organizations, typically conducted under Good Laboratory Practice conditions with species-specific protocols and OECD Test Guideline alignment. The primary purpose is to generate regulatory-compliant data packages that support Investigational New Drug applications, product registrations, and chemical hazard classifications. In vitro testing services are capturing expanding margin pools as sponsors substitute animal models with human-relevant cell-based assays, while bioanalytical testing underpins pharmacokinetic support for every clinical-stage program. Regulatory testing services command premium pricing due to submission-critical timelines and the liability exposure of incomplete dossiers.
FDA's Modernization Act 2.0 and EPA's New Approach Methodologies framework are reshaping demand toward human cell-based and computational models, directly impacting service provider capability requirements. EMA's REACH enforcement and OECD Test Guideline revisions establish the technical standards that outsourced laboratories must maintain for mutual acceptance of data across jurisdictions. Stakeholders must evaluate whether their testing partners possess validated next-generation platforms before regulatory deadlines eliminate legacy study types from acceptable submission pathways.
Market Dynamics
Regulatory mandates from FDA, ECHA, and OECD are compressing timelines for legacy animal study acceptance while accelerating validation requirements for human-relevant alternative methods.
Growth Catalysts
- FDA Modernization Act 2.0:The US mandate removes animal testing requirements for IND submissions, compelling sponsors to secure validated in vitro and computational toxicology partnerships before regulatory deadlines eliminate acceptable legacy pathways.
- Biologics pipeline expansion:Large-molecule therapeutic developers require species-specific immunogenicity and safety pharmacology studies that exceed in-house capabilities, funneling complex programs toward specialized contract research organizations with primate and transgenic model access.
- REACH enforcement tightening:ECHA's substance evaluation workload and data gap identification for existing chemicals are expanding contract laboratory demand for environmental fate, ecotoxicity, and extended one-generation reproductive toxicity studies across European manufacturing supply chains.
Market Restraints
- GLP certification scarcity:OECD-mutual acceptance of data requires facility-specific compliance that concentrates validated capacity in Germany, the United States, and China, creating geographic bottlenecks for sponsors requiring multi-regional submission packages.
- Specialized workforce constraints:Pathology, toxicokinetics, and study director roles require decade-long training pipelines that contract research organizations cannot rapidly scale, constraining throughput expansion even with capital investment.
- Input cost volatility:Purpose-bred non-human primate availability fluctuates with export restrictions from Southeast Asian breeding centers, destabilizing study timelines and pricing for biologics safety assessment programs.
Strategic Opportunities
- Organ-on-chip convergence:Integration of microphysiological systems with high-content imaging and artificial intelligence readouts offers sponsors human-relevant mechanistic data that regulators are progressively accepting for mechanistic toxicity and safety pharmacology endpoints.
- India regulatory alignment:CDSCO's adoption of ICH guidelines and expansion of GLP-certified domestic facilities creates nearshore capacity for cost-sensitive generic pharmaceutical developers seeking bioequivalence and safety data packages.
- Gene therapy toxicology:Viral vector biodistribution, shedding, and insertional mutagenesis studies represent emerging service lines where established in vivo capabilities differentiate contract research organizations from platform-centric biotechnology competitors.
Industry Challenges
- Study director succession:Retirement waves among experienced toxicologists with OECD Test Guideline working group participation are eroding institutional knowledge for regulatory negotiation and protocol deviation management.
- Legacy data system integration:Sponsors demand real-time study access through cloud-based platforms that conflict with validated on-premise laboratory information management systems, forcing costly middleware development or compliance risk acceptance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toxicity Testing Outsourcing Market |
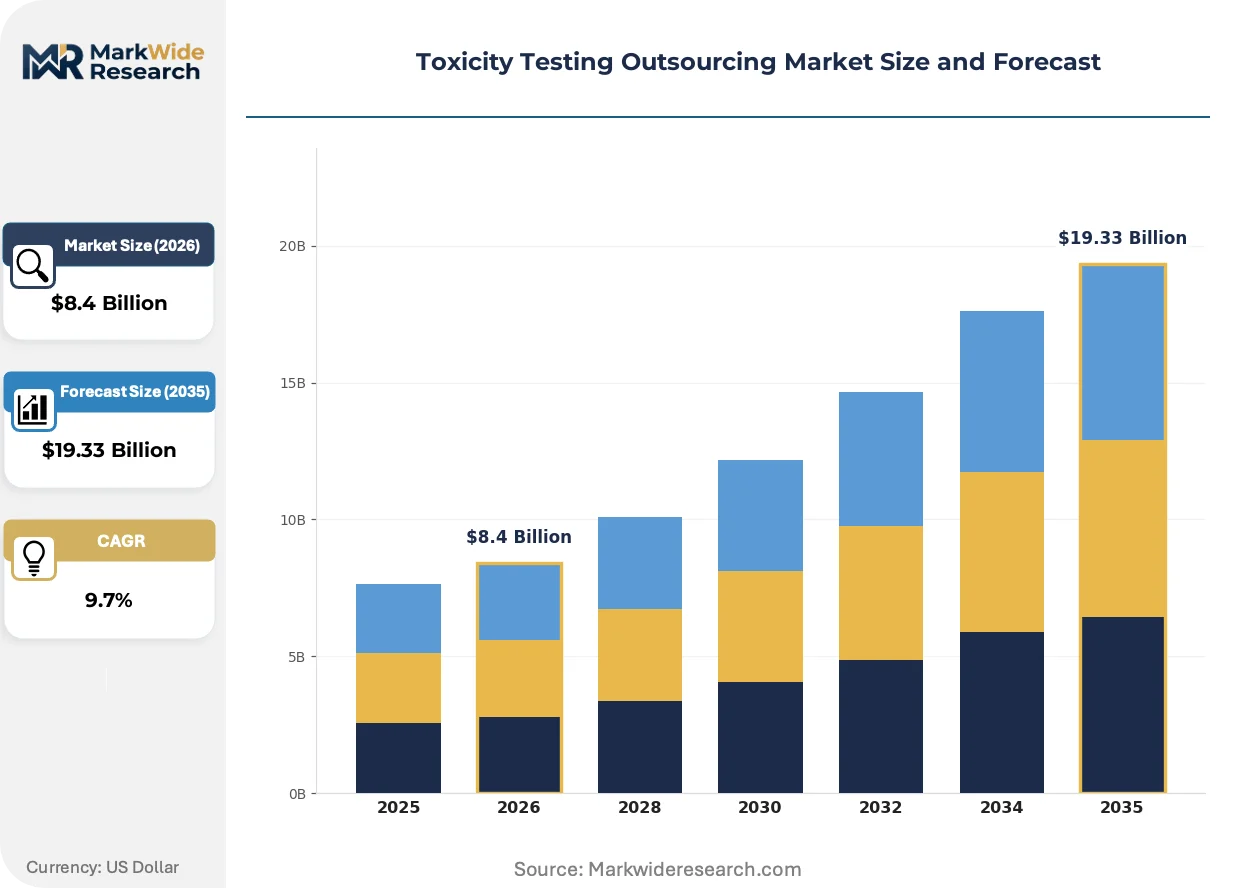
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: In Vivo Testing, In Vitro Testing, Bioanalytical Testing, Regulatory Testing End User: Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations, Academic Institutions Technology: Cell Culture, High-Throughput Screening, Microdosing, Biomarker Analysis Application: Cosmetics, Chemicals, Pharmaceuticals, Agrochemicals |
| Companies Covered | Thermo Fisher Scientific, Inc, Catalent, Inc, Eurofins Scientific, Medpace, ICON plc, SGS SA, Intertek Group plc, Wuxi AppTec, Charles River Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toxicity Testing Outsourcing Market Strategic Shifts & Innovations
Artificial intelligence and microphysiological systems are compressing traditional study timelines while regulatory bodies rewrite acceptance criteria for non-animal safety data packages.
High-throughput transcriptomics and machine learning-based toxicity prediction platforms are rendering obsolete the standard 28-day rodent repeat-dose study for early candidate screening. Mid-sized pharmaceutical developers now commission these assays during lead optimization to deprioritize compounds with human-relevant liability signals before committing to GLP in vivo packages. The structural consequence is a bifurcation in contract research organization service tiers, with technology-anchored providers capturing margin-rich discovery support while traditional toxicology houses compete on commodity regulatory study execution.
REACH authorization and restriction processes under ECHA are mandating annual substance volume reporting and socioeconomic analysis for substances of very high concern. Chemical manufacturers must commission extended toxicity studies and alternatives assessments that extend beyond standard registration dossiers. Specialty chemical producers in Germany and the Netherlands are responding by embedding contract research organization toxicologists into internal product stewardship teams to anticipate regulatory triggers.
Fixed-fee milestone contracts are displacing time-and-materials pricing for standard safety pharmacology and genotoxicity study packages. Biotechnology sponsors with limited cash runway demand cost certainty that transfers timeline risk to service providers, compressing margins for contract research organizations with inefficient operational workflows. This shift is most visible among Boston and San Francisco venture-backed developers where capital efficiency metrics dominate vendor selection criteria.
Toxicity Testing Outsourcing Market Segmentation
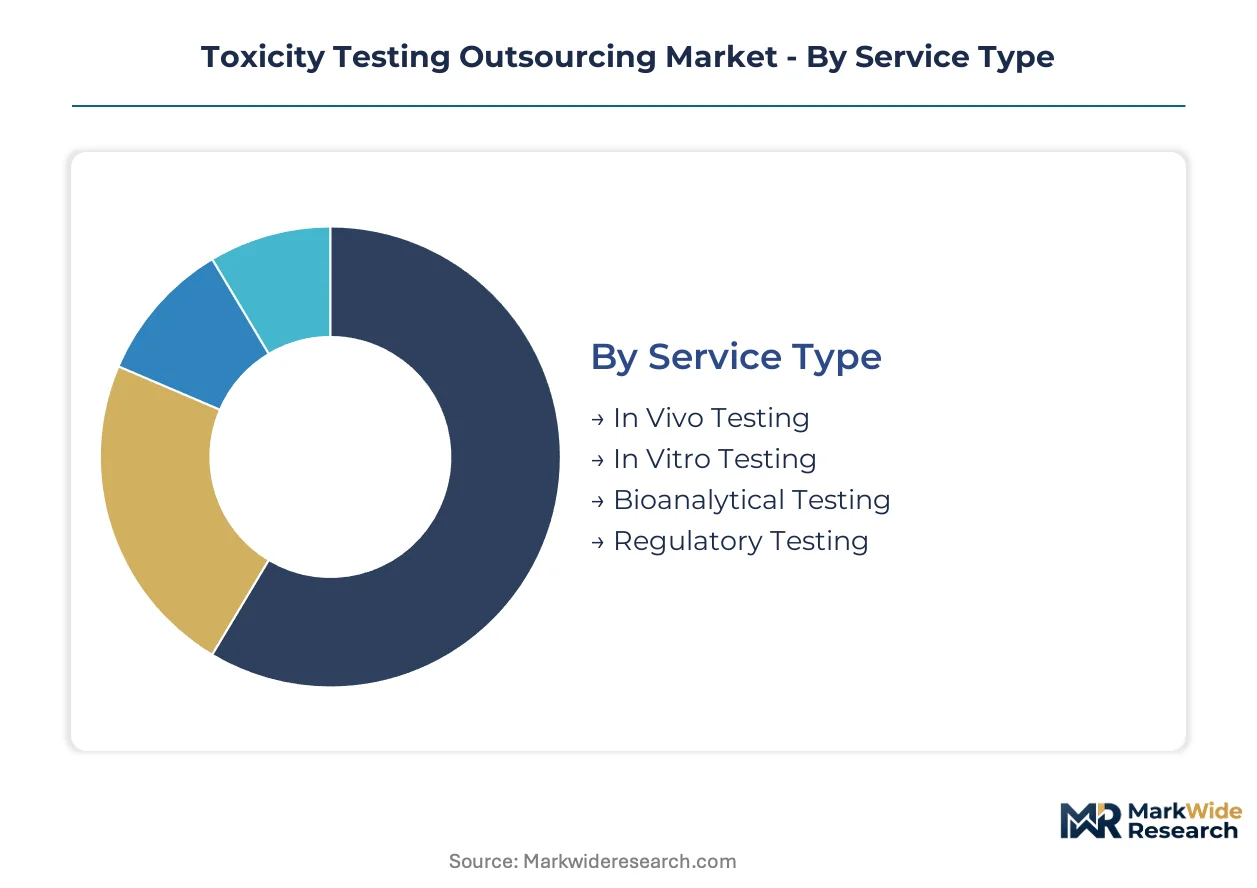
Service providers configure their laboratory networks and scientific staffing around distinct technical workflows, end-user risk profiles, and regulatory submission pathways. Segmentation clarity enables sponsors to match compound class complexity with appropriate contract research organization capabilities and pricing structures.
Service Type:
Pharmaceutical developers deploy distinct service tiers across discovery screening, GLP-enabling studies, and registration-definitive packages based on regulatory criticality and liability exposure.
- In Vivo Testing:Rodent and non-rodent repeat-dose studies, carcinogenicity bioassays, and reproductive toxicology programs generate the bulk of historical regulatory submission data. Large-molecule developers in the United States commission primate studies at Charles River Laboratories and WuXi AppTec facilities to satisfy FDA immunogenicity requirements for IND filings.
- In Vitro Testing:Human cell-based assays for hepatotoxicity, cardiotoxicity, and genotoxicity endpoints are displacing animal models under FDA Modernization Act 2.0 timelines. Eurofins Scientific and Evotec have expanded high-content imaging platforms to capture margin-rich mechanistic toxicology contracts from mid-sized biotechnology sponsors.
- Bioanalytical Testing:LC-MS/MS and ligand-binding assay services underpin pharmacokinetic support for clinical-stage programs. Demand concentrates among Boston and San Francisco venture-backed developers requiring rapid method validation for first-in-human dose escalation.
- Regulatory Testing:REACH dossier preparation, EPA New Chemicals Program submissions, and OECD Test Guideline-compliant packages command premium pricing due to submission-critical timelines. ECHA enforcement actions in Germany and the Netherlands are expanding contract laboratory demand for substance evaluation and alternatives assessment.
The dominant share belongs to In Vivo Testing, while In Vitro Testing is closing the gap fastest as regulatory acceptance criteria for human-relevant methods mature.
End User:
Customer procurement sophistication varies dramatically across capital-constrained biotechnology ventures and integrated pharmaceutical multinationals with captive toxicology capabilities.
- Pharmaceutical Companies:Mid-sized developers with narrowed in-house laboratory operations represent the core revenue base for multi-regional contract research organizations. Pfizer and Bristol Myers Squibb outsource specialized safety pharmacology and carcinogenicity studies to complement retained capabilities in lead optimization screening.
- Biotechnology Firms:Gene therapy and cell therapy developers require viral vector biodistribution and shedding studies that exceed platform-centric internal capacity. Sarepta Therapeutics and CRISPR Therapeutics commission integrated toxicology and bioanalytical packages from Catalent and Charles River Laboratories to accelerate IND timelines.
- Contract Research Organizations:Tier-2 and regional laboratories subcontract specialized endpoints—pathology, toxicokinetics, or primate sourcing—to full-service providers with OECD mutual acceptance of data certification.
- Academic Institutions:University toxicology centers commission GLP validation studies for novel assay platforms seeking regulatory qualification, particularly organ-on-chip and microphysiological system developers at MIT, Stanford, and ETH Zurich.
Pharmaceutical Companies retain the largest procurement volume, though Biotechnology Firms are expanding their outsourcing intensity fastest as therapeutic modality complexity outpaces internal hiring.
Technology:
Platform selection determines study throughput, human relevance, and regulatory defensibility across the candidate selection to registration continuum.
- Cell Culture:Primary human hepatocyte and cardiomyocyte assays from BioIVT and Lonza enable mechanism-of-action toxicology for early liability flagging. Demand is climbing fastest among European sponsors responding to ECHA REACH restrictions on animal testing for cosmetic and chemical endpoints.
- High-Throughput Screening:Automated transcriptomics and high-content imaging platforms compress 28-day rodent study timelines into 72-hour in vitro panels. Recursion Pharmaceuticals and Insitro deploy these capabilities internally, while traditional developers outsource to Evotec and Charles River Laboratories.
- Microdosing:Human Phase 0 pharmacokinetic studies with accelerator mass spectrometry detection support candidate selection for CNS-penetrant compounds. Quotient Sciences and Cyprotex maintain specialized GMP manufacturing and analytical infrastructure for these programs.
- Biomarker Analysis:Translational safety biomarker qualification for kidney, liver, and vascular injury endpoints bridges preclinical and clinical risk assessment. Critical Path Institute consortia in the United States are validating nephrotoxicity biomarkers for regulatory acceptance across FDA and EMA submissions.
Cell Culture anchors current procurement volumes, while High-Throughput Screening is gaining share fastest as artificial intelligence integration improves predictive accuracy.
Application:
Regulatory jurisdiction and hazard classification frameworks create divergent technical requirements and pricing structures across end-market segments.
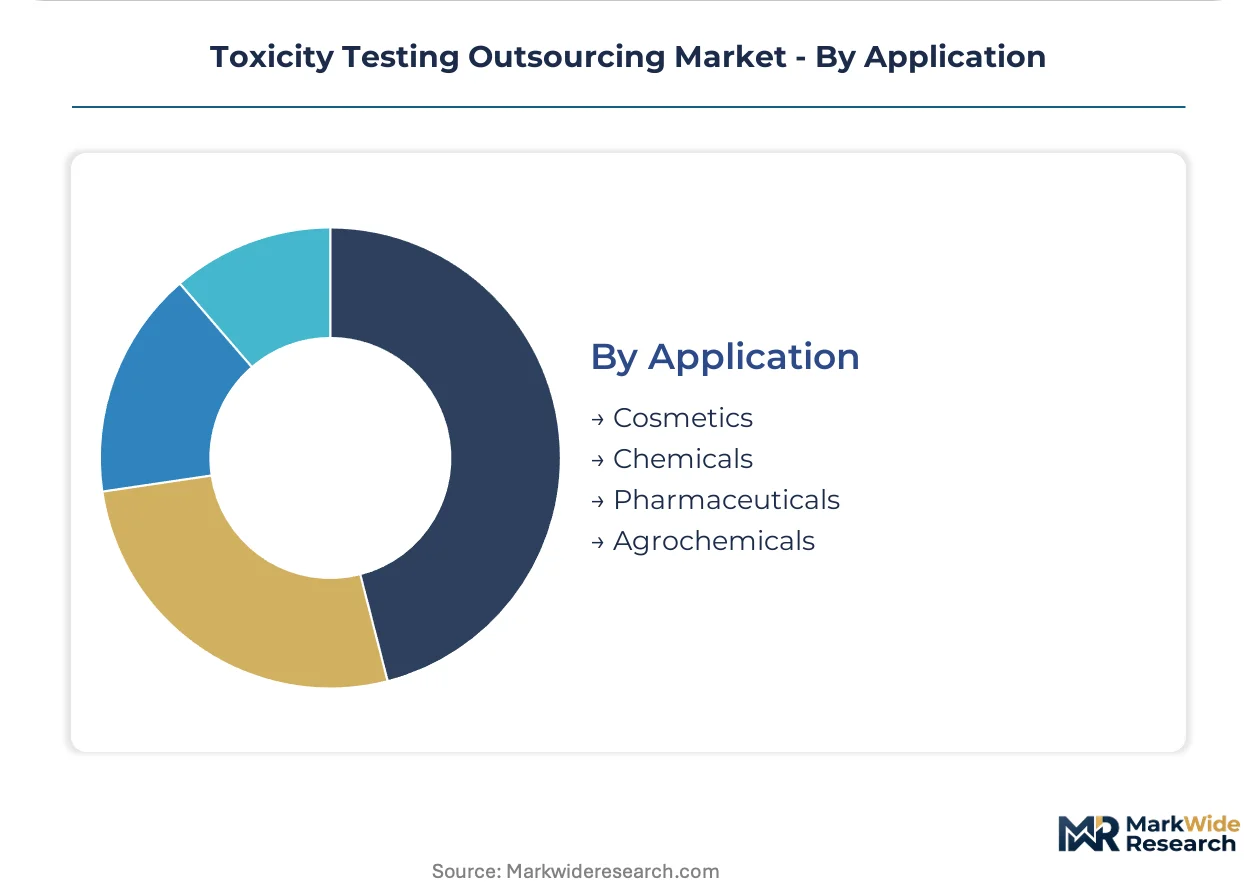
- Cosmetics:EU Cosmetics Regulation and California Cruelty-Free Cosmetics Act mandates have eliminated animal testing options for finished products and ingredients. L'Oréal and Estée Lauder commission reconstructed human epidermis and eye models from Episkin and MatTek for safety substantiation dossiers.
- Chemicals:ECHA REACH authorization processes and EPA TSCA Section 6 risk evaluations mandate extended one-generation reproductive toxicity and endocrine disruption screening. BASF and Covestro embed contract research organization toxicologists into product stewardship teams to anticipate regulatory triggers.
- Pharmaceuticals:IND-enabling and NDA-definitive toxicology packages represent the highest-value service tier, with study directors holding decade-long OECD Test Guideline working group experience commanding premium placement.
- Agrochemicals:Crop protection registrants require multi-species ecotoxicity and environmental fate studies for EPA and PMRA submissions. Syngenta and Bayer outsource extended field residue and pollinator risk assessment programs to Eurofins Agroscience and Smithers.
Pharmaceuticals command the dominant revenue share, though Cosmetics is expanding most quickly as regulatory deadlines eliminate legacy animal study acceptance across additional jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States demonstrate the lowest price elasticity, accepting premium rates for OECD-mutual acceptance of data certification, while sponsors in India and Southeast Asia negotiate aggressively on standard safety pharmacology packages. Geographic concentration of GLP-validated capacity creates supply bottlenecks that reshape procurement patterns across jurisdictions.
United States
FDA Modernization Act 2.0 deadlines are compressing demand for legacy in vivo studies while accelerating partnerships for human cell-based assay platforms. EPA's New Approach Methodologies framework establishes validation requirements that domestic contract laboratories must meet for TSCA submission acceptance. The Boston-Cambridge biotechnology cluster commissions integrated toxicology and bioanalytical packages from Charles River Laboratories and Catalent to accelerate IND timelines.
Germany
ECHA's REACH substance evaluation workload and authorization processes expand contract demand for extended one-generation reproductive toxicity and alternatives assessment studies. The country's national chemical regulator enforces strict OECD Test Guideline alignment for mutual acceptance of data across European manufacturing supply chains. BASF and Covestro in Ludwigshafen embed contract research organization toxicologists into product stewardship teams to anticipate regulatory triggers before they activate volume restrictions.
China
NMPA alignment with ICH guidelines and expansion of domestic GLP-certified facilities position the country as nearshore capacity for Asia-Pacific pharmaceutical developers. The national medical products administration mandates local toxicology data for imported drug registrations, compelling sponsors to commission bridging studies. WuXi AppTec in Shanghai anchors multi-regional submission packages with validated primate facilities serving large-molecule biologics developers.
India
CDSCO adoption of ICH guidelines and domestic GLP certification expansion create cost-sensitive capacity for generic pharmaceutical developers seeking bioequivalence and safety data packages. The Central Drugs Standard Control Organization's streamlined approval pathways attract mid-sized biotechnology sponsors with narrowed cash runways. Hyderabad and Bangalore clusters host emerging contract laboratories that compete on price for standard genotoxicity and safety pharmacology study tiers.
United Kingdom
MHRA post-Brexit regulatory autonomy maintains OECD Test Guideline alignment while creating divergence risks for sponsors requiring dual EU-UK submission packages. The national pharmaceutical regulator's accelerated access pathways compress toxicology study timelines for innovative therapies. The Golden Triangle research cluster between London, Cambridge, and Oxford sustains demand for specialized immunogenicity and viral vector biodistribution studies among gene therapy developers.
Toxicity Testing Outsourcing Market Key Industry Players
Capability concentration sits with full-service providers possessing OECD-mutual acceptance of data certification and primate facility access; scale advantage sits with diversified testing conglomerates leveraging cross-selling across food, environmental, and pharmaceutical verticals. The market structures around three tiers: integrated drug development service providers, specialized preclinical toxicology houses, and diversified analytical testing conglomerates. Dominant competitive moves include GLP facility certification expansion in Germany and the United States, and strategic partnerships with organ-on-chip platform developers to secure next-generation assay capabilities before regulatory deadlines eliminate legacy study acceptance.
Within the integrated service tier, Catalent, Inc and Charles River Laboratories exemplify providers that anchor client relationships through extended development partnerships spanning preclinical safety assessment into commercial manufacturing. Eurofins Scientific occupies a position among diversified analytical testing conglomerates that leverage cross-divisional capacity to absorb volume fluctuations across pharmaceutical, agrochemical, and environmental client segments. Thermo Fisher Scientific, Inc represents the laboratory instrumentation and consumables anchor that supplies validated platforms and reagent systems to the broader contract research organization ecosystem.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc |
| Catalent, Inc |
| Eurofins Scientific |
| Medpace |
| ICON plc |
| SGS SA |
| Intertek Group plc |
| Wuxi AppTec |
| Charles River Laboratories |
| Others |
Cost & Logistics Intelligence
Boston-Cambridge biotechnology cluster demand for accelerated IND timelines concentrates pricing power among GLP-certified providers with integrated toxicology and bioanalytical capabilities. Fixed-fee milestone contracts now displace time-and-materials structures as capital-constrained sponsors demand cost certainty, transferring timeline risk to service providers and compressing margins for inefficient operators.
Pricing Analysis
After-sales revenue from study monitoring, data reconciliation, and regulatory consultation drives lifetime value beyond initial contract value. Three-tier pricing structure across premium, standard, and economy levels stratifies by OECD-GLP certification tier and study director experience depth. Cost compression in standard genotoxicity and safety pharmacology tiers intensifies because Hyderabad and Bangalore contract laboratories compete aggressively on price. Biotechnology sponsors with narrowed cash runways exhibit highest price sensitivity, while integrated pharmaceutical multinationals with captive capabilities demonstrate lowest elasticity for specialized carcinogenicity and primate immunogenicity programs.
Supply Chain Analysis
Charles River Laboratories and WuXi AppTec hold dominant contract-manufacturing capacity for large-molecule safety assessment with primate facility access. Purpose-bred non-human primate supply concentrates in Southeast Asian breeding centers, with Charles River Laboratories maintaining North American capacity and WuXi AppTec anchoring Asia-Pacific availability. Input dependencies rest on purpose-bred rodent strains from Jackson Laboratory and Taconic Biosciences, alongside human hepatocyte and cardiomyocyte supply from BioIVT and Lonza. Single-source vulnerability in non-human primate export channels from Southeast Asia destabilizes study timelines for biologics programs. Distribution runs through direct sponsor-contract research organization relationships with embedded toxicologists in product stewardship teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against platform-centric biotechnology competitors developing internal organ-on-chip and AI-toxicology capabilities that displace traditional GLP study demand.
For Market Incumbents: Pre-empt internalization threats by embedding study directors into sponsor product stewardship teams before regulatory deadlines eliminate legacy animal study acceptance. Secure exclusive partnerships with MIT, Stanford, and ETH Zurich organ-on-chip developers to anchor next-generation assay capabilities. Capacity addition in Germany and United States GLP-certified sites reinforces OECD-mutual acceptance of data positioning for multi-regional submission packages. For New Entrants and Emerging Players: Pursue CDSCO-aligned GLP certification in Hyderabad and Bangalore clusters to capture cost-sensitive generic pharmaceutical bioequivalence demand. Target gene therapy viral vector biodistribution and shedding studies where established in vivo capabilities differentiate from platform-centric competitors. White-space concentration sits with academic institutions seeking GLP validation for novel microphysiological system platforms. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified analytical testing conglomerates with cross-divisional capacity absorption across pharmaceutical, agrochemical, and environmental verticals. Long-term viability hinges on regulatory acceptance timelines for human-relevant alternative methods and sponsor willingness to abandon legacy in vivo pathways. Acquisition target archetype: full-service providers with OECD-GLP certification, primate facility access, and embedded toxicologist relationships. Signal to watch: FDA and EMA guidance document releases on organ-on-chip and AI-toxicology acceptance criteria.| Strategic Initiative | Industry Significance |
|---|---|
| GLP Facility Certification Expansion | OECD-mutual acceptance of data certification in Germany and United States anchors multi-regional submission capability for crop protection and pharmaceutical clients. |
| Organ-on-Chip Platform Partnership | Strategic alliances with MIT and Stanford microphysiological system developers secure next-generation assay capabilities before FDA Modernization Act deadlines. |
| Embedded Toxicologist Deployment | Product stewardship team integration at BASF and Covestro anticipates ECHA REACH authorization triggers before volume restrictions activate. |
| Primate Facility Capacity Addition | Non-human primate access in Shanghai and North America satisfies FDA immunogenicity requirements for large-molecule biologics IND filings. |
| Fixed-Fee Contract Structure Adoption | Milestone-based pricing transfers timeline risk to service providers and aligns with Boston venture-backed developer capital efficiency metrics. |
Research Approach
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, study directors at contract research organizations, and toxicology procurement managers at mid-sized biotechnology sponsors and refined through secondary validation. Primary interviews combined with FDA Modernization Act implementation documents, ECHA REACH substance evaluation records, OECD Test Guideline revision notices, and GLP certification databases. Bottom-up and top-down triangulation cross-validated service provider capacity estimates against sponsor R&D budget disclosures and regulatory submission volume trends.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling segmentation dimensions including service type tier, end-user sophistication, technology platform category, and application regulatory jurisdiction. CAGRs derived from sponsor outsourcing intensity trajectories and regulatory deadline impacts on legacy study acceptance. Forecast inputs incorporated CDSCO ICH guideline alignment timelines and NMPA domestic GLP certification expansion rates.
Sensitivities concentrate around FDA and EMA guidance release schedules for alternative method acceptance, Southeast Asian primate export restriction volatility, and sponsor internalization decisions for discovery-stage screening. Forecasts reflect assumptions regarding regulatory deadline adherence and technology platform validation timelines. Quarterly review of FDA guidance document publications, ECHA authorization list updates, and CDSCO GLP facility certification announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Medical Device Testing and Certification Market
Testing Services
Nipah Virus (Niv) Infection Testing Market
Testing Services
Global Enzyme Linked Immunosorbent Assay (ELISA) Testing Market
Testing Services
South America Endotoxin and Pyrogen Testing Market
Testing Services
Minimal Residual Disease Testing Market
Testing Services
Point of Care Lipid Test Market
Testing Services
Pharmaceutical Dissolution Testing Services Market
Testing Services
Healthcare Analytical Testing Services Market
Testing Services
Influenza a/B Combo Testing Market
Testing Services
US Cannabis Testing Market
Testing Services
Global Lipid Panel Testing Market
Testing Services
Global Enteric Disease Testing Market
Testing Services
Fecal Pancreatic Elastase Testing Market
Testing Services
Drug Screening Laboratory Service Market
Testing Services
Cell Line Authentication and Characterization Tests Market
Testing Services
Global Biologics Safety Testing Market