
 Asia-Pacific Oat Milk Market | 2026-2036
Asia-Pacific Oat Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Oat Milk Market Insights
Cafes and food service providers are redrawing procurement patterns across the Asia-Pacific oat milk landscape, displacing traditional household-led consumption as the primary volume anchor. Oatly Group AB leverages its barista-focused formulation expertise to dominate premium cafe supply chains in metropolitan Australia and Singapore. Sanitarium Health and Wellbeing Company anchors its position through deep retail distribution across Australian supermarkets and health stores. Oatside competes aggressively on price in Southeast Asian convenience channels while building brand recognition through localized marketing.
Oat milk is an aqueous suspension of hydrolyzed oat groats, typically containing 10-15% oat base by weight, enzymatically treated to reduce viscosity and enhance solubility for hot and cold beverage applications. The enzymatic hydrolysis process breaks down starch into maltose, yielding a neutral flavor profile and stable microfoam structure critical for espresso-based drinks. Barista Blend formulations command the strongest margin pools due to specialized fat and protein calibration for steam wand performance. Tetra Pack packaging leads volume throughput by extending ambient shelf life to 9-12 months, reducing cold chain dependency across archipelagic geographies with fragmented logistics. Online Retail distribution is accelerating fastest in South Korea and Japan, where subscription models and direct-to-consumer platforms bypass traditional grocery slotting constraints.
Food Standards Australia New Zealand (FSANZ) governs plant-based milk labeling and compositional standards, while the Korea Ministry of Food and Drug Safety (MFDS) enforces allergen disclosure and novel food registration for oat-derived beverages entering the Korean market. These frameworks shape product formulation, packaging claims, and import clearance timelines for multinational suppliers. China's National Health Commission maintains evolving standards for grain-based beverages that affect cross-border e-commerce positioning. Stakeholders must monitor regulatory divergence on protein content thresholds and "milk" terminology restrictions as these definitions harden across jurisdictions.
Market Dynamics
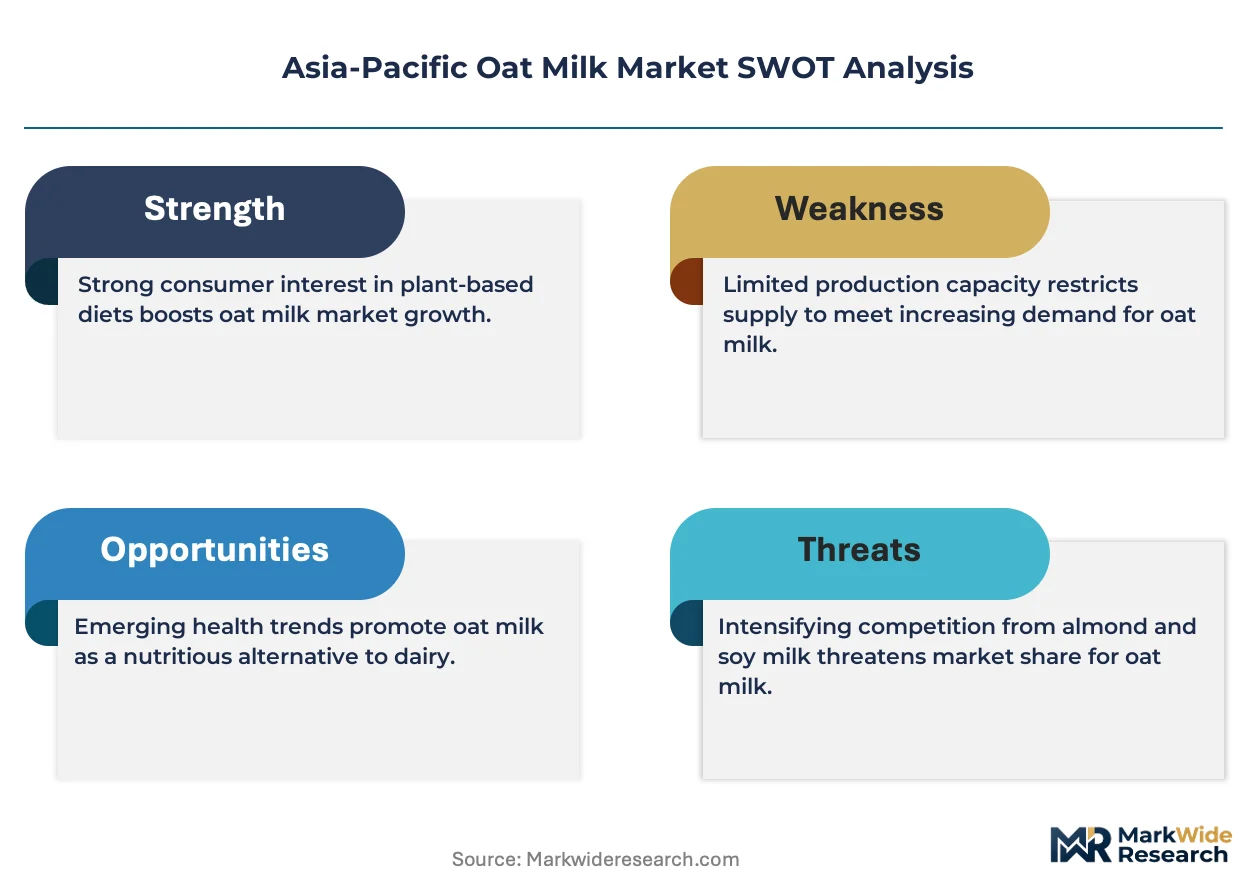
Cafe-led procurement is displacing household consumption as the primary volume anchor across Asia-Pacific oat milk markets, with barista-grade formulations commanding premium positioning and reshaping supplier priorities toward food service specifications.
Growth Catalysts
- MFDS novel food registration pathway:South Korea's streamlined oat beverage approval process accelerates import clearance for European and Australian suppliers, compressing time-to-shelf for new entrants targeting Seoul's cafe-dense districts.
- Enzymatic hydrolysis optimization:Advanced beta-amylase protocols reduce viscosity without compromising foam stability, enabling ambient-stable formulations that slash cold chain costs across Indonesian and Philippine archipelagic logistics.
- Specialty cafe density in Melbourne and Sydney:Australia's third-wave coffee culture normalizes oat milk as default dairy alternative, creating demonstration effects that propagate through Southeast Asian metropolitan markets via tourism and expatriate networks.
Market Restraints
- Oat base input concentration:Regional oat milling capacity clusters in southeastern Australia and China's northern plains, exposing formulated product costs to grain price volatility and freight margin compression.
- FSANZ plant-based labeling revisions:Australia's pending restrictions on "milk" terminology force reformulation of packaging claims and trigger inventory write-downs for non-compliant stock already in distribution.
- Soy milk substitution threat:Established Asian soy beverage infrastructure, particularly Japan's kikkoman-derived supply chains and China's state-supported soymilk programs, undercuts oat milk price positioning in mass retail channels.
Strategic Opportunities
- Vietnam's underpenetrated Ho Chi Minh City corridor:Rapid specialty coffee expansion in District 1 and District 7 creates first-mover positioning for barista-blend suppliers ahead of domestic oat processing investment.
- Direct-to-consumer subscription platforms:South Korean e-commerce ecosystems enable bypass of traditional retail slotting fees, capturing margin pools otherwise surrendered to hypermarket conglomerates.
- Japan's METI sustainable food labeling:Carbon footprint disclosure requirements favor oat milk's lower water intensity versus almond and dairy, creating regulatory tailwind for premium positioning in Tokyo and Osaka convenience channels.
Industry Challenges
- Food technologist scarcity:Formulation expertise combining enzymology, emulsion science, and sensory profiling concentrates in Australian and New Zealand research institutes, constraining Southeast Asian manufacturing scale-up.
- Tetra Pak aseptic line capex intensity:Ambient shelf-life extension requires capital outlays for sterilization and filling equipment that strain mid-tier regional processors seeking cafe channel entry.
- Cross-border e-commerce compliance fragmentation:Divergent allergen disclosure standards between China's NHC grain beverage rules, MFDS oat-specific requirements, and FSANZ compositional thresholds multiply SKU complexity for pan-Asian suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Oat Milk Market |
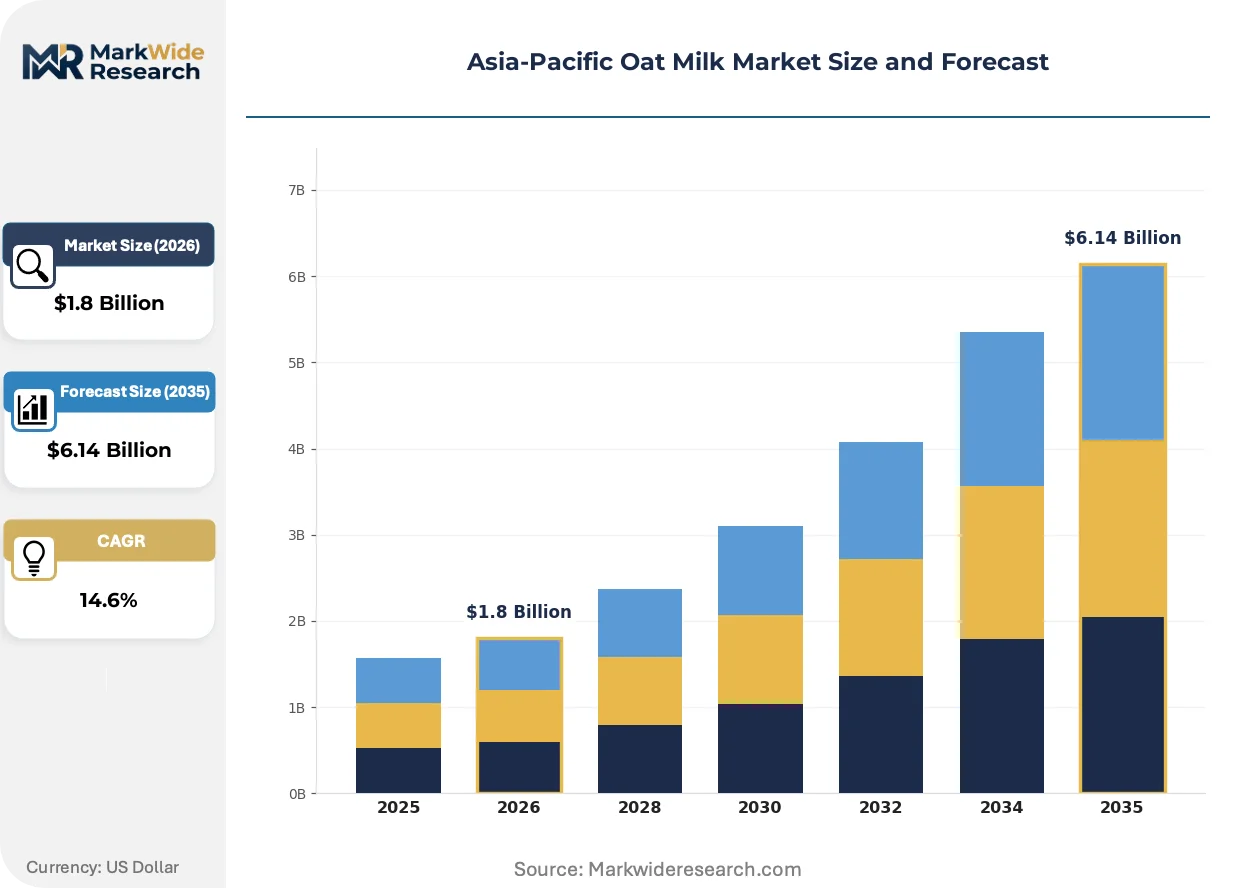
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barista Blend, Original, Chocolate, Vanilla End User: Households, Cafes, Restaurants, Food Service Providers Packaging Type: Cartons, Tetra Packs, Bottles, Pouches Distribution Channel: Supermarkets, Online Retail, Health Stores, Convenience Stores |
| Companies Covered | Oatly Group AB, Freedom Foods Group Ltd, Nestlé SA, PureHarvest, Sanitarium Health and Wellbeing Company, Oatside, Califia Farms LLC, Danone SA, Minor Figures Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Oat Milk Market Trends and Innovations
Enzymatic processing advances and regulatory disclosure mandates are compressing formulation cycles while reshaping how oat milk suppliers compete on transparency and performance metrics rather than commodity positioning.
High-pressure homogenization paired with targeted lipase treatment is decomposing the traditional trade-off between shelf stability and sensory quality that previously forced suppliers into either fresh-chilled or ultra-processed extremes. Australian and Singaporean barista-focused brands adopt these integrated systems fastest, deploying equipment that delivers 12-month ambient stability without the cooked off-notes that plagued first-generation UHT oat beverages. The technology is decomposing category boundaries between retail grocery and food service segments by enabling single-SKU strategies that satisfy both channels.
FSANZ's proposed amendments to Standard 2.5.2 governing plant-based milk descriptors are forcing preemptive packaging redesigns across Australian supermarket shelves and export-bound production lines. The industrial consequence extends beyond label changes to reformulation investments as suppliers adjust protein fortification levels to meet compositional thresholds that preserve "milk alternative" positioning. Barista-blend SKUs face the tightest compliance timelines given their premium price sensitivity to perceptual downgrades from "milk" to "beverage" classification.
Cafe procurement committees in Seoul, Melbourne, and Singapore now specify enzymatic treatment protocols and foam retention metrics in supply agreements, displacing informal taste-test selection with documented performance standards. This procurement formalization compresses supplier switching costs while elevating technical documentation burdens onto smaller regional processors. The shift is most visible in South Korea, where chained cafe conglomerates consolidate purchasing through centralized quality assurance departments that audit manufacturing facilities for enzymatic process control and batch consistency.
Asia-Pacific Oat Milk Market Segmentation
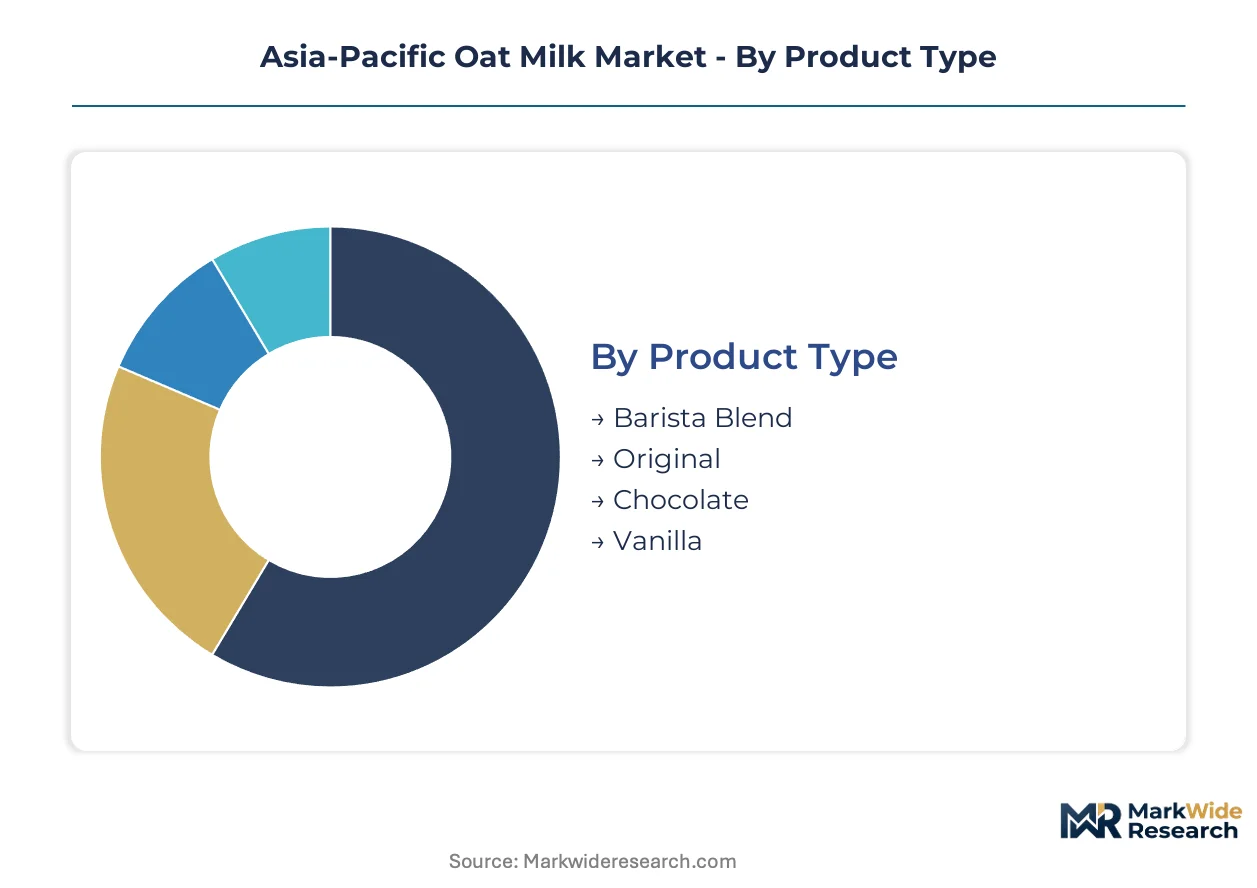
Channel dynamics in Asia-Pacific oat milk markets fragment demand across distinct performance requirements, packaging constraints, and procurement behaviors. Suppliers must calibrate formulations, shelf-life engineering, and logistics to match the divergent specifications of cafe food service versus household retail channels.
Product Type:
Barista Blend formulations flow predominantly through food service channels demanding foam stability, while flavored variants anchor retail expansion targeting younger demographics in metropolitan convenience networks.
- Barista Blend:Specialized fat and protein calibration enables steam wand performance with microfoam retention exceeding 120 seconds. Demand concentrates in Melbourne and Sydney specialty cafes where third-wave coffee culture normalizes oat milk as default dairy alternative, though enzymatic hydrolysis complexity limits regional manufacturing scale-up.
- Original:Standard oat base suspension of 10-12% concentration serves mass retail and household brewing applications with neutral flavor profiles. Expansion concentrates in South Korean online retail channels where subscription models bypass traditional grocery slotting constraints.
- Chocolate:Cocoa-fortified formulations target children's nutrition positioning in Australian supermarkets and health stores.
- Vanilla:Sweetened variants compete in Southeast Asian convenience channels against established soy beverage infrastructure.
Barista Blend dominates installed base in food service procurement. Original formulations represent the fastest-growing trajectory as household channel penetration accelerates.
End User:
Procurement formalization varies sharply across customer types, with centralized quality assurance departments replacing informal taste-test selection among chained operators.
- Cafes:Centralized procurement committees in Seoul, Melbourne, and Singapore now specify enzymatic treatment protocols and foam retention metrics in supply agreements. Procurement formalization compresses supplier switching costs while elevating technical documentation burdens onto smaller regional processors.
- Food Service Providers:Institutional catering contracts demand ambient-stable formulations with 9-12 month shelf life to reduce cold chain dependency across archipelagic geographies with fragmented logistics. Volume concentration in Singaporean and Malaysian contract catering drives formulation standardization.
- Households:Individual consumers purchase through supermarket and online retail channels with price sensitivity elevated by soy milk substitution threats.
- Restaurants:Full-service dining establishments represent smaller volume pools with irregular procurement patterns compared to cafe chains.
Cafes dominate installed base through procurement consolidation. Food Service Providers represent the steepest expansion trajectory as institutional adoption accelerates.
Packaging Type:
Supply concentration in aseptic processing equipment shapes competitive access to extended shelf-life formats.
- Tetra Packs:Aseptic carton systems deliver 9-12 month ambient stability through sterilization and filling equipment that strains mid-tier regional processors. Tetra Pak aseptic line capex intensity creates barrier to entry for Southeast Asian manufacturing scale-up.
- Cartons:Chilled distribution formats serve premium positioning in Australian health stores with shorter shelf life but cleaner label appeal.
- Bottles:PET and glass formats target convenience store impulse purchase in Japanese and South Korean urban corridors.
- Pouches:Flexible packaging competes on price in Indonesian and Philippine mass retail with reduced logistics cube efficiency.
Tetra Packs dominate installed base through food service penetration. Bottles represent the steepest expansion trajectory in convenience channel positioning.
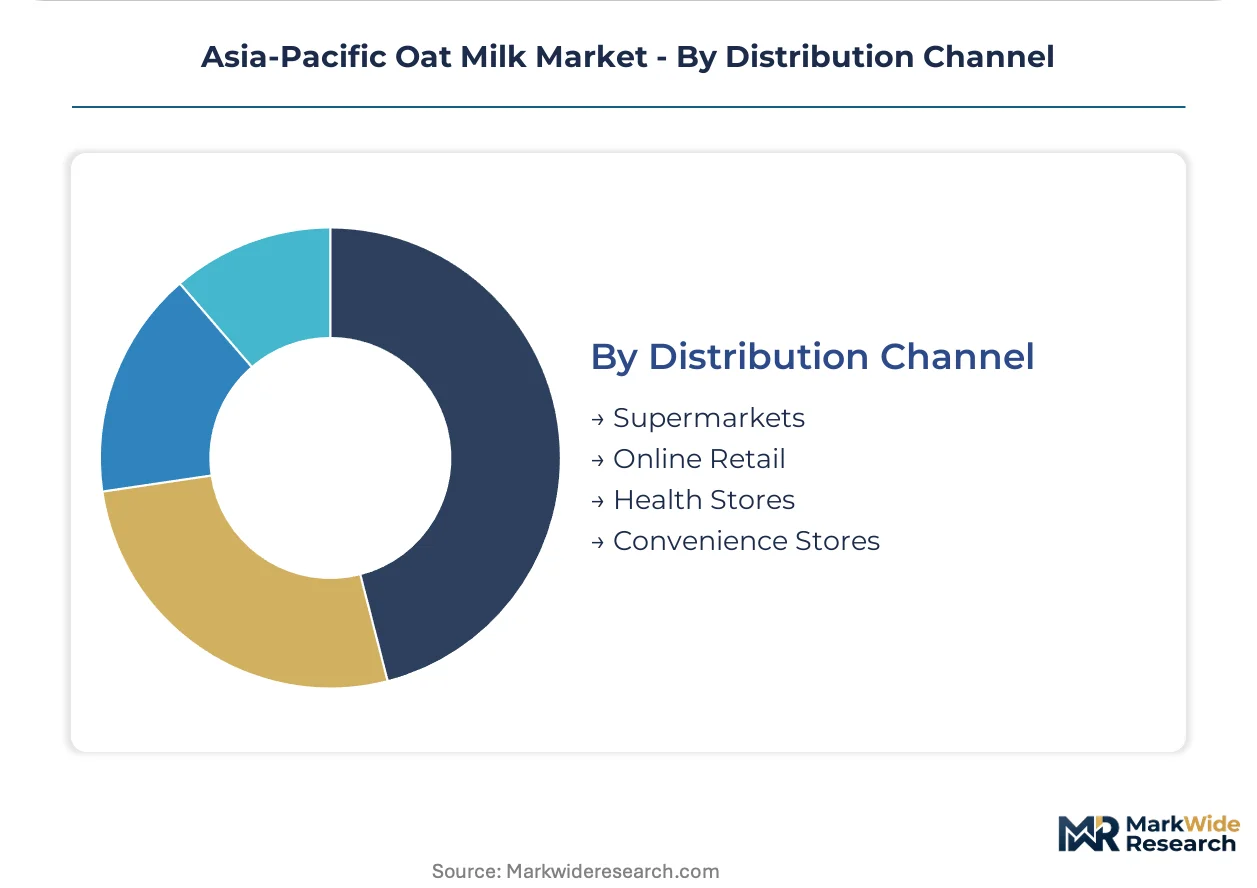
Distribution Channel:
Margin capture diverges between slotting-fee-burdened hypermarket conglomerates and direct-to-consumer subscription platforms.
- Online Retail:South Korean e-commerce ecosystems enable bypass of traditional retail slotting fees, capturing margin pools otherwise surrendered to hypermarket conglomerates. Subscription models and direct-to-consumer platforms accelerate fastest in Seoul and Tokyo metropolitan districts.
- Supermarkets:Australian supermarket chains anchor volume through deep retail distribution, though FSANZ plant-based labeling revisions force reformulation investments and packaging redesigns.
- Health Stores:Specialty retail channels in Australian and New Zealand markets emphasize clean label positioning and organic certification premiums.
- Convenience Stores:Japanese and South Korean urban networks favor single-serve formats with premium pricing for immediate consumption occasions.
Supermarkets dominate installed base through established retail infrastructure. Online Retail represents the steepest expansion trajectory as digital penetration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cafe procurement committees concentrate buying power across metropolitan Australia, South Korea, and Singapore, displacing fragmented household demand as the primary volume anchor for oat milk suppliers.
Australia
Third-wave coffee culture in Melbourne and Sydney normalizes oat milk as default dairy alternative, creating demonstration effects through tourism networks. FSANZ plant-based labeling revisions under Standard 2.5.2 force packaging redesigns and protein fortification adjustments. Southeastern Australia hosts concentrated oat milling capacity that supplies formulated product across the region.
South Korea
Seoul's cafe-dense districts and health-conscious younger consumers accelerate category penetration through subscription models. MFDS novel food registration streamlines import clearance for European and Australian suppliers. Centralized quality assurance departments at chained cafe conglomerates audit manufacturing facilities for enzymatic process control.
Japan
METI sustainable food labeling requirements favor oat milk's lower water intensity versus almond and dairy alternatives. Carbon footprint disclosure mandates create regulatory tailwind for premium positioning in Tokyo and Osaka convenience channels. Kanto region anchors demand concentration through urban retail density.
Singapore
Specialty cafe expansion and institutional catering contracts drive formulation standardization for ambient-stable products. Food service procurement consolidates through contract catering volume concentration with Malaysian partners. The city-state functions as logistics hub for Southeast Asian archipelagic distribution.
Vietnam
Rapid specialty coffee expansion in Ho Chi Minh City's District 1 and District 7 creates first-mover positioning opportunities. Domestic oat processing investment lags behind demand growth, leaving import-dependent supply chains. Localized marketing builds brand recognition ahead of manufacturing scale-up.
Asia-Pacific Oat Milk Market Competitive Landscape
Player mix skews toward multinational beverage conglomerates and regional dairy-alternative specialists, with barista-focused formulation expertise determining food service access. Market structure concentrates around premium-tier suppliers commanding cafe supply chains and mass-market players competing on retail price positioning. Two strategic archetypes dominate: barista-blend specialists leveraging enzymatic hydrolysis IP, and diversified plant-based portfolios anchored by existing distribution infrastructure. Competitive moves center on strategic partnerships with cafe chains and geographic expansion through direct-to-consumer platforms.
Within the barista-specialist tier, Oatly Group AB and Minor Figures Limited exemplify formulation-first positioning built around foam stability metrics and steam wand performance specifications. Sanitarium Health and Wellbeing Company anchors mass-market penetration through Australian supermarket distribution density. Oatside occupies a price-competitive position in Southeast Asian convenience channels. Nestlé SA and Danone SA represent diversified multinational archetypes with plant-based portfolios extending beyond oat-specific lines. Califia Farms LLC and Freedom Foods Group Ltd sit within mid-tier positioning, while PureHarvest exemplifies clean-label specialization targeting health store channels.
| Leading Market Players |
|---|
| Oatly Group AB |
| Freedom Foods Group Ltd |
| Nestlé SA |
| PureHarvest |
| Sanitarium Health and Wellbeing Company |
| Oatside |
| Califia Farms LLC |
| Danone SA |
| Minor Figures Limited |
| Others |
Pricing and Supply Chain Analysis
FSANZ Standard 2.5.2 plant-based labeling revisions gate both supplier qualification and price differentiation simultaneously, forcing protein fortification investments that separate compliant barista-blend premiums from reformulated standard tiers while non-compliant inventory faces write-down pressure.
Pricing Analysis
Cost-plus contracts with Australian grain futures indexation dominate procurement between southeastern oat millers and formulated product manufacturers. Three-tier pricing structure across premium barista blends, standard retail formulations, and economy private-label tiers reflects enzymatic hydrolysis sophistication and foam stability certification. Pricing pressure stems from soy milk substitution in Southeast Asian mass retail channels where established beverage infrastructure undercuts oat positioning. Food service buyers exhibit lowest price sensitivity due to steam wand performance requirements, while Indonesian and Philippine household segments drive cost compression.
Supply Chain Analysis
Port congestion along the Melbourne-Singapore trade lane and container availability constraints on Australian grain exports elevate inbound logistics costs for Southeast Asian processors lacking domestic oat milling capacity. Geographic supply concentrates in southeastern Australia, China's northern plains, and South Korean import clearance hubs. Raw material dependencies center on oat groats, beta-amylase enzymes, and aseptic packaging substrates. Single-source vulnerability runs through Tetra Pak aseptic filling equipment where capital intensity strains mid-tier regional entrants. Distribution runs through Singaporean logistics hubs serving archipelagic Southeast Asian markets with fragmented cold chain infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific oat milk markets are experiencing high-growth disruption catalyzed by MFDS novel food registration streamlining that compresses import clearance timelines for European and Australian suppliers targeting Seoul's cafe-dense districts.
For Market Incumbents: Shield formulation IP through enzymatic hydrolysis patent filings and captive supply agreements with Australian oat milling clusters. Deepen backward integration into beta-amylase sourcing to offset input volatility. Lock in multi-year procurement contracts with chained cafe conglomerates before quality assurance formalization elevates switching costs for competitors. For New Entrants and Emerging Players: Anchor in Vietnam's underpenetrated Ho Chi Minh City corridor where specialty coffee expansion outpaces domestic oat processing investment. Target direct-to-consumer subscription platforms in South Korean e-commerce ecosystems that bypass hypermarket slotting fees. Lead with barista-blend positioning to capture food service margins ahead of retail price wars. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across aseptic packaging line investments as ambient-stable formulations displace chilled distribution. Long-term viability over the next decade rests on enzymatic processing capabilities and cafe channel lock-in rather than commodity scale. Acquisition targets should display established MFDS or FSANZ compliance pathways. Monitor Japan's METI sustainable food labeling enforcement as signal for premium positioning viability in carbon-disclosure-driven markets.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Patent Expansion | Protects foam stability IP against Australian and Singaporean barista-focused competitors. |
| Direct-to-Consumer Platform Launch | Captures South Korean margin pools bypassing hypermarket conglomerate slotting structures. |
| MFDS Registration Fast-Track Investment | Compresses time-to-shelf for European suppliers targeting Seoul cafe procurement committees. |
| Backward Integration into Oat Milling | Secures southeastern Australian grain supply against freight margin compression volatility. |
| Barista Certification Program Development | Locks in food service loyalty through documented steam wand performance standards. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FSANZ regulatory filings, MFDS novel food registration databases, and Australian Bureau of Agricultural and Resource Economics grain production statistics. Primary interviews engaged food technologists at enzymatic processing facilities, procurement directors at chained cafe conglomerates, and quality assurance leads at Tetra Pak aseptic line operators. Secondary validation drew from customs trade data on oat concentrate imports, Nielsen retail audit figures for Australian supermarket channels, and Korea Consumer Agency e-commerce transaction records. Bottom-up volume estimates from individual facility throughput triangulate against top-down category spending projections.
Segmentation dimensions modeled span product type, end user, packaging format, and distribution channel across the projection horizon. The analytical framework disaggregates demand by barista-blend versus original formulations, cafe versus household procurement patterns, and ambient-stable versus chilled shelf-life requirements. CAGRs derive from logistic curve fitting to historical adoption trajectories in comparable beverage categories, adjusted for regulatory inflection timing. Industry-specific forecast inputs include enzymatic hydrolysis adoption rates and cafe channel procurement formalization indices.
Material uncertainties — oat grain price volatility, FSANZ labeling enforcement timing, and Southeast Asian logistics infrastructure development — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding MFDS registration pathway stability and third-wave coffee culture propagation through tourism networks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Europe Dairy Alternatives Market
Dairy Alternatives
A2 Milk Powder Market
Dairy Alternatives
Europe Non-Dairy Cheese Market
Dairy Alternatives
Walnut Milk Market
Dairy Alternatives
Banana Milk Market
Dairy Alternatives
United States Coffee Creamer Market
Dairy Alternatives
Milk Alternatives Market
Dairy Alternatives
North America Non-Dairy Cheese Market
Dairy Alternatives
Vegan Milk Alternatives Market
Dairy Alternatives
China Dairy Alternatives Market
Dairy Alternatives
Fat Free Yogurt Market
Dairy Alternatives
Vegan Coffee Creamer Market
Dairy Alternatives
Camel Milk Products Market
Dairy Alternatives
Vegan Cheese Alternatives Market
Dairy Alternatives
Pea Milk Market
Dairy Alternatives
Germany Non-Dairy Milk Market