
 Global Off-Highway Tire Market | 2026-2036
Global Off-Highway Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Global Off-Highway Tire Market Outlook
Asian tire manufacturing capacity is consolidating around integrated producers with captive rubber processing and steel cord facilities. Michelin leverages its radial technology leadership in large mining applications across Africa and South America. Balkrishna Industries anchors its position through specialized agricultural tire production for European and North American farm equipment OEMs. Yokohama Rubber Company competes aggressively in the Asia-Pacific construction segment with reinforced bias-ply designs for articulated dump trucks.
Off-highway tires are engineered structures comprising multiple rubber compounds, steel belts, and textile plies designed to withstand extreme loads, puncture hazards, and uneven terrain without highway-speed thermal degradation. Radial tires dominate the high-value mining and large construction segments due to superior heat dissipation and tread life under continuous heavy loads. Bias tires retain structural importance in forestry and certain agricultural applications where sidewall flexibility and lower acquisition cost outweigh mileage considerations. Solid tires command premium positioning in material handling and underground mining where puncture elimination justifies reduced cushioning and higher unit prices.
EPA non-road emission tiers and EU F-Gas Regulation on fluorinated greenhouse gases shape tire material specifications and retreading practices across North American and European supply chains. ISO 9001 quality management and ECE R54 load/speed certification govern cross-border market access for radial and bias products destined for regulated jurisdictions. Stakeholders must monitor evolving mine-site sustainability protocols and OEM electrification roadmaps to align tire development programs with emerging equipment weight distributions and torque characteristics.
Market Dynamics
EPA non-road emission tiers and EU F-Gas Regulation are forcing OEMs to specify low-rolling-resistance tire designs, compressing development cycles and favoring integrated producers with captive rubber processing and steel cord facilities.
Growth Catalysts
- Mining fleet replacement cycles:Australian and Chilean operators are expanding tire replacement programs amid deeper ore extraction, sustaining demand for heavy-duty earthmover radials.
- REACH and F-Gas Regulation:European material specifications are accelerating retreading adoption and reshaping compound formulations across North American and European supply chains.
- State-funded infrastructure:China's western provinces are driving heavy-duty earthmover tire demand through government-backed mining and construction projects.
Market Restraints
- Natural rubber price volatility:Input cost swings from Southeast Asian supply disruptions compress margins for non-integrated manufacturers lacking captive processing.
- Steel cord supply concentration:Dependency on Chinese and South Korean metallurgical suppliers creates vulnerability to export restrictions and freight cost spikes.
- Bias-ply technical ceiling:Structural heat dissipation limitations prevent bias designs from penetrating high-value mining segments regardless of acquisition cost advantages.
Strategic Opportunities
- Underground mining electrification:Battery-powered load-haul-dump equipment in Canadian and Scandinavian operations requires redesigned tire carcasses accommodating higher torque and weight distributions.
- Retreading service networks:Independent dealers in Brazil and South Africa are capturing aftermarket value through localized remanufacturing capabilities.
- ISO 9001 and ECE R54 convergence:Harmonized quality and load/speed certification standards are reducing cross-border market access friction for radial and bias products.
Industry Challenges
- Compound formulation expertise gap:Shortages of polymer chemists capable of balancing rolling resistance, cut resistance, and heat dissipation in multi-layer structures.
- OEM electrification timeline compression:Accelerated equipment roadmaps are forcing tire developers to validate prototypes against unfinalized torque and weight specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Off-Highway Tire Market |
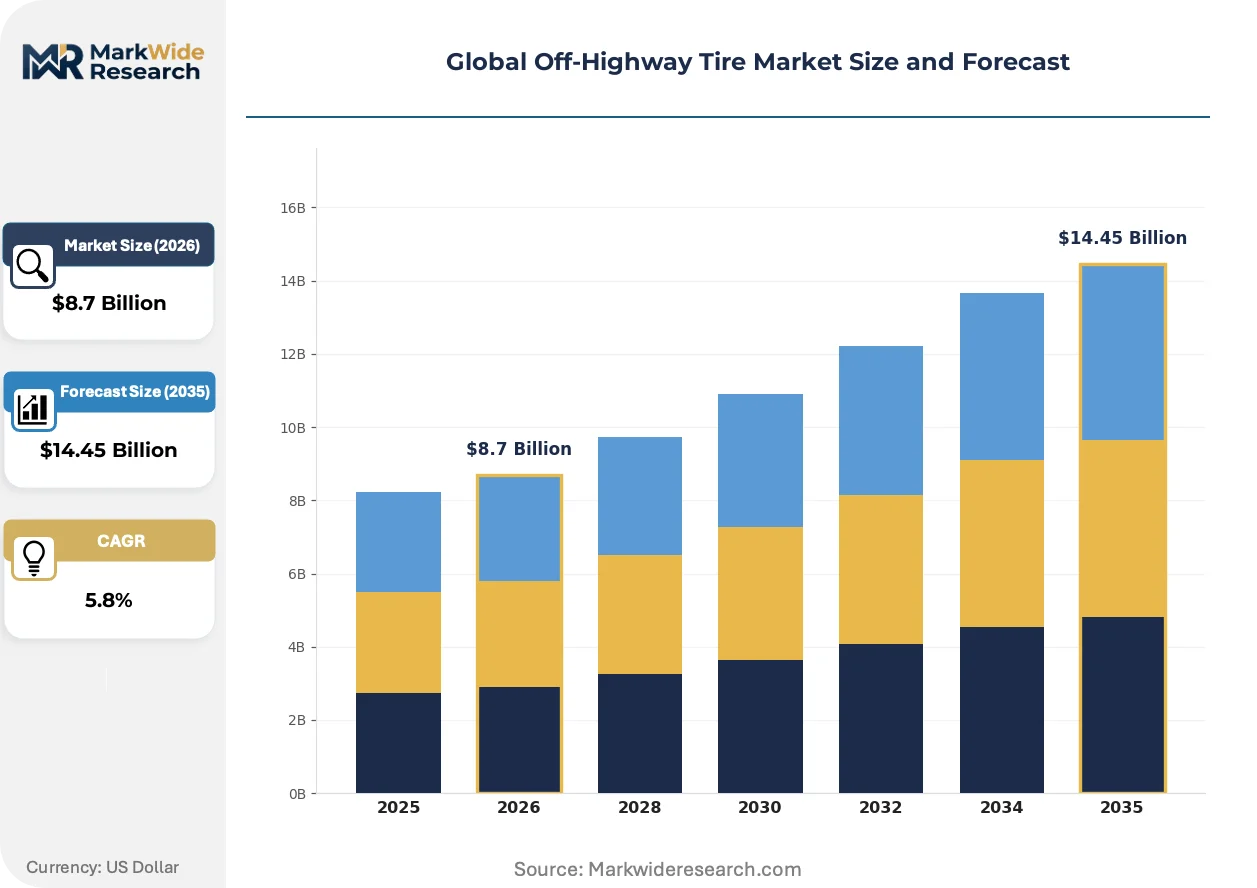
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial Tires, Bias Tires, Tubeless Tires, Solid Tires End User: Agriculture, Construction, Mining, Forestry Application: Tractors, Excavators, Loaders, Dump Trucks Size: Small, Medium, Large, Extra Large |
| Companies Covered | Continental, Yokohama Rubber Company, Michelin, Toyo Tires, Titan International, Bridgestone, Balkrishna Industries, Sailun Group, Goodyear Tire & Rubber Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Off-Highway Tire Market Strategic Shifts
Digital tire monitoring and predictive maintenance systems are automating fleet management decisions, while regulatory pressure on fluorinated compounds and non-road emissions is reshaping material specifications across integrated supply chains.
Embedded RFID sensors and cloud-connected pressure monitoring systems are automating real-time load and temperature tracking for mining fleets. Australian iron ore operators are deploying these systems fleet-wide to optimize replacement timing and prevent thermal failures. The technology is automating procurement decisions that previously relied on manual inspection intervals, compressing the service-contract sales cycle.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are prohibiting certain curing agents and release compounds in tire manufacturing. Compound suppliers are reformulating around hydrocarbon-based alternatives with modified vulcanization kinetics. Large radial producers serving European OEMs are absorbing certification costs fastest, creating compliance distance from bias-ply competitors.
Consolidated mining operators in Chile and Western Australia are unbundling tire procurement from full-service maintenance contracts. Direct purchasing through manufacturer-direct channels is displacing distributor-mediated transactions for high-volume accounts. This pattern concentrates most visibly in copper and iron ore operations with standardized equipment fleets and in-house technical staff.
Global Off-Highway Tire Market Segmentation
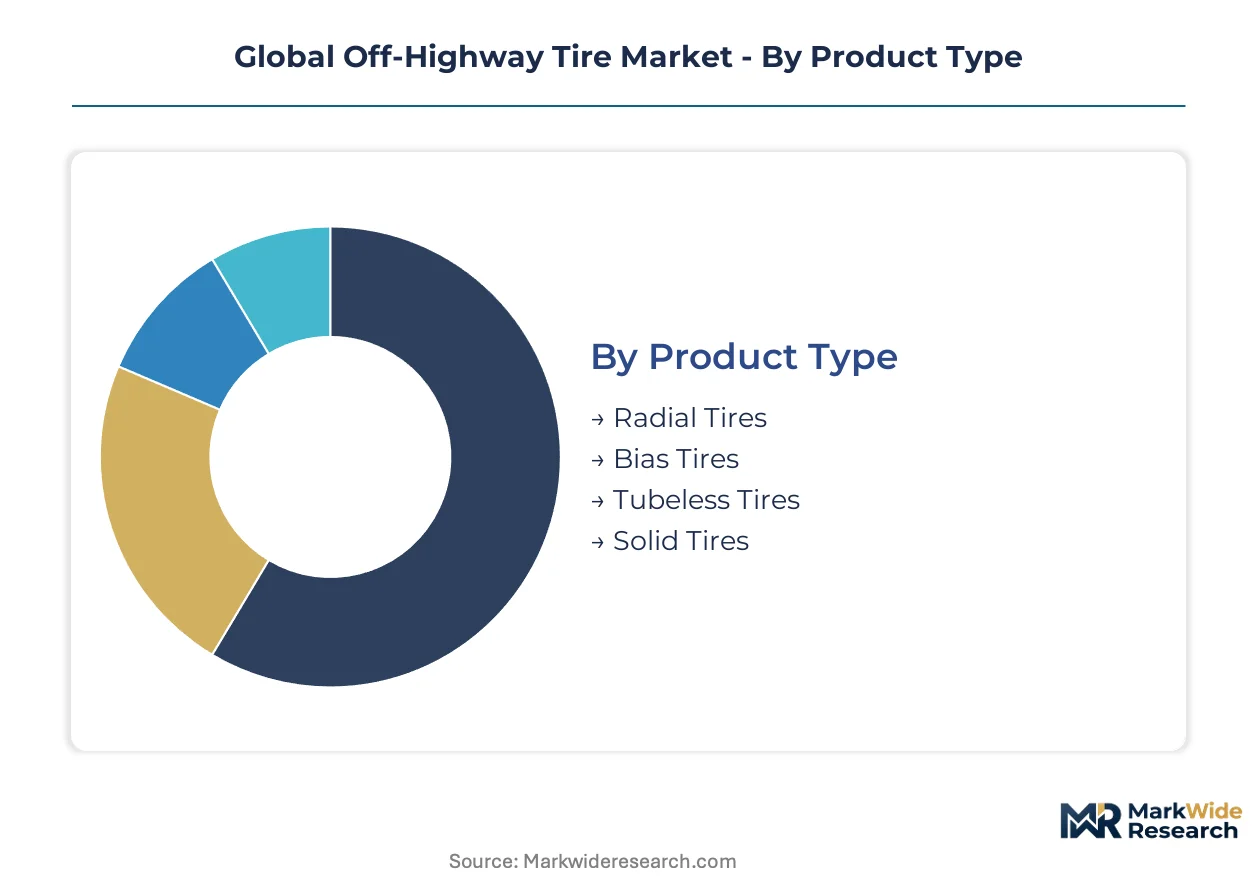
Off-highway tire segmentation tracks divergent engineering requirements across load-bearing capacity, terrain severity, and equipment electrification timelines. Product architecture, end-use intensity, and dimensional class collectively determine margin structures and replacement cycles.
Product Type:
Radial construction dominates where heat dissipation and tread longevity justify premium positioning against acquisition cost.
- Radial Tires:Steel-belted carcass with perpendicular cord orientation enables superior heat management under continuous heavy loads. Mining fleets in Western Australia and Chile specify these exclusively for haul trucks operating 24-hour extraction cycles at depth.
- Bias Tires:Diagonal ply construction delivers sidewall flexibility at lower unit cost. Forestry operations in Sweden and Brazil retain bias specifications where puncture resistance and terrain conformability outweigh mileage metrics.
- Tubeless Tires:Eliminate inner tube failure modes through airtight bead-to-rim sealing. Agricultural OEMs in Germany and Iowa integrate these into high-horsepower tractor platforms.
- Solid Tires:Rubber-filled structure eliminates puncture risk entirely. Underground mining operations in Canada and Finland specify these for battery-powered load-haul-dump vehicles where downtime carries extreme cost.
Mature deployment sits with Bias Tires. Newer deployment is concentrated in Solid Tires.
End User:
Application intensity and fleet standardization determine procurement channel selection and service contract structures.
- Mining:Ultra-class haul trucks require engineered solutions validated against ISO 9001 and ECE R54 load specifications. Copper and iron ore operators in Chile and Western Australia unbundle procurement from full-service contracts.
- Construction:Articulated dump trucks and motor graders demand cut-resistant compounds for abrasive aggregate environments. Chinese state-funded infrastructure projects in western provinces drive heavy-duty earthmover specifications.
- Agriculture:Row-crop and specialty farming equipment requires flotation and high-drawbar configurations. European and North American farm equipment OEMs specify through integrated tire suppliers with captive rubber processing.
- Forestry:Forwarders and harvesters operate on slash debris and steep grades where sidewall protection exceeds speed rating priorities. Nordic and Pacific Northwest operations favor bias-ply flexibility.
Volume concentration sits with Construction. Margin expansion is concentrating in Mining.
Application:
Equipment duty cycle and torque transmission requirements dictate carcass reinforcement and tread pattern engineering.
- Dump Trucks:Rigid and articulated configurations move unconsolidated material over unimproved haul roads. Payload-to-weight ratios exceeding 3:1 in Australian iron ore operations stress sidewall structures.
- Excavators:Tracked and wheeled variants subject tires to pivot shear and concentrated loading. Hydraulic breakout forces in Chilean copper pits accelerate shoulder wear patterns.
- Loaders:Bucket penetration and short-haul cycles generate heat buildup in tread compound. Surface mining operations in South Africa and Indonesia prioritize heat-resistant formulations.
- Tractors:Agricultural and industrial variants require variable inflation systems for field-road transition. North American and European precision farming platforms integrate central tire inflation.
Replacement frequency peaks with Loaders. Technology integration is advancing fastest in Tractors.
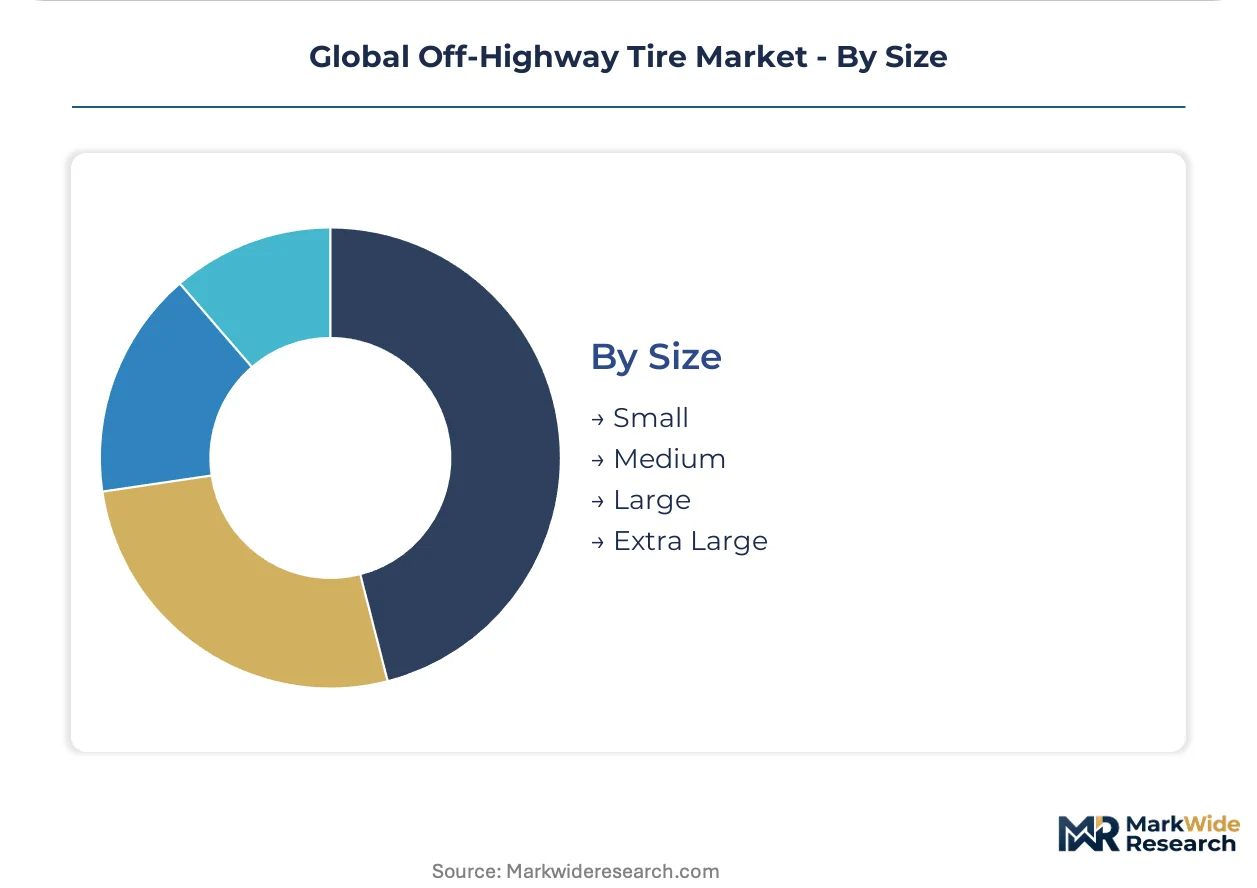
Size:
Dimensional classification tracks equipment weight progression and rim diameter standardization across OEM platforms.
- Extra Large:63-inch and 57-inch rim diameters for ultra-class mining trucks exceeding 400-ton payload. Michelin and Bridgestone dominate through radial technology leadership validated in African and South American pits.
- Large:51-inch to 49-inch configurations for construction and mid-tier mining equipment. Chinese western province infrastructure projects specify these for articulated dump trucks and motor graders.
- Medium:Agricultural tractors and smaller construction loaders populate this tier. European farm equipment OEMs source through specialized producers with captive steel cord facilities.
- Small:Material handling and compact construction equipment where solid and pneumatic bias designs compete. Brazilian and South African independent dealers capture aftermarket value through localized retreading.
Technology differentiation concentrates in Extra Large. Volume manufacturing is scaling fastest in Medium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeast Asian rubber plantations anchor raw material flows for tire manufacturing networks stretching across Asia-Pacific, North America, and Europe. Natural rubber processing clusters in Thailand and Indonesia supply compounders serving OEM specifications in mining and construction equipment.
United States
EPA non-road emission tiers are forcing OEMs to specify low-rolling-resistance tire designs for construction and agricultural equipment. The agency's Tier 4 Final standards apply to diesel engines above 25 horsepower, compressing development cycles for tire compounders. Midwest agricultural equipment manufacturing clusters in Iowa and Illinois integrate these specifications into high-horsepower tractor platforms.
Germany
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are prohibiting certain curing agents in tire manufacturing processes. REACH chemical registration requirements are accelerating retreading adoption and reshaping compound formulations. Industrial machinery OEMs in Baden-Württemberg and Bavaria source through integrated tire suppliers with captive rubber processing and steel cord facilities.
China
State-funded infrastructure projects in western provinces are driving heavy-duty earthmover tire demand for mining and construction applications. MIIT industrial standards govern radial and bias product certification for domestic and export markets. Manufacturing clusters in Shandong and Jiangsu provinces concentrate capacity around producers with backward integration into rubber processing.
Australia
Mining fleet operators in Western Australia and Queensland are expanding tire replacement programs amid deeper ore extraction at Pilbara iron ore and Bowen Basin coal operations. The country's national mining regulator enforces site-specific sustainability protocols affecting procurement decisions. Perth-based technical teams are unbundling tire procurement from full-service maintenance contracts for standardized haul truck fleets.
Chile
Copper mining operations in the Atacama Desert are sustaining demand for ultra-class mining radials operating 24-hour extraction cycles. The national mining regulator Sernageomin oversees equipment safety standards including tire load specifications. Antofagasta and Calama industrial corridors concentrate fleet maintenance capabilities serving state-owned and private copper producers.
Global Off-Highway Tire Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue electrification-ready designs and localized retreading services. The vendor base stratifies across three tiers: integrated multinationals with captive rubber and steel cord facilities, specialized regional producers focused on agricultural or mining segments, and independent retreaders capturing aftermarket value through service networks. Dominant competitive moves include backward integration into raw material processing and geographic expansion through manufacturer-direct sales channels displacing distributor relationships.
Within the integrated multinational tier, Michelin and Bridgestone exemplify producers with radial technology leadership validated in large mining applications. Yokohama Rubber Company occupies a position among Asia-Pacific-focused competitors competing in construction segments. Balkrishna Industries represents specialized agricultural tire production serving European and North American farm equipment OEMs. These anchors demonstrate how technology specialization and geographic focus determine competitive positioning without requiring equivalent scale across all product categories.
| Leading Market Players |
|---|
| Continental |
| Yokohama Rubber Company |
| Michelin |
| Toyo Tires |
| Titan International |
| Bridgestone |
| Balkrishna Industries |
| Sailun Group |
| Goodyear Tire & Rubber Company |
| Others |
Value Chain & Pricing Dynamics
EU F-Gas Regulation restrictions on fluorinated greenhouse gases gate qualified supply for European OEM contracts and lock premium-tier pricing access behind reformulated compound certification. This environmental mandate compresses margin structures for non-integrated manufacturers while rewarding producers with captive rubber processing and in-house vulcanization expertise.
Pricing Analysis
Warranty and service bundling separates full-service maintenance contracts from unbundled tire-only procurement for mining fleet operators in Western Australia and Chile. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 9001 certification grade and after-sales service inclusion, with ultra-class mining radials commanding the highest tier. Pricing pressure stems from natural rubber cost volatility and unbundled procurement trends, compressing margins for distributor-dependent suppliers. Construction fleet operators in China's western provinces exhibit highest price sensitivity, while underground mining operations in Canada prioritize puncture elimination over unit cost.
Supply Chain Analysis
ECE R54 load/speed certification and ISO 9001 quality management standards gate market access for radial and bias products destined for regulated jurisdictions in North America and Europe. Raw material flows draw from Thai and Indonesian rubber plantations, Chinese and South Korean steel cord metallurgical suppliers, and German compound formulation specialists. Single-source vulnerability concentrates in steel cord supply, where export restrictions or freight cost spikes disrupt carcass reinforcement availability. Distribution runs through manufacturer-direct channels displacing traditional distributor relationships for high-volume mining accounts in Chile and Western Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over captive rubber processing and steel cord facilities determines margin defense and contract eligibility for EPA Tier 4 Final and EU F-Gas Regulation compliance.
For Market Incumbents: Deepen backward integration into Southeast Asian rubber processing clusters to insulate margin structures from natural rubber price volatility. Expand manufacturer-direct sales channels in Australian and Chilean mining corridors to capture unbundled procurement flows and displace distributor-mediated transactions. Prioritize ECE R54 certification investment for ultra-class radial portfolios to maintain compliance distance from bias-ply competitors.
For New Entrants and Emerging Players: Independent retreaders serving Brazilian and South African aftermarket segments represent the most penetrable buyer archetype for localized remanufacturing capabilities. Battery-powered load-haul-dump equipment in Canadian and Scandinavian underground operations offers white-space entry for electrification-ready tire carcass designs. Pursue joint development agreements with OEMs finalizing torque and weight specifications ahead of formal electrification roadmaps.
For Investors and Strategic Acquirers: Unbundling of tire procurement from full-service maintenance contracts in Chilean copper and Australian iron ore operations is the leading indicator that aftermarket service network value is migrating toward manufacturer-direct channels. Long-term viability favors integrated producers with captive steel cord facilities and compound formulation expertise over non-integrated assemblers exposed to input cost volatility. Watch for OEM electrification timeline compression as the signal that validated tire prototypes for higher torque applications will command acquisition premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Processing | Thai and Indonesian plantation control insulates margin structures from Southeast Asian supply disruptions. |
| Retreading Service Network Expansion | Brazilian and South African localized remanufacturing captures aftermarket value from distributor displacement. |
| Electrification-Ready Carcass Development | Canadian and Scandinavian battery-powered LHD specifications validate higher-torque tire architectures. |
| Manufacturer-Direct Channel Buildout | Perth and Antofagasta technical teams displace distributor relationships for standardized haul truck fleets. |
| ECE R54 Certification Investment | Harmonized load/speed standards reduce cross-border friction for radial products serving European OEMs. |
Study Parameters
Independent corroboration across mining fleet maintenance directors, OEM procurement teams, tire compound R&D leads, and aftermarket service heads underwrites the qualitative findings in this study. Primary interviews with plant engineers at Western Australian iron ore operations and Chilean copper pits combined with secondary validation from EPA non-road emission filings, EU ECHA REACH registrations, and customs trade data for natural rubber and steel cord imports. Bottom-up equipment population modeling and top-down tire replacement cycle analysis triangulate volume estimates across the analysis window.
Rate-of-change decomposition separates volume growth from price-mix effects across product type, end-use intensity, equipment size class, and regional regulatory cluster dimensions. CAGRs derive from segment-level replacement cycle frequencies, fleet expansion rates at deeper extraction depths, and electrification penetration assumptions for underground mining equipment. Industry-specific forecast inputs include MIIT industrial standard adoption curves in China and Sernageomin equipment safety enforcement patterns in Chile.
Revisions become necessary when EPA emission tier acceleration, EU F-Gas compound restriction expansion, or OEM electrification specification finalization materialize differently than modeled assumptions. A model refresh is warranted upon material change in natural rubber supply disruption frequency or steel cord export restriction enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Rechargeable Tires Market
Tires and Wheels
Global Automotive Tires Market
Tires and Wheels
North America OTR Tire Market
Tires and Wheels
Automotive 3D Printed Tires Market
Tires and Wheels
Ground Support Equipment Tires Market
Tires and Wheels
Automotive Retread Tires Market
Tires and Wheels
Cargo Bike Tire Market
Tires and Wheels
Europe Green Tire Market
Tires and Wheels
Automotive Wheel Rims Market
Tires and Wheels
Tire Changers Market
Tires and Wheels
Performance Tires Market
Tires and Wheels
Bias Tire Market
Tires and Wheels
Carbon Wheels Market
Tires and Wheels
Low Rolling Resistance Tire Market
Tires and Wheels
Wheel Spacers and Adapters Market
Tires and Wheels
Connected Tire Market