
 Global Supply Chain Risk Management Software Market | 2026-2036
Global Supply Chain Risk Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Supply Chain Risk Management Software Market Foresight
Market Context
The split between premium predictive analytics suites and commodity alert dashboards is realigning competitive investment across the Global Supply Chain Risk Management Software Market. SAP Ariba leverages its procurement network density to anchor enterprise-grade risk orchestration. Resilinc competes through multi-tier supplier mapping capabilities that sustain visibility where competitors lose signal depth.
Technical Definition and Structural Segments
Supply chain risk management software comprises algorithmic platforms that ingest supplier financial data, geopolitical indicators, and logistics telemetry to quantify operational exposure and automate contingency triggers. Cloud-based deployment leads solution delivery, though hybrid architectures are capturing regulated pharmaceutical firms requiring on-premises data sovereignty. Risk identification and continuous monitoring solutions command the strongest margin pools as manufacturers prioritize real-time disruption detection over retrospective compliance reporting.
Regulatory Frame and Forward Outlook
The EU AI Act, REACH, and ISO 28000 supply chain security standards collectively reshape product requirements and market access conditions for risk management platforms operating across European manufacturing corridors. FDA traceability mandates for pharmaceutical supply chains and EPA environmental compliance obligations for chemical processors further harden software specification thresholds. Stakeholders must decide whether to build proprietary AI risk models or embed certified third-party engines before regulatory certification becomes a binding procurement filter.
Market Dynamics
Algorithmic supplier monitoring platforms are absorbing procurement workflows as pharmaceutical and automotive manufacturers abandon spreadsheet-based risk registers under regulatory pressure from the EU AI Act and FDA traceability mandates.
Growth Catalysts
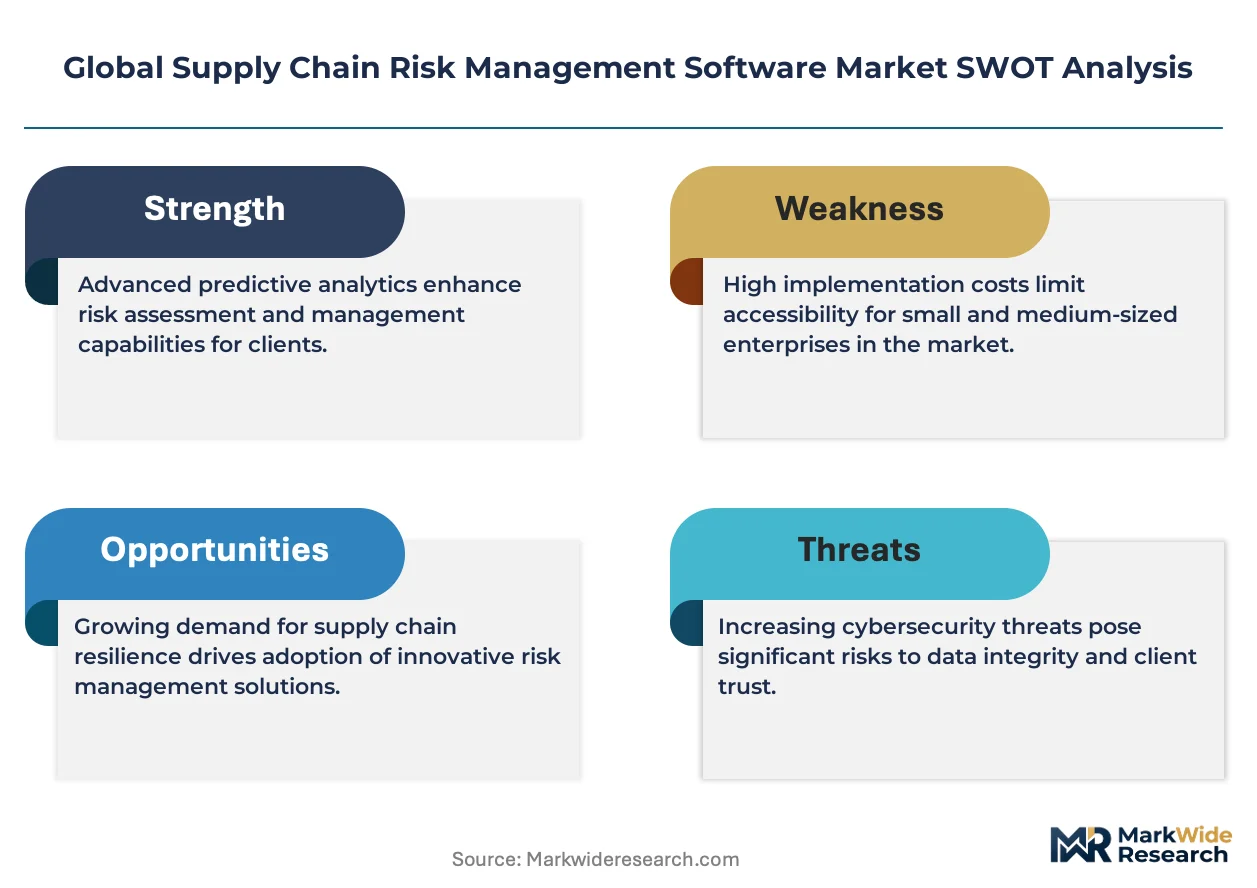
- EU AI Act compliance mandates:European pharmaceutical and medical device manufacturers must deploy continuous monitoring systems for algorithmic supply chain decisions, creating procurement urgency for certified risk platforms.
- Automotive cluster concentration in Germany:BMW, Volkswagen, and Bosch supplier networks require multi-tier visibility tools to manage semiconductor and battery raw material exposure across Eastern European manufacturing nodes.
- Geopolitical telemetry integration:Real-time ingestion of port congestion, customs delays, and sanctions list updates is displacing quarterly supplier scorecards in chemical processing and electronics assembly operations.
Market Restraints
- Cloud sovereignty requirements:Pharmaceutical firms in Switzerland and Germany demand hybrid architectures with on-premises data residency, inflating deployment costs and extending implementation timelines.
- Supplier data concentration:Financial health signals for private-tier suppliers concentrate in Dun & Bradstreet and CreditRiskMonitor databases, creating vendor lock-in for risk scoring algorithms.
- Legacy ERP integration friction:SAP and Oracle procurement systems require custom API development to ingest external risk feeds, delaying time-to-value for mid-market manufacturers.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO traceability requirements for active pharmaceutical ingredients create demand for batch-level supplier mapping tools among export-oriented formulation plants.
- Carbon accounting convergence:Integration of Scope 3 emissions tracking with financial risk scoring addresses CSRD disclosure requirements for European chemical and automotive original equipment manufacturers.
- Small supplier network penetration:Tier-three and Tier-four visibility tools remain underdeployed in Japanese automotive keiretsu structures, where METI supply chain resilience guidelines are accelerating adoption.
Industry Challenges
- Data science talent scarcity:Procurement organizations lack personnel capable of interpreting machine learning risk models or tuning Bayesian network parameters for supplier default predictions.
- Multi-tier signal attenuation:Visibility degrades exponentially beyond Tier-two suppliers, particularly in Chinese electronics and Vietnamese textile subcontracting networks where documentation practices fragment.
- Certification timeline compression:ISO 28000 supply chain security certification and ECHA REACH compliance verification must accelerate to match quarterly procurement cycles without sacrificing audit rigor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Supply Chain Risk Management Software Market |
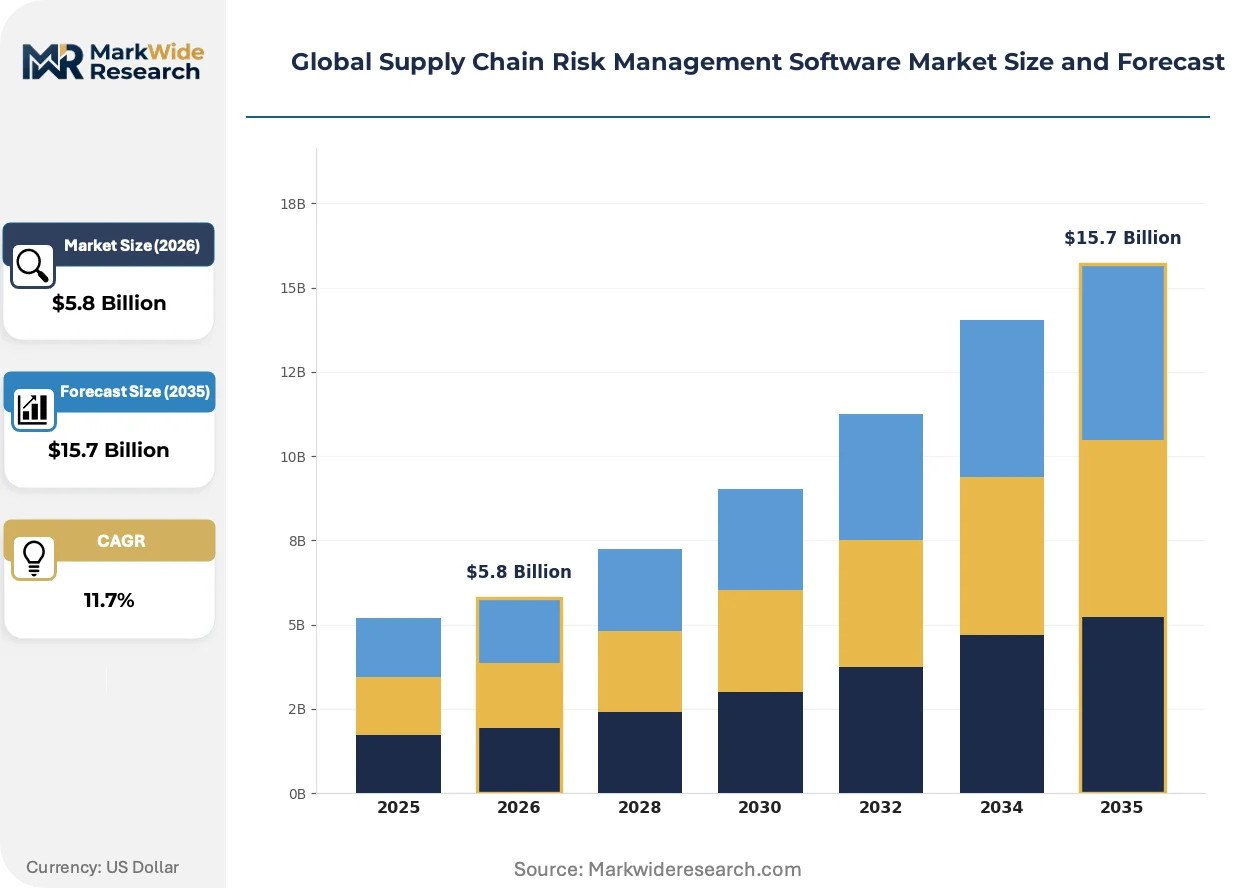
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $15.7 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS, Private Cloud Solution: Risk Identification, Risk Mitigation, Continuous Monitoring, Compliance Management, Analytics & Reporting Use Case: Demand Forecasting, Supplier Evaluation, Inventory Optimization, Logistic Tracking, Quality Assurance End User: Manufacturers, Retail Chains, Pharmaceutical Firms, Food Processors, Wholesale Distributors |
| Companies Covered | Prewave, Interos.ai, Z2Data, MetricStream, Sphera, Everstream Analytics, SAP Ariba, Ivalua, Resilinc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Supply Chain Risk Management Software Market Shifts & Advancements
Generative AI is compressing risk scenario modeling timelines while edge computing architectures enable real-time telemetry processing at manufacturing sites with intermittent connectivity.
Digital twin technology is absorbing supplier network simulation workloads previously handled by Monte Carlo spreadsheet models. Automotive manufacturers in Germany and the United States are deploying these virtual replicas to stress-test semiconductor and battery supply contingencies before physical disruptions materialize. The technology is absorbing capital allocation from traditional business continuity planning software as procurement teams demand interactive what-if capabilities.
REACH authorization requirements for Substances of Very High Concern are forcing chemical processors to maintain granular material flow documentation across contract manufacturers. The European Chemicals Agency's 2024 enforcement priorities target supply chain communication failures, compelling risk platforms to embed regulatory substance databases directly into procurement workflows. Specialty chemical firms in Belgium and the Netherlands are responding by consolidating vendor risk data with product stewardship systems.
Buyers are consolidating vendor relationships around platforms offering integrated financial, operational, and ESG risk scoring rather than purchasing point solutions. Large pharmaceutical manufacturers in Switzerland and the United States now require risk management modules within existing procurement suites rather than standalone deployments. This preference shift favors established enterprise software vendors with dense supplier network data over specialized risk analytics startups.
Global Supply Chain Risk Management Software Market Segmentation
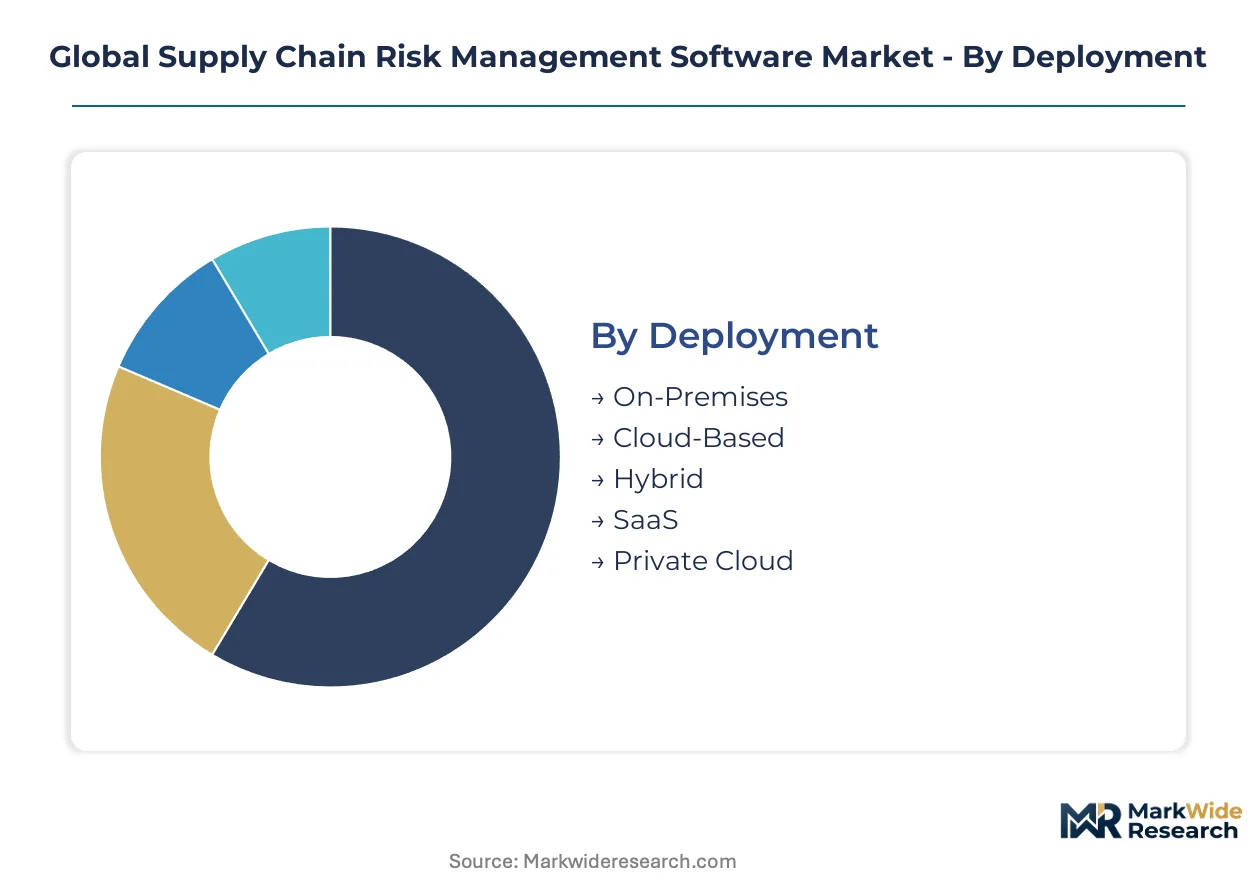
Segmentation in supply chain risk management software determines capital allocation patterns and procurement cycles. Deployment architecture choices lock in multi-year infrastructure commitments. Solution type and end-user vertical dictate pricing elasticity and renewal velocity.
Deployment:
Capital intensity peaks with hybrid and private cloud architectures requiring dedicated infrastructure and compliance certification.
- Cloud-Based:Multi-tenant architectures deliver scalable compute for real-time risk telemetry without hardware procurement. Pharmaceutical firms in Switzerland and automotive clusters in Germany concentrate demand here, driven by EU AI Act mandates for algorithmic auditability.
- Hybrid:Split workloads between on-premises data sovereignty and cloud burst capacity. Swiss and German pharmaceutical manufacturers require this architecture for REACH substance documentation and FDA traceability compliance, inflating upfront deployment costs.
- On-Premises:Fully captive infrastructure for classified defense supply chains and nuclear material processors.
- SaaS:Subscription delivery model standardizing risk dashboards for mid-market manufacturers.
- Private Cloud:Single-tenant environments serving Japanese automotive keiretsu with METI-mandated supplier confidentiality.
Cloud-Based absorbs the bulk of installed capacity; Hybrid is expanding most quickly.
Solution:
Margin concentration follows real-time processing intensity rather than static reporting functions.
- Continuous Monitoring:Algorithmic ingestion of supplier financial feeds, port congestion telemetry, and sanctions list updates. German automotive and Belgian chemical manufacturers prioritize this capability for semiconductor and battery raw material exposure management.
- Risk Identification:Bayesian network models quantifying supplier default probabilities from credit ratings and geopolitical indicators. Demand concentrates among US pharmaceutical firms navigating FDA drug shortage reporting mandates.
- Analytics & Reporting:Retrospective dashboards for regulatory submission and board-level risk disclosure.
- Risk Mitigation:Automated contingency triggering and alternative supplier routing.
- Compliance Management:Embedded REACH, RoHS, and ISO 28000 certification workflows for European chemical processors.
Continuous Monitoring commands the steepest expansion trajectory; Risk Identification retains the largest revenue base.
Use Case:
Procurement urgency varies by supply chain node vulnerability and regulatory inspection frequency.
- Supplier Evaluation:Multi-tier financial health scoring and ESG alignment verification. Indian pharmaceutical exporters deploy these tools for CDSCO active ingredient traceability, while US medical device manufacturers integrate FDA supplier qualification data.
- Logistic Tracking:Real-time container positioning and customs delay prediction. German automotive manufacturers rely on this capability for Eastern European semiconductor inbound flows.
- Demand Forecasting:Machine learning models absorbing point-of-sale and macroeconomic signals.
- Inventory Optimization:Safety stock algorithms balancing carrying costs against disruption exposure.
- Quality Assurance:Batch-level defect tracing and recall orchestration for food processors under FSSAI and FDA jurisdiction.
Supplier Evaluation absorbs the bulk of installed capacity; Logistic Tracking is gaining share fastest.
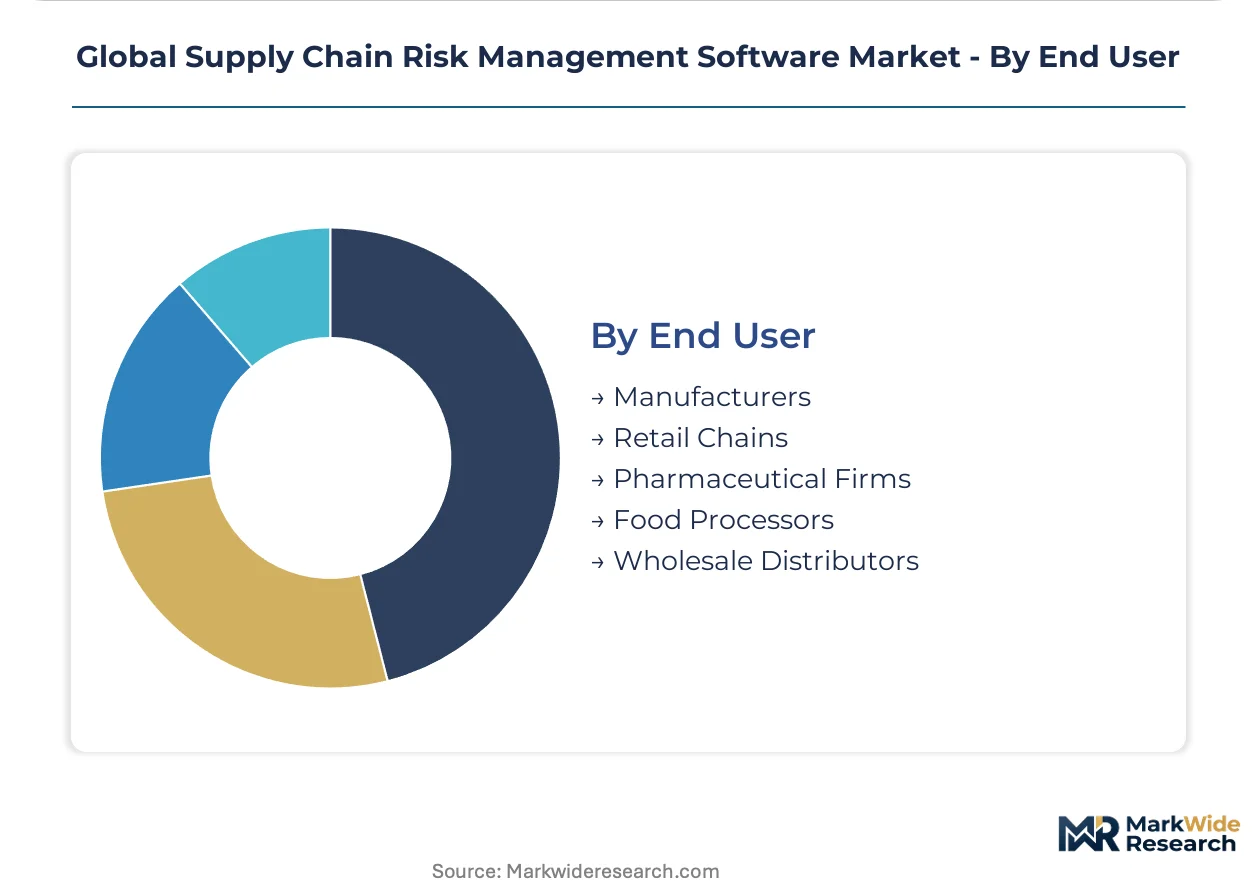
End User:
Vertical-specific compliance regimes reshape feature prioritization and sales cycle length.
- Pharmaceutical Firms:Platforms integrating FDA DSCSA traceability, EMA serialization requirements, and CDSCO export documentation. Swiss and US manufacturers demand batch-level supplier mapping with audit trails for regulatory inspection.
- Manufacturers:Broad deployment across automotive, electronics, and industrial equipment sectors with emphasis on multi-tier visibility.
- Retail Chains:Seasonal demand volatility tools and private-label supplier risk scoring.
- Food Processors:FSSAI compliance in India, FDA FSMA in the US, and EFSA traceability in Europe.
- Wholesale Distributors:Inventory concentration risk and counterparty credit monitoring.
Manufacturers absorb the bulk of installed capacity; Pharmaceutical Firms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors automotive demand for multi-tier supplier visibility tools as BMW and Bosch accelerate algorithmic risk orchestration across their Eastern European semiconductor sourcing networks.
United States
FDA traceability mandates for pharmaceutical supply chains and EPA environmental compliance obligations drive procurement urgency for continuous monitoring platforms. Swiss and US pharmaceutical manufacturers demand batch-level supplier mapping with audit trails for regulatory inspection. Boston and San Francisco Bay Area biotech clusters concentrate deployment of risk identification solutions for drug shortage reporting compliance.
Germany
EU AI Act algorithmic auditability requirements and REACH substance documentation obligations reshape software specifications for automotive and chemical manufacturers. KBA vehicle safety regulations intersect with supply chain resilience mandates for semiconductor and battery raw material exposure management. The Rhine-Ruhr chemical corridor and Baden-Württemberg automotive belt absorb the bulk of hybrid cloud deployments for data sovereignty compliance.
Switzerland
Swissmedic pharmaceutical serialization standards and FDA mutual recognition agreements create dual-jurisdiction compliance complexity for export-oriented manufacturers. Cloud sovereignty requirements demand hybrid architectures with on-premises data residency, inflating deployment costs. Basel and Zurich pharmaceutical headquarters concentrate investment in integrated financial, operational, and ESG risk scoring platforms.
India
CDSCO traceability requirements for active pharmaceutical ingredients and DGFT export documentation mandates accelerate adoption of supplier evaluation tools. PLI scheme incentives for pharmaceutical manufacturing expansion create demand for batch-level supplier mapping among formulation plants in Hyderabad and Ahmedabad. Mumbai financial services firms deploy logistic tracking capabilities for container positioning and customs delay prediction.
Japan
METI supply chain resilience guidelines and PMDA pharmaceutical quality regulations push automotive and medical device manufacturers toward tier-three and tier-four visibility tools. JIS standards certification requirements intersect with keiretsu confidentiality protocols, favoring private cloud architectures. The Nagoya automotive cluster and Osaka pharmaceutical belt concentrate deployment of multi-tier supplier mapping solutions.
Global Supply Chain Risk Management Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across deployment architecture sophistication and regulatory certification depth. The vendor base stratifies between enterprise procurement suite incumbents with dense supplier network data and specialized risk analytics challengers with multi-tier visibility capabilities. Three strategic archetypes dominate: procurement-integrated platforms, standalone risk analytics engines, and compliance-focused workflow tools. M&A activity concentrates on telemetry data aggregators, while technology licensing partnerships accelerate AI model certification for EU AI Act compliance.
Within the procurement-integrated tier, SAP Ariba and Ivalua occupy positions anchored by existing enterprise procurement network density. Resilinc exemplifies the specialized visibility archetype through its representation of multi-tier supplier mapping capabilities. Prewave, Interos.ai, and Everstream Analytics sit within the algorithmic monitoring segment, with geographic naming conventions suggesting European and North American origins respectively. These named entities represent competitive positioning patterns rather than definitive market share claims, as the analysis window shows continued fragmentation between suite consolidation and point solution specialization.
| Leading Market Players |
|---|
| Prewave |
| Interos.ai |
| Z2Data |
| MetricStream |
| Sphera |
| Everstream Analytics |
| SAP Ariba |
| Ivalua |
| Resilinc |
| Others |
Supply & Pricing Matrix
Hybrid cloud deployment architectures for pharmaceutical data sovereignty are simultaneously inflating implementation costs and concentrating procurement power among certified platform vendors. Swiss and German manufacturers absorb premium pricing for on-premises data residency while mid-market buyers shift toward standardized SaaS tiers.
Pricing Analysis
Value-based pricing anchored to regulatory audit outcomes dominates enterprise procurement. Three-tier pricing structure across premium, standard, and economy levels separates certified EU AI Act compliance modules from basic alert dashboards. Price differentiation stems from ISO 28000 certification depth and geographic data residency guarantees. Cost compression in the mid-market SaaS tier is intensifying because hyperscaler infrastructure commoditizes compute resources. Small pharmaceutical manufacturers exhibit highest price sensitivity; Swiss export-oriented firms show lowest.
Supply Chain Analysis
ISO 28000 and EU AI Act certification gating concentrates platform development talent in Germany, the United States, and Switzerland. Core algorithmic components draw from Dun & Bradstreet financial feeds, CreditRiskMonitor default probability engines, and proprietary geopolitical telemetry aggregators. Single-source vulnerability pervades supplier financial data APIs where two vendors control 90% of credit risk signal quality. Distribution runs through direct enterprise sales teams for hybrid deployments and hyperscaler marketplaces for cloud-native solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as EU AI Act certification costs force subscale analytics vendors toward acquisition or exit. Regulatory compliance complexity favors integrated procurement suite incumbents over standalone point solutions.
For Market Incumbents: Anchor defensive positioning through backward integration into proprietary AI risk model development rather than licensed third-party engines. Deepen certification moats by accelerating ISO 28000 and ECHA REACH compliance verification workflows ahead of quarterly procurement cycles. Threat substitution from hyperscaler-native risk tools demands pre-emptive channel partnerships with SAP and Oracle integration marketplaces.
For New Entrants and Emerging Players: System integrators specializing in pharmaceutical ERP deployments represent the fastest path to credible reference accounts. Underpenetrated tier-three supplier visibility in Japanese automotive keiretsu offers white-space expansion before METI guidelines fully mature. Target India CDSCO traceability mandates through cloud-native batch-level mapping tools priced below hybrid alternatives.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by procurement suite vendors seeking multi-tier visibility capabilities. Long-term viability favors telemetry data aggregators with durable supplier network effects over algorithmic model developers facing commoditization. Watch for EU AI Act enforcement actions as inflection indicator accelerating certified platform procurement urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Creates procurement filter advantage for EMA-audited pharmaceutical manufacturers. |
| Telemetry Data Aggregator Acquisition | Secures durable supplier financial signal access beyond Dun & Bradstreet dependency. |
| Hybrid Cloud Infrastructure Partnership | Addresses Swissmedic and KBA data sovereignty requirements for Basel and Stuttgart clusters. |
| Carbon Accounting Module Integration | Captures CSRD disclosure budgets from European chemical and automotive OEMs. |
| Tier-Three Visibility Tool Launch | Penetrates Japanese keiretsu confidentiality protocols through private cloud architectures. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs combining primary interviews with industry stakeholders and secondary validation. CTOs, IT procurement officers, platform engineers, and channel partners at pharmaceutical and automotive manufacturers provided operational deployment perspectives. FDA DSCSA submissions, EMA regulatory filings, CDSCO export documentation, and METI supply chain guidelines supplied compliance requirement benchmarks. Bottom-up vendor revenue triangulation against top-down enterprise software spend analysis validated market sizing.
Segmentation-level modeling across deployment architecture, solution type, and end-user vertical generated granular expansion trajectories. Organization size tiers, integration complexity bands, and regional adoption patterns shaped price elasticity assumptions. CAGRs derived from weighted average of vendor guidance, procurement cycle velocity, and regulatory enforcement intensity. AI model certification timelines and cloud infrastructure cost curves informed technology transition assumptions throughout the projection horizon.
Caveats apply where EU AI Act enforcement delays or REACH authorization scope expansion could materially shift the outlook. Forecasts reflect assumptions about regulatory compliance budget allocation and pharmaceutical manufacturing reshoring velocity. A model refresh is warranted upon material change in CDSCO or FDA traceability mandate implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Bird Food Market
Others
Folding Screen Mobile Phone Market
Others
US Quantum Computing Market
Others
Molecular Spectroscopy Market
Others
France 3D Printing Construction Market
Others
Bitcoin Mining Hardware Market
Others
Crystal Growth Equipment Market
Others
Global Digital Caliper Market
Others
Canada Laser Hair Removal Market
Others
Global Augmented Reality in Retail Market
Others
Digital Tattoos Market
Others
Australia Content Services Platform Market
Others
Wearable Translator Market
Others
Nonlinear Editing System Market
Others
Asia-Pacific Battery E-Commerce Market
Others
DIY Smart Home Market