
 Industrial Gauges Market | 2026-2036
Industrial Gauges Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Gauges Market Foresight
Distributor networks for process instrumentation is tilting toward direct OEM partnerships and integrated service contracts. WIKA Alexander Wiegand SE & Co. KG leverages its German manufacturing scale to dominate high-precision pressure gauge supply for European chemical complexes. Honeywell International Inc. sustains channel control through bundled digital gauge and control system offerings. Emerson Electric Co. anchors its position with smart gauge platforms that integrate into Plantweb digital ecosystems.
Industrial gauges are precision instruments engineered to measure process variables including pressure, temperature, fluid level, and flow rate, typically constructed from stainless steel, brass, or specialized alloys with accuracy ratings from 0.1% to 4% of full scale depending on application criticality. These devices serve as primary sensing elements in process control loops, enabling operators to monitor equipment health, prevent overpressure events, and maintain regulatory compliance across continuous manufacturing operations. Pressure gauges occupy the largest installed base among product types due to universal deployment across steam systems, compressed air networks, and hydraulic machinery. Smart and wireless technologies are expanding fastest as facilities pursue IIoT-enabled predictive maintenance strategies that reduce unplanned downtime. Analog gauges retain substantial share in cost-sensitive applications and hazardous environments where intrinsic safety requirements limit electronic device deployment.
OSHA process safety management standards and EPA leak detection regulations mandate calibrated instrumentation for facilities handling regulated substances above threshold quantities. The FDA enforces gauge calibration protocols in pharmaceutical manufacturing under 21 CFR Part 211, while the EU Pressure Equipment Directive establishes conformity requirements for gauges installed on categorized pressure systems. Stakeholders must monitor evolving cybersecurity frameworks for connected gauges as NIST and IEC publish updated industrial IoT security guidelines that will reshape product certification pathways and procurement specifications.
Market Dynamics
Digital gauge architectures are displacing analog instrumentation across hazardous process environments, driven by EPA emissions tracking mandates and OSHA process safety management requirements that demand real-time data logging and remote monitoring capabilities.
Growth Catalysts
- EPA Emissions Mandates:Updated tracking requirements compel Gulf Coast refineries to deploy smart gauges with integrated data transmission for continuous compliance reporting.
- Petrochemical Capacity Expansion:Texas, Louisiana, and Oklahoma are accelerating instrument procurement cycles as new processing units require calibrated pressure and temperature monitoring infrastructure.
- IIoT Predictive Maintenance:Wireless gauge networks enable facilities to shift from scheduled inspections to condition-based monitoring, reducing unplanned downtime in continuous operations.
Market Restraints
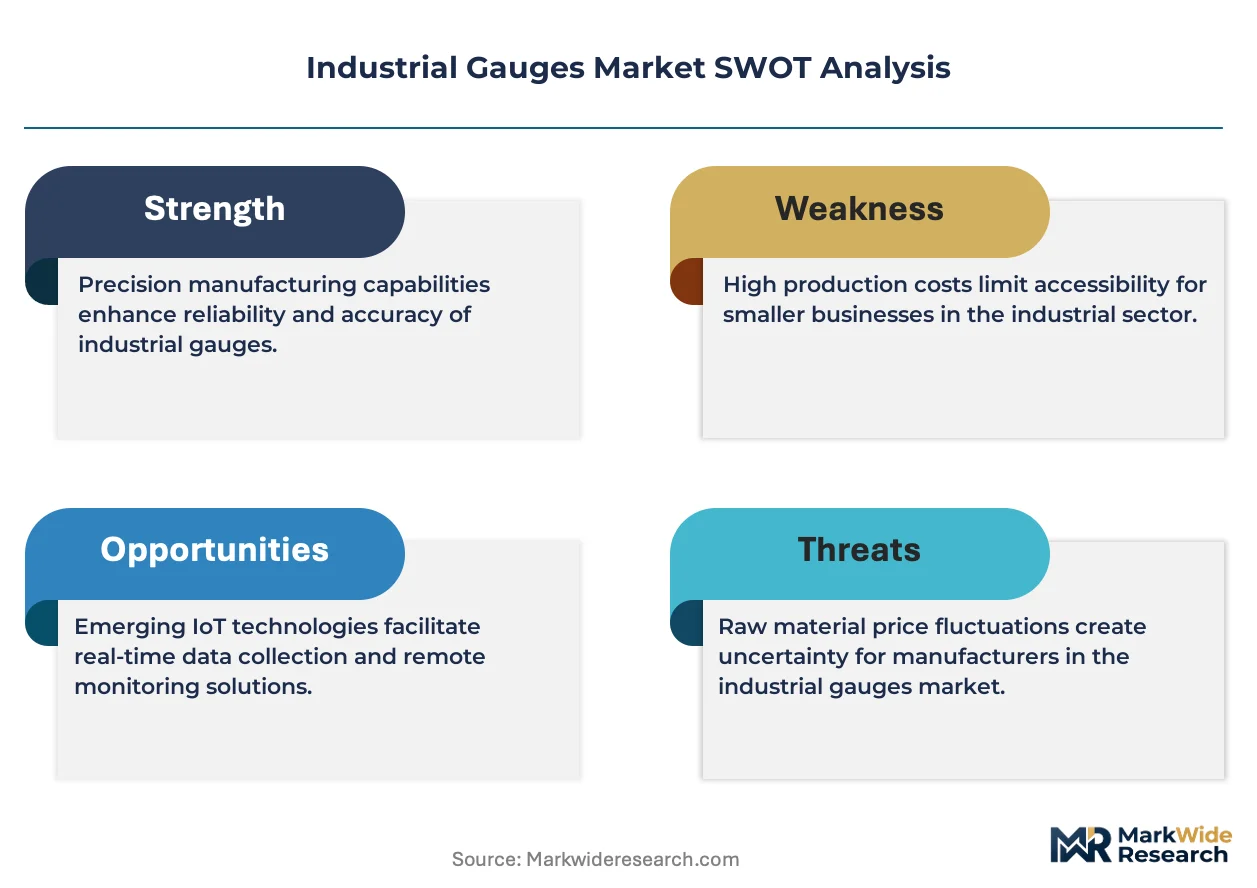
- Stainless Steel Input Volatility:Gauge housings and wetted components face cost pressure from nickel and chromium price fluctuations that compress OEM margins.
- Intrinsic Safety Limitations:Hazardous area classifications in Zone 0 and Division 1 environments restrict electronic gauge deployment, preserving analog market share.
- Calibration Infrastructure Concentration:Accredited laboratories capable of 0.1% accuracy certification cluster in Germany, the United States, and Japan, creating geographic bottlenecks.
Strategic Opportunities
- India Process Industries:BIS certification requirements and expanding chemical manufacturing create demand for pressure equipment compliant with the EU Pressure Equipment Directive.
- Cybersecurity Certification:NIST and IEC industrial IoT security guidelines will reshape procurement specifications, favoring vendors with pre-certified connected gauge platforms.
- Pharmaceutical Cold Chain:FDA 21 CFR Part 211 calibration protocols extend to biologics storage and transport, opening gauge applications beyond fixed installations.
Industry Challenges
- Fieldbus Integration Complexity:Smart gauges must interoperate with legacy 4-20 mA loops and emerging Ethernet-APL networks, demanding dual-protocol engineering.
- Metrology Talent Scarcity:Qualified technicians capable of deadweight tester verification and traceable calibration chain documentation are aging out of the workforce faster than training programs replace them.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Gauges Market |
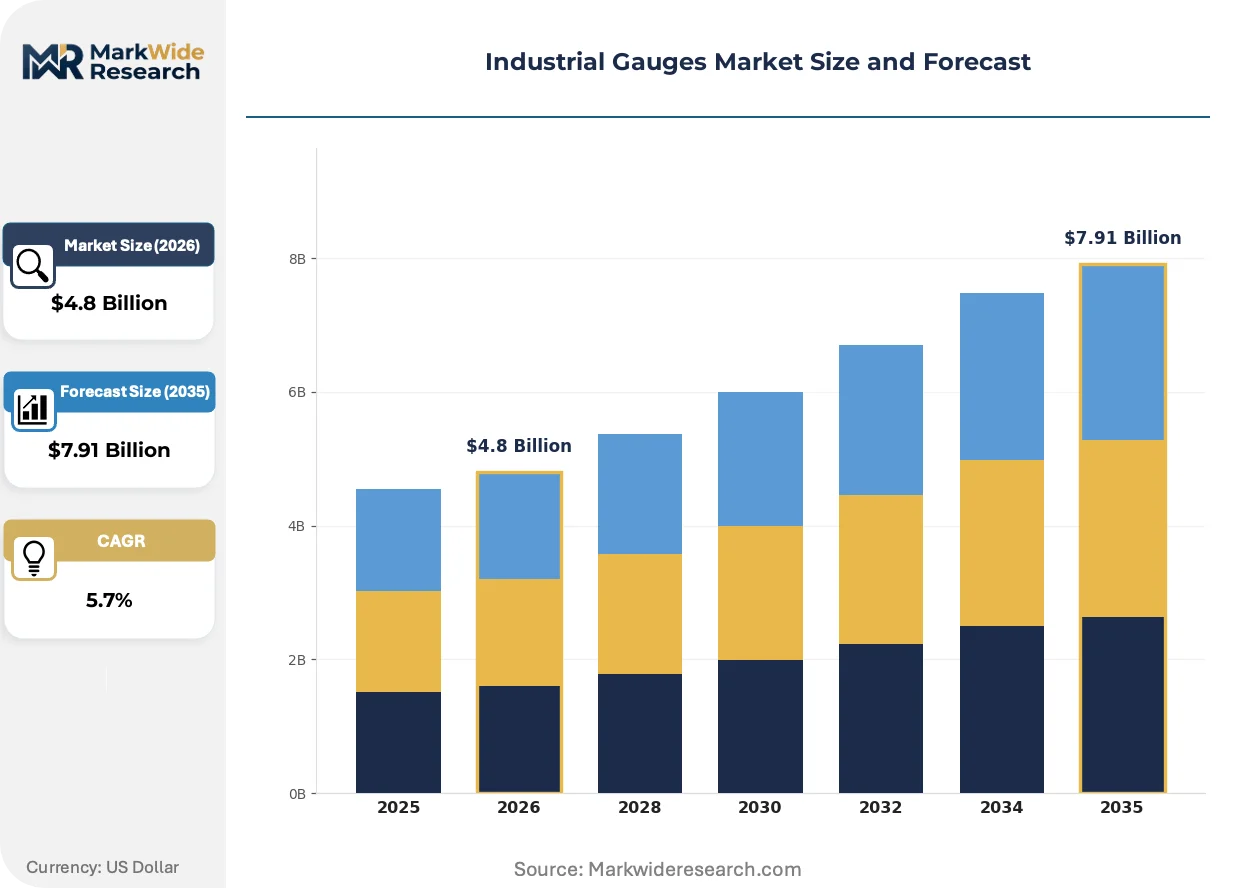
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Gauges, Temperature Gauges, Level Gauges, Flow Meters End User: Manufacturing, Oil & Gas, Water Treatment, Chemicals Technology: Analog, Digital, Smart, Wireless Installation: Fixed, Portable, In-line, Panel Mount |
| Companies Covered | WIKA Alexander Wiegand SE & Co. KG, Honeywell International Inc., Emerson Electric Co., AMETEK Inc., Ashcroft Inc., Winters Instruments, Crane Company, Meggitt PLC, Dwyer Instruments Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Gauges Market Shifts & Advancements
Silicon MEMS pressure sensors are collapsing the cost-performance threshold that previously separated industrial-grade gauges from precision instrumentation. Three distinct vectors are compressing product lifecycles and rewiring competitive advantage.
MEMS-based pressure transducers is collapsing the traditional hierarchy between utility gauges and test-grade instrumentation. Chemical processors in the Gulf Coast region are adopting these solid-state devices at accelerating rates for non-safety-critical monitoring points. The technology is collapsing maintenance budgets by eliminating mechanical wear components and enabling decade-long calibration intervals.
REACH substance restrictions on mercury and cadmium are forcing gauge manufacturers to reformulate bourdon tube alloys and dial face coatings. The regulation is accelerating conversion to dry case designs and bimetallic temperature compensation elements. European chemical complexes face the most immediate compliance deadlines, with 2026 phase-out targets already written into procurement specifications.
Integrated service contracts are displacing transactional gauge sales as buyers seek to outsource calibration, recertification, and failure replacement. EPC firms executing lump-sum turnkey projects are bundling instrumentation into 10-year lifecycle agreements. This pattern is most visible in Middle Eastern petrochemical developments where owner-operators prioritize operational expenditure predictability over capital cost minimization.
Industrial Gauges Market Segmentation
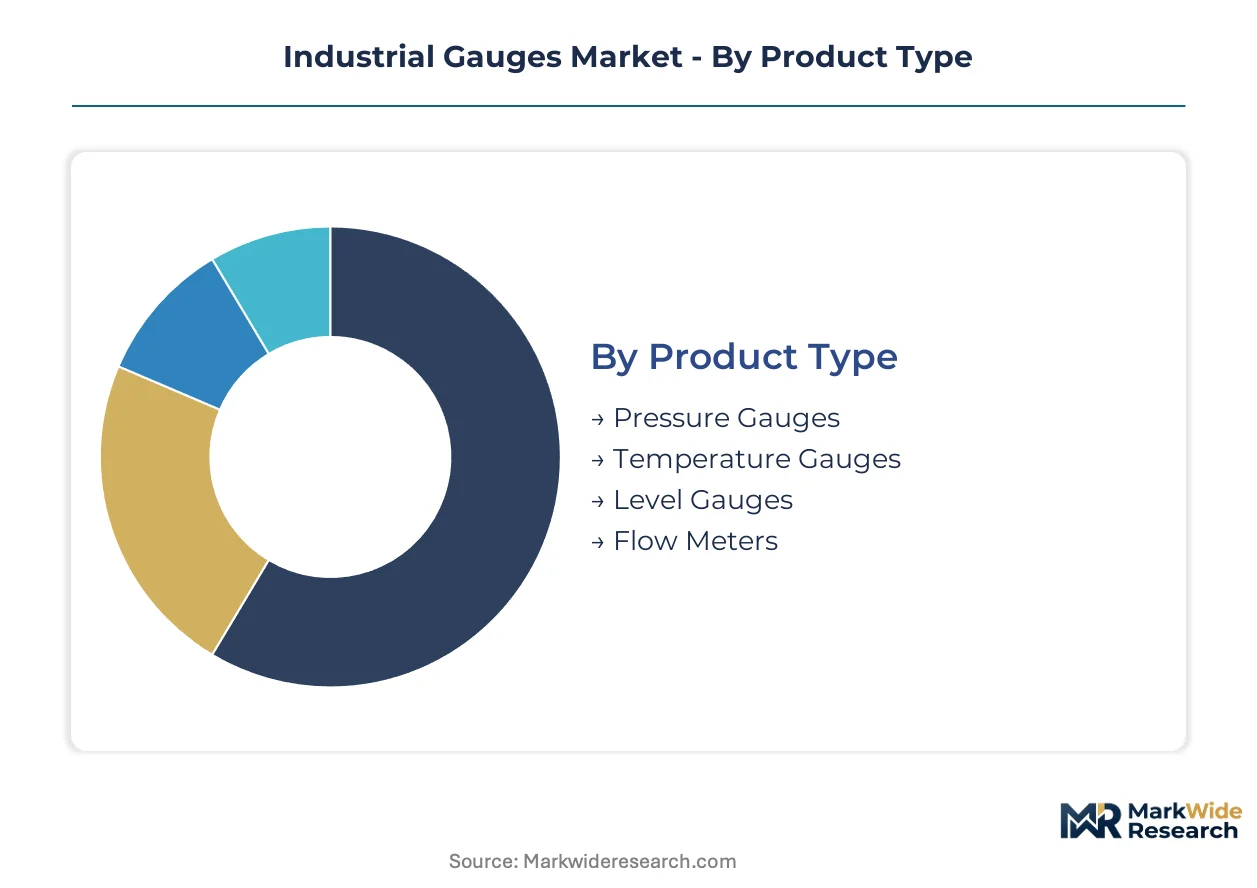
Industrial gauge procurement patterns diverge sharply across product architectures and deployment contexts. Calibration frequency, replacement cycles, and service contract structures vary by segment, creating distinct aftermarket revenue profiles that reshape vendor priorities.
Product Type:
After-sales service intensity peaks with pressure gauges due to mandatory recertification intervals in safety-critical applications, while temperature and level instruments follow extended maintenance schedules.
- Pressure Gauges:Bourdon tube, diaphragm, and capsule constructions measure fluid and gas pressure across 0-100,000 psi ranges. Gulf Coast refineries in Texas and Louisiana are expanding deployments for hydrocracker and reformer units under EPA emissions tracking mandates.
- Temperature Gauges:Bimetallic, gas-actuated, and thermocouple-based designs monitor process heat from -200°C to 1,700°C. Chemical processors in Oklahoma are retrofitting fixed thermowells with smart transmitters for predictive maintenance integration.
- Level Gauges:Sight glass, magnetic, and radar technologies track tank inventories. Water treatment facilities favor these for clarifier and digester monitoring.
- Flow Meters:Differential pressure, electromagnetic, and ultrasonic variants measure volumetric throughput. Oil and gas gathering systems deploy these at custody transfer points.
By volume, pressure gauges lead. By growth pace, smart-enabled pressure instrumentation is climbing the fastest.
End User:
Cost tier stratification separates capital-intensive process industries from maintenance-budget-driven utilities, with procurement authority residing in engineering departments versus operations teams.
- Manufacturing:Automotive stamping plants and food processing lines deploy gauges for compressed air systems and CIP circuits. Michigan and Ohio assembly plants are standardizing on digital pressure transmitters for IIoT connectivity.
- Oil & Gas:Upstream production, midstream pipelines, and downstream refining require SIL-rated instrumentation for safety instrumented systems. Permian Basin operators are replacing mechanical gauges with wireless transmitters for wellhead monitoring.
- Water Treatment:Municipal plants and industrial wastewater facilities use level and pressure devices for pump control and filtration monitoring. California utilities face procurement pressure from state drought resilience bonds.
- Chemicals:Specialty and commodity chemical producers demand corrosion-resistant wetted materials for aggressive process media. Louisiana petrochemical corridors are accelerating instrument procurement for ethylene cracker expansions.
By installed base, manufacturing dominates. By replacement velocity, oil and gas is expanding most quickly.
Technology:
Customer type bifurcation separates asset owners pursuing digital transformation from operators in hazardous zones where intrinsic safety limits electronic deployment.
- Analog:Mechanical dial indicators with 2-3% accuracy ratings persist in Division 1 hazardous areas and budget-constrained maintenance programs. These devices require no external power and withstand electrical isolation failures.
- Digital:Electronic displays with 0.25% accuracy and local data logging bridge legacy 4-20 mA infrastructure. These units are gaining share in pharmaceutical cleanrooms where FDA 21 CFR Part 211 documentation is mandatory.
- Smart:Microprocessor-based devices with HART or Foundation Fieldbus protocols enable remote configuration and diagnostics. Gulf Coast refineries are prioritizing these for OSHA process safety management compliance.
- Wireless:Battery-powered ISA100 or WirelessHART transmitters eliminate conduit costs in remote monitoring applications. These are penetrating tank farms and distributed well pads where wiring economics are prohibitive.
By shipment volume, analog retains plurality share. By technology transition rate, wireless architectures are gaining share fastest.
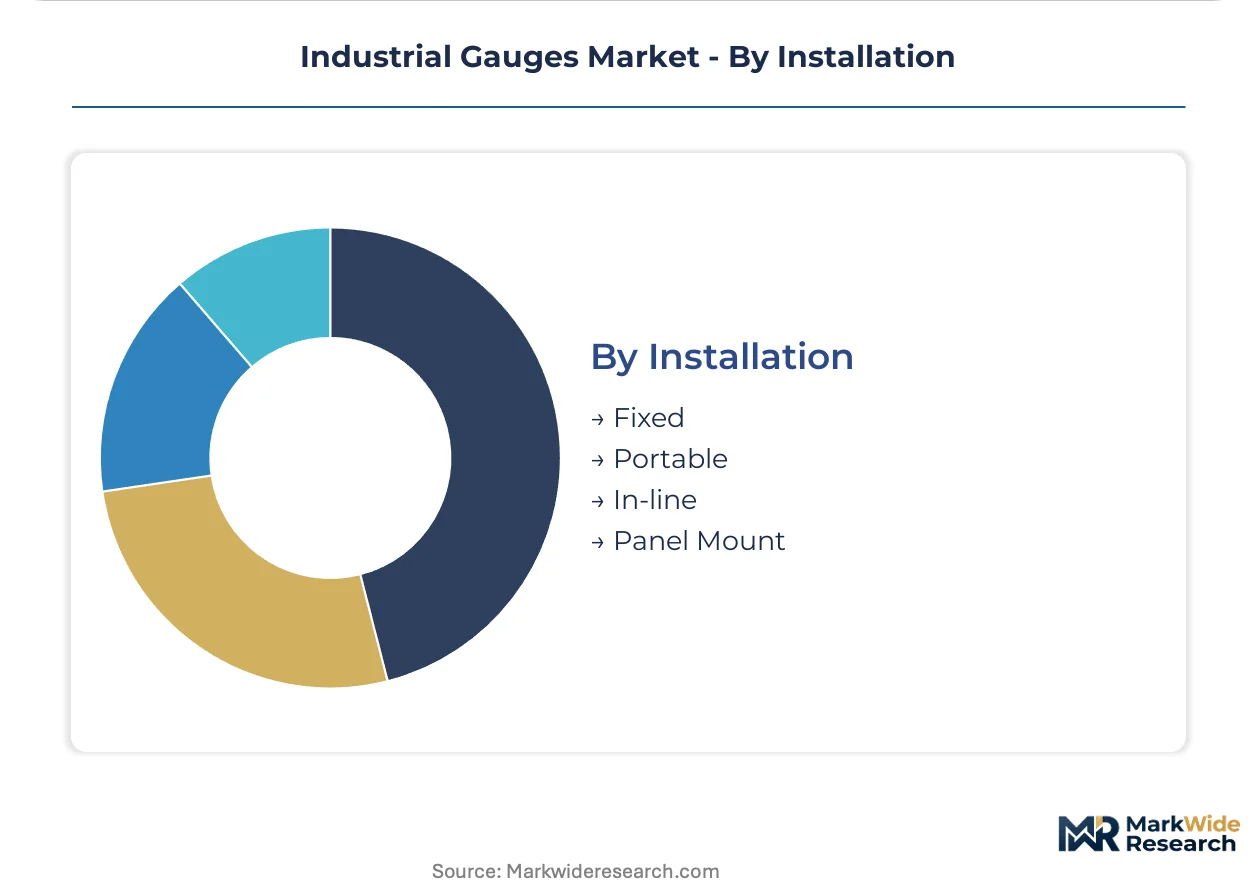
Installation:
Margin structure varies with engineering intensity, as panel mount and in-line configurations demand custom fabrication while portable units standardize.
- Fixed:Permanent threaded or flanged connections serve continuous process monitoring. These installations dominate refinery and chemical plant specifications.
- Portable:Handheld calibrators and test gauges travel between measurement points for verification and troubleshooting. These support metrology talent scarcity in field service organizations.
- In-line:Spool piece and insertion designs integrate directly into piping systems without bypass loops. Water treatment plants favor these for pump suction and discharge monitoring.
- Panel Mount:Square or round bezel configurations fit control cabinet cutouts for centralized operator visibility. OEM panel builders specify these for skid-mounted process equipment.
By unit economics, fixed installations dominate revenue. By flexibility premium, portable configurations command the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions mandates and OSHA process safety requirements are accelerating gauge procurement across industrial clusters, with regulatory pressure concentrating demand in petrochemical corridors and manufacturing belts.
United States
Gulf Coast refineries in Texas and Louisiana are expanding digital gauge deployments for hydrocracker and reformer units under EPA emissions tracking mandates. OSHA process safety management standards compel calibrated instrumentation for facilities handling regulated substances above threshold quantities. The Permian Basin is replacing mechanical gauges with wireless transmitters for wellhead monitoring.
Germany
European chemical complexes face immediate REACH compliance deadlines for mercury and cadmium phase-outs in bourdon tube alloys and dial face coatings. The EU Pressure Equipment Directive establishes conformity requirements for gauges installed on categorized pressure systems. Bavarian industrial zones are standardizing on dry case designs and bimetallic temperature compensation elements.
India
BIS certification requirements and expanding chemical manufacturing are creating demand for pressure equipment compliant with international standards. The country's national industrial regulator enforces calibration protocols for process industries. Gujarat and Maharashtra chemical corridors are accelerating instrument procurement for specialty and commodity chemical production.
Japan
METI industrial standards and JIS certification requirements maintain strict accuracy thresholds for precision instrumentation in automotive and electronics manufacturing. The country's national manufacturing regulator oversees gauge calibration chains for export-oriented production. Chubu and Kansai industrial belts are adopting MEMS-based pressure transducers for non-safety-critical monitoring points.
China
GB standards and MIIT industrial IoT guidelines are reshaping procurement specifications for connected gauge platforms in state-owned petrochemical facilities. The country's national environmental regulator is tightening emissions monitoring requirements for process industries. Yangtze River Delta chemical processors are retrofitting fixed installations with smart transmitters for predictive maintenance integration.
Industrial Gauges Market Competitive Landscape
On the supply side, the industry is consolidating around German precision manufacturers, diversified industrial conglomerates, and specialized instrumentation firms. Three strategic archetypes dominate: European specialists leveraging manufacturing scale for high-precision supply, North American diversified players bundling digital platforms with control systems, and mid-tier regional fabricators serving cost-sensitive maintenance programs. Competitive moves center on integrated service contract expansion and cybersecurity certification acquisition for connected gauge platforms.
Among German-based precision manufacturers, WIKA Alexander Wiegand SE & Co. KG exemplifies the European specialist archetype through its manufacturing scale position. Honeywell International Inc. and Emerson Electric Co. represent the diversified North American tier, anchoring bundled digital offerings and smart platform ecosystems respectively. These three firms occupy positions that reflect the market's bifurcation between precision-engineered components and integrated digital infrastructure.
| Leading Market Players |
|---|
| WIKA Alexander Wiegand SE & Co. KG |
| Honeywell International Inc. |
| Emerson Electric Co. |
| AMETEK Inc. |
| Ashcroft Inc. |
| Winters Instruments |
| Crane Company |
| Meggitt PLC |
| Dwyer Instruments Inc. |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp barge freight corridors transmit nickel and chromium price volatility from European ports directly into gauge housing cost structures, compressing OEM margins while amplifying price spreads between certified and uncertified instrument tiers across downstream procurement channels.
Pricing Analysis
Certification level creates the primary spread between premium and economy gauge tiers, with FDA-grade and SIL-rated instruments commanding substantial premiums over general-purpose utility gauges. Three-tier pricing structure across premium, standard, and economy levels segments buyers by application criticality and regulatory exposure. Cost compression in standard-tier analog gauges is intensifying because MEMS-based pressure transducers eliminate mechanical wear components and extend calibration intervals. Maintenance-budget-driven utilities exhibit highest price sensitivity, while safety-critical oil and gas operators prioritize certification grade over unit cost.
Supply Chain Analysis
Stainless steel feedstock markets in Germany, Japan, and the United States anchor precision gauge manufacturing, with bourdon tube alloys and specialized wetted components drawing from metallurgical suppliers in these jurisdictions. Nickel, chromium, and specialty alloy dependencies create vulnerability to commodity price swings and REACH substance restriction compliance costs. Single-source vulnerability concentrates in accredited calibration laboratories clustering in Germany, the United States, and Japan. Distribution runs through direct OEM partnerships and integrated service contracts that displace transactional sales in large capital projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA emissions mandates and OSHA process safety requirements are triggering instrument replacement cycles that favor vendors with pre-certified digital platforms, creating a regulatory inflection that rewards cybersecurity-ready connected gauge architectures over legacy analog supply.
For Market Incumbents: Entrench platform control by bundling smart gauge offerings with predictive maintenance software and decade-long service contracts that lock out substitute technologies. Deepen backward integration into MEMS sensor fabrication to capture margin erosion from silicon-based displacement of mechanical gauges. Prioritize IEC 62443 cybersecurity certification investment ahead of NIST guideline finalization to preempt procurement specification shifts.
For New Entrants and Emerging Players: Pursue white-space expansion in pharmaceutical cold chain applications where FDA 21 CFR Part 211 calibration protocols extend gauge demand beyond fixed installations into biologics transport monitoring. Target India's BIS certification-driven chemical corridor growth with EU Pressure Equipment Directive-compliant pressure equipment. Differentiate through wireless ISA100 transmitter specialization for tank farm and distributed well pad applications where wiring economics favor battery-powered architectures.
For Investors and Strategic Acquirers: German precision manufacturers with captive metallurgical processing and established calibration laboratory networks present the strongest acquisition target archetype for platform consolidation plays. Long-term viability hinges on service contract revenue predictability rather than transactional hardware margins. Watch for NIST industrial IoT security guideline publication as the inflection signal that will reshape procurement specifications and certification requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | NIST and IEC guideline compliance creates procurement specification barriers for uncertified competitors. |
| Integrated Service Contract Expansion | Ten-year lifecycle agreements with Middle Eastern petrochemical developers convert capital sales into recurring revenue streams. |
| MEMS Sensor Backward Integration | In-house silicon pressure transducer production eliminates mechanical component costs and extends calibration intervals. |
| Pharmaceutical Cold Chain Extension | FDA 21 CFR Part 211 protocols open gauge applications in biologics storage and transport beyond fixed installations. |
| India Market Certification Entry | BIS requirements and expanding chemical manufacturing create demand for EU Pressure Equipment Directive-compliant pressure equipment. |
Research Methodology
Cross-validation between plant engineer interviews and SEC instrument manufacturer filings anchors the qualitative findings in operational reality and financial disclosure. Primary research incorporated maintenance directors at Gulf Coast refineries, OEM procurement teams at chemical equipment fabricators, aftermarket service heads at distributor networks, and technical R&D directors at sensor manufacturers. Secondary validation drew from EPA enforcement databases, OSHA process safety incident reports, customs trade data for stainless steel instrument imports, and EU Pressure Equipment Directive conformity assessment records. Bottom-up gauge shipment analysis triangulated against top-down petrochemical capital expenditure tracking.
Calibration against historical replacement cycles and regulatory compliance deadlines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, end-use industry, technology tier, and regional regulatory cluster. CAGRs were derived from instrument procurement cycle analysis tied to capacity expansion timelines and emissions mandate phase-in schedules. Forecast inputs incorporated MEMS cost-performance trajectory curves and REACH substance restriction compliance cost assumptions.
Macroeconomic conditions sit as an overlay; deviation in nickel and chromium commodity prices, freight corridor cost structures, or petrochemical capital expenditure cycles would shift the trajectory. Forecasts reflect assumptions about regulatory enforcement intensity and technology substitution rates. Cross-checking against EPC firm lump-sum turnkey project announcements and owner-operator maintenance budget disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
South Korea Smart Home Market
Others
South Korea Intellectual Property Market
Others
Smart Home and Office Market
Others
Global Pregnancy Tracker Apps Market
Others
Chip Card Scanners Market
Others
Global Telemetry Market
Others
Ambient Assisted Living and Smart Home Market
Others
Cloud Digital Video Recorder Market
Others
Mobile Edge Computing Market
Others
Rotary Evaporators Market
Others
Industrial Personal Computer Market
Others
Asia-Pacific Professional Scalp Treatment Products Market
Others
Global Geotechnical Instrumentation and Monitoring Market
Others
Versatile Video Coding Market
Others
Durian Fruit Market
Others
Europe Military 4D Printing Market