
 Malta POS Terminal Market | 2026-2036
Malta POS Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
Malta POS Terminal Market Foresight
Capability gaps in hardware customization and software integration are reorganizing competitive dynamics among Malta's POS terminal suppliers. Verifone leverages its established European manufacturing footprint to sustain pricing power across fixed and mobile terminal categories. Trust Payments Ltd anchors its position through deep integration with local merchant acquirers and hospitality-focused software stacks. ZeroBubble mt competes by specializing in compact, connectivity-optimized devices tailored to Malta's dense urban retail environments.
A POS terminal constitutes an electronic payment device incorporating secure encryption modules, EMV chip readers, and near-field communication antennas to process card-based and digital wallet transactions at the point of sale. These systems employ PCI-DSS certified architectures to authenticate payment credentials and transmit encrypted data to banking networks, serving retail, hospitality, and service-sector merchants requiring in-person transaction acceptance. Mobile POS and contactless payment methods represent the fastest-expanding categories as Maltese merchants prioritize countertop flexibility and tap-to-pay speed over legacy mag-stripe hardware. Fixed POS deployments retain margin concentration in high-volume supermarket and fuel-station chains where durability and integrated peripheral support justify premium positioning.
Malta's Financial Intelligence Analysis Unit enforces anti-money laundering protocols that shape terminal transaction monitoring requirements, while EU Payment Services Directive 2 mandates strong customer authentication standards for electronic payments processed through local devices. The Malta Communications Authority governs telecommunications certification for wireless-enabled terminals, ensuring radio spectrum compliance across Bluetooth and WiFi connectivity modules. Stakeholders must monitor evolving EU digital identity frameworks and their interoperability demands on next-generation payment infrastructure.
Market Dynamics
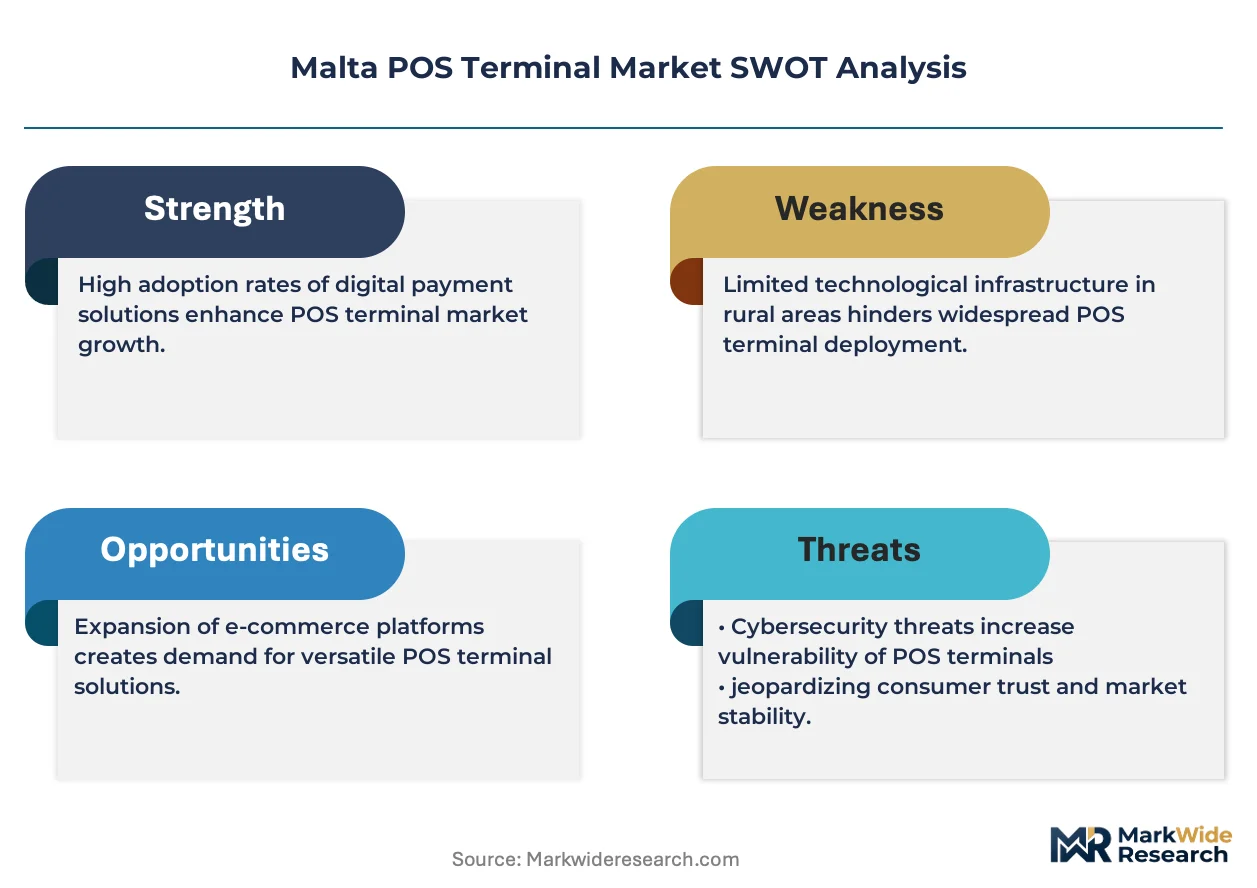
EU Payment Services Directive 2 mandates strong customer authentication standards that force Maltese merchants to replace legacy mag-stripe hardware with EMV-compliant terminals, compressing replacement cycles and reshaping supplier relationships across the archipelago.
Growth Catalysts
- Contactless infrastructure mandates:Malta's Financial Intelligence Analysis Unit enforces transaction monitoring protocols that accelerate terminal upgrades in hospitality and retail corridors.
- Tourism payment digitization:Valletta's hotel and restaurant operators expand tap-to-pay acceptance to capture international visitor spending.
- EU digital identity frameworks:Interoperability requirements for next-generation payment infrastructure drive merchant investment in certified terminal architectures.
Market Restraints
- Hardware import dependency:Malta lacks domestic terminal manufacturing, creating exposure to Eurozone supply chain disruptions and currency fluctuations.
- Small merchant base:The island's limited population of 500,000 constrains addressable market scale for high-volume terminal deployments.
- Legacy system lock-in:Established relationships between merchants and incumbent acquirers slow switching to alternative terminal providers.
Strategic Opportunities
- Gozo island expansion:Underpenetrated retail and hospitality sectors on Malta's sister island present first-mover advantages for mobile POS providers.
- SoftPOS software adoption:Smartphone-based payment acceptance eliminates hardware costs for micro-merchants in dense urban zones.
- Integrated hospitality stacks:Convergence of payment terminals with property management and kitchen display systems creates bundled service opportunities.
Industry Challenges
- PCI-DSS certification timelines:Extended security audit periods delay product launches and compress vendor revenue recognition windows.
- Radio spectrum compliance:Malta Communications Authority certification requirements for Bluetooth and WiFi modules add technical validation layers.
- Merchant acquirer consolidation:Reduced number of payment processors limits terminal distribution channel options for hardware vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malta POS Terminal Market |
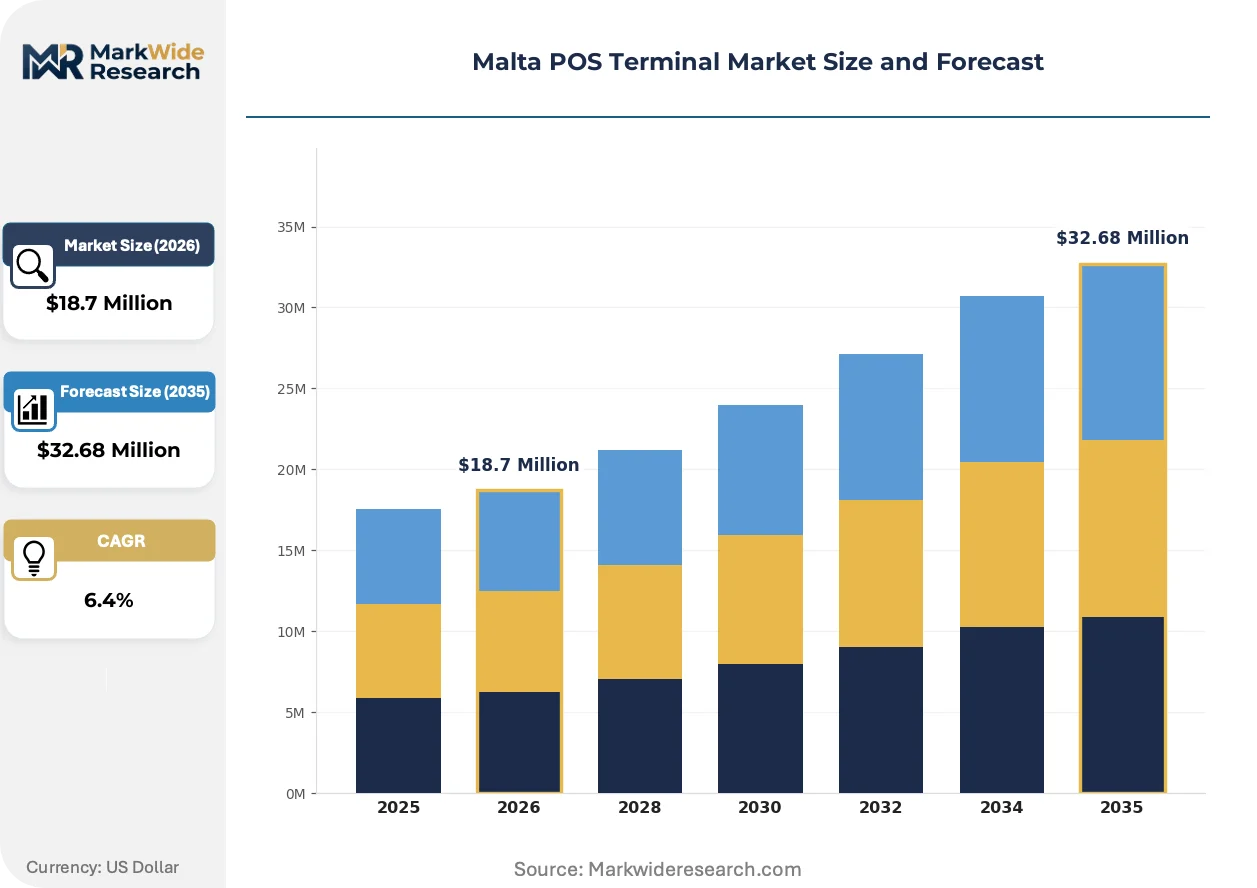
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $32.68 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed POS, Mobile POS, Cloud-Based POS, Hybrid POS Payment Method: Credit Card, Debit Card, Contactless, Mobile Wallet End User: Retailers, Restaurants, Service Providers, E-commerce Deployment: On-Premise, Cloud, Hybrid, SaaS |
| Companies Covered | Verifone, Truevo Payments Ltd, Trust Payments Ltd, ZeroBubble mt, Computer Hardware Design LTD (chdmalta), Ingenico, Nayax, Scope Solutions, Worldline, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malta POS Terminal Market Shifts & Advancements
Malta's POS terminal landscape is restructuring around three converging forces: hardware miniaturization, regulatory authentication mandates, and merchant demand for unified commerce platforms that collapse payment acceptance into broader business operations.
Android-based open-platform terminals are decomposing the traditional closed-loop payment hardware model. Valletta's mid-size restaurant chains adopt these devices at accelerated pace to run third-party applications alongside payment processing. This flexibility is compressing margins for proprietary operating system vendors while enabling software-defined feature differentiation.
EU Payment Services Directive 2 strong customer authentication rules reshape transaction flows across Maltese retail. The regulation forces multi-factor verification for electronic payments above defined thresholds. High-volume supermarket chains respond by deploying biometric-enabled terminals that streamline checkout while maintaining compliance.
Merchant purchasing behavior shifts toward integrated hardware-software subscriptions. Small hospitality operators in Sliema and St. Julian's abandon upfront terminal purchases for monthly service bundles including payment processing, analytics, and technical support. This transformation concentrates vendor relationships around full-stack providers with local service capabilities.
Malta POS Terminal Market Segmentation
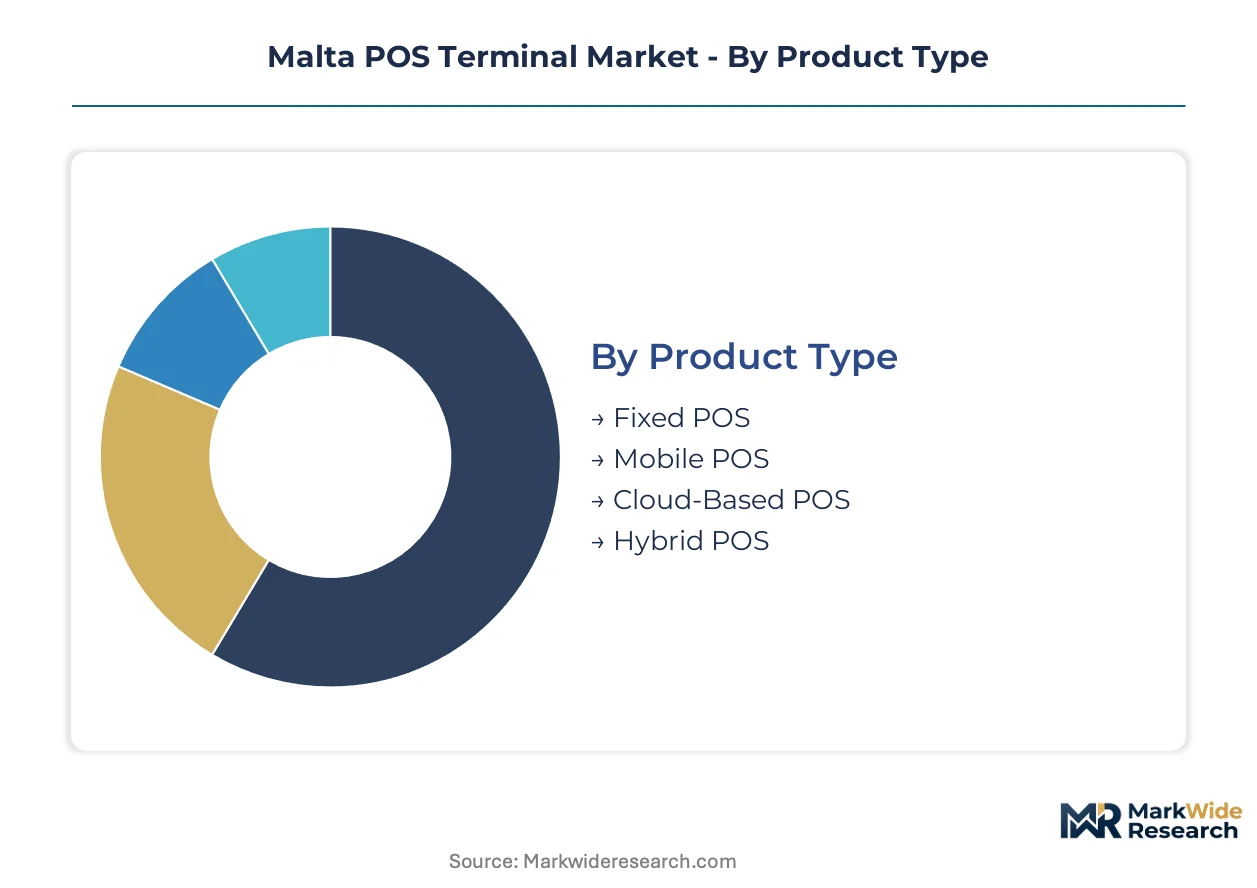
Malta's POS terminal market fragments across hardware form factors, payment modalities, merchant verticals, and infrastructure delivery models. Each segmentation dimension carries distinct channel economics and regulatory implications that shape supplier positioning across the archipelago's concentrated retail and hospitality corridors.
Product Type:
Fixed POS terminals flow through established acquirer relationships with supermarket and fuel station chains, while mobile and cloud variants reach hospitality operators through software-integrated channels.
- Fixed POS:Countertop devices with integrated receipt printers, cash drawers, and peripheral connectivity serve high-volume merchants requiring durability and multi-lane checkout support. Malta's supermarket chains and fuel stations anchor demand for these units, driven by throughput requirements and peripheral integration needs that justify premium hardware investment.
- Mobile POS:Battery-powered terminals with Bluetooth and cellular connectivity enable tableside and curbside payment acceptance. Valletta's restaurant operators and Sliema's boutique retailers are expanding deployments fastest, pressured by EU Payment Services Directive 2 mandates for EMV-compliant contactless infrastructure and visitor expectations for tap-to-pay convenience.
- Cloud-Based POS:Browser-accessible systems with minimal local hardware requirements reduce upfront capital burdens for micro-merchants.
- Hybrid POS:Dual-mode devices switch between local processing and cloud dependency based on connectivity availability.
Fixed POS dominates installed base. Mobile POS is where expansion concentrates.
Payment Method:
Merchant acquisition strategies diverge sharply by payment rail, with contactless and mobile wallet segments commanding premium processing rates and accelerated terminal refresh cycles.
- Credit Card:EMV chip and mag-stripe processing remains the foundational transaction type across Maltese retail, though mag-stripe acceptance is phasing out under regulatory pressure. High-ticket hospitality merchants in St. Julian's retain credit card focus due to international visitor spending patterns and chargeback protection requirements.
- Debit Card:PIN-authenticated domestic transactions concentrate in grocery and everyday retail where Maltese consumers prefer direct account deduction. Local banks' merchant acquiring arms prioritize debit routing for interchange revenue capture.
- Contactless:NFC-enabled tap-to-pay transactions are climbing the fastest trajectory across all merchant categories, driven by Malta's Financial Intelligence Analysis Unit transaction monitoring protocols and visitor economy demands.
- Mobile Wallet:Apple Pay, Google Pay, and Samsung Pay acceptance requires NFC-capable terminal infrastructure that legacy hardware lacks.
Credit and debit card acceptance saturates installed base. Contactless is climbing the fastest trajectory.
End User:
Vertical-specific software integration requirements channel terminal distribution through specialized value-added resellers and direct hospitality technology providers.
- Retailers:Inventory-linked POS systems with barcode scanning and loyalty program integration serve Malta's compact but dense urban retail zones. Supermarket chains and fashion boutiques in Valletta and Sliema drive demand for high-throughput fixed terminals with integrated peripheral support.
- Restaurants:Table management, kitchen display system, and payment convergence creates bundled procurement decisions. Full-service operators across Malta's tourism corridors prioritize mobile POS flexibility for split-check and tip-adjustment workflows.
- Service Providers:Appointment-based businesses require lightweight, appointment-integrated payment acceptance.
- E-commerce:Omnichannel merchants need unified online and in-person payment reconciliation.
Retailers anchor hardware volume. Restaurants are gaining share fastest.
Deployment:
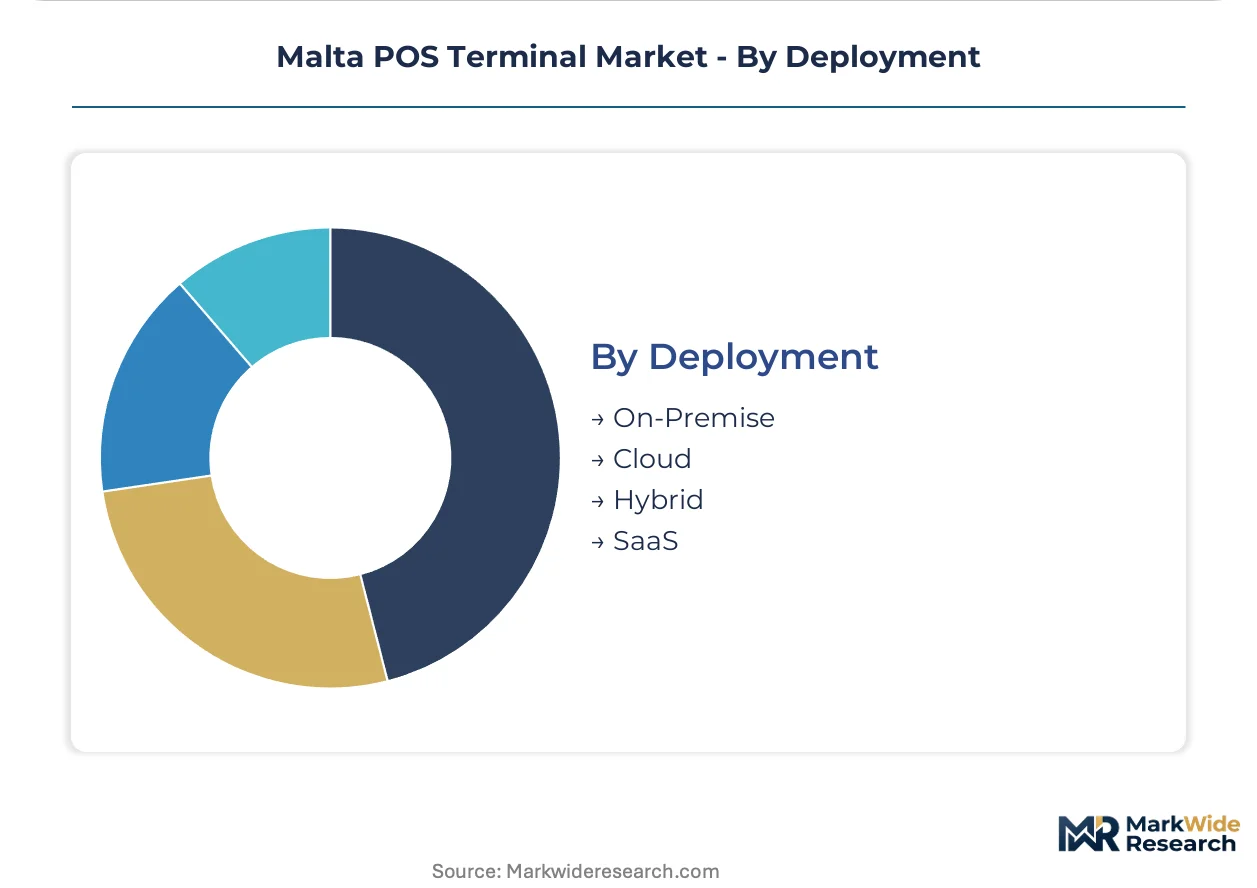
Infrastructure delivery models stratify by merchant technical sophistication and capital constraints, with SaaS and hybrid approaches displacing traditional on-premise ownership.
- On-Premise:Self-managed server infrastructure with perpetual software licenses persists among larger supermarket chains with dedicated IT staff. These merchants prioritize data sovereignty and customization depth over operational simplicity.
- Cloud:Fully hosted systems with browser-based management consoles eliminate local server maintenance. Small hospitality operators across Malta's islands are migrating fastest, attracted by predictable monthly costs and automatic security updates.
- Hybrid:Local transaction processing with cloud backup and analytics balances resilience with accessibility.
- SaaS:Subscription-bundled hardware, software, and payment processing consolidates vendor relationships.
On-premise retains legacy installed base. Cloud is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maltese merchants exhibit sharp demand elasticity variation, with Valletta's high-volume hospitality operators least sensitive to terminal pricing while Gozo's micro-retailers delay upgrades over hardware costs.
Valletta Capital District
Heritage tourism and cruise passenger volumes drive contactless terminal density in UNESCO-protected retail corridors. Malta's Financial Intelligence Analysis Unit transaction monitoring protocols compel merchant compliance upgrades. Independent boutiques along Republic Street cluster around integrated hospitality POS bundles.
Sliema-St. Julian's Conurbation
Upscale restaurant chains and marina-facing retailers prioritize mobile POS flexibility for tableside payment workflows. EU Payment Services Directive 2 strong customer authentication mandates accelerate EMV terminal replacement cycles. Waterfront establishments in Spinola Bay lead tap-to-pay infrastructure deployment.
Gozo Island
Underpenetrated retail and hospitality sectors present first-mover opportunities for low-cost mobile terminal providers. The Malta Communications Authority extends radio spectrum certification requirements to wireless-enabled devices across the sister island. Victoria's central retail zone sees emerging demand from artisan producers and agritourism operators.
Malta International Airport Zone
Duty-free retail and car rental counters require high-throughput fixed terminals with multi-currency support. Central Bank of Malta oversight ensures payment system stability for tourist-facing merchants. Luqa's logistics and distribution facilities anchor terminal supply chain staging.
Malta POS Terminal Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Malta's POS terminal supply structure. Verifone and Ingenico leverage pan-European manufacturing scale to dominate fixed terminal categories through established acquirer relationships. Trust Payments Ltd and Truevo Payments Ltd anchor the integrated tier with deep local merchant banking ties. Specialist competitors including ZeroBubble mt and Scope Solutions compete on connectivity-optimized form factors and hospitality software convergence. Consolidation pressure concentrates around integrated hardware-software subscription models, while geographic expansion into Gozo emerges as a secondary competitive vector.
Among Malta-anchored service providers, Trust Payments Ltd exemplifies the acquirer-integrated archetype through embedded relationships with local hospitality software stacks. ZeroBubble mt occupies a position within the compact-device specialist tier, targeting dense urban retail environments with connectivity-optimized hardware. Verifone represents the scale-driven multinational archetype, sustaining pricing power through European manufacturing proximity and established certification pathways. These three anchors illustrate the competitive tension between global manufacturing scale and local service integration that defines procurement decisions across the archipelago's merchant base.
| Leading Market Players |
|---|
| Verifone |
| Truevo Payments Ltd |
| Trust Payments Ltd |
| ZeroBubble mt |
| Computer Hardware Design LTD (chdmalta) |
| Ingenico |
| Nayax |
| Scope Solutions |
| Worldline |
| Others |
Supply & Pricing Matrix
Long-term service contracts with embedded terminal refresh clauses lock in supply access for Maltese acquirers while anchoring price visibility across multi-year payment infrastructure deployments. These arrangements concentrate procurement leverage among integrated hardware-software providers serving Valletta's hospitality corridors and Sliema's retail zones.
Pricing Analysis
After-sales service revenue tiers including technical support subscriptions and extended warranty bundles drive lifetime value for terminal vendors competing across Malta's concentrated merchant base. Three-tier pricing structure across premium, standard, and economy levels stratifies by EMV certification grade and peripheral integration depth. Cost compression in economy-tier hardware is intensifying because Eurozone supply chain disruptions squeeze import margins. Micro-merchants in Gozo exhibit highest price sensitivity, while Valletta's hotel chains prioritize reliability over unit cost.
Supply Chain Analysis
China and Taiwan anchor printed circuit board and secure element manufacturing for Maltese-bound POS terminals. European assembly facilities in Germany and Poland handle final device configuration and PCI-DSS certification staging. Semiconductor shortages in NFC controller chips create single-source vulnerability for contactless-enabled models. Distribution runs through Malta's merchant acquirer networks and hospitality technology resellers rather than direct vendor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malta's POS terminal market is entering a cyclical recovery phase driven by EU Payment Services Directive 2 compliance deadlines forcing terminal replacement waves across the archipelago's merchant base.
For Market Incumbents: Shield installed base relationships by embedding terminal hardware within integrated hospitality software stacks that raise switching costs for Valletta's restaurant operators. Deepen backward integration into cloud-based management platforms to capture recurring revenue streams. Counter SoftPOS substitution threats by emphasizing PCI-DSS certified security architectures that smartphone-based alternatives cannot replicate. For New Entrants and Emerging Players: Gozo island's underpenetrated retail and agritourism sectors present white-space opportunities where incumbent coverage remains thin. Mobile-first terminal form factors with simplified onboarding workflows address micro-merchant price sensitivity in Victoria's central retail zone. Partner with local software developers specializing in property management and kitchen display system integration to bypass established acquirer channel control. For Investors and Strategic Acquirers: Acquirer-integrated service providers with embedded local banking relationships represent the most defensible acquisition archetype in Malta's concentrated market structure. Monitor EU digital identity framework implementation timelines as inflection indicators for next-generation payment infrastructure investment cycles. Long-term viability hinges on vendor ability to consolidate hardware, software, and processing relationships into unified subscription offerings.| Strategic Initiative | Industry Significance |
|---|---|
| SoftPOS Platform Launch | Smartphone-based acceptance eliminates hardware costs for Malta's micro-merchants in dense urban zones. |
| Integrated Hospitality Stack Partnership | Convergence with property management systems captures bundled procurement decisions across Valletta's hotel sector. |
| Gozo Island Geographic Expansion | First-mover positioning in underpenetrated retail corridors builds channel relationships before incumbent response. |
| Biometric Terminal Certification | EU Payment Services Directive 2 strong customer authentication compliance streamlines high-volume supermarket checkout. |
| Merchant Acquirer Strategic Alliance | Embedded relationships with Trust Payments Ltd and Truevo Payments Ltd accelerate terminal distribution access. |
Research Methodology
A spread of perspectives from merchant acquiring executives, hospitality technology integrators, PCI-DSS compliance auditors, and retail operations managers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against Malta Financial Intelligence Analysis Unit regulatory filings, EU Payment Services Directive 2 implementation guidance, Malta Communications Authority certification databases, and Central Bank of Malta payment system reports. Bottom-up terminal deployment estimates triangulated against top-down merchant base sizing.
Segmentation dimensions modeled span hardware form factor, payment modality, merchant vertical, and infrastructure delivery model across the projection horizon. CAGRs derived from installed base replacement cycles, regulatory compliance deadlines, and tourism spending recovery patterns. Analysis incorporates EMV terminal penetration rates, contactless transaction growth curves, and SoftPOS adoption thresholds as industry-specific forecast inputs.
Underlying assumptions cover sustained EU regulatory enforcement, stable Eurozone supply chain access, and continued tourism sector recovery, with deviation risk concentrated in hardware import disruption and merchant acquirer consolidation. Recalibration cycles align with material shifts in EU digital identity framework implementation and PCI-DSS certification protocol updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Asia-Pacific Payment Analytics Software Market
Payments
Singapore Remittance Market
Payments
Slovenia Point of Sale (POS) Terminal Market
Payments
Buy Now Pay Later Market
Payments
Germany Payments Market
Payments
Electronic Payment System for Transportation Market
Payments
Latin America Mobile Payment Market
Payments
Denmark Payments Market
Payments
Japan Retail Cash Management Market
Payments
Norway Mobile Payments Market
Payments
E-Commerce Payments Market
Payments
Europe Mobile Payment Market
Payments
United Kingdom Mobile Payments Market
Payments
Mobile Card Reader Market
Payments
Proximity Mobile Payment Market
Payments
Saudi Arabia POS Terminal Market