
 Europe Credit Cards Market | 2026-2036
Europe Credit Cards Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Credit Cards Market Insights
PSD2 is rebalancing the cost-of-entry calculus for new payment service providers across European card issuance. Deutsche Bank AG leverages its universal banking infrastructure to sustain dominance in corporate card programs. Visa Inc. anchors the network layer through tokenization investments that reduce fraud liability for partner banks.
A credit card constitutes a revolving payment instrument issued by licensed financial institutions, typically featuring a magnetic stripe, EMV chip, and contactless antenna enabling authentication through PIN, signature, or biometric verification at point-of-sale terminals and digital checkout interfaces. The card type dimension shows rewards products capturing disproportionate interchange revenue as affluent professionals seek cashback and travel benefits, while the payment method dimension reveals contactless as the default acceptance standard across Nordic and Benelux retail environments. Business cards within the customer segment dimension occupy a defensive margin pool as commercial spend recovery outpaces consumer discretionary trends in post-pandemic Europe.
The European Banking Authority enforces strong customer authentication thresholds that directly elevate technology spend for issuers. GDPR compliance obligations from the European Data Protection Board constrain how transaction data monetizes into ancillary revenue streams. EBA stress-testing frameworks further shape capital allocation decisions between unsecured consumer lending and secured product lines. Stakeholders must weigh open banking API investments against proprietary wallet strategies as account-to-account payments threaten traditional interchange economics.
Market Dynamics
PSD2's strong customer authentication mandates are compressing issuer margins while forcing technology stack modernization across European banking infrastructure. The directive's open banking provisions simultaneously dismantle traditional network exclusivity.
Growth Catalysts
- Contactless Infrastructure:Nordic and Benelux retail environments have achieved near-universal terminal deployment, creating network effects that pull lagging Southern European markets toward equivalent acceptance density.
- GDPR-Compliant Data Monetization:The European Data Protection Board's guidance on anonymized transaction analytics permits new revenue streams from merchant insights without individual privacy breaches.
- Corporate Spend Recovery:Business travel and procurement normalization in Germany and France is expanding commercial card volumes faster than consumer discretionary segments.
Market Restraints
- Interchange Compression:EU merchant lobbying has sustained political pressure to cap interchange fees, constraining issuer revenue per transaction across all network tiers.
- Account-to-Account Substitution:SEPA Instant Credit Transfer infrastructure enables direct bank payments that bypass card networks entirely for high-value recurring transactions.
- Capital Allocation Tension:EBA stress-testing frameworks require elevated provisions for unsecured consumer lending, diverting capital toward secured products or corporate programs.
Strategic Opportunities
- Embedded Finance Convergence:Non-financial platforms in Poland and Romania are integrating card issuance through banking-as-a-service APIs, capturing underbanked populations outside traditional branch networks.
- Carbon-Linked Rewards:The EU Green Deal's sustainability disclosure requirements create regulatory tailwinds for issuers linking transaction data to carbon footprint tracking and offset mechanisms.
- Small Merchant Digitization:Independent retailers in Italy and Spain remain underserved by integrated payment-acceptance solutions, representing white space for vertical software providers.
Industry Challenges
- Legacy Core Modernization:Tier-two banks struggle to integrate real-time payment rails with decades-old card management systems, delaying product launches and increasing operational risk.
- Tokenization Compliance:Visa and Mastercard network mandates for credential-on-file security require costly infrastructure overhauls for merchants with stored payment data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Credit Cards Market |
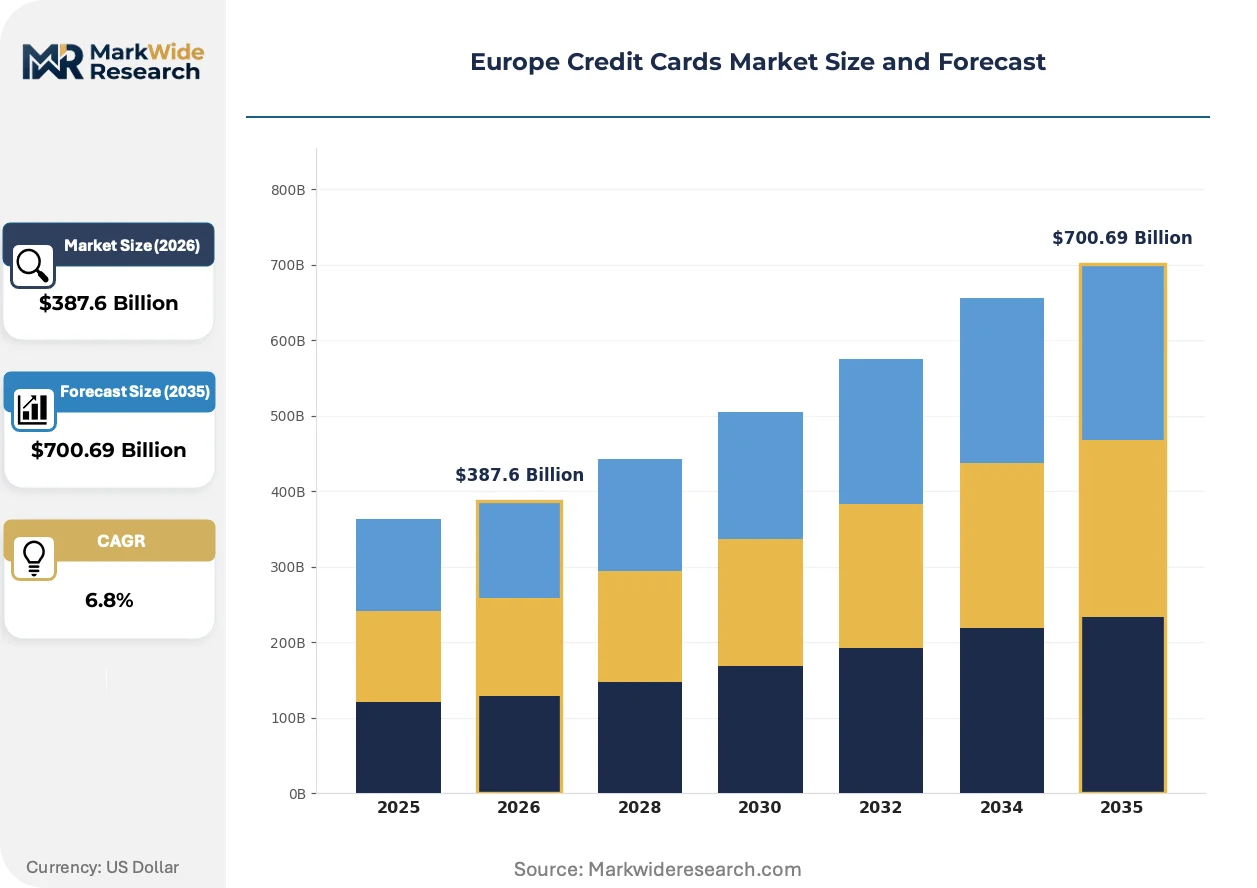
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Card Type: Standard, Rewards, Business, Secured Payment Method: Contactless, Chip & PIN, Online, Mobile Customer Segment: Students, Professionals, Retirees, Corporates Usage Frequency: Daily, Weekly, Monthly, Occasional |
| Companies Covered | Lloyds Banking Group plc, HSBC Holdings plc, Visa Inc., Deutsche Bank AG, Commerzbank AG, Mastercard Inc., Banco Santander SA, Swedbank AB, American Express Co., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Credit Cards Market Trends and Innovations
European card issuance is fragmenting across three simultaneous vectors: payment infrastructure decoupling from banking cores, regulatory data obligations proliferating, and merchant acceptance preferences diverging by country maturity.
Tokenization technology is modularizing how payment credentials secure digital transactions. E-commerce merchants and subscription platforms are adopting network tokens at accelerating velocity to reduce fraud liability exposure. This modularization is compressing the advantage of proprietary issuer wallets by standardizing security architecture across competing payment methods.
GDPR enforcement from the European Data Protection Board is constraining how transaction histories monetize into targeted financial products. Issuers must now implement technical anonymization before data aggregation, elevating compliance costs while limiting precision marketing. Premium rewards segments in the United Kingdom and Netherlands are responding by shifting toward explicit consent-based value exchanges rather than inferred behavioral profiling.
Merchant procurement of payment acceptance is consolidating toward integrated software platforms that bundle acquiring, POS, and inventory management. Independent retailers in France and Belgium are abandoning standalone terminal relationships for vertical solutions from Toast, Lightspeed, and local competitors. This consolidation is most visible in hospitality and retail verticals where payment acceptance has become a feature rather than a standalone purchasing decision.
Europe Credit Cards Market Segmentation
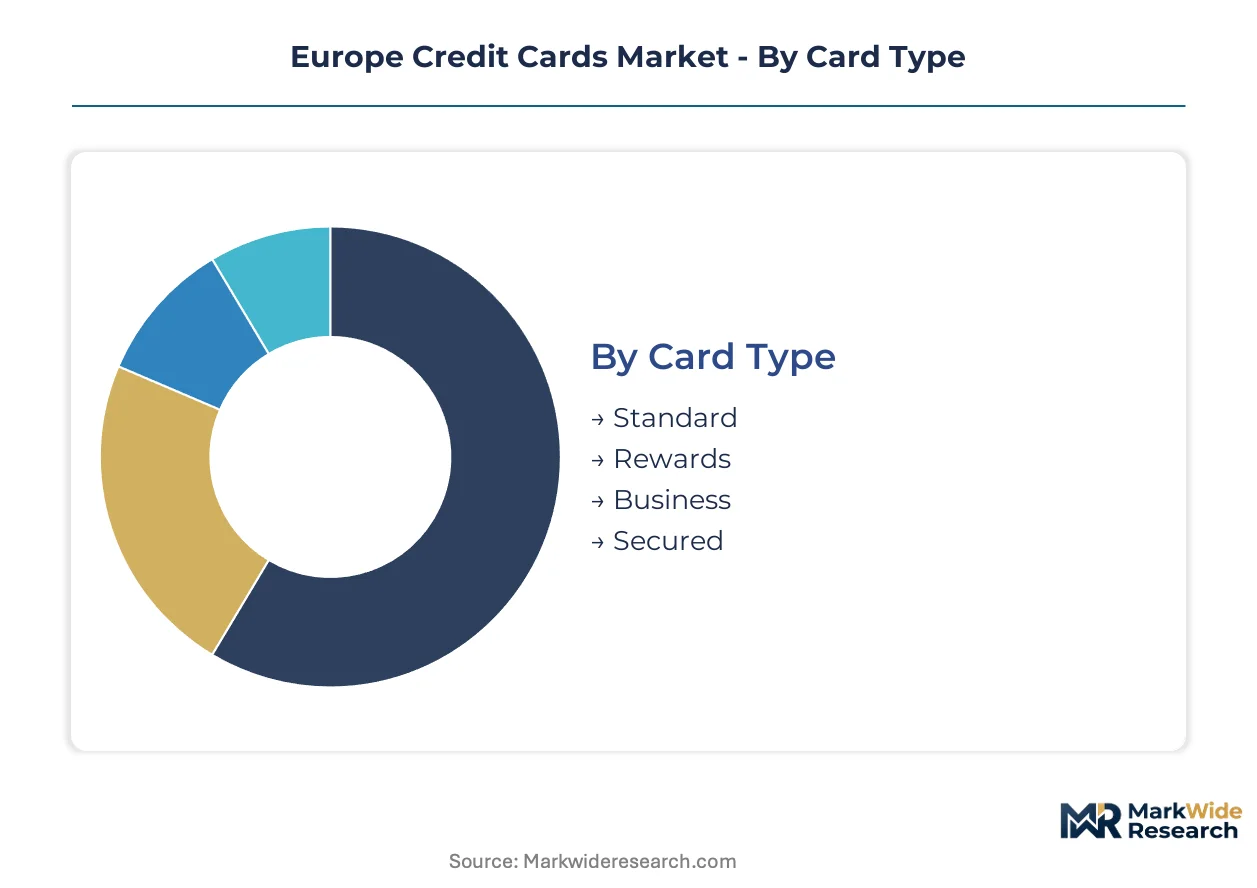
Issuers in Europe calibrate product portfolios across four intersecting dimensions where card type determines interchange economics, payment method shapes infrastructure investment, and customer segment dictates risk-weighted capital allocation. The following categories reveal how product design maps to regulatory constraints and merchant acceptance patterns across the region.
Card Type:
Volume concentration tilts toward mass-market products while premium tiers capture disproportionate revenue per account.
- Rewards:These products bundle cashback, travel points, or merchant discounts with annual fees and elevated interchange rates. Demand concentrates among affluent professionals in the United Kingdom and Netherlands seeking explicit value exchanges rather than inferred behavioral profiling under GDPR constraints.
- Business:Corporate card programs feature enhanced spend controls, detailed reporting, and liability structures separating employer and employee obligations. Commercial spend recovery in Germany and France is expanding volumes faster than consumer discretionary segments, sustaining defensive margin pools.
- Standard:No-fr revolving credit products with minimal annual fees serve mass-market consumers across Southern Europe.
- Secured:Collateral-backed issuance targets credit-restricted populations through deposited guarantees.
Mature deployment sits with Standard products. Newer deployment is concentrated in Rewards.
Payment Method:
Acceptance infrastructure maturity varies sharply between Nordic universal deployment and Southern European terminal gaps.
- Contactless:Near-field communication enables tap-to-pay authentication without PIN entry for transactions below strong customer authentication thresholds. Nordic and Benelux retail environments have achieved near-universal terminal deployment, creating network effects that pull lagging markets toward equivalent acceptance density.
- Mobile:Device-based credentials stored in Apple Pay, Google Pay, or proprietary issuer wallets leverage tokenization for e-commerce and in-app transactions. Poland and Romania show accelerating adoption as banking-as-a-service APIs embed issuance into non-financial platforms.
- Chip & PIN:EMV chip authentication with personal identification number verification remains mandatory for high-value transactions.
- Online:Card-not-present transactions rely on 3D Secure protocols and one-time passwords for remote purchases.
Chip & PIN represents legacy infrastructure. Mobile is expanding most quickly among younger demographics.
Customer Segment:
Risk-adjusted returns diverge between unsecured consumer lending and secured corporate programs under EBA stress-testing frameworks.
- Corporates:Commercial cardholders generate higher average transaction values with lower default rates than consumer segments. Procurement normalization and business travel recovery in Germany and France are expanding volumes through centralized billing and travel management integrations.
- Professionals:Salaried employees with established credit histories qualify for premium rewards products and higher credit limits.
- Students:Limited credit history products feature lower limits and parental guarantee options.
- Retirees:Fixed-income qualification criteria shape product design toward debit-credit hybrid structures.
Corporate programs anchor issuer profitability. Student segments are gaining share fastest through digital onboarding and alternative data scoring.
Usage Frequency:
Transaction density determines interchange revenue velocity and customer lifetime value calculations for acquisition spend.
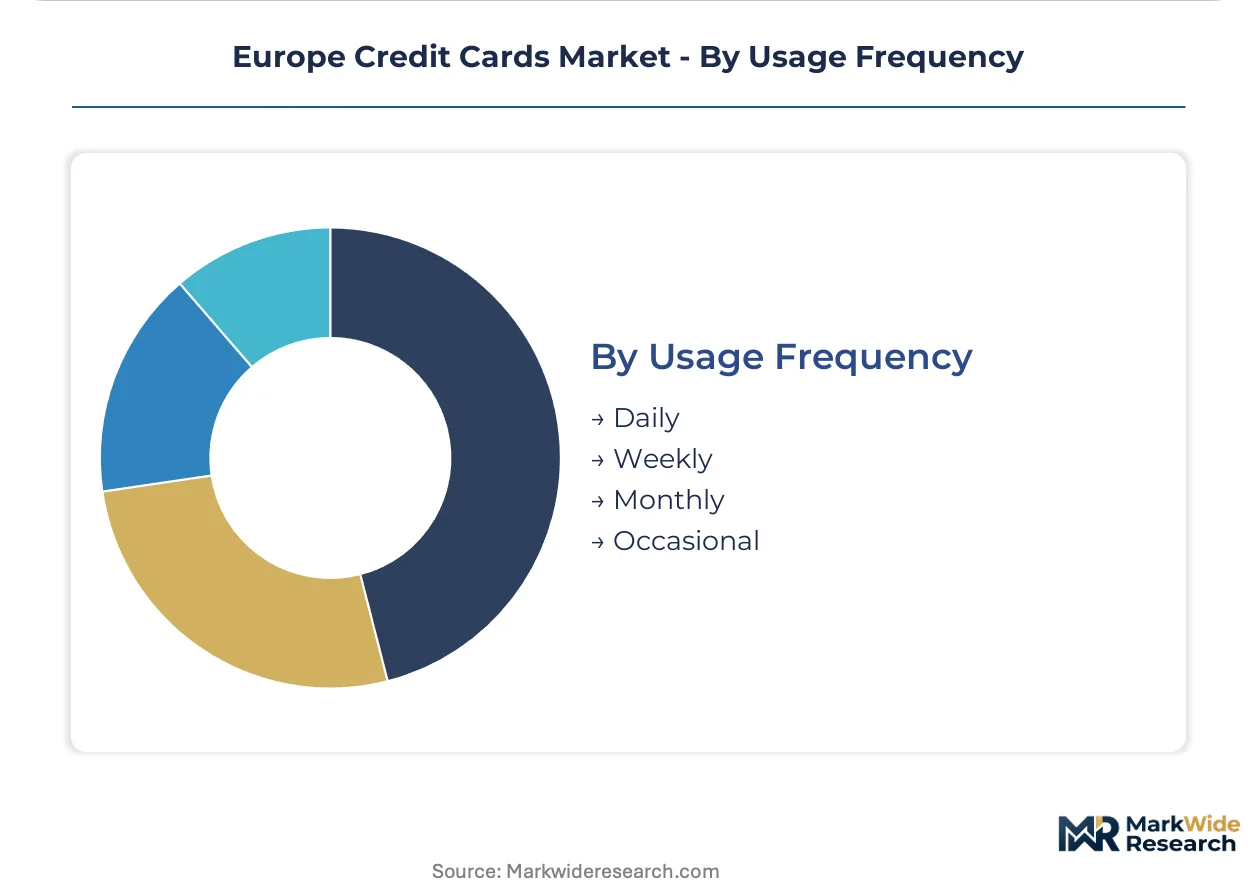
- Daily:High-velocity users integrate cards into routine purchasing across transit, groceries, and digital services. Urban professionals in London, Paris, and Berlin drive concentration as contactless infrastructure enables frictionless low-value transactions.
- Monthly:Periodic users deploy cards for specific categories like travel or large purchases.
- Weekly:Moderate-frequency patterns cluster around salary-aligned spending cycles.
- Occasional:Infrequent usage characterizes backup or emergency credit relationships.
Daily usage dominates transaction volume. Occasional relationships are climbing the fastest as issuers reactivate dormant accounts through targeted rewards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Luxembourg's financial center tax incentives concentrate payment service provider licensing, drawing fintech infrastructure investment from across the continent. This regulatory arbitrage shapes how card issuance and processing capacity distributes among European commercial hubs.
Germany
Corporate card programs from Deutsche Bank AG and Commerzbank AG drive commercial payment volumes through centralized travel management integrations. BaFin's supervisory mandates enforce strong customer authentication thresholds that elevate technology spend for domestic issuers. Frankfurt's banking cluster anchors back-office processing for pan-European card programs.
United Kingdom
Premium rewards products capture disproportionate interchange revenue as affluent professionals in London seek explicit value exchanges under GDPR constraints. The Financial Conduct Authority's consumer duty rules reshape product disclosure and suitability frameworks. The Square Mile hosts concentrated fintech-card issuer partnerships for digital onboarding.
France
Business travel normalization expands commercial card volumes through procurement platforms serving manufacturing supply chains. Banque de France oversight aligns domestic issuance with ECB collateral frameworks for asset-backed securities. Paris fintech clusters develop carbon-linked rewards products tied to EU Green Deal disclosure requirements.
Netherlands
Contactless terminal deployment achieves near-universal density in Amsterdam and Rotterdam retail environments, creating network effects for cross-border acceptance standards. De Nederlandsche Bank's open banking supervision accelerates account-to-account payment integration with card infrastructure. Eindhoven's technology corridor supplies tokenization hardware to Nordic acquiring networks.
Spain
Small merchant digitization lags in independent retail and hospitality segments across Barcelona and Madrid, representing white space for vertical software providers. Banco de España's PSD2 implementation timelines pressure regional banks to modernize legacy core systems. Andalusian tourism corridors drive seasonal card velocity fluctuations affecting issuer liquidity planning.
Europe Credit Cards Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across issuance, network, and acquiring layers. Universal banks leverage balance sheet scale to anchor corporate card relationships, while fintech challengers exploit banking-as-a-service APIs to embed issuance into non-financial platforms. Three archetypes dominate: incumbent universal banks with proprietary processing, global network operators with tokenization infrastructure, and digital-native challengers with alternative data scoring. Competitive moves concentrate on open banking partnership structures and carbon-linked product differentiation.
Within the universal bank tier, Deutsche Bank AG and HSBC Holdings plc occupy positions shaped by pan-European corporate relationships and trade finance integration. Visa Inc. anchors the network layer through tokenization investments that reduce fraud liability exposure for partner institutions. Among Nordic-focused issuers, Swedbank AB exemplifies regional concentration strategies built on contactless infrastructure penetration.
| Leading Market Players |
|---|
| Lloyds Banking Group plc |
| HSBC Holdings plc |
| Visa Inc. |
| Deutsche Bank AG |
| Commerzbank AG |
| Mastercard Inc. |
| Banco Santander SA |
| Swedbank AB |
| American Express Co. |
| Others |
Pricing and Supply Chain Analysis
Pan-European corporate travel management platforms concentrate procurement power for commercial card programs, anchoring contract-based pricing that rewards volume commitment with preferential interchange rates and bundled reporting services.
Pricing Analysis
Short lead-time deployment of tokenized payment credentials commands premium pricing from issuers serving e-commerce merchants with stored payment mandates. Three-tier pricing structure across premium rewards, standard revolving, and secured products differentiates by creditworthiness tier and annual fee scale. Cost compression in standard products intensifies as SEPA Instant Credit Transfer infrastructure erodes transaction volume. Small merchants in Southern Europe exhibit highest price sensitivity, while corporate treasury departments prioritize control features over per-transaction cost.
Supply Chain Analysis
EMV chip and tokenization hardware supply rests on semiconductor fabrication concentrated in Taiwan, South Korea, and Germany. Payment network infrastructure draws from specialized software development in Ireland and Estonia, with card personalization services anchored in France and the Netherlands. Single-source vulnerability sits with EMV chip foundries facing geopolitical trade restrictions. Distribution runs through licensed payment service providers regulated under national central bank oversight.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European card issuance is transitioning from magnetic stripe and static authentication toward tokenized, biometric-enabled payment credentials, with legacy core modernization determining competitive survival.
For Market Incumbents: Acquire cloud-native card management platforms to accelerate real-time payment rail integration and reduce dependency on decades-old legacy systems. Deepen vertical integration into tokenization infrastructure through direct partnerships with Visa and Mastercard network security programs. The threat of account-to-account payment substitution demands defensive technology stack renewal before customer attrition accelerates. For New Entrants and Emerging Players: Begin with embedded finance partnerships targeting Poland and Romania, where banking-as-a-service APIs enable card issuance integration into non-financial platforms serving underbanked populations. Small merchant digitization in Italy and Spain presents the most penetrable white space, with vertical software bundling of POS, inventory, and payment acceptance as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors fintech infrastructure specialists with proprietary alternative data scoring capabilities and regulatory technology compliance automation. Long-term viability hinges on open banking API leverage and carbon-linked product differentiation aligned with EU Green Deal disclosure requirements. Watch SEPA Instant Credit Transfer volume growth as the critical signal for card network displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Tokenization Infrastructure Investment | Reduces fraud liability exposure for partner banks under Visa and Mastercard network mandates. |
| Open Banking API Integration | Enables account-to-account payment convergence with traditional card infrastructure under PSD2 supervision. |
| Carbon-Linked Rewards Program | Aligns transaction data monetization with EU Green Deal sustainability disclosure requirements. |
| Banking-as-a-Service Partnership | Captures underbanked populations in Poland and Romania through non-financial platform embedding. |
| Legacy Core Modernization | Accelerates real-time payment rail deployment for Tier-two banks facing BaFin and Banco de España timelines. |
Research Methodology
Independent corroboration across issuer product executives, merchant acquiring specialists, and regulatory compliance officers underwrites the qualitative findings in this study. Primary fieldwork combined structured interviews with payment network strategists, banking-as-a-service platform engineers, and central bank supervision staff with secondary validation from ECB statistical releases, EBA stress-testing documentation, and national payment system reports. Bottom-up transaction volume modeling and top-down macroeconomic scenario triangulation anchored the analytical framework.
Rate-of-change decomposition across the analysis window separated volume growth drivers by card type, payment method, customer segment, and usage frequency dimensions. Segmentation modeling incorporated product tier, authentication technology, issuer archetype, and regional regulatory cluster as core stratification variables. CAGR derivation applied historical trajectory analysis adjusted for PSD2 implementation phase effects and contactless terminal deployment saturation curves.
Underlying measurement precision varies by segment; contactless payment volumes and Nordic market data carry tighter precision than emerging mobile wallet adoption in Southern Europe. Forecasts reflect documented assumptions regarding SEPA Instant Credit Transfer substitution velocity and GDPR compliance cost trajectories. A small set of regulatory implementation delays, network security mandate changes, and open banking API standardization outcomes warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Retail Cash Management Market
Payments
Global Accounts Payable (AP) Automation Software Market
Payments
Japan POS Terminals Market
Payments
GCC Mobile Payment Market
Payments
Mobile Card Reader Market
Payments
Europe Accounts Payable Automation Market
Payments
Germany POS Terminal Market
Payments
Point-Of-Sale [POS] Terminal Market
Payments
Spain Payment Gateway Market
Payments
North America Payment Gateway Market
Payments
Taiwan Mobile Payments Market
Payments
Voice-Based Payments Market
Payments
Indonesia Prepaid Cards Market
Payments
Middle East and Africa Prepaid Card Market
Payments
Digital Payment Market
Payments
UK Virtual Cards Market