
 Pharmaceutical Intermediates Market | 2026-2036
Pharmaceutical Intermediates Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Intermediates Market Outlook
Continuous flow chemistry is narrowing the gap between bench-scale synthesis and commercial batch production for complex chiral intermediates. Lonza Group leverages its bioconjugation expertise to anchor high-value intermediate supply for oncology payloads. BASF sustains massive alkoxide and Grignard capacity across Ludwigshafen and Antwerp, dominating bulk organic intermediate supply to European generic houses. Evonik Industries specializes in lipid nanoparticle building blocks, competing with emerging Asian entrants on regulatory dossier depth rather than price alone.
Pharmaceutical intermediates are discrete chemical entities—typically non-GMP or early-stage GMP materials—that serve as synthetic precursors to active pharmaceutical ingredients, often requiring stereochemical purity above 98% and residual solvent profiles meeting ICH Q3C thresholds. Their primary purpose is to deconstruct lengthy API syntheses into outsourceable, auditable steps that reduce capital intensity for finished dose manufacturers. Key Starting Materials command outsized margin pools because registrants must lock suppliers into drug master files early, while Catalysts face commoditization pressure from homogeneous precious-metal recovery programs. Generic Drugs applications absorb the largest absolute volume of intermediates, though Biopharmaceuticals—peptide linkers, ADC payloads, mRNA capping reagents—represent the fastest-expanding demand vector.
FDA's enhanced drug quality surveillance and EMA's tightened starting material definition under ICH Q11 are forcing sponsors to elevate supplier qualification rigor, particularly for dual-use chemicals with non-pharma diversion risk. India's CDSCO and China's NMPA are converging toward ICH-aligned impurity specification norms, reshaping export competitiveness for domestic intermediate producers. Stakeholders must monitor how carbon border adjustments and green chemistry mandates in the EU and US redirect capital toward enzymatic and electrosynthetic routes before regulatory deadlines harden process disclosure requirements.
Market Dynamics
Contract development and manufacturing organizations are expanding captive intermediate production to secure supply for generic drug portfolios, tightening the link between synthesis capability and downstream API control.
Growth Catalysts
- ICH Q11 Alignment:India's CDSCO and China's NMPA are converging toward ICH-aligned impurity specification norms, reshaping export competitiveness for domestic intermediate producers.
- Biopharmaceutical Demand:Peptide linkers, ADC payloads, and mRNA capping reagents represent the fastest-expanding demand vector across oncology and infectious disease pipelines.
- Continuous Flow Chemistry:Bench-scale synthesis is narrowing the gap with commercial batch production for complex chiral intermediates above 98% stereochemical purity.
Market Restraints
- Precious Metal Volatility:Homogeneous catalyst recovery programs face commoditization pressure as palladium and rhodium price swings compress margins on high-value synthetic steps.
- Supply Concentration Risk:Western pharma companies remain dependent on Ludwigshafen and Antwerp for bulk alkoxide and Grignard capacity, creating single-point vulnerability.
- REACH Compliance Burden:ECHA's tightened impurity profiling requirements for imported starting materials extend qualification timelines by 12-18 months for non-European suppliers.
Strategic Opportunities
- Lipid Nanoparticle Building Blocks:Evonik's regulatory dossier depth creates defensive moats against emerging Asian entrants competing on price alone.
- Enzymatic Route Adoption:EU Green Deal mandates and US carbon border adjustments are redirecting capital toward biocatalytic and electrosynthetic processes before disclosure deadlines harden.
- Dual-Use Chemical Controls:FDA's enhanced drug quality surveillance creates qualification barriers that favor established intermediates suppliers with audit-ready documentation systems.
Industry Challenges
- Stereochemical Skill Scarcity:Chiral synthesis expertise concentrates in Basel and Boston hubs, limiting workforce mobility for mid-scale manufacturers expanding into complex intermediate production.
- DMF Lock-In Complexity:Key Starting Materials command outsized margin pools because registrants must lock suppliers into drug master files early, freezing supplier switching costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Intermediates Market |
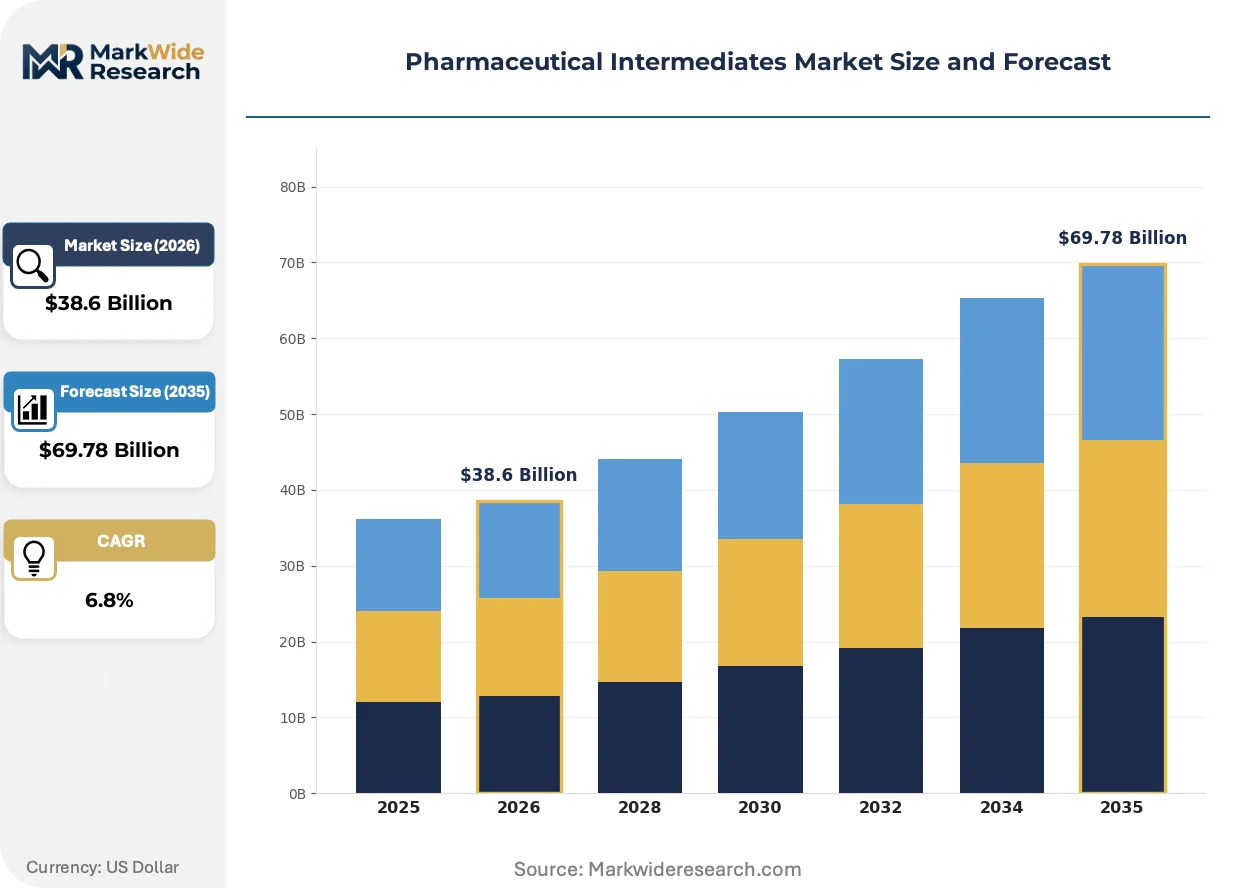
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: APIs, Key Starting Materials, Catalysts, Dual-Use Chemicals Application: Generic Drugs, Branded Drugs, Over-the-Counter Products, Biopharmaceuticals Market Player Type: Contract Manufacturers, In-House Producers, Wholesalers, Distributors Procurement Channel: Direct Sourcing, Online Platforms, Auctions, Brokers |
| Companies Covered | LANXESS, Solvay, Lonza Group, Teva, Aurobindo Pharma, BASF, Arkema, Dr. Reddy’s Laboratories, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Intermediates Market Strategic Shifts
Process intensification and regulatory convergence are compressing the traditional boundary between commodity chemical supply and pharmaceutical-grade intermediate manufacturing.
Continuous flow chemistry is collapsing the scale-up barrier between laboratory synthesis and commercial production for complex chiral intermediates. CDMOs are adopting microreactor platforms to reduce solvent volumes and thermal hazard exposure. This technology is collapsing capital requirements for entry into high-value intermediate segments previously reserved to integrated pharma houses.
EMA's tightened starting material definition under ICH Q11 is forcing sponsors to elevate supplier qualification rigor. The industrial consequence extends audit obligations deeper into the chemical supply chain, beyond traditional GMP boundaries. Generic drug manufacturers in India and China are responding by building captive intermediate capacity rather than qualifying external suppliers.
Buyers are consolidating vendor relationships around suppliers with dual regulatory dossier capability in both FDA and EMA jurisdictions. Long-tail chemical distributors are losing share to integrated CDMOs offering end-to-end documentation packages. This consolidation is most visible in the oncology payload segment, where ADC linkers require simultaneous compliance with biologics and small-molecule guidance documents.
Pharmaceutical Intermediates Market Segmentation
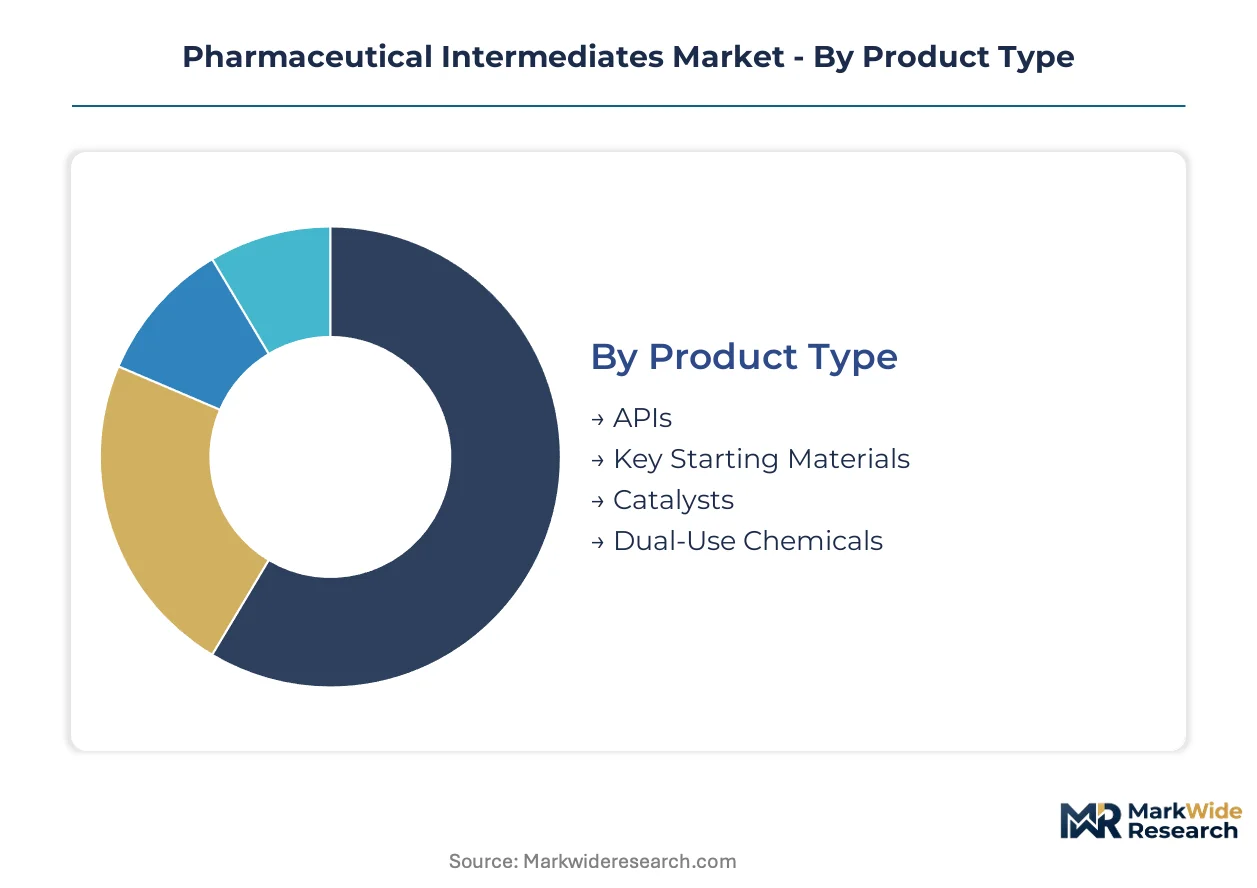
Segmentation in pharmaceutical intermediates reveals how synthesis complexity, regulatory burden, and supply chain control distribute value across distinct commercial layers. Each dimension exposes different margin structures and qualification barriers that shape procurement strategy.
Product Type:
Cost tier stratification separates commodity inputs from regulated materials with locked-in supplier relationships and extended qualification timelines.
- APIs:Advanced intermediates requiring full ICH Q7 compliance and drug master file registration command premium pricing due to regulatory lock-in. Demand concentrates in oncology and infectious disease portfolios where synthetic complexity justifies outsourced manufacture to CDMOs with dual FDA-EMA dossier capability.
- Key Starting Materials:Early-stage synthetic precursors defined under ICH Q11 guidelines carry outsized margin pools because registrants must designate suppliers before clinical Phase II, freezing switching costs for the product lifecycle. India's CDSCO and China's NMPA are converging toward ICH-aligned impurity specifications, reshaping export competitiveness for domestic producers of these critical inputs.
- Catalysts:Homogeneous precious-metal systems face margin compression from recovery programs and palladium price volatility.
- Dual-Use Chemicals:Synthetic precursors with non-pharma diversion risk trigger enhanced FDA surveillance and extended audit protocols.
Key Starting Materials commands the established base. The steepest expansion runs through APIs.
Application:
End-use differentiation tracks patent status, manufacturing scale, and biologic versus small-molecule modality requirements.
- Generic Drugs:High-volume, price-sensitive demand absorbs the largest absolute tonnage of intermediates, with manufacturers prioritizing cost efficiency over synthetic innovation. Western generic houses remain dependent on Ludwigshafen and Antwerp for bulk alkoxide and Grignard capacity, creating single-point vulnerability in European supply.
- Biopharmaceuticals:Peptide linkers, ADC payloads, and mRNA capping reagents represent the fastest-expanding demand vector across oncology and infectious disease pipelines. Lonza Group anchors high-value intermediate supply for oncology payloads through bioconjugation expertise, while Evonik Industries competes on regulatory dossier depth for lipid nanoparticle building blocks.
- Branded Drugs:Patent-protected portfolios sustain margin for complex chiral intermediates above 98% stereochemical purity.
- Over-the-Counter Products:Commodity-grade inputs with simplified qualification requirements serve high-volume, low-margin formulations.
Generic Drugs anchors volume throughput. Biopharmaceuticals is climbing the fastest as modality complexity escalates.
Market Player Type:
Supply chain configuration determines documentation burden, capital intensity, and regulatory exposure for intermediate handlers.
- Contract Manufacturers:CDMOs are expanding captive intermediate production to secure supply for generic drug portfolios, tightening the link between synthesis capability and downstream API control. Continuous flow chemistry adoption narrows the scale-up gap between bench and commercial production, collapsing capital requirements for entry into high-value segments.
- In-House Producers:Integrated pharma houses retain complex chiral synthesis within Basel and Boston hub concentrations where stereochemical expertise concentrates, limiting workforce mobility for mid-scale manufacturers attempting backward expansion.
- Wholesalers:Long-tail chemical distributors are losing share to integrated CDMOs offering end-to-end documentation packages.
- Distributors:Regional logistics providers face margin pressure as buyers consolidate vendor relationships around dual-jurisdiction regulatory capability.
Contract Manufacturers capture the growth trajectory. In-House Producers defend the high-complexity core.
Procurement Channel:
Transaction structure reflects relationship depth, documentation requirements, and supply security priorities across the qualification spectrum.
- Direct Sourcing:Long-term agreements with locked-in suppliers dominate Key Starting Materials procurement, where DMF registration freezes alternative qualification. EMA's tightened starting material definition under ICH Q11 extends audit obligations deeper into the chemical supply chain, favoring established relationships over spot transactions.
- Online Platforms:Digital marketplaces are gaining traction for standardized, non-GMP intermediates where impurity profiling requirements remain less stringent, though REACH compliance burdens for imported starting materials still extend qualification timelines by 12-18 months for non-European suppliers.
- Auctions:Price-driven spot purchasing serves commodity-grade materials with surplus availability and relaxed specification requirements.
- Brokers:Intermediary arrangements persist for dual-use chemicals where enhanced surveillance creates documentation barriers that favor audit-ready broker networks.
Direct Sourcing maintains the volume base. Online Platforms is gaining share fastest as digital infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports pharmaceutical intermediates to Western European generic manufacturers under tightening REACH compliance windows, while Chinese producers redirect capacity toward domestic biopharmaceutical demand.
United States
FDA's enhanced drug quality surveillance and ICH Q11 implementation drive demand for audit-ready intermediate suppliers. The Inflation Reduction Act accelerates domestic API reshoring initiatives. Greater Boston and San Diego biotech clusters absorb specialized peptide linker and ADC payload intermediates for oncology pipelines.
Germany
BASF sustains massive alkoxide and Grignard capacity across Ludwigshafen and Antwerp, dominating bulk organic intermediate supply to European generic houses. ECHA's tightened impurity profiling requirements for imported starting materials extend qualification timelines by 12-18 months for non-European suppliers. The Rhine-Ruhr chemical corridor concentrates stereochemical expertise for complex chiral synthesis above 98% purity.
India
CDMOs expand captive intermediate production to secure supply for generic drug portfolios as Western pharma diversifies API sourcing. CDSCO converges toward ICH-aligned impurity specification norms, reshaping export competitiveness for domestic producers. Hyderabad and Ahmedabad manufacturing belts scale continuous flow chemistry platforms for commercial chiral intermediate production.
China
NMPA alignment with ICH Q11 guidelines elevates documentation requirements for starting material suppliers serving multinational registrants. Dual carbon goals and green chemistry mandates redirect capital toward enzymatic and electrosynthetic routes. The Yangtze River Delta chemical parks dominate lipid nanoparticle building block output for mRNA therapeutic applications.
Switzerland
Swissmedic's stringent quality surveillance creates qualification barriers favoring established intermediates suppliers with dual FDA-EMA dossier capability. Basel anchors global bioconjugation expertise for high-value oncology payload intermediates. The country's pharmaceutical cluster specializes in complex chiral synthesis where stereochemical skill scarcity limits competitor entry.
Pharmaceutical Intermediates Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure consolidating around integrated CDMOs with dual-jurisdiction regulatory capability. The vendor base stratifies between scale-driven bulk chemical suppliers and premium-tier bioconjugation specialists. Three archetypes dominate: European integrated chemical conglomerates with captive alkoxide capacity, Asian CDMOs building backward integration into starting materials, and Swiss-American bioconjugation specialists anchoring oncology payload supply. M&A activity concentrates on acquiring enzymatic platform technologies, while capacity expansion targets lipid nanoparticle building blocks for mRNA applications.
Within the integrated chemical tier, BASF and LANXESS exemplify scale-driven European producers with massive Ludwigshafen-based alkoxide and Grignard capacity serving generic drug manufacturers. Lonza Group occupies a specialist position anchoring high-value intermediate supply for oncology payloads through bioconjugation expertise. Among Asian pharmaceutical manufacturers, Aurobindo Pharma and Dr. Reddy's Laboratories represent CDMOs expanding captive intermediate production to tighten downstream API control. Evonik Industries sits within the regulatory-differentiated tier, competing on dossier depth rather than price alone for lipid nanoparticle building blocks.
| Leading Market Players |
|---|
| LANXESS |
| Solvay |
| Lonza Group |
| Teva |
| Aurobindo Pharma |
| BASF |
| Arkema |
| Dr. Reddy's Laboratories |
| Evonik Industries |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Antwerp corridor's freight cost volatility feeds directly into margin compression for bulk alkoxide and Grignard intermediates, while simultaneously amplifying price differentiation between captive European supply and Asian import alternatives. This logistics chokepoint concentrates pricing power among Ludwigshafen-based producers serving generic drug manufacturers, even as CDMOs in India and China exploit cost arbitrage for non-GMP starting materials.
Pricing Analysis
Cost-plus contracts indexed to palladium and rhodium spot markets dominate homogeneous catalyst procurement, exposing margins to precious metal volatility. Three-tier pricing structure across GMP-certified, DMF-registered, and commodity-grade intermediates separates audit-ready suppliers from price-competitive alternatives. Cost compression in catalyst recovery programs is intensifying because of homogeneous metal reclamation efficiency gains. Generic drug manufacturers exhibit highest price sensitivity, while oncology CDMOs prioritize regulatory dossier depth over unit economics.
Supply Chain Analysis
Upstream petrochemical feedstock availability from Ludwigshafen, Antwerp, and Rotterdam anchors European alkoxide and Grignard capacity. Specialty chemical inputs draw from Indian pharmaceutical manufacturing belts and Chinese Yangtze River Delta chemical parks. Single-source vulnerability concentrates around BASF's Ludwigshafen complex for bulk organic intermediates. Distribution runs through integrated CDMOs with dual FDA-EMA dossier capability, displacing long-tail chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in regulatory dossier maintenance and DMF lifecycle management are expanding faster than commodity intermediate production, creating recurring revenue layers for documentation-capable suppliers.
For Market Incumbents: Entrench market position by acquiring enzymatic platform technologies before EU Green Deal disclosure deadlines harden process requirements. Expand captive intermediate production in Hyderabad and Ahmedabad manufacturing belts to tighten downstream API control against emerging Asian CDMOs. Lock key starting material suppliers into early-phase drug master files to freeze competitor switching costs. For New Entrants and Emerging Players: Pursue white-space opportunities in lipid nanoparticle building blocks for mRNA applications, where regulatory dossier depth matters more than scale economics. Target peptide linker and ADC payload intermediates for oncology pipelines in Greater Boston and San Diego biotech clusters. Lead with continuous flow chemistry platforms to collapse capital requirements for complex chiral synthesis entry. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors CDMOs with backward integration into starting materials and dual-jurisdiction regulatory capability. Long-term viability hinges on enzymatic and electrosynthetic route adoption ahead of carbon border adjustments. Watch FDA enhanced surveillance implementation pace as inflection indicator for qualification barrier height.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Starting Materials | CDMOs secure supply control as ICH Q11 tightens supplier qualification requirements. |
| Enzymatic Platform Acquisition | Biocatalytic capabilities meet EU Green Deal mandates before process disclosure deadlines. |
| Dual-Jurisdiction Dossier Investment | Simultaneous FDA and EMA compliance creates defensive moats against price-only competitors. |
| Continuous Flow Chemistry Scale-Up | Microreactor platforms reduce solvent volumes and thermal hazard exposure for chiral intermediates. |
| Lipid Nanoparticle Capacity Expansion | mRNA therapeutic demand drives specialized building block output in Yangtze River Delta parks. |
Study Parameters
A spread of perspectives from regulatory affairs leads at CDMOs, procurement managers at generic drug manufacturers, and technical R&D directors at specialty chemical firms converged on the working assumptions. Primary interviews combined with secondary validation from FDA filings, EMA submissions, CDSCO notifications, and customs trade data. Bottom-up demand modeling and top-down supply capacity assessments triangulated market sizing.
Demand-supply balance dynamics across product type, application, and procurement channel segments shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories and value-per-unit trends. Forecast inputs incorporated ICH Q11 implementation timelines, REACH compliance burden evolution, and carbon border adjustment policy development.
Macroeconomic conditions sit as an overlay; deviation in freight rates, precious metal prices, or currency exchange would shift the trajectory. Forecasts reflect assumptions about regulatory convergence pace and green chemistry mandate enforcement. Cross-checking against ECHA import qualification timelines and FDA surveillance program expansion is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Nickel Acetate Market
Chemical Intermediates
Myristoyl Chloride Market
Chemical Intermediates
Global Glycinates Market
Chemical Intermediates
Iodoacetonitrile Market
Chemical Intermediates
Refinery Process Chemicals Market
Chemical Intermediates
Metaphenoxy Benzaldehyde (MPBD) Market
Chemical Intermediates
Methoxypropylamine (MOPA) Market
Chemical Intermediates
Global Etoricoxib Intermediate Market
Chemical Intermediates
Global Biochemical Reagents Market
Chemical Intermediates
Fungal Staining Reagent Market
Chemical Intermediates
Leather Chemicals Market
Chemical Intermediates
Global Electrophoresis Reagents Market
Chemical Intermediates
Chemical Synthesizer Market
Chemical Intermediates
Palmitoyl Chloride Market
Chemical Intermediates
Polyamide Intermediate Chemicals Market
Chemical Intermediates
Global Chemical Intermediates Market