
 Thioesters Market | 2026-2036
Thioesters Market Size, Share, and Industry Trends Forecast 2026-2036
Thioesters Market Outlook
Natural antioxidants are repositioning thioester economics in food-grade applications, compelling synthetic producers to reformulate cost structures. Songwon Industrial Co. Ltd leverages backward integration into phenolic chemistry to sustain margin control across Asia. BASF SE anchors European supply through ISO-certified manufacturing hubs in Ludwigshafen. Addivant USA LLC competes on specialized liquid thioester blends for polymer stabilization in North American tire production.
Thioesters are organosulfur compounds characterized by a carbonyl group bonded to a sulfur atom (R-CO-S-R'), synthesized via acylation of thiols or thioesterification of carboxylic acids, functioning primarily as antioxidants, stabilizers, and intermediate reactants in polymer, food, and pharmaceutical systems. Acylthioesters dominate volume due to mature supply chains serving rubber and plastics manufacturers, while alkylthioesters represent the fastest-expanding category driven by clean-label food preservation trends in Europe and North America. Aromatic thioesters command premium positioning in pharmaceutical intermediate applications where purity specifications exceed standard industrial grades.
REACH in Europe and FDA food additive regulations in the United States impose divergent purity and labeling requirements that fragment formulation strategies across Atlantic supply chains. China's SAMR enforces GB standards for sulfur-containing food additives that differ from Codex Alimentarius guidelines, creating compliance complexity for exporters. India's FSSAI is tightening contaminant limits on imported antioxidant premixes, reshaping procurement criteria for domestic food processors. Stakeholders must monitor regulatory divergence between sulfur-content thresholds in pharmaceutical versus food-grade applications to align capacity investments with the stricter of overlapping standards.
Market Dynamics
REACH compliance tightening purity thresholds for sulfur-containing additives is forcing reformulation investments across European supply chains while Chinese polymer production scales concentrate demand in Asia.
Growth Catalysts
- Rubber stabilization demand:Tire manufacturers in China and India are expanding thioester consumption as domestic vehicle production accelerates and radial tire specifications tighten.
- REACH purity mandates:European ECHA enforcement of lower contaminant limits in sulfur-containing additives is upgrading technical specifications and filtering substandard suppliers from the market.
- Edible oil preservation:Food processors across Southeast Asia are adopting thioester antioxidants to extend shelf life in palm oil and packaged snack applications.
Market Restraints
- Feedstock volatility:Mercaptan and phenolic precursor costs fluctuate with crude oil derivatives, compressing margin stability for non-integrated producers.
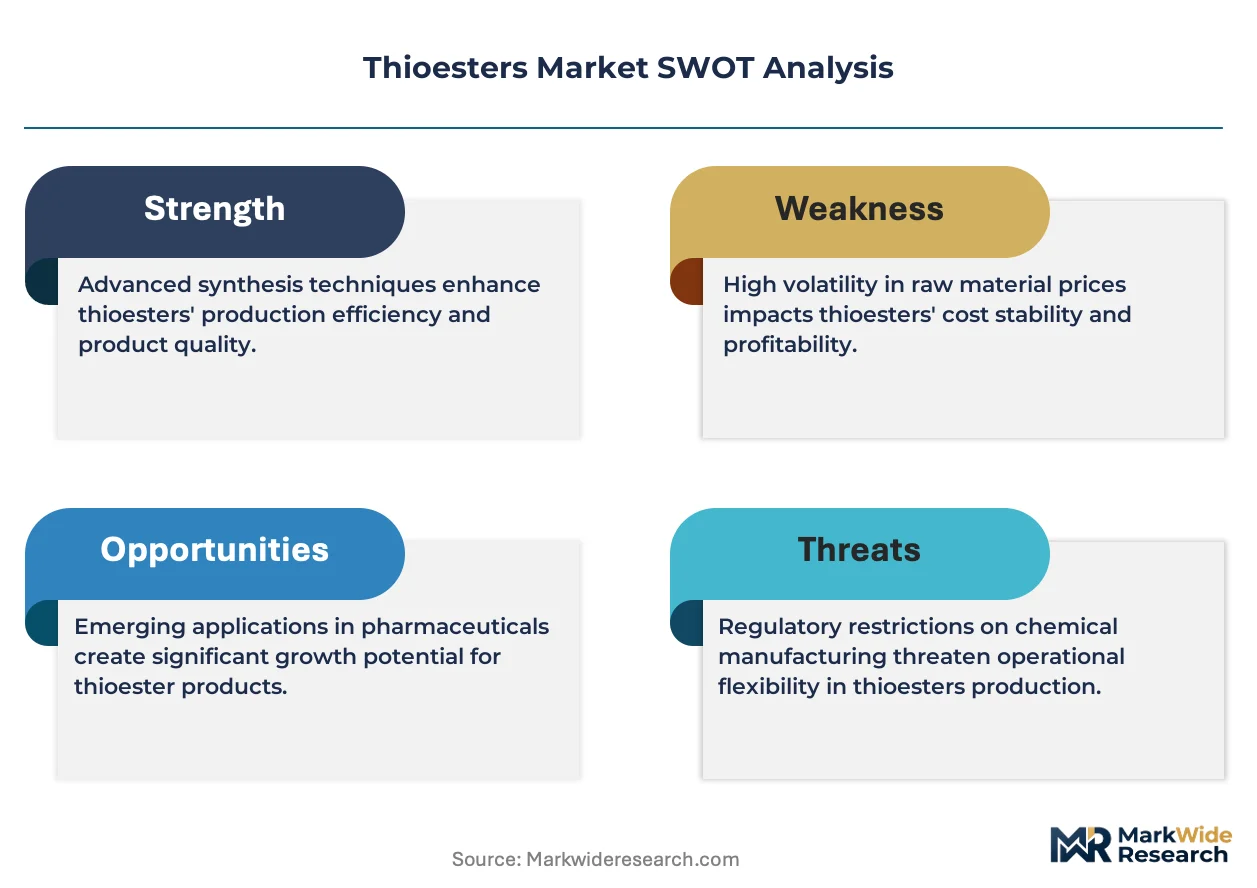
- Substitution pressure:Natural tocopherol and rosemary extract antioxidants are capturing clean-label food segments previously served by synthetic thioesters.
- Regulatory fragmentation:Divergent FDA, EFSA, and SAMR food additive approvals force manufacturers to maintain multiple formulation inventories.
Strategic Opportunities
- Pharmaceutical intermediates:Aromatic thioesters for high-purity drug synthesis command premium positioning as CDMOs expand peptide and nucleotide manufacturing.
- India FSSAI alignment:Tightening domestic contaminant standards on imported antioxidant premixes creates openings for localized blending operations.
- Biopolymer stabilization:Thioesters compatible with PLA and PHA degradation profiles address unmet antioxidant needs in compostable packaging.
Industry Challenges
- Specialized synthesis expertise:Thioesterification process chemistry requires organosulfur handling capabilities that exceed standard antioxidant manufacturing skill bases.
- Cross-grade certification timelines:Food-grade to pharmaceutical-grade conversions demand 18-24 month validation cycles with multiple national regulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thioesters Market |
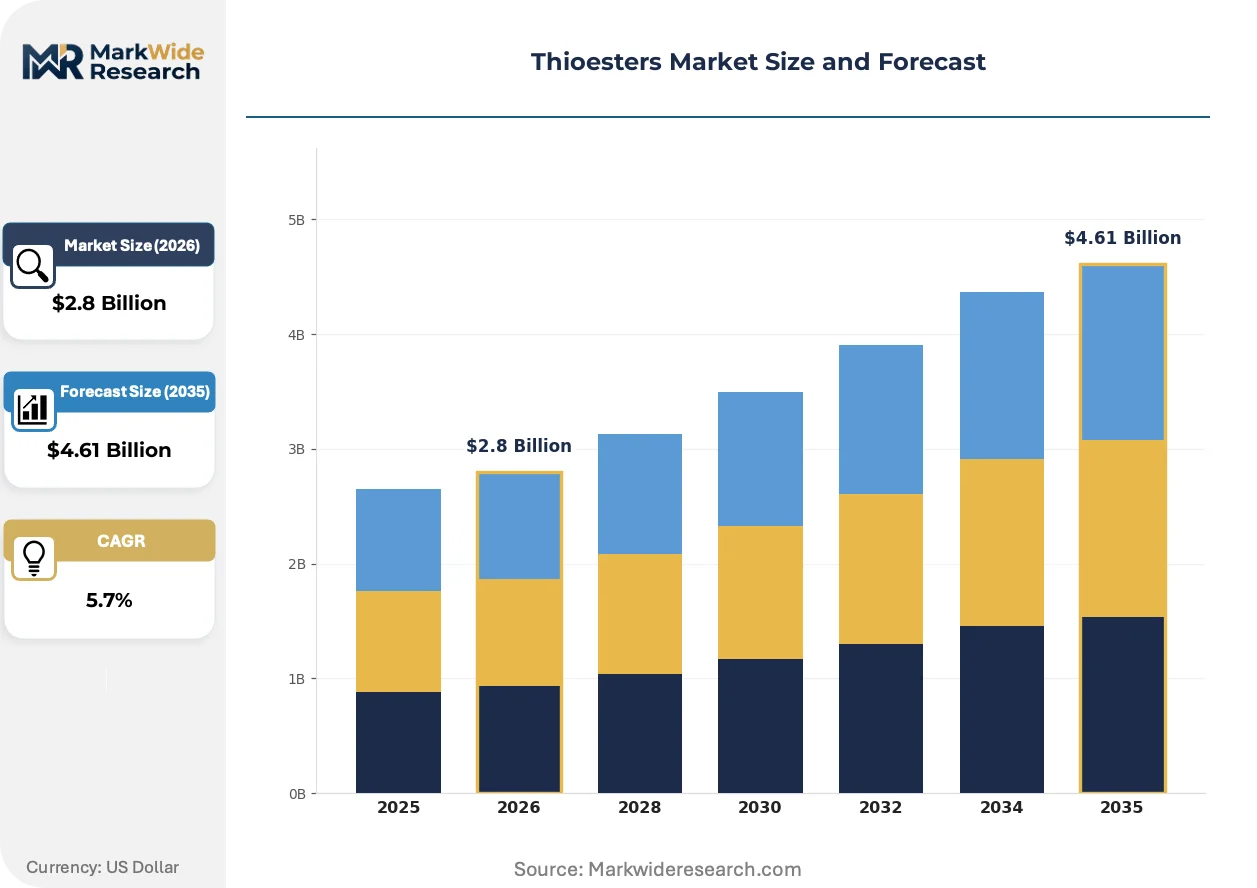
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acylthioesters, Alkylthioesters, Aromatic Thioesters, Dithiocarbonates End Use Industry: Food & Beverage, Agriculture, Pharmaceuticals, Cosmetics Form: Liquid, Solid, Powder, Granule Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | Songwon Industrial Co. Ltd, Addivant USA LLC, Reagens S.p.A., Trigon Antioxidants Pvt. Ltd., Bioray Chemical Co. Ltd., Double Bond Chemical Ind. Co. Ltd., Mayzo, Inc., Tianjin Zhongxin Chemtech Co., Ltd, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thioesters Market Strategic Shifts
Process intensification and regulatory divergence are compressing product development cycles while opening technical differentiation paths beyond commodity antioxidant positioning.
Continuous flow reactor technology for thioesterification is modularizing production economics. Specialty chemical producers in Germany and Japan are adopting microreactor systems to reduce batch-to-batch variability and accelerate grade changeovers. This architecture is enabling smaller-lot, higher-purity output that aligns with pharmaceutical intermediate specifications without dedicated plant investments.
REACH authorization requirements for persistent, bioaccumulative substances are tightening substance evaluation protocols. ECHA's expanded scrutiny of organosulfur compounds is extending registration timelines and elevating toxicological data costs. European polymer stabilizer formulators are responding by pre-qualifying alternative thioester structures and accelerating substance volume tracking systems.
Specification bundling is consolidating procurement authority among multinational food and tire manufacturers. Tier-one buyers are issuing consolidated antioxidant tenders spanning multiple geographies, displacing regional spot purchasing. This concentration is most pronounced in North American tire production and European edible oil processing, where technical service integration now outweighs unit pricing in supplier selection criteria.
Thioesters Market Segmentation
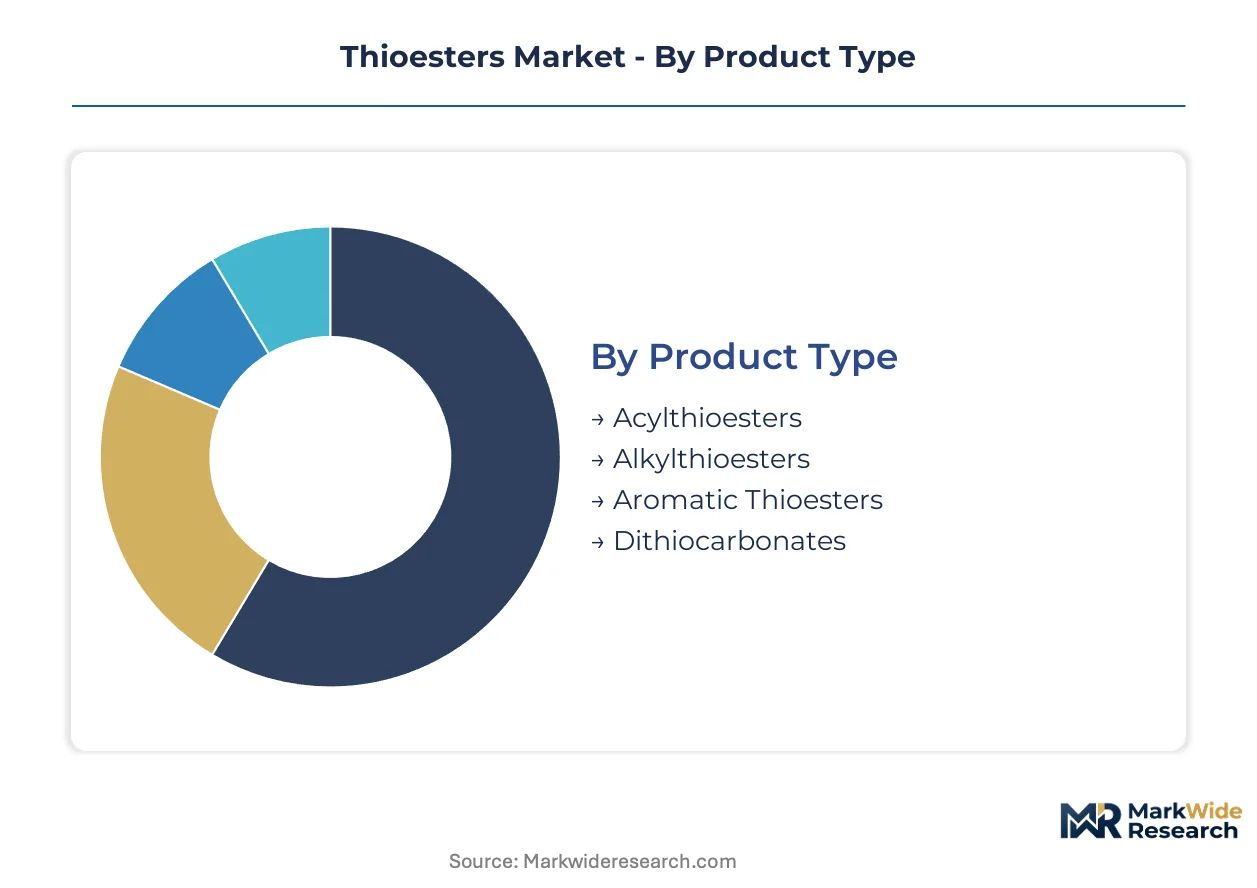
Thioester procurement patterns diverge sharply across product chemistries and end-use specifications, forcing suppliers to maintain parallel formulation inventories. Technical grade differentiation determines margin capture, with pharmaceutical and food-grade certifications commanding substantial premia over industrial applications.
Product Type:
Upgrade cycles in polymer stabilization and clean-label food preservation are redrawing competitive boundaries between synthetic thioester families, with purity thresholds now dictating supplier selection more than unit economics.
- Acylthioesters:Carbonyl-sulfur bonded structures synthesized from carboxylic acid precursors dominate rubber and plastics antioxidant applications. Tire manufacturers in China and India scale consumption as radial tire specifications tighten and domestic vehicle production accelerates.
- Alkylthioesters:Clean-label food preservation trends in Europe and North America propel alkyl variants as processors seek alternatives to traditional synthetic antioxidants. Palm oil refiners across Southeast Asia adopt these grades for extended shelf-life packaging.
- Aromatic Thioesters:Benzene-ring substituted structures serve high-purity pharmaceutical intermediate applications where contaminant limits exceed standard industrial specifications.
- Dithiocarbonates:Sulfur-carbon double-bond configurations function as specialized flotation reagents and agricultural fungicide precursors.
Volume placements concentrate in acylthioesters serving polymer stabilization; the faster expansion belongs to alkylthioesters capturing clean-label food segments.
End Use Industry:
Margin structures stratify sharply across end-use certifications, with pharmaceutical and food-grade compliance timelines stretching 18-24 months versus immediate industrial qualification.
- Food & Beverage:Edible oil processors deploy thioester antioxidants to inhibit rancidity in palm oil, snack foods, and packaged goods. REACH purity mandates and FDA food additive regulations impose divergent formulation requirements that fragment Atlantic supply chains.
- Pharmaceuticals:Peptide synthesis and nucleotide manufacturing drive aromatic thioester demand as CDMOs expand contract development capacity. EMA and FDA impose overlapping but non-identical impurity thresholds that complicate multi-territory supply.
- Agriculture:Crop protection formulators utilize dithiocarbonate derivatives as fungicide intermediates and soil treatment additives.
- Cosmetics:Personal care manufacturers incorporate thioester stabilizers into emulsion systems and oxidative-sensitive active ingredient packaging.
Revenue concentration sits with food and pharmaceutical grades; cosmetics applications are climbing the fastest as clean beauty formulations proliferate.
Form:
Physical state selection hinges on downstream processing economics, with liquid grades reducing handling costs in continuous polymer operations while solids enable precise dosing in batch food systems.
- Liquid:Pumpable formulations dominate tire manufacturing and continuous extrusion processes where automated dosing integrates with production lines. German and Japanese producers deploy microreactor systems to reduce batch variability in liquid grade output.
- Solid:Molded blocks and flakes serve batch polymerization and agricultural blending operations requiring extended shelf stability.
- Powder:Micronized particles enable homogeneous dispersion in dry food premixes and cosmetic powder formulations.
- Granule:Pelletized structures minimize dust generation in rubber compounding and large-scale agricultural handling.
Procurement volumes cluster in liquid grades for polymer integration; powder forms are gaining share fastest as dry blending automation spreads in food processing.
Distribution Channel:
Channel selection reflects buyer scale and technical service requirements, with multinational tire and food manufacturers consolidating procurement authority through direct relationships.
- Direct Sales:Tier-one polymer and food manufacturers issue consolidated multi-territory tenders that displace regional spot purchasing. Technical service integration now outweighs unit pricing in supplier selection.
- Distributors:Regional chemical distributors serve mid-tier rubber processors and agricultural formulators requiring local inventory and formulation support.
- Online Sales:Digital platforms capture research-grade and small-lot pharmaceutical intermediate orders from CDMOs and academic synthesis operations.
- Retail:Limited agricultural co-op and specialty chemical retail channels serve small-holder farmers and artisan food producers.
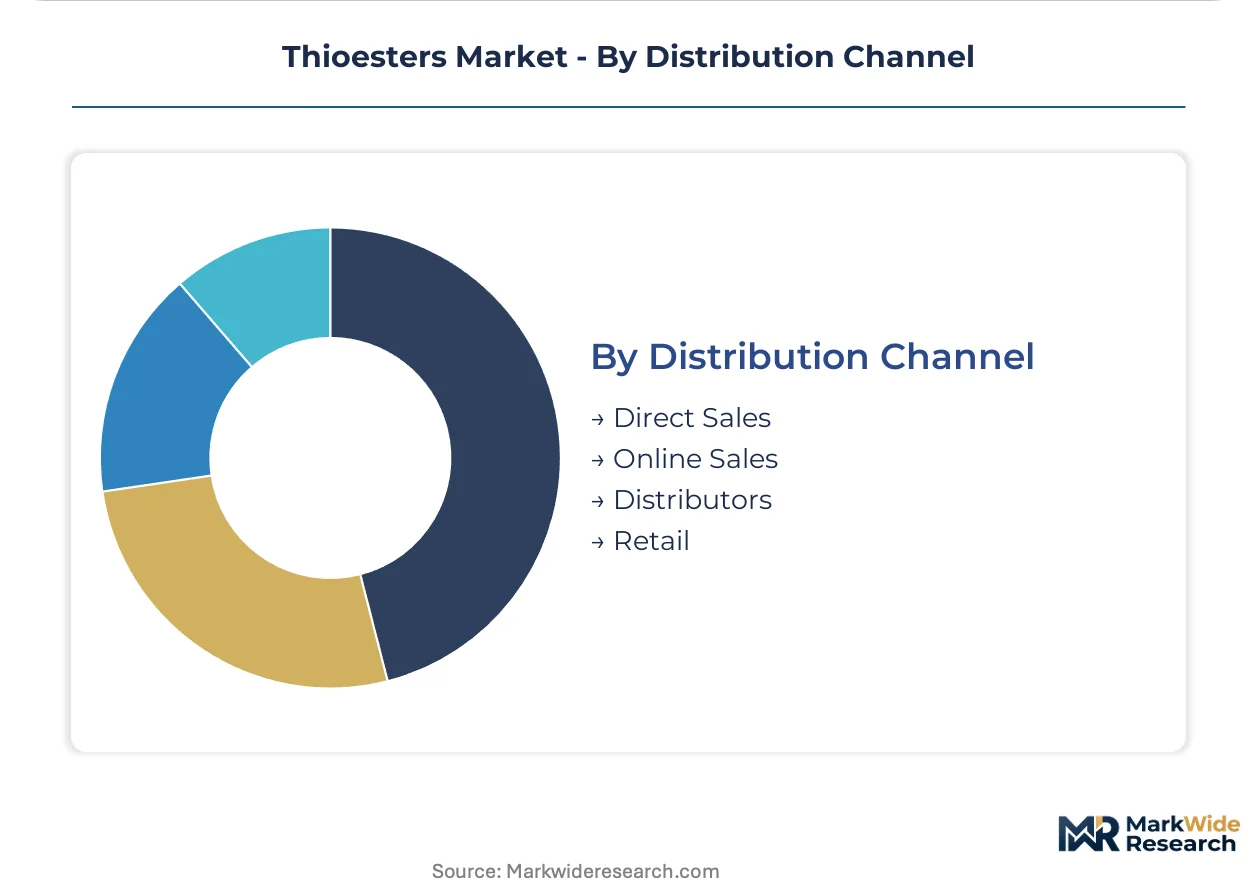
Transaction value concentrates in direct sales relationships; online channels are expanding most quickly as digital procurement penetrates pharmaceutical R&D supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates thioester demand as domestic polymer and rubber production scales, while regulatory divergence across the United States, Germany, and India fragments formulation strategies and reshapes supplier selection criteria.
China
Tire manufacturers in Shandong and Jiangsu provinces scale thioester consumption as radial tire specifications tighten and domestic vehicle production accelerates. SAMR enforces GB standards for sulfur-containing food additives that differ from Codex Alimentarius guidelines, creating compliance complexity for exporters. The Yangtze River Delta hosts concentrated polymer stabilizer production serving both domestic tire makers and Southeast Asian edible oil processors.
United States
North American tire producers deploy liquid thioester blends for continuous extrusion processes where automated dosing integrates with production lines. FDA food additive regulations impose divergent purity and labeling requirements that fragment formulation strategies versus European supply chains. The Gulf Coast petrochemical corridor anchors mercaptan precursor supply, sustaining backward integration advantages for integrated antioxidant producers.
Germany
Specialty chemical producers in Ludwigshafen and Leverkusen adopt microreactor systems to reduce batch-to-batch variability in pharmaceutical-grade thioester output. ECHA enforcement of REACH authorization requirements tightens substance evaluation protocols and extends registration timelines for organosulfur compounds. The Rhine-Ruhr industrial cluster concentrates ISO-certified manufacturing hubs serving European polymer stabilizer formulators.
India
Domestic food processors in Maharashtra and Gujarat reshape procurement criteria as FSSAI tightens contaminant limits on imported antioxidant premixes. CDSCO pharmaceutical regulations create overlapping compliance requirements with food-grade standards, stretching certification timelines. The Delhi-Mumbai Industrial Corridor attracts localized blending operations targeting both domestic edible oil refiners and export-oriented pharmaceutical CDMOs.
Japan
Precision polymer manufacturers in the Kanto region demand high-purity thioester grades for electronic materials and specialty rubber applications. METI industrial standards coordinate with international frameworks while maintaining distinct domestic specifications. The Osaka-Kobe chemical hub sustains advanced thioesterification process capabilities serving pharmaceutical intermediate and clean-label food preservation segments.
Thioesters Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated chemical conglomerates controlling polymer stabilization volumes while regional blenders capture food-grade niches. Three archetypes dominate: backward-integrated phenolic chemistry specialists, ISO-certified pharmaceutical-grade refiners, and distributed liquid formulation blenders. Competitive intensity centers on capacity expansion in Asian manufacturing hubs and technology licensing for continuous flow reactor systems.
Among Asia-Pacific-based industrial groups, Songwon Industrial Co. Ltd exemplifies backward-integrated phenolic chemistry control, while BASF SE occupies a position as the European ISO-certified manufacturing anchor. Addivant USA LLC represents the specialized liquid formulation tier serving North American tire production. These three entities illustrate how geographic origin and corporate structure align with distinct competitive positioning across antioxidant market segments.
| Leading Market Players |
|---|
| Songwon Industrial Co. Ltd |
| Addivant USA LLC |
| Reagens S.p.A. |
| Trigon Antioxidants Pvt. Ltd. |
| Bioray Chemical Co. Ltd. |
| Double Bond Chemical Ind. Co. Ltd. |
| Mayzo, Inc. |
| Tianjin Zhongxin Chemtech Co., Ltd |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
REACH authorization requirements for persistent, bioaccumulative substances gate both qualified supply and premium-tier pricing access in European thioester markets, filtering substandard producers from pharmaceutical-grade segments while concentrating margin capture among ECHA-registered manufacturers with validated toxicological dossiers.
Pricing Analysis
Volume placements concentrate in acylthioesters serving polymer stabilization, while aromatic thioesters for peptide synthesis command substantial premia. Three-tier pricing structure across pharmaceutical, food-grade, and industrial certifications separates margin capture, with ISO-certified manufacturing and REACH registration status as primary price differentiation drivers. Cost compression in industrial grades is intensifying because mercaptan precursor volatility feeds through from crude oil derivatives. Tire manufacturers in China exhibit highest price sensitivity, whereas CDMOs sourcing pharmaceutical intermediates prioritize purity specifications over unit economics.
Supply Chain Analysis
Thioester supply rests on German and Japanese specialty chemical producers for pharmaceutical-grade output, Chinese manufacturers for polymer stabilizer volumes, and Indian blenders for food-grade premixes. Mercaptan feedstocks, phenolic precursors, and sulfur derivatives anchor raw material dependencies. Single-source vulnerability concentrates in European REACH-registered suppliers for high-purity aromatic grades. Distribution runs through direct sales relationships with tier-one tire and food manufacturers, supplemented by regional distributors serving mid-tier rubber processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over phenolic chemistry and mercaptan supply determines margin sustainability across antioxidant grades.
For Market Incumbents: Cement supply security through captive mercaptan production or long-term offtake agreements with Gulf Coast petrochemical operators. Expand ISO-certified capacity in Ludwigshafen or Leverkusen to capture REACH-driven supplier consolidation. Natural tocopherol substitution in clean-label food segments threatens volume positions; respond with alkylthioester reformulation investments. For New Entrants and Emerging Players: FSSAI tightening in India opens a window for localized blending operations serving Maharashtra and Gujarat edible oil refiners. Target pharmaceutical intermediate white space where CDMO demand for peptide synthesis outstrips aromatic thioester supply. Pursue microreactor technology licensing from German or Japanese engineering partners to bypass batch-scale capital barriers. For Investors and Strategic Acquirers: ECHA substance evaluation protocol extensions are the leading indicator that registration asset values will appreciate as timelines lengthen and data costs escalate. Focus acquisition screening on mid-cap European producers with validated REACH dossiers and existing pharmaceutical-grade certifications. Watch for SAMR GB standard harmonization signals as the trigger for Chinese food-grade supply consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mercaptan Supply | Gulf Coast petrochemical corridor access insulates margin from crude derivative volatility. |
| Microreactor Technology Licensing | German and Japanese engineering partners enable pharmaceutical-grade output without dedicated plant investments. |
| REACH Registration Asset Acquisition | ECHA-validated toxicological dossiers appreciate as evaluation timelines extend and data costs rise. |
| Localized Blending Operations in India | FSSAI contaminant limits on imports create captive demand from Maharashtra and Gujarat processors. |
| Alkylthioester Reformulation Investment | Clean-label food preservation trends in Europe and North America propel faster-expanding synthetic antioxidant category. |
Study Parameters
Document review covered customs and trade data, SEC filings from antioxidant producers, and ECHA registration databases, complemented by interviews with plant managers at polymer stabilizer facilities, procurement leads at tire manufacturers, technical R&D directors in specialty chemical divisions, and distribution channel partners serving Southeast Asian edible oil processors. Secondary validation drew from ACC and Cefic industry reports, SAMR GB standard publications, and FSSAI regulatory notifications. Bottom-up volume modeling triangulated against top-down value projections across product chemistry and end-use segments.
Historical consumption patterns cross-referenced against expert panel input on REACH enforcement intensity and tire production forecasts shaped the analytical framework across the analysis window. Segmentation dimensions modeled include thioester chemistry type, certification grade tier, end-use industry, physical form, and regional production hub. CAGRs derived from slope-log regression on normalized volume data, with specific inputs for radial tire specification tightening in China and clean-label antioxidant substitution rates in European food processing.
The model assumes a particular technology adoption path for continuous flow reactor systems; alternative pathways for batch-scale pharmaceutical-grade production would alter the outlook for capital intensity and supplier concentration. Forecasts reflect assumptions on regulatory divergence persistence and feedstock cost trajectories. A small set of triggers—SAMR-EU regulatory harmonization, natural antioxidant cost parity breakthroughs, and ECHA substance restriction list expansions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Triisobutyl Phosphate Market
Chemical Intermediates
Japan Formic Acid Market
Chemical Intermediates
Ph Controlling Agents Market
Chemical Intermediates
Epoxy Silanes Market
Chemical Intermediates
Tertiary Butylhydroquinone Acids Market
Chemical Intermediates
Global Biochemical Reagents Market
Chemical Intermediates
Palmitoyl Chloride Market
Chemical Intermediates
Bromate Substitute Market
Chemical Intermediates
Global Chemical Intermediates Market
Chemical Intermediates
Cytosine Market
Chemical Intermediates
Carboxylic Acid Chlorides Market
Chemical Intermediates
9-Decanoic Acid Methyl Ester Market
Chemical Intermediates
Preformulation Intermediates Market
Chemical Intermediates
Hydroxyisobutyric Acid Market
Chemical Intermediates
Penicillin Intermediate Market
Chemical Intermediates
Tetrahydrocurcumin Reagent Market