
 Sequencing Reagents Market | 2026-2036
Sequencing Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Sequencing Reagents Market Intelligence
Demand from diagnostic laboratories and pharmaceutical companies is rotating away from a singular focus on academic research institutes. Illumina leverages its vast installed base of sequencing systems, creating a significant reagent annuity stream. Thermo Fisher Scientific competes with a broad portfolio of instruments and associated consumables. Oxford Nanopore Technologies plc differentiates with its unique long-read, real-time sequencing platform, opening up novel field-based applications.
Sequencing reagents are the chemical consumables essential for determining the order of nucleotides in a DNA or RNA molecule. These kits typically include high-purity nucleotides, specific enzymes like polymerases, and optimized buffers to control reaction conditions such as pH and ionic strength. While reagents for Next-Generation Sequencing constitute the largest market segment by volume, consumables for Nanopore Sequencing are expanding rapidly. Applications in pharmacogenomics and oncology diagnostics command higher margins compared to general research use.
Regulatory frameworks from the US FDA and the European Medicines Agency dictate standards for reagents used in clinical diagnostics. China's NMPA also enforces strict approval processes for in-vitro diagnostic kits, shaping market access for foreign and domestic manufacturers. These regulations mandate rigorous quality control and validation for any reagent intended for patient care. Future vendor success depends on navigating these complex international regulatory pathways for clinical-grade products.
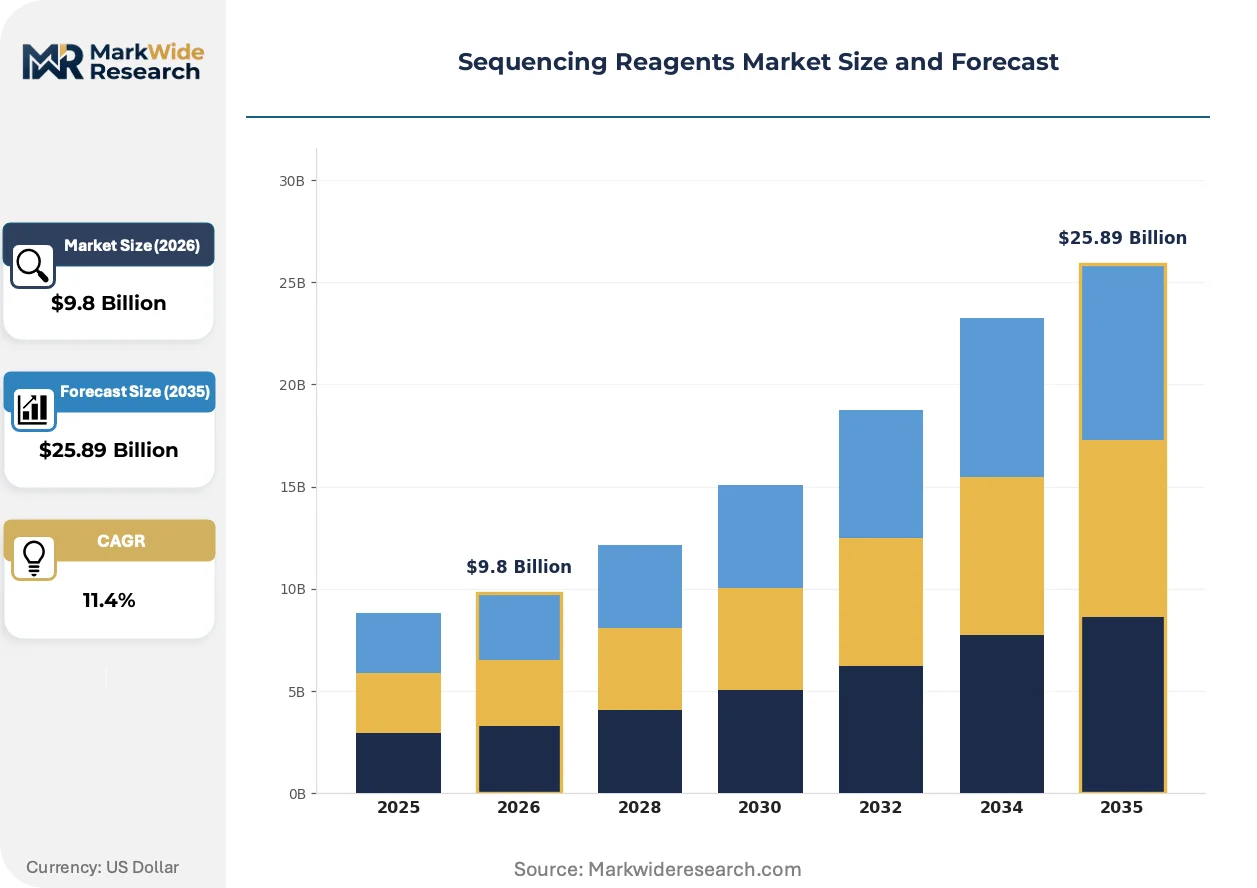
Market Dynamics
The fundamental shift from academic research to clinical diagnostics is the central force shaping the sequencing reagents market. Demand from pharmacogenomics and oncology applications, which require validated, high-margin consumables, is redefining vendor strategies and regulatory priorities across the industry.
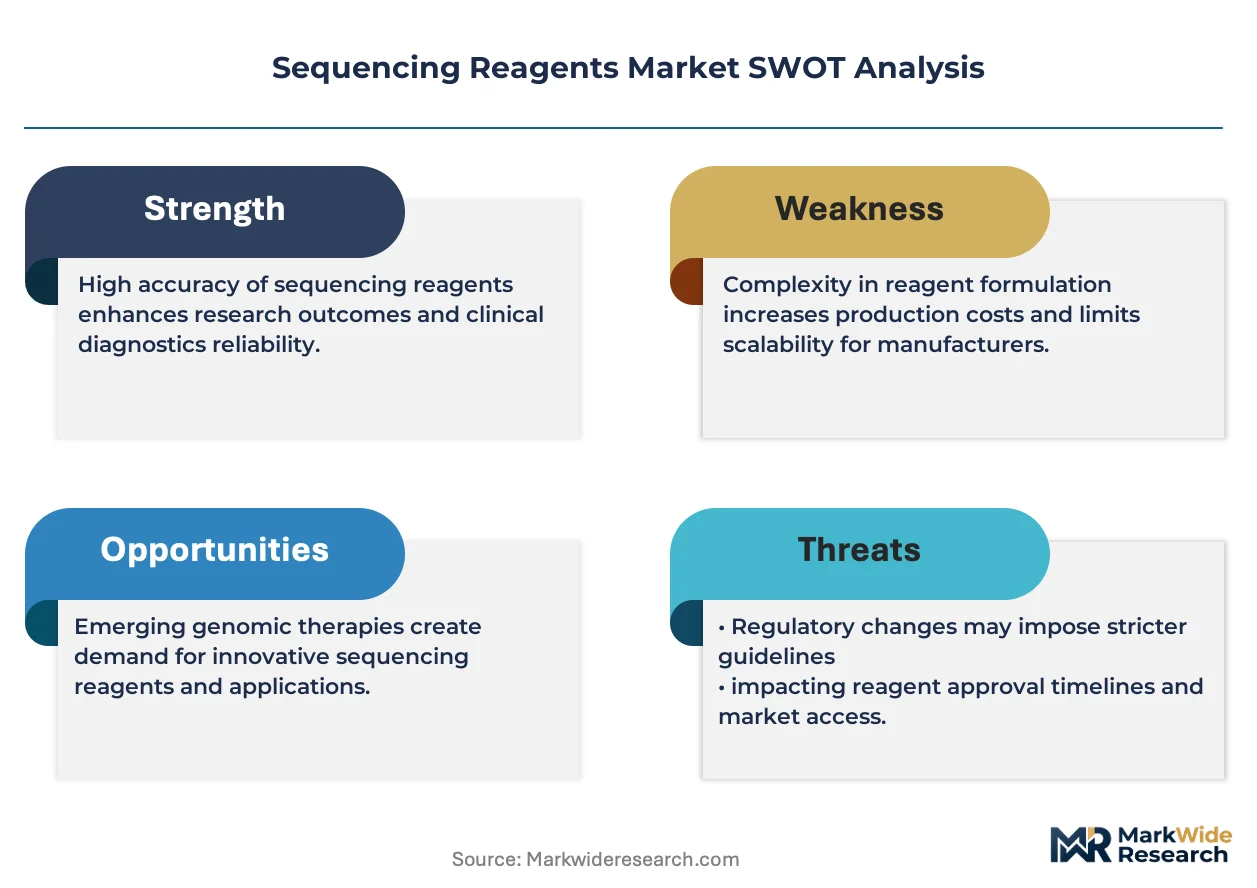
Growth Catalysts
- Nanopore Technology Advancement:Continuous improvements in the accuracy and throughput of Nanopore Sequencing are unlocking novel applications in real-time pathogen surveillance and field-based genomics, expanding the addressable market beyond traditional laboratories.
- National Genomics Initiatives:Substantial government investment in precision medicine programs, such as those in the United States, China, and Germany, provides significant public funding for large-scale sequencing projects, directly boosting reagent consumption.
- Clinical Application Expansion:The growing use of sequencing in clinical oncology for tumor profiling and in pharmacogenomics for predicting drug response creates a recurring, high-value demand stream from diagnostic laboratories and pharmaceutical companies.
Market Restraints
- High Input Costs:The manufacturing of reagent kits relies on high-purity enzymes, polymerases, and nucleotides, whose production costs remain elevated, placing a floor on final product pricing and constraining margin expansion.
- Reagent Stability and Logistics:Many essential sequencing reagents require stringent cold-chain logistics to maintain stability and efficacy, increasing shipping costs and limiting accessibility in regions with underdeveloped infrastructure.
- Complex Regulatory Hurdles:Obtaining approvals for clinical diagnostic reagents from bodies like the US FDA, the EMA in Europe, and China's NMPA involves lengthy and expensive validation processes, acting as a significant barrier to entry.
Strategic Opportunities
- Ambient Temperature-Stable Reagents:Developing lyophilized or chemically stabilized reagents that do not require a cold chain opens significant opportunities for field-based sequencing in agriculture, environmental monitoring, and point-of-care diagnostics.
- Expansion in Agrigenomics:The application of sequencing for crop improvement, livestock breeding, and soil microbiome analysis represents a large, underpenetrated commercial sector with distinct reagent requirements compared to human genomics.
- Diagnostic Kit Development for Infectious Diseases:Creating rapid, sequencing-based diagnostic kits for a wide range of infectious diseases offers a major growth avenue, particularly for public health surveillance in emerging economies.
Industry Challenges
- Cross-Platform Standardization:A persistent lack of standardization in reagent formulations and data output formats across different sequencing platforms creates interoperability challenges for laboratories using instruments from multiple vendors.
- Bioinformatics Skill Gap:The volume and complexity of data generated by modern sequencers outpace the availability of bioinformaticians skilled in data analysis and interpretation, limiting the effective utilization of advanced sequencing capabilities.
- Navigating Global IVD Regulations:Manufacturers face the operational challenge of aligning product development and quality management systems to meet the disparate and evolving in-vitro diagnostic regulations of the US, EU, and China.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sequencing Reagents Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $25.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nucleotides, Primers, Enzymes, Buffers, Adaptors, Probes Technology: Next-Generation Sequencing, Sanger Sequencing, Pyrosequencing, Sequencing by Synthesis, Nanopore Sequencing, Single Molecule Real Time Application: Genetic Disease Research, Agricultural Genomics, Forensic Analysis, Microbial Genomics, Epigenetic Studies, Pharmacogenomics End User: Academic Research Institutes, Pharmaceutical Companies, Biotechnology Firms, Diagnostic Laboratories, Contract Research Organizations, Agricultural Research Centers |
| Companies Covered | F. Hoffmann-La Roche Ltd, PacBio, Illumina, Inc., Integrated DNA Technologies, Inc., Agilent Technologies, Inc., Thermo Fisher Scientific Inc., Oxford Nanopore Technologies plc, Takara Bio Inc., QIAGEN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sequencing Reagents Market Strategic Shifts & Innovations
Automation and the integration of liquid handling robotics are transforming reagent utilization. This evolution moves sequencing from a series of manual benchtop tasks toward a streamlined, high-throughput workflow, minimizing human error and improving reproducibility in clinical and pharmaceutical settings.
Long-read sequencing reagents provide the consumables needed to determine nucleotide order over much longer stretches of DNA than traditional methods. Clinical research laboratories and public health organizations focused on genomic surveillance are adopting these technologies at a swift pace. For applications like complex genome assembly and identifying large structural variations, long-read sequencing is supplanting older short-read methods that struggle with these specific analytical tasks.
The European Union's In Vitro Diagnostic Regulation (IVDR) has introduced a significantly more stringent regulatory framework. Its implementation mandates that all diagnostic reagents, including those used in laboratory-developed tests, provide extensive clinical evidence and undergo rigorous post-market surveillance. This change most profoundly affects academic and hospital labs that previously operated under less strict rules, forcing them to either partner with commercial manufacturers or invest heavily in regulatory compliance.
A pronounced shift in purchasing behavior sees end-users favoring integrated, platform-specific consumable systems over individual, open-market components. This model disrupts the market for standalone enzymes and buffers by creating a recurring revenue stream tied to a vendor's instrument installed base. The trend is most visible in high-volume clinical labs in the United States and Germany, where workflow simplification, result standardization, and vendor support are valued over component-level price optimization.
Sequencing Reagents Market Segmentation
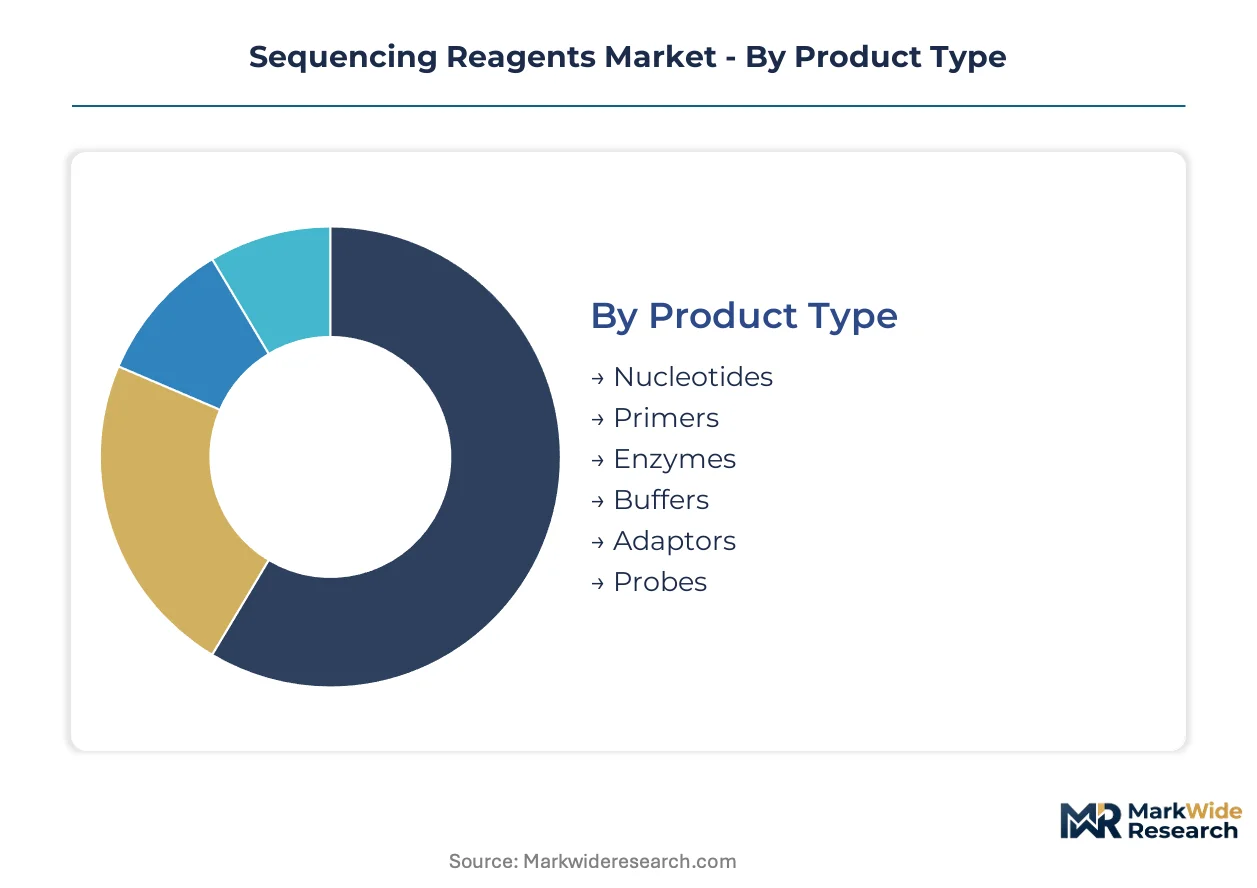
The sequencing reagents market segments across diverse product types, technologies, applications, and end-users, each presenting unique demand drivers and procurement dynamics. Understanding these distinctions is critical for manufacturers to align product development and commercial strategies with evolving industry needs.
Product Type:
The composition of sequencing reagent kits dictates their distribution channels, with high-purity components often sourced directly from specialized chemical manufacturers.
- Nucleotides:These are the fundamental building blocks of DNA and RNA, essential for all sequencing chemistries. Large-scale genomics initiatives in the United States and China require vast quantities of high-purity nucleotides for their research and clinical programs.
- Enzymes:Polymerases are critical for DNA synthesis and amplification in sequencing reactions, ensuring accurate template replication. Demand for high-fidelity enzymes concentrates in clinical diagnostics and pharmaceutical research, driven by the need for precise variant detection.
- Primers:Short oligonucleotide sequences initiate DNA synthesis, crucial for targeted sequencing and polymerase chain reaction-based methods.
- Buffers:Optimized solutions maintain pH and ionic strength, ensuring enzyme activity and reaction stability across diverse sequencing platforms.
- Adaptors:Short DNA sequences facilitate library preparation and attachment to sequencing platforms, particularly for Next-Generation Sequencing workflows.
- Probes:Labeled oligonucleotides enable specific target detection and quantification, vital for advanced diagnostic applications and gene expression studies.
Nucleotides dominate the installed base due to their universal requirement. Adaptors are where expansion concentrates, driven by evolving library preparation methods.
Technology:
Sequencing technologies differ significantly in their throughput and data output, directly influencing the volume of reagents consumed per run.
- Next-Generation Sequencing:This high-throughput technology processes millions of DNA fragments in parallel, generating massive data volumes. Demand for NGS reagents concentrates in large diagnostic laboratories and academic research centers globally, propelled by decreasing sequencing costs.
- Nanopore Sequencing:This real-time, long-read technology offers portability and rapid results, allowing for field-based applications. Its reagents are gaining traction in infectious disease surveillance and environmental monitoring in regions like Africa and Southeast Asia.
- Sanger Sequencing:This first-generation method remains essential for validating NGS results and sequencing individual genes, particularly in small-scale research settings.
- Pyrosequencing:This technique detects DNA sequence variations by measuring light emitted during DNA synthesis, used in specific genotyping applications.
- Sequencing by Synthesis:A core principle in many NGS platforms, this method involves detecting nucleotide incorporation in real-time, requiring specialized reagents.
- Single Molecule Real Time:This long-read technology sequences individual DNA molecules in real-time, valuable for complex genome assembly and epigenetic analysis.
Next-Generation Sequencing reagents hold the largest market share. Nanopore Sequencing reagents are expanding most quickly.
Application:
Different sequencing applications command varying reagent margins, with clinical and diagnostic uses typically yielding higher profitability.
- Pharmacogenomics:This application studies genetic variations influencing drug response, driving demand for highly validated reagents in pharmaceutical R&D and clinical trials. Its adoption is significant in precision medicine initiatives in the United States and Europe.
- Genetic Disease Research:This segment involves identifying genetic mutations linked to inherited disorders, requiring broad-spectrum sequencing reagents for variant detection. Academic institutions and specialized diagnostic labs contribute to this demand.
- Agricultural Genomics:Sequencing reagents support crop improvement and livestock breeding programs, particularly in major agricultural economies like Brazil and India.
- Forensic Analysis:DNA sequencing aids in criminal investigations and human identification, demanding robust and contamination-resistant reagents for crime labs.
- Microbial Genomics:This application analyzes microbial DNA for pathogen identification and microbiome studies, crucial for public health and environmental monitoring.
- Epigenetic Studies:Reagents for epigenetic sequencing investigate DNA modifications like methylation, important for understanding gene regulation in cancer research.
Pharmacogenomics applications drive high-value reagent consumption. Genetic Disease Research accounts for a significant volume of general-purpose reagents.
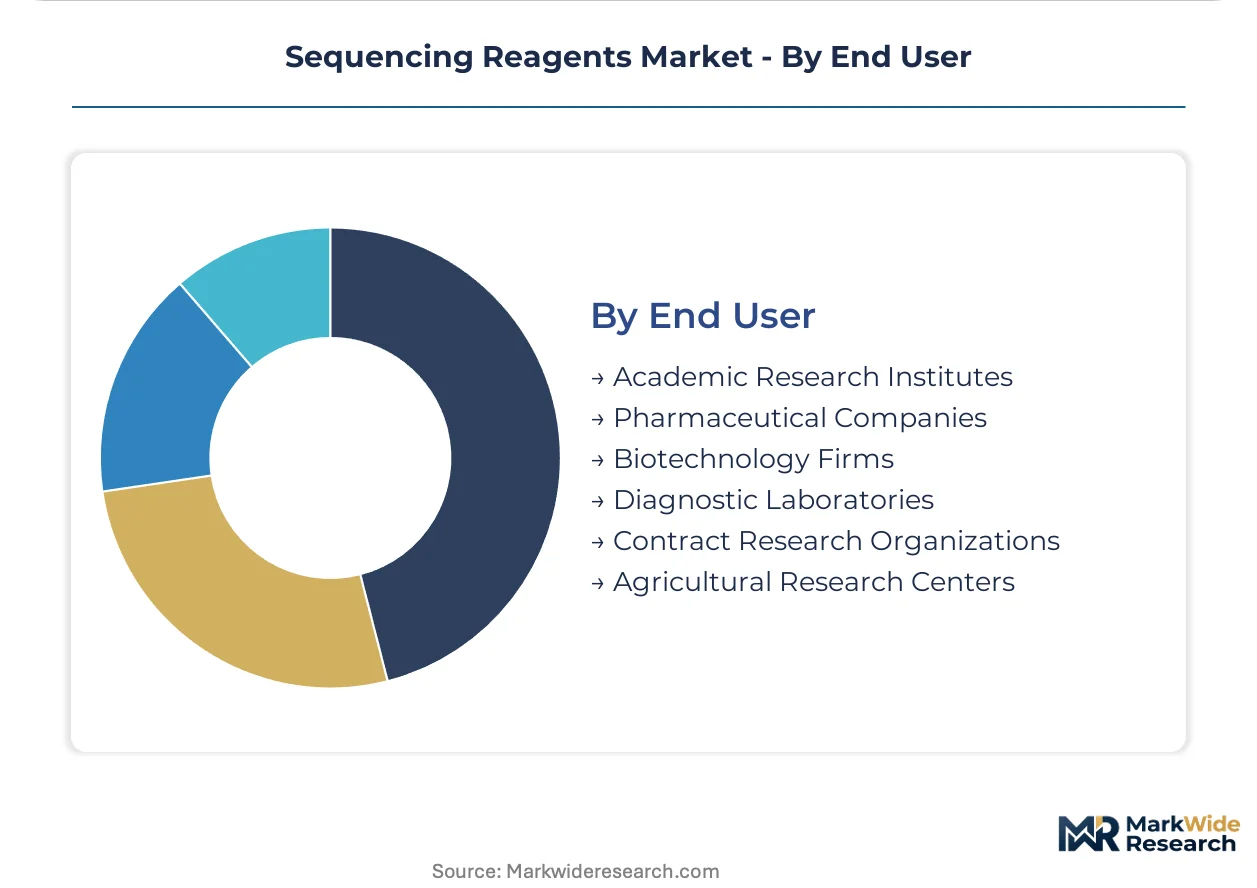
End User:
End-user segments exhibit distinct procurement patterns and regulatory requirements for sequencing reagents, influencing vendor sales strategies.
- Diagnostic Laboratories:These facilities use sequencing reagents for clinical testing, including oncology and infectious disease diagnostics. Demand here is driven by stringent regulatory compliance and the need for high-throughput, validated assay kits.
- Pharmaceutical Companies:These firms utilize sequencing reagents for drug discovery, pharmacogenomics research, and clinical trial support. Their procurement often involves long-term contracts for high-purity, consistent reagent supply.
- Academic Research Institutes:These institutions represent a foundational market for sequencing reagents, supporting basic and translational genomics research projects.
- Biotechnology Firms:These companies develop novel sequencing applications and technologies, consuming reagents for R&D and product validation.
- Contract Research Organizations:CROs provide outsourced research services to pharmaceutical and biotechnology clients, driving reagent consumption for diverse experimental workflows.
- Agricultural Research Centers:These centers apply sequencing to improve crop yields and livestock health, focusing on specialized reagents for non-human genomics.
Diagnostic Laboratories are becoming the largest consumers of clinical-grade reagents. Pharmaceutical Companies are projected to show sustained growth in high-value applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized sequencing reagents often flow from established manufacturing centers to high-demand clinical and research markets. The global supply chain for these critical consumables is increasingly sensitive to regional investment in genomics. Key demand corridors connect major biotech hubs to national precision medicine initiatives.
United States
The United States market for sequencing reagents is shaped by significant demand from pharmacogenomics and clinical oncology applications. US FDA regulations dictate stringent quality standards for clinical-grade diagnostic reagents. Major biotech clusters in Boston and the San Francisco Bay Area drive innovation in sequencing technologies and reagent development.
China
China's substantial national genomics initiatives propel demand for high-volume sequencing reagents. The NMPA enforces strict approval processes for in-vitro diagnostic kits, impacting market access. Large-scale sequencing projects in the Yangtze River Delta and Pearl River Delta consume vast quantities of consumables.
Germany
Germany's robust precision medicine programs and advanced clinical diagnostics drive consistent demand for sequencing reagents. European Medicines Agency guidelines and the EU IVDR establish stringent regulatory frameworks for clinical applications. Research hubs in Munich and Heidelberg are centers for advanced genomic studies and reagent consumption.
Japan
Japan exhibits strong demand for sequencing reagents, particularly in genetic disease research and pharmaceutical R&D. The PMDA regulates the approval of in-vitro diagnostic reagents, ensuring product quality. Major research centers in Tokyo and Osaka focus on advanced genomic analysis and precision medicine applications.
United Kingdom
The United Kingdom's significant investment in genomic surveillance and clinical research supports reagent consumption. The MHRA oversees regulatory compliance for diagnostic reagents used in patient care. Leading genomic research institutes in Cambridge and Oxford are central to the country's sequencing activities.
Sequencing Reagents Market Key Industry Players
Player mix skews toward established life science conglomerates and specialized technology innovators. The market structure features a tiered landscape, with a few dominant players alongside numerous niche providers focusing on specific sequencing chemistries. Strategic archetypes include integrated platform providers, broad-portfolio suppliers, and disruptive technology specialists. Companies pursue portfolio diversification and strategic partnerships to expand their clinical footprint and navigate complex regulatory pathways.
Within the integrated platform tier, Illumina, Inc. occupies a significant position, anchoring a substantial reagent annuity stream through its vast installed base of sequencing systems. This structure creates strong customer loyalty and recurring revenue. Thermo Fisher Scientific Inc. exemplifies a broad-portfolio supplier, offering a comprehensive suite of instruments and associated consumables across diverse applications and end-user segments. Their strategy emphasizes market breadth and solution integration. Oxford Nanopore Technologies plc represents a disruptive technology specialist, differentiating with its unique long-read, real-time sequencing platform for novel field-based applications and real-time pathogen surveillance. Such specialists often drive market expansion into previously unaddressed areas.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| PacBio |
| Illumina, Inc. |
| Integrated DNA Technologies, Inc. |
| Agilent Technologies, Inc. |
| Thermo Fisher Scientific Inc. |
| Oxford Nanopore Technologies plc |
| Takara Bio Inc. |
| QIAGEN |
| Others |
Cost & Logistics Intelligence
US FDA, EMA, and China's NMPA regulatory regimes gate both supply qualification and price differentiation for sequencing reagents. These frameworks mandate rigorous validation for clinical-grade products, allowing manufacturers to command premium pricing for validated kits compared to research-grade consumables.
Pricing Analysis
Next-Generation Sequencing reagents maintain a higher price point compared to older Sanger Sequencing consumables, reflecting advanced technology and higher throughput. Contract-based long-term offtake agreements dominate for pharmaceutical companies, ensuring consistent supply. Price differentiation stems from regulatory approval status, reagent purity grade, and instrument platform compatibility. Pricing softness affects general research reagents due to commoditization and increased competition. Academic research institutes exhibit the highest price sensitivity, while pharmaceutical companies prioritize reliability and validation over cost.
Supply Chain Analysis
Strategic stockpiles are common for critical sequencing reagents due to cold-chain requirements and the need for uninterrupted supply in diagnostic laboratories. Supply concentration for high-purity enzymes and nucleotides centers in the United States, Germany, and China. Raw material dependencies include specialized polymerases, high-purity deoxynucleotides, and optimized buffers. Cold-chain logistics chokepoints and regional infrastructure limitations pose a structural supply chain risk. Distribution runs through direct sales channels for integrated sequencing systems and specialized distributors for individual components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sequencing reagents market presents a capability gap in navigating complex global regulatory pathways for clinical-grade products. This expertise scarcity affects both established players and new entrants seeking to expand into high-margin diagnostic applications.
For Market Incumbents:Compound existing installed bases by offering comprehensive service contracts that include reagent supply and bioinformatics support. This strategy mitigates competitive threats from disruptive Nanopore sequencing platforms. Deepen vertical integration into the production of high-purity enzymes and specialized nucleotides. Invest in robust clinical validation services to streamline regulatory approvals for new diagnostic kits.
For New Entrants and Emerging Players:Lead with novel ambient temperature-stable reagents, targeting field-based genomics applications in regions with underdeveloped cold-chain infrastructure. Focus on agrigenomics as an underpenetrated commercial sector with distinct reagent requirements. Penetrate emerging economies by offering rapid, sequencing-based diagnostic kits for infectious diseases. A go-to-market angle emphasizing open-source data analytics tools can reduce adoption barriers.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upward across the clinical diagnostics segment, driven by stringent regulatory compliance and validation costs. Long-term viability over the next decade favors companies with established regulatory expertise and validated product pipelines for clinical use. Acquire niche specialists in long-read sequencing chemistries or developers of regulatory-compliant in-vitro diagnostic kits. Uptake of sequencing-based infectious disease diagnostics serves as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway Acceleration | Expedites market access for clinical diagnostic reagents, particularly under EU IVDR and US FDA guidelines. |
| Platform Integration with Automation | Enhances workflow efficiency and reduces human error for high-throughput diagnostic laboratories. |
| Manufacturing Scale-Up for High-Purity Inputs | Secures consistent supply of critical enzymes and nucleotides, mitigating raw material dependencies. |
| Strategic Partnerships for Bioinformatics | Addresses the bioinformatics skill gap, enabling better data interpretation and utilization of sequencing capabilities. |
| Pipeline Diversification into Agrigenomics | Unlocks new revenue streams by addressing specialized reagent needs in crop and livestock improvement. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to build a comprehensive view of the market. This involved primary interviews with diagnostic lab directors, pharmaceutical R&D leads, genomics core facility managers, and regulatory affairs specialists. Secondary validation drew from US FDA guidance documents, European Medicines Agency public assessments, China's NMPA approval databases, and academic genomics publications. The analysis employed both bottom-up and top-down triangulation methods.
The analytical framework spans across the analysis window, projecting market trends and dynamics. Segmentation dimensions modeled include product type, technology, application, end-user, and regional regulatory compliance. Compound annual growth rates were derived from historical data trends and projected adoption rates for new sequencing technologies. Public health genomics funding and pharmaceutical R&D spending served as key industry-specific forecast inputs.
Underlying assumptions cover technological advancements and regulatory stability, with deviation risk concentrated in unforeseen pandemic events or major shifts in national genomics funding. Revision becomes warranted when significant changes in clinical trial success rates or in-vitro diagnostic approval timelines cross predefined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Global Electrophoresis Reagents Market
Chemical Intermediates
API Intermediate Market
Chemical Intermediates
Myristoyl Chloride Market
Chemical Intermediates
Dye Intermediates Market
Chemical Intermediates
Ethylene Urea Market
Chemical Intermediates
Enzyme Substrates Market
Chemical Intermediates
Global Iron Chelates Market
Chemical Intermediates
Elemental Formula Market
Chemical Intermediates
Global Biochemical Reagents Market
Chemical Intermediates
Methoxypropylamine (MOPA) Market
Chemical Intermediates
Tertiary Amines Market
Chemical Intermediates
1, 3, 5-Triazine Market
Chemical Intermediates
Lauoryl Chloride Market
Chemical Intermediates
Acetamide MEA Market
Chemical Intermediates
Montelukast Intermediate Market
Chemical Intermediates
Japan Formic Acid Market