
 Pigment Intermediates Market | 2026-2036
Pigment Intermediates Market Size, Share, and Industry Trends Forecast 2026-2036
Pigment Intermediates Market Outlook
Automotive coatings demand is restructuring procurement patterns across the pigment intermediates value chain as OEMs shift toward waterborne and high-performance color systems. Huntsman Corporation leverages its integrated intermediates-to-dyes pipeline to anchor supply security for automotive tier-one formulators. Clariant AG specializes in phthalocyanine chemistry leadership, while Sudarshan Chemical Industries Limited dominates azo intermediate production serving Asian packaging converters.
Pigment intermediates are chemical precursors—typically nitroaromatics, anilines, or phthalonitriles—that undergo diazotization, condensation, or metallization to yield colorants with defined lightfastness, thermal stability, and dispersibility specifications; they serve as the controlled-cost foundation for downstream pigments in coatings, plastics, and printing applications. Phthalocyanine pigments command premium positioning due to copper-complex purity requirements and limited qualified feedstock sources. Azo pigments occupy volume leadership across textile and packaging applications where cost sensitivity outweighs extreme durability demands.
REACH in Europe, EPA toxics release rules in the United States, and China's MEE emission standards are collectively restricting chlorinated and heavy-metal-containing intermediate chemistries, redirecting R&D investment toward bio-based coupling components and closed-loop nitro reduction. India's BIS certification requirements for imported dye intermediates are tightening quality gates for cross-border suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and reformulation costs.
Market Dynamics
Automotive OEMs are consolidating supplier bases around waterborne coating systems that demand higher-purity phthalocyanine and azo intermediates with tighter batch-to-batch consistency, compressing qualification timelines and favoring integrated manufacturers over merchant traders.
Growth Catalysts
- REACH authorization timelines:ECHA's sunset dates for chromium-based pigments are accelerating reformulation demand for copper phthalocyanine alternatives in European industrial coatings.
- India's packaging export expansion:Gujarat and Maharashtra textile-to-packaging clusters are absorbing record volumes of azo intermediates for food-grade flexible printing.
- Continuous nitro reduction:Fixed-bed catalytic hydrogenation is replacing batch iron-acid reduction, cutting wastewater generation and qualifying plants for China's MEE emission permits.
Market Restraints
- Copper phthalonitrile concentration:Three integrated producers control qualified feedstock for high-purity phthalocyanine pigments, creating supply vulnerability.
- Chlorinated solvent restrictions:EPA toxics release inventory rules and REACH annex XVII listings are eliminating dichlorobenzene-based synthesis routes for legacy azo intermediates.
- Natural gas price volatility:Nitro reduction hydrogen feedstock costs fluctuate with European TTF and Asian JKM benchmarks, compressing merchant producer margins.
Strategic Opportunities
- Bio-based coupling components:Fermentation-derived naphthol alternatives from agricultural waste streams qualify for EU Green Deal procurement preferences.
- Indonesia's emerging coatings demand:Batam and Cilegon industrial zones lack qualified local intermediate supply, creating import substitution potential.
- Closed-loop metallization:Solvent recovery and copper recycling systems align with China's dual carbon goals and unlock MEE compliance certification.
Industry Challenges
- Process analytical chemistry talent:Real-time PAT implementation for continuous flow diazotization requires scarce hybrid chemist-engineer profiles.
- Legacy batch asset stranding:Converting iron-acid reduction trains to catalytic hydrogenation demands 18-24 month downtime windows that conflict with customer qualification schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pigment Intermediates Market |
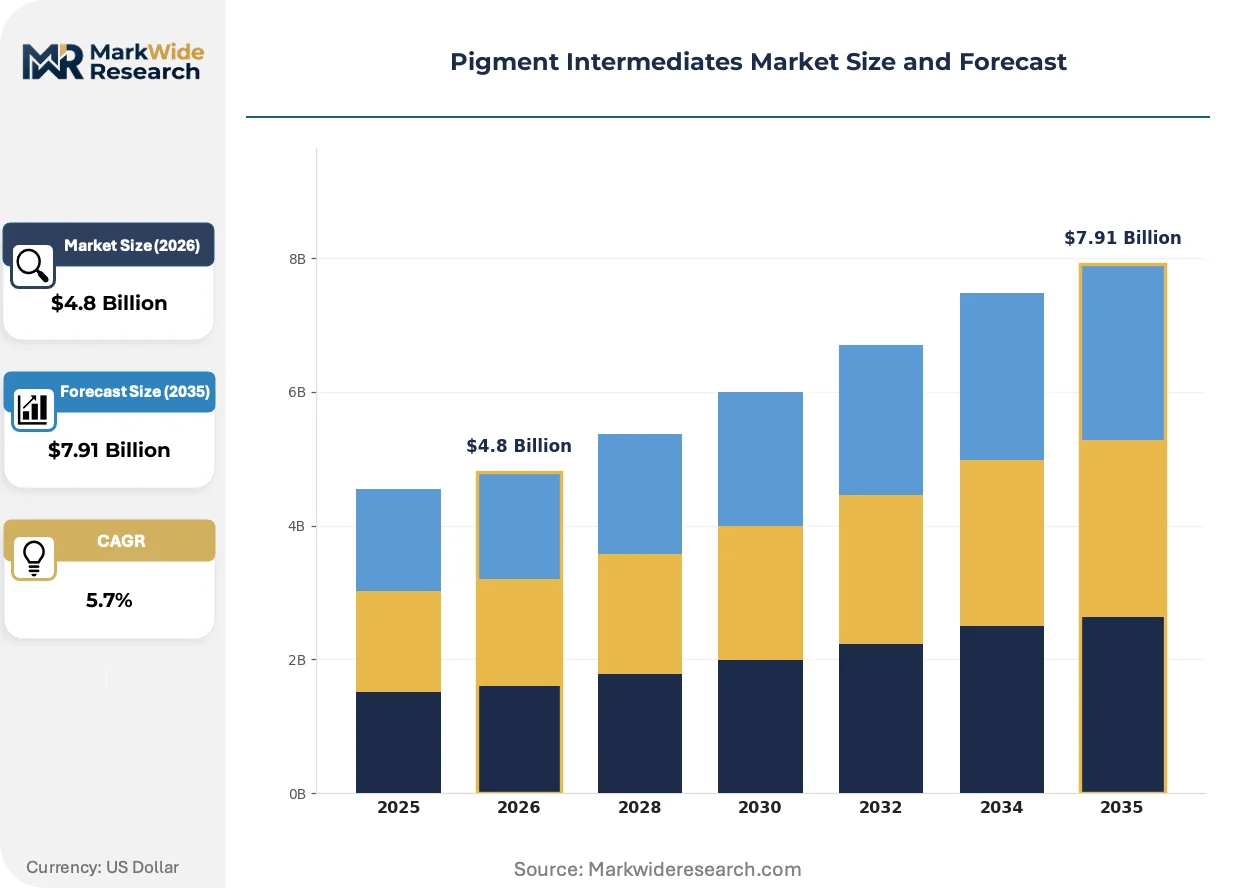
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Azo Pigments, Phthalocyanine Pigments, Inorganic Pigments, Organic Pigments Application: Coatings, Plastics, Textiles, Inks End User: Automotive, Construction, Consumer Goods, Packaging Form: Powder, Granules, Liquid, Paste |
| Companies Covered | Huntsman Corporation, Cabot Corporation, Kawaguchi Chemical Industry, Ambuja Intermediates Pvt Ltd, Atul Ltd., Clariant AG, Sudarshan Chemical Industries Limited, Nantong Acetic Acid Chemical, DIC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pigment Intermediates Market Strategic Shifts
Digital process control and regulatory chemistry constraints are converging to redefine how pigment intermediates are synthesized, qualified, and supplied to downstream formulators.
Continuous flow diazotization with inline spectroscopic monitoring is automating batch-to-batch consistency for azo coupling reactions. Tier-one automotive coating formulators in Germany and Japan are mandating this technology for new supplier qualification. The shift is compressing qualification timelines from 18 months to 6 months while disqualifying legacy batch operators.
REACH restriction proposals for per- and polyfluoroalkyl substances are extending to fluorinated surfactants used in pigment dispersion intermediates. ECHA's 2023 restriction roadmap is forcing reformulation of high-performance colorants for architectural coatings. Western European producers are accelerating bio-based dispersant development to maintain market access.
Direct mill integration contracts are replacing spot market purchases among large coating manufacturers. Formulators in China's Yangtze River Delta are demanding dedicated intermediate storage and just-in-time delivery from qualified suppliers. The model is most advanced in automotive OEM supply chains where inventory carrying costs have shifted upstream to intermediate producers.
Pigment Intermediates Market Segmentation
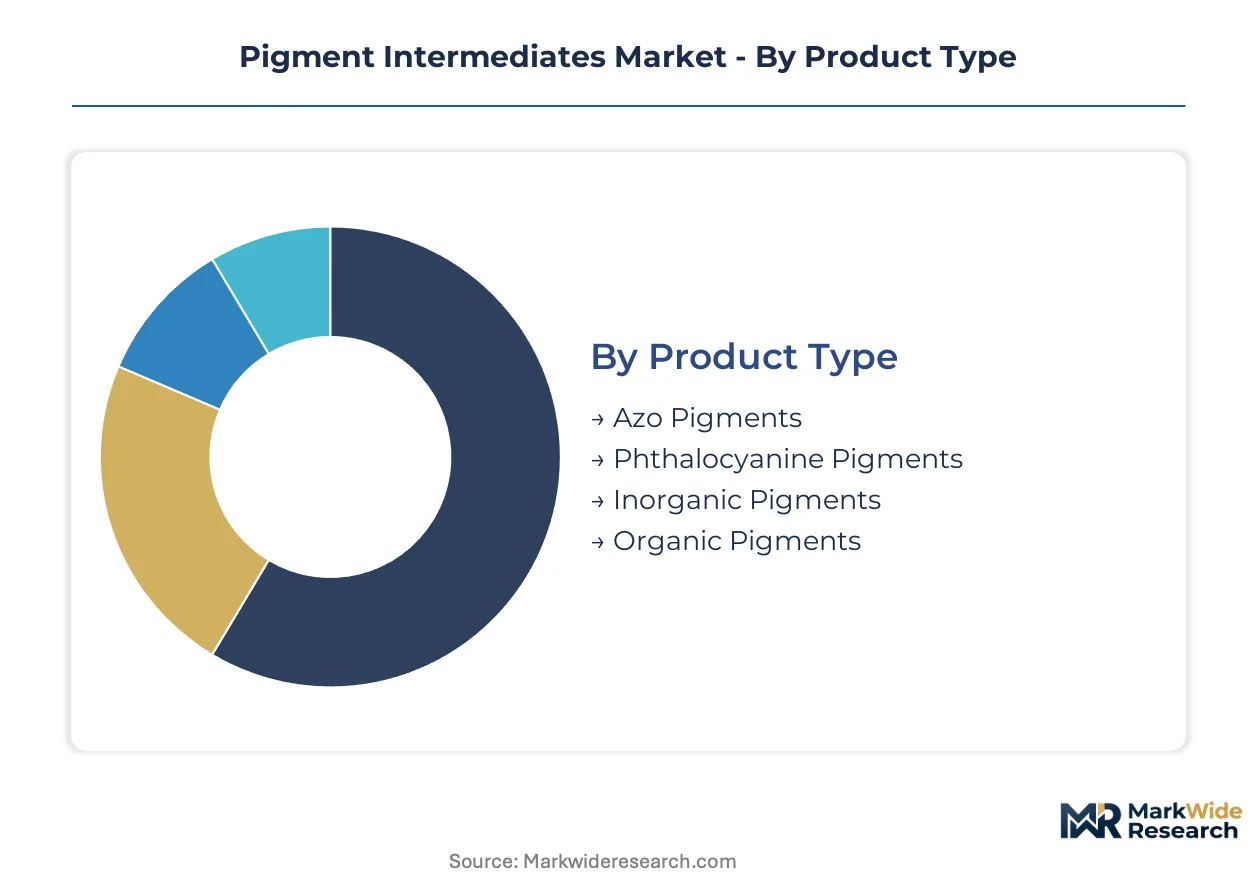
Pigment intermediates differentiate sharply by certification burden, with REACH-registered phthalocyanine precursors commanding distinct supply chains from textile-grade azo couplers. Automotive OEM qualification protocols and food-contact migration limits create tiered entry barriers across each segment axis.
Product Type:
REACH authorization timelines and ECHA sunset dates impose divergent compliance loads across chemistry families, with copper-complex feedstocks facing stricter substance evaluation than azo coupling components.
- Phthalocyanine Pigments:Copper phthalonitrile-derived intermediates require metallization-grade purity above 99.5% for automotive coating compatibility. German and Japanese OEMs mandate batch-level spectroscopic certification, compressing qualified supplier pools to integrated producers with captive nitrile synthesis.
- Azo Pigments:Diazotized aromatic amines and naphthol coupling components dominate textile and packaging volume. India's BIS certification for imported dye intermediates is tightening quality gates for cross-border suppliers serving Gujarat textile clusters.
- Inorganic Pigments:Chromium and cadmium precursor chemistries face REACH annex XVII restrictions accelerating substitution.
- Organic Pigments:High-performance colorant intermediates require specialized dispersibility specifications for engineering plastics.
Leading the category by volume: Azo Pigments. Expanding most quickly: Phthalocyanine Pigments.
Application:
Cost-to-performance ratios stratify procurement patterns, with automotive coatings absorbing premium intermediates and packaging converters optimizing for unit economics.
- Coatings:Waterborne automotive systems demand phthalocyanine intermediates with sub-50ppm ionic contamination. Tier-one formulators in Germany enforce continuous flow diazotization mandates, disqualifying legacy batch suppliers from qualification pipelines.
- Inks:Food-grade flexible printing drives azo intermediate absorption in Maharashtra and Gujarat export corridors. China's MEE emission permits favor producers with closed-loop nitro reduction, shifting supply toward catalytic hydrogenation operators.
- Plastics:Engineering polymer coloration requires thermal stability above 300°C, filtering intermediate specifications.
- Textiles:Conventional fiber dyeing tolerates broader intermediate quality bands, sustaining merchant trader participation.
Coatings command the steepest price premiums. Inks demonstrate the fastest volume climb.
End User:
Customer concentration and contract structures vary dramatically, with automotive consolidating around direct mill integration and construction remaining fragmented.
- Automotive:OEM consolidation around waterborne systems has compressed supplier qualification timelines from 18 months to 6 months. Huntsman Corporation anchors supply security through integrated intermediates-to-dyes pipelines, locking tier-one formulator relationships.
- Packaging:India's export-oriented flexible printing sector is absorbing record azo intermediate volumes. Yangtze River Delta converters demand dedicated storage and just-in-time delivery, shifting inventory carrying costs upstream.
- Construction:Architectural coatings tolerate broader intermediate specifications, sustaining spot market liquidity.
- Consumer Goods:Electronics and appliance coloration requires consistent batch-to-batch dispersibility.
Automotive leads by value concentration. Packaging gains share fastest.
Form:
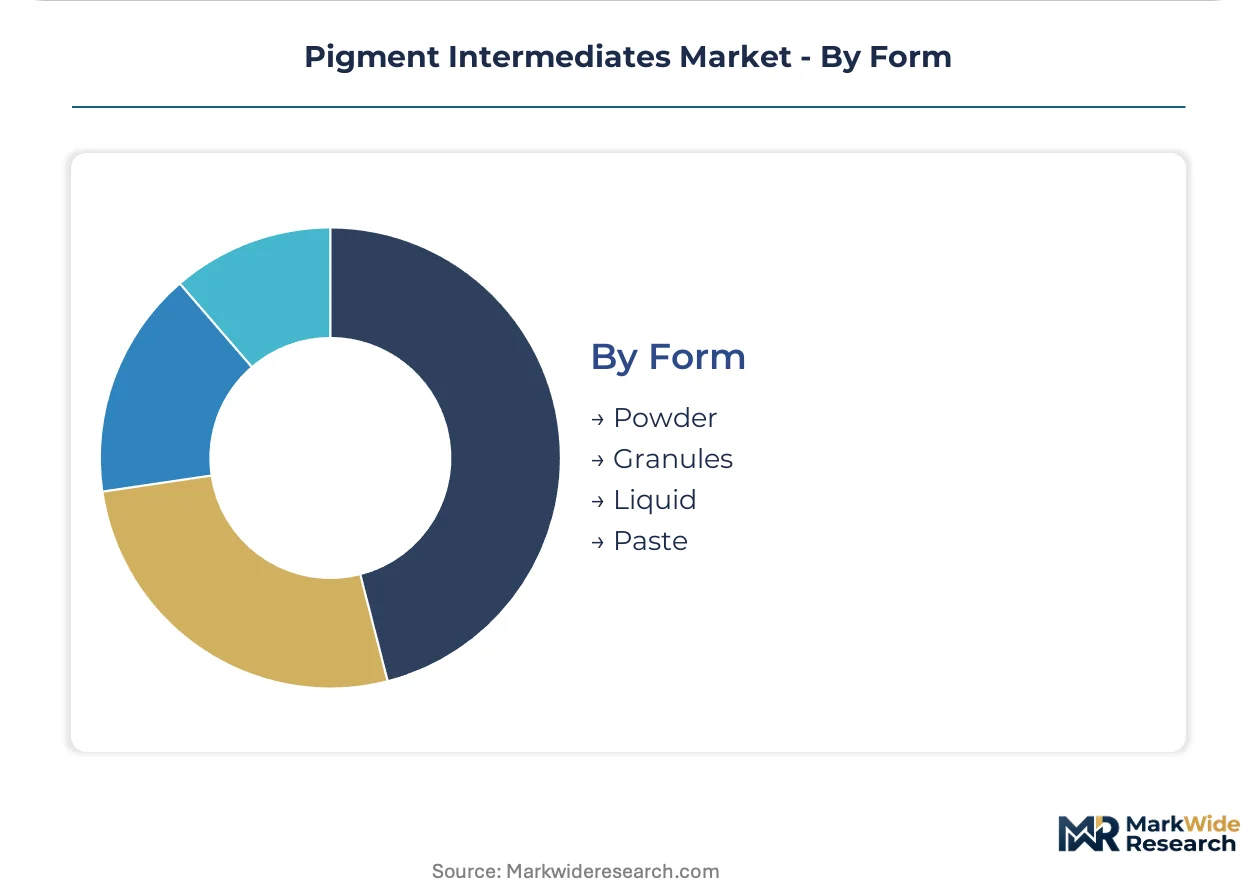
Handling characteristics and dust exposure regulations are redirecting investment toward low-dispersion formats in regulated jurisdictions.
- Powder:Standard crystalline intermediates face OSHA and REACH occupational exposure limits. European producers are accelerating granulation and liquid dispersion investments to maintain market access under tightening workplace safety rules.
- Liquid:Pre-dispersed concentrates eliminate dust handling and align with automated dosing systems in automotive coating plants. The format commands 15-20% price premiums but reduces downstream processing costs.
- Granules:Intermediate density formats balance flowability with reduced airborne particulate generation.
- Paste:High-solid dispersions serve specialized ink and coatings applications requiring immediate incorporation.
Powder retains volume leadership. Liquid climbs fastest on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces the majority of pigment intermediate tonnage while Germany and India absorb premium volumes for automotive and packaging applications. This production-consumption divide shapes cross-border trade flows and regulatory compliance investments across the value chain.
China
Yangtze River Delta coating clusters demand high-purity phthalocyanine intermediates for waterborne automotive systems. MEE emission permits favor producers with closed-loop nitro reduction and catalytic hydrogenation. Nantong and Shanghai industrial zones concentrate qualified suppliers serving German and Japanese OEM qualification pipelines.
Germany
Automotive OEMs in Baden-Württemberg and Bavaria mandate continuous flow diazotization for supplier qualification. ECHA sunset dates for chromium-based pigments accelerate copper phthalocyanine substitution in industrial coatings. Ludwigshafen and Leverkusen chemical corridors anchor integrated intermediates-to-pigments production.
India
Gujarat and Maharashtra textile-to-packaging clusters absorb record azo intermediate volumes for food-grade flexible printing exports. BIS certification requirements tighten quality gates for imported dye intermediates. Ankleshwar and Vapi industrial estates concentrate domestic production serving Asian packaging converters.
United States
EPA toxics release inventory rules eliminate dichlorobenzene-based synthesis routes for legacy azo intermediates. Automotive coating formulators in Michigan and Ohio consolidate supplier bases around waterborne systems. Gulf Coast petrochemical corridors supply hydrogen feedstock for nitro reduction operations.
Japan
METI industrial standards enforce sub-50ppm ionic contamination limits for phthalocyanine intermediates in automotive applications. Kansai and Chubu regions concentrate precision chemical production for electronics and coating colorants. Osaka-based formulators mandate inline spectroscopic certification for new supplier onboarding.
Pigment Intermediates Market Competitive Environment
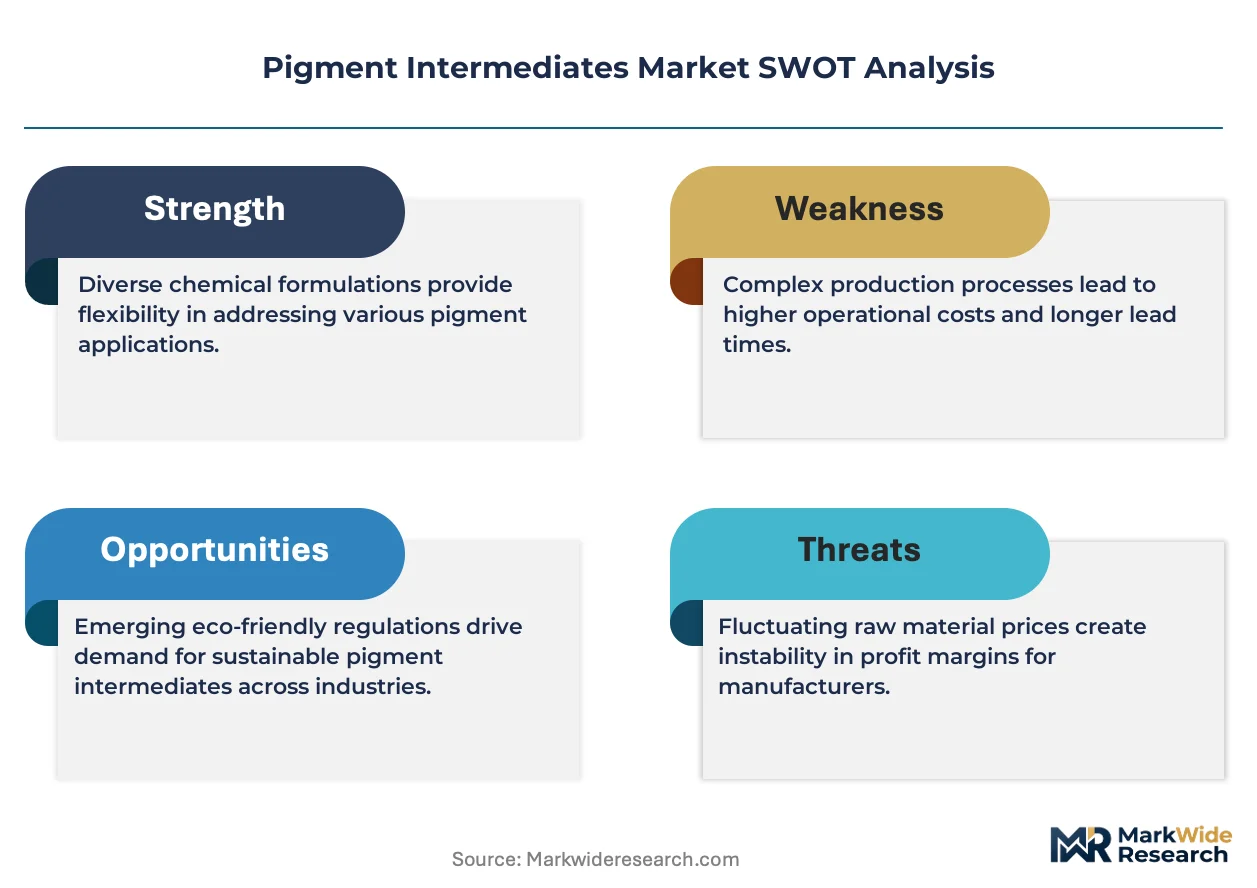
Top-tier vendors anchor integrated production, while merchant traders and regional specialists occupy fragmented niches. The market structures around three qualified producers controlling copper phthalonitrile feedstock and a broader tier of azo intermediate specialists. Strategic archetypes include backward-integrated chemical conglomerates, phthalocyanine purity specialists, and azo volume leaders serving packaging clusters. Competitive moves concentrate on qualification timeline compression and captive storage contracts with coating formulators.
Among integrated chemical producers, Huntsman Corporation and Clariant AG occupy positions exemplifying intermediates-to-pigments pipeline control. Sudarshan Chemical Industries Limited anchors the azo intermediate tier serving Asian packaging demand. These three names represent distinct competitive vectors: captive supply security, metallization-grade purity leadership, and volume-scale responsiveness to textile and flexible printing markets.
| Leading Market Players |
|---|
| Huntsman Corporation |
| Cabot Corporation |
| Kawaguchi Chemical Industry |
| Ambuja Intermediates Pvt Ltd |
| Atul Ltd. |
| Clariant AG |
| Sudarshan Chemical Industries Limited |
| Nantong Acetic Acid Chemical |
| DIC Corporation |
| Others |
Value Chain & Pricing Dynamics
Tier-one automotive coating formulators in Germany and Japan anchor procurement volumes through multi-year offtake agreements, compressing spot market liquidity and forcing merchant producers toward contract-based pricing with embedded volume commitments.
Pricing Analysis
Margin tightening in phthalocyanine intermediates reflects copper phthalonitrile feedstock concentration among three qualified producers. Pricing stratifies across REACH-registered premium grades, BIS-certified standard tiers, and textile-grade economy lots. Cost-down pressure on azo coupling components accelerates as India's packaging export clusters consolidate supplier bases. Packaging converters in Gujarat demonstrate highest price sensitivity, while automotive OEMs absorb premium spreads for batch-level spectroscopic certification.
Supply Chain Analysis
Copper recovery and solvent reclamation flows from closed-loop metallization operations are qualifying Chinese producers for MEE emission permits, creating circular feedstock advantages. Production gravity centers on China, India, and Germany. Feedstock draws from naphthalene, aniline, and copper phthalonitrile streams. Single-source vulnerability concentrates in metallization-grade copper phthalonitrile. Distribution runs through direct mill integration contracts with coating formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around integrated producers as REACH authorization timelines and ECHA sunset dates strand merchant traders with legacy batch assets.
For Market Incumbents: Anticipate qualification timeline compression by investing in continuous flow diazotization with inline PAT systems. Lock tier-one automotive relationships through dedicated storage contracts in Yangtze River Delta clusters. Defend against bio-based coupling component disruptors by accelerating fermentation-derived naphthol pilot programs. For New Entrants and Emerging Players: Catalytic hydrogenation technology for nitro reduction offers entry into China's MEE-compliant supplier pool. Target Indonesia's Batam and Cilegon industrial zones for import substitution. Penetrate through toll manufacturing partnerships with established distributors lacking hydrogenation capabilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor iron-acid reduction asset owners in Ankleshwar and Vapi facing 18-24 month conversion downtime conflicts. Long-term viability hinges on catalytic hydrogenation retrofit completion. Monitor ECHA restriction proposals for fluorinated surfactants as inflection signal for dispersant reformulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Nitrile Synthesis | Huntsman Corporation anchors supply security for automotive tier-one formulators through controlled feedstock. |
| Continuous Flow Process Conversion | Inline spectroscopic monitoring compresses qualification timelines from 18 months to 6 months for German OEMs. |
| Closed-Loop Nitro Reduction Investment | Catalytic hydrogenation systems unlock MEE compliance certification for Yangtze River Delta producers. |
| Bio-Based Coupling Component Development | Fermentation-derived naphthol alternatives qualify for EU Green Deal procurement preferences in architectural coatings. |
| Direct Mill Integration Contracting | Dedicated intermediate storage shifts inventory carrying costs upstream to producers serving packaging converters. |
Study Parameters
Multi-period observation of ECHA authorization timelines, MEE permit issuance patterns, and automotive OEM qualification pipelines anchored the trend analysis, supplemented by interviews with plant managers at nitro reduction facilities, procurement leads at coating formulators, technical R&D directors, and distribution channel partners. Secondary validation drew from customs trade data, Cefic sector reports, SEC 10-K chemical disclosures, and BIS certification registries. Bottom-up capacity modeling and top-down demand triangulation cross-checked volume estimates.
Segment-weighting across chemistry families, application tiers, and regional production clusters shaped the analytical framework over the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating REACH substitution timelines and India's packaging export trajectories. Industry-specific inputs included hydrogen feedstock cost benchmarks tied to European TTF and Asian JKM natural gas indices.
Several conditions sit outside the modeled scope, including abrupt ECHA restriction accelerations, geopolitical disruptions to copper phthalonitrile trade flows, and breakthrough bio-based fermentation yields. Forecasts reflect documented assumptions about regulatory enforcement consistency and OEM qualification protocol stability. Practitioners should monitor ECHA per- and polyfluoroalkyl substance restriction progressions and China's dual carbon policy implementation intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Bromate Substitute Market
Chemical Intermediates
Montelukast Intermediate Market
Chemical Intermediates
API Intermediate Market
Chemical Intermediates
9-Decanoic Acid Methyl Ester Market
Chemical Intermediates
Diketene Derivatives Market
Chemical Intermediates
Natural Chelating Agents Market
Chemical Intermediates
Tertiary Amines Market
Chemical Intermediates
Octenylsuccinate Market
Chemical Intermediates
Diethyl Phthalate Market
Chemical Intermediates
Potential Hydrogen (Ph) Adjusters Market
Chemical Intermediates
Acetamide MEA Market
Chemical Intermediates
Enzyme Substrates Market
Chemical Intermediates
Iodoacetonitrile Market
Chemical Intermediates
US Acids Market
Chemical Intermediates
Global Biochemical Reagents Market
Chemical Intermediates
1, 3, 5-Triazine Market