
 Ethyl Polysilicate Market | 2026-2036
Ethyl Polysilicate Market Size, Share, and Industry Trends Forecast 2026-2036
Ethyl Polysilicate Market Analysis
Electronics manufacturing is decoupling from traditional silicate binders as semiconductor and display producers demand higher-purity ethyl polysilicate grades. Evonik Industries leverages its specialty silica backbone to dominate high-purity tetraethyl orthosilicate supply for foundry applications. Wacker Chemie AG anchors its position through backward integration into silicon metal and chlorosilane precursors. Momentive competes on technical service intensity for Asian electronics OEMs.
Ethyl polysilicate denotes a family of partially hydrolyzed oligomers of tetraethyl orthosilicate, typically specified by silica content ranging from 28% to 40% by weight and delivered in alcoholic solution for controlled reactivity in sol-gel processes. These materials function primarily as inorganic binders, crosslinkers, and surface modifiers where thermal stability and chemical resistance exceed organic polymer capabilities. The tetra grade commands the deepest margin pool due to its role in precision electronics and optical coatings, while construction-oriented di and tri grades face commoditization pressure. Chemicals vertical applications in catalyst supports and zeolite synthesis represent the fastest-expanding demand segment as petrochemical operators retool for lighter feedstocks.
China's MEE enforces GB standards limiting VOC emissions from industrial coatings, directly elevating ethyl polysilicate formulations as compliant inorganic alternatives. REACH registration requirements in Europe constrain import volumes from non-EU producers, shaping competitive access for Asian manufacturers. The EU F-Gas Regulation indirectly supports ethyl polysilicate growth in insulation coatings as fluorinated alternatives face phase-down. Stakeholders must monitor evolving purity specifications from semiconductor equipment makers and assess captive silane production investments against merchant supply reliability.
Market Dynamics
Semiconductor fabricators are consolidating specifications for ultra-high-purity tetraethyl orthosilicate, forcing suppliers to retool distillation trains and analytical protocols. This specification tightening concentrates purchasing power among foundry operators while fragmenting the supplier base into purity-grade tiers.
Growth Catalysts
- GB VOC emission standards:China's MEE mandates under tightening environmental protocols are disqualifying solvent-heavy organic binders from coating formulations. Ethyl polysilicate systems gain automatic compliance preference in industrial coating tenders.
- Sol-gel precision deposition:Display panel manufacturers in South Korea's manufacturing corridor are adopting ethyl polysilicate-derived silica layers for quantum dot encapsulation. This process substitution locks in recurring volume commitments.
- Catalyst support retooling:Petrochemical operators shifting to lighter shale feedstocks require zeolite structures with modified acidity profiles. Ethyl polysilicate precursors enable controlled mesopore engineering unavailable from conventional silica sources.
Market Restraints
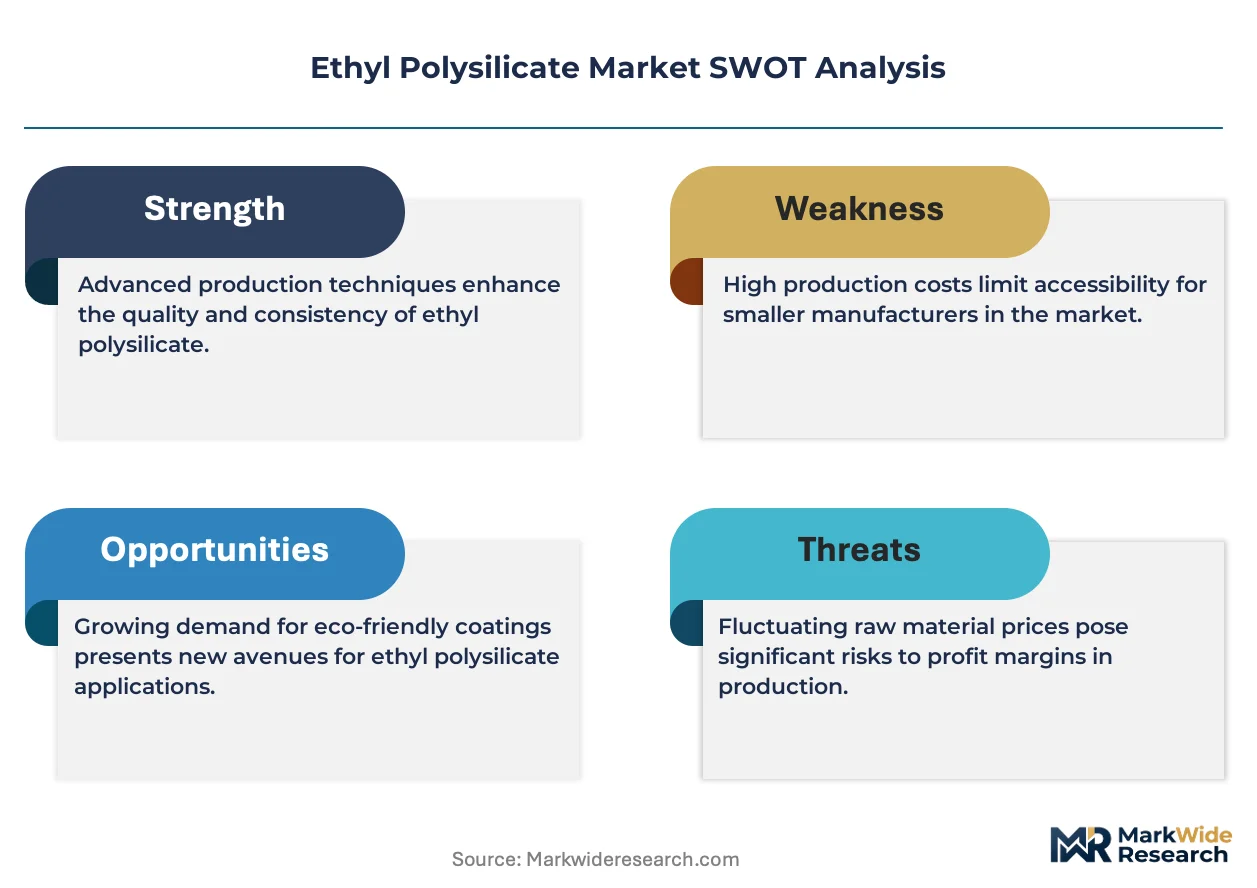
- Chlorosilane feedstock volatility:Silicon metal price swings and energy-intensive chlorination economics transmit directly to ethyl polysilicate cost structures. Producers without captive silicon metal exposure face margin compression during silicon supply disruptions.
- REACH registration barriers:European chemical registration requirements impose documentation burdens and testing costs that exclude smaller Asian exporters from EU market participation. This regulatory friction limits supply source diversification.
- Colloidal silica substitution:Lower-cost aqueous silica dispersions capture construction-grade applications where thermal stability requirements are modest. This displacement pressure commoditizes di-grade and tri-grade product tiers.
Strategic Opportunities
- Indian electronics manufacturing:Production-linked incentive schemes for semiconductor and display fabrication are attracting foundry investments in Gujarat and Tamil Nadu. Early ethyl polysilicate qualification with these greenfield facilities secures anchor supply positions.
- EU F-Gas phase-down:The regulatory phase-down of fluorinated greenhouse gases in insulation applications creates formulation openings for ethyl polysilicate-based aerogel precursors. Thermal insulation OEMs are reformulating to maintain energy efficiency ratings.
- Direct-to-foundry technical service:Bypassing traditional chemical distribution channels, suppliers are embedding application engineers at semiconductor fabrication sites. This channel innovation captures specification influence and locks out merchant competitors.
Industry Challenges
- Analytical chemist scarcity:Purity-grade differentiation requires ICP-MS and gas chromatography expertise that remains concentrated at specialty chemical firms. Foundry qualification timelines stretch when supplier analytical capabilities are inadequate.
- Legacy equipment integration:Semiconductor fabrication lines built for organic spin-on materials require solvent handling modifications to accommodate alcoholic ethyl polysilicate delivery. Retrofit capex delays adoption at older facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethyl Polysilicate Market |
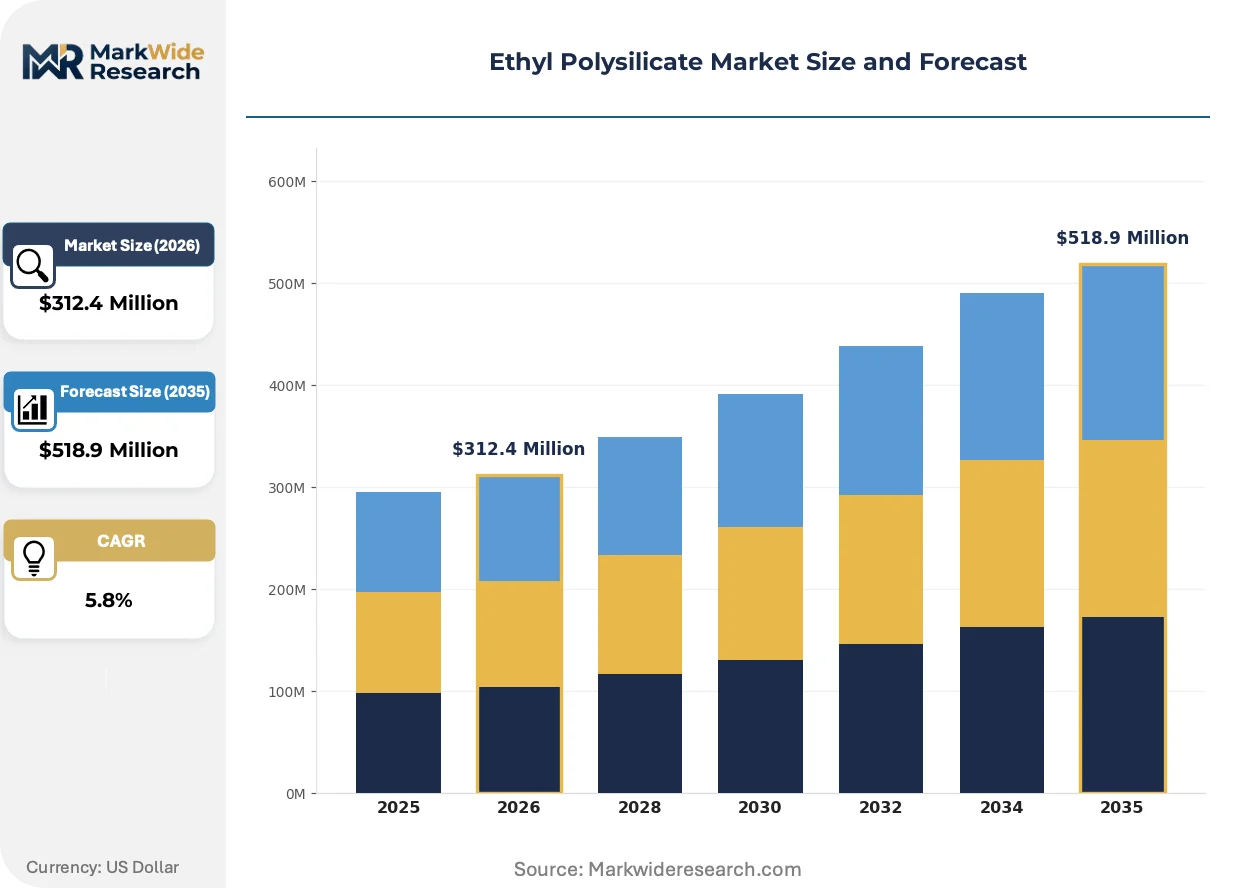
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mono, Di, Tri, Tetra Industry Vertical: Chemicals, Construction, Automotive, Electronics Application: Coatings, Adhesives, Sealants, Textiles End User: Manufacturers, Contractors, Distributors, Retailers |
| Companies Covered | Evonik Industries, Wacker Chemie AG, Momentive, COLCOAT, Nangtong Chengua Chemical Factory, Zhangjiagang Longtai, Hubei Bluesky New Material, Changzhou Wujin Hengye Chemical, Zhejiang Xinan Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethyl Polysilicate Market Emerging Trajectories
Process intensification and regulatory chemistry are reshaping how ethyl polysilicate grades are specified, manufactured, and delivered. Three developments are compressing traditional supply relationships while opening technical service differentiation.
Continuous hydrolysis reactor technology is integrating into tetra-grade production lines, replacing batch processing with steady-state silica oligomer formation. Leading foundry chemical suppliers are adopting this equipment to tighten molecular weight distribution and reduce lot-to-lot variability. The structural consequence is that purity-grade supply is concentrating among capital-intensive producers capable of validated continuous output.
REACH authorization amendments are expanding substance evaluation to imported ethyl polysilicate formulations, compelling non-EU manufacturers to establish EU-based legal entities and analytical representation. Industrial coating formulators in Germany and the Netherlands are pre-qualifying suppliers with complete registration dossiers. The segment most affected is construction-grade material, where Asian exporters face documentation gaps that European competitors exploit.
Specification-driven procurement is compressing supplier approval cycles as semiconductor equipment makers publish tighter purity matrices quarterly. Buyers in South Korea's display corridor are unbundling technical service from material supply, contracting directly with application engineering firms. This pattern is most visible in advanced node logic fabrication, where process chemistry expertise determines foundry yield outcomes.
Ethyl Polysilicate Market Segmentation
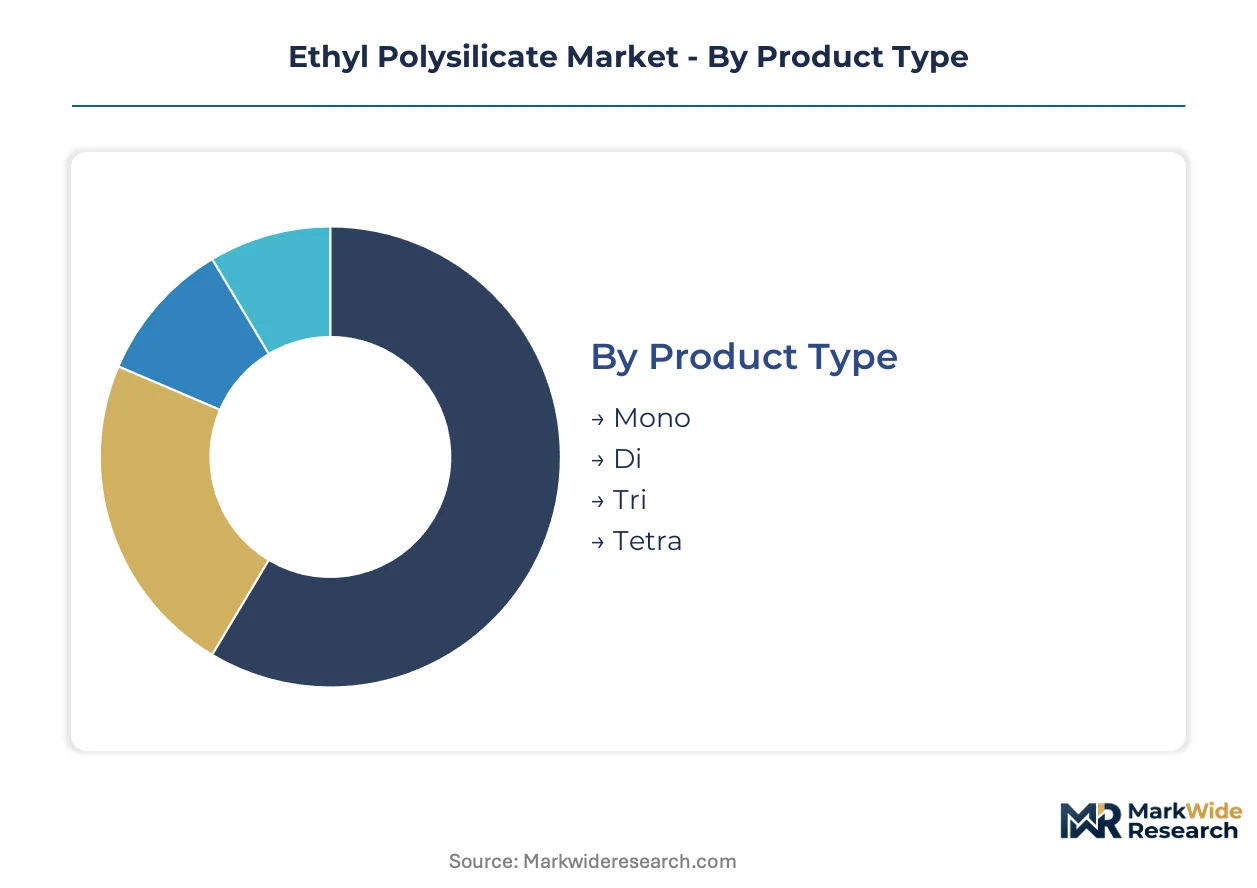
Ethyl polysilicate procurement decisions pivot on purity grades, application-specific reactivity requirements, and regulatory compliance thresholds. Buyers segment supply sources by molecular oligomer distribution, end-use thermal stability demands, and channel service intensity rather than commodity pricing alone.
Product Type:
Formulators select oligomer length based on hydrolysis rate control and final coating hardness requirements.
- Tetra:Tetraethyl orthosilicate delivers the highest silica content and slowest controlled hydrolysis kinetics. Semiconductor foundries in South Korea's display corridor specify this grade for quantum dot encapsulation layers where trace metal contamination below parts-per-billion levels determines yield.
- Di:Partially hydrolyzed dimer structures offer faster gelation rates and lower cost positions. Construction coating formulators in China source di-grade material for GB-compliant VOC reduction in industrial maintenance coatings.
- Tri:Intermediate oligomer distribution balances reactivity with pot-life extension. Textile finishing operations employ tri-grade for fabric stiffness modification where thermal curing constraints limit tetra-grade adoption.
- Mono:Single-unit ethyl silicate serves specialty crosslinking applications in adhesive formulations requiring precise stoichiometric control.
Volume sits with Di; growth tilts toward Tetra.
Industry Vertical:
End-use thermal performance requirements and regulatory exposure determine vertical penetration depth.
- Electronics:Display panel manufacturers and semiconductor fabricators drive specification tightening for ultra-high-purity grades. South Korean OEMs are consolidating supplier qualifications around continuous-process tetra-grade producers with embedded analytical capabilities.
- Chemicals:Petrochemical operators retooling for lighter shale feedstocks demand ethyl polysilicate precursors for zeolite mesopore engineering. Catalyst support applications are climbing the fastest as cracking unit operators seek acidity profile control unavailable from colloidal silica.
- Construction:Industrial coating tenders under China's MEE oversight are displacing solvent-heavy organic binders. Di-grade and tri-grade formulations capture compliance-driven substitution in protective coatings for infrastructure steel.
- Automotive:High-temperature exhaust coating applications and ceramic precursor uses remain niche relative to electronics and chemicals verticals.
Revenue concentrates in Electronics; margin expansion favors Chemicals.
Application:
Process compatibility and substrate adhesion requirements segment formulation choices across surface treatment categories.
- Coatings:Sol-gel silica layers from ethyl polysilicate precursors provide thermal stability and chemical resistance exceeding organic polymer capabilities. Foundry equipment makers are publishing tighter purity matrices quarterly for spin-on dielectric applications.
- Adhesives:Crosslinking functionality in high-temperature structural bonding relies on controlled hydrolysis rates. Automotive and aerospace OEMs specify adhesive grades with validated lot-to-lot consistency.
- Sealants:Inorganic binder applications in construction and industrial maintenance favor lower-cost di-grade and tri-grade materials where thermal cycling requirements are moderate.
- Textiles:Fabric finishing for dimensional stability and flame resistance employs tri-grade ethyl polysilicate in pad-dry-cure operations.
Coatings dominate current offtake; catalyst-derived demand in Chemicals verticals is gaining share fastest.
End User:
Technical service requirements and volume scale differentiate channel relationships across the procurement landscape.
- Manufacturers:Semiconductor fabrication facilities and specialty chemical producers contract directly with ethyl polysilicate suppliers for qualified material streams. Direct-to-foundry technical service models embed application engineers at fabrication sites to capture specification influence.
- Contractors:Construction and industrial maintenance coating applicators source through distribution channels where compliance documentation and local inventory availability determine supplier selection.
- Distributors:Regional chemical distributors aggregate construction-grade and automotive-grade volumes, facing margin pressure as manufacturers consolidate direct relationships for critical purity tiers.
- Retailers:Small-volume specialty adhesive and coating sales through retail channels represent minimal ethyl polysilicate volume.
Procurement gravity centers on Manufacturers; channel disruption is compressing Distributor relevance in high-purity segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's semiconductor fabrication incentives and South Korea's display manufacturing corridor concentrate ethyl polysilicate procurement gravity in designated industrial zones. China's MEE emission protocols and India's PLI schemes reshape formulation requirements across Asia-Pacific electronics clusters.
China
MEE oversight enforces GB VOC emission standards that disqualify solvent-heavy organic binders from industrial coating tenders. Ethyl polysilicate systems gain automatic compliance preference as inorganic alternatives. Yangtze River Delta coating formulators are retooling production lines to meet tightening environmental protocols.
South Korea
Display panel manufacturers in the Gyeonggi-do manufacturing corridor specify ultra-high-purity tetraethyl orthosilicate for quantum dot encapsulation layers. MFDS chemical registration requirements shape import qualification timelines. Seoul Capital Area foundries are consolidating supplier approvals around continuous-process producers with embedded analytical capabilities.
Germany
REACH registration requirements constrain import volumes from non-EU producers, shaping competitive access for Asian manufacturers. ECHA substance evaluation expansions compel non-EU manufacturers to establish EU-based legal entities. North Rhine-Westphalia industrial coating formulators are pre-qualifying suppliers with complete registration dossiers.
India
Production-linked incentive schemes for semiconductor and display fabrication attract foundry investments in Gujarat and Tamil Nadu. BIS standards and CDSCO chemical oversight create dual regulatory compliance requirements. Dholera Special Investment Region greenfield facilities are initiating ethyl polysilicate qualification protocols.
United States
EPA industrial emission guidelines and OSHA chemical handling standards govern coating formulation compliance. Semiconductor fabricators in Arizona and Texas are consolidating specifications for ultra-high-purity grades. Phoenix metropolitan area foundry expansions drive distillation train and analytical protocol investments among qualified suppliers.
Ethyl Polysilicate Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with purity-grade differentiation fragmenting supply into tiered qualification pools. Tetra-grade procurement concentrates among capital-intensive producers capable of validated continuous output, while construction-oriented di-grade and tri-grade segments face commoditization pressure from colloidal silica substitutes. Two strategic archetypes dominate: backward-integrated chlorosilane producers leveraging captive silicon metal supply, and application-engineering specialists embedding technical service at fabrication sites. Capacity expansion and direct-to-foundry channel disruption represent the dominant competitive moves reshaping supplier relationships.
Within the specialty chemical tier, Evonik Industries and Wacker Chemie AG exemplify divergent integration strategies. Evonik leverages its specialty silica backbone to occupy a position in high-purity supply for foundry applications. Wacker Chemie AG anchors its competitive stance through upstream control over silicon metal and chlorosilane precursors. Momentive sits within the technical service-intensive archetype, competing on application engineering depth for Asian electronics OEMs rather than feedstock dominance.
| Leading Market Players |
|---|
| Evonik Industries |
| Wacker Chemie AG |
| Momentive |
| COLCOAT |
| Nangtong Chengua Chemical Factory |
| Zhangjiagang Longtai |
| Hubei Bluesky New Material |
| Changzhou Wujin Hengye Chemical |
| Zhejiang Xinan Chemical |
| Others |
Supply Flow & Price Mechanics
Semiconductor foundry consolidation around ultra-high-purity tetraethyl orthosilicate specifications is compressing supplier margins and forcing capital-intensive distillation investments. This procurement concentration rewards backward-integrated chlorosilane producers while fragmenting merchant suppliers into purity-grade tiers with divergent pricing power.
Pricing Analysis
Short lead-time premiums for qualified tetra-grade material widen spreads between contract and spot pricing, with South Korean display manufacturers paying substantial uplifts for validated continuous-process output. Three-tier pricing structure across premium, standard, and economy levels separates foundry-qualified tetra-grade from industrial di-grade and construction tri-grade tiers. Price differentiation hinges on ICP-MS certification and embedded analytical service intensity. Cost compression in di-grade and tri-grade segments is intensifying because colloidal silica substitutes capture construction applications. Chemicals vertical buyers exhibit lowest price sensitivity due to catalyst yield economics, while construction contractors face acute budget constraints.
Supply Chain Analysis
Direct-to-foundry channels handle hyperscale semiconductor and display manufacturer demand, bypassing traditional chemical distribution. Geographic supply concentration centers on Germany, China, and South Korea, with chlorosilane precursor production anchored in silicon metal-rich regions. Raw material dependencies include silicon metal, ethanol, and hydrochloric acid feedstocks. Single-source vulnerability from concentrated silicon metal supply in specific mining jurisdictions creates disruption exposure. Distribution runs through qualified direct supply agreements for purity grades and regional distributors for construction-tier volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing captive chlorosilane production to secure margin control against silicon metal price volatility.
For Market Incumbents: Anticipate colloidal silica substitution pressure in construction grades by locking in long-term offtake agreements with South Korean display manufacturers. Defend tetra-grade positioning through continuous hydrolysis reactor investments that tighten molecular weight distribution. Prioritize analytical capability expansion to compress foundry qualification timelines and exclude merchant competitors. For New Entrants and Emerging Players: China's GB VOC emission standards under MEE oversight open a window for compliant di-grade supply to Yangtze River Delta coating formulators retooling from organic binders. Target Gujarat's greenfield semiconductor fabrication facilities before incumbent qualification protocols solidify. Lead with technical service bundling rather than price to bypass established distributor relationships. For Investors and Strategic Acquirers: The window for entry favors specialty chemical firms with existing silica chemistry expertise and analytical infrastructure. Long-term viability rests on securing positions in catalyst support and zeolite precursor applications as petrochemical feedstock shifts accelerate. Monitor chlorosilane feedstock contract renegotiation cycles as inflection indicators for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorosilane Precursors | Wacker Chemie AG's silicon metal control insulates margins against energy-intensive chlorination cost swings. |
| Continuous Hydrolysis Reactor Deployment | Evonik Industries validates steady-state tetra-grade output to tighten lot-to-lot variability for foundry specifications. |
| Direct-to-Foundry Technical Service Embedding | Momentive places application engineers at Seoul Capital Area fabrication sites to capture specification influence. |
| REACH Registration Dossier Completion | Asian manufacturers establish EU legal entities to access North Rhine-Westphalia industrial coating formulators. |
| Indian Greenfield Facility Qualification | Early supplier protocols at Dholera Special Investment Region secure anchor positions under PLI scheme incentives. |
Methodological Framework
Multi-period observation of ethyl polysilicate purity specification tightening, chlorosilane feedstock contract structures, and foundry qualification timelines anchored the trend analysis, supplemented by interviews with plant managers at specialty chemical producers, procurement leads at South Korean display manufacturers, distribution channel partners in China's Yangtze River Delta, and technical R&D directors at catalyst support operations. Secondary validation drew from customs and trade data, chemical industry association reports, SEC 10-K filings of listed materials companies, and semiconductor equipment maker specification disclosures. Bottom-up volume modeling across grade tiers and end-use verticals was triangulated against top-down market sizing from production capacity assessments.
Input-output matrices connected silicon metal and ethanol feedstock pricing to ethyl polysilicate grade-specific production economics across the projection horizon. Segmentation dimensions modeled include purity grade tier, end-use industry vertical, geographic production hub, and channel structure. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements. Industry-specific forecast inputs incorporated MEE emission enforcement timelines and semiconductor node migration patterns.
The model assumes a particular technology adoption path for continuous hydrolysis reactor deployment; alternative pathways for batch processing retention would alter the outlook for supplier concentration and margin distribution. Forecasts reflect base-case assumptions regarding chlorosilane feedstock availability and REACH authorization amendment implementation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Phenylbenzimidazole Sulfonic Acid Market
Specialty Chemicals
Antioxidant 412S Market
Specialty Chemicals
Panthenol Market
Specialty Chemicals
Micronized PTFE Market
Specialty Chemicals
Glucosinolates Market
Specialty Chemicals
Silicone Acrylate Market
Specialty Chemicals
Photoinitiators Market
Specialty Chemicals
North America Mexoryl SX (Ecamsule) Market
Specialty Chemicals
Australia and New Zealand Aerosol Market
Specialty Chemicals
Specialty Oxidants Market
Specialty Chemicals
Cellulose Ether Market
Specialty Chemicals
Barium Derivatives Market
Specialty Chemicals
Salt Hydrate Market
Specialty Chemicals
Glutathione Market
Specialty Chemicals
Sophorolipids Market
Specialty Chemicals
Fixing Agent Market