
 Panthenol Market | 2026-2036
Panthenol Market Size, Share, and Industry Trends Forecast 2026-2036
Panthenol Market Analysis
Clean-beauty formulators is unwinding legacy reliance on mass-market hair-care brands as the primary volume anchor. DSM specializes in high-purity D-panthenol for pharmaceutical applications, leveraging its biotechnology platform to sustain quality differentiation across European supply chains. BASF SE anchors global liquid-grade production through integrated feedstock operations, while Croda International Plc competes in emulsion formats for prestige cosmetics brands.
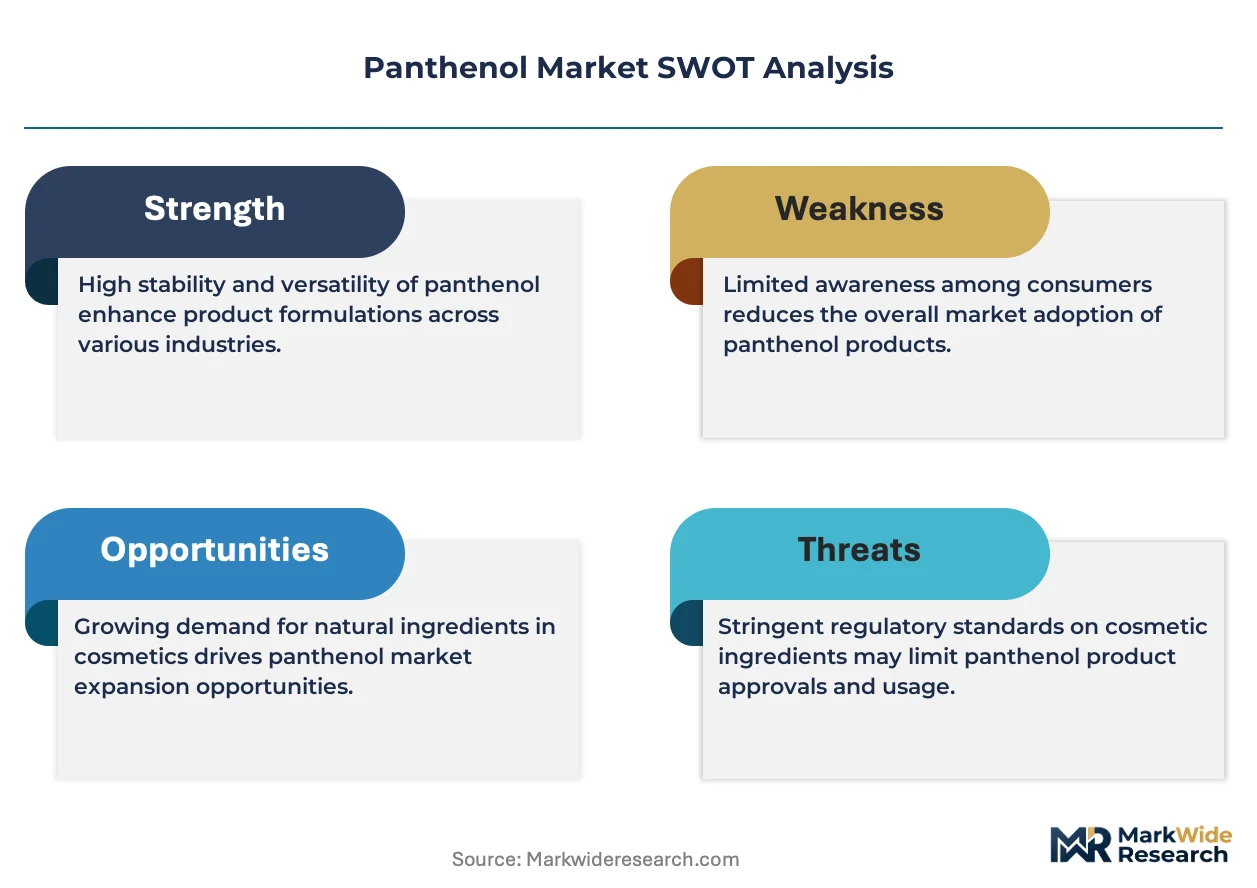
Panthenol, the alcohol analog of pantothenic acid (vitamin B5), functions as a humectant, emollient, and wound-healing promoter in topical and oral preparations; cosmetic-grade material typically achieves minimum assay of 98.5% with specified optical rotation confirming D-isomer identity. Liquid panthenol dominates volume throughput due to ease of incorporation into aqueous cosmetic bases, though powder grades command margin premiums in pharmaceutical tablet and capsule applications. Hair Care represents the most mature application segment with established brand loyalty, while Cosmetics skin-care formulations generate the fastest growth as consumers prioritize barrier-repair claims.
The EU Cosmetics Regulation and REACH framework mandate full ingredient traceability and restricted substance screening for panthenol entering European personal-care supply chains, elevating compliance costs for non-integrated importers. FDA oversight of cosmetic ingredient safety through the Modernization of Cosmetics Regulation Act is intensifying documentation requirements for US-bound panthenol shipments. Stakeholders must monitor evolving purity specifications across jurisdictions to determine whether captive synthesis or strategic sourcing better protects margin structures.
Market Dynamics
Clean-beauty formulators are unwinding legacy reliance on mass-market hair-care brands as the primary volume anchor for panthenol, redirecting procurement toward pharmaceutical-grade suppliers capable of documenting EU Cosmetics Regulation and REACH compliance.
Growth Catalysts
- Barrier-repair cosmetics demand:Skin-care formulations now absorb panthenol volumes once reserved for hair conditioners, with prestige brands specifying D-isomer optical rotation certificates.
- REACH purity escalation:The EU's tightened traceability mandates are filtering out commodity-grade importers, concentrating procurement among integrated European manufacturers.
- Pharmaceutical wound-healing applications:Oral and topical preparations for tissue repair are expanding panthenol's addressable market beyond cosmetic humectant functions.
Market Restraints
- Feedstock volatility:Pantothenic acid precursor costs fluctuate with agricultural commodity cycles, squeezing margin structures for non-integrated producers.
- German production concentration:BASF SE and Merck KGaA anchor liquid-grade supply near Ludwigshafen and Darmstadt, creating geographic single-point vulnerability.
- Biotechnology substitution:Fermentation-derived alternatives to chemical synthesis threaten incumbent process economics for mid-tier suppliers.
Strategic Opportunities
- US pharmaceutical channel expansion:FDA Modernization of Cosmetics Regulation Act documentation requirements favor suppliers with pre-existing drug-master files.
- Powder-grade pharmaceutical tablets:Capsule and solid-dose applications command margin premiums over liquid cosmetic grades.
- Biotechnology platform licensing:DSM's high-purity D-panthenol fermentation expertise offers partnership models for regional market entry.
Industry Challenges
- Optical rotation certification backlog:Analytical laboratories face capacity constraints verifying D-isomer identity for EU Cosmetics Regulation submissions.
- Legacy emulsion reformulation:Croda International Plc's prestige cosmetic customers require compatibility testing when switching panthenol suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Panthenol Market |
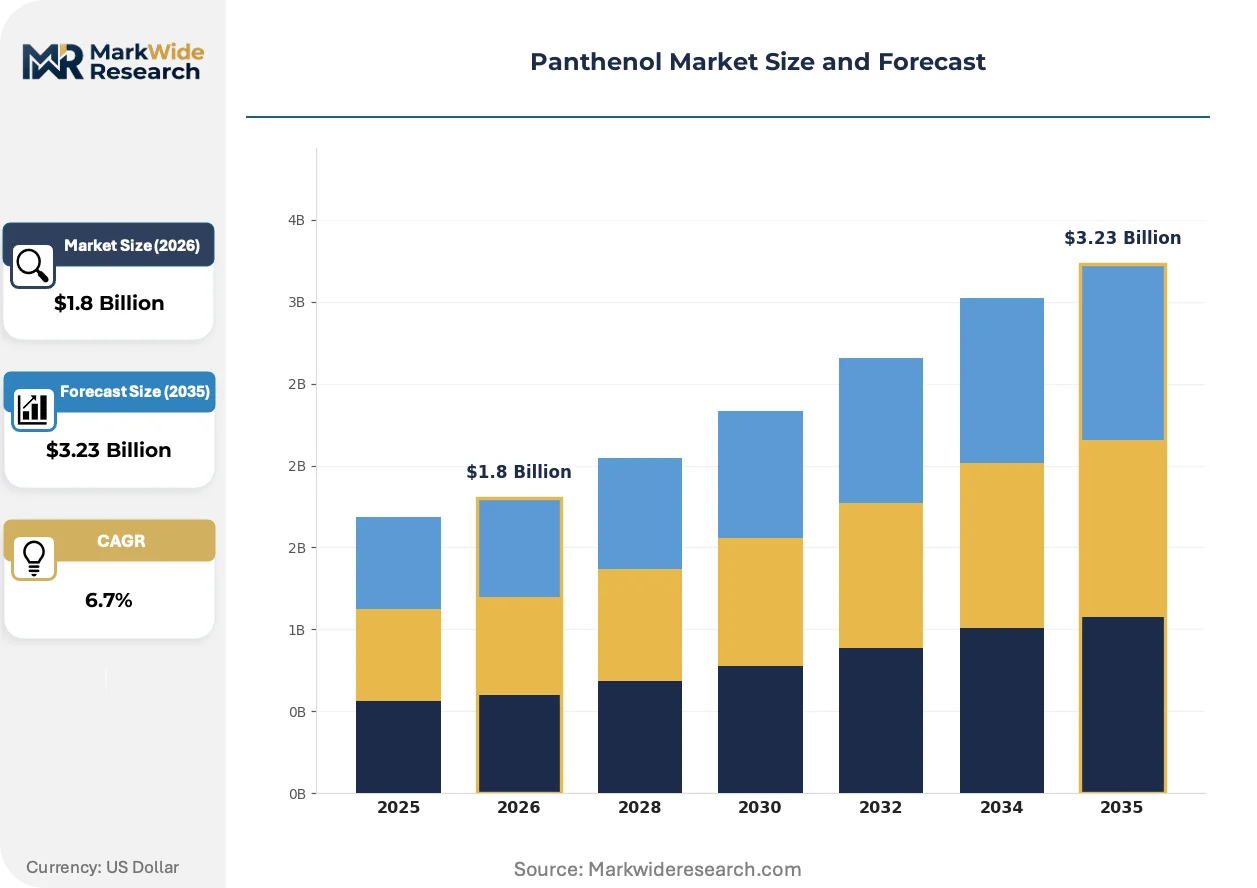
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Emulsion, Gel Application: Cosmetics, Hair Care, Pharmaceuticals, Food Additives End User: Manufacturers, Retailers, Distributors, Consumers Distribution Channel: Online, Offline, Direct Sales, B2B |
| Companies Covered | BASF SE, DSM, Merck KGaA, TRI-K Industries, Inc., Yifan Pharmaceutical Co., Ltd., Evonik Industries AG, Lonza, Croda International Plc, Anhui Huaheng Biotechnology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Panthenol Market Emerging Trajectories
Biotechnology-derived synthesis routes are displacing petrochemical processes across high-purity panthenol production, altering competitive positioning between fermentation specialists and integrated chemical conglomerates.
Fermentation-based D-panthenol manufacturing is displacing conventional chemical synthesis for pharmaceutical-grade material. DSM leverages its biotechnology platform to sustain quality differentiation, while specialty chemical houses retrofit existing pantothenic acid plants. This technology is displacing capital-intensive hydrogenation equipment from new facility designs.
REACH substance screening requirements are intensifying documentation burdens for panthenol importers. The EU Cosmetics Regulation now mandates full supply-chain traceability back to pantothenic acid precursors. German customs authorities are rejecting shipments lacking ECHA-registered substance data, forcing non-EU suppliers to establish European repackaging operations.
Direct procurement from biotechnology platforms is shortening traditional distribution channels. Prestige cosmetics brands now contract DSM and BASF SE directly, bypassing regional chemical distributors. This pattern concentrates most visibly in Germany, where integrated manufacturers offer combined pharmaceutical and cosmetic grade portfolios.
Panthenol Market Segmentation
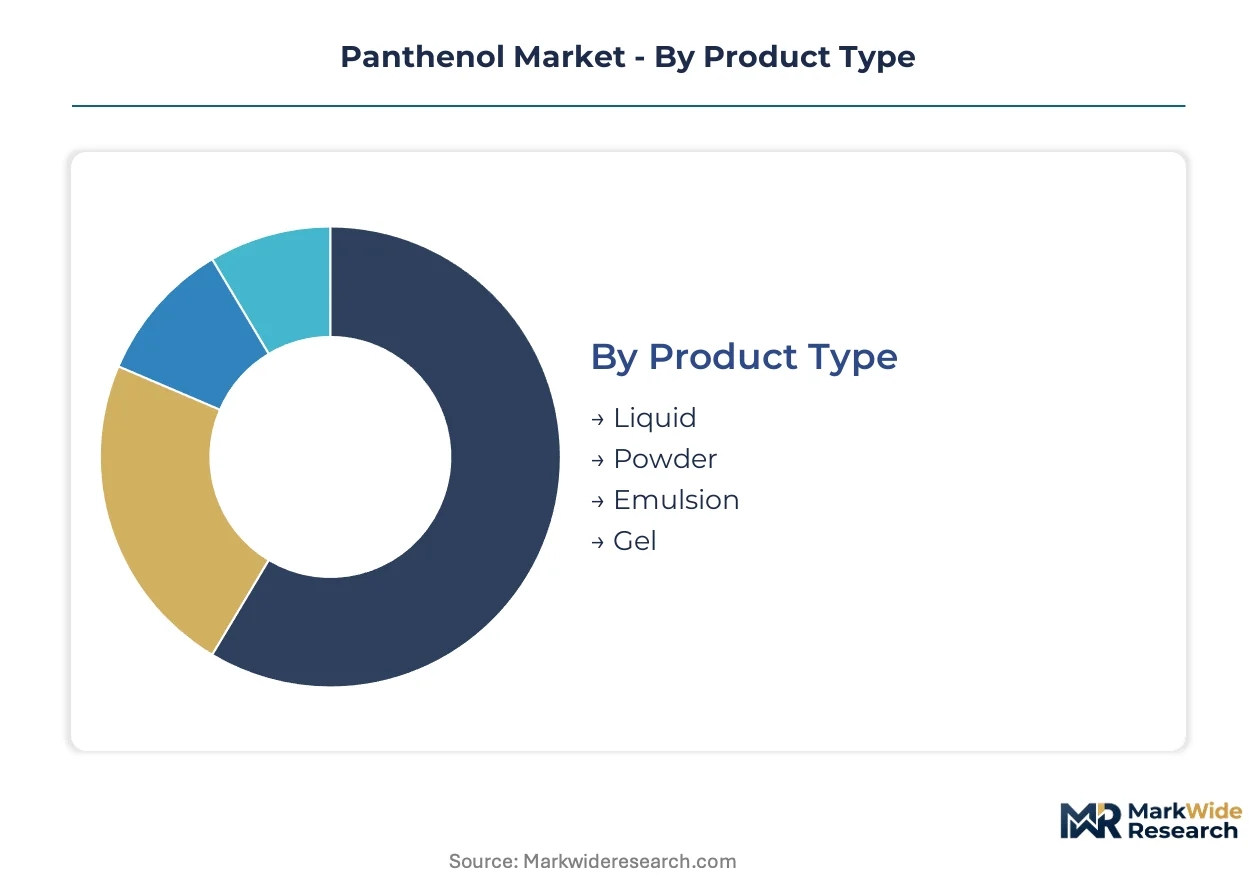
Panthenol procurement patterns diverge sharply across product formats, with liquid grades flowing through high-volume cosmetic supply chains while powder variants serve pharmaceutical tablet manufacturers demanding optical rotation certification. Application-level segmentation reveals a structural pivot from mature hair-care formulations toward barrier-repair skin-care and wound-healing pharmaceuticals.
Product Type:
Domestic consumption concentrates in liquid and emulsion formats near German and Dutch formulation hubs, while powder-grade exports serve pharmaceutical tablet manufacturers across Switzerland and North America.
- Liquid:Aqueous solution format dominates cosmetic incorporation due to seamless blending into serums and conditioners. German manufacturers near Ludwigshafen absorb the majority of European liquid volumes, driven by integrated BASF SE supply chains and REACH-compliant documentation.
- Powder:Crystalline D-panthenol achieves minimum 98.5% assay with specified optical rotation for pharmaceutical solid-dose applications. Swiss and North American tablet manufacturers command premium pricing for certified D-isomer identity, constrained by analytical laboratory capacity for EU Cosmetics Regulation submissions.
- Emulsion:Oil-in-water dispersions serve prestige cosmetic brands requiring compatibility-tested delivery systems.
- Gel:Thickened aqueous matrices target topical wound-healing preparations and medicated skin-care formats.
Liquid commands the established base. The steepest expansion runs through powder pharmaceutical applications.
Application:
Cost-tier stratification separates commodity hair-care formulations from premium skin-repair serums and prescription wound-healing preparations.
- Cosmetics:Skin-care formulations now absorb panthenol volumes once reserved for hair conditioners, with prestige brands specifying barrier-repair claims and D-isomer optical rotation certificates. German and French clean-beauty formulators drive fastest adoption.
- Hair Care:The most mature segment maintains established brand loyalty in mass-market conditioners and shampoos. Volume throughput remains substantial but growth has flattened as procurement shifts toward pharmaceutical-grade suppliers.
- Pharmaceuticals:Oral and topical tissue-repair preparations expand addressable market beyond cosmetic humectant functions, with FDA documentation requirements favoring suppliers holding drug-master files.
- Food Additives:Nutritional fortification applications for pantothenic acid derivatives serve dietary supplement manufacturers.
Hair Care anchors volume throughput. Cosmetics skin-care formulations are expanding most quickly.
End User:
Customer-type concentration favors direct manufacturer procurement over distributor intermediation, shortening traditional chemical supply chains.
- Manufacturers:Integrated cosmetic and pharmaceutical producers contract DSM and BASF SE directly, bypassing regional distributors. German production clusters concentrate procurement power for combined pharmaceutical and cosmetic grade portfolios.
- Retailers:Specialty beauty and pharmacy chains stock finished formulations containing certified panthenol grades.
- Distributors:Regional chemical distributors face margin compression as direct biotechnology platform procurement accelerates.
- Consumers:End-user awareness of panthenol ingredient labeling influences brand selection in premium personal-care categories.
Manufacturers control procurement leverage. Retailers represent the emerging channel for transparency-driven consumer selection.
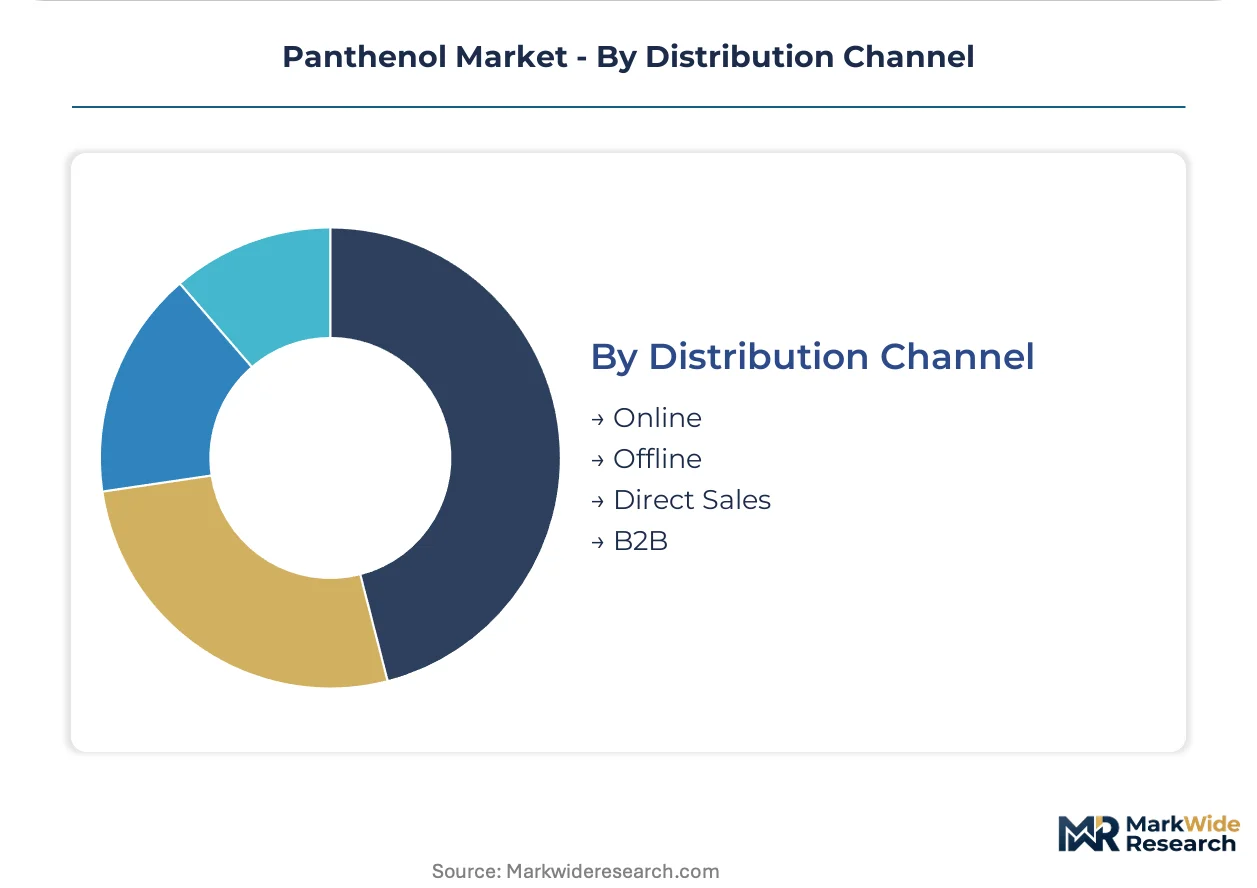
Distribution Channel:
Volume scale separates bulk B2B chemical transfers from fragmented online and offline retail pathways serving finished goods.
- Online:E-commerce platforms serve small-batch cosmetic formulators and research institutions requiring documented purity certificates.
- Offline:Traditional chemical distribution networks maintain relevance for standardized liquid-grade cosmetic applications.
- Direct Sales:Biotechnology platforms and integrated manufacturers deploy technical sales teams for pharmaceutical-grade contracts requiring regulatory documentation.
- B2B:Bulk contractual supply agreements dominate liquid-grade volume movement, with German customs authorities rejecting shipments lacking ECHA-registered substance data.
B2B channels handle the volume base. Direct sales from biotechnology platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade buyers concentrate procurement decisions in Germany, where integrated manufacturers offer combined cosmetic and drug-grade portfolios with REACH-compliant documentation chains.
Germany
Barrier-repair skin-care formulations and wound-healing pharmaceuticals absorb the majority of European panthenol volumes. ECHA substance registration requirements filter out non-compliant importers at Ludwigshafen and Darmstadt customs checkpoints. BASF SE and Merck KGaA anchor liquid-grade production clusters along the Rhine-Neckar metropolitan region.
United States
Prestige cosmetics brands and dietary supplement manufacturers drive demand for certified D-isomer panthenol. FDA Modernization of Cosmetics Regulation Act documentation requirements favor suppliers with established drug-master files. New Jersey and California formulation hubs source directly from biotechnology platforms, bypassing traditional chemical distributors.
Switzerland
Pharmaceutical tablet and capsule manufacturers command premium pricing for powder-grade panthenol with optical rotation certification. Swissmedic oversight of excipient quality elevates documentation burdens for imported material. Basel-area production facilities specialize in solid-dose applications requiring minimum 98.5% assay specifications.
China
Domestic cosmetic brands and nutritional fortification applications expand addressable market for fermentation-derived panthenol. NMPA registration pathways for pharmaceutical-grade material remain complex for foreign suppliers. Zhejiang and Jiangsu province manufacturing clusters develop biotechnology platforms to serve Asian personal-care supply chains.
India
Generic pharmaceutical manufacturers and Ayurvedic personal-care formulators create dual demand channels for panthenol imports. CDSCO quality standards for topical excipients tighten purity requirements for EU-export-oriented producers. Maharashtra and Gujarat state industrial corridors concentrate contract manufacturing operations serving regulated export markets.
Panthenol Market Vendor Landscape
Player mix skews toward integrated chemical conglomerates with captive feedstock operations and biotechnology specialists leveraging fermentation platforms. The structure concentrates procurement leverage among German and Dutch manufacturers with REACH-registered substance portfolios. Strategic archetypes divide between scale-driven liquid-grade suppliers, purity-focused pharmaceutical-grade specialists, and regional fermentation platforms. Dominant competitive moves include biotechnology licensing partnerships and backward integration into pantothenic acid precursor supply.
Among integrated chemical manufacturers, BASF SE anchors global liquid-grade production through Rhine-Neckar feedstock operations. DSM represents the biotechnology specialist archetype with high-purity D-panthenol fermentation expertise. Merck KGaA occupies a position bridging pharmaceutical-grade certification and cosmetic-grade volume supply.
| Leading Market Players |
|---|
| BASF SE |
| DSM |
| Merck KGaA |
| TRI-K Industries, Inc. |
| Yifan Pharmaceutical Co., Ltd. |
| Evonik Industries AG |
| Lonza |
| Croda International Plc |
| Anhui Huaheng Biotechnology Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between BASF SE and Ludwigshafen-area formulators lock in liquid-grade supply access while indexing pantothenic acid feedstock costs to agricultural commodity benchmarks, creating price visibility that spot purchasers lack.
Pricing Analysis
Cost-plus contracts with pantothenic acid indexation dominate pharmaceutical-grade transactions, with DSM and Merck KGaA layering optical rotation certification premiums atop base chemical costs. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and commodity-grade levels separates certified D-isomer material from mass-market hair-care inputs. Cost compression in commodity liquid grades is intensifying because Zhejiang fermentation platforms are expanding capacity. Generic pharmaceutical manufacturers in India exhibit highest price sensitivity, while Swiss tablet producers accept premiums for Swissmedic-compliant documentation.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for non-integrated importers seeking REACH-compliant panthenol. Supply concentrates in Germany, China, and India, with Rhine-Neckar production clusters drawing from captive pantothenic acid synthesis. Raw material dependencies span beta-alanine, calcium pantothenate, and hydrogenation catalysts. Single-source vulnerability around German liquid-grade output creates geographic concentration risk. Distribution runs through direct manufacturer contracts for pharmaceutical grades, with regional distributors retaining relevance only for standardized cosmetic applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward integrated German manufacturers as clean-beauty formulators consolidate procurement around REACH-registered suppliers capable of full traceability documentation.
For Market Incumbents: Secure backward integration into pantothenic acid precursor supply to defend against fermentation-based substitution threats from Chinese biotechnology platforms. Expand analytical laboratory capacity for optical rotation certification to eliminate submission backlogs that delay EU Cosmetics Regulation compliance. Prioritize capacity addition near Darmstadt to reduce geographic single-point exposure. For New Entrants and Emerging Players: FDA drug-master file fast-track pathways offer regulatory differentiation for US pharmaceutical channel entry without ECHA registration burdens. Target powder-grade pharmaceutical tablet manufacturers in Switzerland and North America, where premium pricing tolerates new entrant cost structures. Pursue licensing partnerships with established fermentation platforms rather than greenfield synthesis investment. For Investors and Strategic Acquirers: Biotechnology specialists with pharmaceutical-grade certification and existing EU substance registrations represent the most defensible acquisition profile for long-term viability. Monitor CDSCO quality standard tightening in India as an inflection indicator for export-oriented contract manufacturing consolidation. Outcomes outside this envelope would require model recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pantothenic Acid | BASF SE's captive feedstock operations insulate margin structures from agricultural commodity volatility. |
| Biotechnology Platform Licensing | DSM's fermentation expertise enables regional entrants to bypass capital-intensive hydrogenation equipment. |
| Analytical Laboratory Expansion | Merck KGaA's D-isomer certification capacity eliminates EU Cosmetics Regulation submission bottlenecks. |
| Direct Manufacturer Procurement | Prestige cosmetics brands contracting BASF SE bypass distributor margins and accelerate traceability documentation. |
| Pharmaceutical-Grade Capacity Addition | Swiss and North American solid-dose manufacturers command premium pricing for certified powder grades. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs/trade data, SEC 10-K filings, and Cefic chemical industry reports through bottom-up and top-down triangulation. Primary interviews engaged plant managers at integrated panthenol manufacturers, procurement leads at downstream cosmetic OEMs, distribution channel partners, and technical R&D directors at fermentation platforms. Secondary validation drew from ECHA substance registration databases, FDA drug-master file listings, and Swissmedic excipient quality directives.
Segmentation dimensions modeled span grade tier (pharmaceutical versus cosmetic versus commodity), product format (liquid, powder, emulsion, gel), end-use industry (skin-care, hair-care, wound-healing pharmaceuticals), and regional production hub concentration. CAGRs were derived from volume trajectory analysis across the projection horizon, incorporating biotechnology substitution curves and REACH compliance cost escalation. Industry-specific forecast inputs include optical rotation certification capacity constraints and pantothenic acid feedstock price index movements.
Underlying assumptions cover sustained EU Cosmetics Regulation enforcement intensity and stable agricultural commodity pricing for pantothenic acid precursors, with deviation risk concentrated in NMPA regulatory pathway liberalization for Chinese pharmaceutical-grade entrants and fermentation technology cost breakthroughs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
UV Light Stabilizers Market
Specialty Chemicals
Fragrance-Release Control Agents for Long-Lasting Home Care Scents Market
Specialty Chemicals
Fabric Antibacterial Spray Market
Specialty Chemicals
Microcrystalline Wax Market
Specialty Chemicals
Insoluble Fibers Market
Specialty Chemicals
Superdisintegrants Market
Specialty Chemicals
Polyquaternium 6 Market
Specialty Chemicals
Alpha Bisabolol Market
Specialty Chemicals
Photoinitiators Market
Specialty Chemicals
Global Non-Halogenated Flame Retardants Market
Specialty Chemicals
Fatliquoring Agents Market
Specialty Chemicals
Global Prepacked Chromatography Columns Market
Specialty Chemicals
Allantoin Market
Specialty Chemicals
Esterquats Market
Specialty Chemicals
Non-Commercial Acrylic Paints Market
Specialty Chemicals
Australia and New Zealand Aerosol Market