
 Crotonaldehyde Market | 2026-2036
Crotonaldehyde Market Size, Share, and Industry Trends Forecast 2026-2036
Crotonaldehyde Market Intelligence
Revenue from value-added crotonaldehyde derivatives for pharmaceuticals is tilting the margin pool away from high-volume, lower-margin technical grade sales. Celanese Corporation leverages its integrated production capabilities to serve large-scale industrial accounts. BASF SE differentiates through its extensive portfolio of downstream chemical products derived from crotonaldehyde. Jubilant Ingrevia Limited specializes in intermediates for the life sciences and agrochemical sectors.
Crotonaldehyde is a highly reactive unsaturated aldehyde, primarily produced via the aldol condensation of acetaldehyde. Its chemical structure, featuring both an aldehyde and a double bond, makes it a versatile intermediate for organic synthesis. The production of sorbic acid, a key preservative, drives a significant portion of demand within the pharmaceuticals and food additives application. While technical grade material dominates production volume, the purified grade and stabilized form segments command higher price points for sensitive end-uses.
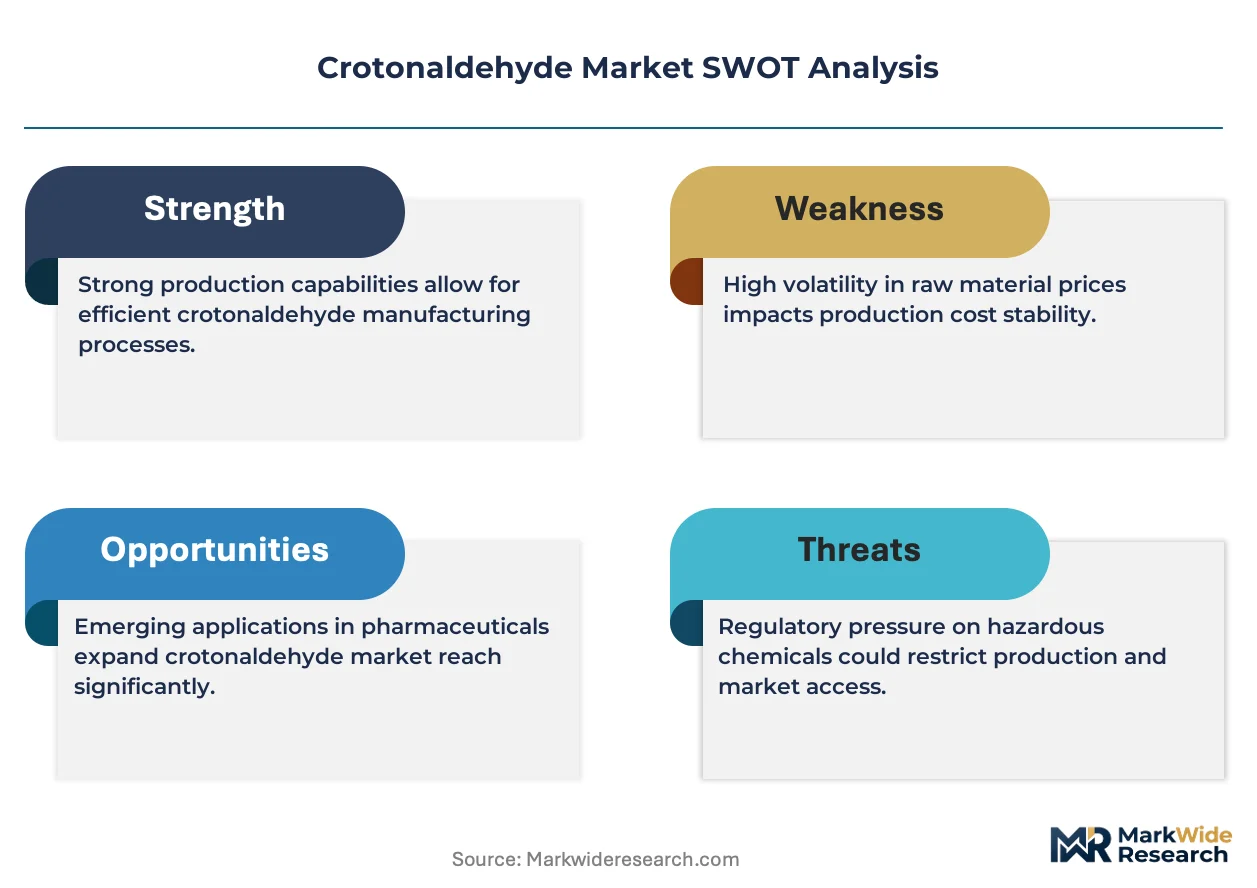
Regulations from the US Environmental Protection Agency (EPA) and the European Chemicals Agency (ECHA) under REACH mandate strict controls on its handling and emissions due to its toxicity. In China, the Ministry of Ecology and Environment (MEE) enforces similar stringent standards on chemical producers. Navigating these complex regulations while investing in greener production pathways is the central challenge for manufacturers seeking long-term market access.
Market Dynamics
The central structural force shaping the crotonaldehyde market is the escalating stringency of global environmental and safety regulations. Mandates from the EPA, ECHA, and China's MEE are compelling producers to invest in cleaner synthesis routes and stricter emission controls.
Growth Catalysts
- Agrochemical Formulation:Demand from agrochemical producers for manufacturing next-generation pesticides and fungicides, which require crotonaldehyde as a key building block, is a primary catalyst for volume growth in developing agricultural economies.
- Food Preservation Demand:The production of sorbic acid and its salts, critical food preservatives, relies heavily on crotonaldehyde as a precursor, linking market demand directly to trends in the processed food and beverage industry.
- Chemical Park Concentration:The development of specialized chemical industrial parks in China provides producers with integrated infrastructure, streamlined logistics, and shared utilities, lowering operational costs and fostering synergistic production of downstream derivatives.
Market Restraints
- Feedstock Price Volatility:The market is sensitive to price fluctuations of acetaldehyde, its primary feedstock, which is derived from ethylene or ethanol, exposing producers to volatility in the broader petrochemical and agricultural commodities markets.
- High Compliance Costs:Adherence to stringent regulations like the EU's REACH and US EPA rules requires significant investment in testing, documentation, and specialized handling equipment, creating high barriers to entry for new players.
- Substitution from Alternative Synthetics:For certain downstream products, the development of alternative synthesis pathways that bypass the use of crotonaldehyde presents a long-term substitution threat, particularly if these routes offer better safety or cost profiles.
Strategic Opportunities
- High-Purity Pharmaceutical Intermediates:Manufacturing value-added derivatives for the pharmaceutical industry, such as those used in the synthesis of vitamins or active pharmaceutical ingredients, offers a significant opportunity to capture higher margins than bulk technical-grade sales.
- Green Chemistry Pathways:Developing and commercializing bio-based production routes or novel catalytic processes that reduce toxicity and waste generation can create valuable intellectual property and meet growing demand for sustainable chemical manufacturing.
- Life Sciences Sector in India:India's expanding life sciences and specialty chemicals industry presents an opportunity for producers to supply intermediates for both domestic consumption and export, leveraging the country's manufacturing capabilities.
Industry Challenges
- Capital-Intensive Upgrades:Meeting tightening emissions standards set by bodies like China's MEE requires substantial capital expenditure on advanced abatement technologies, process control systems, and environmental monitoring infrastructure, impacting producer profitability.
- Logistical Complexity:The inherent toxicity and reactivity of crotonaldehyde mandate specialized, costly logistics, including dedicated transport containers, stringent storage protocols, and certified handling personnel, complicating supply chain management.
- End-Use Certification Delays:Securing approval for crotonaldehyde-derived products in sensitive applications like food additives or pharmaceuticals involves lengthy and rigorous validation processes with agencies such as the EFSA or FDA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crotonaldehyde Market |
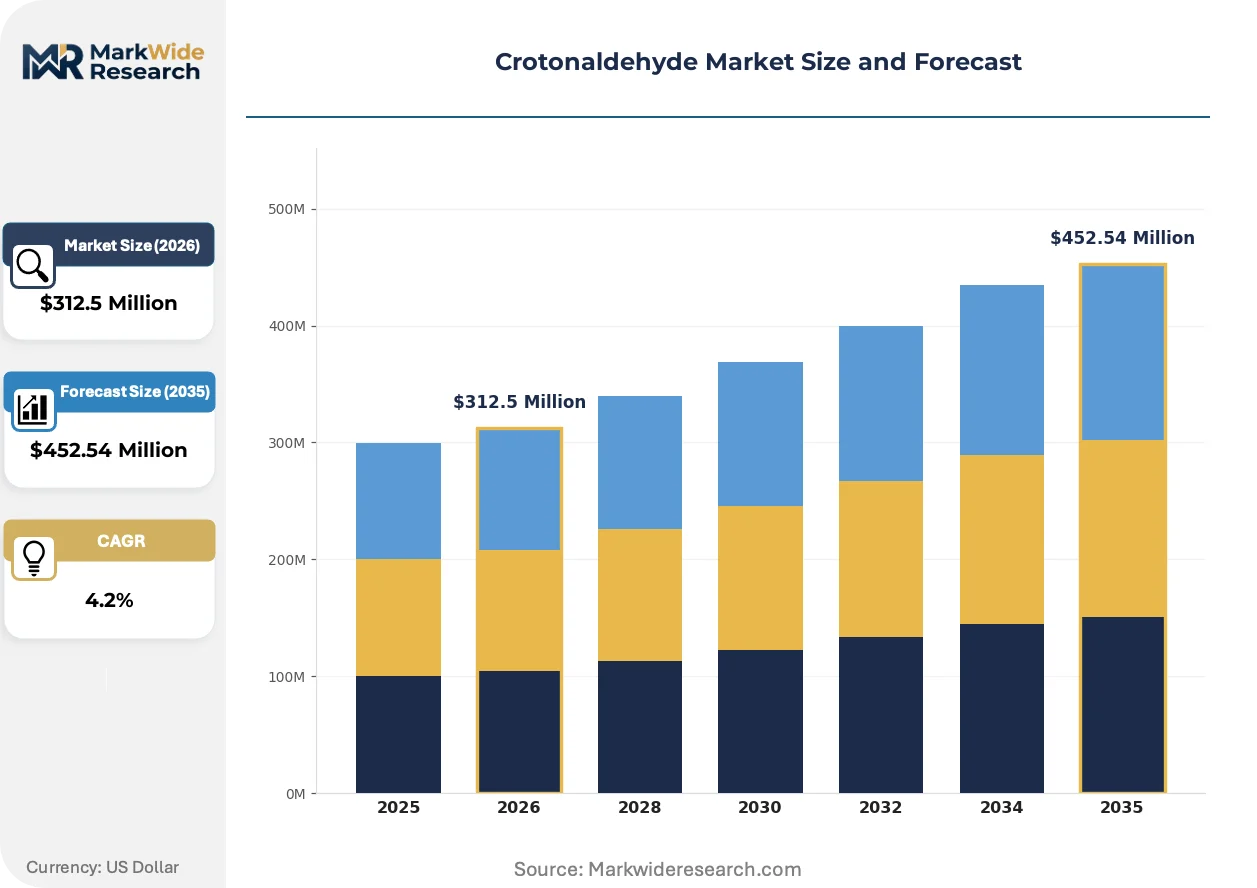
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $452.54 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Crotonaldehyde, Aqueous Solution, Stabilized Form, Technical Grade, Purified Grade Technology: Oxidation Process, Dehydrogenation, Catalytic Hydrogenation, Hydroformylation, Condensation Application: Plasticizers, Synthetic Resins, Pesticides, Pharmaceuticals, Rubber Chemicals End User Industry: Chemical Manufacturing, Agrochemical Producers, Pharmaceutical Formulators, Polymer Processors, Adhesive Manufacturers |
| Companies Covered | Nantong Acetic Acid Chemical Co., Ltd, Shandong Kunda Biotechnology Co., Ltd, Celanese Corporation, Tokyo Chemical Industry Co., Ltd, Haihang Industry Co., Ltd, BASF SE, Eastman Chemical Company, Jubilant Ingrevia Limited, Godavari Biorefineries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crotonaldehyde Market Strategic Shifts & Innovations
A fundamental shift toward higher-purity grades and sustainable manufacturing is underway, driven by stringent end-use requirements in life sciences and tightening environmental regulations. This pivot moves the market's focus from sheer volume to specialized, value-added chemical synthesis.
Continuous flow chemistry using microreactors provides precise control over the highly exothermic aldol condensation reaction used to produce crotonaldehyde. Specialty chemical and pharmaceutical intermediate manufacturers are adopting this approach to improve safety, selectivity, and product consistency. This advanced synthesis method is collapsing the economic and safety barriers associated with traditional, large-scale batch reactors, enabling more flexible production.
The European Union's REACH regulation continues to exert significant influence on the supply chain. Its mandate for comprehensive substance registration forces producers to generate extensive data on crotonaldehyde's health and environmental impacts. The agrochemical and polymer additive segments are most affected, investing heavily in toxicological studies and reformulation to ensure their products remain compliant for access to the European market.
A notable behavioral change involves customers demanding application-specific grades with certified impurity profiles. This trend disrupts the legacy model of supplying a single technical-grade product, forcing producers to develop capabilities for advanced purification and detailed analytical certification. The shift is most visible in the North American and European pharmaceutical and food ingredient sectors, where regulatory scrutiny is highest.
Crotonaldehyde Market Segmentation
The crotonaldehyde market's segmentation highlights the diverse requirements of end-use industries and the varying purity standards across its product applications. Understanding these distinctions is crucial for manufacturers to optimize production processes and target specific customer needs effectively. This granular view reveals where value creation is concentrated within the broader chemical value chain.
Product Type:
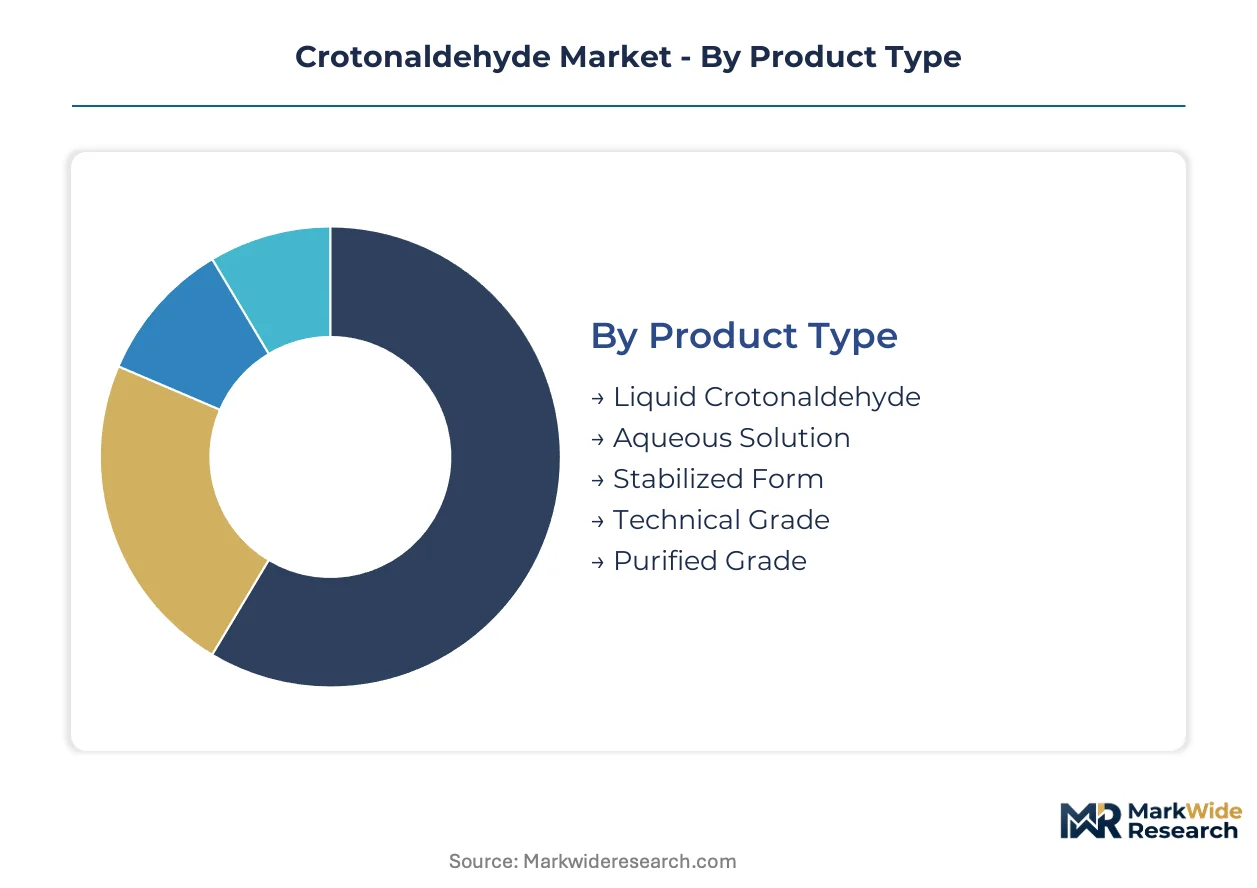
The product type segmentation reveals a market balancing mature, high-volume offerings with emerging, specialized grades demanding stringent purity.
- Purified Grade:This segment comprises crotonaldehyde with minimal impurities, often exceeding 99% purity, essential for sensitive applications. Demand concentrates in the North American and European pharmaceutical and food ingredient sectors, driven by rigorous regulatory standards from agencies like the FDA and EFSA.
- Technical Grade:Technical grade crotonaldehyde represents the bulk volume, characterized by standard industrial purity levels suitable for less demanding applications. This material dominates production for large-scale industrial accounts, particularly in the synthesis of high-volume chemicals and resins.
- Liquid Crotonaldehyde:This refers to the standard physical state of the chemical as a clear, colorless liquid, primarily used directly as an intermediate.
- Aqueous Solution:Crotonaldehyde is supplied as an aqueous solution for certain applications, offering easier handling and reduced volatility compared to its pure liquid form.
- Stabilized Form:The stabilized form includes inhibitors to prevent polymerization and degradation during storage and transport, crucial for maintaining product integrity in logistics.
Technical Grade crotonaldehyde retains volume leadership; Purified Grade holds the steepest expansion curve.
Technology:
Technology segmentation highlights the varying efficiency and cost profiles inherent in crotonaldehyde synthesis pathways.
- Condensation:The aldol condensation of acetaldehyde is the primary and most established industrial route for crotonaldehyde production, offering high yields and established process economics. This method is foundational for large-scale manufacturing, especially in specialized chemical industrial parks in China.
- Catalytic Hydrogenation:While not a primary production method for crotonaldehyde itself, catalytic hydrogenation processes are crucial for converting crotonaldehyde into various downstream derivatives like n-butanol and crotyl alcohol. This transformation is vital for value-added chemical synthesis in Europe.
- Oxidation Process:Alternative routes involving oxidation of other precursors exist, but they are less common for direct crotonaldehyde production compared to condensation.
- Dehydrogenation:Dehydrogenation processes can be used to produce unsaturated aldehydes, though this method is less prevalent for crotonaldehyde specifically than the aldol route.
- Hydroformylation:This technology is primarily used for producing aldehydes from olefins and synthesis gas, offering a route to various aldehyde intermediates, but not typically the direct synthesis of crotonaldehyde.
Condensation remains the foundational production method, while catalytic processes offer pathways for greener synthesis.
Application:
Application segments are defined by their distinct volume contributions and the specific performance requirements of downstream products.
- Pesticides:Crotonaldehyde serves as a critical building block for manufacturing next-generation pesticides and fungicides, supporting agricultural productivity. Demand from agrochemical producers in developing agricultural economies drives significant volume growth in this segment.
- Pharmaceuticals:In the pharmaceutical sector, crotonaldehyde is an intermediate for synthesizing vitamins, active pharmaceutical ingredients, and sorbic acid, a key preservative. This application commands higher-purity grades and offers substantial margin opportunities for producers.
- Plasticizers:Crotonaldehyde derivatives are utilized in the production of plasticizers, which enhance the flexibility and durability of polymers.
- Synthetic Resins:As a versatile aldehyde, crotonaldehyde contributes to the synthesis of various synthetic resins, influencing their chemical and physical properties.
- Rubber Chemicals:Crotonaldehyde finds application in the formulation of rubber chemicals, impacting the processing and performance characteristics of rubber products.
Pesticides continue to drive significant volume, with pharmaceutical demand increasingly influencing purity standards.
End User Industry:
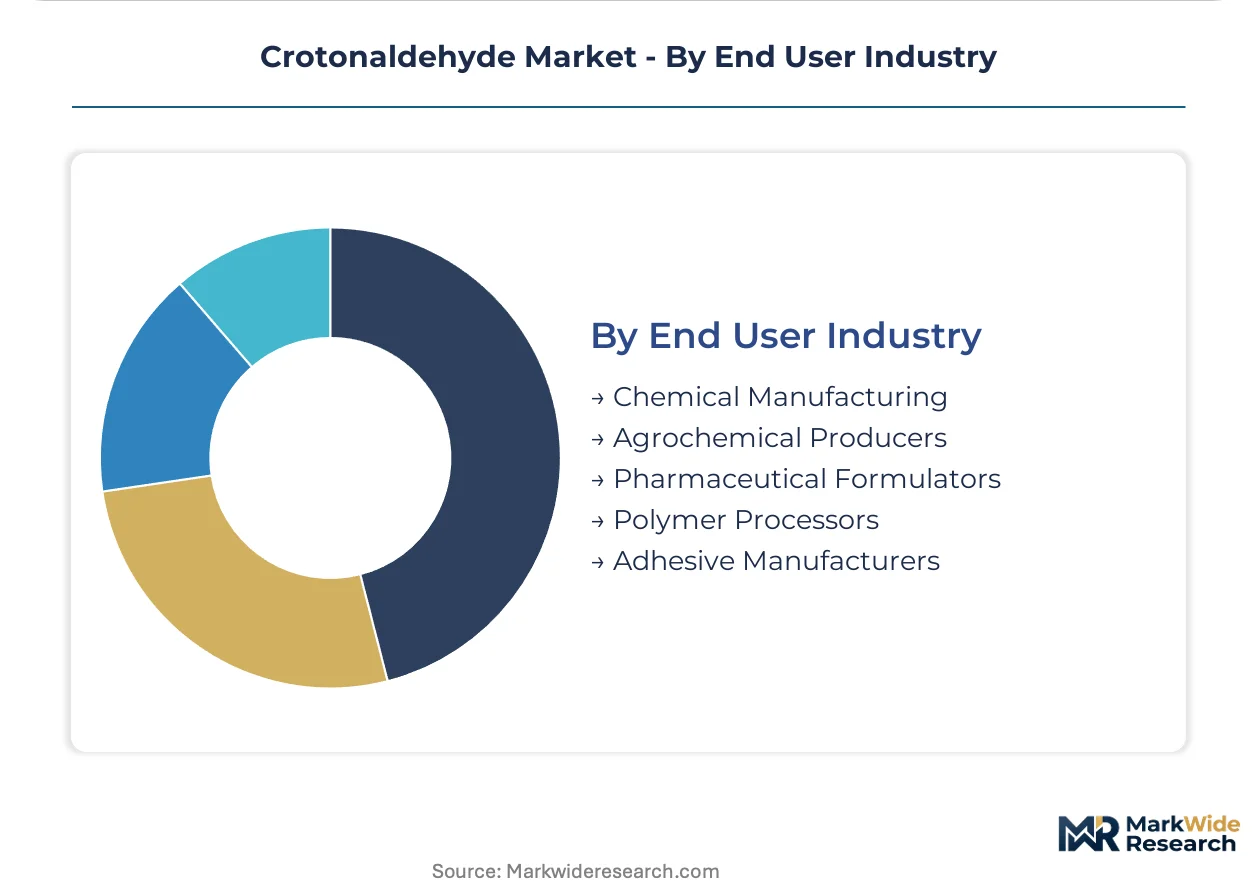
End user industry segmentation reflects the strategic importance of crotonaldehyde as a chemical intermediate across diverse manufacturing sectors.
- Agrochemical Producers:This industry segment represents a major consumer of crotonaldehyde, utilizing it as a precursor for advanced crop protection chemicals. Agrochemical producers, particularly in regions with expanding agricultural sectors, drive substantial demand for the chemical.
- Pharmaceutical Formulators:Pharmaceutical formulators require high-purity crotonaldehyde derivatives for synthesizing complex molecules, including vitamins and specific drug intermediates. This sector demands stringent quality control and certified impurity profiles from its suppliers.
- Chemical Manufacturing:The broader chemical manufacturing sector uses crotonaldehyde as a versatile intermediate for producing a wide array of organic compounds.
- Polymer Processors:Polymer processors integrate crotonaldehyde-derived additives and monomers into their production to enhance material properties.
- Adhesive Manufacturers:Adhesive manufacturers utilize crotonaldehyde in formulations that contribute to the specific bonding characteristics and performance of their products.
Agrochemical Producers represent a critical demand base, as Pharmaceutical Formulators seek specialized, high-value intermediates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for crotonaldehyde varies significantly, with high-purity pharmaceutical applications exhibiting low price sensitivity while technical-grade material for bulk chemicals faces greater pressure. This market dynamic shapes regional investment priorities for production and distribution. Manufacturers prioritize strategic locations to serve both high-value and volume-driven segments.
China
China's demand for crotonaldehyde is primarily driven by its extensive agrochemical industry and the development of specialized chemical industrial parks. The Ministry of Ecology and Environment (MEE) enforces stringent environmental standards, compelling producers to invest in cleaner manufacturing technologies. Chemical industrial parks in regions like the Yangtze River Delta offer integrated infrastructure and shared utilities, fostering efficient production of downstream derivatives.
United States
The United States market emphasizes high-purity crotonaldehyde for pharmaceutical intermediates and specialized chemical applications. Regulations from the US Environmental Protection Agency (EPA) mandate strict controls on handling and emissions, influencing production processes. Major chemical manufacturing hubs in states like Texas and Louisiana are adapting to these standards, focusing on advanced purification and sustainable synthesis routes.
Germany
Germany represents a key European hub for value-added crotonaldehyde derivatives, particularly in the pharmaceutical and specialty chemical sectors. The European Chemicals Agency (ECHA) and REACH regulation necessitate comprehensive substance registration and strict purity standards. Integrated chemical complexes, such as those in Ludwigshafen, are pivotal for developing advanced catalytic processes and producing high-grade materials for European markets.
India
India's expanding life sciences and agrochemical industries are driving demand for crotonaldehyde as a crucial intermediate. Regulatory bodies like the Central Drugs Standard Control Organization (CDSCO) influence the quality requirements for pharmaceutical applications. Industrial clusters in states such as Gujarat and Maharashtra are emerging as significant production centers, serving both domestic consumption and export markets for specialty chemicals.
Japan
Japan's crotonaldehyde market is characterized by a focus on specialty chemicals and advanced materials, with a strong emphasis on environmental compliance. The country's strict industrial safety and environmental regulations guide manufacturing practices. Chemical industrial zones, particularly in regions like Kansai, concentrate on research and development for novel derivatives and sustainable production methods.
Crotonaldehyde Market Key Industry Players
Capability concentration sits with one tier, focusing on high-purity and specialized derivatives, while scale advantage sits with another, dominating technical-grade production. The market structure exhibits a tiered consolidation, with large integrated chemical companies alongside specialized producers. Strategic archetypes include diversified chemical giants, niche specialty chemical manufacturers, and regional players. Portfolio diversification and strategic partnerships represent dominant competitive moves among these archetypes.
Within the diversified chemical giants archetype, Celanese Corporation and BASF SE exemplify companies leveraging extensive production capabilities and broad product portfolios. Jubilant Ingrevia Limited occupies a position as a specialized producer, focusing on intermediates for the life sciences and agrochemical sectors. These companies anchor their competitive positioning through integrated supply chains and advanced derivative offerings. Their market presence reflects a strategic emphasis on both high-volume technical grades and high-margin purified products.
| Leading Market Players |
|---|
| Nantong Acetic Acid Chemical Co., Ltd |
| Shandong Kunda Biotechnology Co., Ltd |
| Celanese Corporation |
| Tokyo Chemical Industry Co., Ltd |
| Haihang Industry Co., Ltd |
| BASF SE |
| Eastman Chemical Company |
| Jubilant Ingrevia Limited |
| Godavari Biorefineries Ltd |
| Others |
Cost & Logistics Intelligence
Acetaldehyde feedstock price volatility, stemming from petrochemical and agricultural commodities, directly influences the cost structure of crotonaldehyde production, shifting margin pools towards specialized, high-purity derivatives. This upstream dynamic dictates downstream pricing power.
Pricing Analysis
High-purity pharmaceutical intermediates, demanding stringent quality control and certified impurity profiles, command premium pricing and drive long-term value. The dominant pricing model for technical grade crotonaldehyde is contract-based long-term offtake, while purified grades utilize value-based pricing. Price differentiation arises from specific regulatory certifications and required purity levels. Pricing pressure on technical grade material stems from feedstock price fluctuations, but pharmaceutical formulators demonstrate lower price sensitivity for specialized derivatives.
Supply Chain Analysis
Logistical complexity, driven by crotonaldehyde's inherent toxicity and reactivity, imposes significant costs on its supply chain. Production concentrates in specialized chemical industrial parks in China and integrated chemical complexes in Germany. The supply chain relies heavily on acetaldehyde as a primary feedstock, linking it to broader petrochemical markets. Distribution runs through direct sales channels for large industrial accounts and specialized distributors for high-purity applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The crotonaldehyde market reveals a critical shortage of advanced purification and certified analytical capabilities. This scarcity drives competitive advantage, particularly for producers serving sensitive end-use applications like pharmaceuticals.
For Market Incumbents: Pre-empt emerging substitution threats by investing in novel catalytic processes and bio-based production routes. Deepen vertical integration into high-purity derivative manufacturing, securing long-term supply agreements with pharmaceutical formulators. Capacity expansion in European chemical complexes, coupled with stringent certification investment, protects market share against regulatory shifts like REACH. This strategic focus mitigates risks from alternative synthesis pathways.
For New Entrants and Emerging Players: Establish a beachhead in the high-purity pharmaceutical intermediates segment, leveraging advanced purification technologies. Target the expanding life sciences sector in India, which presents an opportunity for supplying specialized agrochemical building blocks. A go-to-market strategy focusing on continuous flow chemistry can offer superior product consistency and safety, appealing to stringent end-users. This approach bypasses the capital intensity of traditional batch processes.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialized chemical producers focusing on high-purity crotonaldehyde derivatives. The market offers long-term viability given its essential role in pharmaceutical and agrochemical synthesis. Target acquisition archetypes include niche specialty chemical manufacturers with proven expertise in green chemistry pathways or advanced purification. A signal to watch is increased M&A activity for companies holding intellectual property in continuous flow chemistry.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Secures long-term market access under tightening environmental regulations. |
| Capacity Expansion | Meets growing demand from agrochemical producers in developing economies. |
| Long-term Supply Agreement | Stabilizes revenue streams for high-purity pharmaceutical intermediates. |
| Joint Venture | Accelerates development of novel catalytic processes for sustainable production. |
| R&D Investment in Purification | Enhances product quality for sensitive food and pharmaceutical applications. |
Research Approach
Desk research of customs/trade data, industry association reports, and regulatory agency publications preceded structured interviews with plant managers, procurement leads, and technical R&D directors. This primary fieldwork validated secondary findings, ensuring comprehensive market understanding. The analysis employed both bottom-up and top-down triangulation to derive robust market estimates.
Assumptions regarding feedstock price stability and regulatory compliance costs were held constant across the analysis window. The analytical framework modeled market dynamics by product type, application, end-user industry, and regional regulatory environment. Compound annual growth rates were derived from projected volume and value outputs. This comprehensive approach integrated industry-specific inputs like production capacity additions.
Sensitivities concentrate around unforeseen regulatory shifts and significant feedstock supply disruptions. Forecasts reflect current market dynamics and producer investment intentions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Ketene Market
Solvents
Hexylene Glycol Market
Solvents
Diethanolamide Market
Solvents
India High Purity Solvents Market
Solvents
Isoparaffin Solvents Market
Solvents
Mineral Turpentine Market
Solvents
Global Green and Bio-Based Solvents Market
Solvents
Xylene Market
Solvents
2-Phenylethanol Market
Solvents
Propylene Glycol Methyl Ether Market
Solvents
Global Ink Solvents Market
Solvents
Vapor Degreasing Solvents Market
Solvents
Green Solvents Market
Solvents
Methyl Diethanolamine Market
Solvents
Pharmaceutical Solvent Market
Solvents
Saudi Arabia Methanol Market