
 Diethylene Glycol Monobutyl Ether Market | 2026-2036
Diethylene Glycol Monobutyl Ether Market Size, Share, and Industry Trends Forecast 2026-2036
Diethylene Glycol Monobutyl Ether Market Analysis
REACH restrictions on volatile organic compounds are restructuring formulation preferences across European coatings supply chains. Dow Chemical Company leverages backward integration into ethylene oxide feedstocks to sustain margin stability. BASF anchors its position through specialized solvent blends tailored to waterborne industrial coatings.
Diethylene Glycol Monobutyl Ether is a butyl ether of diethylene glycol with the molecular formula C8H18O3, manufactured through the catalytic etherification of ethylene glycol with n-butanol; it functions primarily as a high-boiling solvent with excellent coalescing properties for surface coatings and cleaning applications. Solvent-grade material dominates volume consumption in paints and inks applications where slow evaporation rates enable flow and leveling control. Coating agent formulations for automotive end users represent the fastest-expanding demand pool as OEMs transition from solvent-borne to waterborne systems.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent emissions from coating operations, while OSHA permissible exposure limits govern workplace handling protocols for glycol ether compounds. China's MEE enforces dual carbon goals that tighten volatile organic compound discharge permits for manufacturing facilities using conventional solvents. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with divergent compliance thresholds.
Market Dynamics
Waterborne coating transitions across automotive and industrial sectors are compressing solvent selection windows, forcing reformulation investments while simultaneously expanding addressable volume for high-boiling coalescing agents.
Growth Catalysts
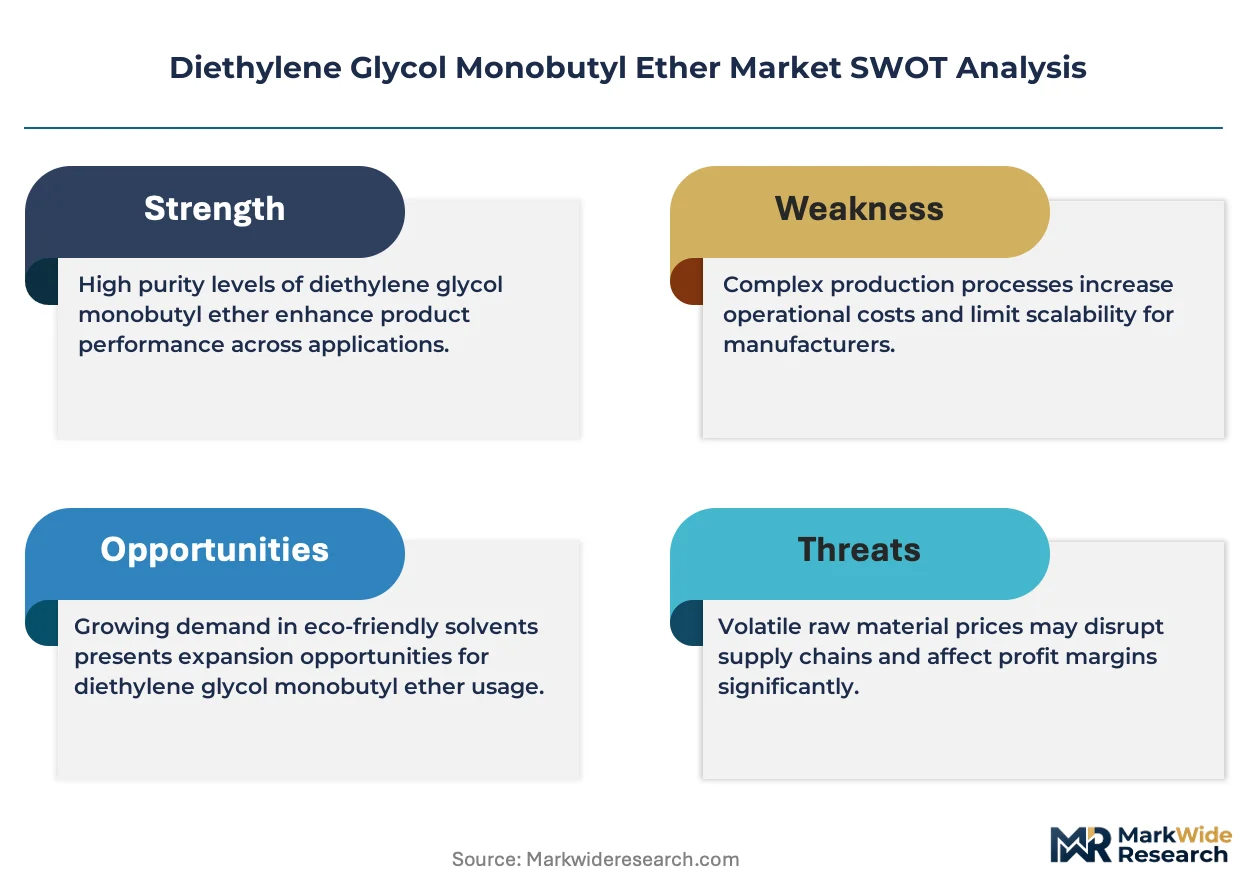
- REACH VOC restrictions:European coatings manufacturers face mandatory solvent emission reductions, redirecting procurement toward compliant glycol ether alternatives.
- China's automotive manufacturing scale:Domestic OEM capacity expansion drives concentrated demand for refinishing solvents in waterborne basecoat systems.
- High-boiling coalescing technology:Slow-evaporation solvent properties enable superior film formation in ambient-cure industrial coatings.
Market Restraints
- Ethylene oxide feedstock volatility:Crude oil price swings transmit directly to diethylene glycol production economics, compressing margin stability.
- Northeast Asian supply concentration:Chinese and South Korean producers control majority capacity, creating geographic vulnerability for Atlantic buyers.
- Propylene glycol ether substitution:Lower-toxicity alternatives gain traction in consumer-facing cleaning formulations, eroding traditional application share.
Strategic Opportunities
- India's industrial coatings penetration:Domestic manufacturing incentives under PLI schemes accelerate solvent demand from underdeveloped automotive refinishing infrastructure.
- EPA NESHAP compliance services:Technical consulting and reformulation support create service-layer revenue above commodity solvent sales.
- MEE dual carbon enforcement:China's tightening VOC discharge permits favor suppliers with verified low-emission production processes.
Industry Challenges
- Specialized formulation chemist scarcity:Waterborne system expertise gaps delay customer technical service response times.
- Multi-jurisdiction certification complexity:Divergent OSHA, REACH, and GB standard exposure limits complicate unified product portfolio management.
- Legacy solvent-borne equipment retrofit costs:End-user capital constraints slow waterborne transition timelines despite regulatory pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diethylene Glycol Monobutyl Ether Market |
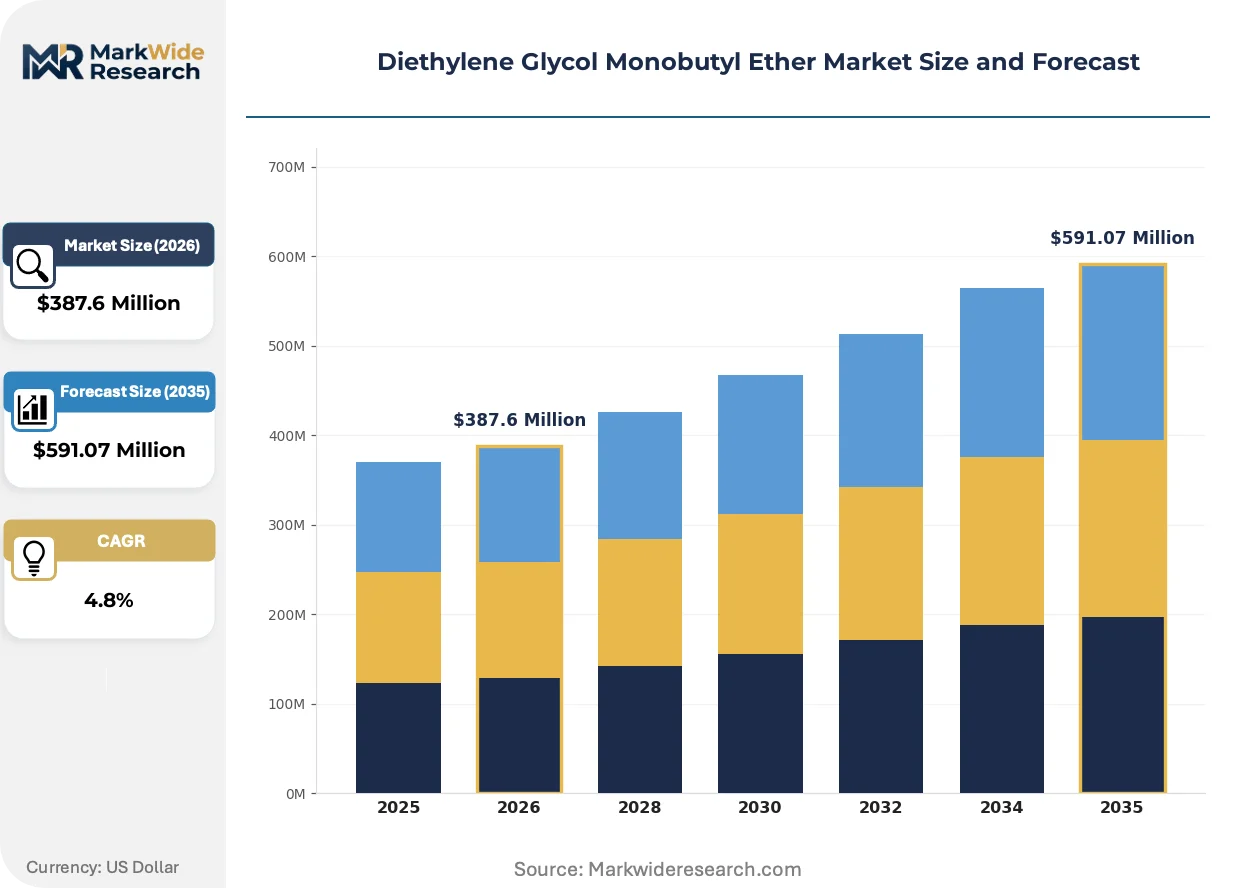
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Surfactant, Coating Agent, Cleaning Agent Application: Paints, Inks, Adhesives, Personal Care End User: Manufacturing, Automotive, Construction, Consumer Goods Delivery Mode: Bulk, Drum, Tote, Small Containers |
| Companies Covered | Dow Chemical Company, LyondellBasell Industries, BASF, SABIC, Bharat Petroleum Corporation Limited, Kraton Corporation, Huntsman Corporation, Shell, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diethylene Glycol Monobutyl Ether Market Emerging Trajectories
Reformulation chemistry is accelerating as regulatory thresholds tighten across major manufacturing jurisdictions, compressing development cycles and rewarding solvent suppliers with technical service depth.
Reactive diluent technology is unifying coalescing performance with reduced volatile organic compound contribution in two-component polyurethane coatings. Automotive refinish shops in Germany and the US Midwest are adopting these hybrid systems at twice the rate of conventional waterborne conversions. This unification is collapsing the historical trade-off between application latitude and emission compliance.
REACH authorization requirements for Substances of Very High Concern are forcing coatings formulators to document solvent substitution rationales in supply chain audits. Industrial maintenance coatings sold into European marine and offshore infrastructure face the strictest documentation burdens. Formulators are responding by consolidating supplier relationships with glycol ether producers holding full substance registration dossiers.
Specification-driven procurement is concentrating buying power among tier-one automotive OEMs and their approved refinish networks. Distributor intermediaries lose ground as direct technical partnerships between solvent manufacturers and certified body shops replace traditional resale relationships. This pattern is most pronounced in China's eastern province manufacturing clusters where state-owned vehicle brands enforce unified coating standards.
Diethylene Glycol Monobutyl Ether Market Segmentation
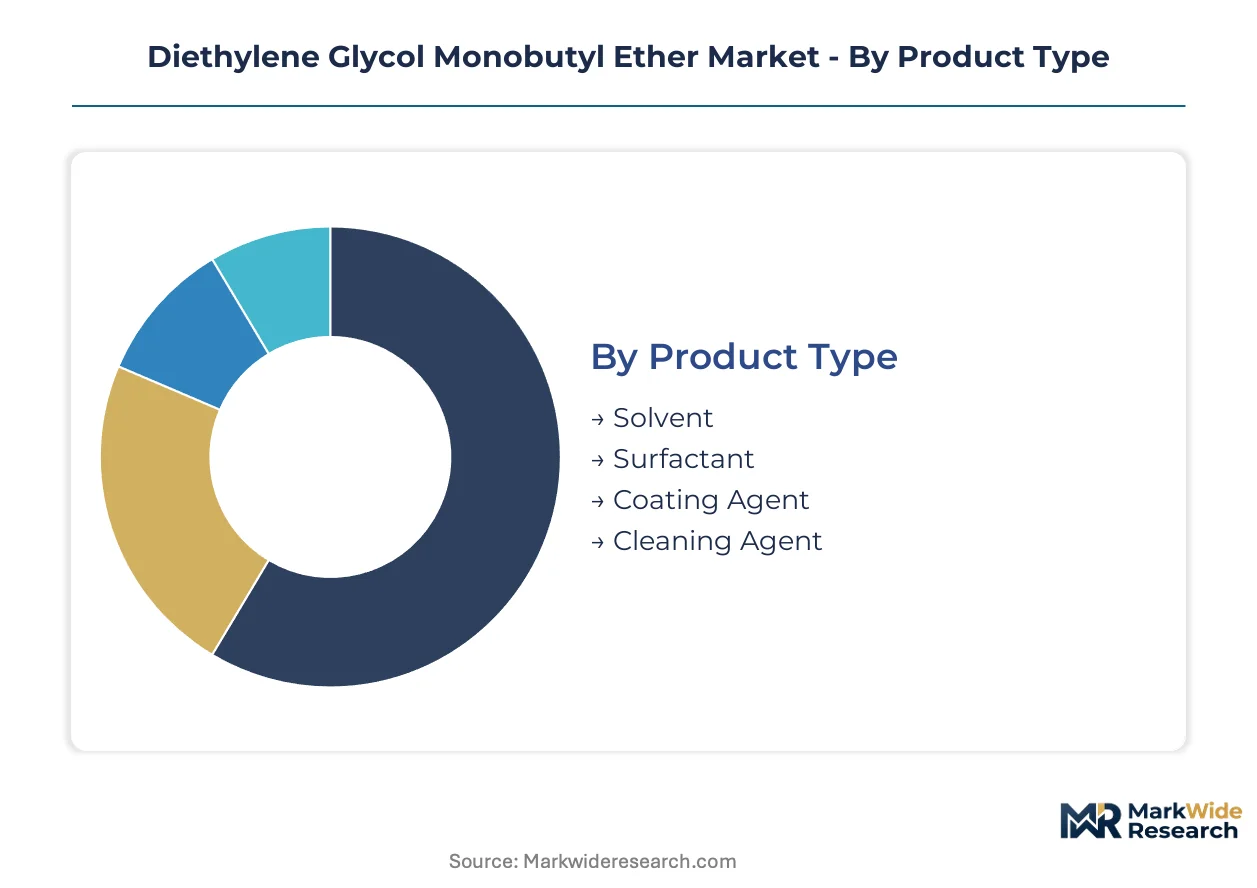
Diethylene Glycol Monobutyl Ether demand fragments across formulation roles and delivery logistics that reshape procurement economics. Buyers balance coalescing performance against VOC compliance thresholds while managing inventory carrying costs tied to packaging scale.
Product Type:
Formulators select product grades based on evaporation profile requirements and regulatory emission budgets for finished goods.
- Solvent:High-boiling glycol ether with slow evaporation rates enables flow control in ambient-cure industrial coatings. Demand concentrates in automotive refinishing across Germany and the US Midwest as shops convert from solvent-borne to waterborne basecoats under EPA NESHAP and REACH VOC limits.
- Coating Agent:Specialized coalescing additive promotes film formation in latex systems at low temperatures. Chinese automotive OEMs in Shanghai and Guangdong manufacturing clusters drive procurement volume for waterborne clearcoat formulations meeting MEE dual carbon enforcement.
- Surfactant:Surface-active properties reduce interfacial tension in aqueous cleaning formulations.
- Cleaning Agent:Grease-cutting solvency targets industrial maintenance and electronics degreasing applications.
Volume sits with Solvent; growth tilts toward Coating Agent.
Application:
End-use specifications determine purity grades and certification documentation burdens across downstream markets.
- Paints:Architectural and industrial coating formulations consume the majority of solvent-grade material. German marine coatings producers face REACH Substances of Very High Concern documentation requirements that favor suppliers with complete registration dossiers.
- Inks:Publication gravure and flexographic printing rely on controlled evaporation for print clarity. Chinese packaging converters in Zhejiang province scale waterborne ink capacity under tightening MEE discharge permits.
- Adhesives:Pressure-sensitive and laminating adhesive formulations require consistent coalescing performance.
- Personal Care:Cosmetic-grade specifications demand low-odor, high-purity material for fragrance solubilization.
Procurement weight rests with Paints; reformulation activity runs fastest in Inks.
End User:
Customer scale and technical service requirements fragment pricing power and contract structures.
- Automotive:OEM-approved refinish networks enforce specification-driven procurement with direct manufacturer relationships. China's state-owned vehicle brands in eastern province clusters mandate unified coating standards that bypass traditional distributor channels.
- Manufacturing:Industrial maintenance coatings for marine and offshore infrastructure in European ports face strictest REACH authorization documentation.
- Construction:Architectural coatings producers balance cost pressure against VOC compliance in decorative paint lines.
- Consumer Goods:Household cleaning formulations face substitution pressure from propylene glycol ether alternatives.
Contract value concentrates in Automotive; expansion opportunity sits with Manufacturing.
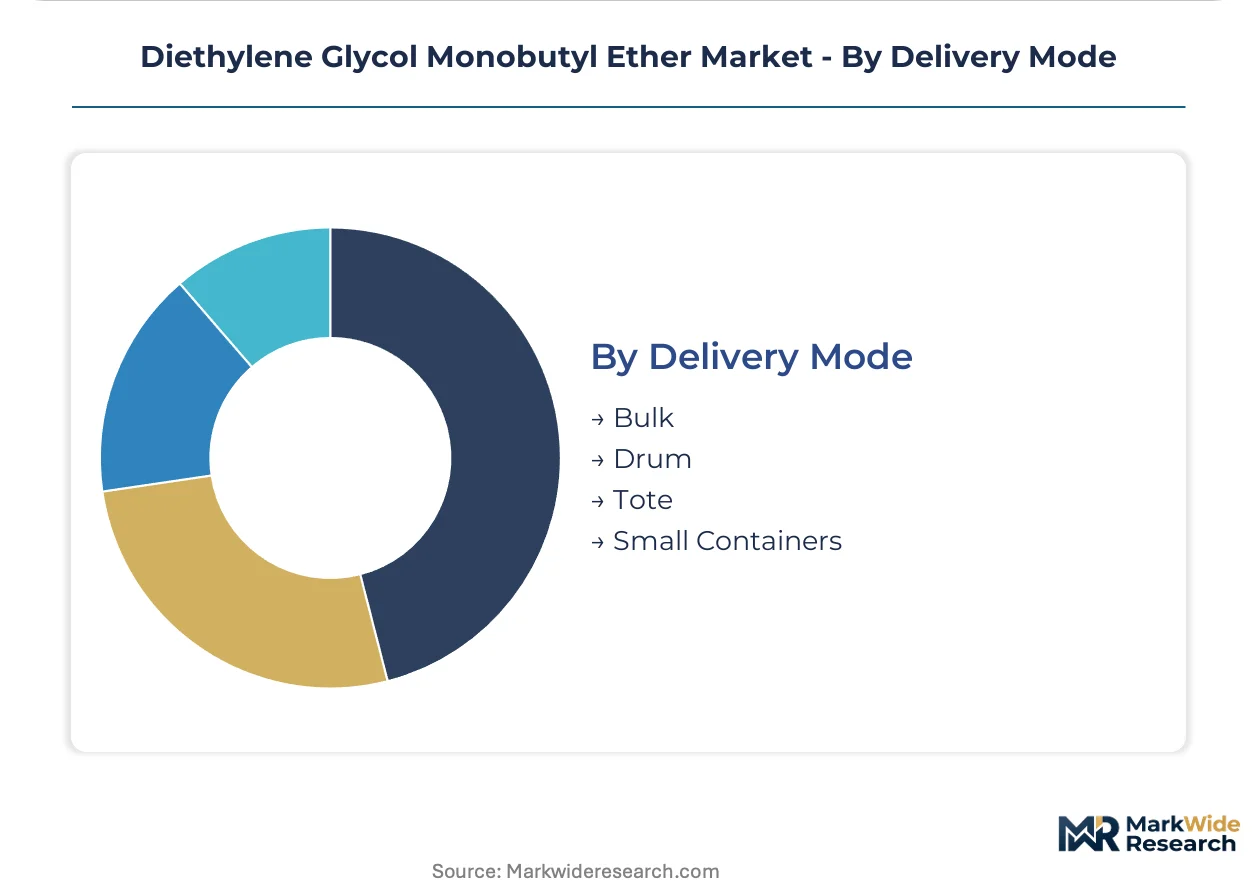
Delivery Mode:
Packaging economics and inventory velocity determine working capital requirements and freight optimization.
- Bulk:Tank truck and railcar delivery serves high-volume coating plants with dedicated storage infrastructure. German automotive refinishing hubs and Chinese OEM manufacturing parks favor direct bulk supply to minimize handling costs.
- Drum:Standard 55-gallon steel drums balance mobility with volume for mid-scale formulators.
- Tote:Intermediate bulk containers reduce drum waste for medium-volume consumers.
- Small Containers:Pails and cans serve specialty chemical distributors and laboratory-scale buyers.
Shipment volume flows through Bulk; flexibility premium attaches to Small Containers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's automotive manufacturing corridor anchors solvent demand as Chinese OEMs scale waterborne coating capacity under tightening environmental enforcement.
China
Domestic automotive production in Guangdong and Jiangsu provinces drives concentrated consumption of coating-grade material. MEE dual carbon goals tighten VOC discharge permits for manufacturing facilities, favoring suppliers with verified low-emission processes. State-owned vehicle brands in eastern province clusters mandate unified coating standards that bypass traditional distributor channels.
Germany
Automotive refinishing hubs in Bavaria and Baden-Württemberg convert from solvent-borne to waterborne basecoats. REACH authorization requirements for Substances of Very High Concern force coatings formulators to document solvent substitution rationales. Marine coatings producers in Hamburg and Bremen ports face strictest documentation burdens for industrial maintenance applications.
United States
Midwest automotive refinish shops adopt reactive diluent technology at twice the rate of conventional waterborne conversions. EPA NESHAP regulations constrain solvent emissions from coating operations across Michigan and Ohio manufacturing belts. Specification-driven procurement concentrates buying power among tier-one OEMs and their approved refinish networks.
South Korea
Busan-Ulsan petrochemical complexes supply glycol ether derivatives to domestic coatings formulators. KOSHA workplace exposure limits govern handling protocols for glycol ether compounds in manufacturing facilities. Industrial coatings producers in the Seoul Capital Area accelerate reformulation investments under tightening environmental enforcement.
India
Domestic manufacturing incentives under PLI schemes accelerate solvent demand from underdeveloped automotive refinishing infrastructure in Maharashtra and Gujarat. BIS certification requirements for industrial chemicals create entry barriers for unverified imports. Specialty solvent distributors in Tamil Nadu establish technical service partnerships to address formulation chemist scarcity.
Diethylene Glycol Monobutyl Ether Market Vendor Landscape
The competitive structure tilts toward integrated petrochemical conglomerates with captive ethylene oxide feedstock positions. Dow Chemical Company and BASF anchor the premium tier through backward integration into raw material supply chains. Mid-scale regional producers compete on logistics proximity to Asian manufacturing clusters. Dominant competitive moves include capacity expansion in China and strategic partnerships for waterborne coating formulation support.
Among US-based integrated producers, Dow Chemical Company and Eastman Chemical Company occupy positions emphasizing upstream control over ethylene oxide derivatives. LyondellBasell Industries represents the scale-driven archetype with broad petrochemical portfolio diversification. BASF anchors the European specialist tier through registration dossier completeness for REACH compliance.
| Leading Market Players |
|---|
| Dow Chemical Company |
| LyondellBasell Industries |
| BASF |
| SABIC |
| Bharat Petroleum Corporation Limited |
| Kraton Corporation |
| Huntsman Corporation |
| Shell |
| Eastman Chemical Company |
| Others |
Supply Flow & Price Mechanics
Waterborne coating transitions across automotive refinishing simultaneously compress margin structures and concentrate procurement power among integrated suppliers with captive ethylene oxide positions. Dow Chemical Company and BASF leverage backward integration into feedstock supply to defend pricing power against spot-market volatility in diethylene glycol derivatives.
Pricing Analysis
Value-based pricing anchors on film formation performance in ambient-cure waterborne systems, with coating-grade material commanding premium spreads over commodity solvent grades. Price differentiation separates REACH-registered suppliers with complete SVHC documentation from unregistered traders facing audit exclusion. Pricing pressure intensifies in standard solvent grades as Chinese domestic capacity expansion floods regional spot markets. Tier-one automotive OEMs exhibit lowest price sensitivity given specification-locked procurement, while mid-scale industrial formulators in India and Southeast Asia drive hard volume negotiations.
Supply Chain Analysis
China's domestic-content enforcement under MEE dual carbon permitting favors local glycol ether producers with verified low-emission processes, reshaping sourcing patterns for multinational coatings formulators. Supply concentrates in China, South Korea, and Germany, with Busan-Ulsan and Ludwigshafen petrochemical complexes serving as Atlantic and Pacific basin anchors. Raw material dependencies center on ethylene oxide, n-butanol, and catalytic etherification capacity. Single-source vulnerability runs through Northeast Asian ethylene oxide derivatives. Distribution runs through direct bulk supply to automotive OEM parks, bypassing traditional distributor channels in China's eastern province clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive ethylene oxide supply determines margin sustainability. Players pursuing upstream control into feedstock production gain structural advantage over formulation-dependent competitors.
For Market Incumbents: Deploy technical service depth as a retention lever against propylene glycol ether substitution threats in consumer-facing cleaning applications. BASF and Dow Chemical Company should extend REACH registration dossier completeness into Substances of Very High Concern audit support services, creating switching costs for European marine coatings producers. Capacity addition in China's Jiangsu province manufacturing corridor captures domestic automotive OEM procurement consolidation. For New Entrants and Emerging Players: EPA NESHAP compliance services in the US Midwest open a window for technical consulting revenue above commodity solvent sales. India's PLI-driven automotive manufacturing incentives present the most penetrable geography, with Maharashtra and Gujarat refinishing infrastructure gaps demanding specialty solvent distributors with formulation chemist partnerships. Target direct technical relationships with state-owned vehicle brands in China's eastern provinces, bypassing legacy distributor relationships. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale regional producers holding captive ethylene oxide positions and verified MEE low-emission processes, given China's tightening VOC discharge enforcement. Long-term viability over the next decade hinges on backward integration depth and registration dossier completeness for REACH authorization requirements. Watch for inflection signals in automotive OEM waterborne conversion rates across Germany and the US Midwest.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Dow Chemical Company secures margin stability against crude oil volatility in diethylene glycol production economics. |
| REACH Registration Dossier Expansion | BASF consolidates supplier relationships with European marine coatings producers facing SVHC documentation burdens. |
| Capacity Expansion in Jiangsu Province | Domestic Chinese producers capture procurement consolidation from state-owned vehicle brands in eastern manufacturing clusters. |
| Technical Service Partnership Model | Specialty distributors in Tamil Nadu address formulation chemist scarcity for India's PLI-accelerated automotive sector. |
| Reactive Diluent Technology Development | Hybrid system suppliers collapse the trade-off between application latitude and EPA NESHAP emission compliance. |
Methodological Framework
Document review covered customs and trade flow data, SEC 10-K filings from integrated chemical producers, and ECHA REACH registration databases, complemented by interviews with plant managers at glycol ether production facilities, procurement leads at automotive OEM coating operations, distribution channel partners in Asian manufacturing corridors, and technical R&D directors specializing in waterborne formulation chemistry. Bottom-up volume estimates triangulated against top-down market sizing from petrochemical industry association reports.
Segment-level projections across solvent grade, coating agent, surfactant, and cleaning agent categories were generated through demand elasticity modeling tied to automotive production forecasts and industrial coatings penetration rates. The analytical framework incorporated grade-tier differentiation, end-use industry concentration, packaging format economics, and regional production hub competitiveness throughout the forecast period. CAGRs were derived from regression analysis against ethylene oxide feedstock price indices and regulatory enforcement timelines.
Caveats apply where MEE dual carbon enforcement intensity or REACH SVHC list expansion could materially shift the outlook for compliant supplier premiums. Forecasts reflect assumptions regarding waterborne coating conversion rates and ethylene oxide supply availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Global Ethyl Lactate Market
Solvents
Global Chloroform Market
Solvents
Diethylene Glycol (DEG) Market
Solvents
Ortho-Xylene Market
Solvents
Glycerol Market
Solvents
Ionic Liquids Market
Solvents
Global 2-Ethoxyethanol Market
Solvents
Global Glycol Market
Solvents
Acetone Market
Solvents
Diethanolamide Market
Solvents
2-(4-Aminopentyl(Ethyl)Amino)Ethanol Market
Solvents
Mono Propylene Glycol Market
Solvents
Methyl Acetate Market
Solvents
Propylene Glycol Ether Market
Solvents
Butyl Acetate (BAC) Market
Solvents
Trifluoroethanol Market