
 Animal Feed Phytase Market | 2026-2036
Animal Feed Phytase Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Feed Phytase Market Analysis
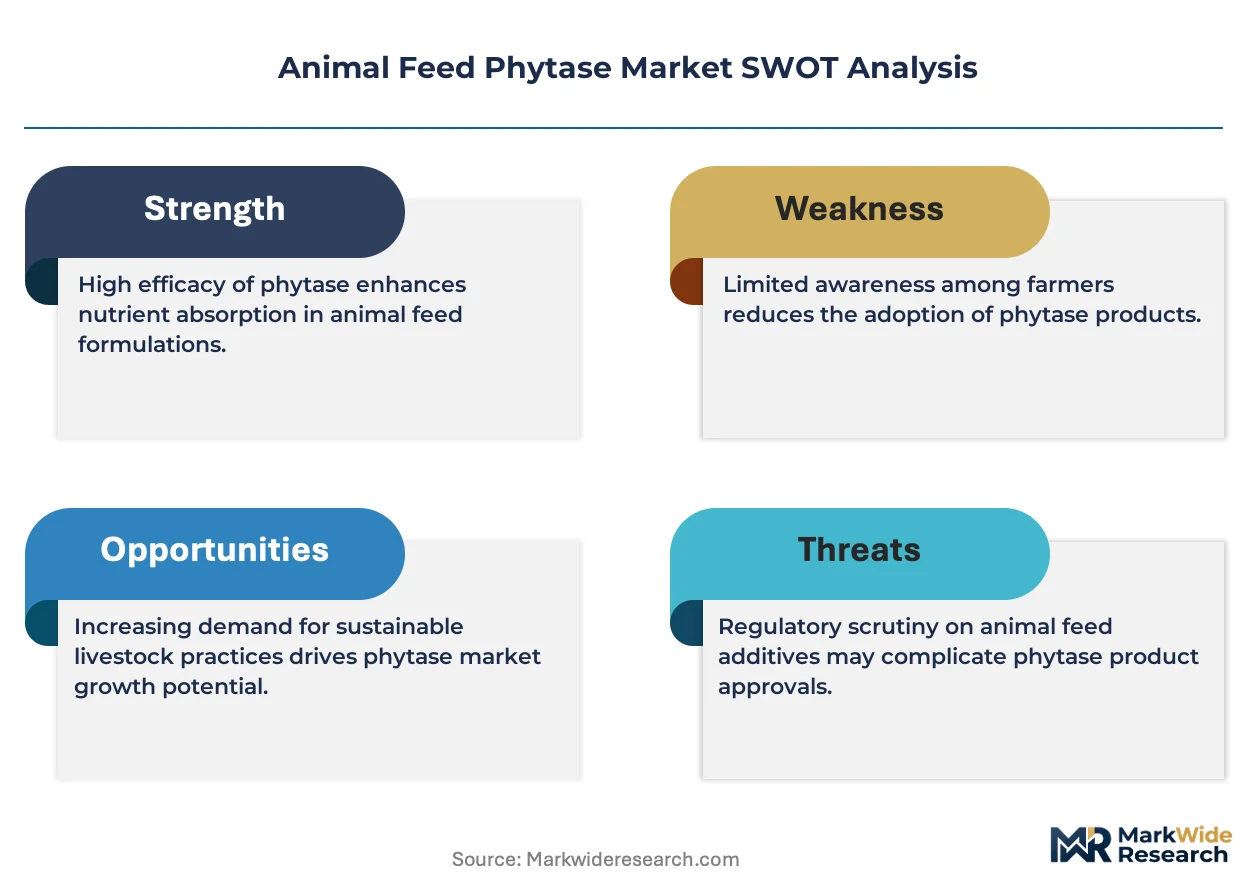
The animal feed phytase market is pivoting around a widening split between premium microbial and recombinant formulations and commodity-grade solid phytase products. BASF SE leverages its integrated biotechnology platform to sustain leadership in high-activity enzyme solutions. AB Enzymes anchors its position in European markets through specialized fungal-derived phytase production. DSM differentiates by dominating the recombinant segment with advanced protein engineering capabilities.
Animal feed phytase comprises enzymes that hydrolyze phytic acid in plant-based feedstuffs, releasing digestible phosphorus and reducing environmental phosphorus excretion; commercial formulations typically express activity levels between 500 and 10,000 FYT per gram depending on concentration and carrier matrix. Solid phytase occupies the largest volume share among product types due to its stability in pelleting processes and lower logistics burden for feed manufacturers. Microbial phytase leads the source category in commercial adoption, while recombinant variants represent the fastest-growing margin pool as producers seek heat-stable alternatives for high-temperature feed processing. Aquaculture feed applications are expanding rapidly as shrimp and finfish operations adopt enzyme supplementation to improve feed conversion ratios in intensive production systems.
The European Food Safety Authority evaluates phytase additives under feed additive authorization protocols, while China's Ministry of Agriculture and Rural Affairs enforces GB standards for enzyme use in compound feeds. The EPA in the United States monitors phosphorus runoff from livestock operations, indirectly steering producers toward phytase adoption as a nutrient management tool. Stakeholders must track evolving enzyme registration pathways and heat-stability benchmarks as feed processing temperatures continue to rise across industrial milling operations.
Market Dynamics
Feed millers are confronting a structural squeeze between rising pelleting temperatures and the thermal degradation limits of conventional phytase formulations, forcing enzyme suppliers to engineer heat-stable alternatives or risk volume displacement.
Growth Catalysts
- China's livestock scaling:The Ministry of Agriculture and Rural Affairs is mandating enzyme supplementation in compound feeds as the country's pork and poultry sectors consolidate operations.
- EPA phosphorus runoff controls:Livestock producers across the Chesapeake Bay watershed face nutrient discharge limits that make phytase adoption a compliance necessity rather than an option.
- Heat-stable protein engineering:Directed evolution techniques now yield phytase variants retaining 85% activity post-pelleting at 85°C, unlocking formulation flexibility for high-temperature feed processing.
Market Restraints
- Fermentation input cost volatility:Corn steep liquor and soybean meal prices swing with commodity grain markets, compressing margins for microbial phytase producers.
- EU regulatory friction:EFSA feed additive authorization timelines stretch 18-24 months, freezing product pipelines and favoring incumbents with established dossiers.
- Phosphorus source substitution:Dicalcium phosphate remains price-competitive in regions with weak environmental enforcement, undermining phytase value propositions.
Strategic Opportunities
- Aquaculture enzyme penetration:Vietnamese shrimp farms and Norwegian salmon operations are accelerating phytase adoption to improve feed conversion ratios in intensive recirculating systems.
- EU F-Gas Regulation tailwinds:Manufacturing emissions constraints favor domestic enzyme production over imported alternatives, creating localization incentives for European suppliers.
- Precision dosing via liquid application:Post-pelleting spray systems enable enzyme recovery rates above 95%, opening retrofit markets among legacy feed mills.
Industry Challenges
- Protein engineering talent scarcity:Directed evolution and computational enzyme design require specialized biochemists that feed additive firms compete for against pharmaceutical and biotech employers.
- Heat stability certification bottlenecks:Commercial claims for thermal tolerance must validate across varying pelleting protocols, creating testing backlogs at third-party laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Feed Phytase Market |
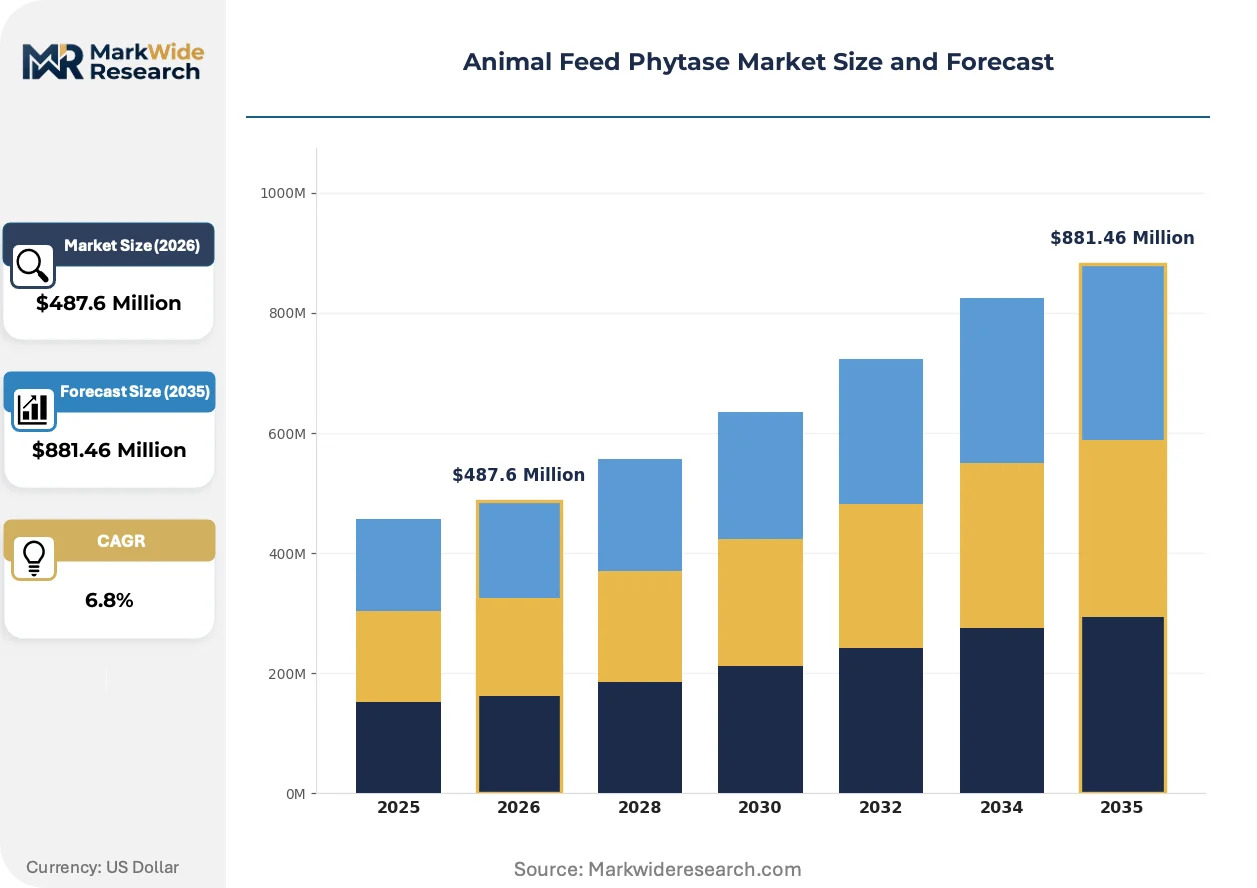
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
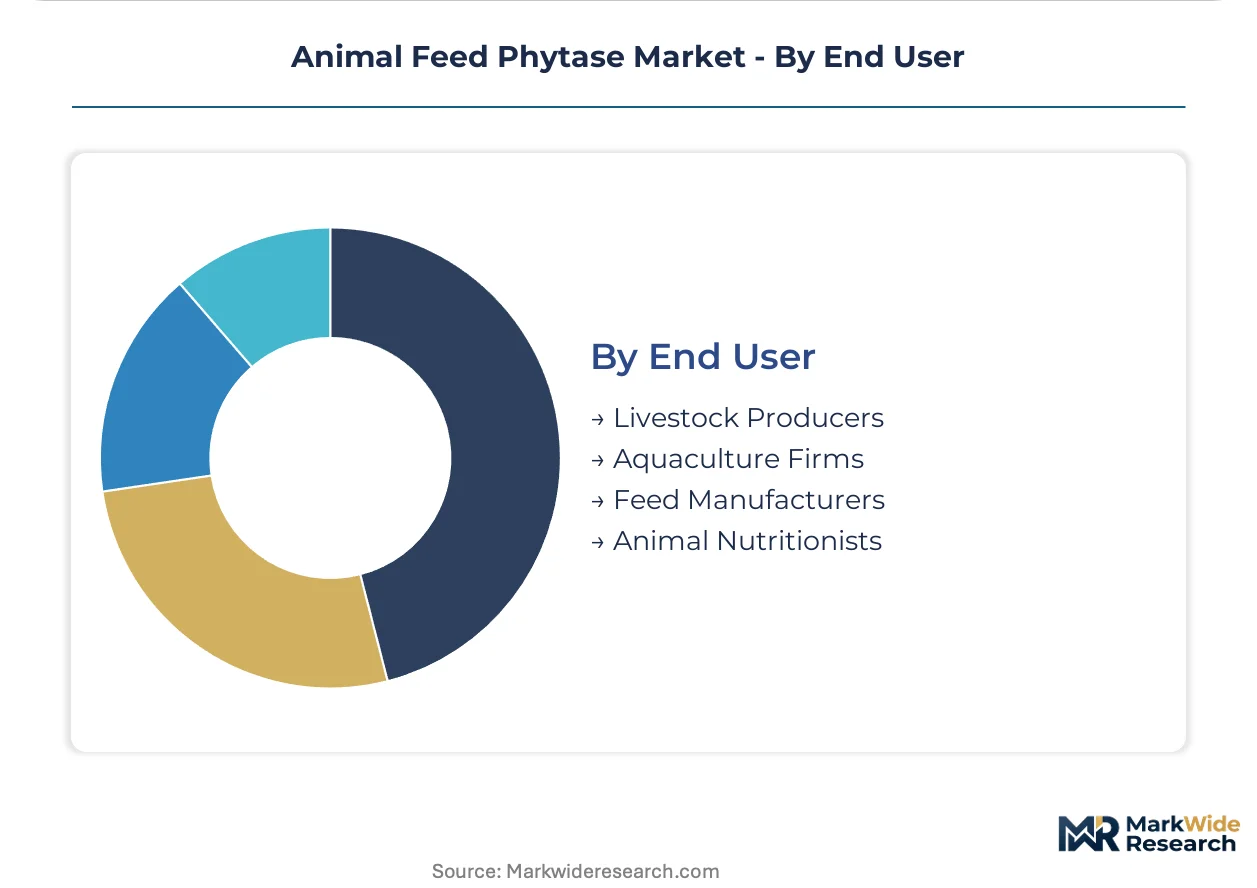
| Segmentation | Product Type: Liquid Phytase, Solid Phytase, Granulated Phytase, Microencapsulated Phytase Application: Poultry Nutrition, Swine Nutrition, Ruminant Feed, Aquaculture Feed Source: Microbial Phytase, Fungal Phytase, Recombinant Phytase, Plant-Based Phytase End User: Livestock Producers, Aquaculture Firms, Feed Manufacturers, Animal Nutritionists |
| Companies Covered | BASF SE, AB Enzymes, DSM, Adisseo, Novozymes, DuPont, Alltech, Novus International, Huvepharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Feed Phytase Market Emerging Trajectories
Enzyme engineering and regulatory stringency are converging to redefine competitive advantage in feed phytase, with thermal tolerance and manufacturing footprint emerging as the decisive differentiators.
Granular phytase formulations are overtaking traditional powder carriers in North American feed mills. These engineered particles withstand pelleting shear and thermal stress while enabling precise dosing via automated handling systems. Major pork and poultry integrators are specifying granular grades in procurement tenders, compressing demand for standard powder products that suffer activity losses during processing.
REACH chemical registration requirements are tightening traceability standards for enzyme manufacturing intermediates. Suppliers must now document full substance flows from fermentation through formulation, elevating compliance costs for smaller producers. European compound feed manufacturers are responding by consolidating supplier bases toward integrated biotechnology platforms with established regulatory dossiers.
Direct procurement relationships between livestock integrators and enzyme developers are displacing traditional distribution through feed additive traders. Large poultry operations in Brazil and Thailand now negotiate multi-year supply agreements with technical service provisions, extracting formulation support and stability guarantees that commodity channels cannot match. This channel shift concentrates volume among vertically capable suppliers while marginalizing regional distributors.
Animal Feed Phytase Market Segmentation
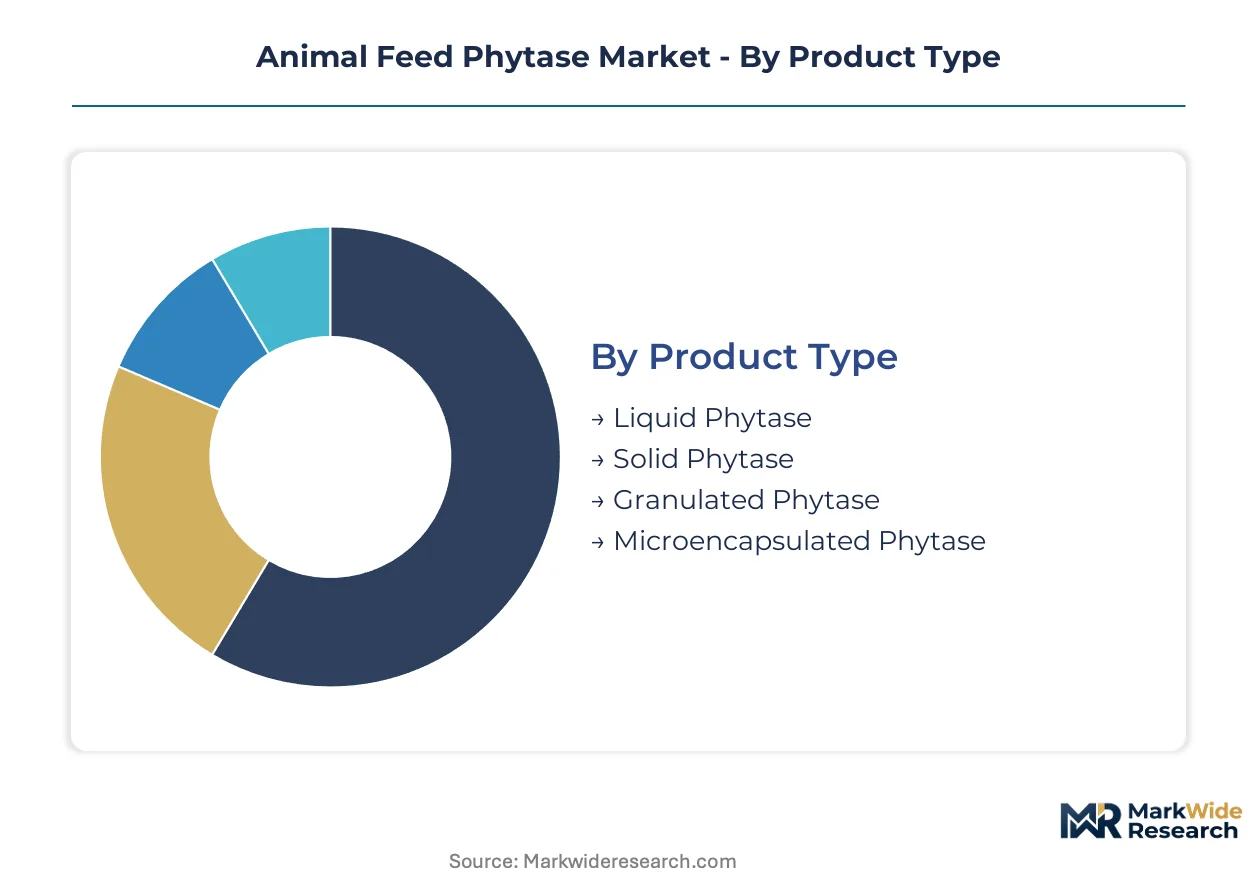
Phytase segmentation reflects divergent priorities across the feed value chain: thermal stability demands from millers, precision dosing requirements from integrators, and cost absorption capacity from livestock producers. Understanding these fault lines clarifies why formulation choices cluster around specific processing technologies and end-use applications.
Product Type:
Feed millers select formats based on pelleting temperature exposure and automated handling infrastructure, creating a clear hierarchy between legacy powder systems and engineered granules.
- Solid Phytase:Powder formulations bound to wheat bran or rice hull carriers dominate volume due to lower unit costs and established handling protocols at mid-sized mills. Demand concentrates in China's provincial feed compounders where pelleting temperatures rarely exceed 75°C and capital constraints delay automation upgrades.
- Granulated Phytase:Engineered particles with thermal protective coatings withstand shear stress and retain activity through high-temperature conditioning. Pork and poultry integrators in Brazil and Thailand now specify granular grades in procurement tenders, extracting formulation guarantees that commodity channels cannot match.
- Liquid Phytase:Aqueous suspensions enable post-pelleting spray application with recovery rates above 95%.
- Microencapsulated Phytase:Lipid or polymer shell technologies protect enzyme integrity through aggressive thermal regimes.
Volume sits with solid formats; growth tilts toward granulated and microencapsulated variants as pelleting temperatures climb across industrial milling operations.
Application:
Species-specific digestive physiology and production intensity determine phytase inclusion rates, with monogastric operations driving absolute consumption and aquaculture emerging as the margin expansion frontier.
- Poultry Nutrition:Broiler and layer operations deploy phytase to unlock phosphorus from corn-soy diets while reducing dicalcium phosphate supplementation. Chinese poultry integrators scaling enzyme programs under Ministry of Agriculture mandates anchor regional demand concentration.
- Aquaculture Feed:Intensive shrimp and finfish operations adopt phytase to improve feed conversion ratios in recirculating systems. Vietnamese shrimp farms and Norwegian salmon producers are accelerating adoption as stocking densities intensify and discharge regulations tighten.
- Swine Nutrition:Sow and grower-finisher diets incorporate phytase to reduce phosphorus excretion and lower manure management costs.
- Ruminant Feed:Dairy and beef operations show limited phytase penetration due to rumen microbial phosphorus cycling.
Poultry commands current volume; aquaculture represents the steepest expansion trajectory as intensive marine production systems proliferate.
Source:
Production biology and intellectual property positioning separate commodity enzyme supply from premium recombinant alternatives, with protein engineering capabilities determining competitive durability.
- Microbial Phytase:Fermentation-derived enzymes from Aspergillus and Bacillus species anchor commercial supply through established manufacturing infrastructure. AB Enzymes maintains European market position via specialized fungal production platforms with documented EFSA dossiers.
- Recombinant Phytase:Genetically engineered variants with enhanced thermostability and pH optima command premium positioning. DSM dominates this segment through advanced directed evolution capabilities, supplying heat-stable alternatives for feed processing above 85°C.
- Fungal Phytase:Native Aspergillus niger strains produce acid-stable enzymes suited to monogastric gastric pH conditions.
- Plant-Based Phytase:Transgenic crop expression systems remain experimental with limited commercial scale.
Microbial sources dominate current volume; recombinant variants gain share fastest as thermal tolerance specifications escalate across feed manufacturing.
End User:
Procurement sophistication and technical service requirements fragment the customer base, with large integrators extracting value beyond commodity supply while smaller operations prioritize cost minimization.
- Feed Manufacturers:Compound feed mills specify phytase grades based on pelleting equipment and thermal profiles, consolidating supplier relationships toward integrated biotechnology platforms with stability guarantees and regulatory dossiers.
- Livestock Producers:Vertically integrated pork and poultry operations negotiate direct supply agreements with enzyme developers, bypassing additive traders to secure multi-year contracts with embedded technical support.
- Aquaculture Firms:Marine and freshwater producers seek feed conversion optimization in intensive systems.
- Animal Nutritionists:Formulation consultants influence specification decisions at mid-sized operations.
Feed manufacturers hold current volume concentration; livestock integrators are capturing procurement influence fastest as direct supply relationships displace traditional distribution channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangzhou anchors the densest concentration of animal feed phytase demand through its position as the southern hub of China's livestock processing corridor. The city's feed compounders supply protein to the Pearl River Delta's integrated poultry operations.
China
Pork sector consolidation and Ministry of Agriculture enzyme mandates drive formulation shifts across provincial feed mills. GB standards for compound feed enzymes enforce minimum activity specifications. Shandong Peninsula manufacturers scale thermal-stable phytase output to serve domestic integrators.
United States
Chesapeake Bay watershed pork and poultry producers face EPA nutrient discharge limits that mandate phosphorus reduction strategies. State-level CAFO permitting programs in Maryland and Virginia accelerate enzyme adoption. Iowa's corn-soy belt feed mills specify heat-stable grades for high-temperature pelleting lines.
Germany
EFSA feed additive authorization timelines shape procurement toward established dossier holders. REACH chemical registration requirements tighten traceability for fermentation intermediates. Lower Saxony's compound feed sector consolidates supplier relationships toward integrated biotechnology platforms.
Brazil
Vertically integrated poultry exporters negotiate direct supply agreements with technical service provisions. MAPA agricultural inspection protocols govern enzyme import and registration. São Paulo state feed manufacturers deploy post-pelleting liquid application systems to recover thermal-degraded activity.
Vietnam
Intensive shrimp farm operations in Mekong Delta provinces adopt phytase to improve feed conversion ratios in recirculating systems. Ministry of Agriculture and Rural Development aquaculture standards tighten discharge parameters. Can Tho industrial zones concentrate feed milling capacity for export-oriented marine production.
Animal Feed Phytase Market Vendor Landscape
Premium-margin players sit above commodity-margin players across thermal stability certification and regulatory dossier depth. The vendor base stratifies between integrated biotechnology platforms with protein engineering capabilities and regional fermentation houses supplying standard-grade powder formulations. Three archetypes dominate: multinational enzyme specialists with directed evolution platforms, mid-scale fungal fermentation operators with EFSA-established dossiers, and commodity solid-phytase suppliers competing on logistics cost. Consolidation pressures favor backward integration into captive fermentation capacity and multi-year supply agreements with embedded technical service provisions.
Within the integrated platform tier, BASF SE and DSM exemplify archetypes anchored by biotechnology infrastructure and recombinant protein engineering capabilities respectively. AB Enzymes occupies a position among specialized fungal-derived producers with documented European regulatory dossiers. These three entities represent the spectrum from commodity solid formulations through premium heat-stable recombinant alternatives.
| Leading Market Players |
|---|
| BASF SE |
| AB Enzymes |
| DSM |
| Adisseo |
| Novozymes |
| DuPont |
| Alltech |
| Novus International |
| Huvepharma |
| Others |
Supply Flow & Price Mechanics
Livestock integrators in Brazil and Thailand now specify granular phytase grades with embedded thermal stability guarantees, forcing suppliers to absorb certification costs or surrender volume to integrated biotechnology platforms with established dossiers.
Pricing Analysis
Value-based pricing tied to feed conversion ratio improvements anchors premium tiers, with heat-stable recombinant formulations commanding substantial premiums over commodity powder grades. Price differentiation separates EFSA-certified suppliers from regional fermentation houses lacking documented thermal tolerance validation. Pricing pressure stems from dicalcium phosphate substitution in markets with weak environmental enforcement. Mid-sized feed compounders in China's provincial markets exhibit highest price sensitivity, while vertically integrated poultry exporters in São Paulo state prioritize stability guarantees over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from European compound feed manufacturers mandate qualification of at least two EFSA-dossiered suppliers, fragmenting volume among BASF SE, DSM, and AB Enzymes. Fermentation capacity concentrates in Germany, China, and the Netherlands, with corn steep liquor and soybean meal inputs drawing from commodity grain markets. Single-source vulnerability runs through specialized protein engineering talent pools competing with pharmaceutical employers. Distribution runs through direct procurement relationships displacing traditional additive traders, particularly among Brazilian poultry integrators negotiating multi-year technical service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story: EFSA feed additive authorization timelines stretching 18-24 months create a regulatory moat that entrenches incumbents with established dossiers while freezing product pipelines for aspirants.
For Market Incumbents: Extend thermal stability certification leadership by capturing third-party laboratory capacity before testing backlogs worsen. Deepen backward integration into captive fermentation infrastructure in Lower Saxony and Shandong Peninsula to secure margin control against corn steep liquor volatility. Direct evolution platforms represent the priority R&D anchor against emerging recombinant specialists. For New Entrants and Emerging Players: Vietnamese shrimp farm operations present the most penetrable buyer archetype, with Mekong Delta intensive recirculating systems accelerating enzyme adoption ahead of domestic supply consolidation. Target post-pelleting liquid application system retrofits at legacy feed mills in Brazil's São Paulo state, where procurement sophistication lags behind integrator direct-negotiation models. Lead with precision dosing technical service rather than commodity price competition. For Investors and Strategic Acquirers: The window for entry favors mid-scale fungal fermentation operators with partial EFSA dossier progress and stranded capacity in European peripheral markets. Acquisition targets should demonstrate documented thermal tolerance validation pathways and existing relationships with at least two national compound feed associations. Watch for phosphorus discharge limit tightening in Chesapeake Bay watershed states as the inflection signal accelerating substitution away from dicalcium phosphate.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Stability Certification Investment | Third-party laboratory validation unlocks procurement tenders from Brazilian poultry integrators specifying 85°C retention benchmarks. |
| Backward Integration into Fermentation Capacity | Captive corn steep liquor processing in Shandong Peninsula insulates margin compression from commodity grain price swings. |
| Direct Supply Agreement Structuring | Multi-year contracts with embedded technical service provisions displace traditional additive traders in Thai livestock procurement. |
| Aquaculture Application Development | Feed conversion ratio optimization for Vietnamese shrimp farms opens the steepest margin expansion trajectory in marine production. |
| EFSA Dossier Acceleration | Expedited feed additive authorization timelines capture procurement consolidation among Lower Saxony compound feed manufacturers. |
Methodological Framework
Multi-period observation of pelleting temperature specifications, EFSA authorization timelines, and Ministry of Agriculture mandate enforcement anchored the trend analysis, supplemented by interviews with feed mill procurement directors, enzyme formulation specialists, regulatory affairs leads at biotechnology platforms, and aquaculture nutrition consultants. Secondary validation drew from EFSA feed additive registers, EPA nutrient discharge monitoring reports, GB standards documentation, customs trade data for fermentation equipment imports, and SEC filings of publicly traded enzyme developers. Bottom-up volume modeling across product type, application, source, and end-user segments triangulated against top-down industry association estimates.
Segment-weighting approaches applied differential growth assumptions across microbial and recombinant source categories, with thermal stability specifications and regulatory dossier status as cross-cutting modifiers. The analytical framework modeled poultry nutrition, aquaculture feed, swine nutrition, and ruminant feed applications separately across the projection horizon, with species-specific inclusion rate trajectories calibrated to intensive production system expansion. CAGRs were derived from logistic adoption curves fitted to historical enzyme penetration patterns in comparable feed additive categories, with China livestock sector consolidation and Chesapeake Bay watershed discharge limits as primary demand drivers.
Revisions become necessary when EFSA authorization timelines compress or extend materially, when heat-stable protein engineering yields variants surpassing current 85°C retention benchmarks, or when phosphorus source substitution economics shift with dicalcium phosphate price volatility. Deviation in Ministry of Agriculture mandate enforcement consistency across China's provincial feed compounders would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Global Animal Feed Amino Acids Market
Veterinary Nutritional Products
Animal Growth Promoter Market
Veterinary Nutritional Products
Organic Acids in Animal Nutrition Market
Veterinary Nutritional Products
Animal Nutrition Market
Veterinary Nutritional Products
Nutritional Ingredients in Animal Feed Market
Veterinary Nutritional Products
South America Feed Vitamins Market
Veterinary Nutritional Products
Animal Probiotics Market
Veterinary Nutritional Products
Animal Digest Market
Veterinary Nutritional Products
Trace Minerals Chelated Feed Market
Veterinary Nutritional Products
Animal Based Protein Supplements Market
Veterinary Nutritional Products
Poultry Vitamin Market
Veterinary Nutritional Products
Feed Anticoccidials Market
Veterinary Nutritional Products
Broiler Premix Market
Veterinary Nutritional Products
Essential Oils in Animal Nutrition Market
Veterinary Nutritional Products
Global Animal Feed Antioxidants Market
Veterinary Nutritional Products
Animal Salt Licks Market