
 Natural Feed Additive Market | 2026-2036
Natural Feed Additive Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Feed Additive Market Foresight
Capital-intensity divergence between fermentation-based probiotic manufacturers and commodity botanical extractors is rotating competitive advantage toward in-house strain development capabilities. DSM-Firmenich AG leverages its integrated biotechnology platform to control upstream fermentation capacity for livestock-specific probiotic strains. Alltech, Inc. anchors its position through yeast culture specialization and direct technical service relationships with integrated poultry operators. Cargill, Incorporated sustains global distribution density by embedding natural additives within broader nutrition premix contracts.
Natural feed additives comprise biologically active compounds—microbial cultures, plant-derived metabolites, enzymatic proteins, and organic acid complexes—formulated to enhance nutrient utilization, gut microbiome stability, and immune competence in food-producing animals without synthetic pharmacological intervention; production relies on submerged fermentation, solvent-free extraction, or solid-state propagation to preserve bioactivity. Probiotics and essential oils command premium positioning as antibiotic replacement protocols harden across regulated supply chains, while amino acids represent the volume anchor where margin compression from Chinese fermentation overcapacity persists. Application demand tilts toward poultry and aquaculture, species where feed conversion efficiency gains translate most directly to processor profitability and where residue-testing protocols are most stringent.
The EU Green Deal's Farm to Fork strategy, enforced by EFSA and national veterinary regulators, mandates measurable antibiotic reduction targets that restructure procurement specifications for livestock integrators. The FDA's Veterinary Feed Directive in the United States restricts medically important antimicrobials, redirecting formulation R&D toward GRAS-affirmed phytogenics and direct-fed microbials. China's Ministry of Agriculture and Rural Affairs accelerates national standard-setting for microbial feed additives under GB framework alignment. Stakeholders must monitor regulatory divergence between jurisdictions where precautionary bans outpace toxicological data generation and those where performance claims face escalating evidentiary demands.
Market Dynamics
The EU Green Deal's Farm to Fork antibiotic reduction mandates are restructuring livestock procurement specifications, forcing integrators to validate phytogenic and probiotic alternatives through residue-free certification protocols.
Growth Catalysts
- EFSA enforcement protocols:The EU veterinary regulator's measurable reduction targets compel livestock integrators to substitute botanical extracts for growth-promoting antibiotics in broiler and swine operations.
- Fermentation capacity expansion:Submerged bioreactor installations for livestock-specific probiotic strains are scaling across Denmark and the Netherlands to meet contract manufacturing demand.
- Export certification requirements:Brazil's integrated poultry processors mandate residue-free additive documentation for EU-bound protein shipments, accelerating phytogenic formulation adoption.
Market Restraints
- Chinese amino acid overcapacity:Fermentation-based lysine and methionine production surplus is compressing margins for European and North American microbial additive manufacturers.
- Strain development timelines:GRAS-affirmation and EFSA novel food dossier preparation for direct-fed microbials extends commercialization cycles beyond typical R&D amortization periods.
- Botanical raw material volatility:Climate-dependent harvests of oregano, thyme, and cinnamon bark in Mediterranean and Southeast Asian sourcing regions create input cost instability.
Strategic Opportunities
- Vietnam aquaculture expansion:Shrimp and pangasius feed formulators in the Mekong Delta are adopting phytogenic gut health additives to replace prophylactic antibiotics in export-oriented operations.
- Precision fermentation convergence:Synthetic biology platforms for bioactive peptide production are intersecting with livestock nutrition science to create next-generation microbiome modulators.
- FDA Veterinary Feed Directive compliance services:Technical advisory bundled with probiotic premix contracts is capturing margin from US pork and cattle integrators navigating restricted antimicrobial protocols.
Industry Challenges
- Strain banking and cryopreservation expertise:Qualified microbiologists capable of maintaining viable culture collections for multi-year product lifecycles are concentrated among legacy fermentation houses.
- Multi-jurisdiction dossier harmonization:Divergent evidentiary requirements between EFSA's precautionary bans and FDA's GRAS self-affirmation pathways force redundant toxicology investment.
- Legacy premix integration complexity:Phytogenic oil stability in high-temperature pelleting processes requires reformulation of existing mineral-vitamin matrices without disrupting feed mill throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Feed Additive Market |
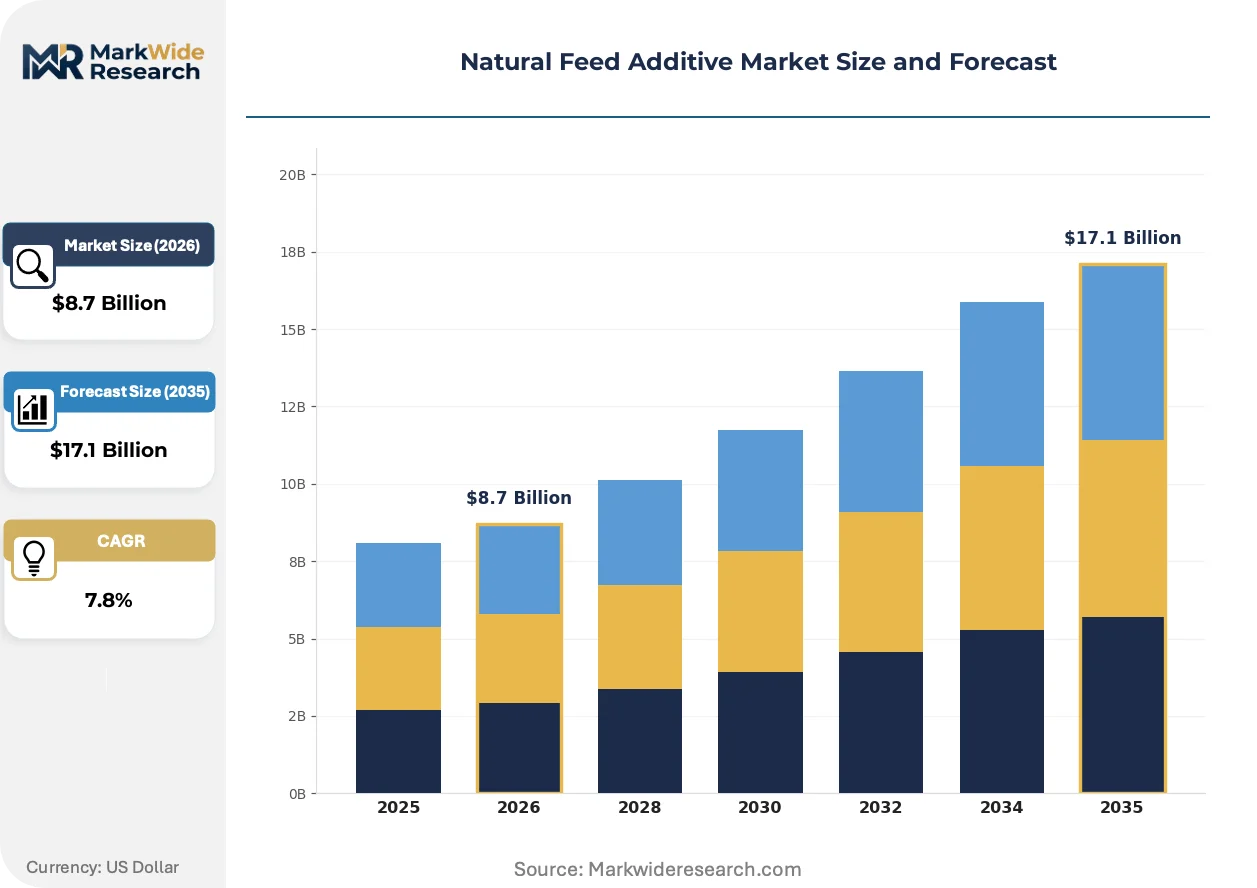
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Enzymes, Amino Acids, Essential Oils Source: Plant-Based, Animal-Based, Microbial-Based, Others Application: Ruminants, Poultry, Swine, Aquaculture Form: Powder, Liquid, Granular, Pellet |
| Companies Covered | DSM-Firmenich AG, Alltech, Inc., Cargill, Incorporated, Kemin Industries, Inc., Adisseo, Archer Daniels Midland Co., BASF SE, Nutreco N.V., Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Feed Additive Market Shifts & Advancements
Biotechnology platforms are converging with livestock nutrition science to create functionally differentiated additive categories that command premium positioning in antibiotic-restricted supply chains.
Encapsulated essential oil microspheres are displacing unprotected phytogenic powders in poultry and swine applications. Thai and Vietnamese integrators are adopting these heat-stable formulations for pelleted feed matrices. The technology is displacing commodity botanical extracts by preserving bioactive compound integrity through extrusion processing, compressing price premiums for standard essential oil blends.
China's GB standards framework for microbial feed additives is accelerating national strain registration requirements. The Ministry of Agriculture and Rural Affairs mandates full genome sequencing and safety dossiers for probiotic product approval. Domestic fermentation houses and joint-venture partners are restructuring R&D budgets to comply, while importers face exclusion from government procurement tenders lacking GB certification.
Integrated poultry operators in Brazil and Thailand are consolidating additive procurement through nutrition premix contracts rather than standalone phytogenic purchases. This channel consolidation compresses supplier margins while embedding technical service obligations. The shift is most pronounced among export-oriented processors seeking unified residue accountability from single-source nutrition providers.
Natural Feed Additive Market Segmentation
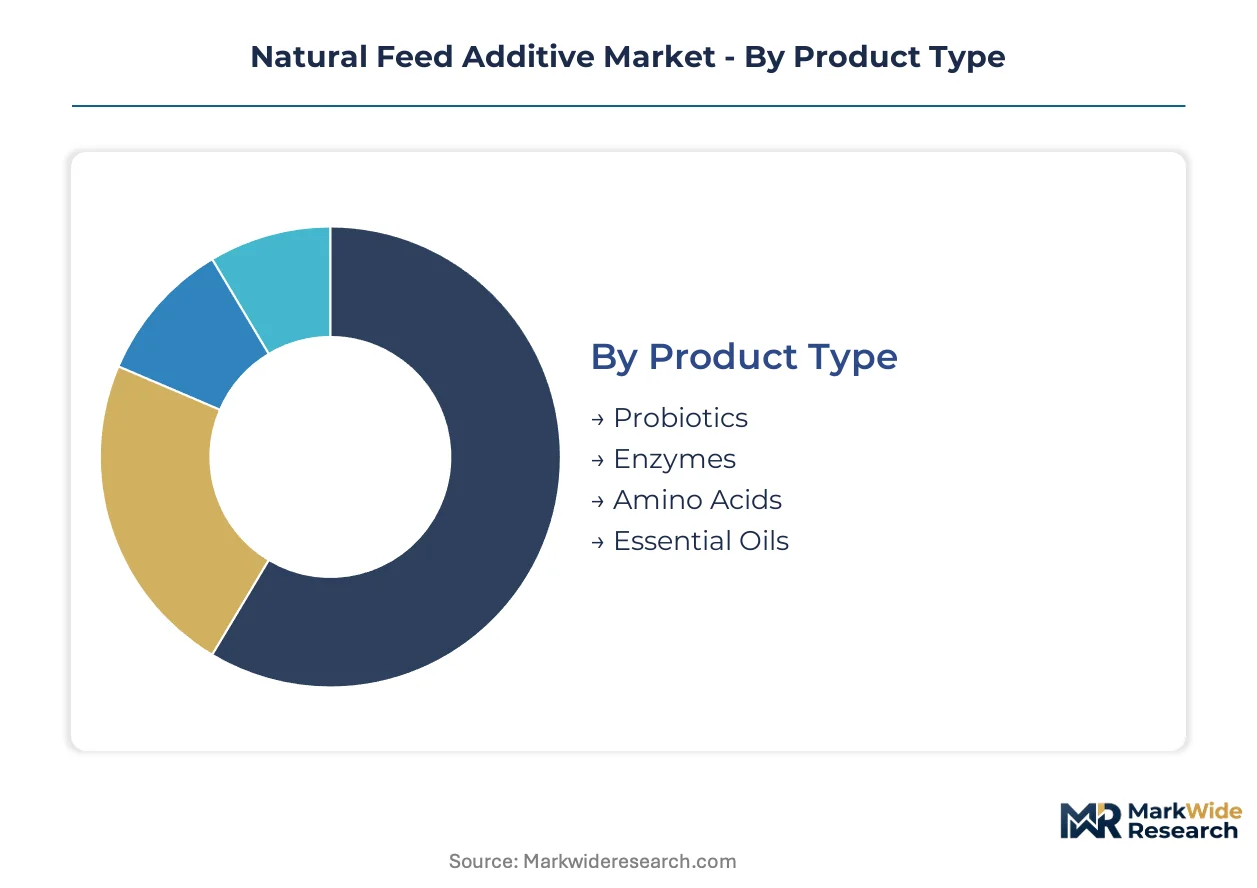
Natural feed additive segmentation reveals where antibiotic substitution pressure concentrates procurement spend and where formulation complexity creates supplier stickiness. Product type and source categories show the clearest divergence between commodity amino acid oversupply and premium probiotic strain scarcity.
Product Type:
Substitution pressure from antibiotic restrictions falls unevenly across product categories, with microbial and botanical alternatives facing divergent technical validation requirements.
- Probiotics:Live microbial cultures of Bacillus, Lactobacillus, and Enterococcus strains colonize gut epithelium to outcompete pathogenic bacteria. Demand concentrates among EU and Brazilian poultry integrators seeking EFSA-compliant residue-free certification for export shipments.
- Essential Oils:Terpenoid and phenolic compounds from oregano, thyme, and cinnamon bark disrupt bacterial quorum sensing. Thai and Vietnamese feed mills are adopting encapsulated microsphere formulations to survive high-temperature pelleting without bioactivity loss.
- Enzymes:Exogenous carbohydrases and proteases degrade anti-nutritional factors in cereal and oilseed meals.
- Amino Acids:Fermentation-derived lysine, methionine, and threonine face margin compression from Chinese overcapacity.
Amino acids retain volume leadership; probiotics hold the steepest expansion curve.
Source:
Cost tier stratification separates capital-intensive microbial fermentation from extraction-dependent botanical supply chains with divergent raw material risk profiles.
- Microbial-Based:Submerged fermentation and solid-state propagation yield standardized cell counts and metabolite concentrations. Danish and Dutch bioreactor installations are scaling to meet contract manufacturing demand from European livestock integrators.
- Plant-Based:Solvent-free supercritical CO2 extraction preserves heat-sensitive phytochemicals from Mediterranean and Southeast Asian botanical harvests. Climate volatility in oregano and cinnamon sourcing regions creates input cost instability for formulators.
- Animal-Based:Hydrolyzed proteins and marine-derived compounds supply concentrated bioactive peptides.
- Others:Mineral-organic acid complexes and synthetic analogs fill specification gaps in legacy premix matrices.
Plant-based sources retain volume leadership; microbial-based holds the steepest expansion curve.
Application:
Application demand concentrates where feed conversion efficiency gains translate most directly to processor profitability and where residue-testing protocols are most stringent.
- Poultry:Broiler and layer operations in Brazil, Thailand, and Vietnam drive phytogenic adoption for gut health management. Export-oriented processors mandate residue-free additive documentation to maintain EU-bound protein shipment eligibility.
- Aquaculture:Shrimp and pangasius feed formulators in Vietnam's Mekong Delta are replacing prophylactic antibiotics with phytogenic gut health additives to satisfy import market veterinary drug limits.
- Swine:Post-weaning diarrhea prevention in nursery operations favors direct-fed microbials over zinc oxide.
- Ruminants:Methane mitigation and fiber digestion enhancement target dairy and beef feedlot efficiency.
Poultry retains volume leadership; aquaculture holds the steepest expansion curve.
Form:
Form selection depends on feed mill processing temperatures, storage stability requirements, and species-specific dosing precision needs.
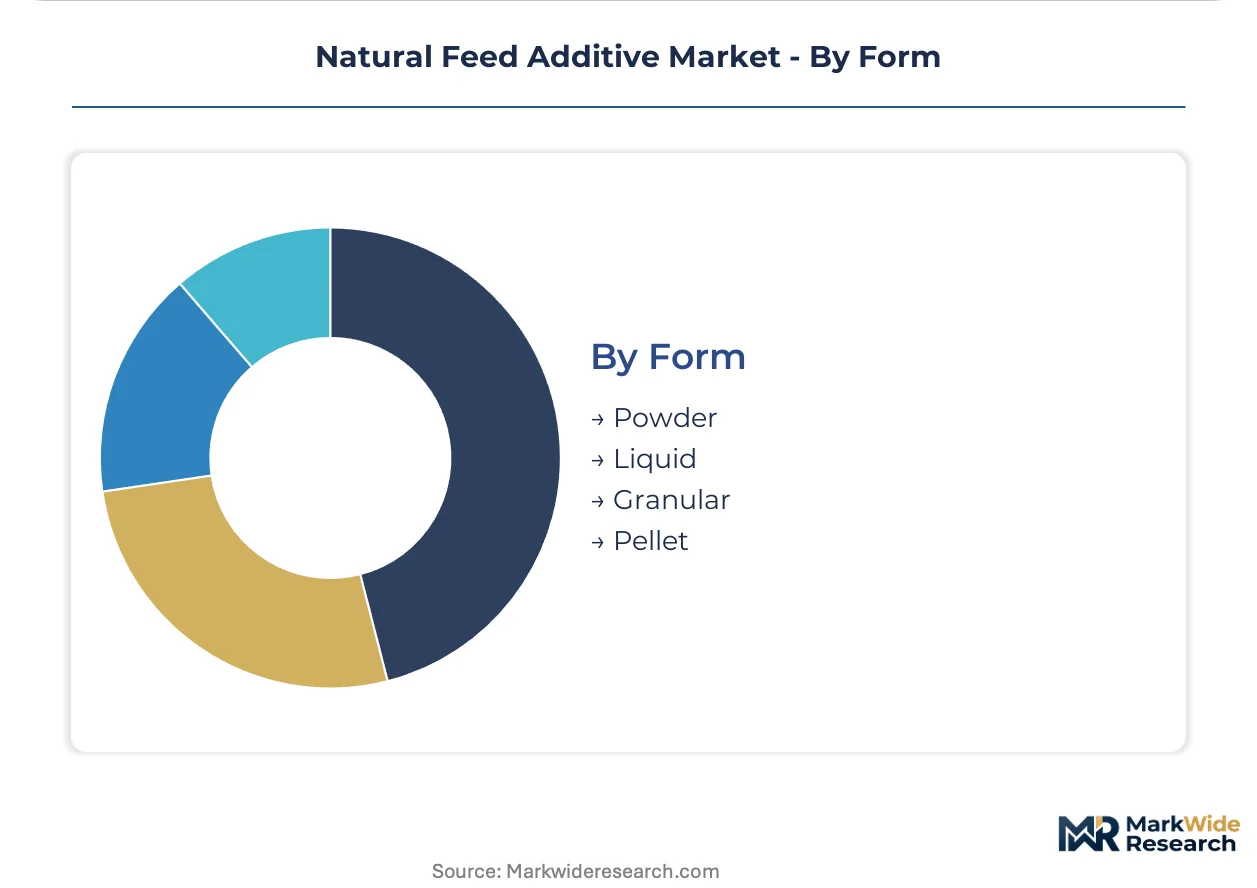
- Powder:Standardized particle size distributions enable homogeneous premix blending but limit heat stability. Unprotected phytogenic powders face displacement by encapsulated alternatives in pelleted feed applications.
- Liquid:Aqueous suspensions and oil-based concentrates allow post-pelleting application through spray systems. Post-pelleting liquid application preserves thermolabile probiotic viability in high-temperature extrusion processes.
- Granular:Agglomerated particles reduce dust generation during handling and improve flowability.
- Pellet:Compressed forms integrate directly into finished feed without additional processing steps.
Powder retains volume leadership; liquid holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for natural feed additives varies sharply across procurement contexts. Export-oriented Brazilian poultry processors absorb premium pricing for residue-free certification, while Vietnamese aquaculture operators remain acutely price-sensitive in domestic market supply chains.
Brazil
Integrated broiler processors in São Paulo and Paraná drive phytogenic additive procurement to maintain EU-bound protein shipment eligibility. ANVISA coordinates with the Ministry of Agriculture on veterinary drug residue monitoring protocols. The western Paraná poultry cluster around Cascavel mandates additive documentation from single-source nutrition providers.
United States
Pork and cattle integrators in Iowa and North Carolina redirect formulation spend toward direct-fed microbials under FDA Veterinary Feed Directive restrictions. The FDA's GRAS self-affirmation pathway accelerates commercialization timelines relative to European precautionary frameworks. Technical advisory services bundled with probiotic premix contracts capture margin in the Midwest feedlot corridor.
China
Domestic fermentation houses in Shandong and Jiangsu provinces restructure R&D budgets to comply with Ministry of Agriculture GB standards for microbial strain registration. The GB framework mandates full genome sequencing and safety dossiers for probiotic product approval. Government procurement tenders in the Yangtze River Delta increasingly exclude importers lacking domestic certification.
Germany
Livestock integrators in Lower Saxony and Bavaria scale submerged bioreactor installations for contract manufacturing of livestock-specific probiotic strains. EFSA enforcement of EU Green Deal antibiotic reduction targets compels measurable substitution of botanical extracts for growth-promoting antimicrobials. The Münsterland dairy cluster adopts precision fermentation platforms for methane mitigation additives.
Vietnam
Shrimp and pangasius feed formulators in the Mekong Delta replace prophylactic antibiotics with phytogenic gut health additives to satisfy import market veterinary drug limits. The Department of Animal Health accelerates residue testing protocols for export-oriented aquaculture operations. Can Tho and An Giang provinces concentrate adoption of encapsulated essential oil microspheres for pelleted feed matrices.
Natural Feed Additive Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in the natural feed additive sector. Fermentation-based probiotic manufacturers command premium positioning through in-house strain development capabilities, while commodity botanical extractors compete on input sourcing scale and extraction throughput. The market structures around three strategic archetypes: integrated biotechnology platforms with captive fermentation capacity, specialized yeast culture producers with direct technical service relationships, and diversified nutrition conglomerates embedding additives within broader premix contracts. Dominant competitive moves include backward integration into upstream strain banking and geographic expansion through jurisdiction-specific regulatory dossier preparation.
Within the integrated biotechnology tier, DSM-Firmenich AG and Evonik Industries AG exemplify players controlling fermentation infrastructure for livestock-specific microbial production. BASF SE anchors the diversified chemical conglomerate archetype, leveraging existing industrial biotechnology platforms to cross-apply synthetic biology capabilities into animal nutrition applications. Cargill, Incorporated occupies the nutrition-integrated position, sustaining global distribution density through additive embedding within broader feed premix contracts rather than standalone product sales.
| Leading Market Players |
|---|
| DSM-Firmenich AG |
| Alltech, Inc. |
| Cargill, Incorporated |
| Kemin Industries, Inc. |
| Adisseo |
| Archer Daniels Midland Co. |
| BASF SE |
| Nutreco N.V. |
| Evonik Industries AG |
| Others |
Supply & Pricing Matrix
EFSA residue-free certification gates both supplier qualification and price tier placement in EU-bound livestock supply chains, compressing uncertified botanical extractors into commodity pricing while rewarding validated probiotic manufacturers with contract premiums. Brazilian export processors absorb this cost bifurcation to maintain shipment eligibility, redirecting procurement toward documented single-source providers.
Pricing Analysis
Technical service contracts bundled with probiotic premix deliveries capture lifetime value exceeding standalone product margins. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-validated strain formulations from generic microbial cultures and unprotected essential oil powders. Pricing pressure stems from Chinese amino acid fermentation overcapacity bleeding into adjacent microbial additive categories. Vietnamese aquaculture feed formulators exhibit acute price sensitivity, while German dairy integrators prioritize certification compliance over unit cost.
Supply Chain Analysis
Port congestion on Mediterranean-Southeast Asian trade lanes elevates inbound logistics costs for oregano and cinnamon bark shipments to European extraction facilities. Raw material supply concentrates in Denmark and the Netherlands for submerged bioreactor capacity, in Mediterranean coastal zones for solvent-free botanical extraction, and in Shandong province for fermentation-derived amino acids. Climate volatility in Thai and Vietnamese harvest regions threatens input cost stability for phytogenic formulators. Distribution runs through nutrition premix contracts that embed additives within broader feed matrices rather than standalone channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical advisory and residue-testing services attach to core additive sales at expansion rates exceeding base product growth, repositioning supplier relationships around compliance partnerships rather than transactional supply.
For Market Incumbents: Secure captive fermentation capacity in Denmark and the Netherlands to lock in contract manufacturing demand from EFSA-compliant integrators. Defend margin position by embedding phytogenic formulations within unified premix contracts that consolidate procurement accountability for Brazilian export processors facing ANVISA documentation requirements. For New Entrants and Emerging Players: Differentiate on encapsulated essential oil microsphere technology that survives high-temperature pelleting in Thai and Vietnamese feed mills. Target Vietnam's Mekong Delta aquaculture sector, where pangasius and shrimp formulators seek antibiotic alternatives under tightening Department of Animal Health protocols. Enter through technical service partnerships with established regional nutrition distributors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized industrial biotechnology platforms applicable to livestock-specific strain development. Long-term viability hinges on regulatory dossier capabilities spanning EFSA precautionary frameworks and FDA GRAS pathways. Watch for GB certification completion by Chinese domestic fermentation houses as a signal of import substitution pressure on European probiotic suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Banking | In-house cryopreservation capabilities reduce dependency on legacy fermentation houses for viable culture collections. |
| EFSA Novel Food Dossier Preparation | Regulatory investment unlocks premium positioning in EU Green Deal-compliant livestock supply chains. |
| Encapsulation Technology Licensing | Heat-stable microsphere formulations displace commodity phytogenic powders in pelleted feed applications. |
| Precision Fermentation Platform Buildout | Synthetic biology capabilities intersect with microbiome science to create differentiated bioactive peptide additives. |
| GB Standards Compliance Investment | Genome sequencing and safety dossier completion secures access to Chinese government procurement tenders. |
Research Methodology
Desk research of EFSA guidance documents, FDA Veterinary Feed Directive amendments, and Chinese Ministry of Agriculture GB standards preceded structured interviews with livestock nutrition directors, feed mill procurement managers, fermentation R&D leads, and veterinary regulatory affairs specialists. Primary fieldwork captured formulation specification trends and residue-testing protocol evolution across Brazilian, German, and Vietnamese operations. Secondary validation drew from customs trade data, ANVISA monitoring reports, and industry association technical publications. Bottom-up strain registration counts and top-down premix contract value estimates were triangulated to anchor market sizing.
Variance decomposition across product type, source category, application species, and geographic regulatory cluster shaped the analytical framework over the projection horizon. Modeled dimensions included microbial strain specificity, extraction method sophistication, species-specific feed conversion efficiency targets, and jurisdiction-specific certification requirements. CAGRs were derived from segment-level demand elasticity calibrated against antibiotic restriction implementation timelines. Forecast inputs incorporated EFSA enforcement intensity indices and Brazilian export shipment certification rates.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal implementation and stable Chinese amino acid export volumes; material deviation would warrant model refresh. Regulatory acceleration or trade disruption in Mediterranean botanical sourcing regions could compress phytogenic additive availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Essential Oils in Animal Nutrition Market
Veterinary Nutritional Products
Animal Growth Promoter Market
Veterinary Nutritional Products
Feed Electrolytes Market
Veterinary Nutritional Products
Animal Nutrition Chemicals Market
Veterinary Nutritional Products
Animal Probiotics Market
Veterinary Nutritional Products
Calf Milk Replacers Market
Veterinary Nutritional Products
Cattle Nutrition Market
Veterinary Nutritional Products
China Animal Milk Replacer Market
Veterinary Nutritional Products
Nutritional Ingredients in Animal Feed Market
Veterinary Nutritional Products
Trace Minerals Chelated Feed Market
Veterinary Nutritional Products
Global Trace Minerals in Feed Market
Veterinary Nutritional Products
Latin America Animal Feed Organic Trace Minerals Market
Veterinary Nutritional Products
Poultry Vitamin Market
Veterinary Nutritional Products
Feed Carotenoids Market
Veterinary Nutritional Products
Animal Salt Licks Market
Veterinary Nutritional Products
Probiotics in Animal Feed Market