
 Animal Digest Market | 2026-2036
Animal Digest Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Digest Market Outlook
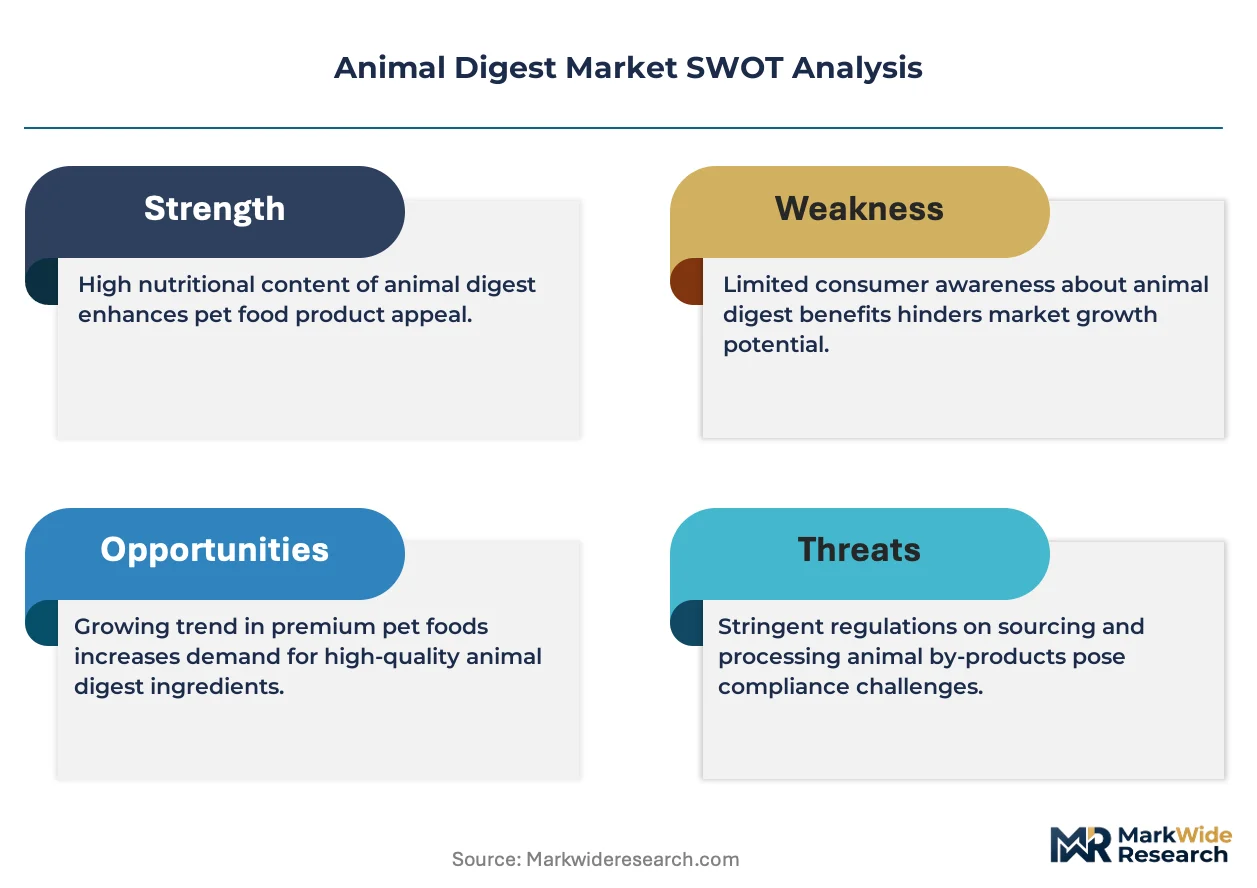
EU Green Deal sustainability thresholds for pet food ingredient sourcing is decoupling conventional rendering practices from premium supply chains. Darling Ingredients leverages vertical integration across rendering and rendering-adjacent operations to secure raw material streams. Kemin Industries differentiates through R&D intensity in palatability science and antioxidant stabilization. ADM Animal Nutrition anchors North American manufacturing scale with backward integration into protein processing infrastructure.
Animal digest denotes a hydrolyzed protein material produced through enzymatic or acid breakdown of animal tissues, yielding a concentrated liquid or powder with elevated free amino acid content and pronounced organoleptic properties that enhance feed and pet food acceptance. The manufacturing process typically operates at controlled temperature and pH to preserve peptide bioactivity while achieving pathogen reduction. Dry food formulations occupy the largest volume position within product type segmentation, though treats command disproportionate margin contribution through ingredient claim premiums. Grain-free positioning within ingredient type segmentation has matured following FDA dilated cardiomyopathy investigations, redirecting formulation investment toward meat-based and limited-ingredient variants. Veterinary clinics as a distribution channel sustain pricing power through prescription-adjacent therapeutic diets that incorporate certified digest grades.
FDA Center for Veterinary Medicine oversees ingredient safety notifications and facility registration for animal digest used in pet food, while AAFCO establishes model definitions that state regulators adopt for labeling compliance. USDA Agricultural Marketing Service inspects rendering facilities under federal meat and poultry inspection statutes, creating dual jurisdictional oversight for raw material traceability. Stakeholders must monitor evolving state-level packaging waste regulations and biodegradable claim standards that will reshape coproduct utilization economics across the value chain.
Market Dynamics
EU Green Deal sustainability thresholds are decoupling conventional rendering practices from premium supply chains, forcing ingredient suppliers to revalidate hydrolyzed protein sourcing against carbon-intensity benchmarks and circular-economy criteria.
Growth Catalysts
- AAFCO labeling modernization:Updated ingredient definitions are clarifying hydrolyzed protein classifications, reducing formulation uncertainty for pet food manufacturers seeking palatability certification.
- Veterinary therapeutic diet expansion:Prescription-adjacent nutrition programs in the United States are absorbing certified digest grades at premium price points through clinic-exclusive distribution.
- Enzymatic hydrolysis refinement:Controlled temperature and pH processing is preserving peptide bioactivity while achieving pathogen reduction, expanding application into sensitive life-stage formulations.
Market Restraints
- Rendering feedstock volatility:Raw material availability fluctuates with meat and poultry processing volumes, concentrating supply risk in Midwestern US rendering corridors.
- FDA dual-jurisdictional compliance:Facility registration under Center for Veterinary Medicine overlaps with USDA Agricultural Marketing Service inspection statutes, creating redundant audit burdens.
- Plant protein substitution:Fermented microbial proteins and precision-fermentation alternatives are capturing formulation share in grain-free positioning segments.
Strategic Opportunities
- Biodegradable packaging mandates:State-level packaging waste regulations are creating coproduct utilization economics for digest-derived materials in sustainable film applications.
- Limited-ingredient diet pivot:FDA dilated cardiomyopathy investigations have redirected investment toward meat-based variants, elevating single-source animal digest demand.
- Antioxidant stabilization convergence:Integration of palatability science with lipid preservation technology is opening shelf-life extension contracts for premium dry food manufacturers.
Industry Challenges
- Peptide characterization expertise gap:Free amino acid profiling and organoleptic consistency require specialized analytical chemists scarce in conventional rendering operations.
- Legacy system integration friction:Batch processing equipment retrofits for enzymatic hydrolysis demand capital deployment while maintaining acid-hydrolysis output for existing contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Digest Market |
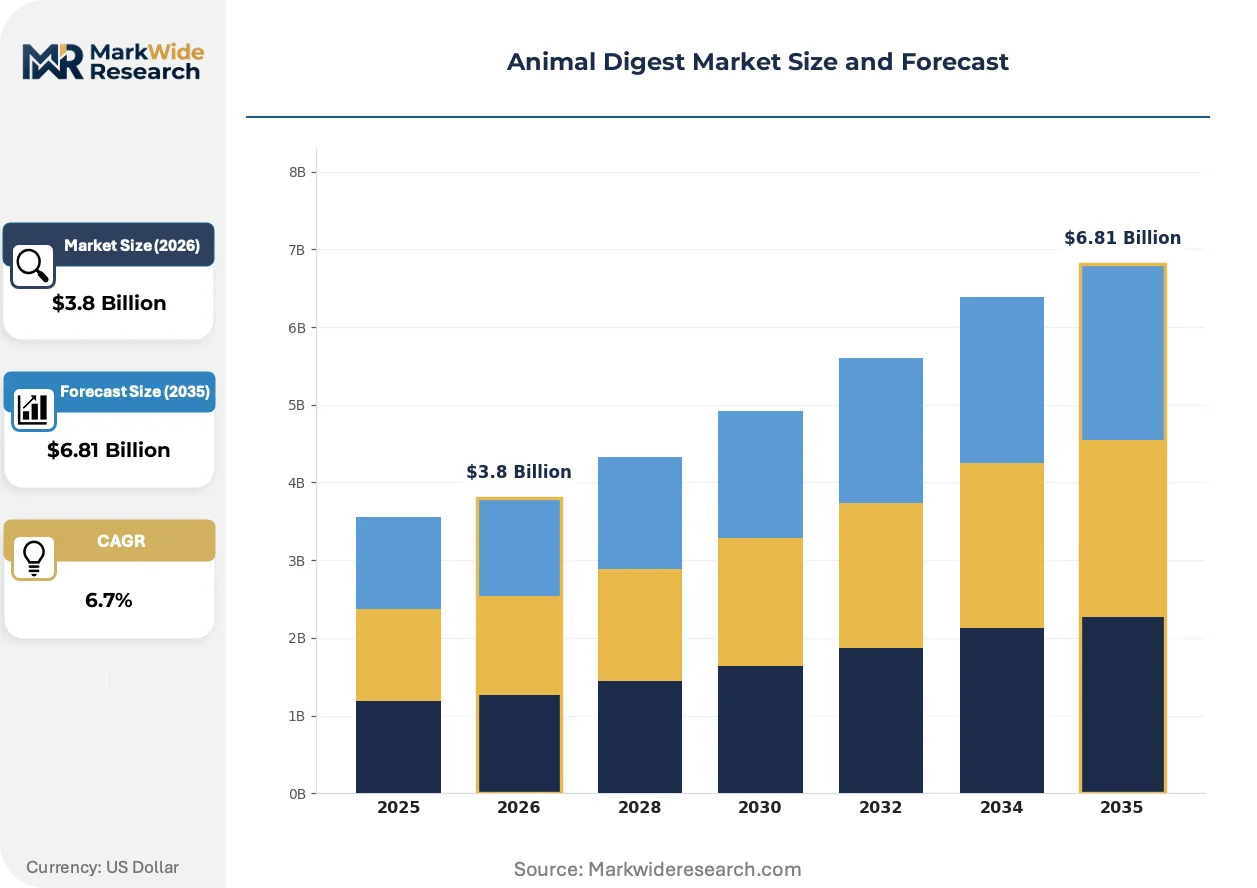
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements End User: Pet Owners, Veterinarians, Animal Shelters, Zoos Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Veterinary Clinics Ingredient Type: Meat-Based, Grain-Free, Organic, Others |
| Companies Covered | Kemin Industries, ADM Animal Nutrition, Cargill, BASF SE, Darling Ingredients, Omega Protein Corporation, Nestlé, B&G Foods, Inc., John Pointon and Sons Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Digest Market Strategic Shifts
Processing automation and regulatory transparency requirements are compressing batch-to-batch variability while elevating traceability standards across North American and European manufacturing lines.
Continuous enzymatic reactor systems are automating temperature and pH control sequences that previously demanded manual intervention between hydrolysis stages. Premium pet food manufacturers in the United States are adopting these systems at pilot scale before full-line conversion. This automation is compressing skilled technician requirements while tightening peptide molecular weight distribution specifications.
EU Green Deal circular-economy criteria are mandating carbon-intensity disclosures for rendering-adjacent ingredient sourcing. Pet food brands selling into German and French veterinary channels must now validate supply chain emissions against bloc-wide thresholds. Specialty manufacturers are responding by segregating premium digest streams from conventional rendering coproducts.
Treat formulations are commanding disproportionate margin contribution through ingredient claim premiums that dry food cannot support. Independent pet retailers in the United States are consolidating shelf space around limited-SKU premium brands with certified digest grades. This channel concentration is most visible in coastal metropolitan markets where veterinary clinic co-location drives cross-selling opportunities.
Animal Digest Market Segmentation
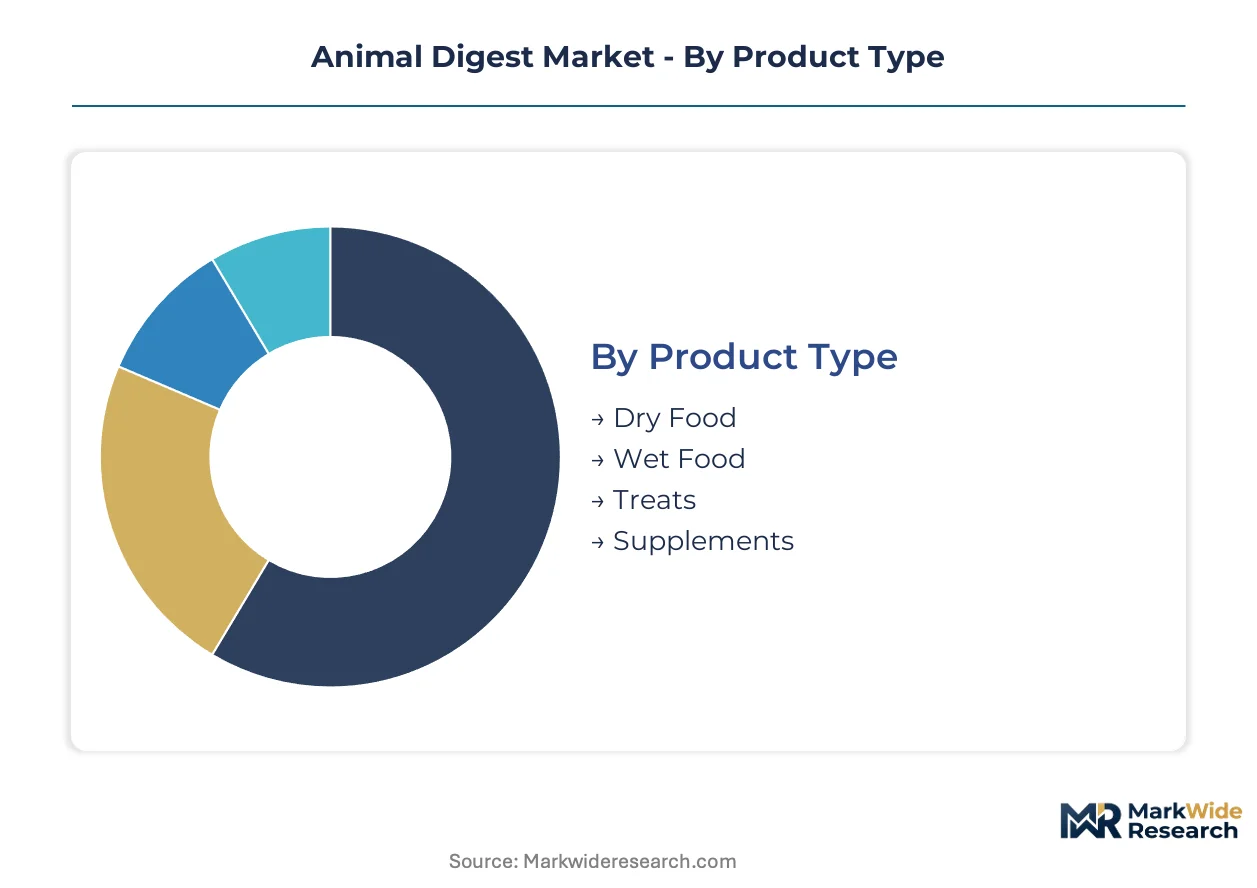
Animal digest formulation requirements diverge sharply across pet food categories, with palatability intensity, moisture tolerance, and certification grade driving procurement decisions. Manufacturers segment production lines by end-use performance specifications rather than raw material origin alone.
Product Type:
Premium pet food manufacturers select digest grades based on thermal stability requirements and moisture content tolerance during extrusion or canning processes.
- Dry Food:Powdered digest variants with low moisture content withstand high-temperature extrusion without Maillard degradation. Kibble manufacturers in the United States specify hydrolyzed protein with controlled molecular weight distribution to ensure uniform coating adhesion and shelf-stable palatability retention.
- Treats:Semi-moist digest applications command formulation premiums through limited-ingredient positioning and single-source protein claims. Independent pet retailers in coastal metropolitan markets concentrate shelf space around treat SKUs with certified organoleptic grades that support price premiums dry food cannot sustain.
- Wet Food:Liquid digest integrates directly into gravy and loaf matrices without rehydration steps, preserving peptide bioactivity through reduced thermal processing.
- Supplements:Highly concentrated digest powders serve functional nutrition applications targeting digestive health and appetite stimulation in therapeutic contexts.
Dry Food leads volumes today; Treats is gaining share fastest through margin expansion in premium positioning.
End User:
Procurement authority and quality certification requirements separate institutional buyers from consumer-direct channels.
- Pet Owners:Mass-market purchasers respond to ingredient transparency claims and AAFCO-compliant labeling, driving demand for hydrolyzed protein with defined peptide profiles in retail-accessible formats.
- Veterinarians:Prescription-adjacent therapeutic diet programs absorb certified digest grades at premium price points through clinic-exclusive distribution networks in the United States.
- Animal Shelters:Volume procurement prioritizes cost-efficient digest inclusion for palatability enhancement in maintenance rations.
- Zoos:Exotic species formulations require specialized organoleptic profiles matching non-domestic carnivore preference patterns.
Pet Owners dominate absolute consumption; Veterinarians is expanding most quickly through therapeutic nutrition program growth.
Distribution Channel:
Channel selection determines certification tier access and pricing flexibility for digest-integrated products.
- Veterinary Clinics:Prescription diet authorization creates captive demand for certified-grade digest with documented peptide characterization and pathogen reduction validation.
- Specialty Stores:Independent pet retailers curate limited-SKU premium brands with single-source digest claims, concentrating shelf space in high-margin coastal markets.
- Online Retail:Direct-to-consumer platforms enable ingredient transparency storytelling and subscription-based therapeutic diet delivery.
- Supermarkets:Mass-market placement emphasizes price-competitive digest inclusion in mainstream palatability positioning.
Supermarkets anchor volume throughput; Veterinary Clinics is climbing the fastest on prescription-adjacent pricing power.
Ingredient Type:
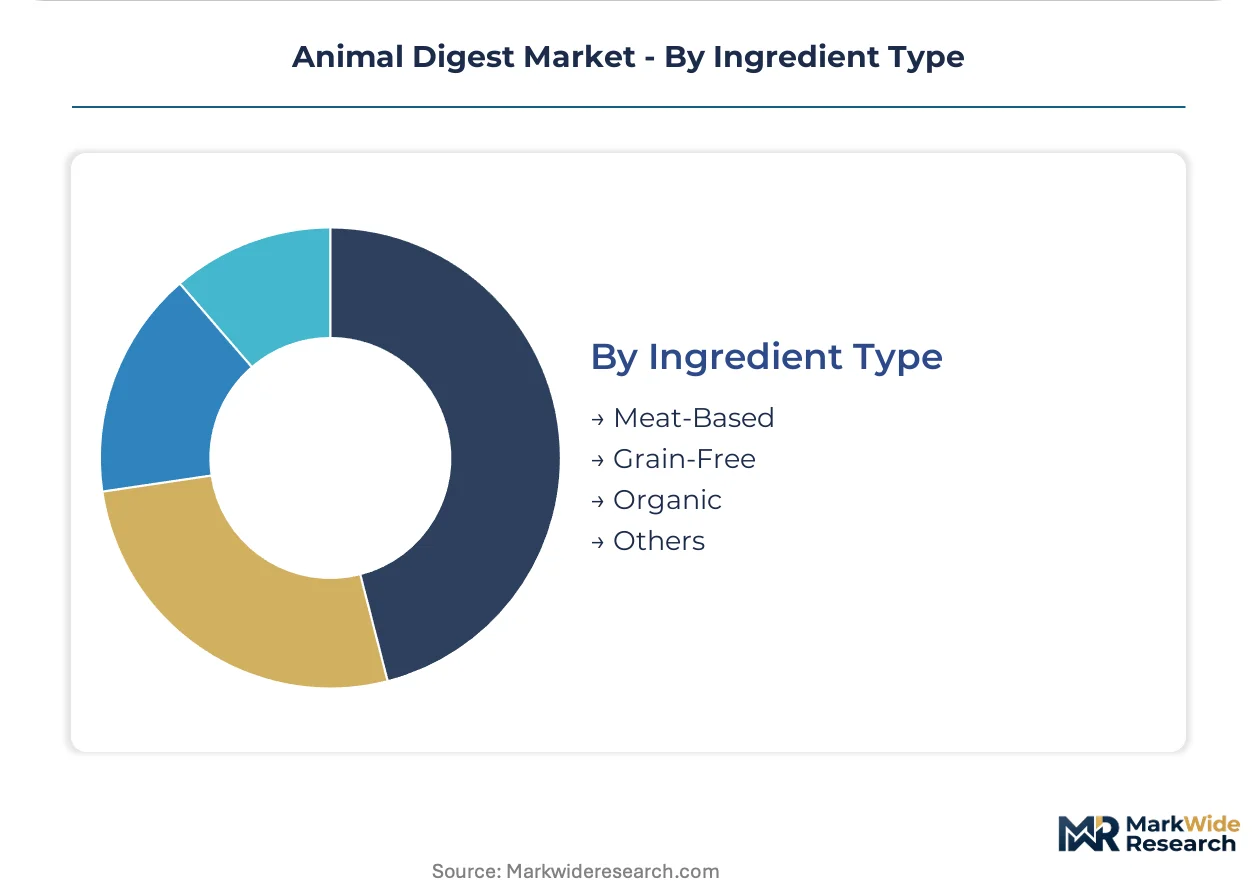
Formulation philosophy and regulatory scrutiny intensity differentiate sourcing strategies across ingredient positioning claims.
- Meat-Based:Single-source animal digest from named species satisfies limited-ingredient diet requirements following FDA dilated cardiomyopathy investigations redirecting investment away from grain-dependent formulations.
- Grain-Free:Peptide-enhanced palatability systems compensate for reduced carbohydrate binder functionality, requiring precise hydrolysis control to maintain extrusion performance.
- Organic:Certified organic digest streams demand segregated rendering and processing infrastructure with documented feedstock traceability.
- Others:Novel protein sources including insect and fermented microbial hydrolysates serve emerging allergen-avoidance and sustainability positioning segments.
Meat-Based formulations lead current volumes; Organic is expanding most quickly through EU Green Deal circular-economy procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The animal digest industry traces its commercial origins to the industrial rendering corridors of the United States Midwest, where meatpacking coproduct streams first achieved systematic valorization into hydrolyzed protein ingredients during the mid-twentieth century.
United States
Midwestern rendering clusters in Iowa and Nebraska supply the majority of domestic hydrolyzed protein feedstock, with FDA Center for Veterinary Medicine facility registrations exceeding any other jurisdiction. AAFCO labeling modernization efforts in 2024 clarified hydrolyzed protein classifications, reducing interstate formulation uncertainty. Chicago and Kansas City anchor procurement networks where specialty pet nutrition brands source certified digest grades for veterinary therapeutic diets.
Germany
German pet food manufacturers absorb premium digest streams at carbon-intensity thresholds mandated by EU Green Deal circular-economy criteria. EFSA guidance on processed animal protein safety notifications shapes import requirements for non-EU hydrolyzed protein suppliers. The North Rhine-Westphalia industrial corridor hosts segregated rendering infrastructure serving organic-certified digest demand from Dutch and French veterinary channels.
France
French veterinary clinic networks command premium pricing for prescription-adjacent therapeutic diets incorporating documented peptide characterization. ANSM oversight of feed ingredient safety converges with EU Green Deal sustainability disclosure requirements for imported hydrolyzed proteins. The Brittany agricultural processing cluster maintains specialized enzymatic hydrolysis capacity for limited-ingredient diet formulations targeting allergen-avoidance positioning.
United Kingdom
UK independent pet retailers concentrate shelf space around premium treat SKUs with single-source digest claims, particularly in London and Southeast England metropolitan markets. Post-Brexit import protocols for animal-derived feed ingredients require enhanced pathogen reduction documentation from EU suppliers. The Midlands rendering infrastructure serves domestic dry food manufacturers seeking AAFCO-equivalent certification for export positioning.
China
Chinese pet food production scale drives hydrolyzed protein demand for palatability enhancement in mass-market kibble formulations. SAMR feed ingredient safety standards and GB standards for processed animal proteins regulate domestic manufacturing and import clearance. The Yangtze River Delta manufacturing belt hosts extrusion facilities sourcing digest materials from both domestic rendering operations and imported premium streams.
Animal Digest Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification-grade and peptide-characterization capabilities, with veterinary-channel authorization creating the primary pricing wedge. The vendor base stratifies into three functional tiers: integrated rendering operators controlling upstream feedstock, specialized palatability-science firms with enzymatic hydrolysis R&D intensity, and diversified nutrition conglomerates leveraging manufacturing scale. Dominant competitive moves include backward integration into protein processing infrastructure and strategic partnerships with veterinary distribution networks securing prescription-adjacent positioning.
Among integrated rendering operators, Darling Ingredients exemplifies upstream feedstock control through captive supply of meat and poultry processing coproducts. Kemin Industries and ADM Animal Nutrition occupy positions within the palatability-science and manufacturing-scale archetypes respectively, with the former representing R&D-intensive peptide characterization capabilities and the latter anchoring North American production volume. These three firms illustrate how competitive positioning diverges across feedstock security, technical differentiation, and operational scale vectors.
| Leading Market Players |
|---|
| Kemin Industries |
| ADM Animal Nutrition |
| Cargill |
| BASF SE |
| Darling Ingredients |
| Omega Protein Corporation |
| Nestlé |
| B&G Foods, Inc. |
| John Pointon and Sons Ltd |
| Others |
Value Chain & Pricing Dynamics
Captive supply of meat and poultry processing coproducts anchors both procurement security and margin capture for integrated rendering operators, with Midwestern US feedstock concentration translating into pricing leverage over specialty pet food manufacturers seeking certified digest grades.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates veterinary-certified peptide-characterized grades from commodity acid-hydrolyzed streams and unbranded coproducts. Certification grade and volume scale drive price differentiation, with clinic-exclusive therapeutic diet authorization commanding the widest spreads. Cost compression in standard-tier dry food applications is intensifying because plant protein substitutes capture formulation share. Mass-market supermarkets exhibit highest price sensitivity; veterinary clinics demonstrate least sensitivity due to prescription-adjacent captive demand.
Supply Chain Analysis
Rendering coproduct returns and reprocessing flows sustain circular-economy positioning for EU Green Deal compliance, with spent material streams re-entering hydrolysis circuits for secondary valorization. Geographic supply concentrates in the United States, Germany, and China, with Midwestern rendering corridors, North Rhine-Westphalia industrial clusters, and Yangtze River Delta manufacturing belts anchoring regional output. Raw material dependencies center on cattle and poultry processing volumes, enzymatic catalyst inputs, and antioxidant stabilization additives. Single-source vulnerability in Midwestern US rendering corridors poses structural supply risk. Distribution runs through veterinary clinic networks, specialty independent retailers, and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge from divergent EU Green Deal carbon-intensity thresholds and US FDA facility registration burdens, with sustainability compliance costs in European markets creating margin capture potential for North American exporters meeting bloc-wide circular-economy criteria.
For Market Incumbents: Extend peptide characterization capabilities into antioxidant stabilization convergence, securing shelf-life extension contracts that bind premium dry food manufacturers through multi-year technical service agreements. Deepen backward integration into named-species protein processing infrastructure to defend against precision-fermentation substitutes capturing grain-free positioning share. Channel control through veterinary distribution partnerships remains the critical lever for margin defense. For New Entrants and Emerging Players: Veterinary clinic co-location partnerships in coastal US metropolitan markets offer the most penetrable white-space, with independent pet retailer consolidation creating shelf-access bottlenecks for unbranded digest suppliers. Target limited-ingredient treat formulations where single-source protein claims command disproportionate margin premiums dry food cannot sustain. Direct-to-consumer subscription platforms enable ingredient transparency storytelling that bypasses incumbent slotting-fee barriers. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap enzymatic hydrolysis specialists because peptide characterization expertise scarcity concentrates in fragmented regional rendering operations lacking R&D scale. Long-term viability across the five-to-ten year window hinges on backward integration into protein processing infrastructure and veterinary channel authorization. Acquisition targets should demonstrate segregated premium digest streams with documented carbon-intensity disclosures. The signal to watch is FDA dilated cardiomyopathy investigation outcomes redirecting formulation investment toward meat-based variants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Protein Processing | Captive feedstock supply from Iowa and Nebraska rendering corridors secures raw material traceability for AAFCO-certified grades. |
| Veterinary Channel Partnership Expansion | Clinic-exclusive distribution networks in the United States sustain prescription-adjacent pricing power for therapeutic diet applications. |
| Enzymatic Hydrolysis R&D Intensification | Controlled temperature and pH processing preserves peptide bioactivity for sensitive life-stage formulations targeting premium positioning. |
| EU Green Deal Compliance Certification | Carbon-intensity disclosure validation unlocks German and French veterinary channel access for North American premium digest exporters. |
| Antioxidant Stabilization Technology Integration | Convergence of palatability science with lipid preservation opens shelf-life extension contracts for premium dry food manufacturers. |
Study Parameters
Multiple input streams — primary interviews with rendering facility operators, pet food formulation scientists, and veterinary procurement managers; secondary validation through FDA Center for Veterinary Medicine facility registries, AAFCO ingredient definition updates, and USDA Agricultural Marketing Service inspection records; customs and trade data from USITC and Eurostat; and SEC 10-K disclosures from publicly listed ingredient suppliers — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Segment-level volume and value outputs were modeled across product type, end user, distribution channel, and ingredient type dimensions, with additional granularity applied to certification grade tiers and peptide characterization specifications. CAGRs were derived from trend extrapolation of historical procurement patterns and forward projection of regulatory-driven formulation shifts. Industry-specific forecast inputs included AAFCO labeling modernization implementation timelines and EU Green Deal circular-economy procurement mandate adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA dilated cardiomyopathy investigation resolutions, precision-fermentation protein substitute cost curves, and state-level biodegradable packaging mandate rollouts. Forecasts reflect documented assumptions regarding enzymatic hydrolysis capacity expansion rates and veterinary therapeutic diet program growth trajectories. Practitioners should monitor EFSA processed animal protein safety notification revisions and SAMR feed ingredient standard updates for early signals of supply chain reconfiguration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Feed Carotenoids Market
Veterinary Nutritional Products
Animal Growth Promoter Market
Veterinary Nutritional Products
South America Feed Vitamins Market
Veterinary Nutritional Products
Animal Based Protein Supplements Market
Veterinary Nutritional Products
Animal Probiotics Market
Veterinary Nutritional Products
Latin America Animal Feed Organic Trace Minerals Market
Veterinary Nutritional Products
Calf Milk Replacers Market
Veterinary Nutritional Products
Feed Electrolytes Market
Veterinary Nutritional Products
Natural Feed Additive Market
Veterinary Nutritional Products
Probiotics in Animal Feed Market
Veterinary Nutritional Products
Animal Nutrition Market
Veterinary Nutritional Products
Feed Anticoccidials Market
Veterinary Nutritional Products
Cattle Nutrition Market
Veterinary Nutritional Products
Feed Supplements Market
Veterinary Nutritional Products
Essential Oils in Animal Nutrition Market
Veterinary Nutritional Products
Cow Colostrum Market