

Ergonomic Strap Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Ergonomic Strap Systems Market Insights
Advanced textile engineering is reshaping how ergonomic strap systems integrate moisture-wicking composites and 3D-knit structures into load-bearing designs. Mosca leverages its European manufacturing footprint to supply precision-woven tension bands for industrial back supports. Tsubaki anchors its position through specialized metal-and-fabric hybrid fastening systems that serve heavy-lifting applications. FROMM Packaging Systems differentiates by controlling distribution channels for adjustable strapping solutions across logistics and material-handling sectors.
Ergonomic strap systems are load-distribution devices constructed from layered polymers, woven synthetics, or molded elastomers, typically rated for tensile strengths between 200 and 2,000 Newtons depending on application. These systems redistribute mechanical stress away from vulnerable anatomical points to prevent musculoskeletal injury during repetitive motion or sustained load carriage. Shoulder straps dominate revenue due to their ubiquity across outdoor gear and medical brace categories, while waist straps represent the fastest-expanding segment as employers adopt anti-fatigue belts for warehouse and construction environments. Silicone interfaces command premium positioning in medical supports because of hypoallergenic certification requirements, whereas nylon remains the volume leader in sports equipment for its abrasion resistance and dye compatibility.
ISO 13485 quality management standards govern medical-grade strap production, while OSHA ergonomic guidelines in the United States mandate employer-provided back support for manual material-handling roles above specified weight thresholds. The EU Medical Device Regulation requires notified body involvement for straps claiming therapeutic or injury-prevention benefits, creating compliance barriers for uncertified Asian suppliers. Stakeholders must monitor evolving biomechanical testing protocols and regional certification reciprocity agreements to align product development with enforceable standards.
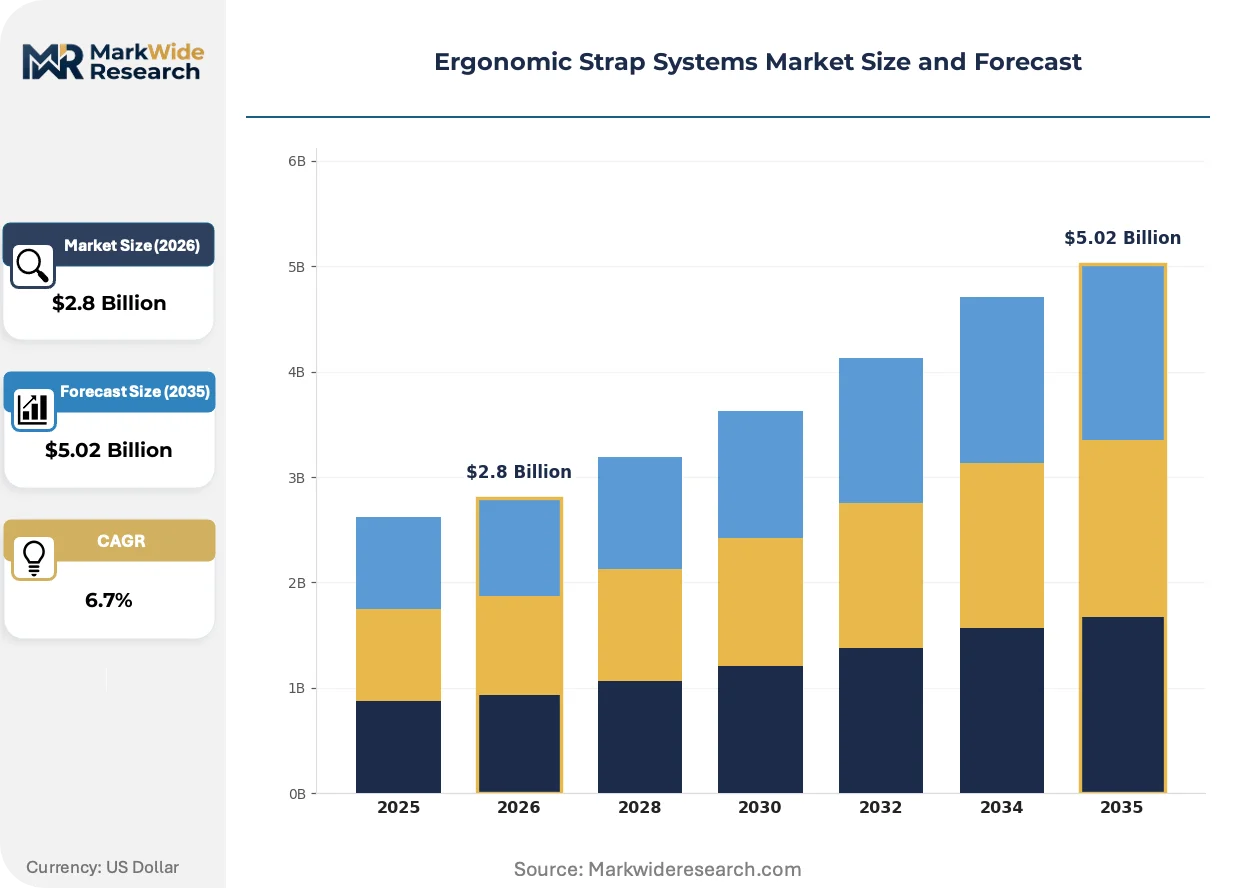
Market Dynamics
The EU Medical Device Regulation's tightened biocompatibility mandates are forcing manufacturers to reformulate skin-contact polymers and revalidate entire product lines, creating asymmetric compliance burdens across supplier tiers.
Growth Catalysts
- German occupational health mandates:Employers in manufacturing and logistics must provide adjustable lumbar support for manual material-handling roles above specified weight thresholds, accelerating institutional procurement cycles.
- 3D-knit moisture-wicking composites:Advanced textile engineering enables seamless integration of load-bearing structures with breathable interfaces, expanding adoption into sports medicine and outdoor equipment categories.
- Aging workforce demographics:Japan's expanding elderly population drives demand for medical-grade shoulder and waist straps in rehabilitation centers and home healthcare settings.
Market Restraints
- Medical-grade silicone cost volatility:Hypoallergenic certification requirements for skin-contact materials concentrate input dependency on specialized chemical suppliers, compressing margin buffers for mid-tier manufacturers.
- Notified body capacity constraints:EU MDR compliance bottlenecks delay market entry for uncertified Asian suppliers, extending certification timelines and freezing working capital.
- Mechanical fastening substitution:Rigid exoskeleton systems for heavy-lifting applications displace fabric-based tension bands in industrial warehouse environments.
Strategic Opportunities
- India's PLI scheme for technical textiles:Domestic manufacturing incentives attract strap system producers seeking alternative production bases outside concentrated East Asian supply networks.
- Telehealth-integrated wearable monitoring:Convergence of load-distribution hardware with biometric sensors creates subscription revenue streams in remote patient monitoring.
- Direct-to-employer channel bypass:Occupational health service providers aggregate demand from small and mid-sized enterprises, reducing distributor margin capture.
Industry Challenges
- Biomechanical testing protocol fragmentation:Divergent ISO, OSHA, and national standards require redundant validation cycles, extending product development timelines.
- Polymer formulation IP thickets:Patent clustering around elastomer blends and woven synthetic structures complicates freedom-to-operate analysis for new entrants.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ergonomic Strap Systems Market Trends and Innovations
Material science breakthroughs and regulatory harmonization pressures are compressing traditional product development cycles while opening new performance tiers previously separated by certification boundaries.
Shape-memory alloy integration into tension bands is collapsing the distinction between passive support and active assistive devices. Rehabilitation centers in Germany and Japan are piloting these systems for post-surgical mobility recovery. The technology is collapsing price stratification between medical and industrial strap categories as shared manufacturing platforms emerge.
REACH restrictions on persistent organic pollutants in textile coatings are forcing reformulation of abrasion-resistant surface treatments. Manufacturers serving European markets must substitute legacy fluorocarbon-based finishes with bio-based alternatives. Medical brace suppliers face the steepest transition costs due to extended biocompatibility revalidation requirements.
Employer procurement departments are consolidating vendor relationships through multi-year occupational health equipment frameworks. Third-party occupational health service providers in the United States are displacing traditional distributor networks by bundling ergonomic assessments with strap system provisioning. This concentration is most visible in German automotive manufacturing clusters where works councils mandate standardized equipment across plant networks.
Ergonomic Strap Systems Market Segmentation
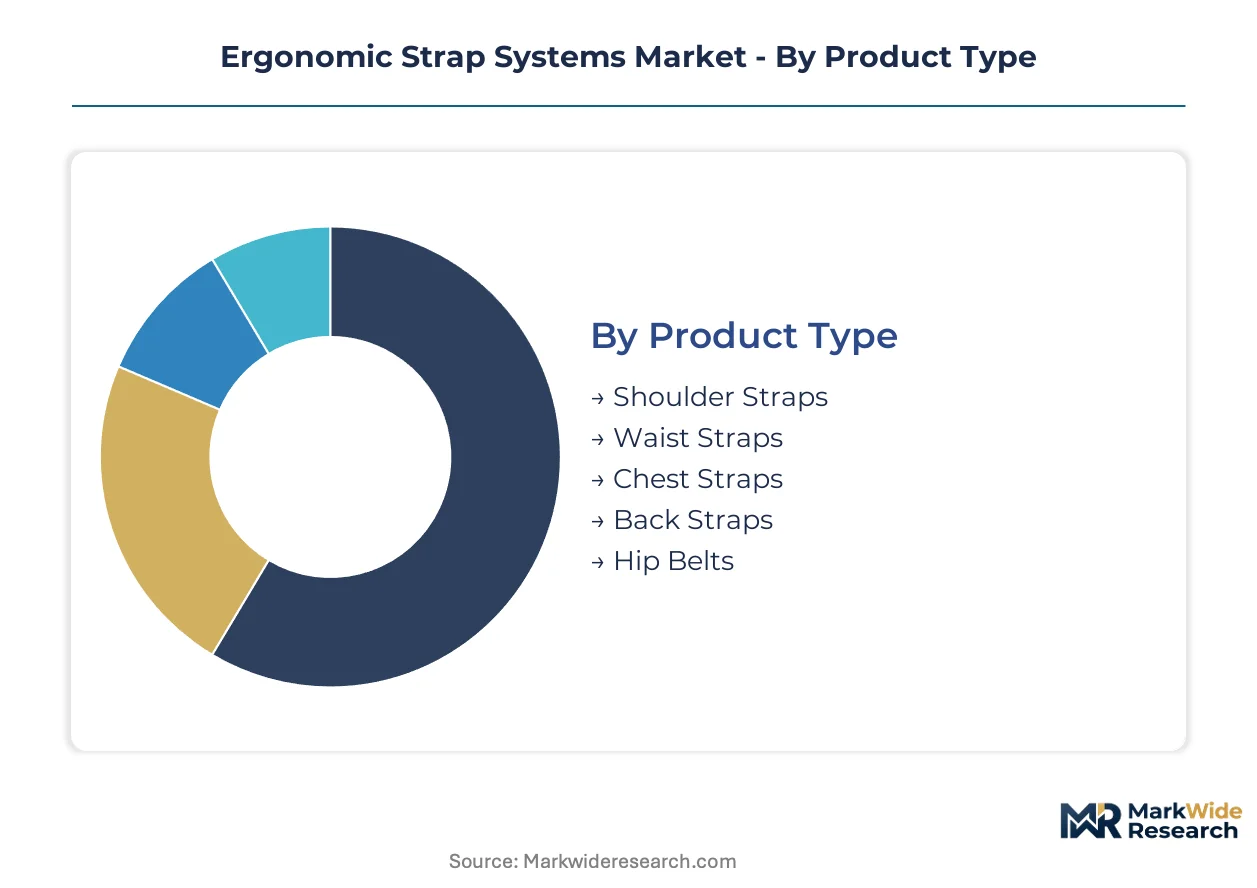
Segmentation in ergonomic strap systems reflects divergent biomechanical requirements across load-bearing anatomical zones and end-use environments. Each category reveals distinct material specifications, certification thresholds, and procurement channel preferences that shape supplier positioning.
Product Type:
Mature industrial applications anchor established segments while emerging medical-grade innovations redefine performance boundaries.
- Shoulder Straps:Layered polymer-and-webbing constructs distribute compressive loads across the trapezius and deltoid muscle groups, typically rated for 200-800 Newton tensile strength. Demand concentrates in German rehabilitation centers where post-operative mobility protocols mandate adjustable tension systems for rotator cuff recovery.
- Waist Straps:Broad circumferential bands with rigid anterior panels redirect lumbar shear forces through the abdominal cavity. Warehouse employers across Japan's logistics hubs are adopting anti-fatigue belts as mandatory personal protective equipment under revised occupational health directives.
- Chest Straps:Sternum-stabilizing configurations prevent pack sway during dynamic movement. Trail running communities in the Swiss Alps drive specialized demand for minimal-bounce designs.
- Back Straps:Vertical tension systems spanning the thoracic spine serve heavy-lifting applications in South Korean shipbuilding yards.
- Hip Belts:Pelvic load-transfer mechanisms enable extended load carriage without spinal compression. Expedition outfitters serving Himalayan trekking routes specify reinforced buckle systems.
Shoulder straps retain volume leadership; waist straps hold the steepest expansion curve.
Application:
Cost tier stratification separates premium-certified medical devices from commoditized consumer categories.
- Outdoor Gear:Technical backpacks and climbing harnesses integrate adjustable torso-length systems with moisture-wicking back panels. Alpine guide services in Austria specify modular strap architectures for multi-day expeditions.
- Medical Supports:ISO 13485-certified braces for post-surgical immobilization and chronic condition management require biocompatibility validation and notified body oversight under EU MDR. German orthopedic clinics are expanding procurement of adjustable lumbar systems for degenerative disc disease protocols.
- Industrial Safety:Employer-mandated back support for manual material-handling roles above OSHA-specified weight thresholds. Construction contractors in Texas oilfield regions specify heavy-duty configurations for repetitive lifting cycles.
- Sports Equipment:Weightlifting belts and resistance training harnesses prioritize rapid adjustability between sets. CrossFit affiliate networks in California drive demand for quick-release buckle systems.
- Travel Accessories:Anti-theft bag straps and luggage stabilization systems emphasize lightweight portability. Business travelers through Dubai International Airport favor slash-resistant webbing constructions.
Outdoor gear commands the broadest SKU proliferation; medical supports generate the highest margin realization.
Material:
Supply concentration for specialized polymers creates asymmetric input dependencies across manufacturer tiers.
- Neoprene:Closed-cell synthetic rubber provides thermal insulation and cushioning for water-adjacent applications. Surf rescue teams along Australia's Gold Coast specify marine-grade neoprene harness systems.
- Nylon:High-tenacity polyamide fibers dominate volume production due to abrasion resistance and dye compatibility. Abrasion-resistant 1050-denier ballistic weaves serve military contractor specifications in Virginia.
- Polyester:UV-stable synthetic with superior colorfastness for extended outdoor exposure. Agricultural workers in Brazil's soybean belt specify polyester-based back supports for sun-intensive harvest seasons.
- Leather:Traditional vegetable-tanned hides retain niche positioning in heritage craftsmanship categories. Artisan saddle makers in Argentina's Pampas region supply custom hip belt systems for gaucho culture preservation.
- Silicone:Medical-grade elastomers with hypoallergenic certification command premium positioning for skin-contact applications. Japanese home healthcare providers specify platinum-cured silicone interfaces for elderly patients with dermatological sensitivities.
Nylon retains volume leadership; silicone holds the steepest expansion curve.
End User:
Customer type fragmentation demands distinct distribution channel strategies and certification documentation packages.
- Hiking Enthusiasts:Recreational trekkers prioritize weight-to-durability ratios and modular attachment compatibility. Pacific Crest Trail through-hikers in Oregon specify ultralight shoulder strap systems sub-150 grams per pair.
- Rehabilitation Centers:Institutional procurement departments require ISO 13485 traceability and extended warranty terms. National health service networks in the United Kingdom are consolidating vendor relationships through multi-year framework agreements.
- Construction Workers:Employer-funded personal protective equipment programs emphasize cost amortization across multi-year replacement cycles. Unionized carpentry crews in New York City mandate standardized back support across municipal infrastructure projects.
- Athletes:Performance-oriented users demand rapid adjustability and moisture management during high-exertion intervals. Professional cycling teams in Italy specify aerodynamic chest strap configurations for time trial disciplines.
- Frequent Travelers:Convenience-focused consumers prioritize packability and airport security compatibility. Corporate road warriors through Singapore Changi favor magnetic-quick-release buckle systems for TSA checkpoint efficiency.
Rehabilitation centers anchor institutional procurement volume; construction workers represent the fastest-climbing demand segment among employer-funded categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rehabilitation centers and employer-mandated occupational health programs concentrate procurement across industrialized economies with aging workforces and stringent safety regulations. Demand clusters where medical device certification requirements and manual material-handling mandates overlap.
Germany
Works councils in automotive manufacturing clusters mandate standardized lumbar support systems across plant networks. The EU Medical Device Regulation requires notified body involvement for therapeutic claims, creating compliance barriers for uncertified suppliers. Bavarian industrial zones anchor procurement volume for adjustable tension bands serving warehouse and construction environments.
United States
OSHA ergonomic guidelines mandate employer-provided back support for manual material-handling roles above specified weight thresholds. Third-party occupational health service providers displace traditional distributor networks by bundling assessments with equipment provisioning. Texas oilfield contractors specify heavy-duty configurations for repetitive lifting cycles in energy extraction zones.
Japan
Expanding elderly populations drive institutional procurement of medical-grade shoulder and waist straps for home healthcare and rehabilitation settings. METI standards govern quality benchmarks for assistive devices distributed through national health service channels. Osaka-Kobe manufacturing corridors supply precision-woven components for hybrid metal-fabric fastening systems.
India
The PLI scheme for technical textiles attracts strap system producers seeking alternative production bases outside concentrated East Asian supply networks. BIS certification requirements create entry barriers for imported medical-grade products. Gujarat textile clusters are expanding capacity for high-tenacity woven synthetics serving industrial safety applications.
South Korea
Shipbuilding yards in the Busan-Ulsan corridor specify vertical tension systems spanning the thoracic spine for heavy-lifting applications. MFDS regulations govern biocompatibility requirements for skin-contact materials in medical supports. Seoul Capital Area rehabilitation centers are piloting shape-memory alloy integration for post-surgical mobility recovery.
Ergonomic Strap Systems Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure shaped by certification depth and manufacturing scale. The vendor base separates into three strategic archetypes: precision-woven tension band suppliers, metal-fabric hybrid fastening system fabricators, and adjustable strapping solution distributors. Dominant competitive moves include strategic partnerships with occupational health service providers and geographic expansion through regional manufacturing footprints.
Among European-based manufacturers, Mosca leverages its continental production footprint to supply industrial applications, while FROMM Packaging Systems exemplifies channel-control positioning through distribution network management. Tsubaki anchors the Asia-Pacific specialist tier with metal-and-fabric hybrid configurations. These three represent distinct competitive vectors: continental manufacturing scale, distribution channel dominance, and specialized fastening engineering.
| Leading Market Players |
|---|
| Mosca |
| Signode |
| Tsubaki |
| UFlex |
| FROMM Packaging Systems |
| Orgapack |
| StraPack |
| Transpak Equipment Corp. |
| Samuel Strapping Systems |
| Others |
Pricing and Supply Chain Analysis
German precision-woven tension band suppliers command disproportionate margin capture downstream, as automotive works councils and rehabilitation centers prioritize certified supply security over unit cost minimization. This upstream concentration in Bavarian manufacturing clusters funnels pricing power toward ISO 13485-compliant producers while compressing mid-tier Asian competitors into commodity tiers.
Pricing Analysis
Cost-plus contracts with medical-grade silicone indexation dominate procurement frameworks for skin-contact applications, insulating certified suppliers from raw material volatility. Three-tier pricing structure across premium, standard, and economy levels separates platinum-cured silicone interfaces from nylon webbing and untreated polyester blends. Cost compression in the standard tier intensifies because India's PLI scheme attracts volume manufacturers seeking alternative production bases. Employer-funded industrial safety programs exhibit highest price sensitivity due to multi-year amortization mandates, while Japanese home healthcare providers show least sensitivity given dermatological certification requirements.
Supply Chain Analysis
Export-control restrictions on shape-memory alloy technologies limit flows from South Korean and Japanese suppliers to third-country manufacturers, fragmenting access to active-assistive components. Production gravity centers on Germany for precision-woven synthetics, China for high-tenacity nylon substrates, and India for technical textile expansion under PLI incentives. Raw material dependencies span medical-grade silicone elastomers, shape-memory alloy wire feedstock, and REACH-compliant bio-based coatings. Single-source vulnerability concentrates in platinum-cured silicone supply from specialized chemical processors. Distribution runs through third-party occupational health service providers bundling assessments with equipment provisioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment moat where EU MDR notified body certification creates switching costs that freeze out uncertified competitors for multi-year validation cycles.
For Market Incumbents: Harden certification depth through backward integration into polymer formulation capabilities, eliminating dependency on specialized chemical suppliers subject to REACH reformulation mandates. Expand captive production of bio-based coating alternatives ahead of fluorocarbon restrictions. Rigid exoskeleton substitution in heavy-lifting applications threatens fabric-based tension band displacement; counter by piloting shape-memory alloy hybrid systems in German rehabilitation networks. For New Entrants and Emerging Players: Pursue India's technical textile PLI incentives as a manufacturing beachhead, leveraging BIS certification barriers to serve domestic industrial safety demand while building compliance capabilities for eventual EU MDR entry. Target Gujarat textile clusters for high-tenacity woven synthetic production. Direct-to-employer channel bypass through occupational health service provider partnerships offers the most penetrable go-to-market angle, circumventing entrenched distributor relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision-woven tension band specialists holding automotive supply contracts but lacking medical-grade certification depth. Long-term viability over a five-to-ten year horizon hinges on regulatory reciprocity expansion between EU MDR and Asian notified body frameworks. Watch for MFDS-Japan METI mutual recognition agreements as the inflection signal for cross-border M&A acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Certification Investment | EU MDR compliance unlocks German automotive and rehabilitation center procurement frameworks. |
| Backward Integration into Polymer Formulation | In-house silicone compounding insulates margins from medical-grade elastomer cost volatility. |
| Shape-Memory Alloy Pilot Programs | Rehabilitation center trials in Seoul and Munich collapse price stratification between medical and industrial tiers. |
| PLI Scheme Manufacturing Relocation | Gujarat technical textile clusters attract capacity seeking alternatives to concentrated East Asian supply networks. |
| Occupational Health Service Partnership | Third-party bundling of ergonomic assessments with strap provisioning displaces traditional distributor margin capture. |
Research Methodology
Cross-validation between primary interviews with procurement directors at German automotive works councils and secondary validation through EU MDR notified body filings anchors the qualitative findings. Conversations with biomedical engineers at Japanese rehabilitation centers, occupational health service provider contract managers, and textile R&D directors at Indian PLI beneficiaries complement customs data and ISO 13485 certification registries. Bottom-up segment sizing triangulates against top-down macroeconomic indicators across the analysis window.
Calibration against historical procurement cycles and regulatory implementation timelines shapes the analytical framework. Segmentation dimensions span anatomical load zone, application environment, material certification grade, and end-user procurement channel. CAGRs derive from slope-consistent modeling of institutional adoption curves and employer mandate expansion. Forecast inputs incorporate REACH reformulation timelines and METI assistive device quality benchmark revisions.
Sensitivities concentrate around notified body capacity constraints extending EU MDR certification timelines and shape-memory alloy export control expansion. Forecasts reflect documented assumptions regarding regulatory reciprocity progression and polymer substitution elasticity. Material shifts in EU-Asia mutual recognition frameworks or REACH substance restriction scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.