
 Clay Pigeon Thrower Market | 2026-2036
Clay Pigeon Thrower Market Size, Share, and Industry Trends Forecast 2026-2036
Clay Pigeon Thrower Market Analysis
The clay pigeon thrower market is pivoting on a widening split between premium automatic units with programmable trajectories and commodity-grade manual throwers sold through mass retail. Trius leverages its heritage in mechanical designs to sustain a loyal base of traditional shooters who prioritize durability over digital features. MEC Outdoors anchors its position through in-house production of replacement parts, ensuring aftermarket revenue streams that competitors struggle to replicate. Champion competes aggressively on price while extending distribution through big-box sporting goods chains across the southern United States.
A clay pigeon thrower is a mechanical or electromechanical device designed to launch standardized clay targets at variable angles, speeds, and elevations, typically employing a spring-loaded arm, pneumatic piston, or motorized carousel with launch velocities between 65 and 95 miles per hour. These devices serve shooting ranges, sports clubs, and competitive venues by simulating the flight patterns of game birds for trap, skeet, and sporting clays disciplines. Automatic throwers with electronic programming dominate the product type landscape due to their capacity for randomized target presentations that challenge experienced shooters, while portable throwers represent the fastest-growing segment as individual users seek mobile training setups for private land use. The technology dimension shows electronic control systems capturing margin pools through subscription-based firmware updates and Bluetooth-enabled remote operation, whereas mechanical systems retain volume leadership in emerging markets with limited electrical infrastructure.
The United States Bureau of Alcohol, Tobacco, Firearms and Explosives maintains oversight of shooting range operations, indirectly shaping thrower demand through facility licensing requirements that mandate equipment safety certifications. The Consumer Product Safety Commission monitors mechanical failure reports, pressuring manufacturers toward redundant safety interlocks and improved arm guard designs. Shooters and range operators must weigh total cost of ownership against programmable capability as electronic throwers require specialized maintenance networks that remain sparse outside metropolitan shooting corridors.
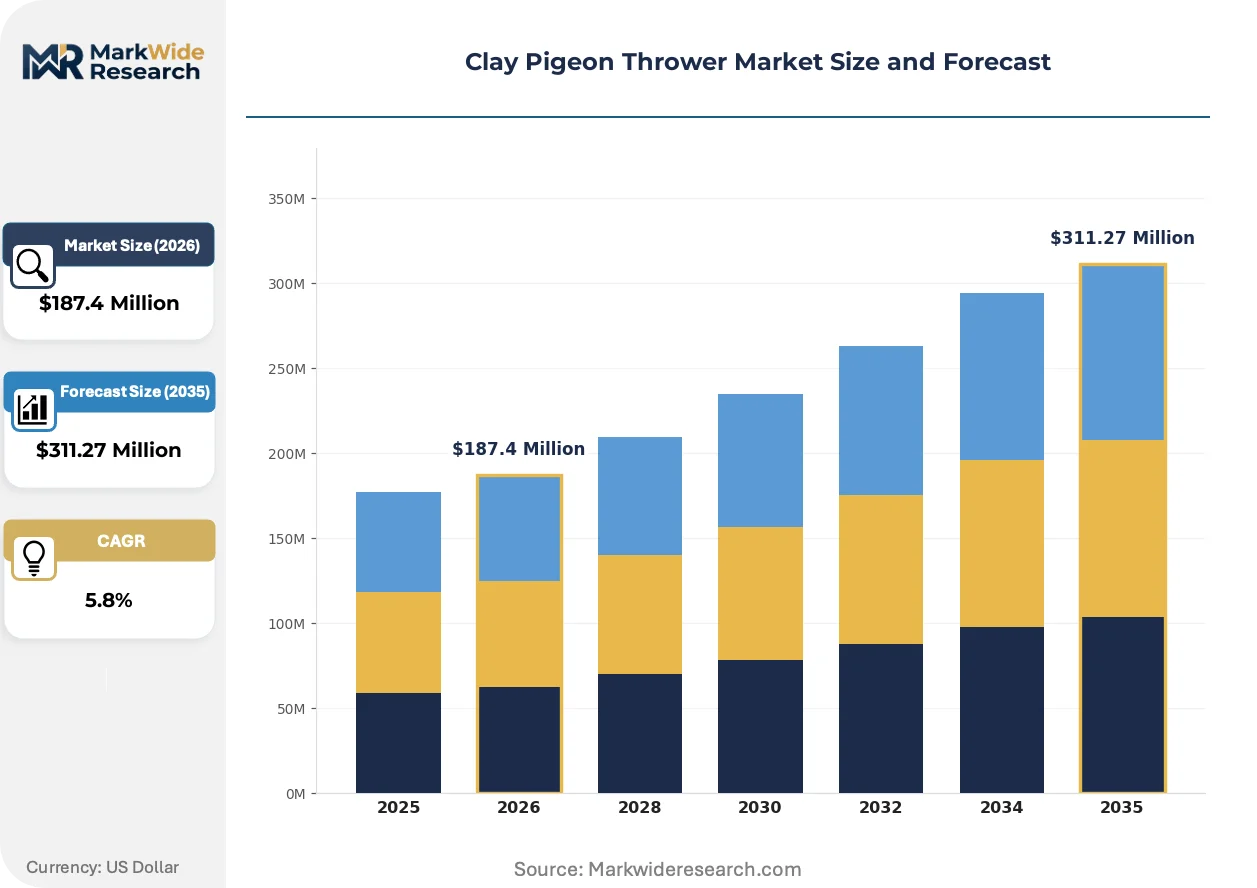
Market Dynamics
The clay pigeon thrower market is bifurcating around electronic control systems that enable programmable trajectories and randomized target presentations, compressing demand for mechanical pull-cord units while expanding service revenue through firmware subscriptions.
Growth Catalysts
- Collegiate athletics expansion:NCAA-sanctioned trap and skeet programs across the United States are mandating standardized electronic throwers for championship qualification, forcing equipment upgrades at university ranges.
- Wireless remote activation:Bluetooth-enabled trigger systems are eliminating manual pull-cord labor costs at commercial shooting facilities, reducing staffing requirements by half during peak hours.
- REACH-compliant materials:European manufacturers are substituting lead-free counterweights and RoHS-certified electronics to maintain access to EU member state procurement contracts.
Market Restraints
- Specialized maintenance networks:Electronic throwers require certified technicians for circuit board diagnostics, and these service hubs concentrate in Dallas, Phoenix, and Atlanta metropolitan corridors.
- Steel price volatility:Spring-loaded arm mechanisms depend on high-tensile steel alloys, and input cost swings compress margins for mechanical thrower producers who cannot pass through increases to price-sensitive rural buyers.
- Limited electrical infrastructure:Emerging market shooting clubs in sub-Saharan Africa and rural Southeast Asia lack reliable grid access, constraining adoption of automatic units despite demand for competitive training equipment.
Strategic Opportunities
- Private land mobile setups:Portable throwers with battery-powered motors are penetrating individual ownership segments in Texas and Florida, where recreational shooters train on personal acreage outside formal range infrastructure.
- Subscription firmware models:Manufacturers are monetizing trajectory randomization algorithms through annual software licenses, creating recurring revenue streams distinct from hardware sales cycles.
- Indian PLI scheme alignment:Domestic assembly of electronic control modules under India's production-linked incentive framework reduces landed costs for South Asian shooting clubs.
Industry Challenges
- Electromechanical technician shortage:Shooting range operators struggle to hire staff capable of diagnosing pneumatic piston failures and recalibrating motorized carousel timing mechanisms.
- ATF facility licensing delays:Bureau of Alcohol, Tobacco, Firearms and Explosives certification timelines for new commercial ranges stretch 14-18 months, freezing equipment procurement decisions until permits clear.
- Legacy mechanical inventory:Distributors hold depreciating stocks of pull-cord throwers as demand pivots toward programmable units, forcing write-downs or fire-sale liquidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clay Pigeon Thrower Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Throwers, Automatic Throwers, Electric Throwers, Portable Throwers End User: Shooting Ranges, Sports Clubs, Individual Users, Law Enforcement Agencies Technology: Mechanical, Pneumatic, Electronic, Hybrid Distribution Channel: Online Retail, Physical Stores, Distributors, Direct Sales |
| Companies Covered | Trius, MEC Outdoors, Caldwell, Parvalux Electric Motors, Nordic Clays, Do All Outdoors, Laporte, Birchwood Casey, Champion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clay Pigeon Thrower Market Emerging Trajectories
Digital trajectory programming is displacing fixed-angle mechanical systems across competitive venues, while aftermarket service unbundling and regulatory material mandates are reshaping supplier economics and procurement specifications.
Programmable microcontroller arrays with stored flight-pattern libraries are automating target presentation sequences that previously required manual operator judgment. Championship-grade sporting clays facilities in the United States are adopting these systems to simulate unpredictable game-bird flight paths. This capability is automating the role of human pullers and compressing labor cost structures at commercial ranges.
REACH substance restrictions and RoHS electronics directives in the European Union are mandating lead-free counterweights and halogen-free circuit boards in thrower manufacturing. Industrial consequence includes accelerated R&D spending on alternative alloy formulations and polymer composites. German and Italian shooting equipment producers are most affected, responding by vertically integrating compound foundry operations to control material certification documentation.
Shooting clubs are unbundling after-sales service contracts from hardware purchases, preferring third-party maintenance providers over manufacturer-captive service networks. This behavior disrupts traditional OEM revenue models and elevates independent repair shops in the southern United States. Texas and Florida exhibit the strongest unbundling momentum, where high humidity and salt-air corrosion accelerate component replacement cycles.
Clay Pigeon Thrower Market Segmentation
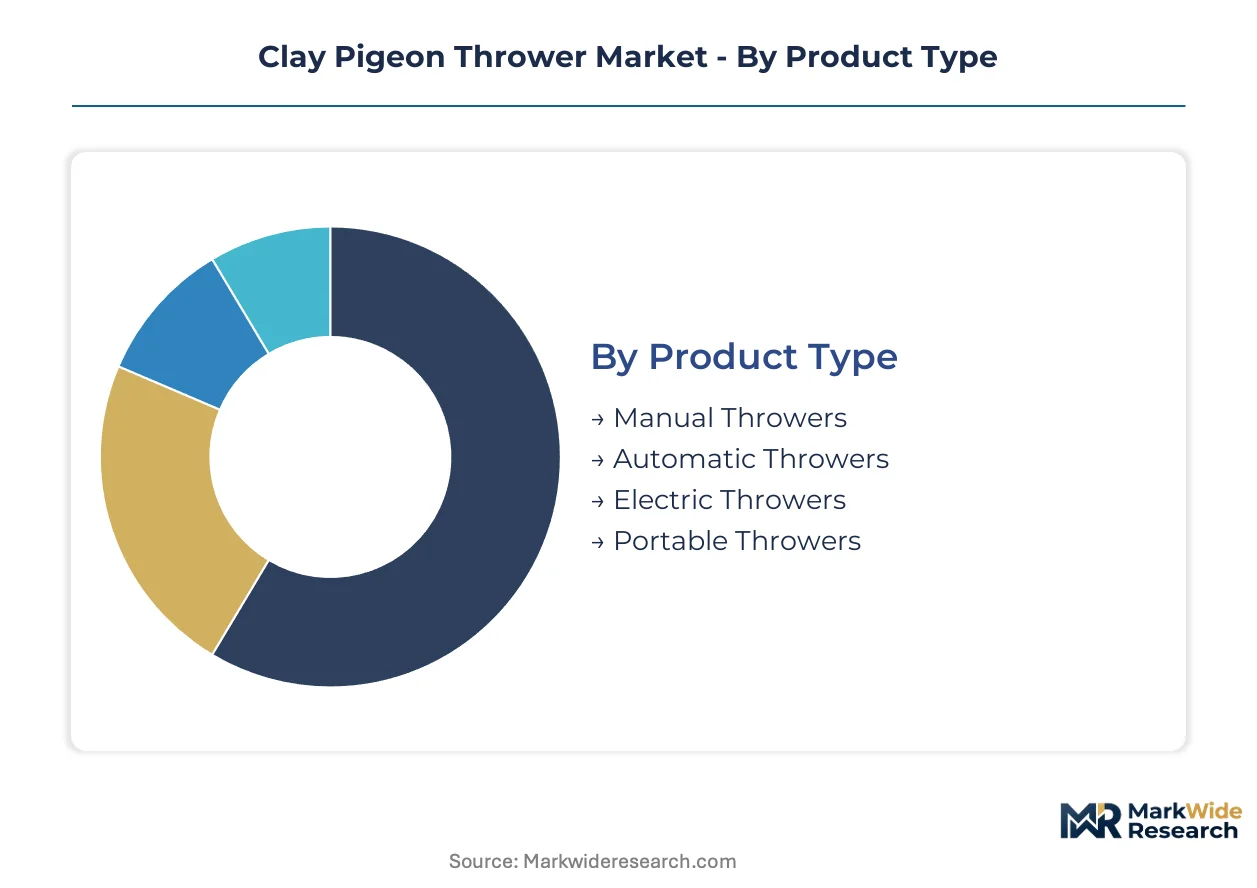
Clay pigeon thrower procurement decisions split across capability requirements, infrastructure constraints, and total cost of ownership calculations. Buyers weigh programmable sophistication against maintenance access and electrical reliability.
Product Type:
Buyers prioritize trajectory control precision and labor reduction when selecting thrower mechanisms.
- Automatic Throwers:Motorized carousel systems with programmable launch angles and variable speed settings dominate competitive venues. Demand concentrates at NCAA-sanctioned university ranges and championship-grade sporting clays facilities where randomized target presentations are mandatory for qualification standards.
- Portable Throwers:Battery-powered units with collapsible frames enable mobile training setups on private acreage. Texas and Florida recreational shooters drive adoption where formal range infrastructure is distant and personal land access is common.
- Manual Throwers:Spring-loaded arm mechanisms with pull-cord activation serve budget-conscious rural buyers and traditional shooting clubs with limited electrical access.
- Electric Throwers:Grid-dependent systems with consistent launch velocity appeal to commercial ranges with stable power supply and on-site maintenance capability.
Automatic throwers lead on scale; portable throwers lead on momentum.
End User:
Facility type determines duty cycle intensity and feature requirements across the installed base.
- Sports Clubs:Competitive trap and skeet programs require electronic throwers with firmware-update capability and championship-standard trajectory libraries. North American clubs sustain replacement cycles through collegiate athletics expansion and tournament hosting revenue.
- Shooting Ranges:Commercial operations prioritize wireless remote activation to reduce pull-cord labor costs and enable single-staff operation during peak hours.
- Individual Users:Private land owners in southern United States states seek battery-powered portability and minimal setup complexity for personal training regimens.
- Law Enforcement Agencies:Tactical training programs require durable mechanisms with consistent flight patterns for shotgun qualification protocols.
Sports clubs command the highest per-unit spend; individual users are expanding most quickly.
Technology:
Power source and control architecture determine maintenance burden and geographic deployability.
- Electronic:Microcontroller arrays with stored flight-pattern libraries and Bluetooth connectivity enable trajectory randomization. Metropolitan shooting corridors in Dallas, Phoenix, and Atlanta concentrate demand where certified technician networks exist.
- Mechanical:Spring-loaded arm and pull-cord systems retain volume leadership in emerging markets with unreliable grid infrastructure and limited service access.
- Pneumatic:Compressed-air piston mechanisms deliver consistent launch velocity with reduced mechanical wear compared to spring systems.
- Hybrid:Combined mechanical-electronic systems balance programmable capability with simplified field repair options.
Electronic systems capture margin concentration; mechanical systems retain volume breadth.
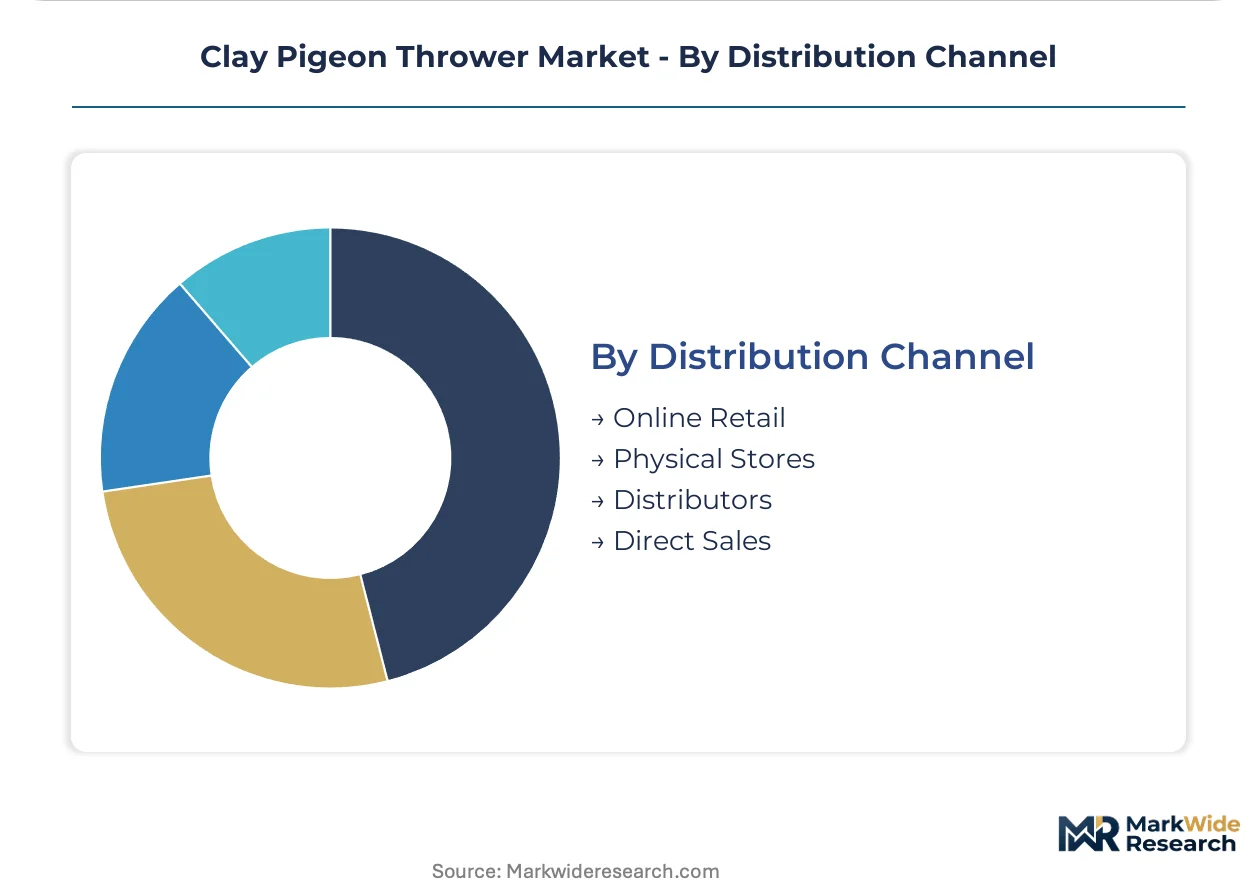
Distribution Channel:
Channel selection reflects buyer technical sophistication and urgency of replacement needs.
- Distributors:Specialized shooting equipment wholesalers provide technical consultation and aftermarket parts availability. Southern United States distributors hold depreciating mechanical inventory as demand pivots toward programmable units.
- Physical Stores:Big-box sporting goods chains in the southern United States extend mass-market reach for commodity-grade manual throwers.
- Direct Sales:Manufacturer-captive channels serve large-volume sports club and range operator accounts with customized installation and training.
- Online Retail:E-commerce platforms penetrate individual user segments with portable thrower specifications and comparison tools.
Distributors anchor commercial volume; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified electromechanical technicians concentrate in Dallas, Phoenix, and Atlanta metropolitan corridors, anchoring service infrastructure for electronic thrower deployments. Shooting range operators in these clusters report shorter equipment downtime and faster firmware update turnaround. Talent scarcity outside these hubs constrains automatic thrower adoption in secondary markets.
United States
NCAA-sanctioned trap and skeet programs mandate standardized electronic throwers for championship qualification, forcing equipment upgrades at university ranges from Texas to Minnesota. The Bureau of Alcohol, Tobacco, Firearms and Explosives maintains facility licensing requirements that indirectly shape thrower demand through safety certification mandates. Dallas-Fort Worth shooting corridors sustain replacement cycles as commercial ranges adopt wireless remote activation to halve staffing requirements during peak hours.
Germany
REACH substance restrictions and RoHS electronics directives mandate lead-free counterweights and halogen-free circuit boards in thrower manufacturing. German shooting equipment producers respond by vertically integrating compound foundry operations to control material certification documentation. Bavarian and North Rhine-Westphalian industrial clusters concentrate precision machining capacity for high-tensile steel alloy components used in spring-loaded arm mechanisms.
Italy
Championship-grade sporting clays facilities adopt programmable microcontroller arrays with stored flight-pattern libraries to simulate unpredictable game-bird flight paths. Italian manufacturers face REACH compliance pressures similar to German counterparts, accelerating R&D spending on alternative alloy formulations. The Lombardy and Emilia-Romagna regions host precision engineering workshops supplying pneumatic piston components to European thrower assemblers.
India
Domestic assembly of electronic control modules under India's production-linked incentive framework reduces landed costs for South Asian shooting clubs. The Bureau of Indian Standards monitors mechanical safety specifications for imported shooting equipment, shaping procurement documentation requirements. Maharashtra and Gujarat industrial zones concentrate contract manufacturing capacity for battery-powered portable thrower motors targeting individual ownership segments.
Australia
Recreational shooters on private acreage in Queensland and New South Wales drive demand for battery-powered portable throwers with collapsible frames. State-level firearms registries indirectly influence range infrastructure investment through licensing processing timelines. Melbourne and Sydney metropolitan shooting clubs favor electronic throwers with firmware-update capability for competitive trap and skeet program standardization.
Clay Pigeon Thrower Market Vendor Landscape
Top-tier vendors anchor the premium automatic thrower segment, while commodity-grade manual thrower producers compete on price through mass retail distribution. The vendor base spans heritage mechanical specialists, in-house parts manufacturers, and aggressive price competitors extending reach through big-box sporting goods chains. Three strategic archetypes dominate: durability-focused traditionalists, aftermarket revenue stream builders, and volume-driven mass-market suppliers. Competitive moves concentrate on geographic expansion through distributor partnerships and portfolio diversification into portable battery-powered units.
Within the heritage mechanical tier, Trius and MEC Outdoors exemplify contrasting approaches to sustaining market position. Trius occupies a position emphasizing traditional shooter loyalty through durability-focused design philosophy, while MEC Outdoors anchors its standing through in-house production of replacement parts that competitors struggle to replicate. Champion sits within the aggressive price-competition archetype, extending distribution through big-box sporting goods chains across the southern United States. These three companies collectively represent the spectrum from premium durability positioning to volume-driven mass-market penetration.
| Leading Market Players |
|---|
| Trius |
| MEC Outdoors |
| Caldwell |
| Parvalux Electric Motors |
| Nordic Clays |
| Do All Outdoors |
| Laporte |
| Birchwood Casey |
| Champion |
| Others |
Supply Flow & Price Mechanics
Captive production of replacement parts at MEC Outdoors anchors both supply security and aftermarket pricing power, insulating premium thrower manufacturers from commodity margin erosion while forcing competitors into transactional hardware-only revenue models.
Pricing Analysis
Bundled after-sales service contracts versus unbundled third-party maintenance splits the pricing landscape across customer tiers. Three-tier pricing structure across premium programmable units, mid-range electric systems, and economy manual throwers reflects firmware capability and certification grade differentials. Cost compression in mechanical throwers is intensifying because distributors liquidate depreciating pull-cord inventory amid electronic pivot demand. Rural individual buyers exhibit highest price sensitivity; NCAA-sanctioned university ranges show lowest sensitivity due to standardized equipment mandates.
Supply Chain Analysis
High-tensile steel alloy supply rests on German and Italian precision machining clusters, while electronic control module assembly concentrates in Maharashtra and Gujarat industrial zones under India's PLI framework. Spring-loaded arm mechanisms draw from Bavarian foundry capacity; battery-powered motor components source from East Asian contract manufacturers. Single-source vulnerability in certified electromechanical technician networks constrains electronic thrower deployment outside Dallas, Phoenix, and Atlanta corridors. Distribution runs through specialized shooting equipment wholesalers holding depreciating mechanical stocks alongside growing programmable unit allocations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in firmware subscription layering and captive aftermarket parts production, with cost-down drivers emerging from Indian PLI-aligned electronic module assembly and premium-tier shifts toward championship-grade programmable systems.
For Market Incumbents: Hedge against electronic technician scarcity by building certified service hub density in secondary metropolitan shooting corridors before competitor encroachment. Prioritize backward integration into replacement parts manufacturing to replicate MEC Outdoors' aftermarket revenue insulation. Lock in distributor exclusivity for firmware-update-enabled units to prevent third-party service unbundling from eroding recurring revenue streams. For New Entrants and Emerging Players: Direct-to-consumer e-commerce channels bypass established wholesale relationships and enable portable thrower penetration of Texas and Florida private land segments. Target battery-powered individual ownership as the most penetrable white space, where formal range infrastructure gaps create unmet training demand. Pursue white-label assembly partnerships with Maharashtra-based motor suppliers to compress landed costs for South Asian club procurement. For Investors and Strategic Acquirers: Roll-up economics work for regional distributor networks because fragmented southern United States wholesale holdings face inventory obsolescence pressure and will transact at compressed multiples. Long-term viability hinges on firmware-capable thrower installed base expansion rather than mechanical unit volume. Watch ATF facility licensing velocity as the key inflection signal; accelerated permit timelines would unlock commercial range equipment procurement backlogs.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Subscription Launch | Annual software licenses monetize trajectory randomization algorithms beyond hardware sales cycles. |
| Certified Technician Network Expansion | Service hub density in secondary markets removes adoption constraints for electronic thrower deployments. |
| Indian PLI Module Assembly | Domestic electronic control production under India's incentive framework reduces landed costs for South Asian clubs. |
| Replacement Parts Vertical Integration | In-house manufacturing of high-wear components replicates MEC Outdoors' aftermarket revenue insulation. |
| Portable Battery-Powered Product Line | Collapsible frame designs penetrate Texas and Florida recreational shooter segments on private acreage. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with range operators, shooting club procurement managers, aftermarket service technicians, and collegiate athletics equipment directors alongside secondary validation through ATF facility licensing databases, NCAA equipment standard documentation, and REACH compliance certification records. Bottom-up triangulation against top-down trade flow estimates anchored volume and value outputs.
Segment-weighting across product type, end-user facility category, technology architecture, and geographic shooting corridor density shaped the analytical framework. CAGRs were derived from installed base replacement cycle analysis and collegiate program expansion trajectories. Firmware subscription attach rates and certified technician network growth curves served as industry-specific forecast inputs across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for mechanical-to-electronic thrower transition would alter the outlook. Forecasts reflect assumptions regarding ATF licensing velocity, steel price stability, and Indian PLI scheme continuity. Regulatory material mandate acceleration or technician training program expansion represent revision triggers. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Global Mountain Bicycles Market
Sports Equipment
US Sports Flooring Market
Sports Equipment
Kick Scooter Tire Market
Sports Equipment
Sports Mouthguard Market
Sports Equipment
Global Bicycle Market
Sports Equipment
Golf Club Market
Sports Equipment
Carbon-Fiber Badminton Racquet Market
Sports Equipment
Ladderball Market
Sports Equipment
Shuffleboard Equipment Market
Sports Equipment
Waist Support Belt Market
Sports Equipment
Bicycle Drivetrain Cassette Market
Sports Equipment
Boxing Equipment Market
Sports Equipment
Smart Swim Goggles Market
Sports Equipment
Dance Equipment Market
Sports Equipment
Ice Hockey Equipment Market
Sports Equipment
Sports Protection Equipment Market