
 Kiteboarding Equipment Market | 2026-2036
Kiteboarding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Kiteboarding Equipment Market Outlook
Aftermarket service revenue from kite refurbishment, line replacement, and bladder repair is rewriting how manufacturers capture lifetime customer value. Duotone leverages its global dealer network to control post-sale maintenance flows, while Naish International anchors its brand equity through school partnership programs that lock in repeat equipment purchases. Cabrinha competes by extending proprietary valve and pump systems that complicate third-party servicing.
Kiteboarding equipment encompasses traction kites, directional and twin-tip boards, harnesses, and control systems engineered from ripstop nylon canopies, inflated leading-edge bladders, and composite or wood-core laminates with fins and foot straps, designed to harness wind power for propulsion across water surfaces. Kites and boards dominate product-type revenue, though foil technology is displacing traditional inflatable designs among advanced riders seeking reduced drag and broader wind-range utility. The amateur end-user segment sustains volume, while competitive and rental applications concentrate margin pools through premium-specification procurement cycles.
REACH compliance in Europe restricts certain polymer plasticizers in kite bladder construction, compelling reformulation of PVC and TPU compounds, while the F-Gas Regulation phases out greenhouse-gas-intensive blowing agents used in board core production. ISO standards for water-sports equipment safety shape product certification requirements across export markets, with national regulators in Brazil and the United States adopting variant testing protocols that fragment conformity costs. Stakeholders must monitor how evolving chemical restrictions cascade through material supply chains and whether foil technology penetration accelerates equipment replacement rates beyond traditional product lifecycles.
Market Dynamics
Foil technology penetration is restructuring competitive positioning across kiteboarding equipment categories, compressing replacement cycles for inflatable kites while expanding addressable wind-range utility for advanced riders and rental operators.
Growth Catalysts
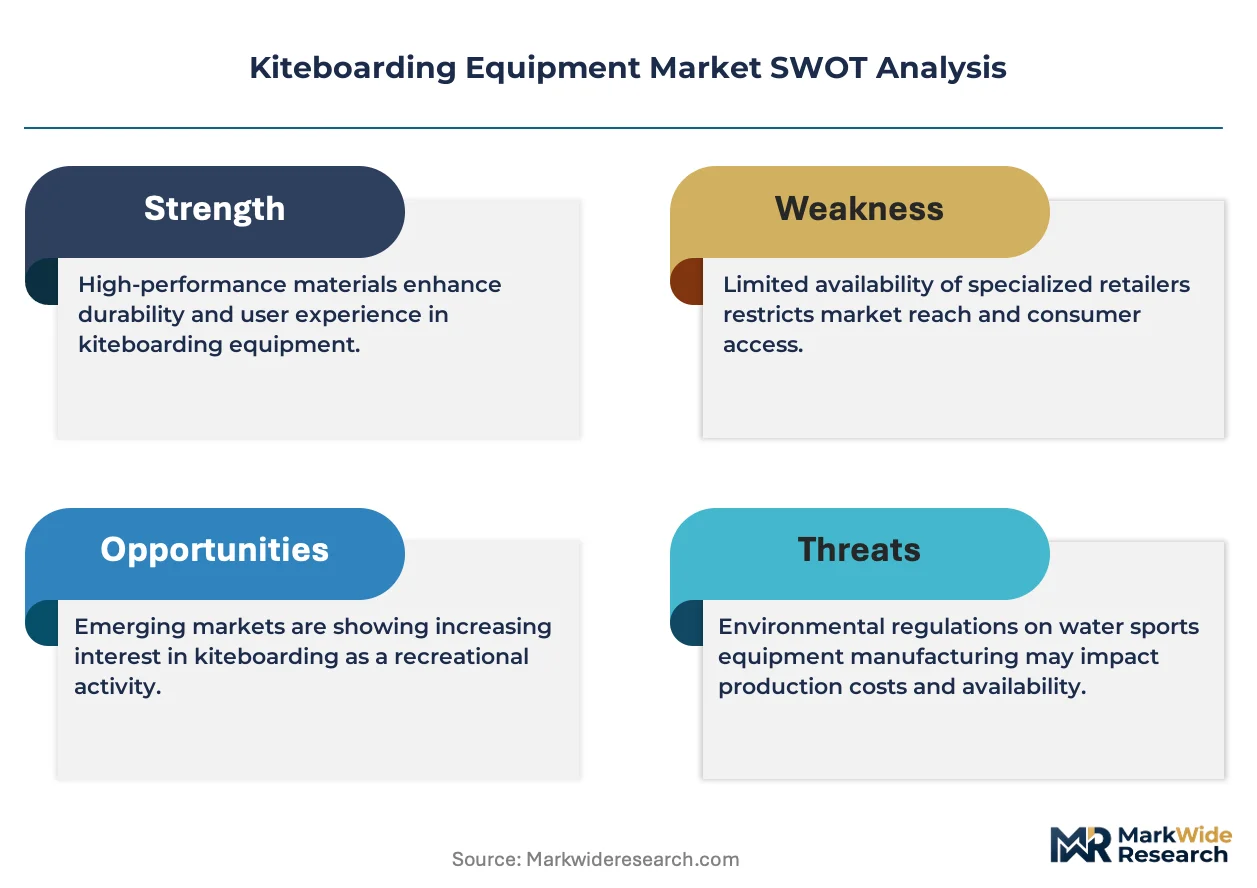
- EU F-Gas Regulation:The phase-out of greenhouse-gas-intensive blowing agents in board core production is accelerating reformulation toward bio-based polyurethane foams, creating first-mover advantages for manufacturers with compliant supply chains.
- Recreational coastal tourism:Adventure sports integration into mainstream hospitality offerings in Brazil, Portugal, and Morocco is expanding equipment procurement from hotel groups and resort operators seeking turnkey activity packages.
- Aluula composite fabric:Ultra-lightweight canopy materials are extending kite lifespan and performance envelopes, justifying premium positioning among competitive riders and driving technology licensing demand.
Market Restraints
- REACH chemical compliance:Restricted polymer plasticizers in PVC and TPU bladder compounds are forcing material reformulation that elevates unit costs and fragments supplier qualification pools across European markets.
- Wind condition dependency:Geographic concentration of viable kiteboarding locations in coastal zones with consistent trade winds limits addressable market expansion to inland or variable-wind regions.
- Seasonal demand compression:Northern hemisphere winter troughs create inventory carrying cost burdens and cash flow volatility for distributors without southern hemisphere counterbalancing.
Strategic Opportunities
- Egypt Red Sea corridor:Underdeveloped rental infrastructure along Hurghada and El Gouna coastlines presents white-space expansion for school-network operators seeking year-round warm-water destinations.
- ISO 21853 safety certification:Emerging harmonization of water-sports equipment testing protocols is creating regulatory tailwinds for manufacturers with pre-certified product lines to accelerate export market entry.
- Modular foil systems:Interchangeable mast and wing configurations are enabling cross-platform compatibility that reduces customer switching costs and expands aftermarket attachment revenue streams.
Industry Challenges
- Composite technician scarcity:Specialized lamination and finishing skills for carbon fiber mast production are concentrated in marine and aerospace supply chains, creating recruitment friction for board manufacturers scaling foil programs.
- Multi-jurisdiction certification timelines:Divergent testing protocols between ANVISA in Brazil and state-level consumer safety regulators in the United States extend product launch cycles and duplicate conformity assessment expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kiteboarding Equipment Market |
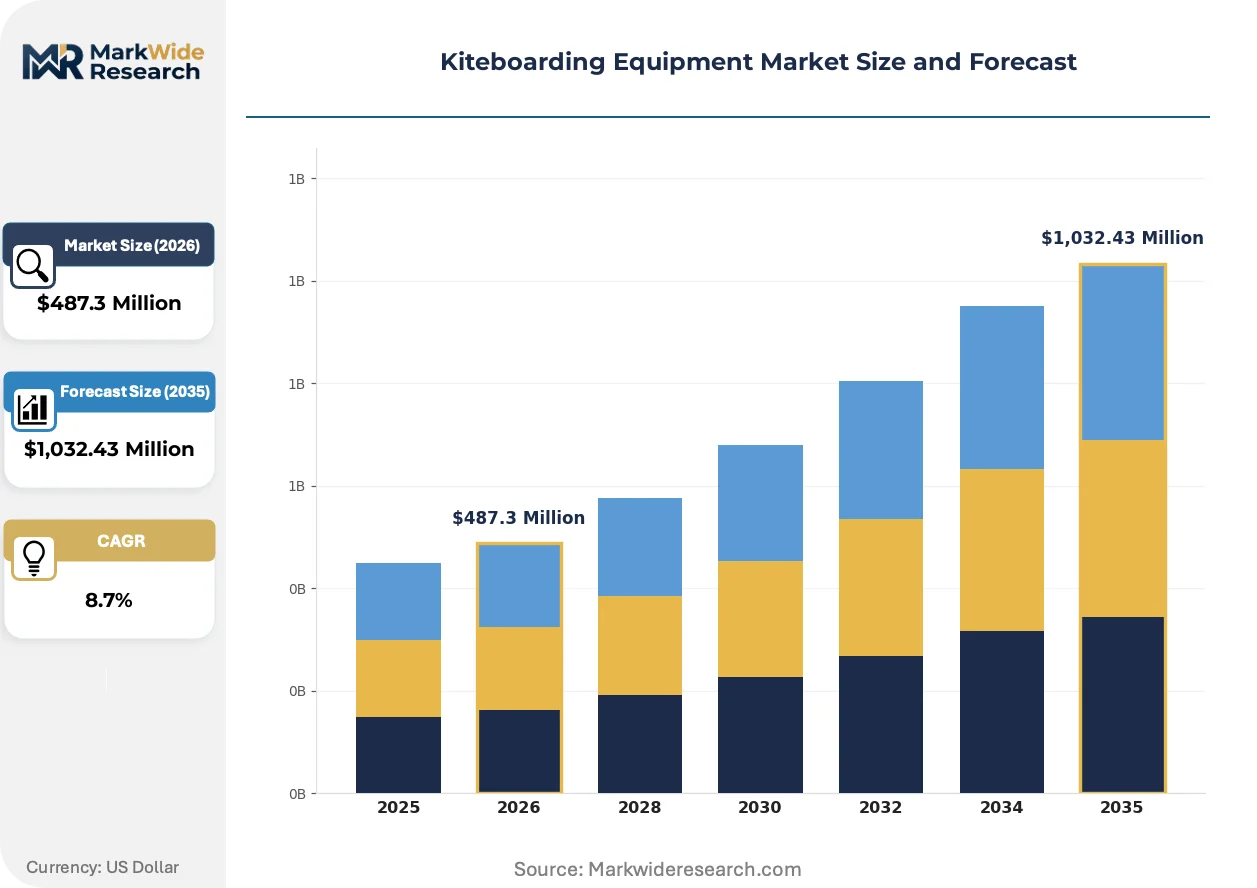
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kites, Boards, Harnesses, Accessories Technology: Inflatable, C-Shape, Hybrid, Foil Application: Recreational, Competitive, Rental, Training End User: Amateurs, Professionals, Schools, Rentals |
| Companies Covered | Duotone, Slingshot Sports, Naish International, F-One, Cabrinha, North Actionsports, Boards and More, Core Kiteboarding, Airush Kiteboarding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kiteboarding Equipment Market Strategic Shifts
Active sensor integration and predictive maintenance algorithms are digitizing how riders interact with equipment and how manufacturers capture post-sale value. Three concurrent developments are reshaping product architecture and go-to-market models.
Embedded load-cell sensors in control bars and harness spreader bars are digitizing real-time force measurement and performance analytics. Rental operators and schools in Ceará and Tarifa are adopting these systems to quantify rider progression and justify equipment upgrade recommendations. The data infrastructure is digitizing subscription-based service models that lock in recurring revenue beyond initial hardware sales.
ECHA enforcement of REACH substance restrictions is compelling bladder manufacturers to validate alternative plasticizer chemistries through extended migration and fatigue testing. Industrial consequence includes elongated new product introduction timelines and elevated R&D overhead for European market access. Board core producers are responding by consolidating blowing agent supply relationships with specialty chemical houses possessing validated sustainable alternatives.
Direct-to-consumer configuration platforms are fragmenting traditional dealer-distributor hierarchies. Advanced riders in Germany and the Netherlands are specifying custom canopy colorways, line lengths, and board dimensions through manufacturer websites, bypassing retail markup layers. This channel compression is most visible in premium foil board categories where technical specification complexity previously required intermediated consultation.
Kiteboarding Equipment Market Segmentation
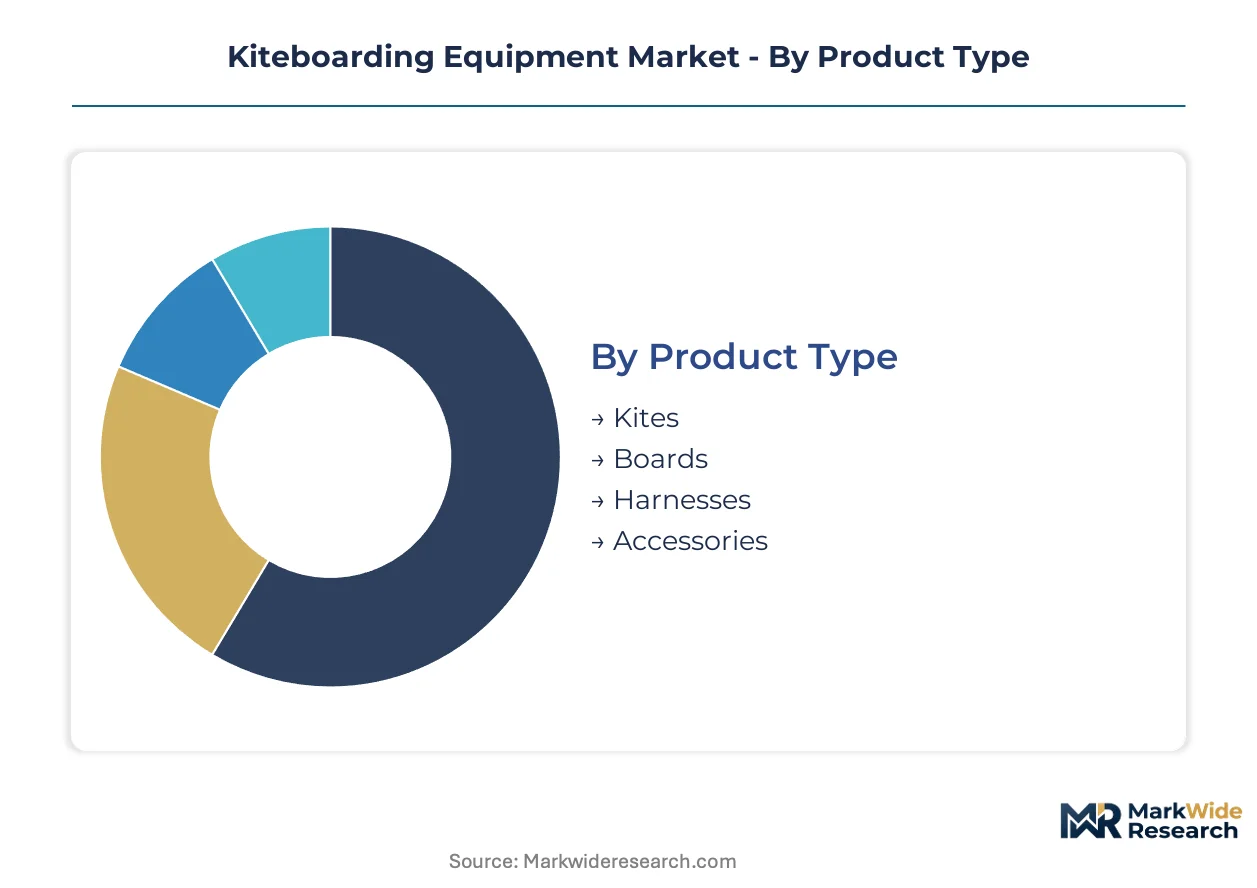
Segmentation in kiteboarding equipment reveals divergent replacement rhythms and margin architectures across product categories. Understanding these patterns exposes where manufacturers must defend installed base versus capture expansion.
Product Type:
Replacement cycles vary dramatically: kites turn over every 2-3 seasons from canopy fatigue, boards persist 5-7 years, while harnesses and accessories occupy intermediate positions.
- Kites:Ripstop nylon canopies with inflated leading-edge bladders deliver propulsion power through wind capture. Demand clusters in Brazil's Ceará corridor where year-round school operations consume high volumes for rental fleet rotation and student progression models.
- Boards:Composite or wood-core laminates with fins and foot straps provide the riding platform. Replacement concentrates among foil adopters in Germany and the Netherlands where advanced riders upgrade to reduced-drag designs, compressing traditional inflatable kite replacement timelines.
- Harnesses:Spreader bar systems distribute kite pull across rider torso. Schools in Portugal specify quick-release configurations for safety certification compliance.
- Accessories:Control bars, lines, pumps, and repair kits complete equipment packages. Line replacement drives recurring aftermarket revenue.
Kites dominate installed base. Boards are where expansion concentrates.
Technology:
Cost tiers separate mass-market inflatable designs from premium foil systems commanding 3-4x unit pricing and specialized maintenance infrastructure.
- Inflatable:Leading-edge bladder architecture with strut inflation dominates rental fleets and school instruction. ANVISA certification requirements in Brazil favor established inflatable designs with validated safety testing.
- Foil:Carbon fiber mast and wing configurations eliminate hydrodynamic drag for advanced wind-range utility. Adoption concentrates among competitive riders and high-end rental operators in Tarifa seeking premium positioning.
- C-Shape:Traditional arc geometry without bridles delivers direct steering response. Niche demand persists among legacy riders.
- Hybrid:Bridled canopy designs blend depower range with stability. Schools favor hybrids for student progression programs.
Inflatable technology anchors volume. Foil systems are climbing the fastest.
Application:
Volume flows through recreational channels while margin pools concentrate in competitive procurement and rental fleet specifications.
- Recreational:Individual ownership for weekend and vacation riding. Brazil's coastal tourism integration drives equipment bundling with hospitality packages.
- Competitive:Premium-specification gear for Big Air, Freestyle, and Racing disciplines. ISO 21853 safety certification shapes equipment selection for sanctioned events.
- Rental:Fleet procurement by schools and resort operators for hourly or daily use. High-turnover environments prioritize durability and standardized maintenance protocols.
- Training:Beginner-specific equipment with enhanced depower and relaunch characteristics. Schools in Morocco's Dakhla corridor expand training infrastructure.
Recreational application sustains volume base. Rental is where margin expansion concentrates.
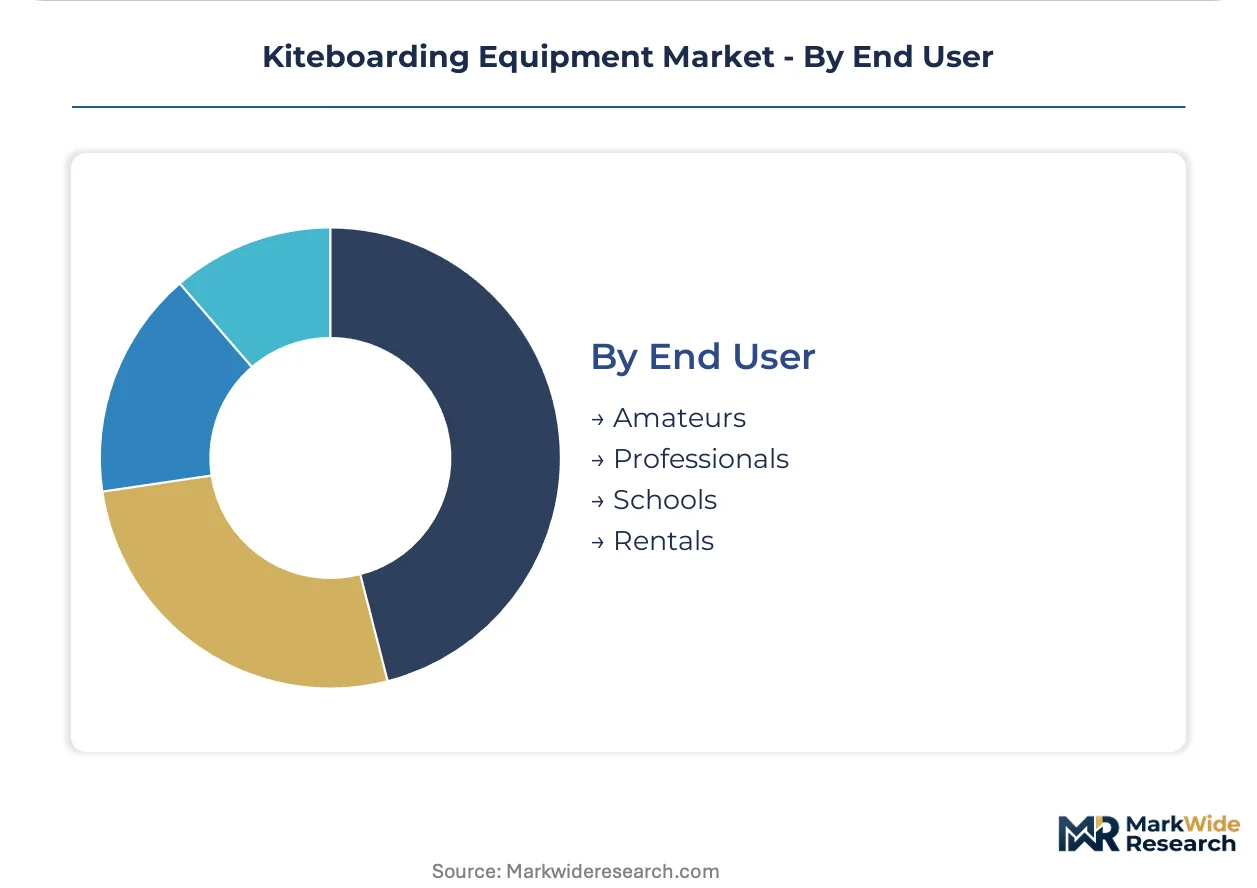
End User:
Customer type determines pricing architecture and service attachment models across the equipment lifecycle.
- Amateurs:Weekend riders and vacation enthusiasts purchasing entry-to-mid-tier equipment. Direct-to-consumer configuration platforms in Germany enable custom specification bypassing retail markup.
- Professionals:Sponsored athletes and instructors requiring maximum performance envelopes. Aluula composite fabric adoption justifies premium positioning.
- Schools:Instructional businesses procuring durable fleet equipment with volume discounts. REACH-compliant bladder materials are mandatory for European school networks.
- Rentals:Commercial operators balancing acquisition cost against maintenance burden and theft risk. Embedded sensor systems enable usage-based pricing models.
Amateurs dominate unit volume. Schools represent the steepest expansion trajectory for recurring procurement contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil consumes kiteboarding equipment through rental fleet rotation and school procurement cycles, while Germany and the Netherlands favor direct-to-consumer premium foil configurations that bypass traditional retail channels entirely.
Brazil
Ceará's coastline sustains year-round school operations with steady trade winds driving equipment turnover every 2-3 seasons. ANVISA certification requirements favor established inflatable designs with validated safety testing. Fortaleza and Jericoacoara anchor rental infrastructure expansion as coastal tourism operators bundle equipment into hospitality packages.
Germany
Advanced riders in Hamburg and the Baltic coast specify custom canopy configurations through manufacturer websites, fragmenting dealer-distributor hierarchies. ECHA enforcement of REACH substance restrictions compels bladder manufacturers to validate alternative plasticizer chemistries. The North Sea and inland lake clusters concentrate foil adoption among competitive riders seeking reduced-drag designs.
Netherlands
Tarifa-facing Dutch riders and IJsselmeer-based schools drive premium equipment procurement with quick-release harness specifications for safety certification compliance. The country's national consumer safety regulator aligns with ISO 21853 water-sports equipment standards. Rotterdam and Amsterdam serve as distribution hubs for northwest European school networks.
Portugal
Algarve and Lisbon coastal tourism integration expands equipment bundling with resort activity packages. EU F-Gas Regulation phase-out of greenhouse-gas-intensive blowing agents accelerates reformulation toward bio-based polyurethane foams in board core production. Peniche and Guincho concentrate school infrastructure with year-round Atlantic wind exposure.
Egypt
Underdeveloped rental infrastructure along the Red Sea corridor presents white-space expansion for school-network operators. The country's national tourism investment programs target Hurghada and El Gouna for adventure sports infrastructure development. Warm-water conditions enable year-round operations that counterbalance northern hemisphere seasonal demand compression.
Kiteboarding Equipment Market Competitive Environment
Capability concentration sits with composite fabric specialists and valve-system engineers; scale advantage sits with global distribution networks controlling school partnership flows. The vendor base spans three tiers: heritage windsurfing brands extending into kiteboarding, pure-play kite specialists, and watersports conglomerates with multi-brand portfolios. Dominant competitive moves include school-network exclusivity contracts that lock in recurring fleet procurement, and proprietary valve and pump architectures that complicate third-party servicing.
Within the heritage brand tier, Duotone and Naish International exemplify divergent post-sale value capture strategies. Duotone leverages dealer network control over maintenance flows, while Naish anchors brand equity through instructional partnership programs. Cabrinha occupies a position on the proprietary-systems vector, extending valve architectures that fragment aftermarket service access. These three represent how competitive positioning in kiteboarding equipment increasingly depends on lifetime customer value mechanics rather than initial hardware margins alone.
| Leading Market Players |
|---|
| Duotone |
| Slingshot Sports |
| Naish International |
| F-One |
| Cabrinha |
| North Actionsports |
| Boards and More |
| Core Kiteboarding |
| Airush Kiteboarding |
| Others |
Value Chain & Pricing Dynamics
Carbon fiber mast production concentrates in China and Taiwan, tethering premium foil board pricing to aerospace and marine composite supply chains that command 40-60% of finished goods value. This upstream concentration funnels margin capture toward lamination specialists with qualified technician pools, while inflatable kite manufacturers compete on volume scale and bladder material compliance costs.
Pricing Analysis
Long-term offtake contracts between school networks and manufacturers dominate fleet procurement, insulating volume buyers from spot market volatility in canopy fabrics. Three-tier pricing structure across premium, standard, and economy levels separates Aluula composite kites from ripstop nylon designs from PVC bladder entry models. Cost compression in standard-tier inflatable kites is intensifying because REACH-compliant TPU reformulation elevates raw material overhead. Rental operators exhibit lowest price sensitivity due to usage-based revenue models, while individual amateurs in Germany and the Netherlands migrate toward direct-to-consumer configuration platforms to bypass retail markup.
Supply Chain Analysis
Tariff exposure between China and the United States dominates risk calculus for carbon fiber mast and wing imports, compelling manufacturers to qualify secondary suppliers in South Korea and Japan. Ripstop nylon canopies draw from textile mills in China and Vietnam, while bladder PVC and TPU compounds source from German and Belgian specialty chemical houses. Single-source vulnerability concentrates in aerospace-certified carbon fiber prepreg grades. Distribution runs through dealer networks for school partnerships and direct-to-consumer platforms for advanced rider segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment interoperability is emerging as the platform-economics inflection, with modular foil systems and standardized valve architectures creating ecosystem lock-in effects that reshape competitive moats beyond individual product generations.
For Market Incumbents: Harden school-network exclusivity contracts against modular foil entrants by embedding proprietary sensor infrastructure that fragments data portability. Anchor supply security through backward integration into REACH-compliant TPU compounding or captive carbon fiber lamination capacity in Portugal. Foil technology substitution threatens inflatable kite replacement cycles; defend through accelerated hybrid product pipelines. For New Entrants and Emerging Players: Egypt's Red Sea corridor offers underdeveloped rental infrastructure with warm-water year-round operations that counterbalance northern hemisphere seasonality. Target school-network white space in Hurghada and El Gouna with turnkey fleet procurement packages bundling equipment, maintenance, and instructor certification. Pursue ISO 21853 pre-certification to accelerate export market entry against incumbent compliance timelines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed watersports conglomerates holding multi-brand portfolios but lacking foil technology integration. Five-to-ten year viability hinges on conversion from transactional hardware sales to subscription-based service models with embedded sensor revenue. Monitor Aluula fabric licensing adoption rates as inflection signal for premium tier margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Foil System Development | Interchangeable mast and wing configurations reduce customer switching costs and expand aftermarket attachment revenue across school networks. |
| REACH-Compliant Material Reformulation | Alternative plasticizer validation through ECHA-mandated testing secures European market access and qualifies suppliers for school procurement contracts. |
| Embedded Sensor Integration | Load-cell systems in control bars digitize usage analytics and enable subscription-based service models for rental operators in Brazil and Tarifa. |
| Direct-to-Consumer Platform Launch | Configuration tools bypass dealer markups and capture premium foil demand from advanced riders in Germany and the Netherlands. |
| School Network Partnership Expansion | Exclusivity contracts in Ceará and Dakhla lock in recurring fleet procurement and standardize maintenance protocol adoption. |
Study Parameters
A spread of perspectives from kite school operators, composite manufacturing engineers, regulatory compliance officers, and hospitality procurement managers converged on the working assumptions. Primary fieldwork encompassed equipment distributors in Brazil, Germany, and Portugal alongside bladder material suppliers navigating ECHA enforcement. Secondary validation drew from ANVISA certification databases, EU F-Gas Regulation implementation reports, customs trade records for carbon fiber composites, and ISO 21853 safety standard documentation. Bottom-up demand modeling across end-user segments triangulated against top-down manufacturer production capacity assessments.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions encompassed product type, technology tier, application mode, and end-user category with regional regulatory cluster overlays. CAGRs derived from replacement cycle analysis, school fleet expansion trajectories, and foil technology penetration curves. Industry-specific inputs included wind condition seasonality patterns, REACH compliance cost pass-through elasticities, and coastal tourism integration rates.
Practitioners should monitor ECHA substance restriction expansions, ANVISA testing protocol revisions, and Aluula fabric licensing adoption for early signals that would necessitate forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Equestrian Equipment Market
Sports Equipment
Football Market
Sports Equipment
Sandbells Market
Sports Equipment
Winter Sporting Goods Market
Sports Equipment
Surfing Equipment Market
Sports Equipment
Gym Shoes Market
Sports Equipment
Global Mountain Bicycles Market
Sports Equipment
Sports Protective Equipment Market
Sports Equipment
Gymnastic Bars Market
Sports Equipment
Global Sports Sunglasses Market
Sports Equipment
Padel Balls Market
Sports Equipment
Smart Boxing Gear Market
Sports Equipment
Trail Shoes Market
Sports Equipment
Global Horse Riding Equipment Market
Sports Equipment
Golf Club Grips Market
Sports Equipment
Europe Winter Sports Equipment Market