
 Gymnastic Hoops Market | 2026-2036
Gymnastic Hoops Market Size, Share, and Industry Trends Forecast 2026-2036
Gymnastic Hoops Market Analytics
The split between premium competition-grade hoops and mass-market training equipment is realigning procurement patterns across the industry. Venturelli leverages its Italian manufacturing heritage to dominate European competitive apparatus supply. TheSpinsterz anchors North American demand through specialized rhythmic gymnastics equipment. Sport System S.r.l. competes on technical certification depth for federation-approved competition hoops.
Gymnastic hoops are circular apparatus engineered from polypropylene, aluminum, or rubber composites, typically ranging from 70 to 90 centimeters in diameter and designed for rhythmic gymnastics training, artistic gymnastics conditioning, or fitness exercise routines. Competition hoops demand precision-molded construction with exact weight tolerances, while weighted training variants serve strength-building protocols for gymnasts and coaches. Plastic and metal materials command the structural core of the market, with foam-covered options expanding among recreational users and youth programs seeking impact-absorbing surfaces.
ISO gymnastics equipment standards, FIG apparatus norms, and national federation certification requirements shape product design cycles and market access barriers across producing regions. European manufacturers navigate REACH material compliance and CE marking obligations, while US suppliers align with USA Gymnastics equipment specifications. Stakeholders must monitor evolving federation material bans and sustainability mandates that could redirect material sourcing decisions before the next competitive equipment refresh cycle.
Market Dynamics
ISO gymnastics equipment standards and FIG apparatus norms are compressing product development cycles while elevating material certification requirements across all supply tiers. Manufacturers must now synchronize R&D timelines with federation equipment refresh schedules.
Growth Catalysts
- NCAA Equipment Procurement:Collegiate gymnastics programs in the United States sustain bulk orders for competition-grade apparatus, creating predictable demand pipelines for certified manufacturers.
- REACH Material Compliance:European chemical safety regulations are accelerating substitution of legacy plasticizers with bio-based polypropylene formulations in hoop construction.
- Rhythmic Gymnastics Expansion:Youth academy enrollment in Eastern European training centers is driving replacement cycles for standardized 85-centimeter competition hoops.
Market Restraints
- Aluminum Price Volatility:Raw material cost swings for aircraft-grade aluminum alloys constrain margin stability for precision-molded competition hoop producers.
- Italian Manufacturing Concentration:Competitive apparatus supply clusters in Northern Italy create geographic single-point vulnerability for European federation procurement.
- Foam Composite Durability Limits:Impact-absorbing surface materials degrade faster than bare polypropylene, shortening replacement intervals for recreational youth programs.
Strategic Opportunities
- Indian Training Infrastructure:Underdeveloped rhythmic gymnastics coaching networks in Maharashtra and Karnataka present first-mover expansion potential for equipment distributors.
- USA Gymnastics Safety Mandates:Updated equipment specifications for impact absorption create compliance-driven upgrade windows for domestic training facilities.
- Direct-to-Academy E-commerce:Specialized online portals bypass traditional sporting goods distributors, capturing margin from elite training centers with predictable reorder patterns.
Industry Challenges
- Federation Certification Lag:FIG apparatus approval timelines extend 18-24 months, freezing product launch schedules and straining working capital for specialized manufacturers.
- Legacy Inventory Obsolescence:Rapid material standard evolution strands pre-certified hoop stock when federation bans target specific polymer compositions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gymnastic Hoops Market |
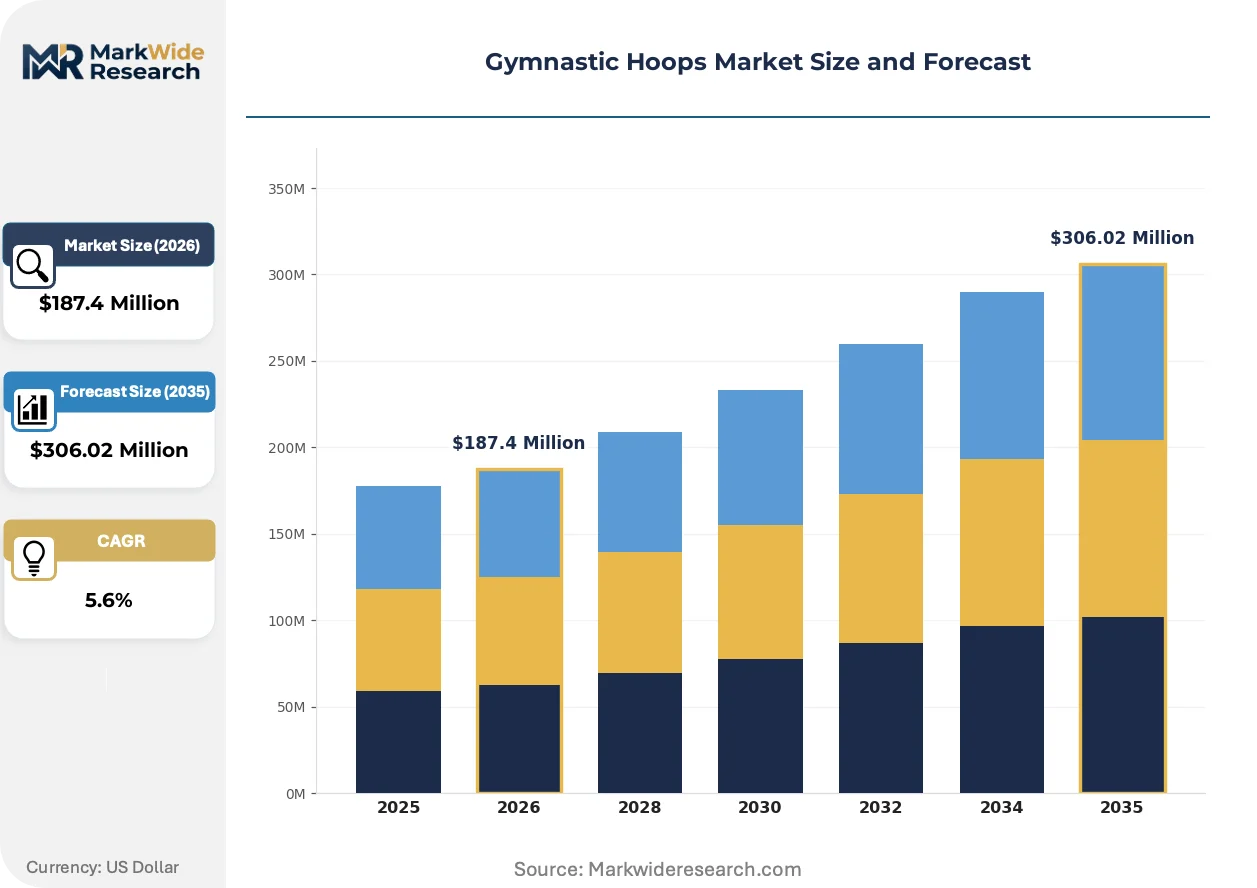
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $306.02 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Training Hoops, Competition Hoops, Weighted Hoops, Inflatable Hoops Material: Plastic, Metal, Rubber, Foam End User: Gymnasts, Fitness Enthusiasts, Coaches, Recreational Users Distribution Channel: Online Retail, Specialty Stores, Sporting Goods Shops, Direct Sales |
| Companies Covered | Venturelli, Nishohi, TheSpinsterz, Sport System S.r.l., Gisco Sport, Diutengsom, K.R. Industries, Pernatete, GOKISPORT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gymnastic Hoops Market Evolving Landscape
Material science advances and federation digitization initiatives are converging to transform how gymnastic hoops are specified, certified, and deployed across training and competitive environments. Three developments merit particular attention.
Smart sensor-embedded hoop prototypes from German engineering labs are rewriting performance analytics capabilities for elite rhythmic gymnastics training. National team coaching staffs in Stuttgart and Berlin pilot these devices to capture real-time rotational velocity and grip pressure data. The technology is compressing the feedback loop between athlete execution and biomechanical adjustment, potentially displacing video-only analysis protocols.
REACH substance restriction updates from ECHA are mandating phase-out of certain phthalate plasticizers in apparatus contact surfaces by 2027. European manufacturers face reformulation deadlines that overlap with FIG equipment certification windows. Italian and French suppliers are accelerating bio-polymer R&D to maintain CE marking eligibility without disrupting federation approval timelines.
Academy procurement officers now specify outcome-based equipment lifecycle contracts rather than discrete purchase orders. Performance guarantees covering durability, weight tolerance retention, and injury incident rates define vendor selection at elite US training centers. Texas and California gymnastics institutes lead this contractual evolution, unbundling traditional capital expenditure into operational service agreements.
Gymnastic Hoops Market Segmentation
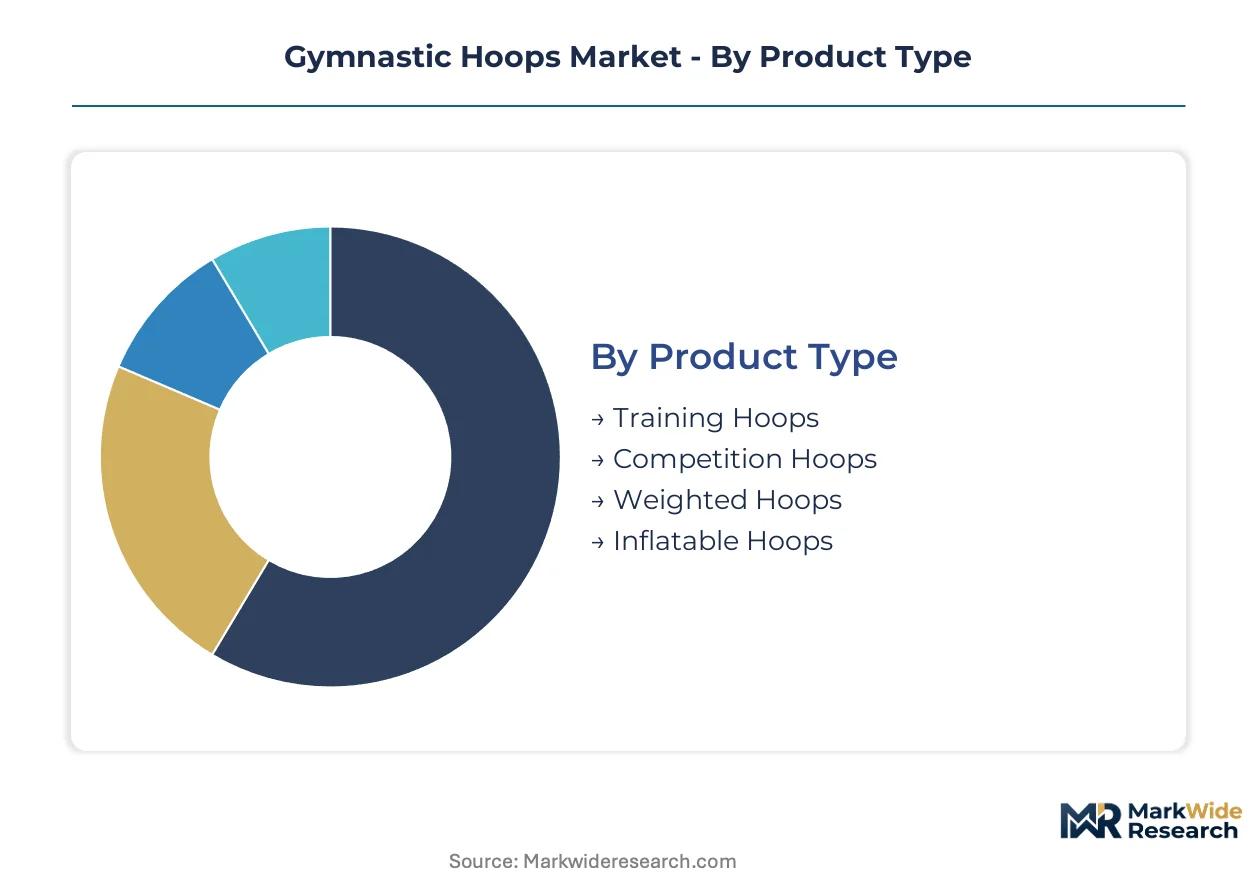
Procurement patterns for gymnastic hoops diverge sharply between elite training facilities demanding FIG-certified apparatus and mass-market consumers prioritizing cost accessibility. Material certification requirements and distribution economics create distinct competitive arenas that manufacturers must navigate simultaneously.
Product Type:
Volume concentration separates institutional buyers with predictable replacement cycles from discretionary purchasers driving seasonal demand spikes.
- Training Hoops:Polypropylene or aluminum construction with standardized 80-85 centimeter diameters serves daily practice regimens at NCAA programs and Eastern European academies. Texas and California training centers sustain bulk procurement through multi-year equipment refresh contracts.
- Competition Hoops:Precision-molded apparatus meeting exact weight tolerances and FIG apparatus norms for federation-sanctioned events. Italian manufacturers dominate supply to European championships and World Cup circuits through technical certification depth.
- Weighted Hoops:Resistance training variants for strength-building protocols in artistic gymnastics conditioning programs.
- Inflatable Hoops:Portable recreational formats targeting youth fitness programs and physical education curricula.
Training hoops lead volumes today; competition hoops are gaining share fastest through federation standardization mandates.
Material:
REACH compliance deadlines and FIG material bans are compressing sourcing decisions across all supply tiers.
- Plastic:Polypropylene formulations dominate mass-market production, though ECHA phthalate restrictions are forcing bio-based polymer transitions before 2027. European manufacturers face overlapping reformulation and recertification timelines.
- Metal:Aircraft-grade aluminum alloys deliver the structural integrity required for competition apparatus. Price volatility in raw aluminum markets constrains margin stability for precision-molded hoop producers in Northern Italy.
- Rubber:Composite formulations for impact-absorbing surfaces in recreational and youth program equipment.
- Foam:Covering materials degrade faster than bare substrates, shortening replacement intervals for school and community center programs.
Plastic maintains volume leadership; metal is expanding most quickly through competitive apparatus upgrades.
End User:
Skill-level stratification determines equipment specification complexity and price elasticity across buyer categories.
- Gymnasts:Elite and aspiring competitive athletes requiring FIG-certified hoops with documented weight tolerance retention. Stuttgart and Berlin national team facilities pilot smart sensor-embedded prototypes for biomechanical analytics.
- Coaches:Academy directors specifying outcome-based lifecycle contracts with performance guarantees covering durability and injury incident rates.
- Fitness Enthusiasts:Adult recreational users purchasing through online retail channels for home exercise routines.
- Recreational Users:Youth and casual participants in school programs and community centers prioritizing impact-absorbing surfaces.
Gymnasts drive premium segment value; coaches are shifting procurement fastest toward service-based contracts.
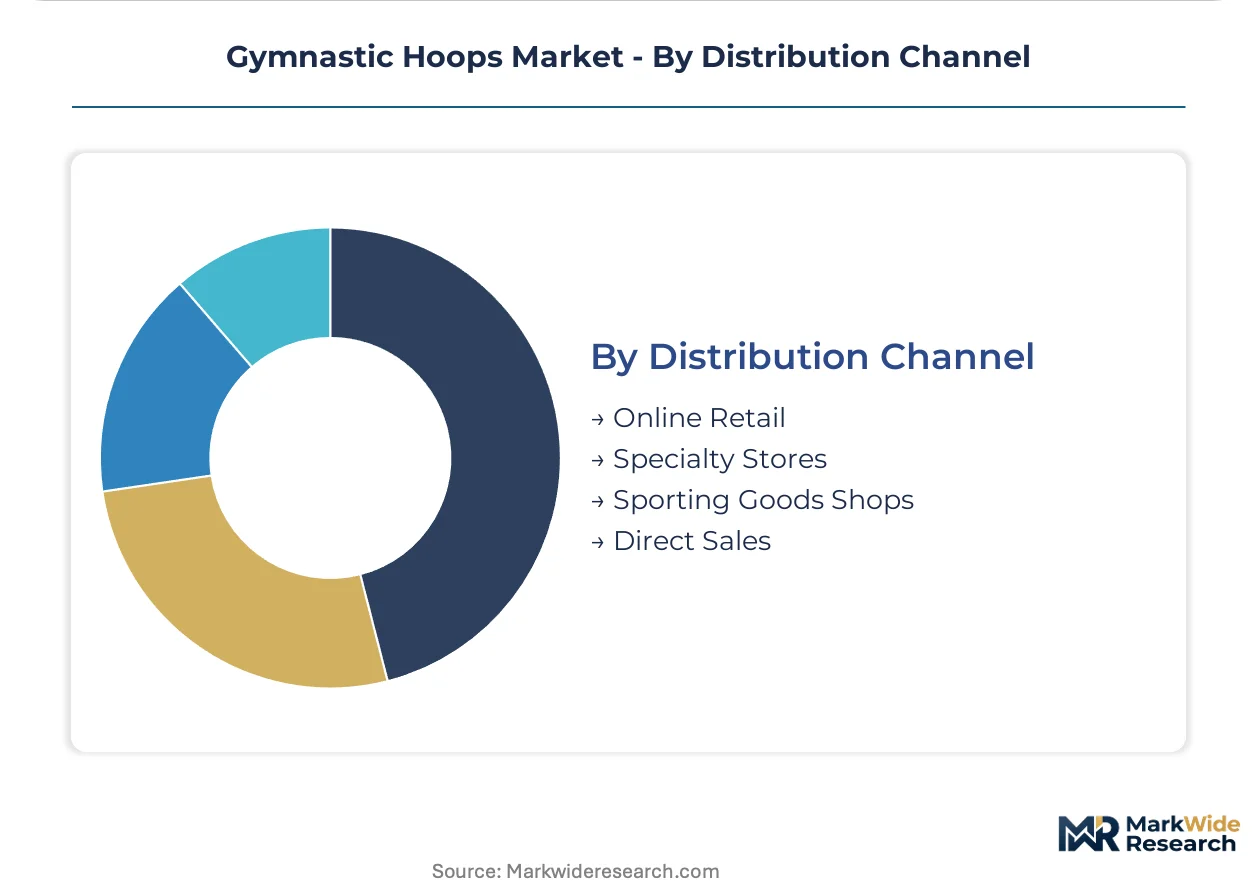
Distribution Channel:
Margin capture and customer relationship depth vary dramatically across channel structures.
- Online Retail:E-commerce portals serving fitness enthusiasts and recreational users with standardized product configurations. Direct-to-academy platforms are bypassing traditional sporting goods distributors for elite training center reorders.
- Specialty Stores:Rhythmic gymnastics equipment retailers providing technical consultation and fitting services. TheSpinsterz anchors North American demand through specialized inventory depth.
- Sporting Goods Shops:Generalist retailers carrying mass-market training and fitness variants for casual consumers.
- Direct Sales:Manufacturer relationships with NCAA programs and federation procurement officers for competition-grade apparatus.
Online retail holds volume dominance; direct sales is climbing the fastest as academy procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Elite coaching talent concentrates in Northern Italy, Stuttgart, and Texas, anchoring equipment procurement gravity for competition-grade apparatus. These workforce clusters synchronize with federation certification timelines and academy refresh cycles. Geographic proximity to FIG headquarters in Lausanne tightens compliance coordination for European manufacturers.
United States
NCAA gymnastics programs in Texas and California sustain bulk orders for FIG-certified hoops through multi-year equipment contracts. USA Gymnastics equipment specifications govern impact absorption mandates for domestic training facilities. Austin and Los Angeles training institutes pilot outcome-based lifecycle procurement with performance guarantees.
Italy
Northern Italian manufacturing clusters supply European championships and World Cup circuits through technical certification depth. REACH substance restrictions from ECHA force bio-polymer transitions in polypropylene formulations by 2027. Venturelli leverages its Italian heritage to dominate competitive apparatus supply from precision-molded production centers near Modena.
Germany
Stuttgart and Berlin national team facilities pilot smart sensor-embedded hoop prototypes for biomechanical analytics. ECHA phthalate restrictions accelerate reformulation deadlines overlapping with FIG certification windows. Bavarian engineering labs develop rotational velocity capture systems for elite rhythmic gymnastics training protocols.
India
Underdeveloped rhythmic gymnastics coaching networks in Maharashtra and Karnataka present first-mover expansion potential for equipment distributors. BIS standards for sporting goods create compliance entry barriers for imported apparatus. Mumbai and Bangalore academy formations drive initial demand for standardized 85-centimeter competition hoops.
Japan
Metropolitan Tokyo and Osaka training centers maintain rigorous FIG apparatus compliance for national team preparation. JIS standards for gymnastics equipment align with international federation norms, streamlining import certification. Japanese manufacturers concentrate on precision aluminum processing for competition-grade structural integrity.
Gymnastic Hoops Market Competitive Landscape
Top-tier vendors anchor federation-certified competition apparatus, while mid-tier specialists capture training equipment demand through technical consultation depth. Italian manufacturers consolidate European competitive supply through geographic proximity to FIG governance. Three archetypes dominate: heritage European precision fabricators, North American specialty distributors, and Asian scale producers. Capacity expansion in bio-polymer formulations and strategic partnerships with academy procurement officers represent the dominant competitive moves.
Within the heritage European tier, Venturelli and Sport System S.r.l. exemplify technical certification depth for federation-approved competition hoops. TheSpinsterz anchors North American demand through specialized rhythmic gymnastics equipment and direct-to-academy distribution channels. These three occupy positions spanning precision manufacturing, regulatory compliance navigation, and specialized retail consolidation.
| Leading Market Players |
|---|
| Venturelli |
| Nishohi |
| TheSpinsterz |
| Sport System S.r.l. |
| Gisco Sport |
| Diutengsom |
| K.R. Industries |
| Pernatete |
| GOKISPORT |
| Others |
Value Network & Pricing Analysis
Bio-polymer reformulation deadlines in European manufacturing are compressing production economics while redrawing supplier tier boundaries between certified federation vendors and mass-market producers. REACH phthalate restrictions force simultaneous R&D investment and certification timeline synchronization, elevating capital requirements for competition-grade hoop suppliers.
Pricing Analysis
The bundled-vs-unbundled service split separates federation-certified competition apparatus from transactional training equipment procurement. Three-tier pricing structure across premium FIG-certified, standard academy-grade, and economy recreational levels reflects certification depth and after-sales performance guarantees. Cost compression in mass-market polypropylene tiers intensifies because of bio-polymer transition investments. Recreational users through online retail channels exhibit highest price sensitivity; NCAA programs and national team facilities demonstrate lowest sensitivity due to outcome-based lifecycle contracting.
Supply Chain Analysis
Workforce availability constraints in Northern Italian precision molding centers and Bavarian engineering clusters tether production capacity to specialized technician pools. Aircraft-grade aluminum sourcing draws from German and Italian metallurgical suppliers; polypropylene resin feeds from European petrochemical complexes. Single-source vulnerability concentrates in Modena-area competition apparatus fabrication. Distribution runs through federation procurement officers for elite tiers and direct-to-academy platforms for institutional reorders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gymnastic hoops market compounds steadily through federation-mandated equipment refresh cycles that institutionalize replacement demand. NCAA programs and national team facilities provide predictable revenue baselines regardless of macroeconomic fluctuation.
For Market Incumbents: To counter aluminum price volatility eroding margin stability, backward integration into precision aluminum processing secures cost control. Certification investment acceleration compresses FIG approval timelines before bio-polymer mandates take full effect.
For New Entrants and Emerging Players: USA Gymnastics equipment specification updates in Texas and California training corridors open a window for compliance-first market entry. Direct-to-academy e-commerce platforms bypass entrenched distributor relationships. White-space concentration in Indian Maharashtra and Karnataka academy formations offers geographic diversification with lower competitive density.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier training equipment specialists lacking federation certification depth. Five-to-ten year viability rests on regulatory compliance navigation capability rather than volume scale. The signal to watch is FIG apparatus approval timeline compression indicating working capital stress among specialized manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Polymer R&D Investment | REACH compliance maintenance preserves CE marking eligibility for Italian and French suppliers. |
| Direct-to-Academy Platform Launch | Margin capture from Texas and California training institutes bypasses traditional sporting goods distributors. |
| Smart Sensor Technology Integration | Stuttgart and Berlin national team pilots validate performance analytics demand for elite rhythmic gymnastics. |
| Indian Distribution Partnership | Maharashtra and Karnataka academy formations create first-mover positioning in underdeveloped coaching networks. |
| Outcome-Based Lifecycle Contracting | Performance guarantees covering durability and injury rates unbundle capital expenditure into operational service agreements. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement covered gymnastics equipment procurement officers at NCAA programs, academy directors in Texas and California, federation certification specialists, Italian precision manufacturing operators, and Bavarian engineering lab researchers. Secondary validation drew from FIG apparatus norm documentation, ECHA REACH substance restriction updates, USA Gymnastics equipment specifications, and customs trade data for aluminum alloy and polypropylene resin movements. Bottom-up equipment shipment analysis and top-down federation budget allocation modeling provided triangulation anchors.
Historical reference periods anchored projection modeling against documented equipment refresh cycles and federation certification timelines. Segmentation dimensions included product type tier, material composition, end-user skill level, and distribution channel structure across the modeling period. CAGR derivation integrated replacement cycle frequency, academy enrollment trends, and regulatory mandate implementation pacing. Industry-specific inputs captured FIG approval timeline duration and bio-polymer formulation transition cost curves.
Revisions become necessary when federation material bans accelerate, aluminum price volatility exceeds historical bands, or smart sensor technology adoption disrupts traditional apparatus specifications. Forecasts reflect documented assumptions about certification timeline stability and REACH compliance deadline adherence. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Winter Sporting Goods Market
Sports Equipment
Surfing Equipment Market
Sports Equipment
Sports Equipment Market
Sports Equipment
Golf Equipment Market
Sports Equipment
Juggling Clubs Market
Sports Equipment
Rowing Oars Market
Sports Equipment
Triathlon Bikes Market
Sports Equipment
Sports Protection Equipment Market
Sports Equipment
Balance Bike Market
Sports Equipment
Sports Mouthguard Market
Sports Equipment
Starting Blocks Market
Sports Equipment
Europe Kickboxing Equipment Market
Sports Equipment
North America Kickboxing Equipment Market
Sports Equipment
Carbon-Fiber Badminton Racquet Market
Sports Equipment
Europe Winter Sports Equipment Market
Sports Equipment
Stadium Seating Market