
 Aprotic Solvents Market | 2026-2036
Aprotic Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
Aprotic Solvents Market Analysis
German chemical producers is restructuring aprotic solvent supply chains to reduce reliance on imported intermediates. BASF SE leverages integrated acetonitrile production at its Ludwigshafen complex to sustain European pharmaceutical demand. Eastman Chemical Company anchors North American supply through specialized dimethylformamide grades for polymer processing. Dow competes on manufacturing scale in tetrahydrofuran, serving electronics and coatings customers across multiple continents.
Aprotic solvents are polar liquids that lack acidic hydrogen atoms, typically exhibiting dielectric constants above 15 and dipole moments exceeding 2.5 Debye, which enables them to dissolve ionic compounds without participating in hydrogen bonding reactions. These properties make them essential for lithium battery electrolyte formulation, pharmaceutical synthesis, and polymer processing where proton transfer would degrade product integrity. Dimethylformamide dominates volume consumption in pharmaceutical active ingredient crystallization, while acetonitrile captures premium pricing in high-performance liquid chromatography applications. Tetrahydrofuran shows the fastest structural expansion as battery manufacturers adopt it for cathode slurry preparation in lithium-ion cell assembly.
EPA standards govern volatile organic compound emissions from aprotic solvent handling in the United States, while REACH registration requirements in Europe mandate toxicological documentation for dimethyl sulfoxide and acetonitrile imports. China's MEE enforces wastewater discharge limits on dimethylformamide producers in the Yangtze River basin, raising compliance costs for regional manufacturers. Stakeholders must monitor how evolving battery safety certifications and pharmaceutical purity standards reshape qualification requirements across solvent grades.
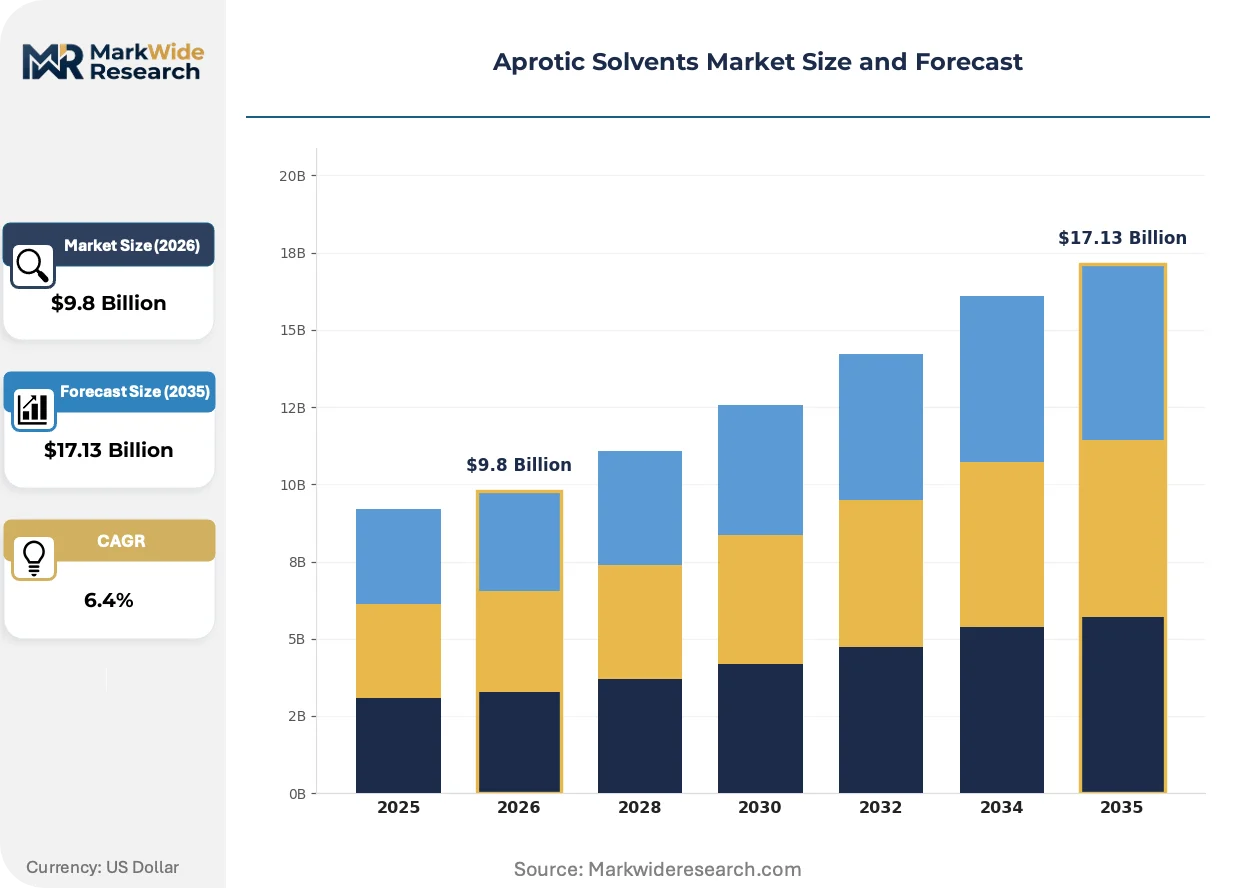
Market Dynamics
Lithium-ion battery electrolyte formulation is concentrating demand for high-purity tetrahydrofuran and dimethyl sulfoxide grades, reshaping capacity allocation across chemical producers and tightening qualification timelines for solvent suppliers.
Growth Catalysts
- Battery Manufacturing Scale-Up:Cathode slurry preparation for lithium-ion cells is absorbing increasing tetrahydrofuran volumes as gigafactory construction accelerates in China, Germany, and the United States.
- REACH Registration Requirements:European pharmaceutical manufacturers are securing long-term acetonitrile supply contracts to satisfy toxicological documentation mandates for active ingredient synthesis.
- Dimethylformamide Capacity Expansion:Domestic Chinese producers are commissioning new plants in the Yangtze River basin to serve regional agrochemical and electronics customers.
Market Restraints
- Acetonitrile Feedstock Concentration:Acrylonitrile production byproduct supply is geographically concentrated, creating vulnerability for chromatography-grade solvent availability.
- EPA Volatile Organic Compound Limits:Emission controls on dimethylformamide handling are raising compliance costs for polymer processors in the United States.
- Green Solvent Substitution:Bio-based alternatives are capturing share in coatings applications where performance specifications permit lower polarity.
Strategic Opportunities
- India Pharmaceutical Manufacturing:CDSCO quality standards are driving demand for imported high-purity solvents as domestic active ingredient production expands.
- Solid-State Battery Electrolyte Development:Hybrid polymer-ceramic systems are creating specifications for ultra-dry tetrahydrofuran that command premium positioning.
- EU Green Deal Chemicals Strategy:Sustainability certification requirements are opening differentiation pathways for producers with verified carbon footprint reductions.
Industry Challenges
- Pharmaceutical Purity Certification Timelines:FDA and EMA qualification protocols for new solvent grades extend 18-24 months, delaying revenue recognition.
- Analytical Chromatography Skill Shortages:Specialized technicians for high-performance liquid chromatography solvent validation are scarce in emerging manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aprotic Solvents Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dimethylformamide, Acetonitrile, Tetrahydrofuran, Dimethyl sulfoxide Application: Pharmaceuticals, Agrochemicals, Electronics, Polymer Production End User: Chemical Industry, Coatings, Battery Manufacturing, Research Laboratories Packaging Type: Drums, IBC Tanks, Bottles, Bulk Containers |
| Companies Covered | BASF SE, Eastman Chemical Company, Dow, INEOS, Arkema SA, Asahi Kasei, Ashland, Celanese Corporation, Mitsubishi Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aprotic Solvents Market Emerging Trajectories
Process intensification and closed-loop solvent recovery systems are redefining operational economics, while regulatory pressure on carbon intensity is accelerating adoption of electrochemical synthesis routes.
Continuous flow reactor technology for dimethylformamide production is overtaking traditional batch processes in new capacity installations. Battery electrolyte manufacturers are specifying flow-synthesized grades for reduced water content and metallic impurity profiles. This shift is compressing capital recovery timelines for integrated producers while marginalizing standalone batch operators.
REACH authorization requirements for substances of very high concern are tightening supply chain documentation for dimethyl sulfoxide imports into Europe. Pharmaceutical compounders are consolidating supplier bases to reduce audit burden and ensure continuity of registration dossiers. German and Swiss chemical distributors are investing in dedicated pharmaceutical-grade storage infrastructure to maintain compliance.
Long-term offtake agreements are replacing spot purchasing for high-purity acetonitrile in chromatography applications. Contract durations are extending from 12 months to 36-48 months as buyers prioritize supply security over price optimization. This pattern is most pronounced in United States biotechnology clusters and European generic pharmaceutical manufacturing hubs.
Aprotic Solvents Market Segmentation
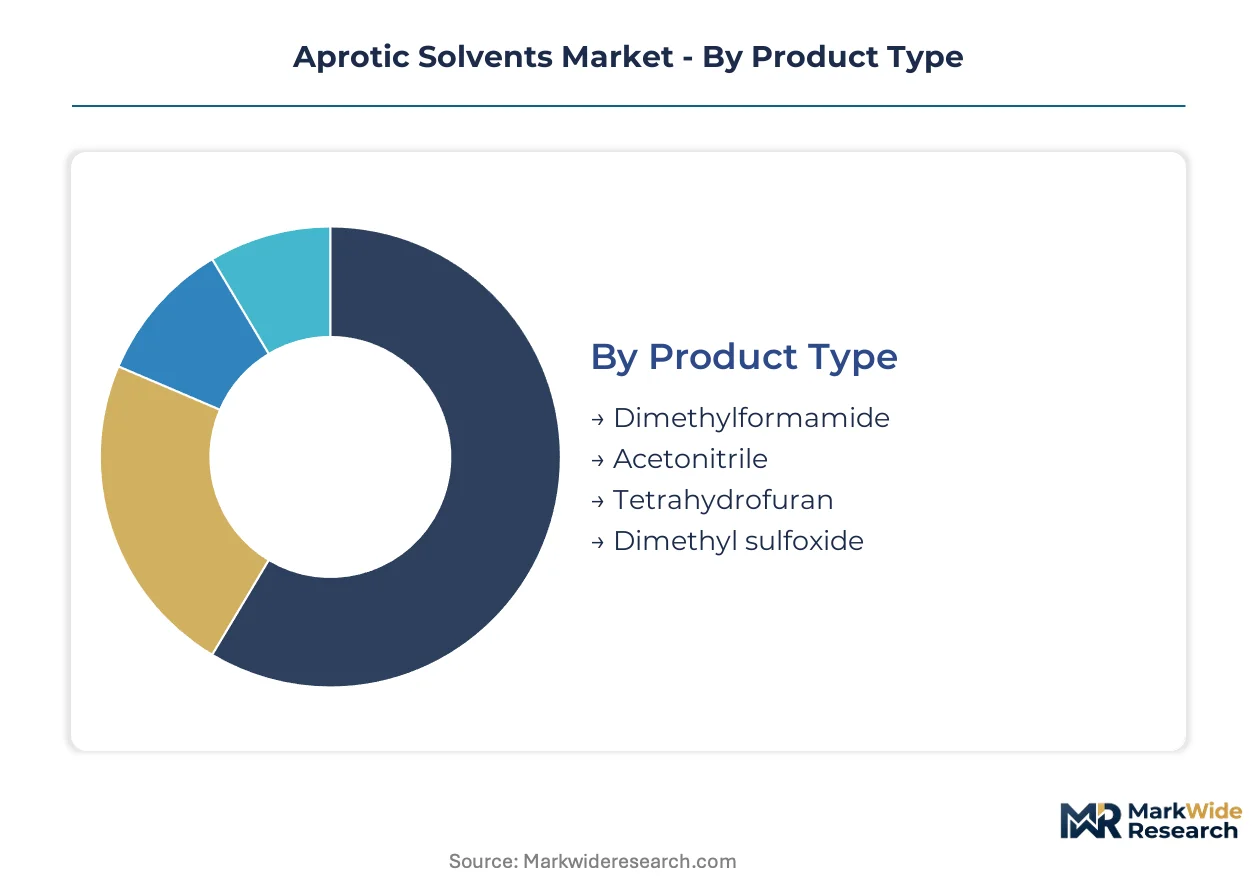
Aprotic solvent supply chains fragment across four distinct product chemistries, each commanding specialized production assets and purity certifications. Segmentation reveals how battery electrolyte specifications, pharmaceutical synthesis protocols, and electronics-grade requirements are reshaping capacity allocation and margin structures across the industry.
Product Type:
Supply concentration varies sharply across chemistries, with integrated petrochemical complexes dominating high-volume grades while specialty producers capture chromatography and battery-electrolyte niches.
- Dimethylformamide:Polar aprotic liquid with dielectric constant near 37 and exceptional solvation power for polar substrates. Pharmaceutical crystallization in India and China absorbs the majority of volume, though Yangtze River basin wastewater discharge limits under MEE enforcement are compressing regional supply availability.
- Tetrahydrofuran:Cyclic ether exhibiting low viscosity and high vapor pressure, enabling rapid drying in polymer processing. Cathode slurry preparation for lithium-ion cells is concentrating demand fastest, with gigafactory construction in Germany, China, and the United States tightening spot market availability.
- Acetonitrile:Nitrile solvent with UV transparency and low viscosity, indispensable for high-performance liquid chromatography mobile phases.
- Dimethyl sulfoxide:Sulfoxide with exceptional hydrogen bond acceptance and membrane permeability, serving cryopreservation and pharmaceutical formulation.
Today's leader: Dimethylformamide. Tomorrow's challenger: Tetrahydrofuran.
Application:
Cost tier differentiation separates commodity polymer processing from premium pharmaceutical and battery-grade specifications, with qualification timelines and purity documentation driving margin dispersion.
- Pharmaceuticals:Active ingredient synthesis and crystallization demand acetonitrile and dimethylformamide grades meeting FDA and EMA residual solvent guidelines. REACH registration dossiers for imported acetonitrile are extending European supply contracts to 36-48 month durations as manufacturers prioritize registration continuity over spot pricing.
- Electronics:Semiconductor fabrication and display manufacturing require sub-ppm metallic impurity profiles in dimethyl sulfoxide and tetrahydrofuran. Solid-state battery electrolyte development is creating specifications for ultra-dry tetrahydrofuran that command substantial premia over standard battery grades.
- Agrochemicals:Pesticide formulation and active ingredient production concentrate dimethylformamide consumption in China and India.
- Polymer Production:Polyurethane and polyimide synthesis represent mature demand with limited growth differentiation.
Electronics applications are climbing the fastest, while pharmaceuticals maintains the deepest contract backlogs.
End User:
Customer type determines procurement sophistication, with multinational battery and pharmaceutical manufacturers imposing supplier consolidation and audit requirements that marginalize regional distributors.
- Battery Manufacturing:Gigafactory operators specify tetrahydrofuran and dimethyl sulfoxide grades with controlled water content below 50 ppm for electrolyte formulation. Long-term offtake agreements are displacing spot purchasing as qualification timelines extend and supply security priorities intensify.
- Chemical Industry:Integrated producers consume captive dimethylformamide for downstream agrochemical and polymer intermediates, reducing merchant market exposure.
- Research Laboratories:Chromatography and analytical applications require acetonitrile grades with batch-level certification and traceable impurity documentation.
- Coatings:Industrial finishes and protective coatings represent price-sensitive demand vulnerable to bio-based solvent substitution where performance specifications permit.
Battery manufacturing is gaining share fastest, though research laboratories retain the stickiest supplier relationships.
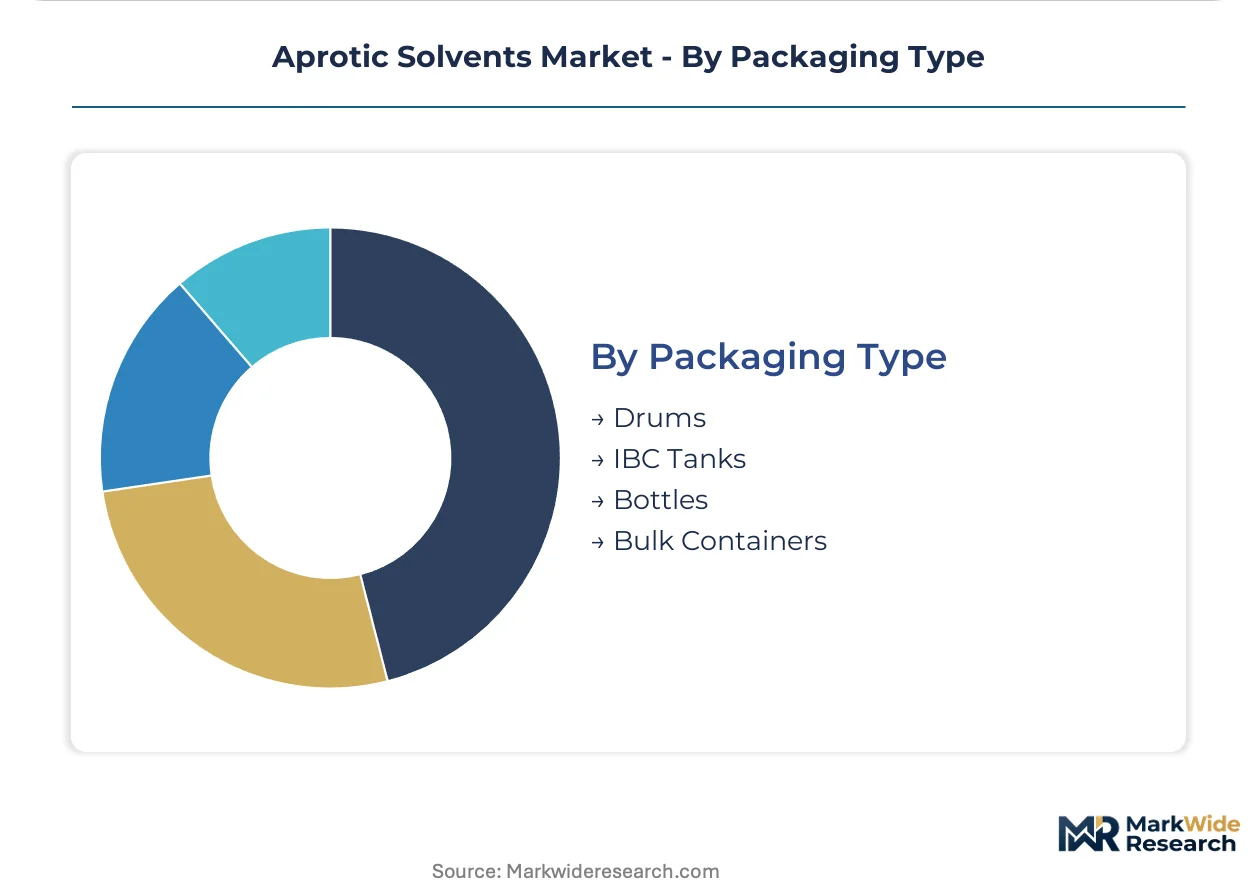
Packaging Type:
Volume scale and handling economics separate bulk integrated supply from specialized packaging for remote or low-volume end users.
- Bulk Containers:Railcar and tank truck deliveries serve polymer processors and large pharmaceutical manufacturers with dedicated storage infrastructure. EPA volatile organic compound emission controls on handling equipment are raising compliance capital requirements for United States facilities.
- IBC Tanks:Intermediate bulk containers balance logistics flexibility with volume scale for mid-sized chemical and coatings customers.
- Drums:Standard 200-liter steel drums serve fragmented coatings and specialty chemical demand with established distribution networks.
- Bottles:Laboratory-scale packaging for chromatography and research applications commands substantial per-liter premia for certified purity and traceability.
Today's volume anchor: Bulk containers. Tomorrow's growth format: IBC Tanks for expanding mid-tier manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing aprotic solvent production toward jurisdictions with lower compliance costs, even as end-use demand concentrates in developed markets with stringent purity standards. This tension shapes capacity location decisions and trade flows across the industry.
China
Yangtze River basin manufacturers are expanding dimethylformamide and acetonitrile capacity to serve domestic electronics and agrochemical customers. MEE wastewater discharge enforcement is raising compliance costs for producers in Jiangsu and Zhejiang provinces. Shanghai and Ningbo port clusters are consolidating pharmaceutical-grade solvent exports to India and Southeast Asia.
United States
Gigafactory construction in Texas and the Midwest is concentrating tetrahydrofuran demand for battery cathode slurry preparation. EPA volatile organic compound emission controls are tightening handling requirements for polymer processors in the Gulf Coast chemical corridor. Boston and San Francisco biotechnology clusters are securing long-term acetonitrile contracts for chromatography applications.
Germany
BASF SE's Ludwigshafen complex anchors European acetonitrile supply for pharmaceutical active ingredient synthesis. REACH registration requirements are extending supply contract durations to 36-48 months as manufacturers prioritize toxicological documentation continuity. The Rhine-Main chemical corridor is restructuring supply chains to reduce imported intermediate dependence.
India
CDSCO quality standards are driving demand for imported high-purity solvents as domestic active ingredient production expands. Maharashtra and Gujarat pharmaceutical hubs are absorbing increasing dimethylformamide volumes for crystallization processes. Hyderabad and Ahmedabad manufacturing clusters are qualifying new solvent suppliers to meet export market requirements.
Japan
METI battery safety certifications are reshaping qualification timelines for tetrahydrofuran suppliers to domestic lithium-ion cell producers. Osaka and Nagoya electronics manufacturing centers require sub-ppm metallic impurity profiles in dimethyl sulfoxide for semiconductor fabrication. Japanese chemical distributors are consolidating supplier bases to reduce audit burden under pharmaceutical purity standards.
Aprotic Solvents Market Vendor Landscape
German producers anchor one tier; Chinese specialists hold volume-driven positions in high-capacity dimethylformamide grades. The vendor base stratifies across integrated petrochemical complexes, standalone solvent refiners, and regional distributors. Three archetypes dominate: backward-integrated chemical conglomerates with captive feedstock access; specialty refiners focused on chromatography and battery-electrolyte purity grades; and regional traders serving fragmented coatings and agrochemical demand. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with producers securing long-term offtake agreements to lock in gigafactory demand.
Among European chemical conglomerates, BASF SE exemplifies the backward-integrated archetype with complex-level production integration. Eastman Chemical Company and Dow occupy positions spanning specialty and commodity grades, with geographic footprints aligning to regional demand clusters. These three anchors represent the competitive spectrum from integrated petrochemical operations to diversified specialty chemical portfolios.
| Leading Market Players |
|---|
| BASF SE |
| Eastman Chemical Company |
| Dow |
| INEOS |
| Arkema SA |
| Asahi Kasei |
| Ashland |
| Celanese Corporation |
| Mitsubishi Chemical |
| Others |
Supply Flow & Price Mechanics
Acrylonitrile spot price volatility cascades through aprotic solvent value chains, compressing margins for standalone acetonitrile refiners while integrated petrochemical complexes capture feedstock-cost advantages across pharmaceutical and battery-grade pricing tiers.
Pricing Analysis
Distributor margins of 12-18 percent separate bulk polymer-grade dimethylformamide from chromatography-certified acetonitrile sold in laboratory packaging. Three-tier pricing structure across premium, standard, and economy levels reflects purity certification, metallic impurity documentation, and volume scale. Cost compression in standard battery-grade tetrahydrofuran is intensifying because Chinese gigafactory operators are consolidating supplier bases for long-term offtake security. Coatings manufacturers represent the most price-sensitive segment, while biotechnology clusters in Boston and San Francisco exhibit lowest sensitivity due to chromatography solvent qualification requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale battery manufacturer demand for tetrahydrofuran and dimethyl sulfoxide, while specialty distributors serve fragmented pharmaceutical and research laboratory customers. Supply concentrates in China, Germany, and the United States, with Yangtze River basin producers dominating dimethylformamide capacity and Ludwigshafen anchoring European acetonitrile supply. Feedstock dependence draws from acrylonitrile byproduct streams, propylene oxidation routes, and maleic anhydride hydrogenation. Single-source vulnerability for chromatography-grade acetonitrile concentrates risk around acrylonitrile production economics. Distribution runs through integrated petrochemical complexes, regional solvent refiners, and specialized pharmaceutical-grade distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
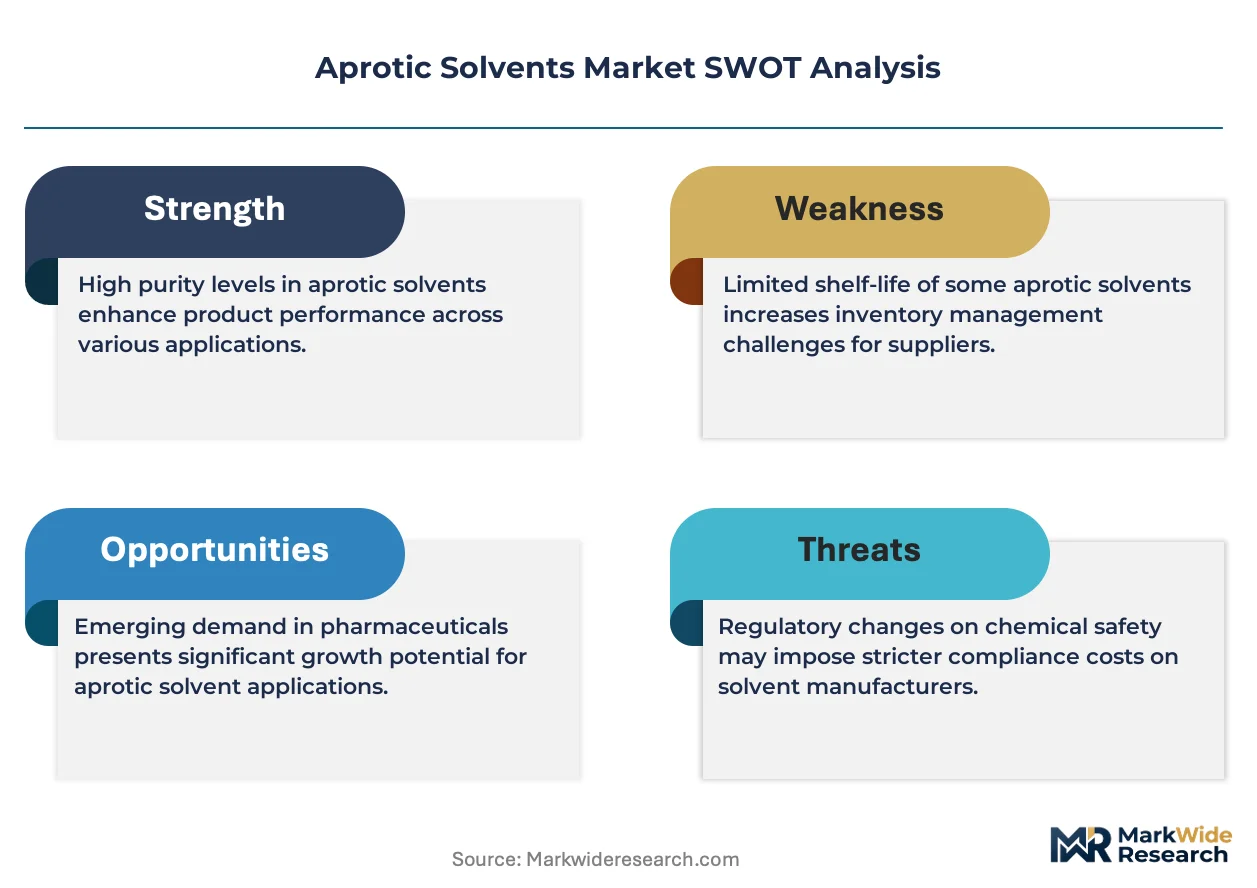
The aprotic solvents market functions as a stable compounder anchored by lithium-ion battery manufacturing expansion, which generates predictable offtake demand across multiple solvent chemistries and purity grades.
For Market Incumbents: Cement supply security through long-term acrylonitrile feedstock agreements and captive dimethylformamide capacity in the Yangtze River basin. Bio-based solvent substitution in coatings applications threatens commodity-grade margins, requiring incumbents to deepen certification investments in pharmaceutical and battery-electrolyte grades. Channel control through dedicated pharmaceutical-grade storage infrastructure at German and Swiss distribution hubs reinforces customer lock-in. For New Entrants and Emerging Players: EU Green Deal Chemicals Strategy in Europe opens a window for producers with verified carbon footprint reductions to capture sustainability-premium positioning. Ultra-dry tetrahydrofuran for solid-state battery electrolyte development represents the most penetrable white-space segment, with qualification timelines creating barriers for established commodity producers. A go-to-market angle anchored in electrochemical synthesis routes and closed-loop solvent recovery systems differentiates against incumbent batch-process economics. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty refiners focused on chromatography and battery-electrolyte purity grades. The five-to-ten year viability window favors acquisition targets with established REACH registration dossiers and qualified supplier status at biotechnology clusters. Watch for inflection when solid-state battery electrolyte specifications achieve commercial scale and reshape tetrahydrofuran demand profiles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylonitrile Feedstock | Secures raw material supply against price volatility for integrated producers. |
| Electrochemical Synthesis Route Adoption | Reduces carbon intensity to meet EU Green Deal certification requirements. |
| Long-term Supply Agreement with Gigafactory Operators | Locks in tetrahydrofuran demand from battery manufacturers in Germany and Texas. |
| Pharmaceutical-grade Storage Infrastructure Investment | Enables REACH compliance for dimethyl sulfoxide distribution in the Rhine-Main corridor. |
| Closed-loop Solvent Recovery System Deployment | Compresses operational costs for dimethylformamide producers under MEE wastewater limits. |
Methodological Framework
Coverage spans China, the United States, Germany, India, and Japan, with primary inputs from each region combined with secondary validation. Plant managers at dimethylformamide and tetrahydrofuran facilities, procurement leads at lithium-ion battery manufacturers, distribution channel partners in pharmaceutical-grade solvents, and technical R&D directors at electrolyte formulators provided structured interviews. Secondary sources include customs and trade data from Chinese and Indian port authorities, Cefic and ACC industry reports, SEC 10-K filings from chemical conglomerates, and REACH registration dossiers from ECHA. Bottom-up capacity and consumption estimates triangulate against top-down market sizing derived from end-use industry production data.
Rate-of-change decomposition separates volume growth from price evolution across the projection horizon. Segmentation dimensions modeled include solvent chemistry type, purity grade tier, end-use industry application, packaging format, and regional production hub. CAGRs were derived from regression analysis against lithium-ion battery manufacturing capacity expansion, pharmaceutical active ingredient production indices, and polymer processing output trends. Industry-specific forecast inputs incorporate gigafactory construction timelines, REACH authorization schedules for substances of very high concern, and MEE wastewater discharge enforcement patterns in the Yangtze River basin.
Revisions become necessary when battery safety certification protocols shift, pharmaceutical purity standards tighten, or feedstock supply disruptions alter acrylonitrile economics. Forecasts reflect assumptions about continued lithium-ion cell manufacturing scale-up, regulatory stability in European chemical registration frameworks, and sustained agrochemical demand in India and China. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Citrus Solvents Market
Solvents
Nitromethane Market
Solvents
North America Toluene Market
Solvents
Benzene-Toluene-Xylene (BTX) Market
Solvents
Benzene Market
Solvents
N-Methyl Pyrrolidone Market
Solvents
Global Solvent Evaporation Market
Solvents
Organic Solvents Market
Solvents
Hydrofluoroether Market
Solvents
Global Ink Solvents Market
Solvents
Global Green and Bio-Based Solvents Market
Solvents
Diethylene Glycol Monobutyl Ether Market
Solvents
United States Acetonitrile Market
Solvents
Global Chloroform Market
Solvents
Fluid Neutralizing Market
Solvents
Alpha-Methylstyrene Market