
 Soil Remediation Market | 2026-2036
Soil Remediation Market Size, Share, and Industry Trends Forecast 2026-2036
Soil Remediation Market Insights
Buyer concentration among large environmental agencies and government bodies is recalibrating contract structures toward multi-site framework agreements. Veolia Environnement S.A. leverages its integrated waste-to-remediation platform across European industrial corridors. Clean Harbors Inc. anchors its competitive position through hazardous waste logistics that feed directly into treatment networks. AECOM competes on engineering scale, bundling site assessment with infrastructure redevelopment across North American metropolitan regions.
Soil remediation encompasses the physical, chemical, or biological treatment of contaminated soil to restore ecological function and regulatory compliance, typically targeting petroleum hydrocarbons, heavy metals, or chlorinated solvents at concentrations measured against jurisdiction-specific risk thresholds. The process serves industrial redevelopment, agricultural safety, and groundwater protection objectives across public and private land holdings. Bioremediation occupies the technology space where microbial degradation of organic contaminants offers lower operational intensity for petroleum-impacted sites. Thermal treatment leads where rapid destruction of recalcitrant compounds justifies higher energy input at concentrated source zones. Phytoremediation extends into agricultural land applications where hyperaccumulator plants address diffuse metal contamination with minimal soil disturbance.
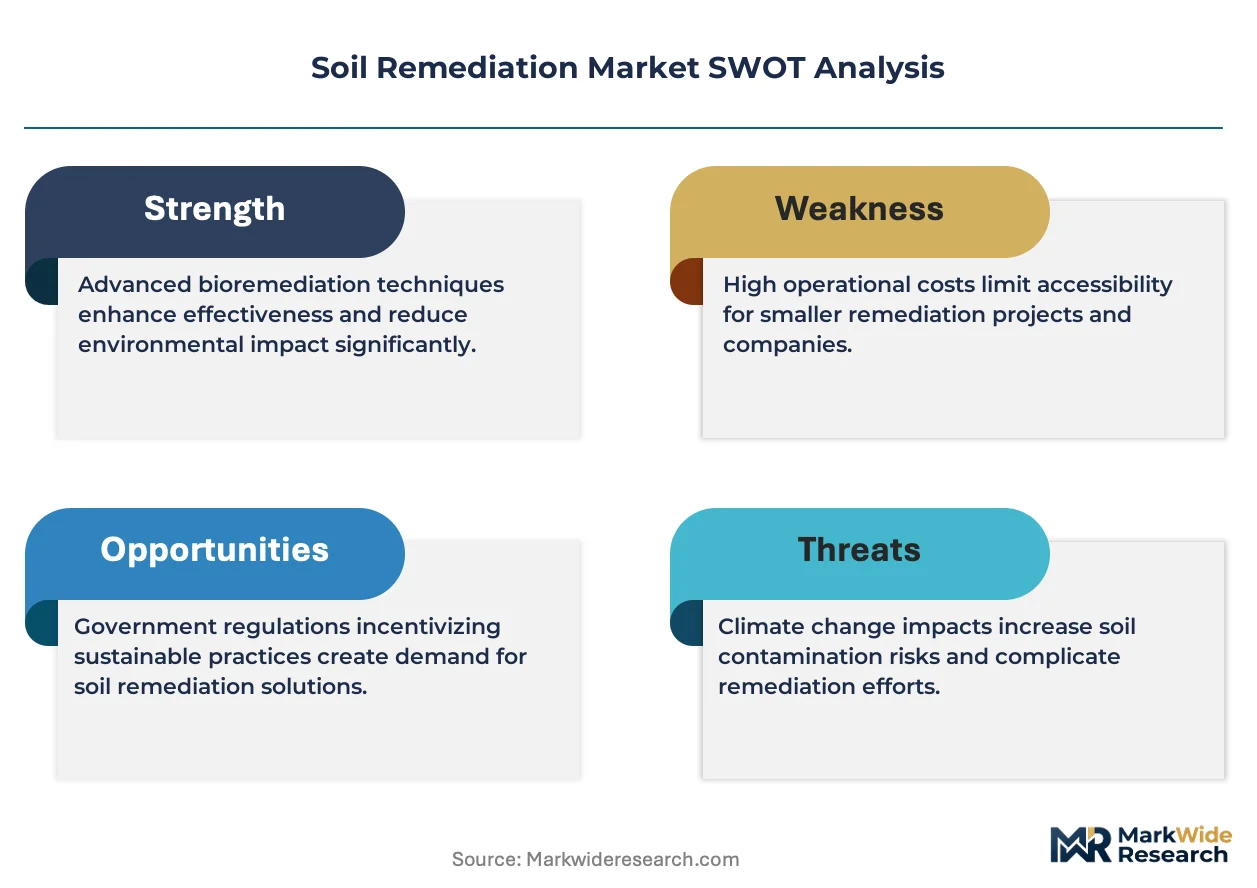
The EPA administers CERCLA liability and RCRA corrective action programs that compel responsible parties to fund remediation at listed facilities across the United States. The European Commission advances soil health requirements through the EU Soil Monitoring Law and embeds remediation obligations within the Environmental Liability Directive. China's MEE enforces GB standard compliance for contaminated site redevelopment in urban land conversion projects. Stakeholders must monitor how emerging pollutant criteria for PFAS and microplastics expand technical scope beyond legacy contaminant protocols.
Market Dynamics
Industrial brownfield redevelopment across Germany, the United States, and China is compressing remediation timelines and forcing contractors to integrate real-time monitoring with accelerated treatment protocols. The shift from single-site projects to multi-location framework agreements concentrates purchasing power among environmental agencies and infrastructure developers.
Growth Catalysts
- EU Soil Monitoring Law:Mandatory soil health assessments across member states create recurring revenue streams for assessment and treatment providers. The directive embeds remediation obligations into land transactions.
- Petroleum-impacted sites:Decommissioned fuel terminals and refinery clusters in the US Gulf Coast require urgent hydrocarbon degradation. Bioremediation contractors secure multi-year maintenance contracts.
- China's urban land conversion:MEE enforcement of GB standards for contaminated site redevelopment in Shanghai and Beijing accelerates pre-construction remediation spending.
Market Restraints
- Energy input costs:Thermal desorption and incineration treatments face margin pressure from natural gas price volatility in European industrial corridors.
- Specialized equipment supply:Mobile thermal treatment units concentrate among German and US manufacturers, creating procurement bottlenecks for Asian contractors.
- PFAS technical limitations:Existing bioremediation protocols fail to degrade per- and polyfluoroalkyl substances, forcing costly excavation and off-site disposal.
Strategic Opportunities
- India's industrial corridor cleanup:The PLI scheme for manufacturing expansion triggers remediation obligations at former chemical sites in Gujarat and Maharashtra.
- Phytoremediation in agricultural transition zones:Hyperaccumulator crops address diffuse cadmium and arsenic contamination in Chinese rice paddies without soil removal.
- Sensor-integrated treatment monitoring:Real-time contaminant tracking converges with IoT platforms to enable performance-based contracting for long-term site management.
Industry Challenges
- Geotechnical modeling expertise:Site characterization requires hydrogeologists capable of integrating 3D plume mapping with treatment design, a skill set concentrated among aging specialists in North America and Europe.
- Multi-jurisdictional liability:CERCLA's retroactive strict liability in the United States complicates insurance underwriting for contractors operating across state lines with varying joint-and-several enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soil Remediation Market |
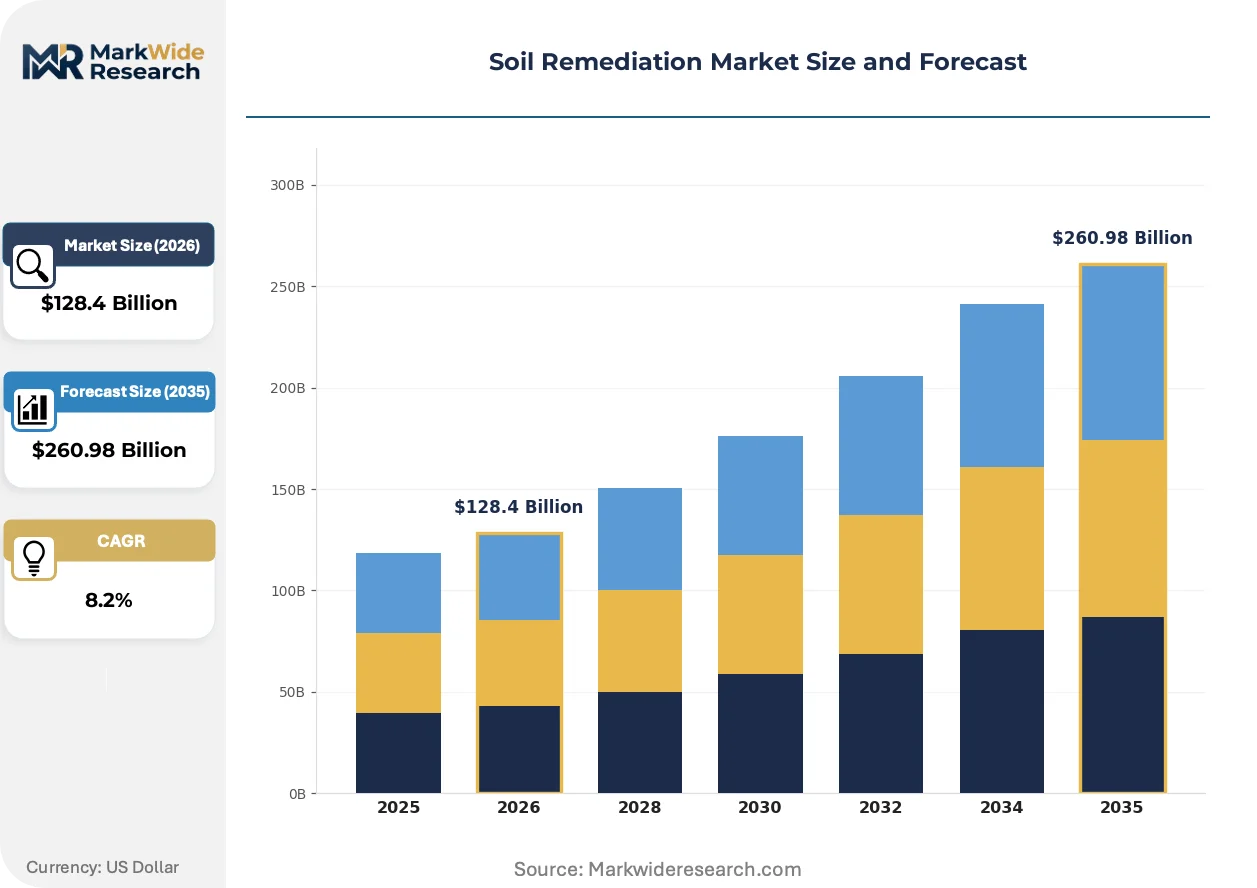
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $260.98 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Bioremediation, Thermal Treatment, Chemical Extraction, Phytoremediation Application: Industrial Sites, Agricultural Land, Landfills, Contaminated Waterways End User: Construction Companies, Environmental Agencies, Agricultural Sector, Government Bodies Service Type: Consultation, Site Assessment, Remediation Services, Monitoring |
| Companies Covered | Veolia Environnement S.A., Clean Harbors Inc., AECOM, Jacobs Engineering Group Inc., Tetra Tech, Inc., WSP Global Inc., Arcadis N.V., SUEZ S.A., Stantec Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soil Remediation Market Trends and Innovations
Remediation technology is pivoting from excavation-dependent approaches to in-situ treatment modalities that minimize soil disturbance and transportation costs. The convergence of biological degradation with digital monitoring platforms is compressing project timelines and reshaping contractor capabilities.
Electrokinetic remediation is rewriting treatment economics for clay-heavy soils where hydraulic conductivity blocks conventional flushing. Dutch and Belgian contractors deploy electrode arrays to mobilize heavy metals in low-permeability source zones. The technology enables treatment of former smelter sites previously deemed too geologically complex for cost-effective cleanup.
REACH authorization requirements for persistent organic pollutants are tightening disposal pathways for contaminated soil across EU member states. The regulation forces contractors to document destruction efficiency rather than simple containment. Thermal treatment providers in Germany and France invest in emission control upgrades to maintain access to industrial redevelopment contracts.
Environmental liability transfer mechanisms are displacing traditional cost-plus contracting in North American commercial real estate transactions. Buyers demand fixed-price remediation with insurance-backed completion guarantees. Specialized underwriters in London and Bermuda now structure policies covering cost overruns and regulatory reopeners, concentrating risk assessment expertise among a narrow pool of technical advisors.
Soil Remediation Market Segmentation
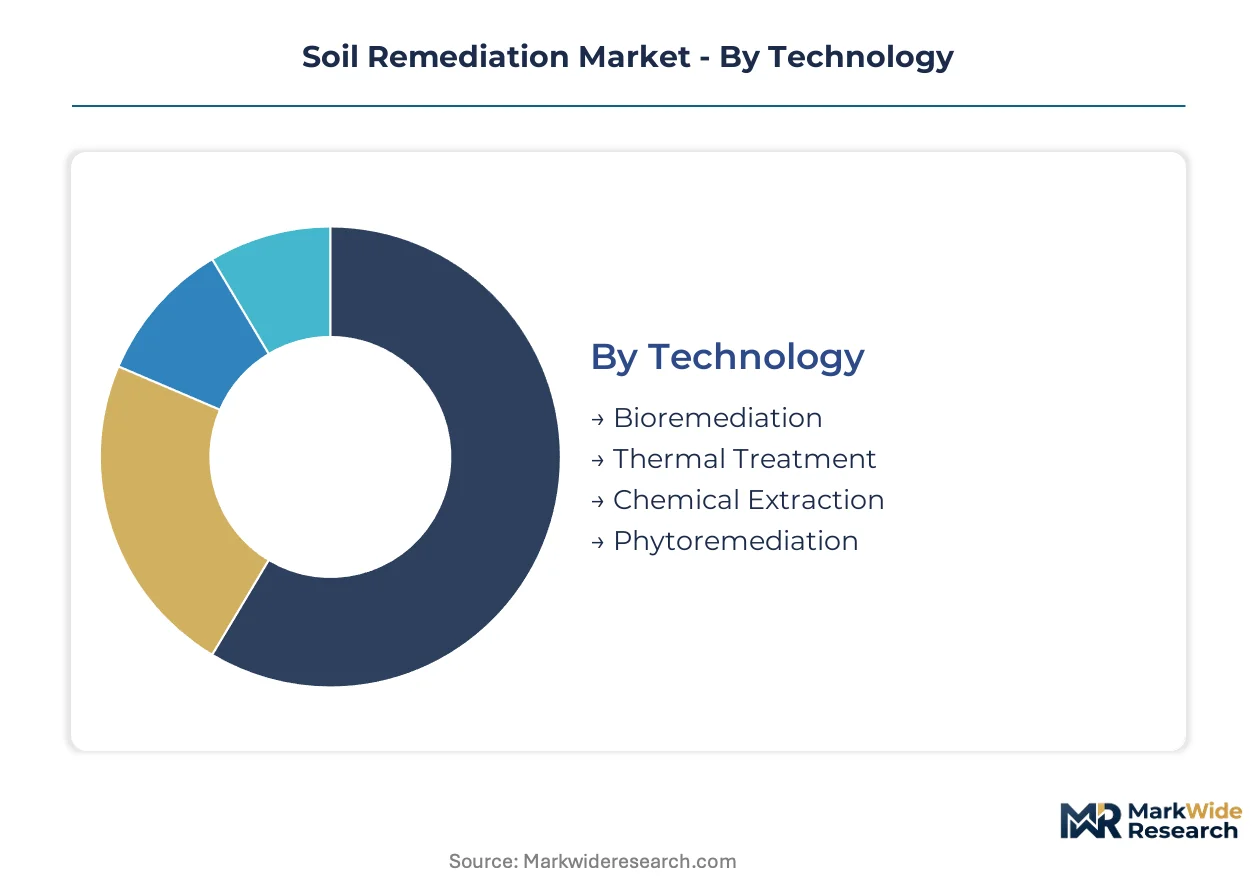
Technology selection in soil remediation hinges on contaminant chemistry, geological constraints, and regulatory destruction mandates. Each segment carries distinct certification burdens from EPA, ECHA, or national environmental agencies that shape contractor capabilities and client procurement criteria.
Technology:
Certification requirements vary sharply across modalities, with thermal treatment demanding EPA hazardous waste combustion permits and bioremediation navigating state-level microbial release protocols.
- Bioremediation:Microbial consortia degrade petroleum hydrocarbons and chlorinated solvents through aerobic or anaerobic metabolic pathways. Gulf Coast refinery decommissioning in Texas and Louisiana concentrates demand, driven by EPA RCRA corrective action timelines that favor lower-energy alternatives.
- Thermal Treatment:High-temperature desorption or incineration destroys recalcitrant compounds including PCBs and dioxins. REACH authorization requirements in Germany and France mandate documented destruction efficiency rather than containment, concentrating procurement among EU-permitted facility operators.
- Chemical Extraction:Solvent flushing or soil washing mobilizes heavy metals and polar organics for liquid-phase separation.
- Phytoremediation:Hyperaccumulator plants address diffuse cadmium and arsenic contamination in Chinese rice paddies with minimal soil disturbance.
Thermal Treatment sits at the top of the volume ranking, with Bioremediation climbing the fastest.
Application:
Site characteristics determine liability exposure and treatment urgency, with industrial brownfields carrying CERCLA enforcement risk and agricultural land facing food safety thresholds.
- Industrial Sites:Former manufacturing facilities and fuel terminals require rapid hydrocarbon or solvent remediation to enable construction financing. Germany's Ruhr Valley corridor accelerates brownfield redevelopment, compressing project timelines through integrated assessment-treatment contracts.
- Agricultural Land:Metal-contaminated cropland demands restoration for food safety compliance or land-use conversion. China's MEE enforces GB standards for urban land conversion, triggering pre-construction remediation in Shanghai and Beijing peri-urban zones.
- Landfills:Leachate-impacted soils surrounding waste disposal facilities require containment and treatment.
- Contaminated Waterways:Riparian sediment remediation addresses historical industrial discharge and urban runoff accumulation.
Industrial Sites dominate current expenditure, with Agricultural Land expanding most quickly on food security priorities.
End User:
Procurement sophistication varies by institutional capacity, with environmental agencies leveraging multi-site frameworks and agricultural operators prioritizing cost containment.
- Construction Companies:Developers of industrial and commercial real estate require liability transfer mechanisms and fixed-price remediation with insurance-backed completion guarantees. North American metropolitan regions concentrate demand where CERCLA liability complicates land transactions.
- Environmental Agencies:Government bodies administer superfund sites and enforce corrective action through cost-recovery litigation. The EPA's multi-site framework agreements concentrate purchasing power and reshape contractor competitive dynamics.
- Agricultural Sector:Farm operators and cooperatives pursue phytoremediation for metal-contaminated soils.
- Government Bodies:Municipal and state entities fund public land restoration and brownfield revitalization programs.
Environmental Agencies anchor procurement volume, while Construction Companies are gaining share fastest on private-sector redevelopment velocity.
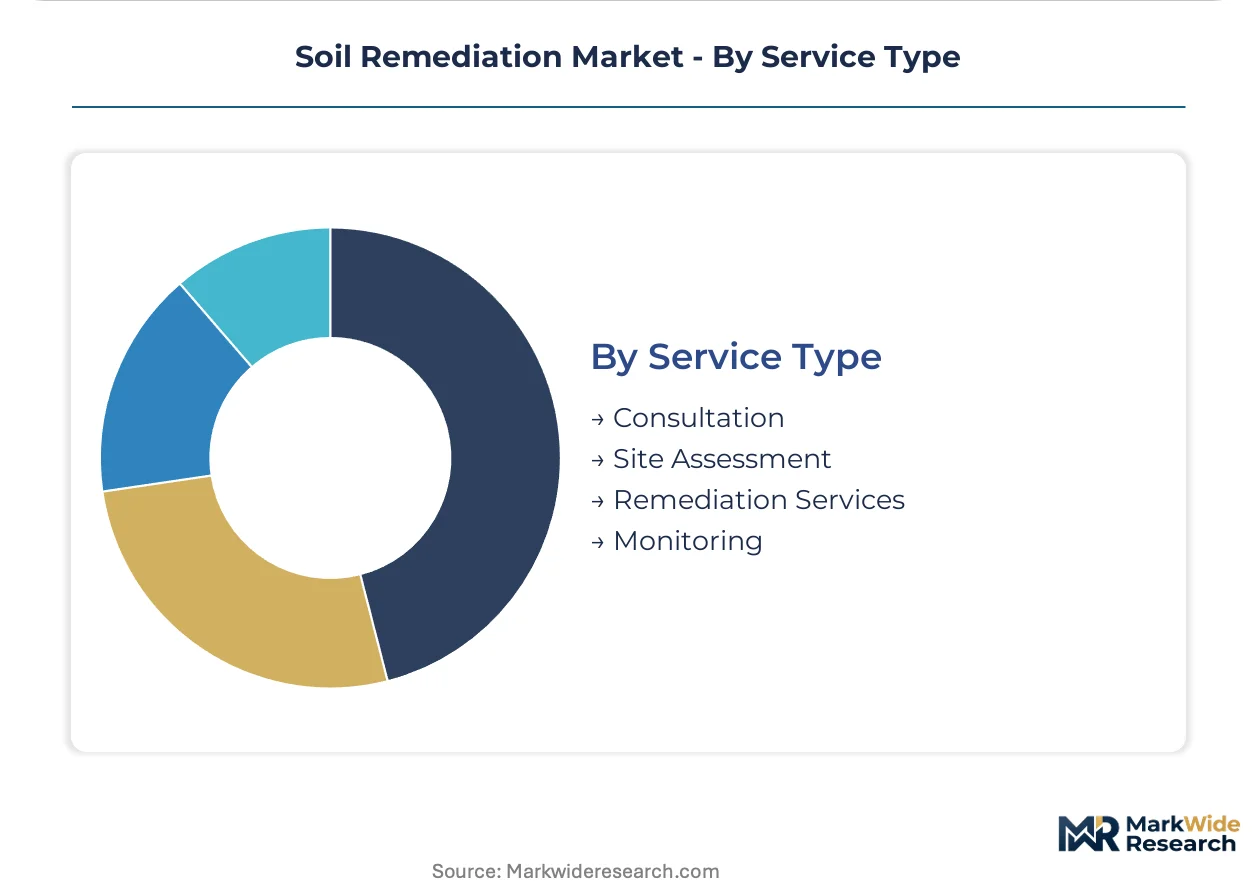
Service Type:
Margin structure inverts across the project lifecycle, with front-end assessment commanding premium pricing and long-term monitoring shifting to performance-based contracting.
- Consultation:Regulatory navigation and liability assessment for property transactions and enforcement response. European industrial corridors concentrate demand where EU Soil Monitoring Law embeds remediation obligations into land transactions.
- Site Assessment:Characterization drilling, laboratory analysis, and hydrogeological modeling to define contaminant plume geometry. Aging specialist concentration in North America and Europe constrains capacity expansion.
- Remediation Services:Physical implementation of treatment technologies including excavation, in-situ injection, or thermal processing.
- Monitoring:Long-term verification of treatment performance and institutional controls through sensor networks and periodic sampling.
Remediation Services capture the largest revenue share, with Monitoring posting the steepest expansion trajectory on IoT-enabled performance contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr Valley corridor generates remediation contract density that rivals the US Gulf Coast petroleum cluster, while China's urban land conversion programs are compressing project timelines in Shanghai and Beijing peri-urban zones.
United States
Decommissioned fuel terminals and refinery clusters along the Gulf Coast drive hydrocarbon remediation demand. The EPA administers CERCLA liability and RCRA corrective action programs that compel responsible parties to fund cleanup at listed facilities. Houston and Louisiana industrial corridors concentrate bioremediation contractors securing multi-year maintenance contracts.
Germany
The Ruhr Valley brownfield redevelopment accelerates integrated assessment-treatment contracts. REACH authorization requirements mandate documented destruction efficiency for persistent organic pollutants. Thermal treatment providers in North Rhine-Westphalia invest in emission control upgrades to maintain access to industrial redevelopment contracts.
China
Urban land conversion in Shanghai and Beijing triggers pre-construction remediation spending. The MEE enforces GB standards for contaminated site redevelopment in metropolitan land conversion projects. Yangtze River Delta manufacturing zones require urgent cleanup at former chemical sites to enable construction financing.
India
The PLI scheme for manufacturing expansion triggers remediation obligations at former chemical sites. State pollution control boards enforce site closure norms that embed treatment requirements into land transactions. Gujarat and Maharashtra industrial corridors concentrate demand for petroleum-impacted site restoration.
Netherlands
Electrokinetic remediation contractors deploy electrode arrays to mobilize heavy metals in low-permeability source zones. Dutch and Belgian firms treat former smelter sites previously deemed too geologically complex for cost-effective cleanup. Randstad urban regeneration projects integrate real-time monitoring with accelerated treatment protocols.
Soil Remediation Market Competitive Landscape
North American environmental service conglomerates anchor one tier; European integrated waste-to-remediation platforms hold specialized positions in industrial corridor markets. The vendor base concentrates among engineering-scale generalists and hazardous waste logistics specialists. Three archetypes dominate: integrated environmental platforms, engineering-led infrastructure bundlers, and hazardous waste treatment networks. M&A activity consolidates regional assessment capabilities; strategic partnerships embed contractors into multi-site framework agreements with government agencies.
Within the integrated environmental platform tier, Veolia Environnement S.A. and SUEZ S.A. exemplify the European model of waste-to-remediation vertical integration. Clean Harbors Inc. anchors the North American hazardous waste logistics archetype. These three occupy positions that reflect distinct geographic regulatory environments rather than direct product competition.
| Leading Market Players |
|---|
| Veolia Environnement S.A. |
| Clean Harbors Inc. |
| AECOM |
| Jacobs Engineering Group Inc. |
| Tetra Tech, Inc. |
| WSP Global Inc. |
| Arcadis N.V. |
| SUEZ S.A. |
| Stantec Inc. |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up environmental service specialists anchor supply-side consolidation across North American and European industrial corridors, compressing vendor counts while hardening pricing discipline through multi-year framework agreements with EPA and EU Soil Monitoring Law enforcement bodies.
Pricing Analysis
Capacity additions in Germany and the United States are reshaping price floors for thermal treatment services, with REACH-authorized facility operators commanding premium rates for documented destruction efficiency against containment-only alternatives. Three-tier pricing structure across premium certified, standard permitted, and economy containment tiers separates EPA hazardous waste combustion permit holders from state-level bioremediation contractors. Cost compression in the economy tier is intensifying because natural gas price volatility erodes margins for thermal desorption providers. Construction companies show highest price sensitivity due to fixed-price remediation demands with insurance-backed completion guarantees, while environmental agencies exhibit lowest sensitivity through cost-recovery litigation mechanisms.
Supply Chain Analysis
Reverse-logistics flows for contaminated soil excavation and off-site disposal concentrate procurement bottlenecks among German and US mobile thermal treatment unit manufacturers, with refurbishment and redeployment cycles extending equipment utilization across Asian contractor networks. Supply concentrates in Germany, the United States, and China for specialized remediation equipment, with component dependencies on high-temperature refractory materials, electrode arrays for electrokinetic systems, and microbial consortia cultivation. Single-source vulnerability runs through German thermal treatment technology licensors. Distribution runs through multi-site framework agreements with environmental agencies and construction company procurement consortiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Soil remediation operates as a late-cycle quality market where liability transfer mechanisms and documented destruction efficiency command premium pricing, with buyer procurement shifting toward performance-based contracting with real-time IoT monitoring integration.
For Market Incumbents: Deploy sensor-integrated treatment monitoring platforms to defend against emerging digital-native contractors offering performance-guaranteed remediation contracts. Consolidate geotechnical modeling expertise through targeted assessment capability acquisitions, as aging specialist concentration in North America and Europe constrains competitor expansion. Secure backward integration into hazardous waste logistics networks to maintain margin control against Clean Harbors Inc.'s anchored position. For New Entrants and Emerging Players: Regional environmental engineering firms represent the most accessible channel partnership archetype for penetrating India's Gujarat and Maharashtra industrial corridors under PLI-scheme manufacturing expansion. Target phytoremediation applications in Chinese agricultural transition zones, where hyperaccumulator crop protocols for cadmium and arsenic remain underdeveloped relative to petroleum-impacted site saturation. Pursue fixed-price remediation with insurance-backed completion guarantees as the dominant go-to-market angle for North American commercial real estate transactions. For Investors and Strategic Acquirers: Integrated waste-to-remediation platforms are the most active acquirer in this space, with Veolia Environnement S.A. and SUEZ S.A. consolidating European assessment capabilities. Five-to-ten year viability hinges on PFAS technical capability development, as existing bioremediation protocol limitations force costly excavation alternatives. Acquisition targets should display electrokinetic remediation expertise for clay-heavy soil applications or real-time monitoring platform integration. Watch for EPA emerging pollutant criteria expansion as the inflection signal for technical scope revision beyond legacy contaminant protocols.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS Technical Capability Development | EPA emerging pollutant criteria expansion forces costly excavation alternatives without viable degradation protocols. |
| Sensor-Integrated Treatment Monitoring | IoT platform convergence enables performance-based contracting with real-time contaminant tracking for long-term site management. |
| Electrokinetic Remediation Expansion | Dutch and Belgian contractors deploy electrode arrays to unlock former smelter sites previously deemed geologically complex. |
| Multi-Site Framework Agreement Embedding | EPA and EU Soil Monitoring Law enforcement concentrates purchasing power among environmental agencies and infrastructure developers. |
| Insurance-Backed Completion Guarantee Structuring | London and Bermuda underwriters concentrate risk assessment expertise for fixed-price remediation in North American commercial real estate. |
Research Methodology
Multiple input streams — regulatory filing analysis, contractor procurement database review, and contaminated site inventory reconciliation — were reconciled across primary interviews with EPA enforcement officers, state pollution control board administrators, environmental agency procurement directors, and brownfield redevelopment project managers, validated against EPA CERCLA and RCRA corrective action records, EU ECHA REACH authorization databases, China MEE GB standard enforcement reports, and India Central Pollution Control Board site closure documentation, with bottom-up project pipeline aggregation triangulated against top-down expenditure estimates from national environmental agency budget disclosures.
Data-stream reconciliation applied across the projection horizon modeled technology selection by contaminant chemistry and geological constraint, application segment by liability exposure and treatment urgency, end-user procurement sophistication by institutional capacity, and service type margin structure by project lifecycle position, with CAGRs derived from expenditure trajectory analysis against regulatory enforcement timeline compression and brownfield redevelopment velocity indicators including construction financing availability and urban land conversion permitting rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PFAS regulatory criteria expansion, natural gas price volatility for thermal treatment energy inputs, and mobile thermal treatment unit manufacturing capacity constraints. Forecasts reflect documented assumptions regarding EU Soil Monitoring Law implementation pacing and China MEE enforcement consistency. Practitioners should monitor EPA emerging pollutant protocol revisions, REACH authorization requirement tightening, and sovereign manufacturing incentive scheme expansion for early signals of technical scope and procurement pattern shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Global Voluntary Carbon Credit Trading Market
Environment & Sustainability
Reusable Oil Absorbents Market
Environment & Sustainability
South America Air Quality Monitoring Market
Environment & Sustainability
Philippines Gravity-Based Water Purifier Market
Environment & Sustainability
Chile Water Consumption Market
Environment & Sustainability
Home Water Softener System Market
Environment & Sustainability
Packaging Waste Recycling Market
Environment & Sustainability
Landfill Compactor Market
Environment & Sustainability
Compostable and Biodegradable Refuse Bags Market
Environment & Sustainability
US Municipal Solid Waste Management Market
Environment & Sustainability
Smart Carbon Market
Environment & Sustainability
Biofuel Testing Services Market
Environment & Sustainability
Construction and Demolition Waste Management Market
Environment & Sustainability
Sustainable Construction Market
Environment & Sustainability
Water Quality Monitoring Equipment Market
Environment & Sustainability
Europe Green Cement Market