
 South Korea Digital Twin Market | 2026-2036
South Korea Digital Twin Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Digital Twin Market Insights
Asset-light leasing models for industrial simulation software is reconfiguring competitive entry barriers, allowing mid-sized manufacturers to access twin infrastructure without capital-heavy licensing. Samsung Electronics leverages its semiconductor fabrication expertise to anchor digital twin services for precision manufacturing clients. KT Corporation competes through telecommunications-integrated edge computing platforms that reduce latency for real-time asset monitoring.
A digital twin constitutes a virtual representation of a physical entity, continuously synchronized through sensor data streams and simulation algorithms to mirror operational states, thermal profiles, and mechanical degradation patterns across industrial assets. Its primary purpose enables predictive maintenance, process optimization, and scenario testing without disrupting live production systems. Manufacturing application segments dominate current deployment volumes as automotive and electronics producers pursue zero-downtime targets. Cloud-based technology layers capture expanding margin pools as hybrid architectures allow manufacturers to balance computational intensity against data sovereignty requirements.
MFDS guidelines on pharmaceutical manufacturing traceability and KOSHA industrial safety standards shape digital twin adoption by mandating real-time equipment monitoring and predictive hazard detection. METI-aligned smart factory frameworks further reinforce integration requirements for cross-border supply chain visibility. Stakeholders must weigh subscription delivery models against custom solution development as client sophistication diverges across heavy industry versus municipal deployment contexts.
Market Dynamics
Cloud-native simulation architectures are compressing deployment cycles for South Korean manufacturers, forcing legacy on-premise vendors to pivot toward subscription models or cede mid-market share to agile software-as-a-service entrants.
Growth Catalysts
- MFDS pharmaceutical traceability mandates:Real-time batch monitoring requirements for drug manufacturers are accelerating digital twin adoption for equipment validation and contamination tracking across Gyeonggi Province production clusters.
- Semiconductor fabrication precision demands:Samsung and SK Hynix process nodes below 3nm require thermal and mechanical digital twins to maintain yield rates, creating captive demand for high-fidelity simulation infrastructure.
- KOSHA predictive safety frameworks:Heavy manufacturing groups in Ulsan and Pohang steel corridors must deploy hazard-detection twins to comply with industrial accident prevention protocols.
Market Restraints
- High-performance computing cost volatility:GPU cluster pricing fluctuations and memory chip supply constraints inflate operational expenditures for real-time physics simulation workloads.
- Data sovereignty localization requirements:Domestic cloud certification regimes restrict foreign platform operators, limiting competitive pressure and software pricing flexibility for end-users.
- Interoperability gaps with legacy SCADA:Proprietary protocols from 1990s-era automation systems resist API integration, fragmenting data streams essential for synchronized twin fidelity.
Strategic Opportunities
- Busan smart port infrastructure:Container terminal automation and vessel traffic optimization present untapped demand for maritime logistics twins integrating crane kinematics with tidal simulation.
- 5G-Advanced edge convergence:KT and SK Telecom network slicing capabilities enable sub-10 millisecond latency for mobile asset twins in construction and mining equipment fleets.
- Carbon accounting integration:KEIT industrial efficiency incentives reward manufacturers deploying energy-consumption twins that track Scope 1 and 2 emissions against reduction targets.
Industry Challenges
- Multiphysics simulation expertise scarcity:The labor pool combining computational fluid dynamics, finite element analysis, and industrial IoT architecture remains concentrated in Seoul metropolitan universities, creating recruitment bottlenecks for Busan and Daegu operations.
- Cross-functional integration complexity:Bridging OT engineering teams with IT data science units requires organizational restructuring that delays pilot-to-production scaling by 12-18 months at typical chaebol manufacturing divisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Digital Twin Market |
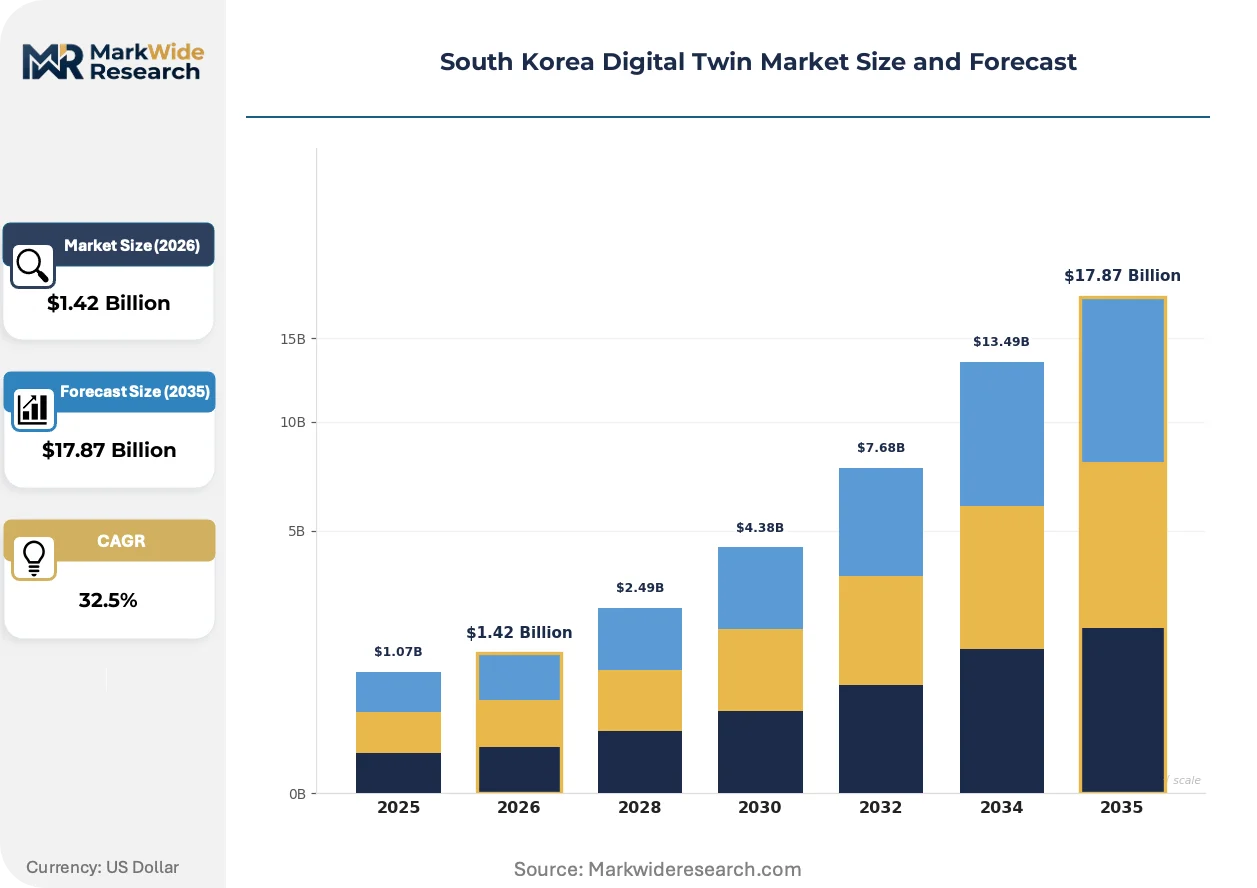
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $17.87 Billion |
| CAGR (2026 – 2036) | 32.5% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Manufacturing, Healthcare, Smart Cities, Automotive Technology: Cloud-Based, Edge Computing, IoT Integration, Simulation Software End User: Manufacturers, Healthcare Providers, Urban Planners, Transportation Agencies Delivery Model: Licensing, Subscription, Managed Services, Custom Solutions |
| Companies Covered | Korea Hydro & Nuclear Power, LG Electronics, Siemens, SK Hynix, Hyundai Motor Company, Robert Bosch GmbH, Samsung Electronics, KT Corporation, Naver Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Digital Twin Market Trends and Innovations
Physics-informed neural networks are compressing simulation runtime from hours to seconds, enabling South Korean manufacturers to embed real-time optimization directly into production control loops rather than confining analysis to offline planning phases.
Generative AI-powered surrogate modeling is rendering obsolete traditional finite element preprocessing workflows that required manual mesh refinement and boundary condition specification. Automotive stamping and battery cell formation lines in Hwaseong and Ochang are adopting these tools within 18-month procurement cycles. The technology is compressing time-to-insight for process engineers who previously outsourced complex thermal simulations to specialized consulting boutiques.
MFDS good manufacturing practice updates now mandate digital batch records with equipment state traceability, compelling pharmaceutical producers to retrofit legacy filling and packaging lines with sensor-integrated twins. The regulation is accelerating hybrid cloud deployments where validated on-premise edge nodes handle real-time critical control while non-critical analytics migrate to domestic sovereign cloud infrastructure. Domestic contract manufacturing organizations in Songdo and Incheon free economic zones are absorbing compliance costs faster than multinational subsidiaries.
Heavy industry procurement committees are unbundling simulation software from multi-year enterprise resource planning contracts, creating direct vendor relationships with specialized twin platform providers. Steel and petrochemical buyers in Yeosu and Gwangyang industrial complexes now evaluate physics engines separately from manufacturing execution systems. This pattern is most visible in chaebol heavy industry divisions where centralized IT procurement authority has decentralized to plant-level engineering managers with operational P&L accountability.
South Korea Digital Twin Market Segmentation
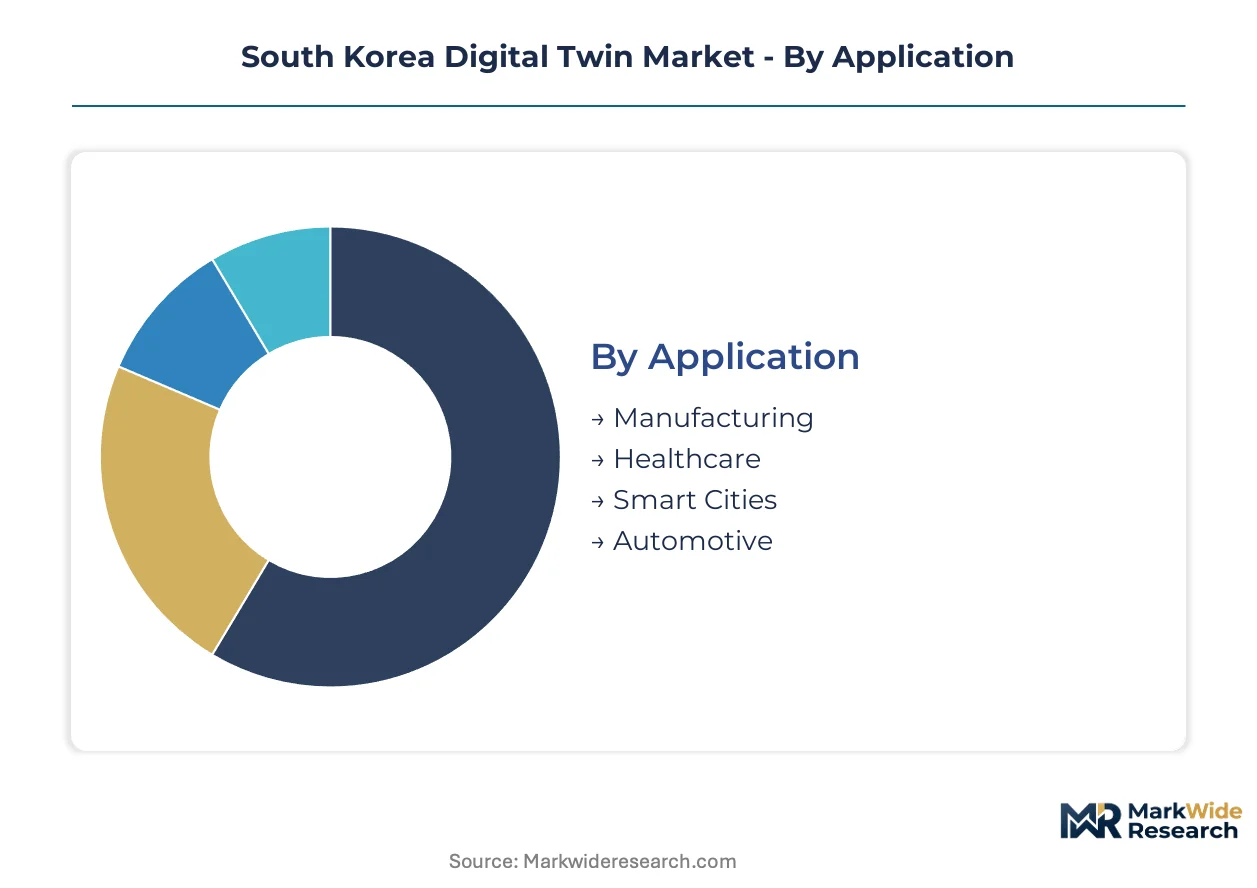
Digital twin deployments in South Korea fragment sharply across operational contexts, with precision manufacturing demanding nanometer-scale thermal fidelity while municipal infrastructure prioritizes interoperability over computational intensity. Segmentation logic must distinguish between asset-critical twins where downtime costs dominate and compliance-driven deployments where regulatory audit trails determine architecture.
Application:
Use-case spectrum spans deterministic process control in semiconductor fabrication through predictive urban traffic modeling, with each vertical imposing distinct latency, fidelity, and integration requirements on underlying infrastructure.
- Manufacturing:Process twins synchronize thermal, mechanical, and chemical state variables across semiconductor wafer processing, battery cell formation, and automotive assembly lines. Samsung and SK Hynix fabs in Giheung and Icheon anchor demand for sub-millisecond synchronization fidelity to maintain 3nm yield rates.
- Healthcare:Patient-specific organ modeling and hospital facility twins support surgical planning and pharmaceutical batch traceability under MFDS good manufacturing practice mandates. Seoul National University Hospital and Asan Medical Center pilot cardiac and orthopedic planning applications.
- Smart Cities:Urban digital twins integrate building information models with real-time traffic, energy grid, and emergency response systems. Songdo International Business District and Busan Eco-Delta Smart City serve as testbeds for municipal-scale deployment.
- Automotive:Vehicle lifecycle twins span design-phase crash simulation through connected car predictive maintenance. Hyundai Motor Group deploys production line twins in Ulsan and Asan plants alongside autonomous vehicle testing environments in Hwaseong.
Established volume favors Manufacturing; emerging adoption favors Smart Cities.
Technology:
Deployment architecture selection hinges on data sovereignty requirements against computational elasticity needs, with domestic cloud certification regimes constraining foreign platform participation.
- Cloud-Based:Scalable simulation workloads leverage Seoul-Incheon data center density for batch processing and non-critical analytics. Naver Cloud and KT Cloud capture sovereign infrastructure demand from pharmaceutical and public sector clients.
- Edge Computing:Sub-10 millisecond latency requirements for real-time process control drive on-premise GPU clusters and 5G network slicing deployments. KT and SK Telecom infrastructure supports mobile asset monitoring in construction and mining fleets.
- IoT Integration:Sensor fusion platforms aggregate vibration, thermal, and vision data streams into unified state representations. Legacy SCADA protocol fragmentation in Yeosu and Gwangyang petrochemical complexes impedes seamless integration.
- Simulation Software:Physics engines for computational fluid dynamics and finite element analysis form the computational core. Domestic vendors compete with Ansys and Siemens through specialized modules for Korean industrial equipment.
Cloud-Based deployments claim dominant share; Edge Computing climbs the fastest as latency-sensitive manufacturing expands.
End User:
Procurement authority patterns diverge between centralized IT divisions of chaebol conglomerates and decentralized operational budgets of municipal agencies and independent healthcare networks.
- Manufacturers:Heavy industry groups in Ulsan steel corridors and Gyeonggi electronics clusters pursue asset optimization under KOSHA safety mandates. Plant-level engineering managers increasingly control simulation software procurement independent of ERP contracts.
- Healthcare Providers:Tertiary hospitals and contract manufacturing organizations absorb MFDS traceability compliance costs through hybrid edge-cloud deployments. Domestic CMOs in Songdo and Incheon free economic zones retrofit faster than multinational subsidiaries.
- Urban Planners:Metropolitan governments in Seoul, Busan, and Sejong integrate building energy models with transportation and utility networks. Carbon accounting requirements under KEIT industrial efficiency incentives accelerate procurement cycles.
- Transportation Agencies:Korea Expressway Corporation and port authorities deploy infrastructure twins for predictive maintenance and traffic optimization. Busan container terminal automation presents untapped demand for maritime logistics integration.
Manufacturers dominate current procurement; Healthcare Providers gain share fastest as pharmaceutical traceability mandates tighten.
Delivery Model:
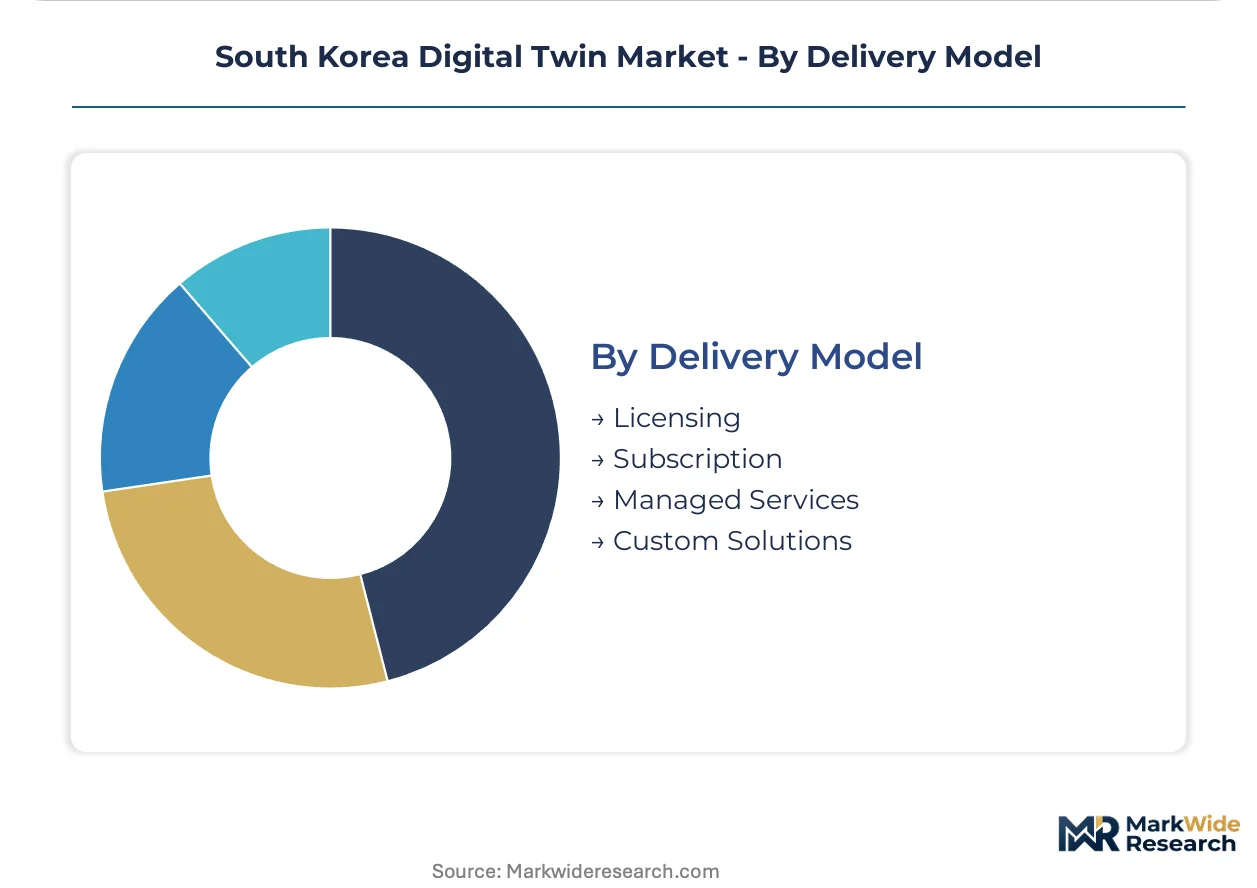
Commercial structure selection reflects client sophistication divergence between capital-constrained mid-market manufacturers and compliance-bound pharmaceutical multinationals.
- Licensing:Perpetual software licenses with maintenance contracts persist in large chaebol divisions with captive IT infrastructure and long depreciation cycles. Legacy on-premise vendors defend position through enterprise-wide agreements.
- Subscription:SaaS models compress entry barriers for mid-sized manufacturers in Daegu and Daejeon industrial zones. Asset-light leasing reconfigures competitive dynamics by eliminating upfront capital requirements.
- Managed Services:Outsourced twin operation and maintenance appeals to municipal agencies and healthcare networks lacking specialized simulation expertise. Vendor accountability for uptime and compliance outcomes shifts risk allocation.
- Custom Solutions:Bespoke development for unique process configurations or proprietary equipment integration commands premium pricing. Steel and petrochemical buyers in Pohang and Yeosu unbundle physics engines from manufacturing execution systems.
Subscription models capture emerging mid-market demand; Custom Solutions retain premium positioning in process-intensive verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
KEIT industrial efficiency incentives and MFDS pharmaceutical traceability mandates concentrate digital twin adoption in manufacturing-intensive sub-regions. Municipal smart city deployments in Sejong and Busan complement industrial demand.
Seoul Capital Area
Semiconductor fabrication precision requirements from Samsung and SK Hynix drive sub-millisecond synchronization fidelity demand. MFDS guidelines on pharmaceutical batch monitoring accelerate retrofitting of filling and packaging lines in Songdo and Incheon free economic zones. Cloud infrastructure from Naver Cloud and KT Cloud anchors sovereign data processing for healthcare and public sector clients.
Busan-Ulsan
Container terminal automation and steel manufacturing hazard detection create dual demand vectors. KOSHA predictive safety frameworks mandate real-time equipment monitoring in Ulsan steel corridors. Maritime logistics twins integrating crane kinematics with tidal simulation remain underdeveloped despite port infrastructure modernization timelines.
Daegu-Gyeongbuk
Mid-sized manufacturers in Daegu industrial zones adopt subscription-based simulation software to bypass capital-heavy licensing. Asset-light leasing models reconfigure competitive entry barriers for this segment. Physics engine procurement unbundles from enterprise resource planning contracts as plant-level engineering managers gain operational P&L authority.
Daejeon-Sejong
Government-led smart city pilot programs in Sejong test urban-scale digital twin integration. Metropolitan infrastructure models combine building energy systems with transportation and utility networks. KEIT carbon accounting incentives reward municipal agencies deploying energy-consumption tracking against Scope 1 and 2 reduction targets.
Gwangju-Honam
Petrochemical complexes in Yeosu and Gwangyang industrial zones pursue process optimization through custom physics engine development. Legacy SCADA protocol fragmentation impedes seamless IoT integration for synchronized twin fidelity. Heavy industry procurement committees now evaluate simulation software separately from manufacturing execution systems.
South Korea Digital Twin Market Competitive Landscape
Channel-controlling players compete with product-specialist players across deployment architecture and physics engine specialization. The market structure consolidates around telecommunications-integrated platforms and semiconductor-derived simulation services, with mid-tier SaaS entrants capturing subscription demand from capital-constrained manufacturers. Strategic archetypes span sovereign cloud operators, fabrication-captive service providers, and edge-computing infrastructure vendors. Dominant competitive moves include unbundling simulation software from ERP contracts and pivoting legacy on-premise vendors toward subscription delivery models.
Within the telecommunications-integrated tier, KT Corporation anchors edge computing platform development. Samsung Electronics exemplifies the fabrication-captive service archetype, leveraging semiconductor process expertise for precision manufacturing clients. Siemens and Robert Bosch GmbH occupy positions among industrial automation incumbents adapting physics engine portfolios for Korean regulatory compliance requirements.
| Leading Market Players |
|---|
| Korea Hydro & Nuclear Power |
| LG Electronics |
| Siemens |
| SK Hynix |
| Hyundai Motor Company |
| Robert Bosch GmbH |
| Samsung Electronics |
| KT Corporation |
| Naver Corporation |
| Others |
Pricing and Supply Chain Analysis
Single-source GPU cluster dependency from NVIDIA and AMD data center silicon determines both the premium spread for real-time physics simulation tiers and the geographic concentration of sovereign cloud infrastructure investments. Pricing stratification across certification-grade, standard, and economy levels reflects this upstream chokepoint, with MFDS-validated pharmaceutical deployments commanding substantial premiums over general manufacturing SaaS tiers.
Pricing Analysis
Certification level (MFDS-validated versus general manufacturing grade) creates the primary spread between subscription tiers. SaaS models dominate mid-market procurement, while perpetual licensing persists in chaebol divisions with captive IT infrastructure. Price differentiation stems from computational fidelity requirements and data sovereignty compliance depth. Cost compression in standard-tier edge computing subscriptions is intensifying because GPU memory pricing volatility feeds directly through to operational expenditure quotes. Municipal agencies and mid-sized manufacturers in Daegu industrial zones exhibit highest price sensitivity; semiconductor fabs in Giheung and Icheon demonstrate lowest sensitivity due to yield-loss economics.
Supply Chain Analysis
Upstream feedstock for digital twin infrastructure draws from Taiwan (TSMC advanced node GPUs), USA (NVIDIA data center silicon, Ansys/Siemens physics engines), and domestic South Korean sources (Samsung memory, SK Hynix HBM). Critical component dependencies include high-bandwidth memory modules, precision sensor arrays, and specialized CFD meshing software licenses. Single-source vulnerability concentrates in GPU accelerator supply chains subject to export control friction. Distribution runs through telecommunications-integrated platform vendors and direct relationships with physics engine specialists, bypassing traditional industrial automation distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's digital twin market sits in early-cycle expansion, with MFDS pharmaceutical traceability mandates and KOSHA predictive safety frameworks creating structural tailwinds that will compound through the decade.
For Market Incumbents: Pre-empt SaaS-native entrants by unbundling physics engines from legacy ERP contracts before plant-level engineering managers complete procurement authority decentralization. Accelerate sovereign cloud certification investments to defend position against Naver Cloud and KT Cloud domestic infrastructure advantages. Vertical integration into edge computing hardware assembly creates margin protection against GPU pricing volatility. For New Entrants and Emerging Players: Build out specialized maritime logistics twin capabilities for Busan container terminal automation, where incumbent coverage remains thin and port modernization timelines create immediate procurement windows. Target mid-sized manufacturers in Daegu-Gyeongbuk industrial corridors through asset-light subscription models that bypass capital-heavy licensing barriers. Lead with generative AI-powered surrogate modeling as the go-to-market wedge to compress sales cycles against established finite element preprocessing workflows. For Investors and Strategic Acquirers: MFDS good manufacturing practice enforcement reshapes the acquisition landscape by elevating compliance-validated platform providers above generalist simulation vendors. Position holdings for sustained viability through the projection horizon by targeting physics-informed neural network specialists with proven semiconductor fabrication deployments. Monitor KT and SK Telecom 5G-Advanced network slicing commercialization as the signal to watch for edge computing latency inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | MFDS and KOSHA compliance requirements elevate domestic infrastructure providers above foreign platform competitors. |
| Physics Engine Unbundling | Steel and petrochemical procurement committees now evaluate simulation software separately from manufacturing execution systems. |
| Generative AI Surrogate Modeling | Automotive stamping and battery formation lines in Hwaseong adopt these tools within compressed procurement cycles. |
| 5G-Advanced Edge Convergence | KT network slicing enables sub-10 millisecond latency for mobile asset twins in construction equipment fleets. |
| Carbon Accounting Integration | KEIT industrial efficiency incentives reward manufacturers deploying energy-consumption twins against Scope 1 and 2 targets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineering managers at chaebol manufacturing divisions, pharmaceutical compliance officers at Songdo CMOs, KT and SK Telecom network infrastructure planners, and physics engine product specialists at domestic simulation vendors. Secondary validation drew from MFDS regulatory filings, KEIT industrial efficiency program disclosures, hyperscaler capex announcements, and customs data on GPU cluster imports. Bottom-up deployment estimates across Seoul-Incheon, Busan-Ulsan, and Daegu-Gyeongbuk corridors were triangulated against top-down market sizing from sovereign cloud revenue disclosures.
Calibration across the analysis window employed segmented growth rate derivation by deployment architecture, application vertical, and end-user procurement authority pattern. Modeled dimensions included cloud versus edge infrastructure, manufacturing versus healthcare versus smart city use cases, and centralized chaebol IT versus decentralized plant-level purchasing. CAGRs were computed from installation base expansion rates and average revenue per deployment trends. Industry-specific forecast inputs incorporated semiconductor fabrication node transition timelines and KOSHA enforcement intensity scoring.
Stress conditions across GPU supply disruption scenarios, MFDS regulatory acceleration or delay profiles, and chaebol capital expenditure cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about physics engine vendor competitive dynamics and telecommunications infrastructure buildout pacing. Cross-checking against Naver Cloud and KT Cloud disclosed infrastructure capacity figures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital Twin in Construction Market
Digital Solutions
Data Broker Market
Digital Solutions
UK High Performance Computing Market
Digital Solutions
Canada ICT Market
Digital Solutions
Global Remote Monitoring and Management (RMM) Tools Market
Digital Solutions
Global Enterprise Metadata Management Market
Digital Solutions
Global Dock and Yard Management System Market
Digital Solutions
Europe Multichannel Order Management Market
Digital Solutions
Digital Marketing Software Market
Digital Solutions
Utility Cases Market
Digital Solutions
Online Home Service Market
Digital Solutions
Enterprise Mobility Market
Digital Solutions
Global Digital Experience Platform Market
Digital Solutions
Italy Digital Twin Market
Digital Solutions
Service Orchestration Market
Digital Solutions
European Digital Transaction Management Software Market