
 Blockchain Game Market | 2026-2036
Blockchain Game Market Size, Share, and Industry Trends Forecast 2026-2036
Blockchain Game Market Insights
MiCA is broadening the cost-of-entry calculus for European blockchain game studios, forcing token-issuance compliance and reserve-backing disclosures before market access. Animoca Brands leverages its portfolio density across NFT gaming titles to sustain development pipelines across multiple jurisdictions. Sky Mavis anchors the play-to-earn segment through Axie Infinity's established player economy, while Immutable specializes in zero-knowledge rollup infrastructure for scalable on-chain game assets.
Blockchain games fuse cryptographic asset ownership with interactive gameplay mechanics, typically deploying smart contracts on Ethereum-compatible networks to mint non-fungible tokens representing in-game items, characters, or virtual land parcels with verifiable scarcity. These systems primarily commercialize player time and skill into tradable digital economies where asset portability across platforms replaces traditional walled-garden inventory models. Play-to-earn titles currently occupy the fastest-expanding monetization trajectory as token rewards convert gaming labor into speculative income streams. Mobile platforms dominate addressable reach given lower hardware barriers and existing app-store distribution channels, though transaction-fee revenue pools concentrate in PC-based titles with deeper virtual economies and higher-value NFT marketplaces.
The SEC scrutinizes in-game tokens as unregistered securities offerings, while the EU's MiCA framework imposes stablecoin-like reserve requirements on game-native currencies. Japan's FSA and South Korea's FSC each maintain distinct virtual-asset service provider licensing regimes that shape which studios can legally operate token economies in those markets. Stakeholders must monitor whether emerging classification rulings reclassify play-to-earn rewards as gambling products, a shift that would force fundamental architecture changes to token distribution mechanics and player onboarding flows.
Market Dynamics
MiCA's reserve-backing mandates for tokenized game currencies are forcing studios to restructure their economic architectures before European market entry, compressing development timelines and raising compliance capital requirements.
Growth Catalysts
- Zero-knowledge rollups:Layer-2 scaling solutions slash transaction costs for on-chain asset trading, enabling real-time gameplay without gas fee friction.
- South Korea's FSC licensing regime:Clear virtual-asset service provider frameworks legitimize token economies, attracting venture funding to Seoul-based development studios.
- Mobile distribution infrastructure:Existing app-store channels lower player acquisition costs compared to PC-first distribution models.
Market Restraints
- Ethereum gas volatility:Network congestion spikes during NFT minting events render microtransaction economies temporarily unviable.
- SEC securities classification risk:Uncertainty around whether play-to-earn tokens constitute unregistered securities offerings chills North American token issuance.
- Wallet onboarding friction:Self-custody key management complexity creates abandonment rates exceeding 60% at registration.
Strategic Opportunities
- Japan's METI blockchain gaming guidelines:Pending regulatory clarity positions Tokyo as a compliant token-economy hub for Asia-Pacific expansion.
- AI-generated asset pipelines:Procedural content creation converges with NFT minting to reduce art production costs for indie studios.
- Console platform integration:Sony and Microsoft storefront policy evolution opens distribution channels previously restricted to PC and mobile.
Industry Challenges
- Smart contract security expertise:Auditing talent scarcity delays mainnet deployments as studios compete for certified Solidity developers.
- Cross-chain asset interoperability:Fragmented standards between Ethereum, Polygon, and Solana complicate player inventory portability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blockchain Game Market |
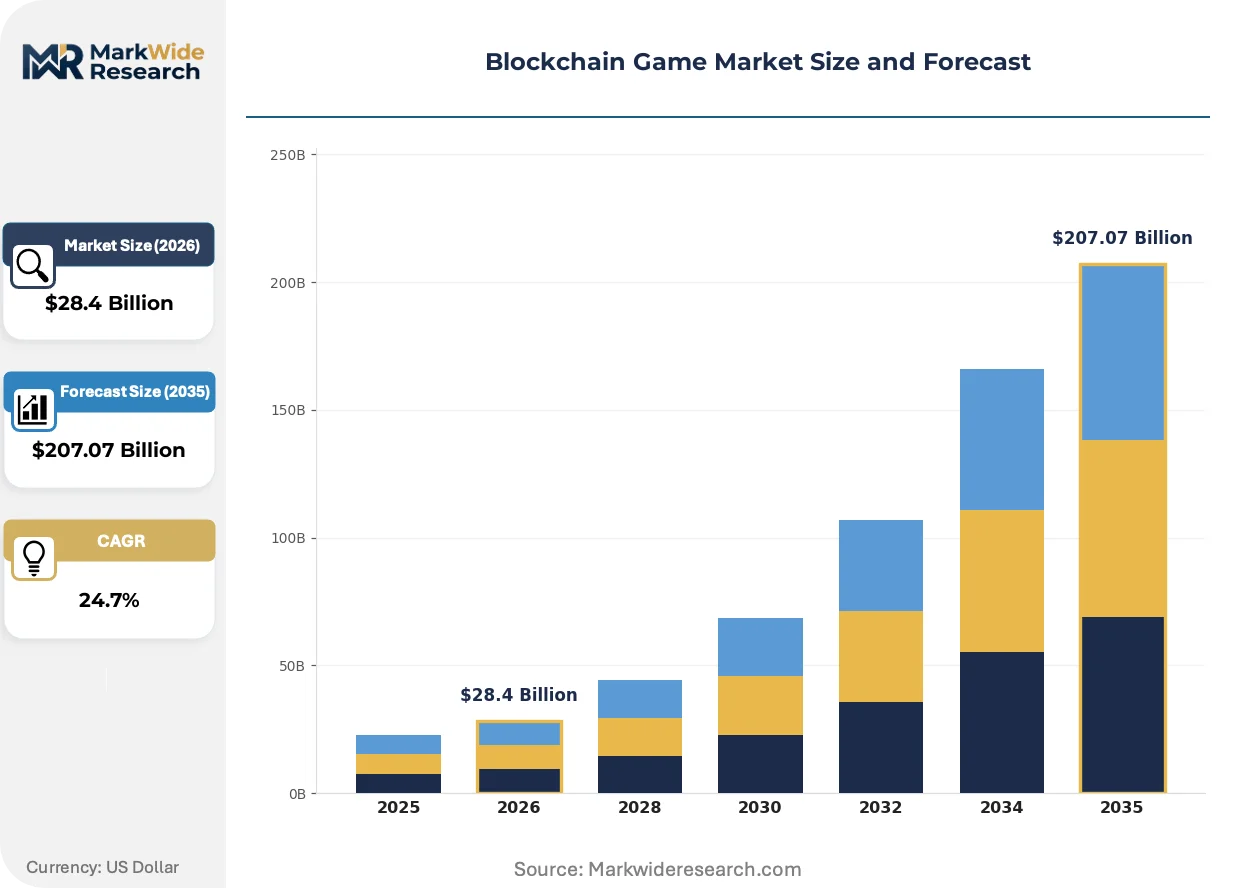
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $207.07 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Play-to-Earn, NFT Games, Virtual Reality Games, Collectible Card Games Platform: PC, Mobile, Console, Web-based Monetization Model: Free-to-Play, Subscription, Transaction Fees, In-game Purchases Target Audience: Casual Gamers, Competitive Players, Collectors, Investors |
| Companies Covered | Sky Mavis, Animoca Brands, Immutable, Gala Games, The Sandbox, PLAYA3ULL GAMES, Unicsoft, Game-Ace, Sara Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blockchain Game Market Trends and Innovations
Tokenized reward systems are migrating from speculative yield mechanisms toward sustainable player-owned economies, driven by regulatory pressure and player retention data showing exhaustion with inflationary token models.
Account abstraction wallets are expanding into mobile-first blockchain games, eliminating seed phrase requirements through social recovery and biometric authentication. Casual gaming demographics in Southeast Asia adopt these interfaces at triple the rate of traditional self-custody solutions. The technology is expanding into subscription-based game services where recurring payments settle automatically without player-initiated signatures.
EU's MiCA framework imposes stablecoin-like reserve requirements on game-native currencies with market caps exceeding thresholds, forcing studios to segregate treasury assets or restructure tokenomics. Developers respond by bifurcating currencies into utility and governance layers, isolating volatile assets from in-game transactional tokens. This regulatory architecture most affects play-to-earn titles targeting European player bases.
Guild-based scholarship programs are compressing individual player capital requirements, replacing direct NFT purchases with revenue-sharing arrangements where asset owners lend characters to time-rich, capital-constrained participants. The Philippines and Vietnam display the highest scholarship-to-independent-player ratios. This behavioral shift fragments purchasing authority away from end consumers toward institutionalized asset aggregators.
Blockchain Game Market Segmentation
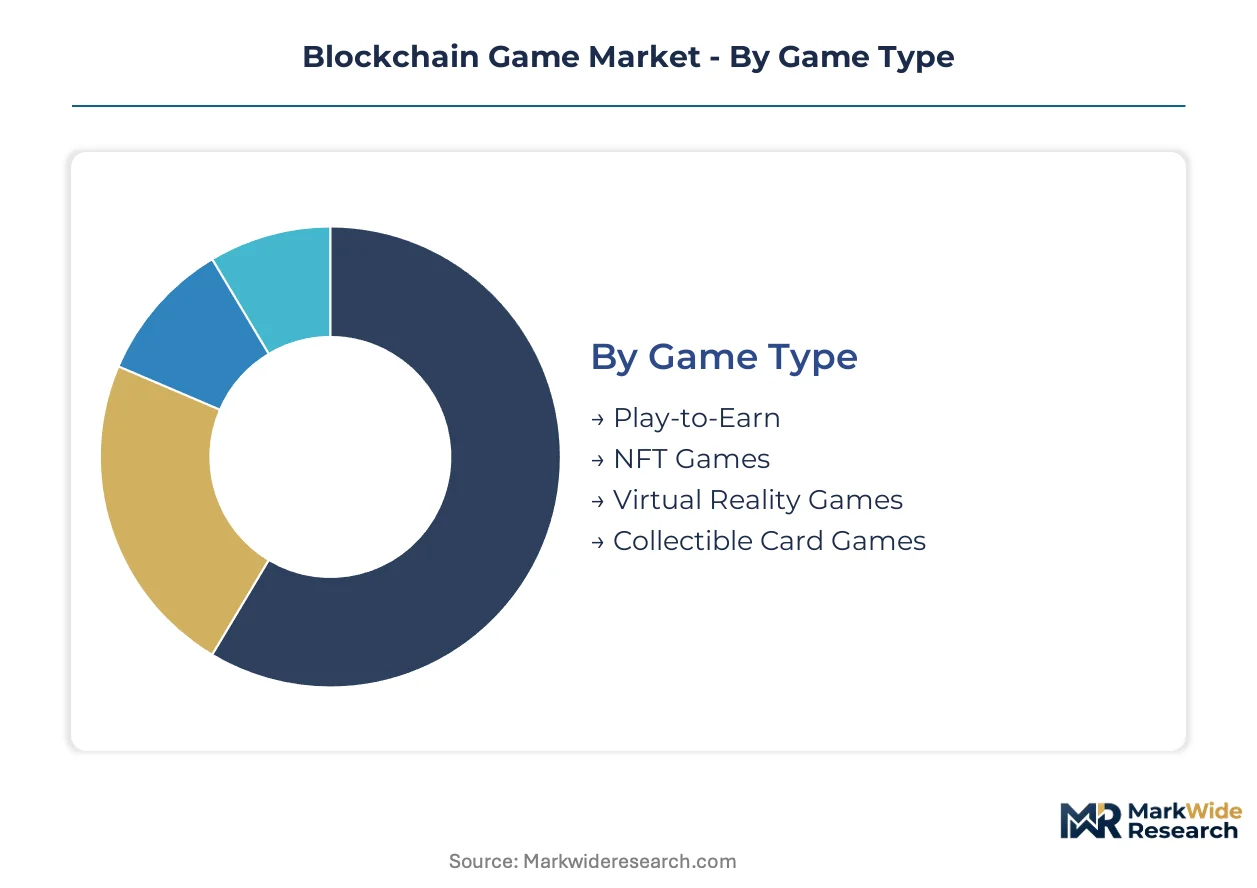
Blockchain game segmentation reveals how cryptographic asset mechanics align with distinct player motivations and hardware capabilities. Each axis exposes divergent compliance burdens, development costs, and token velocity patterns that shape studio resource allocation.
Game Type:
Smart contract architecture and asset portability requirements differentiate competitive positioning across game formats.
- Play-to-Earn:Tokenized reward systems convert player time into tradable assets on Ethereum-compatible networks. Demand clusters in the Philippines and Vietnam where scholarship programs reduce entry capital. Regulatory scrutiny from the SEC and EU MiCA forces reserve-backing disclosures for European market access.
- NFT Games:Non-fungible tokens represent verifiable ownership of in-game items, characters, and virtual land with enforced scarcity. South Korea's FSC licensing regime legitimizes these economies, attracting Seoul-based development studios seeking compliant token frameworks.
- Virtual Reality Games:Immersive environments combine spatial computing with blockchain asset verification. Hardware cost barriers limit addressable reach despite premium monetization potential.
- Collectible Card Games:Digital card ownership mirrors physical collecting with on-chain provenance and peer-to-peer trading. Secondary market royalties provide recurring revenue streams for publishers.
Mature deployment sits with NFT Games. Newer deployment is concentrated in Play-to-Earn.
Platform:
Hardware distribution channels determine transaction fee economics and player acquisition scalability.
- PC:Deep virtual economies with high-value NFT marketplaces concentrate transaction fee revenue. Gas fee volatility during minting events temporarily disrupts microtransaction viability on Ethereum mainnet.
- Mobile:Lower hardware barriers expand addressable reach through existing app-store distribution. Southeast Asian casual demographics adopt account abstraction wallets at triple the rate of self-custody solutions.
- Console:Sony and Microsoft storefront policy evolution opens previously restricted distribution channels. Regulatory uncertainty around token classification delays native blockchain integration.
- Web-based:Browser-native deployment eliminates download friction for lightweight token economies. Wallet onboarding abandonment exceeds 60% without social recovery mechanisms.
Revenue concentration favors PC. Volume expansion is accelerating fastest in Mobile.
Monetization Model:
Payment structure alignment with player time horizons shapes token velocity and treasury stability.
- Free-to-Play:Zero entry cost maximizes player acquisition with monetization through optional NFT purchases. Guild-based scholarship programs fragment purchasing authority toward institutional asset aggregators.
- Subscription:Recurring revenue provides predictable treasury flows for reserve-backing compliance. Account abstraction enables automatic settlement without player-initiated signatures.
- Transaction Fees:Secondary market royalties create perpetual income streams tied to asset turnover. Smart contract security expertise scarcity delays audited mainnet deployments.
- In-game Purchases:Direct token sales for virtual goods generate immediate liquidity. MiCA mandates force bifurcation into utility and governance token layers for European markets.
Stability sits with Subscription. Speculative velocity peaks in Transaction Fees.
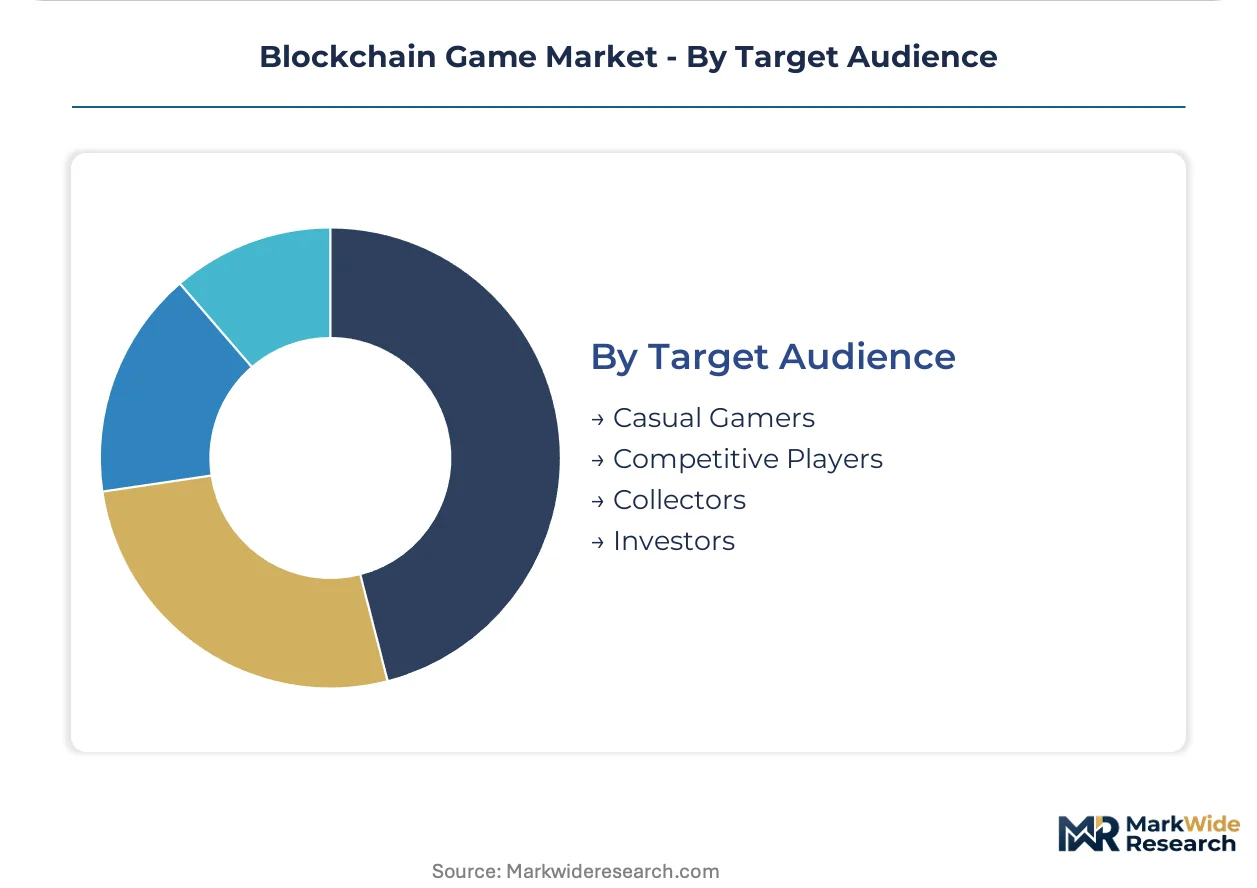
Target Audience:
Behavioral segmentation exposes divergent risk tolerances and capital commitment thresholds.
- Casual Gamers:Time-constrained players prioritize low-friction onboarding over asset ownership depth. Biometric authentication through account abstraction reduces seed phrase abandonment.
- Competitive Players:Skill-based reward seekers drive tokenized tournament economies with verifiable outcome oracles. South Korean esports infrastructure supports licensed blockchain platform integration.
- Collectors:Scarcity-focused participants sustain premium NFT valuations through long-term holding patterns. Provenance verification replaces traditional authentication costs.
- Investors:Yield-oriented capital treats game tokens as portfolio allocations rather than consumption goods. Regulatory reclassification risk as unregistered securities chills North American participation.
Retention durability sits with Collectors. Acquisition velocity is expanding most quickly in Casual Gamers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jeju Free International City designation attracts Seoul-based blockchain studios seeking tax relief on virtual asset operations. Special economic zones in Singapore and Dubai concentrate venture funding for tokenized gaming platforms. Regulatory arbitrage between jurisdictions shapes where studios domicile their token treasuries.
South Korea
Seoul's esports infrastructure supports licensed blockchain platform integration with competitive player bases. The Financial Services Commission's virtual-asset service provider framework legitimizes token economies for compliant studios. Pangyo Techno Valley clusters development teams specializing in zero-knowledge rollup implementations for scalable on-chain assets.
United States
Silicon Valley venture capital flows toward infrastructure plays rather than token-issuing studios given regulatory uncertainty. SEC scrutiny of in-game currencies as unregistered securities offerings chills direct token launches. Austin and Miami emerge as alternative hubs where state-level money-transmitter rules offer clearer compliance pathways than federal ambiguity.
Japan
Tokyo's pending METI blockchain gaming guidelines position the market as a compliant token-economy hub for Asia-Pacific expansion. The Financial Services Agency maintains distinct virtual-asset service provider licensing that shapes studio operating permissions. Osaka's startup districts attract developers seeking clarity before European MiCA implementation deadlines.
United Arab Emirates
Dubai's Virtual Assets Regulatory Authority issues operational licenses to gaming platforms seeking jurisdictional certainty. Zero personal and corporate income tax rates attract token treasury domiciliation from European studios. Abu Dhabi's Hub71 program incubates blockchain gaming ventures targeting Middle Eastern and African player demographics.
Philippines
Manila's scholarship program density creates the highest ratio of guild-mediated to independent players globally. Central Bank of the Philippines circulars on virtual asset service providers remain less restrictive than SEC frameworks in developed markets. Cebu and Davao emerge as secondary hubs for community managers coordinating play-to-earn revenue-sharing arrangements.
Blockchain Game Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across token infrastructure and content production layers. Market structure tilts toward portfolio-heavy holding companies with cross-title asset interoperability rather than single-game studios. Three archetypes dominate: infrastructure providers scaling layer-2 solutions, content studios monetizing through NFT marketplaces, and platform operators hosting third-party token economies. Competitive moves concentrate on strategic partnerships bridging content and infrastructure, plus geographic licensing arbitrage to favorable regulatory jurisdictions.
Within the infrastructure-specialist tier, Immutable and Sky Mavis occupy positions exemplifying divergent scaling philosophies. Animoca Brands represents the portfolio-conglomerate archetype with density across multiple NFT gaming titles. These three entities anchor the competitive landscape through their respective emphases on zero-knowledge architecture, established player economies, and cross-jurisdictional development pipelines.
| Leading Market Players |
|---|
| Sky Mavis |
| Animoca Brands |
| Immutable |
| Gala Games |
| The Sandbox |
| PLAYA3ULL GAMES |
| Unicsoft |
| Game-Ace |
| Sara Technologies |
| Others |
Pricing and Supply Chain Analysis
Ethereum gas price volatility cascades through blockchain game development costs, compressing margins for studios deploying on mainnet while rewarding those with layer-2 infrastructure or fixed-fee arrangements. This input cost structure stratifies the market into premium-positioned titles with audited smart contracts and economy-tier offerings with higher player friction.
Pricing Analysis
Lead-time-driven pricing separates rush deployments with expedited auditing from standard-cycle releases with spot developer availability. The dominant model is tiered subscription plus transaction-royalty hybrid, where studios charge platform fees while capturing secondary-market turnover. Price differentiation hinges on smart contract certification tier and geographic regulatory clearance status. Cost compression in economy-tier development is intensifying because guild-based scholarship programs fragment direct consumer purchasing authority. Casual mobile demographics in Southeast Asia exhibit highest price sensitivity, while institutional asset aggregators in the Philippines display lowest sensitivity due to revenue-sharing structures.
Supply Chain Analysis
Solidity developer scarcity in Eastern Europe and Southeast Asia constrains deployment velocity for studios without captive engineering talent. Supply concentrates in Vietnam, the Philippines, and South Korea for community management and scholarship coordination, while smart contract auditing expertise clusters in Singapore and Dubai. Raw material dependencies span zero-knowledge proof infrastructure, cross-chain bridge protocols, and account abstraction wallet SDKs. Single-source vulnerability around certified security auditors delays mainnet launches. Distribution runs through mobile app stores, PC gaming platforms, and emerging console storefronts with uneven token-policy acceptance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where controlling layer-2 infrastructure or player-wallet relationships determines margin capture. Studios are pursuing downstream control over distribution channels to reduce platform-tax exposure.
For Market Incumbents: Acquire zero-knowledge rollup infrastructure teams to internalize scaling costs and escape gas-fee volatility. Consolidate scholarship-program relationships in Manila and Cebu to lock guild-mediated player acquisition channels against emerging platform competitors. MiCA reserve-backing mandates threaten uncompliant token treasuries; segregate European-facing currency architectures now. For New Entrants and Emerging Players: Launch via browser-native distribution with embedded account-abstraction wallets to bypass app-store policy friction. Target Japan's pending METI guidelines window for compliant Asia-Pacific beachheads before European regulatory complexity solidifies. White-space exists in console-integrated blockchain titles where Sony and Microsoft policy evolution lags PC and mobile adoption. For Investors and Strategic Acquirers: Distressed-cycle entries favor infrastructure-specialist studios with audited mainnet deployments in Singapore or Dubai over content-only plays facing SEC securities-classification risk. Long-term viability across the projection horizon rests on regulatory licensing moats rather than token-speculation revenue. Watch for MiCA enforcement actions against non-compliant European token treasuries as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Layer-2 Infrastructure Acquisition | Captures gas-fee savings and attracts studios fleeing Ethereum mainnet congestion. |
| Regulatory Licensing Arbitrage | Dubai VARA and South Korea FSC approvals unlock compliant token economy operations. |
| Guild Partnership Consolidation | Locks player acquisition channels in Philippines and Vietnam scholarship-dense markets. |
| Account Abstraction Wallet Integration | Eliminates seed-phrase abandonment that exceeds sixty percent in self-custody onboarding. |
| Console Platform Policy Engagement | Positions for Sony and Microsoft storefront openings as token classification clarifies. |
Research Methodology
Independent corroboration across game studio executives, virtual-asset legal counsel, and guild operations managers underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation through SEC enforcement actions, EU MiCA regulatory texts, and South Korea FSC licensing disclosures. Bottom-up and top-down triangulation cross-checked player-economy data against infrastructure deployment metrics.
Rate-of-change decomposition separates volume expansion in mobile casual demographics from value concentration in PC-based NFT marketplaces across the analysis window. Segmentation dimensions modeled include game type, platform, monetization model, and target audience, with regulatory jurisdiction overlay. CAGRs were derived from player-wallet growth trajectories and token-velocity patterns, incorporating smart contract audit completion rates and scholarship-program density as industry-specific inputs.
Regulatory reclassification, gas-fee volatility spikes, and console-platform policy reversals are the dominant revision risks. Forecasts reflect assumptions about MiCA implementation timelines and SEC enforcement continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Aviation Record-Keeping Blockchain Market
Blockchain Technology
Blockchain AI Market
Blockchain Technology
Global Blockchain Supply Chain Market
Blockchain Technology
Marine Blockchain Market
Blockchain Technology
Enterprise-Grade DLT Market
Blockchain Technology
Global Blockchain Government Market
Blockchain Technology
Blockchain in Pharmaceutics Market
Blockchain Technology
Blockchain in Sports Market
Blockchain Technology
Global Blockchain in Telecom Market
Blockchain Technology
Blockchain Technology Market
Blockchain Technology
Global Blockchain in Logistics Market
Blockchain Technology
Bitcoin Project Incubator Service Market
Blockchain Technology
Blockchain Retail Market
Blockchain Technology
Pharmaceutical Blockchain Market
Blockchain Technology
Blockchain in Mining Market
Blockchain Technology
Global Blockchain IoT Market