
 Blockchain in Aviation Market | 2026-2036
Blockchain in Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
Blockchain in Aviation Market Outlook
Buyer concentration among full-service carriers is shifting as low-cost airlines and ground handling cooperatives enter blockchain procurement. International Business Machines Corporation leverages enterprise-grade distributed ledger architectures to anchor its position in airline consortium networks. SITA competes through aviation-specific middleware that bridges legacy passenger service systems with immutable record layers. Zamna Technologies specializes in identity verification protocols that reduce document fraud at check-in gates.
Blockchain in Aviation refers to cryptographically linked distributed databases that timestamp maintenance events, passenger identities, and cargo manifests across peer-to-peer networks without central authority. The technology employs consensus algorithms such as proof-of-authority to validate transactions among MRO shops, lessors, and regulators in under three seconds per block. Smart Contracts automate escrow payments between airlines and parts suppliers when IoT sensors confirm delivery conditions. Private Blockchain deployments dominate current airline budgets because carriers restrict node access to vetted maintenance partners and national aviation authorities.
The FAA mandates airworthiness documentation retention under Part 91, Part 121, and Part 135, creating compliance demand for tamper-resistant digital logs. EASA's continuing airworthiness regulation and the UAE's GCAA digital transformation framework push European and Gulf operators toward standardized ledger formats. Stakeholders must evaluate whether hybrid blockchain architectures can satisfy both passenger privacy laws and cross-border cargo transparency requirements without fragmenting network interoperability.
Market Dynamics
The FAA's Part 43 digital recordkeeping modernization is forcing U.S. operators to replace paper-based maintenance logs with cryptographically verifiable ledgers, creating immediate procurement pressure for compliant distributed ledger infrastructure.
Growth Catalysts
- UAE GCAA Digital Transformation:Dubai's aviation free zones attract ledger-technology pilot programs that validate cross-border component tracking protocols.
- IoT Sensor Convergence:Smart contracts automate escrow payments between airlines and parts suppliers when delivery conditions are confirmed.
- EASA Continuing Airworthiness Mandates:European operators face standardized ledger format requirements that accelerate fleet-wide blockchain deployment.
Market Restraints
- Legacy System Integration Costs:Airlines must bridge immutable record layers with decades-old passenger service systems, inflating implementation budgets.
- Private Blockchain Vendor Concentration:Node access restrictions to vetted maintenance partners limit supplier choice and negotiating leverage.
- Cross-Border Data Friction:Passenger privacy laws in the European Union conflict with cargo transparency requirements, fragmenting network interoperability.
Strategic Opportunities
- Ground Handling Cooperatives:Low-cost airlines and regional handlers represent underpenetrated buyers entering blockchain procurement for the first time.
- Proof-of-Authority Consensus:MRO shops, lessors, and regulators validate transactions in under three seconds per block, opening real-time settlement applications.
- India PLI Scheme Alignment:Component provenance tracking for MRO service providers qualifies for production-linked incentives in aviation manufacturing.
Industry Challenges
- Distributed Ledger Talent Scarcity:Aviation-specific middleware development requires engineers fluent in both cryptographic protocols and airworthiness regulations.
- Hybrid Architecture Certification:Stakeholders must demonstrate that mixed public-private deployments satisfy multiple national aviation authorities simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blockchain in Aviation Market |
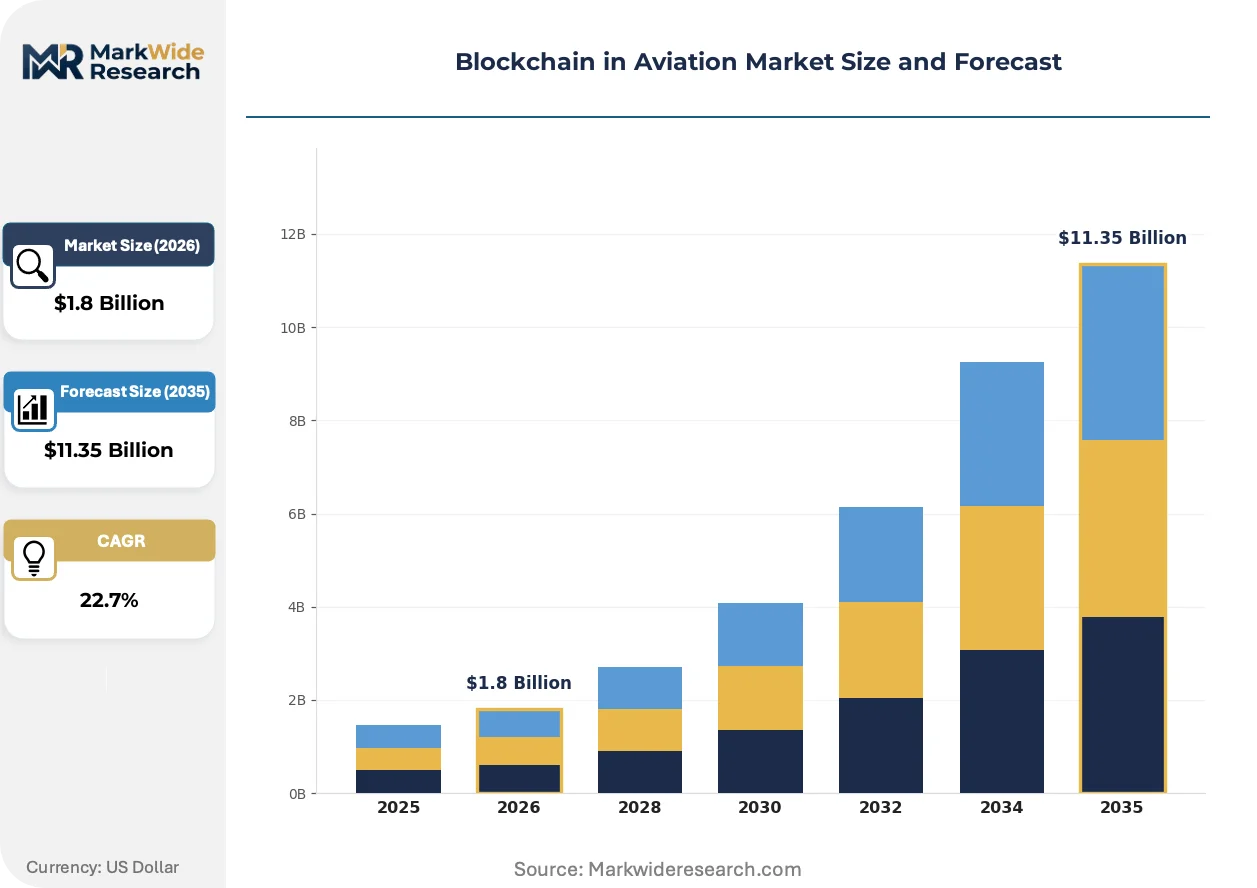
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Contracts, Identity Management, Data Storage, Secure Transactions Application: Flight Logistics, Ticketing Systems, Maintenance Records, Cargo Tracking Technology: Public Blockchain, Private Blockchain, Consortium Blockchain, Hybrid Blockchain End User: Airlines, Airports, Ground Handling Services, Regulatory Authorities |
| Companies Covered | Aeron Labs, Zamna Technologies, International Business Machines Corporation, SITA, Winding Tree, Microsoft Corporation, LeewayHertz, Moog Inc., Infosys Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blockchain in Aviation Market Strategic Shifts
Aviation blockchain is pivoting from experimental pilots to operational infrastructure as consensus mechanisms mature and regulatory deadlines harden. Three developments are compressing implementation timelines and reshaping vendor selection criteria.
Smart contracts with embedded IoT oracles are electrifying maintenance payment workflows by triggering automatic settlement when sensor data confirms part delivery. Full-service carriers and MRO providers are deploying these systems across engine overhaul contracts. The technology is electrifying traditional 90-day payment cycles into near-instantaneous settlement, compressing working capital requirements for suppliers.
EASA's continuing airworthiness regulation now explicitly references tamper-resistant digital logs as acceptable compliance evidence. European operators must restructure record retention systems before audit cycles renew. Lessors with mixed EU-U.S. fleets face the steepest reconfiguration burden as they harmonize documentation formats across regulatory jurisdictions.
Buyer concentration patterns are fragmenting as low-cost airlines bypass legacy procurement consortiums and source blockchain middleware directly. Regional carriers in the Middle East and Southeast Asia are negotiating standalone contracts rather than joining airline alliance networks. This disintermediation is most visible in the United Arab Emirates, where Dubai-based handlers operate independent node infrastructure outside global airline group frameworks.
Blockchain in Aviation Market Segmentation
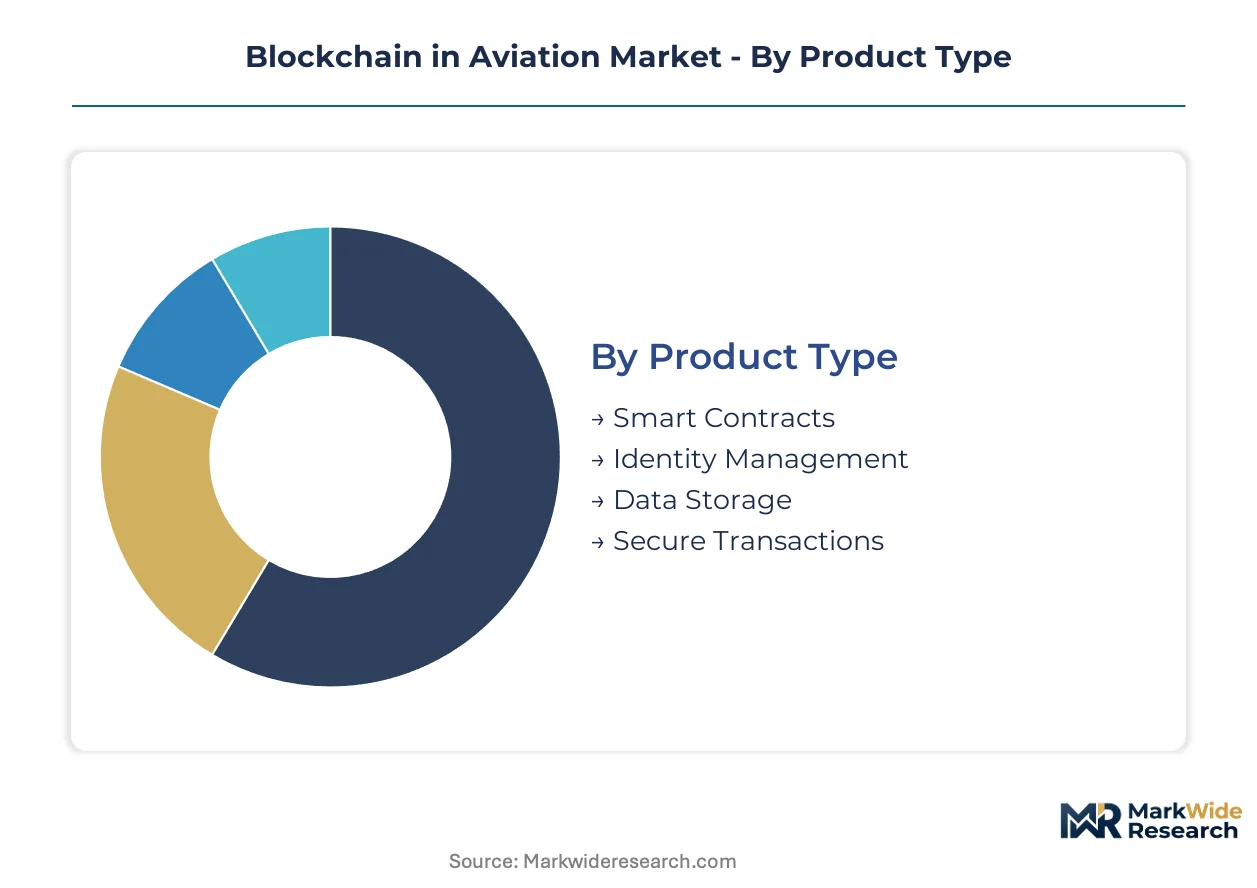
Blockchain deployment in aviation fragments across four structural axes that determine procurement priorities and integration complexity. Each segmentation layer imposes distinct capital requirements, regulatory exposure, and interoperability demands on operators and vendors alike.
Product Type:
Capital intensity varies sharply across product categories, with infrastructure-heavy segments demanding multi-year deployment cycles while software-native offerings compress implementation timelines.
- Smart Contracts:Self-executing code protocols automate escrow releases and maintenance payment triggers when IoT sensors verify delivery conditions. Airlines in the United Arab Emirates deploy these most aggressively for engine overhaul contracts, cutting supplier payment cycles from ninety days to near-instantaneous settlement.
- Identity Management:Cryptographic credential systems reduce document fraud at check-in gates by binding biometric data to immutable ledger entries. Low-cost carriers across Southeast Asia prioritize this segment to bypass legacy passenger service system upgrades.
- Data Storage:Distributed archival systems timestamp maintenance events across peer-to-peer networks without central authority. MRO shops favor tamper-resistant logs for FAA Part 43 compliance.
- Secure Transactions:Encrypted payment rails connect airlines with parts suppliers across jurisdictional boundaries. Ground handling cooperatives adopt these for real-time settlement with limited IT infrastructure.
Most installed capacity flows through Smart Contracts. Expansion is steepest in Identity Management.
Application:
Application segments map directly to operational workflows where regulatory deadlines and cost pressures intersect most acutely.
- Maintenance Records:Cryptographically verifiable ledgers replace paper-based airworthiness documentation under EASA continuing airworthiness mandates. European operators with mixed EU-U.S. fleets face the steepest reconfiguration burden as they harmonize formats across jurisdictions.
- Cargo Tracking:Immutable manifest records resolve cross-border transparency requirements that conflict with passenger privacy laws in the European Union. Dubai's aviation free zones pilot these protocols for pharmaceutical and high-value shipments.
- Flight Logistics:Distributed coordination systems synchronize ground handling, fueling, and slot allocation across independent node operators. Regional carriers in the Middle East negotiate standalone contracts outside airline alliance frameworks.
- Ticketing Systems:Tokenized inventory management reduces fraud and enables interline settlement without clearinghouse intermediaries. Full-service carriers with legacy reservation architectures face the highest integration costs.
Deployment density concentrates in Maintenance Records. Cargo Tracking climbs the fastest as customs authorities mandate provenance verification.
Technology:
Technology selection determines network governance models and the breadth of participant access permitted on the ledger.
- Private Blockchain:Restricted node access limits validation to vetted maintenance partners and national aviation authorities. Current airline budgets concentrate here due to compliance predictability and data sovereignty control.
- Consortium Blockchain:Multi-party governance structures distribute infrastructure costs across airline alliances and MRO networks. SITA leverages this architecture to bridge legacy passenger service systems with immutable record layers.
- Hybrid Blockchain:Mixed public-private deployments attempt to satisfy both passenger privacy laws and cargo transparency requirements. Stakeholders must demonstrate simultaneous certification to multiple national aviation authorities.
- Public Blockchain:Permissionless validation offers lowest infrastructure costs but exposes transaction data to unrestricted visibility. Limited adoption among regulated operators due to audit trail confidentiality requirements.
Private Blockchain absorbs the majority of current procurement spend. Hybrid Blockchain gains share fastest as cross-border use cases proliferate.
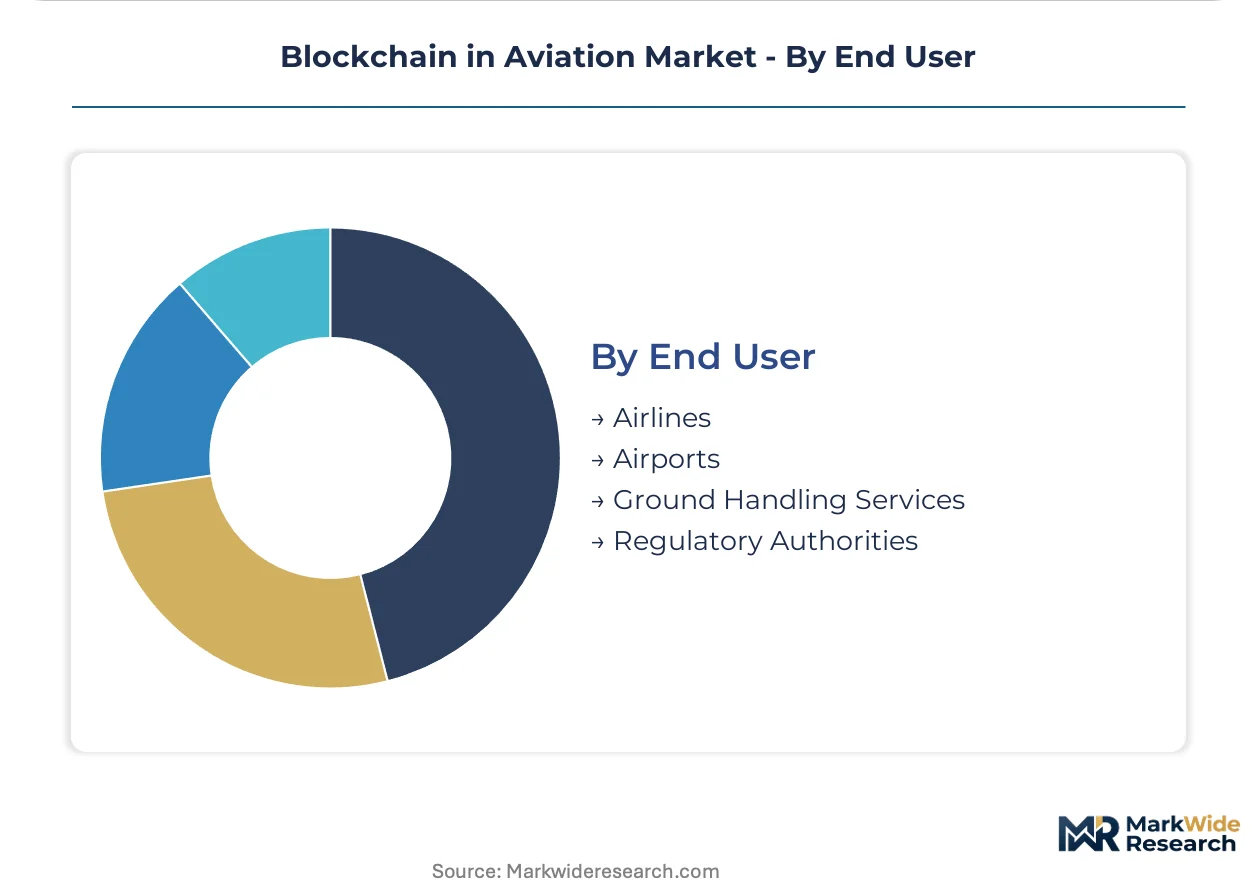
End User:
End user categories reflect divergent purchasing authority and technical sophistication across the aviation value chain.
- Airlines:Fleet operators drive demand for integrated platforms spanning maintenance, ticketing, and cargo functions. Full-service carriers historically dominated procurement, though low-cost airlines now enter blockchain sourcing directly.
- Airports:Terminal operators deploy identity verification and baggage tracking systems to reduce congestion and improve passenger throughput. Dubai International Airport operates independent node infrastructure outside global airline group frameworks.
- Ground Handling Services:Regional handlers represent underpenetrated buyers entering procurement for the first time. Limited IT budgets favor lightweight middleware over enterprise-grade distributed ledger architectures.
- Regulatory Authorities:National aviation bodies specify ledger formats and validation standards that shape vendor product roadmaps. The FAA's Part 43 digital recordkeeping modernization and EASA's continuing airworthiness regulation create compliance-driven demand.
Airlines command the largest share of installed systems. Ground Handling Services represent the most rapidly expanding buyer category.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Arab Emirates outpaces Germany in aviation blockchain deployment velocity, while the United States and United Kingdom concentrate regulatory innovation. China and India represent emerging procurement frontiers with distinct policy architectures.
United Arab Emirates
Dubai's aviation free zones attract ledger-technology pilot programs for component provenance tracking. The UAE's GCAA digital transformation framework mandates tamper-resistant documentation standards for MRO service providers. Abu Dhabi International Airport hosts independent node infrastructure validating cross-border cargo manifests.
United States
Full-service carriers and regional operators face immediate procurement pressure for compliant distributed ledger infrastructure. The FAA's Part 43 digital recordkeeping modernization forces replacement of paper-based maintenance logs with cryptographically verifiable systems. Dallas-Fort Worth and Atlanta metropolitan clusters concentrate MRO blockchain deployment for engine overhaul contracts.
Germany
European operators with mixed EU-U.S. fleets face steep reconfiguration burdens harmonizing documentation formats. EASA's continuing airworthiness regulation explicitly references tamper-resistant digital logs as acceptable compliance evidence. Hamburg and Munich aviation hubs pilot hybrid blockchain architectures for lessor fleet management.
United Kingdom
Low-cost carriers prioritize identity management protocols to bypass legacy passenger service system upgrades. The country's national aviation regulator aligns with EASA standards while retaining distinct certification pathways for distributed ledger vendors. London Heathrow operates consortium blockchain node infrastructure bridging airline alliance networks.
India
Component provenance tracking for MRO service providers qualifies under the PLI scheme for aviation manufacturing incentives. The country's national aviation regulator develops localized ledger format standards for domestic carrier compliance. Bangalore and Hyderabad technology corridors host middleware development centers for cryptographic protocol integration.
Blockchain in Aviation Market Competitive Environment
United States technology conglomerates anchor one tier; European aviation-specialist firms hold middleware and identity verification positions. Vendor concentration remains moderate with enterprise software incumbents competing against sector-native developers. Two strategic archetypes dominate: infrastructure-scale platform providers and compliance-focused vertical specialists. Dominant competitive moves include strategic partnerships with airline consortiums and technology licensing agreements with MRO networks.
Within the enterprise platform tier, International Business Machines Corporation and Microsoft Corporation occupy positions emphasizing distributed ledger infrastructure for regulated industries. SITA exemplifies the aviation-native archetype, bridging legacy passenger service systems with immutable record layers. Zamna Technologies represents the identity verification specialization, reducing document fraud through cryptographic credential protocols.
| Leading Market Players |
|---|
| Aeron Labs |
| Zamna Technologies |
| International Business Machines Corporation |
| SITA |
| Winding Tree |
| Microsoft Corporation |
| LeewayHertz |
| Moog Inc. |
| Infosys Limited |
| Others |
Value Chain & Pricing Dynamics
Proof-of-authority consensus migration to sub-three-second validation blocks simultaneously compresses infrastructure operating costs and concentrates node operator selection among certified MRO shops and national aviation authorities. This technical transition rewards early standardization investments while penalizing carriers locked into legacy middleware architectures.
Pricing Analysis
Capacity additions in the United Arab Emirates are reshaping price floors for private blockchain deployments as Dubai's aviation free zones attract competing ledger-technology pilot programs. Pricing stratifies across enterprise-grade distributed ledger architectures, aviation-specific middleware, and lightweight identity verification protocols. Cost compression in middleware tiers is intensifying because IBM and Microsoft enterprise platforms compete directly with sector-native developers like SITA. Ground handling cooperatives exhibit highest price sensitivity due to limited IT budgets, while full-service carriers demonstrate lowest sensitivity given compliance-driven procurement mandates.
Supply Chain Analysis
Refurbishment flows for legacy passenger service system components create secondary demand channels as airlines bridge decades-old architectures with immutable record layers. Supply concentrates in the United States, Germany, and the United Arab Emirates where FAA Part 43 modernization, EASA continuing airworthiness mandates, and GCAA digital transformation frameworks drive procurement. Component provenance tracking draws from cryptographic protocol libraries, IoT sensor hardware, and aviation-certified cloud infrastructure. Single-source vulnerability persists in middleware development talent pools concentrated in Bangalore and Hyderabad technology corridors. Distribution runs through airline consortium networks, MRO shop partnerships, and direct procurement from national aviation authority pilot programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blockchain in aviation market functions as a stable compounder anchored by regulatory deadline hardening across FAA, EASA, and GCAA jurisdictions that mandates fleet-wide distributed ledger deployment regardless of macroeconomic cycles.
For Market Incumbents: Deploy certification investment to lock in preferred vendor status with national aviation authorities before hybrid blockchain architectures require simultaneous multi-jurisdiction approval. Incumbents must backward integrate into IoT sensor oracle development to control smart contract trigger infrastructure and defend against middleware disintermediation by low-cost carriers sourcing directly from specialized developers. For New Entrants and Emerging Players: MRO service providers in India represent the most penetrable buyer segment as PLI scheme alignment for component provenance tracking creates first-mover subsidy capture opportunities. New entrants should target ground handling cooperatives in Southeast Asia with lightweight identity verification protocols that bypass legacy passenger service system upgrade costs, using channel partnerships with regional aviation technology distributors as the primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among aviation-native middleware developers bridging legacy passenger service systems with immutable record layers, as enterprise software conglomerates trade at platform premiums. Long-term viability centers on regulatory compliance moats deepening through successive FAA, EASA, and GCAA certification cycles. Acquisition target archetypes include hybrid blockchain architects with demonstrated simultaneous multi-authority certification. Practitioners should monitor EASA audit cycle renewal dates and FAA Part 43 enforcement phase-ins for early signals of compliance-driven procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | FAA Part 43 compliance locks in multi-year maintenance contract renewals with U.S. operators. |
| IoT Oracle Integration | Smart contract automation of engine overhaul payments compresses supplier working capital cycles. |
| Hybrid Blockchain Development | Simultaneous EASA and FAA certification opens lessor fleet management across jurisdictional boundaries. |
| Ground Handling Cooperative Partnership | Direct middleware sales to regional handlers bypass legacy airline alliance procurement bottlenecks. |
| PLI Scheme Alignment | Indian production-linked incentives subsidize MRO provenance tracking infrastructure deployment costs. |
Study Parameters
Direct dialogue with airline CTOs, MRO shop technical directors, national aviation authority digital transformation leads, and distributed ledger middleware engineers grounded qualitative findings in operational implementation constraints. Secondary validation drew from FAA docket filings, EASA continuing airworthiness regulation updates, GCAA digital framework documentation, and airline consortium blockchain pilot disclosures. Bottom-up triangulation across deployment cost structures and top-down validation against regulatory compliance timelines ensured segmentation integrity.
Market size outputs across the analysis window reflect modeled adoption curves for private, consortium, and hybrid blockchain architectures segmented by maintenance records, cargo tracking, flight logistics, and ticketing applications. CAGRs were derived from regulatory deadline enforcement schedules, IoT sensor convergence rates, and smart contract payment automation penetration in engine overhaul contracts. Forecast inputs incorporated MRO service provider procurement cycles, lessor fleet reconfiguration burdens, and ground handling cooperative IT budget trajectories.
Revisions become necessary when FAA Part 43 enforcement phases accelerate, EASA harmonization deadlines shift, or hybrid blockchain certification requirements fragment across national aviation authorities. Practitioners should monitor GCAA pilot program expansion rates and India PLI scheme aviation manufacturing incentive adjustments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Blockchain-As-A-Service (Baas) Market
Blockchain Technology
Enterprise-Grade DLT Market
Blockchain Technology
Decentralized Identity Market
Blockchain Technology
Europe Blockchain Market
Blockchain Technology
Global Blockchain in Logistics Market
Blockchain Technology
Automotive Blockchain Market
Blockchain Technology
Aviation Transaction Blockchain Market
Blockchain Technology
Web 3.0 Market
Blockchain Technology
Global Blockchain in Healthcare Market
Blockchain Technology
Global Blockchain Supply Chain Market
Blockchain Technology
Aviation Record-Keeping Blockchain Market
Blockchain Technology
Global Blockchain in Energy Market
Blockchain Technology
Marine Blockchain Market
Blockchain Technology
Tokenization Market
Blockchain Technology
Global Blockchain Market
Blockchain Technology
Web 3.0 Blockchain Market