
 Industrial Blockchain Technology Market | 2026-2036
Industrial Blockchain Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Blockchain Technology Market Foresight
Distributed ledger interoperability is rewriting how industrial enterprises orchestrate multi-party workflows. IBM Corporation leverages its Hyperledger Fabric foundation to anchor enterprise consortia across manufacturing verticals. Microsoft Corporation competes through Azure Blockchain integration with existing ERP ecosystems. SAP SE dominates in supply chain management by embedding blockchain natively into its S/4HANA logistics modules.
Industrial blockchain technology comprises cryptographically linked distributed databases that maintain tamper-evident transaction records across permissioned networks using consensus mechanisms such as Practical Byzantine Fault Tolerance or Raft. Its primary industrial purpose is to establish shared, immutable ledgers that eliminate reconciliation latency between untrusted counterparties in complex supply chains. Private blockchain deployments currently capture the deepest margin pools due to enterprise demand for controlled governance and data sovereignty. Hybrid blockchain architectures represent the fastest-growing technology segment as organizations balance transparency requirements with confidentiality needs. Asset tracking applications lead adoption among end-use cases, particularly in pharmaceuticals where serialization mandates require end-to-end provenance verification.
The EU's GDPR and upcoming Data Act shape how blockchain nodes store personal data across European industrial networks, forcing architectural choices toward zero-knowledge proofs and off-chain storage. In the United States, NIST's blockchain technology overview and emerging SEC custody rules for digital assets influence enterprise procurement standards and vendor qualification. China's MIIT blockchain development guidelines and SAMR data security regulations constrain how multinational firms architect cross-border ledger deployments. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded infrastructure investments as compliance frameworks mature.
Market Dynamics
Supply chain provenance mandates from pharmaceutical and automotive sectors are forcing industrial enterprises to deploy immutable ledger infrastructure, compressing procurement cycles for compliant blockchain nodes.
Growth Catalysts
- EU Markets in Crypto-Assets Regulation:The framework mandates auditable infrastructure for tokenized industrial assets, accelerating enterprise migration toward permissioned ledger architectures.
- Pharmaceutical serialization requirements:End-to-end drug provenance tracking under FDA DSCSA and EMA mandates drives blockchain deployment for lot-level traceability.
- Germany's industrial corridor concentration:Automotive and machinery producers in Bavaria and Baden-Württemberg pilot blockchain-enabled supplier verification systems.
Market Restraints
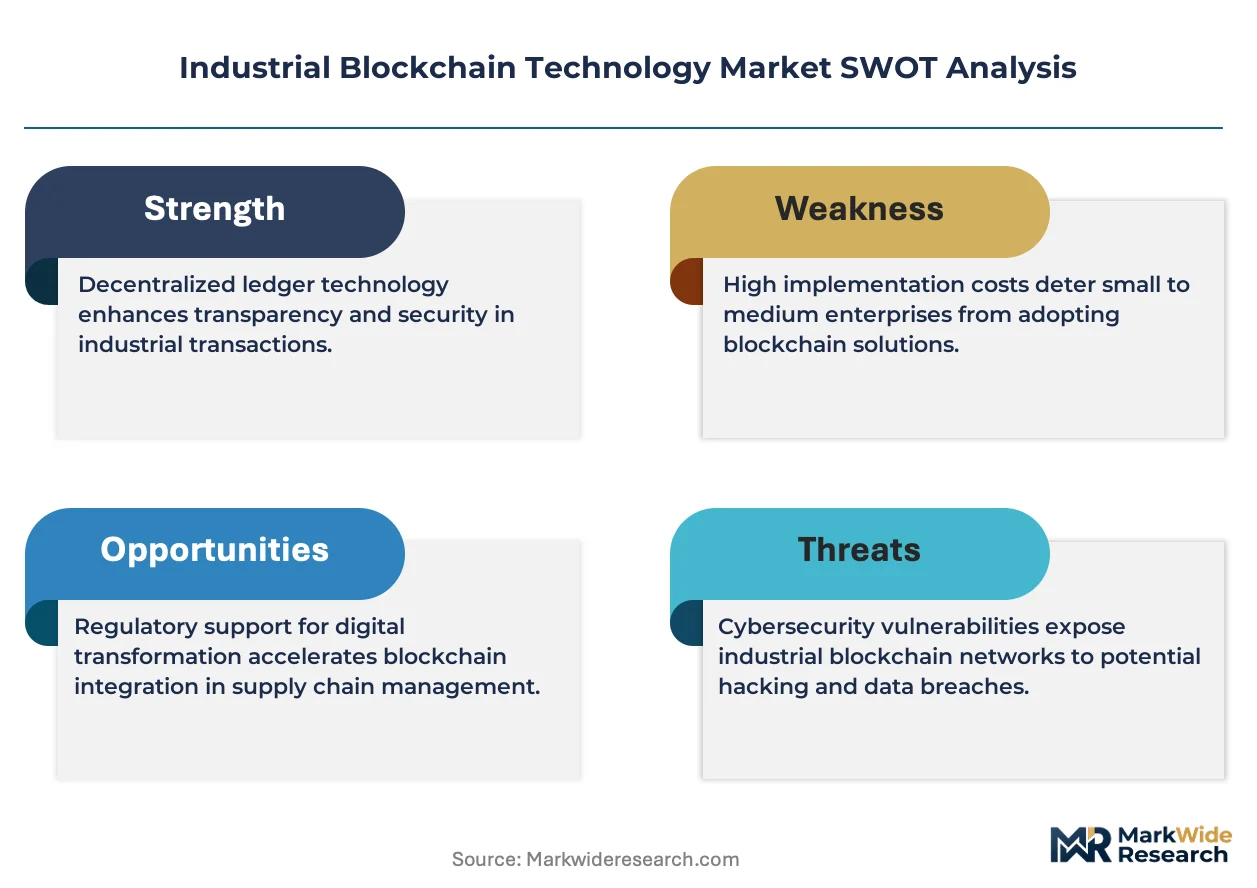
- Specialized cryptographic hardware costs:HSM modules and secure enclave processors required for enterprise-grade node security inflate initial deployment budgets by 40-60% versus standard server infrastructure.
- Consensus latency limitations:Practical Byzantine Fault Tolerance mechanisms impose throughput ceilings that constrain real-time manufacturing execution system integration.
- Cross-border data residency conflicts:China's SAMR data localization requirements clash with EU GDPR portability rules, fragmenting multinational ledger architectures.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Component traceability incentives create entry points for blockchain vendors serving smartphone and semiconductor supply chains.
- Convergence of IoT sensor networks with edge computing:Distributed ledger nodes embedded in industrial gateways enable automated condition-based smart contracts for predictive maintenance.
- Carbon accounting verification:ISO 14064-aligned emissions tracking opens new revenue streams for ledger providers serving Scope 3 disclosure requirements.
Industry Challenges
- Smart contract audit talent scarcity:Solidity and Rust security expertise remains concentrated in financial services, creating recruitment bottlenecks for industrial automation projects.
- Legacy ERP integration complexity:SAP and Oracle systems require custom middleware development, extending implementation timelines by 8-14 months.
- Interoperability standard delays:Competing consortium frameworks prevent seamless data exchange between Hyperledger Fabric, R3 Corda, and enterprise Ethereum deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Blockchain Technology Market |
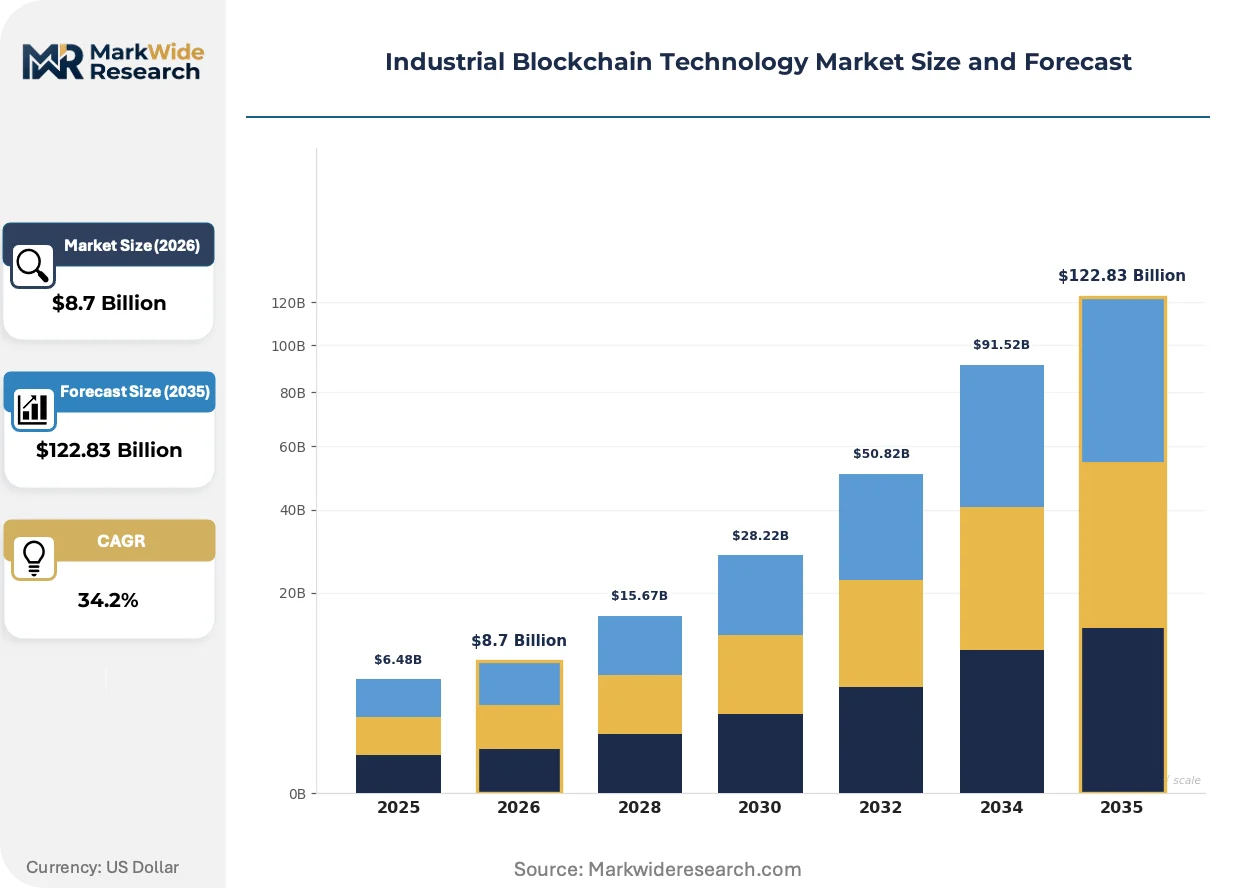
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $122.83 Billion |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Supply Chain Management, Asset Tracking, Quality Assurance, Smart Contracts End User: Manufacturing, Oil & Gas, Logistics, Pharmaceuticals Technology: Public Blockchain, Private Blockchain, Consortium Blockchain, Hybrid Blockchain Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | IBM Corporation, Microsoft Corporation, Amazon Web Services, Oracle Corporation, SAP SE, Digital Asset Holdings, R3, Accenture, Deloitte Touche Tohmatsu Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Blockchain Technology Market Shifts & Advancements
Zero-knowledge proof architectures and modular consensus layers are compressing the trade-off between transaction privacy and auditability that has long constrained industrial blockchain adoption.
Zero-knowledge succinct non-interactive arguments of knowledge (zk-SNARKs) are collapsing the verification overhead for confidential supply chain transactions. Pharmaceutical manufacturers in Switzerland and Germany now embed zk-proofs into batch certification workflows without exposing proprietary formulation data. This compression eliminates the historical need for separate permissioned channels per counterparty, reducing node infrastructure requirements by half.
China's MIIT blockchain service management regulations now require algorithmic filing and security assessments for all industrial ledger deployments. Multinational firms operating joint ventures in Jiangsu and Guangdong provinces must architect dual-node configurations satisfying both domestic audit access and headquarters data sovereignty. The automotive sector responds by segmenting vehicle provenance data across jurisdictional boundaries.
Subscription-based node-as-a-service procurement is displacing capital-intensive on-premise deployments among mid-tier manufacturers. German Mittelstand firms in the tooling and automation sectors now procure validated validator infrastructure through cloud marketplaces rather than building captive data centers. This shift concentrates vendor relationships with hyperscale providers and compresses buyer negotiation leverage on service-level agreements.
Industrial Blockchain Technology Market Segmentation
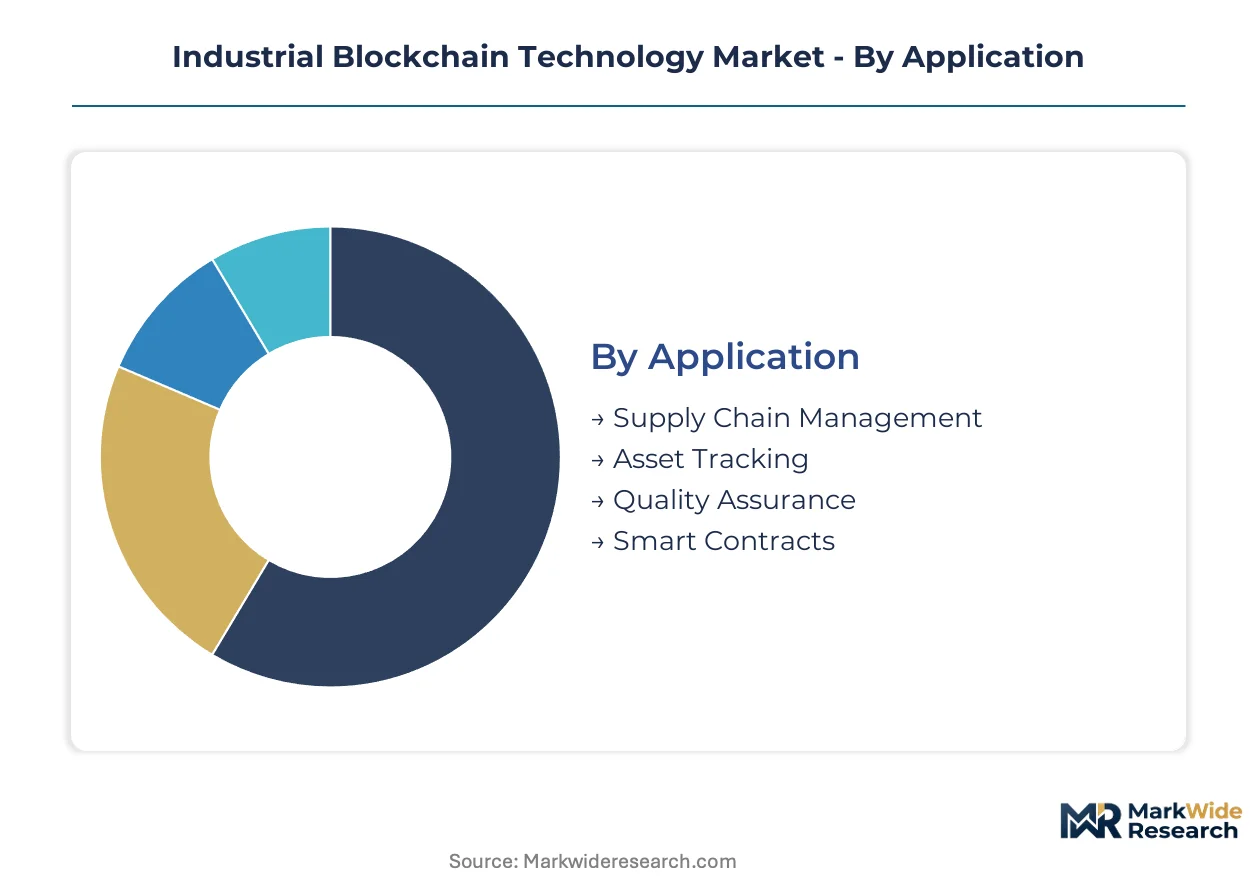
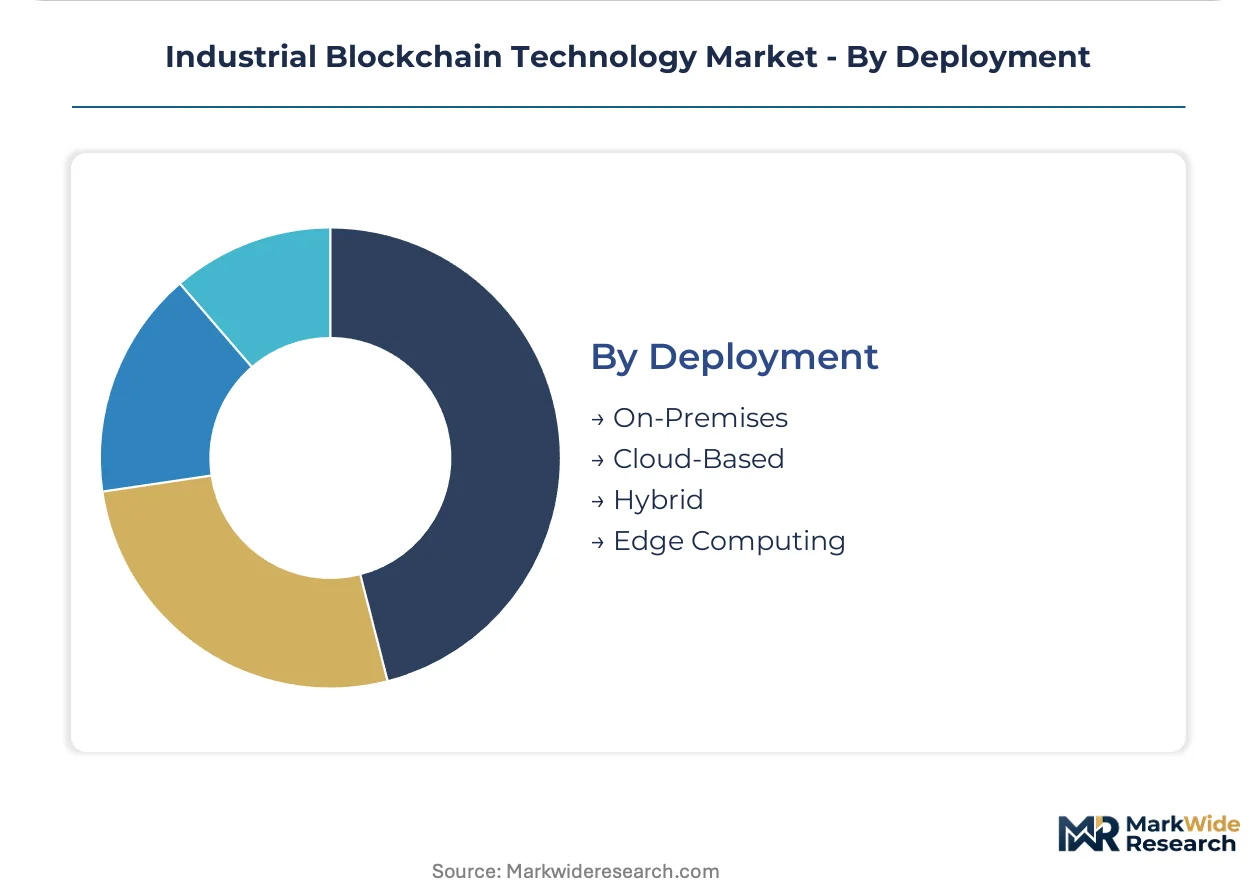
Industrial blockchain deployments fragment across four intersecting dimensions that determine architectural complexity and vendor selection criteria. Application use cases dictate consensus mechanism requirements, while end-user verticals impose distinct regulatory compliance burdens. Technology and deployment choices together govern total cost of ownership and data sovereignty posture.
Application:
After-sales service intensity varies dramatically across blockchain applications, with asset tracking demanding continuous node maintenance and smart contracts requiring ongoing audit support.
- Supply Chain Management:Distributed ledger systems synchronize multi-tier supplier data across immutable audit trails. Pharmaceutical manufacturers in Germany and automotive assemblers in Bavaria drive procurement for lot-level and component-level traceability under EMA and FDA mandates.
- Asset Tracking:Serialization engines embed cryptographic identifiers into physical goods for provenance verification. Demand concentrates in Swiss pharmaceutical packaging lines and German machinery export documentation where end-to-end custody records satisfy customs authorities.
- Quality Assurance:Immutable inspection records automate compliance certification workflows.
- Smart Contracts:Self-executing agreements trigger payments upon IoT-verified delivery events.
By volume, Supply Chain Management leads. By growth pace, Smart Contracts is ahead.
End User:
Cost tier stratification separates capital-intensive on-premise deployments in oil and gas from subscription-based cloud procurement among mid-tier logistics providers.
- Manufacturing:Discrete and process manufacturers deploy permissioned ledgers for supplier qualification and work-in-progress tracking. Automotive producers in Baden-Württemberg and electronics assemblers under India's PLI scheme anchor demand for component provenance systems.
- Pharmaceuticals:Batch certification workflows leverage zero-knowledge proofs to protect formulation data while satisfying EMA and FDA serialization mandates. Swiss and German drug manufacturers pilot the most advanced confidential computing integrations.
- Logistics:Freight forwarders and 3PL providers adopt cloud-hosted nodes for document digitization.
- Oil & Gas:Upstream operators track custody transfer across joint venture partnerships.
Manufacturing captures the largest deployment base. Pharmaceuticals shows the steepest expansion trajectory.
Technology:
Customer type segmentation separates enterprise consortia seeking controlled governance from startup ecosystems prioritizing permissionless innovation.
- Private Blockchain:Closed networks with designated validators dominate enterprise deployments requiring data sovereignty and configurable consensus. German Mittelstand firms in tooling and automation sectors favor this architecture for supplier verification systems.
- Hybrid Blockchain:Architectures combining permissioned transaction processing with public settlement layers balance confidentiality and interoperability. Multinational automotive firms operating across China's MIIT jurisdiction and EU GDPR zones drive architectural innovation here.
- Consortium Blockchain:Pre-selected node operators share infrastructure costs across industry verticals.
- Public Blockchain:Open validator sets attract tokenized asset pilots and carbon credit verification use cases.
Private Blockchain holds the deepest margin pools. Hybrid Blockchain is gaining share fastest as jurisdictional fragmentation intensifies.
Deployment:
Supply concentration in hyperscale cloud providers is compressing negotiation leverage for mid-tier manufacturers procuring validator infrastructure.
- Cloud-Based:Managed node services eliminate capital expenditure for hardware security modules and data center construction. German mid-market automation firms increasingly procure through Azure and AWS marketplaces rather than building captive infrastructure.
- Edge Computing:Distributed ledger nodes embedded in industrial gateways enable automated condition-based smart contracts. IoT sensor convergence in predictive maintenance applications drives pilot deployments in Japanese automotive plants and German machinery installations.
- On-Premises:Captive data centers satisfy stringent data residency requirements in regulated verticals.
- Hybrid:Split architectures process sensitive transactions locally while anchoring proofs to public networks.
Cloud-Based deployment leads in new installations. Edge Computing climbs the fastest as IoT sensor density increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive and machinery producers export blockchain-verified component documentation to assembly plants across the United States and China, establishing the Rhine-Main corridor as the primary trade-flow hub for industrial ledger technology.
United States
Pharmaceutical manufacturers and defense contractors drive permissioned ledger procurement for serialization and supply chain security. FDA DSCSA mandates for drug traceability compress implementation timelines for lot-level tracking systems. Boston's biotech cluster and Detroit's automotive corridor anchor pilot deployments for cross-border provenance verification.
Germany
Automotive assemblers and precision machinery builders demand immutable supplier audit trails for export compliance. EU Markets in Crypto-Assets regulation pushes Mittelstand firms toward compliant infrastructure architectures. Bavaria's industrial corridor hosts the densest concentration of blockchain-enabled provenance pilots for automotive component verification.
China
Electronics manufacturers and joint-venture automotive firms deploy dual-node configurations to satisfy data localization requirements. MIIT blockchain service management regulations mandate algorithmic filing for all industrial ledger deployments. Jiangsu and Guangdong provinces fragment vehicle provenance data across jurisdictional boundaries for multinational compliance.
Switzerland
Pharmaceutical packaging lines and luxury goods producers embed zero-knowledge proofs into batch certification workflows. Swissmedic serialization mandates align with EMA requirements for end-to-end drug traceability. Basel's pharmaceutical cluster pilots the most advanced confidential computing integrations for formulation data protection.
India
Electronics assemblers and component manufacturers leverage PLI scheme incentives for traceability infrastructure investment. DGFT import monitoring requirements accelerate adoption of immutable documentation systems. Karnataka's smartphone manufacturing belt and Gujarat's semiconductor packaging facilities anchor blockchain vendor entry points.
Industrial Blockchain Technology Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Hyperscale cloud providers and enterprise software incumbents dominate infrastructure procurement through integrated marketplace distribution. Systems integrators and boutique ledger specialists occupy mid-market positions with vertical-specific configurations. Consolidation pressure intensifies as middleware requirements and interoperability standards favor scale-driven vendors. Dominant competitive moves include strategic partnerships with ERP ecosystem providers and geographic expansion through regulatory-compliant node hosting.
Within the enterprise software tier, IBM Corporation and Microsoft Corporation exemplify contrasting architectural philosophies for industrial consortia formation. SAP SE anchors supply chain management positioning through native ERP embedding. Amazon Web Services occupies the cloud-native infrastructure vector with managed node services. Oracle Corporation and Accenture represent the systems integration archetype, bridging legacy database environments with distributed ledger deployments. R3 and Digital Asset Holdings exemplify specialized protocol developers serving regulated financial and industrial workflows. Deloitte Touche Tohmatsu Limited anchors professional services positioning for smart contract audit and compliance advisory.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Amazon Web Services |
| Oracle Corporation |
| SAP SE |
| Digital Asset Holdings |
| R3 |
| Accenture |
| Deloitte Touche Tohmatsu Limited |
| Others |
Supply & Pricing Matrix
Undercapacity in cryptographic hardware manufacturing across Germany and Taiwan is compressing supplier margins while amplifying pricing power for HSM-integrated node providers serving automotive and pharmaceutical buyers.
Pricing Analysis
Next-generation zero-knowledge proof architectures command 40-60% premiums over standard Practical Byzantine Fault Tolerance deployments due to reduced node infrastructure requirements. Pricing stratifies across premium, standard, and economy tiers based on consensus mechanism complexity and GDPR compliance certification level. Cost compression in mid-market cloud-hosted validator services is intensifying because hyperscale providers are consolidating managed node marketplaces. Small-to-mid Mittelstand manufacturers exhibit highest price sensitivity, while pharmaceutical serialization mandates make large drugmakers least sensitive to per-node costs.
Supply Chain Analysis
Extended payment terms from German automotive OEMs are forcing HSM suppliers and consensus protocol developers to rely on supply-chain finance facilities anchored in Frankfurt and Singapore banking networks. Hardware security module production draws from Taiwan, South Korea, and Germany, while cryptographic processor IP rests on ARM and RISC-V licensing from the United Kingdom and United States. Single-source vulnerability in secure enclave fabrication creates exposure to export control restrictions. Distribution runs through hyperscale cloud marketplaces and systems integrators rather than direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated automotive and pharmaceutical procurement consortiums, fragmenting vendor negotiation leverage as enterprise software incumbents absorb middleware specialists.
For Market Incumbents: Build switching-cost moats through native ERP embedding and certified interoperability frameworks. Deepen backward integration into hardware security module supply to offset cryptographic processor shortages. Defensive consolidation should target middleware developers bridging SAP and Oracle environments, as legacy system integration complexity represents the stickiest retention mechanism against cloud-native challengers. For New Entrants and Emerging Players: India's electronics manufacturing clusters under PLI scheme incentives represent the most penetrable entry point for component traceability specialists. Carbon accounting verification for Scope 3 disclosure requirements offers adjacent white-space with lower incumbent saturation. Go-to-market should leverage channel partnerships with hyperscale cloud marketplaces rather than direct enterprise sales cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across subscription-based node-as-a-service providers as German Mittelstand firms displace on-premise deployments. Long-term viability favors vendors with dual-jurisdiction architectural capabilities spanning EU GDPR and China's MIIT compliance zones. Acquisition targets should display proven validator infrastructure hosting across fragmented regulatory environments. Watch for MIIT algorithmic filing acceleration as inflection signal for China market access premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Knowledge Proof Integration | Swiss pharmaceutical manufacturers embed zk-SNARKs to protect proprietary formulation data under EMA mandates. |
| Hybrid Blockchain Architecture Development | Multinational automotive firms balance GDPR portability with SAMR localization across Bavaria and Jiangsu operations. |
| ERP Native Embedding | SAP S/4HANA logistics modules create captive demand through embedded ledger functionality. |
| Cloud Marketplace Distribution | Azure and AWS validator procurement compresses implementation timelines for German mid-market automation firms. |
| Smart Contract Audit Capability Buildout | Deloitte and boutique specialists address Solidity talent scarcity constraining industrial automation deployment. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with blockchain platform engineers, enterprise IT procurement officers, automotive supplier quality managers, pharmaceutical serialization leads, and cloud marketplace channel partners. Secondary validation drew from SEC 10-K infrastructure disclosures, EU MiCA regulatory filings, MIIT algorithmic registration databases, and hyperscaler capex reports. Bottom-up deployment estimates across application segments were triangulated against top-down market sizing from vendor revenue aggregation.
Calibration against historical permissioned ledger adoption curves in manufacturing verticals anchored growth rate derivation across the projection horizon. Segmentation dimensions modeled include technology architecture, deployment model, end-user vertical, application use case, and jurisdictional compliance cluster. Consensus mechanism throughput benchmarks and IoT sensor density projections served as industry-specific forecast inputs alongside regulatory filing velocity indicators.
Practitioners should monitor MiCA implementation timelines and MIIT security assessment acceleration for early signals of infrastructure procurement compression. Forecasts reflect documented assumptions regarding interoperability standard convergence and cryptographic hardware supply normalization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Blockchain in Smart Home Market
Blockchain Technology
Blockchain Gaming Market
Blockchain Technology
Europe Blockchain Market
Blockchain Technology
Global Blockchain in Healthcare Market
Blockchain Technology
Blockchain in Manufacturing Market
Blockchain Technology
Blockchain in Sports Market
Blockchain Technology
Blockchain in Pharmaceutics Market
Blockchain Technology
Blockchain Messaging Apps Market
Blockchain Technology
Aviation Transaction Blockchain Market
Blockchain Technology
Blockchain in Aviation Market
Blockchain Technology
Bitcoin Technology Market
Blockchain Technology
Global Blockchain in Logistics Market
Blockchain Technology
Smart Contracts on Blockchain Market
Blockchain Technology
Bitcoin Project Incubator Service Market
Blockchain Technology
Blockchain AI Market
Blockchain Technology
Global Blockchain in Agriculture and Food Supply Chain Market