
 Automotive Blockchain Market | 2026-2036
Automotive Blockchain Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Blockchain Market Intelligence
Compliance with the ISO 27001 standard for information security management is bifurcating the vendor landscape between enterprise-grade platforms and niche startups. IBM Corporation leverages its extensive enterprise client base to deploy private blockchain solutions for supply chain integrity. Microsoft Corporation competes through its Azure Blockchain Service, offering scalable cloud infrastructure for automotive clients. Accenture PLC specializes in systems integration and consulting, connecting blockchain technology with existing automotive enterprise resource planning systems.
Automotive blockchain refers to a distributed, immutable digital ledger technology applied to vehicle-related data and transactions. It uses cryptographic hashing to chain together blocks of information, creating a tamper-evident record of events from manufacturing to end-of-life. Supply chain management and vehicle data management represent the dominant applications, driven by OEM and Tier-1 Supplier demand for provenance and security. While OEMs are the principal end-users, adoption is also occurring among telematics firms for secure data exchange.
Regulatory frameworks such as Europe’s GDPR dictate how personal vehicle data is managed on-chain, influencing platform architecture. In parallel, mandates from the US EPA on emissions reporting and standards from China's MIIT on connected vehicle data create compliance-driven use cases. The critical decision for stakeholders revolves around establishing interoperability protocols between different consortium and private blockchains to avoid industry fragmentation.
Market Dynamics
The central conflict defining the automotive blockchain market is the need for industry-wide interoperability protocols against the competitive advantage sought by enterprises deploying proprietary, private ledger solutions for supply chain control and data monetization.
Growth Catalysts
- Component Provenance:OEM demand for supply chain transparency to verify the origin of critical components like batteries is a primary catalyst.
- Data Privacy Regulation:Europe's GDPR compels automakers to use blockchain for secure management of vehicle data, creating a compliance-driven use case.
- Manufacturing Hub Adoption:Pilot programs by automakers in Germany and the United States validate technology and encourage wider ecosystem participation.
Market Restraints
- Interoperability Gaps:The absence of accepted standards between blockchain platforms creates data silos, hindering information exchange between automotive consortia.
- Legacy System Integration:High costs and complexity of integrating immutable ledgers with existing ERP systems deter adoption.
- Scalability Limitations:The transaction throughput of some architectures is insufficient for high-volume data streams from connected vehicles.
Strategic Opportunities
- Vehicle Data Monetization:Platforms for selling anonymized vehicle data to third parties like insurance firms or city planners represent a key revenue opportunity.
- Convergence with AI:Combining blockchain with AI enables advanced applications like automated warranty claims and predictive vehicle maintenance.
- EV Battery Lifecycle Management:Applying blockchain to manage electric vehicle battery data, including charging history and degradation, addresses a critical need.
Industry Challenges
- Talent Scarcity:A shortage of professionals with dual expertise in automotive engineering and distributed ledger technology impedes solution development.
- Data Standardization Delays:Slow industry consensus on data models for on-chain vehicle identity and service history records limits network effects.
- Consortium Governance:Establishing effective governance for multi-stakeholder consortia, particularly on data access and cost-sharing, remains a significant hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Blockchain Market |
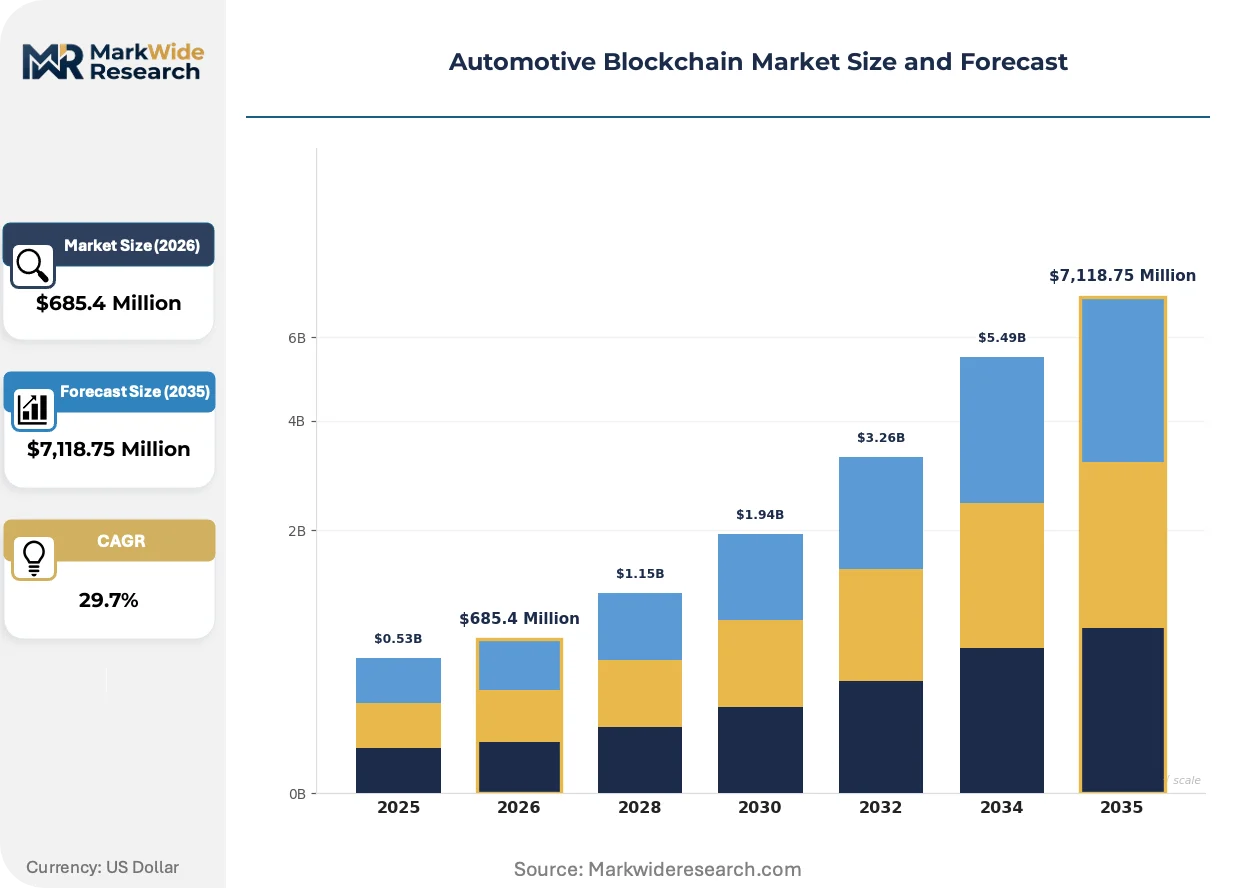
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $7,118.75 Million |
| CAGR (2026 – 2036) | 29.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Supply Chain Management, Vehicle Data Management, Insurance & Claims, Fleet Management, Autonomous Vehicle Coordination, Ride Sharing Technology: Public Blockchain, Private Blockchain, Consortium Blockchain, Directed Acyclic Graph, Proof of Authority, Sidechain End User: OEMs, Tier-1 Suppliers, Dealerships, Aftermarket Providers, Vehicle Assemblers, Telematics Firms Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing, Decentralized Network, Distributed Ledger |
| Companies Covered | IBM Corporation, Microsoft Corporation, Accenture PLC, BigchainDB GmbH, Tech Mahindra Ltd., carVertical, SHIFTMobility Inc., ConsenSys, Amazon Web Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Blockchain Market Strategic Shifts & Innovations
Movement from isolated proofs-of-concept to scalable, multi-party platforms defines the market's current phase. Enterprise-grade deployments are being prioritized to address complex challenges in supply chain integrity, regulatory compliance, and the creation of new service ecosystems.
Zero-Knowledge Proofs (ZKPs) provide a method to verify information on a blockchain without revealing the underlying data. OEMs and suppliers are adopting ZKPs for sharing confidential commercial data like parts pricing within consortia. This trend is fragmenting the architectural landscape between private ledgers and more collaborative, privacy-preserving consortium models.
The US EPA's mandates on emissions reporting create a driver for using blockchain to create an immutable audit trail for vehicle components. This forces automakers to align on-chain data collection with environmental compliance frameworks. The supply chain management segment is most impacted, integrating EPA reporting fields into ledger designs.
A behavioral shift is underway from single-vendor solutions towards participation in open, industry-led consortia. Automakers are choosing collaborative platforms to pool resources and establish common standards for applications like vehicle identity. This cooperative model is gaining traction in Europe for cross-border data sharing.
Automotive Blockchain Market Segmentation
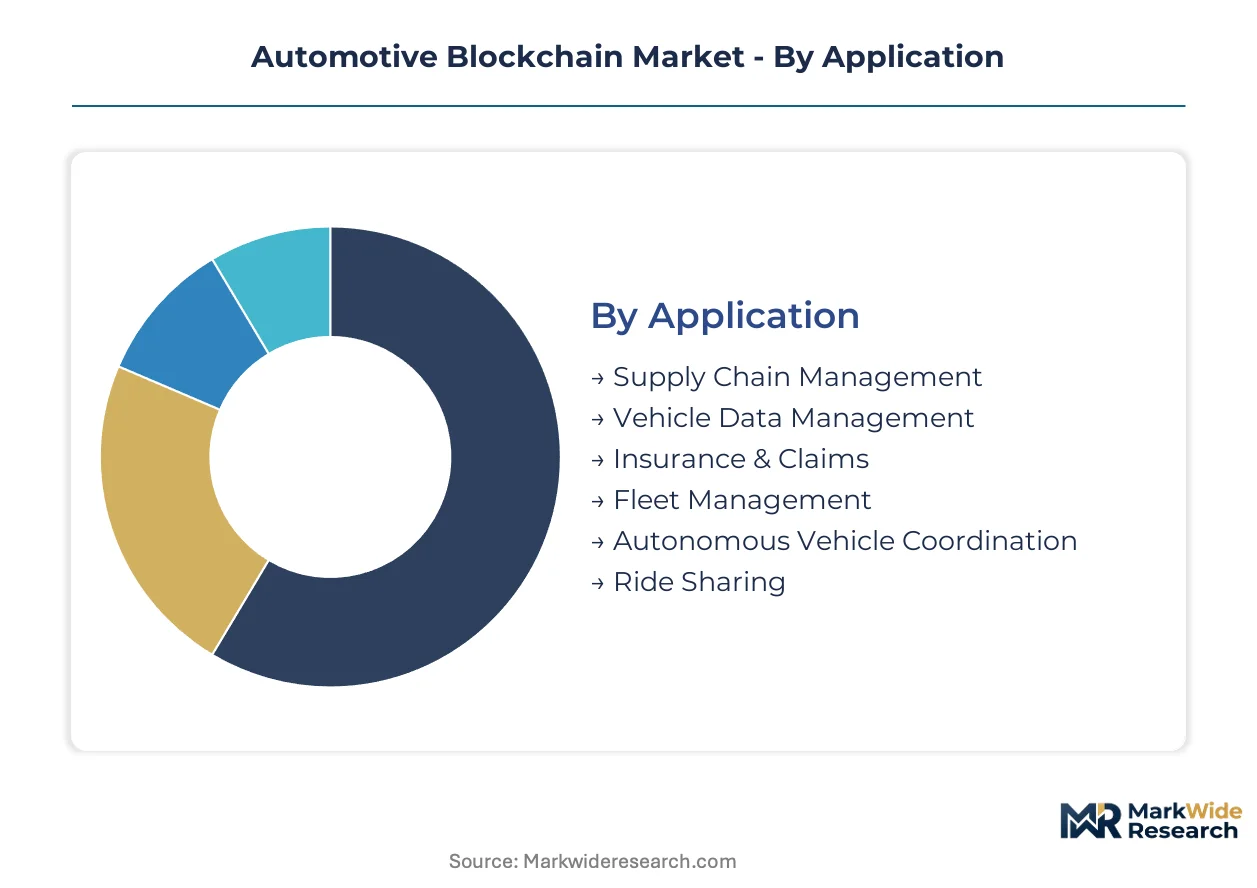
Detailed segmentation analysis of the Automotive Blockchain Market reveals how diverse applications, technologies, and end-users shape its evolution. This granular breakdown identifies key investment areas and strategic focus, highlighting critical market dynamics.
Application:
Margin pools within automotive blockchain applications concentrate in solutions addressing high-value challenges like component provenance and secure vehicle data.
- Supply Chain Management:This application leverages distributed ledgers to track components from manufacturing to assembly, ensuring authenticity. Demand concentrates in Germany and the United States, driven by OEM requirements for battery origin verification.
- Vehicle Data Management:This involves securing and managing data from connected vehicles, including telematics and diagnostics. Adoption accelerates in Europe due to GDPR mandates and among telematics firms seeking secure data exchange.
- Insurance & Claims:Blockchain streamlines claims processing and fraud detection by providing immutable records of incidents and vehicle history.
- Fleet Management:This segment uses blockchain for transparent tracking of vehicle usage, maintenance, and compliance within commercial fleets.
- Autonomous Vehicle Coordination:Blockchain enables secure communication and transaction settlement between autonomous vehicles and infrastructure.
- Ride Sharing:This application facilitates transparent payment systems and user reputation management within decentralized ride-sharing platforms.
Supply Chain Management holds installed capacity. Vehicle Data Management is rotating up the share rankings.
Technology:
Automotive blockchain technology choices reflect a strategic balance between decentralization requirements and enterprise control, influencing supply concentration.
- Private Blockchain:These permissioned networks are controlled by a single entity, offering high transaction speed and data privacy for internal operations. IBM clients deploy private blockchain solutions for supply chain integrity.
- Consortium Blockchain:Operated by a group of pre-selected organizations, these hybrid networks balance decentralization with controlled access for multi-party collaborations. Pilot programs in Germany and the US utilize consortium models.
- Public Blockchain:Open, decentralized networks suitable for highly transparent, trustless environments, less common for core automotive enterprise functions.
- Directed Acyclic Graph:This technology offers high scalability and low transaction fees, suitable for high-volume data streams from connected vehicles.
- Proof of Authority:A consensus mechanism where transactions are validated by approved entities, providing efficiency and scalability for private networks.
- Sidechain:A separate blockchain linked to a main blockchain, allowing for specialized transactions and improved scalability without impacting the main chain.
Consortium Blockchain solutions are expanding most quickly. Private Blockchain deployments maintain significant market presence.
End User:
End-user volume is dominated by entities directly involved in vehicle manufacturing and data generation within the automotive ecosystem.
- OEMs:Original Equipment Manufacturers represent the principal end-users, driving demand for blockchain to ensure component provenance and manage vehicle data. Automakers in Germany lead pilot projects.
- Tier-1 Suppliers:These large component manufacturers adopt blockchain for traceability and compliance, integrating their supply chains with OEM requirements. Demand is high in regions with dense automotive manufacturing.
- Dealerships:This segment uses blockchain for transparent vehicle history records, improving trust in used car sales and maintenance.
- Aftermarket Providers:Blockchain helps track parts authenticity and service history, benefiting independent repair shops and parts distributors.
- Vehicle Assemblers:These entities leverage blockchain for efficient tracking of parts and production milestones, ensuring quality control and auditability.
- Telematics Firms:Adoption occurs among telematics firms for secure data exchange and monetization of vehicle-generated information.
OEMs drive core innovation in blockchain applications. Telematics Firms are demonstrating emergent use cases.
Deployment:
Deployment models are stratified by cost tier and operational complexity, influencing implementation strategies for automotive blockchain solutions.
- Cloud-Based:This deployment offers scalability and reduced infrastructure costs, making it attractive for automotive clients leveraging services like Azure Blockchain. Demand concentrates as enterprises seek flexible environments.
- Hybrid:Combining on-premises and cloud resources, hybrid deployments balance control and scalability, integrating legacy ERP systems with new blockchain solutions. This model addresses data residency concerns.
- On-Premises:This traditional deployment offers maximum control over data and infrastructure, preferred by organizations with strict security and compliance requirements.
- Edge Computing:Blockchain at the edge processes data closer to the source, reducing latency for connected vehicle applications and real-time processing.
- Decentralized Network:This refers to blockchain architectures where no single entity controls the network, promoting transparency and censorship resistance.
- Distributed Ledger:A foundational technology underlying blockchain, representing a shared, synchronized database spread across multiple nodes.
Cloud-Based deployments are gaining preference for new initiatives. On-Premises solutions maintain a foothold for sensitive data.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's GDPR regulations compel automakers to adopt blockchain for secure vehicle data management, driving significant compliance-driven demand. Mandates from the US EPA on emissions reporting and China's MIIT standards for connected vehicle data also create critical use cases. These regulatory pressures, combined with OEM demand, are accelerating regional adoption in major automotive manufacturing hubs.
United States
OEM demand for component provenance and secure vehicle data management drives blockchain adoption in the United States. US EPA mandates on emissions reporting necessitate immutable audit trails for vehicle components. Automakers in Michigan, particularly around the Detroit area, are actively piloting blockchain solutions for supply chain transparency.
Germany
Germany's automotive sector focuses on supply chain transparency to verify battery origin and manage vehicle data securely. Europe's GDPR dictates strict protocols for on-chain personal vehicle data, influencing platform architecture. Major automakers in Bavaria and Baden-Württemberg are leading pilot projects for consortium blockchain models.
China
China's MIIT standards on connected vehicle data create a strong regulatory push for blockchain implementation in vehicle data management. Demand for supply chain integrity and emissions reporting compliance also underpins market expansion. Technology hubs like Shenzhen and the Yangtze River Delta are seeing increased activity in blockchain development for the automotive sector.
Japan
Japanese automakers seek blockchain solutions for enhanced supply chain efficiency and secure telematics data exchange. METI initiatives encourage industrial digitalization and the adoption of advanced technologies like distributed ledgers. Aichi Prefecture, a major automotive manufacturing region, is a focal point for pilot programs involving secure data sharing among industry players.
Automotive Blockchain Market Key Industry Players
Player mix skews toward a bifurcated landscape, with established enterprise technology firms and specialized blockchain startups. The market structure is characterized by a blend of large-scale solution providers and niche innovators. Strategic archetypes include enterprise blockchain platform providers, cloud infrastructure specialists, and systems integrators. Competitive moves often involve strategic partnerships to build consortia and portfolio diversification into automotive-specific applications.
Within the enterprise-grade platform tier, IBM Corporation leverages its extensive client base to deploy private blockchain solutions for supply chain integrity. Microsoft Corporation represents a key cloud infrastructure specialist, offering scalable services through its Azure Blockchain Service for automotive clients. Accenture PLC occupies a significant position as a systems integrator, connecting blockchain technology with existing automotive ERP systems for large enterprises.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Accenture PLC |
| BigchainDB GmbH |
| Tech Mahindra Ltd. |
| carVertical |
| SHIFTMobility Inc. |
| ConsenSys |
| Amazon Web Services, Inc. |
| Others |
Cost & Logistics Intelligence
Digital ledger technology adoption, substituting legacy data management, reshapes both the geographic concentration of trusted data providers and the pricing models for secure vehicle information services.
Pricing Analysis
ISO 27001 compliance and enterprise-grade security features create the primary price differentiation in automotive blockchain solutions. Project-based implementation fees dominate initial deployments, transitioning to SaaS-tiered subscription models for ongoing data management and transaction processing. Customization for specific OEM supply chain integrations drives higher costs, while standardized consortium solutions offer more competitive pricing. Pricing pressure stems from the emergence of niche startups offering more focused, cost-effective solutions for specific use cases. Telematics firms and smaller Tier-1 suppliers exhibit higher price sensitivity compared to major OEMs.
Supply Chain Analysis
Talent scarcity in distributed ledger technology development underwrites the concentrated supply of specialized blockchain solution providers. Geographic supply for these platforms centers in technology hubs across the United States, Germany, and China. Automotive blockchain solutions depend on robust cloud infrastructure from hyperscalers and specialized DLT software components. Supply chain risk arises from the absence of accepted interoperability standards, creating data silos and hindering ecosystem-wide adoption. Distribution runs through direct sales channels to OEMs and via systems integrators connecting blockchain with existing ERP systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive blockchain market enters a cyclical recovery phase, driven by renewed OEM investment in supply chain resilience and compliance post-disruption. This rebound focuses on integrating distributed ledger technology into core enterprise operations.
For Market Incumbents: Secure existing enterprise client bases by aggressively investing in interoperability protocols and advanced privacy-preserving technologies like Zero-Knowledge Proofs. This defends against fragmentation from niche startups offering single-point solutions. Consolidate market share through strategic acquisitions of specialized DLT development firms to expand automotive-specific application portfolios. Focus R&D on seamless integration with legacy ERP systems, a critical lever for large-scale deployments.
For New Entrants and Emerging Players: Anchor in specific, high-growth white-space applications like EV battery lifecycle management and secure vehicle data monetization platforms. The most penetrable segment lies within telematics firms in Europe, driven by GDPR compliance mandates. Develop specialized solutions for Tier-1 suppliers facing OEM provenance requirements. A strong go-to-market angle involves active participation in industry-led consortia to establish common standards and gain early ecosystem traction.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialized blockchain platform providers focused on automotive applications. These firms offer strong long-term viability over the next 5-10 years as the market matures beyond pilot projects. Target acquisition candidates include systems integrators with deep automotive ERP expertise and firms developing interoperability solutions. The critical signal to watch as an inflection indicator is the establishment of widely adopted industry-wide data standardization protocols.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces fragmentation and enables seamless data exchange across diverse automotive stakeholders. |
| Zero-Knowledge Proofs Integration | Facilitates secure sharing of confidential commercial data among consortium members without revealing specifics. |
| EV Battery Lifecycle Management | Establishes immutable audit trails for battery provenance and degradation data, meeting regulatory demands. |
| Consortium Governance Development | Ensures equitable data access and cost-sharing frameworks for multi-party automotive blockchain networks. |
| Cloud-Native DLT Solutions | Provides scalable and flexible infrastructure to process high-volume data streams from connected vehicles. |
Research Approach
Cross-validation between primary interviews and extensive secondary research anchors the qualitative findings and quantitative projections. Primary data collection involved conversations with OEM platform engineers, Tier-1 procurement leads, telematics firm CTOs, and DLT solution architects. Secondary sources included regulatory filings from the US EPA and Europe's GDPR, automotive industry reports, and patent databases. This approach enabled comprehensive bottom-up market sizing and top-down validation.
Sensitivity analysis was applied to key market variables, informing the projection of market trajectories across the analysis window. The analytical framework modeled segmentation dimensions including application, technology, end-user, deployment model, and regional adoption patterns. Compound Annual Growth Rates were derived from historical trends and projected future demand. Key industry-specific forecast inputs included connected vehicle data volumes and anticipated regulatory compliance timelines.
Material uncertainties — delays in interoperability standard adoption and talent scarcity — sit outside the modeled envelope. Forecasts reflect assumptions regarding technological maturity and market acceptance. Practitioners should keep alternative scenarios live as the regulatory landscape for vehicle data evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Global Blockchain in Logistics Market
Blockchain Technology
Aviation Transaction Blockchain Market
Blockchain Technology
Blockchain Messaging Apps Market
Blockchain Technology
Global Blockchain IoT Market
Blockchain Technology
Managed Blockchain Services Market
Blockchain Technology
Global Blockchain for Non-Profits Market
Blockchain Technology
Web 3.0 Market
Blockchain Technology
Global Blockchain in Agriculture and Food Supply Chain Market
Blockchain Technology
Global Blockchain in Healthcare Market
Blockchain Technology
Blockchain Technology in Healthcare Market
Blockchain Technology
Global Blockchain in Energy Market
Blockchain Technology
Bitcoin Project Incubator Service Market
Blockchain Technology
Blockchain in Energy Utilities Market
Blockchain Technology
Web 3.0 Blockchain Market
Blockchain Technology
Blockchain Technology in Energy Market
Blockchain Technology
Tokenization Market