
 Global Blockchain in Telecom Market | 2026-2036
Global Blockchain in Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blockchain in Telecom Market Foresight
The capital-intensity divergence between cloud-native blockchain startups and legacy telecom infrastructure giants is collapsing as both camps pour comparable resources into distributed ledger R&D. IBM leverages its enterprise blockchain pedigree to anchor large-scale telecom consortium deployments across multiple continents. ConsenSys specializes in Ethereum-based smart contract architectures that power automated interconnect settlement platforms for mobile network operators.
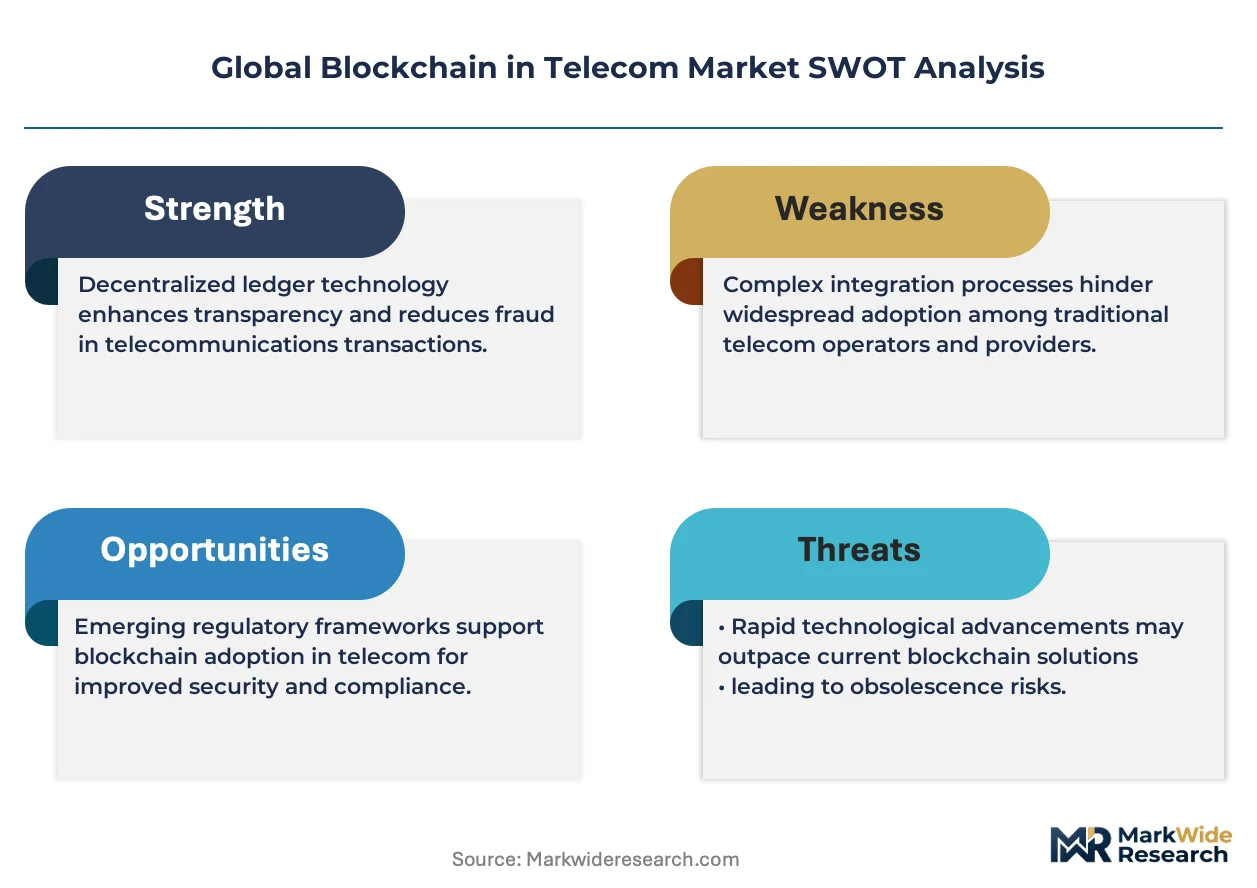
Blockchain in telecom denotes a cryptographically secured, distributed ledger system integrated with carrier-grade network infrastructure to enable tamper-proof transaction validation, subscriber identity verification, and automated service-level agreement enforcement without intermediary clearinghouses. The technology employs consensus mechanisms such as proof-of-authority or Byzantine fault tolerance to process roaming records, interconnect charges, and digital identity credentials at latencies compatible with real-time billing cycles. Identity Management and Fraud Detection solutions currently occupy the most mature margin pools, while Smart Contracts for automated roaming settlements represent the fastest-expanding application area as carriers seek to eliminate multi-month reconciliation delays. Public Blockchain deployments dominate experimental carrier pilots, though Consortium Blockchain configurations are gaining traction among regional operator alliances seeking shared governance without full data transparency.
The European Telecommunications Standards Institute and the GSMA's Fraud and Security Group shape technical interoperability requirements that determine which blockchain architectures gain carrier adoption, while the EU's Digital Operational Resilience Act imposes stringent uptime and auditability standards on critical telecom infrastructure. The US FCC and India's TRAI are separately exploring blockchain-based numbering resource management and spam call traceability mandates that would create regulated demand for carrier-grade distributed systems. Stakeholders must monitor which regulatory body first mandates blockchain-native audit trails for cross-border traffic, as that jurisdiction will likely set the de facto global compliance template that equipment vendors and software providers must engineer toward.
Market Dynamics
Telecom operators face mounting pressure from the EU's Digital Operational Resilience Act to implement real-time audit trails for cross-border traffic, forcing carriers to replace legacy reconciliation systems with distributed ledger infrastructure that can satisfy cryptographic proof requirements without service degradation.
Growth Catalysts
- GDPR-Compliant Identity Frameworks:The EU's Digital Identity Wallet mandates push carriers toward decentralized credential systems that eliminate centralized breach risks while streamlining subscriber onboarding.
- Roaming Fraud Automation:Smart contract architectures enable instant settlement of interconnect charges between operators, compressing multi-month reconciliation cycles to real-time validation.
- Germany's Innovation Concentration:Deutsche Telekom and Vodafone blockchain labs in Berlin and Düsseldorf anchor R&D spillover that accelerates consortium formation across neighboring markets.
Market Restraints
- Energy-Intensive Consensus Mechanisms:Proof-of-work validation protocols impose electricity costs that conflict with carrier sustainability commitments and EU Green Deal carbon reduction targets.
- Silicon Supply Concentration:Specialized hardware security modules for carrier-grade blockchain nodes depend on concentrated semiconductor fabrication capacity in Taiwan and South Korea.
- Latency Constraints:Distributed ledger finality times currently exceed the 50-millisecond thresholds required for real-time billing systems in high-velocity roaming corridors.
Strategic Opportunities
- India's TRAI Mandate Exploration:The regulator's blockchain-based spam call traceability pilots create first-mover advantage for vendors establishing carrier-grade deployments in the world's second-largest mobile market.
- 5G Network Slicing Integration:Convergence between edge computing infrastructure and smart contract automation enables dynamic SLA enforcement for enterprise IoT connectivity without manual intervention.
- Cross-Carrier Data Marketplaces:Consortium blockchain configurations allow regional operator alliances to monetize anonymized subscriber mobility patterns while preserving competitive data boundaries.
Industry Challenges
- Distributed Systems Engineering Scarcity:Carriers struggle to recruit cryptographers with both telecommunications protocol expertise and Byzantine fault tolerance implementation experience.
- Legacy Billing Integration Complexity:SAP and Oracle ERP systems require extensive API middleware development to interface with immutable ledger architectures without disrupting existing invoice workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blockchain in Telecom Market |
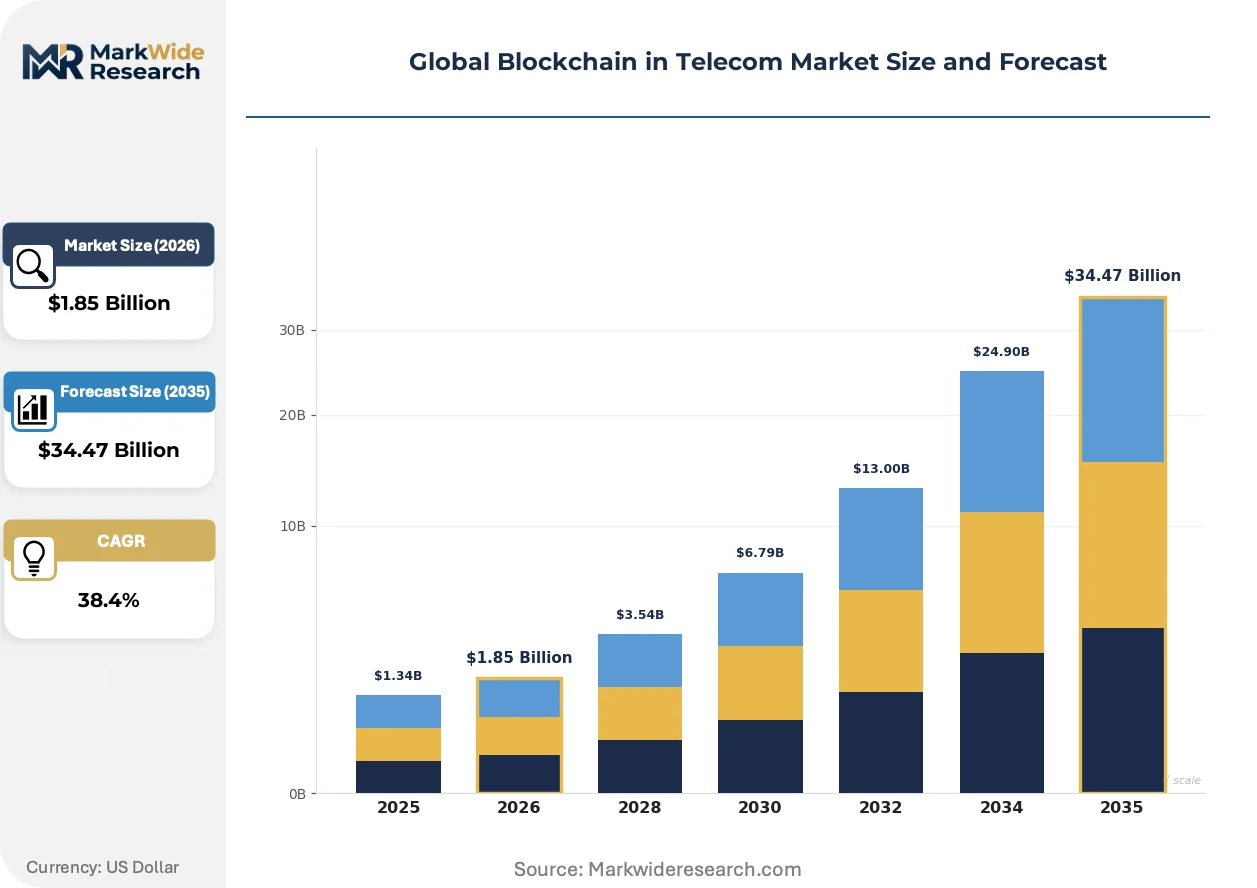
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $34.47 Billion |
| CAGR (2026 – 2036) | 38.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Identity Management, Fraud Detection, Smart Contracts, Data Security, Network Optimization, Billing Automation Application Area: Roaming Management, Subscriber Data Management, Interconnect Settlements, Supply Chain Management, Mobile Payments, Customer Loyalty Programs End User: Telecom Operators, Mobile Virtual Network Operators, Equipment Vendors, Service Providers, Content Aggregators, Infrastructure Providers Deployment Model: Public Blockchain, Private Blockchain, Consortium Blockchain, Hybrid Blockchain |
| Companies Covered | Wildnet Edge, Ethereum, IBM, Alchemy, Chainalysis, ConsenSys, Hyperledger Fabric, Mastercard, LeewayHertz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blockchain in Telecom Market Shifts & Advancements
Blockchain architectures in telecommunications are pivoting from experimental pilots toward production-grade deployments as consensus mechanisms optimize for carrier latency requirements. Three developments dominate this transition.
Proof-of-authority validation is supplanting energy-intensive proof-of-work models in carrier environments. European operators led by Swisscom and Telefónica deploy permissioned networks where pre-approved validator nodes achieve sub-second finality for roaming records. This shift compresses settlement cycles from 90-day reconciliation periods to instantaneous clearing without intermediary correspondent banks.
The EU AI Act's risk classification framework imposes algorithmic transparency requirements on automated decision systems used for fraud detection. Telecom carriers must now maintain immutable audit trails for machine learning models that flag anomalous roaming patterns. German operators have responded by integrating zero-knowledge proof circuits that verify model integrity without exposing proprietary training data.
Enterprise procurement teams now demand consumption-based pricing for blockchain infrastructure rather than perpetual license models. Tier-1 carriers in Singapore and Australia negotiate throughput-metered contracts with platform vendors, replacing upfront capital expenditure with variable costs tied to transaction volume. This shift accelerates adoption among mid-market operators previously priced out of enterprise distributed ledger deployments.
Global Blockchain in Telecom Market Segmentation
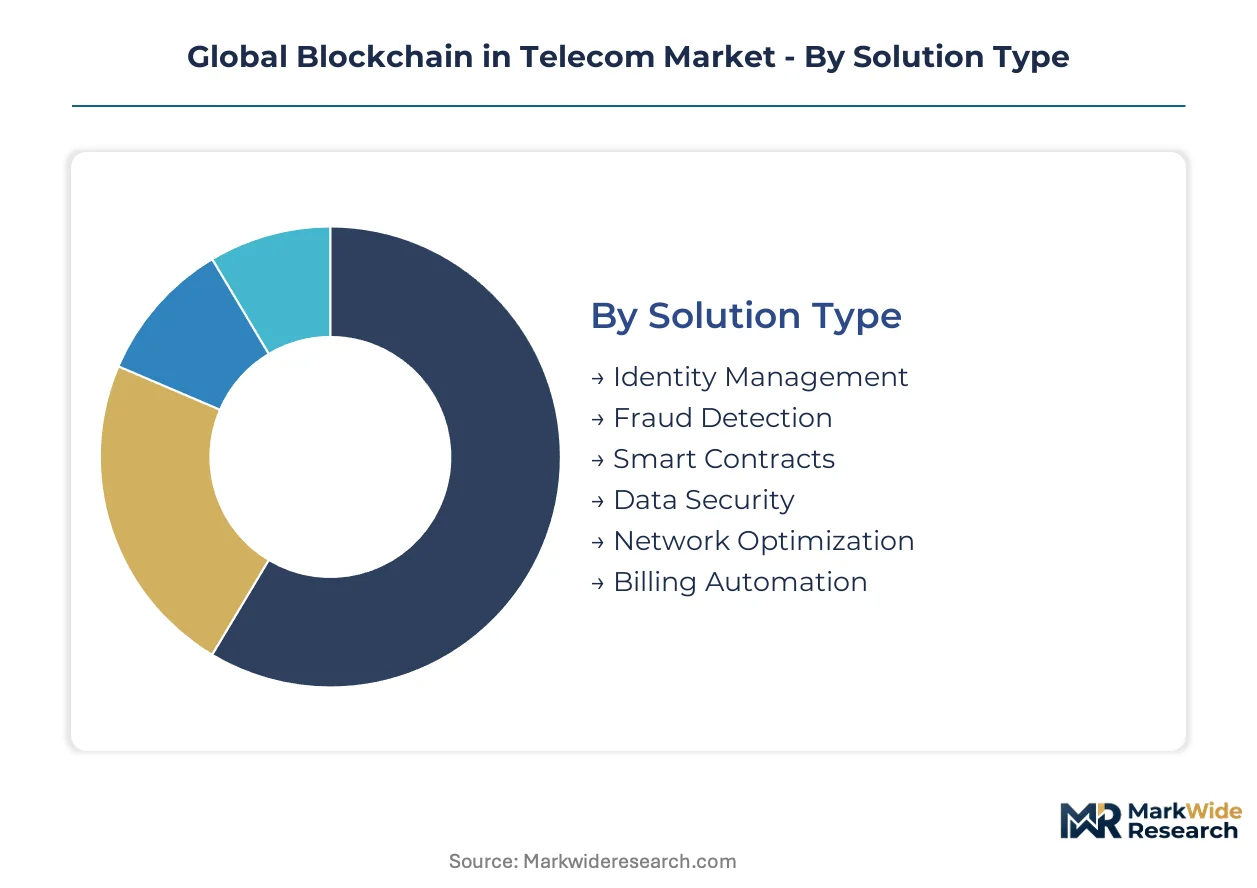
Blockchain deployment patterns in telecommunications diverge sharply across solution architectures and stakeholder configurations. Carrier procurement teams prioritize segments offering immediate compliance leverage against regulatory mandates while deferring speculative infrastructure investments.
Solution Type:
Mature margin pools concentrate in identity verification and fraud prevention where carriers face immediate regulatory deadlines.
- Fraud Detection:Real-time anomaly detection algorithms flag synthetic identity attempts and SIM swap attacks before network entry. Deutsche Telekom and Vodafone Germany deploy these systems under EU Digital Identity Wallet mandates, compressing fraud investigation cycles from weeks to minutes.
- Smart Contracts:Self-executing code automates interconnect charge settlements between roaming partners without correspondent banking delays. Swisscom and Telefónica achieve sub-second finality for cross-border traffic records, eliminating 90-day reconciliation backlogs that plague legacy systems.
- Identity Management:Decentralized credential systems eliminate centralized subscriber databases vulnerable to breach.
- Data Security:Cryptographic hashing protects signaling data integrity across multi-operator exchanges.
- Network Optimization:Distributed ledgers coordinate spectrum allocation in dense urban deployments.
- Billing Automation:Immutable transaction records reduce invoice disputes between carriers and enterprise customers.
The dominant share belongs to Fraud Detection, while Smart Contracts is closing the gap fastest.
Application Area:
Deployment velocity tracks directly to which use cases deliver immediate cost recovery versus long-term infrastructure bets.
- Roaming Management:Blockchain-verified traffic records eliminate clearinghouse intermediaries from international voice and data exchanges. Carriers in Germany and Switzerland report settlement cost reductions exceeding 60% versus legacy correspondent arrangements.
- Interconnect Settlements:Automated reconciliation of termination charges between domestic operators replaces manual invoice matching. India's TRAI pilots demonstrate 48-hour settlement cycles versus 60-day industry averages, creating template demand across South Asian markets.
- Subscriber Data Management:Portable credentials enable seamless carrier switching under GDPR portability rules.
- Supply Chain Management:Equipment provenance tracking secures 5G infrastructure procurement integrity.
- Mobile Payments:Carrier-billed micropayments bypass traditional banking rails for digital content.
- Customer Loyalty Programs:Tokenized reward systems interoperate across partner merchant networks.
Roaming Management commands the installed base, though Interconnect Settlements expands most quickly as regulators mandate faster clearing.
End User:
Procurement authority and technical sophistication determine which stakeholder categories capture implementation value.
- Telecom Operators:Tier-1 carriers deploy consortium architectures to share infrastructure costs while preserving competitive data boundaries. Berlin and Düsseldorf innovation labs anchor R&D spillover accelerating adoption across neighboring European markets.
- Mobile Virtual Network Operators:Thin-capitalized resellers leverage blockchain APIs from host networks to offer differentiated compliance services without proprietary infrastructure investment.
- Equipment Vendors:Hardware manufacturers embed ledger verification into base station firmware for tamper-proof configuration management.
- Service Providers:Systems integrators build middleware connecting carrier legacy billing to distributed ledger architectures.
- Content Aggregators:Media distributors use carrier-grade ledgers for transparent royalty allocation across streaming platforms.
- Infrastructure Providers:Tower companies verify site access permissions through immutable credential systems.
Telecom Operators hold decisive budget authority, while Mobile Virtual Network Operators gain share fastest through API-based service layering.
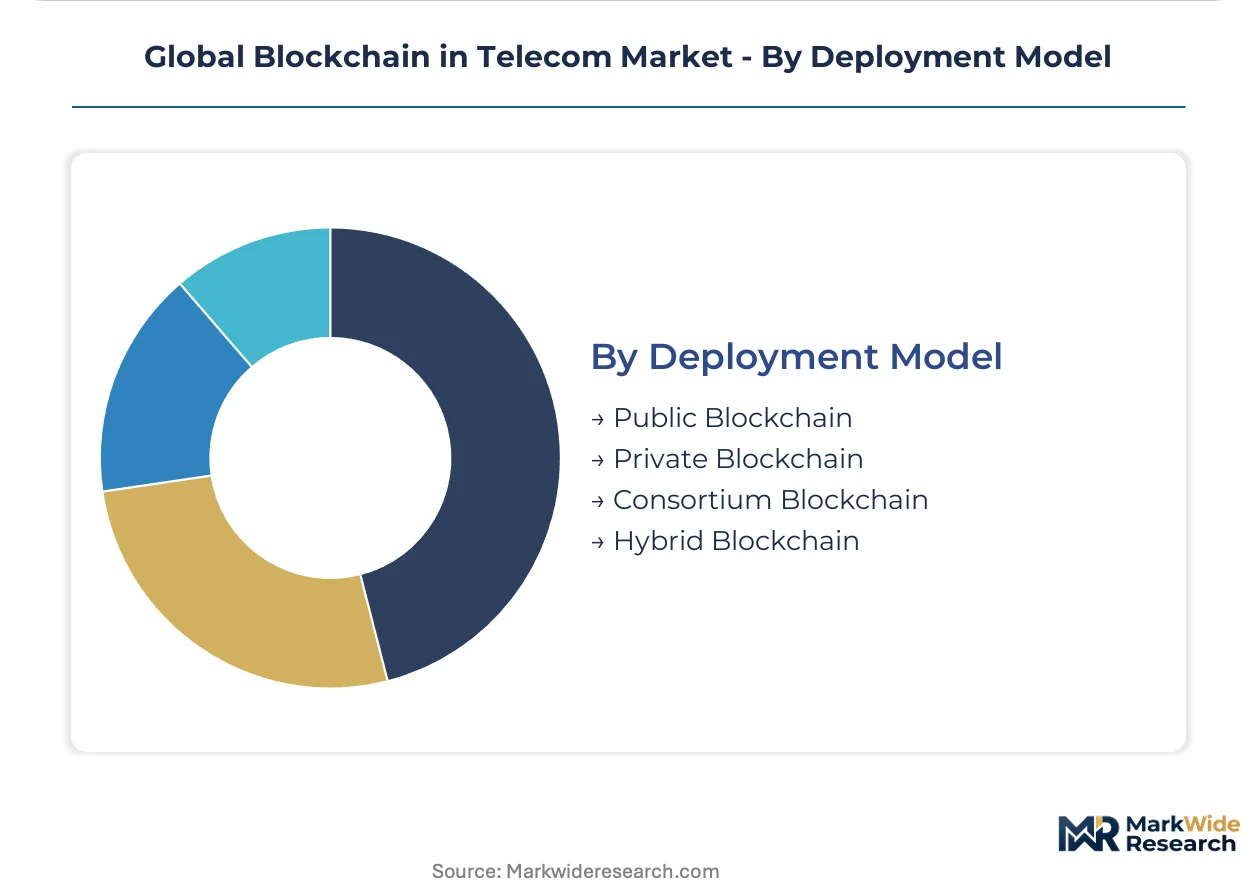
Deployment Model:
Governance requirements and data sensitivity dictate architectural selection across carrier environments.
- Consortium Blockchain:Shared validator networks among regional operator alliances balance transparency with competitive confidentiality. European carrier groups favor this configuration for cross-border roaming exchanges where mutual auditability matters but full data disclosure does not.
- Public Blockchain:Permissionless networks support experimental pilots and cryptocurrency-integrated payment services. Latency constraints and energy costs limit production deployment for real-time billing applications.
- Private Blockchain:Single-operator controlled ledgers satisfy internal audit requirements without external coordination overhead.
- Hybrid Blockchain:Segmented architectures isolate sensitive subscriber data on private chains while anchoring proof to public networks for notarization.
Consortium Blockchain leads commercial deployment, yet Hybrid Blockchain climbs fastest as carriers seek regulatory auditability without full transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across deployment contexts. Operators in Germany and Switzerland absorb premium infrastructure costs to satisfy EU Digital Operational Resilience Act mandates. Indian and Brazilian carriers prioritize per-transaction economics over upfront platform investments.
Germany
Deutsche Telekom and Vodafone anchor Europe's densest carrier blockchain R&D cluster. The EU Digital Identity Wallet mandates under GDPR force rapid decentralized credential deployment. Berlin and Düsseldorf innovation labs drive consortium formation across neighboring Benelux markets.
United States
Verizon and AT&T pilot proof-of-authority networks for cross-border roaming settlements. The FCC explores blockchain-native numbering resource management and spam call traceability frameworks. Dallas-Fort Worth and Seattle metro areas concentrate vendor engineering talent for carrier-grade distributed systems.
India
Reliance Jio and Bharti Airtel test 48-hour interconnect settlement cycles under TRAI blockchain pilots. The regulator's spam traceability mandate creates regulated demand for carrier-grade ledgers. Bengaluru and Hyderabad anchor domestic systems integrator capacity for SAP-Oracle middleware development.
Switzerland
Swisscom achieves sub-second finality for roaming records through permissioned validator networks. The country's financial regulator aligns telecom infrastructure rules with banking-grade auditability standards. Zurich concentrates Ethereum enterprise engineering talent for smart contract automation platforms.
Singapore
Singtel negotiates throughput-metered blockchain contracts replacing perpetual license models. The Monetary Authority of Singapore's digital asset framework permits carrier-billed micropayments for digital content. The city-state's data center density supports edge-ledger convergence for 5G network slicing.
Global Blockchain in Telecom Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier. IBM and ConsenSys anchor enterprise consortium deployments with comparable R&D scale to legacy infrastructure giants. Three archetypes dominate: cloud-native protocol developers, enterprise systems integrators, and financial services incumbents. Competitive moves concentrate on strategic partnerships for carrier API integration and geographic expansion into regulator-mandated pilot markets.
Within the protocol infrastructure tier, Ethereum and Hyperledger Fabric exemplify contrasting architectural philosophies for carrier environments. IBM represents the enterprise systems integrator archetype with cross-continental telecom consortium anchoring. Among payment-integrated specialists, Mastercard occupies a position bridging traditional banking rails with carrier-billed transaction architectures.
| Leading Market Players |
|---|
| Wildnet Edge |
| Ethereum |
| IBM |
| Alchemy |
| Chainalysis |
| ConsenSys |
| Hyperledger Fabric |
| Mastercard |
| LeewayHertz |
| Others |
Supply & Pricing Matrix
EU Digital Operational Resilience Act compliance gates both vendor qualification and price differentiation simultaneously, forcing carriers to pay premiums for cryptographic audit trails while excluding uncertified middleware providers from procurement shortlists.
Pricing Analysis
Throughput-metered service contracts now drive lifetime value more than perpetual licensing. Three-tier pricing structure across premium, standard, and economy levels separates carriers requiring sub-second finality from those tolerating batch settlement delays. Price differentiation rests on consensus mechanism latency and GDPR certification tier. Cost compression in economy-tier deployments is intensifying because Indian and Brazilian carriers prioritize per-transaction economics. Mobile Virtual Network Operators exhibit highest price sensitivity; tier-1 German operators absorb premium infrastructure costs with minimal negotiation leverage.
Supply Chain Analysis
Just-in-time inventory strategies dominate hardware procurement for carrier-grade blockchain nodes, though strategic stockpiling of specialized hardware security modules persists given Taiwan and South Korea fabrication concentration. Semiconductor fabrication for HSMs centers on Taiwan, South Korea, and select German foundries. Raw material dependencies include advanced lithography equipment, cryptographic accelerator chips, and carrier-grade server chassis. Single-source vulnerability concentrates in TSMC advanced node capacity for validator hardware. Distribution runs through systems integrators with SAP-Oracle middleware expertise rather than direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as regulatory mandates for real-time roaming audit trails force carrier infrastructure replacement faster than organic technology adoption curves would predict.
For Market Incumbents: Compound consortium membership advantages by anchoring cross-border validator networks before regional operator alliances crystallize around competing platforms. Invest in zero-knowledge proof R&D to defend margin position against cloud-native challengers undercutting on implementation speed. Prioritize backward integration into cryptographic accelerator supply through foundry partnerships mitigating Taiwan concentration risk.
For New Entrants and Emerging Players: API-based compliance services for Mobile Virtual Network Operators represent the most penetrable white-space target, as thin-capitalized resellers lack proprietary infrastructure investment capacity. India's TRAI-mandated spam traceability pilots offer first-mover positioning in the world's second-largest mobile market. Pursue consumption-based pricing models that replace upfront capital expenditure with variable costs tied to transaction volume.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across consortium blockchain deployments as shared infrastructure costs replace standalone platform builds. Long-term viability over the next decade favors vendors with demonstrated carrier ERP integration capabilities rather than protocol-layer specialists. Acquisition targets should show proven SAP-Oracle middleware development capacity. The signal to watch is which regulator first mandates blockchain-native audit trails for cross-border traffic, as that jurisdiction will set the de facto global compliance template.
| Strategic Initiative | Industry Significance |
|---|---|
| Consortium Blockchain Deployment | Shared validator networks among Deutsche Telekom and Vodafone reduce infrastructure costs while preserving competitive data boundaries. |
| Zero-Knowledge Proof Integration | German operators deploy ZK circuits under EU AI Act algorithmic transparency mandates without exposing proprietary training data. |
| Throughput-Metered Contract Negotiation | Singtel replaces perpetual licenses with variable pricing tied to transaction volume, accelerating mid-market operator adoption. |
| Proof-of-Authority Network Migration | Swisscom and Telefónica achieve sub-second finality for roaming records, eliminating 90-day reconciliation backlogs. |
| ERP Middleware Development | Systems integrators build API layers connecting carrier legacy billing to distributed ledger architectures without disrupting invoice workflows. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in this study. Primary research encompassed blockchain protocol engineers, carrier procurement executives, regulatory affairs leads at tier-1 operators, and systems integration specialists with SAP-Oracle middleware expertise. Secondary sources included ETSI technical standards documentation, GSMA Fraud and Security Group publications, EU Digital Operational Resilience Act regulatory texts, TRAI consultation papers, and SEC filings from publicly traded telecom infrastructure vendors. Bottom-up deployment estimates triangulate against top-down market sizing derived from carrier capex disclosures.
Sensitivity analysis around consensus mechanism adoption rates and regulatory mandate timing shapes the projection framework. The model segments by solution architecture, application area, deployment model, and end-user category across the analysis window. CAGRs derive from carrier infrastructure replacement cycles and regulatory compliance deadlines rather than organic technology diffusion curves. Key inputs include EU Digital Identity Wallet implementation timelines, TRAI spam traceability mandate progression, and 5G network slicing investment trajectories.
Forecasts assume regulatory continuity in EU GDPR enforcement, India's TRAI mandate exploration, and US FCC numbering resource management pilots; material policy shifts would require re-modeling. Carrier consolidation, semiconductor supply disruptions, or latency breakthroughs in alternative consensus mechanisms present specific revision triggers. Revision becomes warranted when sub-second finality thresholds breach 50-millisecond roaming corridor requirements at scale.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Global Blockchain Market
Blockchain Technology
Blockchain Messaging Apps Market
Blockchain Technology
Bitcoin Technology Market
Blockchain Technology
Blockchain Game Market
Blockchain Technology
Blockchain in Aviation Market
Blockchain Technology
Blockchain Gaming Market
Blockchain Technology
Global Blockchain Government Market
Blockchain Technology
Web 3.0 Blockchain Market
Blockchain Technology
Aviation Transaction Blockchain Market
Blockchain Technology
Blockchain Identity Management Market
Blockchain Technology
Blockchain Device Market
Blockchain Technology
Blockchain Retail Market
Blockchain Technology
Europe Blockchain Market
Blockchain Technology
Global Blockchain in Energy Market
Blockchain Technology
Global Blockchain for Non-Profits Market
Blockchain Technology
Tokenization Market