
 Managed Blockchain Services Market | 2026-2036
Managed Blockchain Services Market Size, Share, and Industry Trends Forecast 2026-2036
Managed Blockchain Services Market Foresight
Singapore's sovereign blockchain infrastructure build-out is rewriting competitive dynamics for managed ledger platforms in Asia-Pacific. Amazon Web Services leverages its cloud-native architecture to dominate enterprise node hosting and consensus-layer management. Microsoft Azure sustains deep integration with legacy enterprise resource planning systems, anchoring its position in hybrid deployment environments. IBM Blockchain specializes in permissioned network configurations for regulated industries, differentiating through hardware security module compatibility.
Managed blockchain services encompass the outsourced operation, maintenance, and governance of distributed ledger networks, typically delivered through API-accessible infrastructure with guaranteed uptime thresholds and cryptographic key escrow protocols. These services eliminate the capital expenditure and specialized engineering talent required for self-hosted node clusters, enabling enterprises to deploy smart contracts and immutable audit trails without maintaining consensus infrastructure. Infrastructure management commands the largest revenue pool among service types, reflecting the operational complexity of validator node orchestration and network synchronization across geographically dispersed participants. Security services represent the fastest-expanding segment, driven by escalating demand for multi-party computation vaults and quantum-resistant signature schemes. Consulting engagements retain the highest margin profile, particularly for firms architecting cross-organizational governance frameworks for consortium chains.
The US SEC, EU's EBA, and Singapore's MAS collectively shape market access through divergent custody, disclosure, and reserve-auditing mandates that determine which service architectures qualify for institutional deployment. ISO 27001 and SOC 2 Type II certifications function as baseline procurement filters, with financial institutions increasingly requiring additional CCSS Level 3 attestation for cryptocurrency-adjacent operations. Stakeholders must evaluate whether their compliance investments align with the most restrictive jurisdiction in their client footprint, as regulatory arbitrage opportunities narrow with bilateral information-sharing agreements.
Market Dynamics
Enterprise demand for quantum-resistant cryptographic infrastructure is compressing procurement cycles for managed ledger platforms as financial institutions race to secure cross-border settlement networks against future decryption threats.
Growth Catalysts
- Project Guardian (Singapore):The Monetary Authority of Singapore's institutional blockchain initiative is accelerating deployment of tokenized asset infrastructure across Asia-Pacific wealth management hubs.
- Cross-border settlement automation:Distributed ledger networks are eliminating correspondent banking delays for trade finance, with commodity traders demanding real-time atomic settlement.
- Hardware security module integration:Regulated industries are mandating HSM-compatible key custody for validator node operations, expanding managed service attach rates.
Market Restraints
- Specialized engineering talent scarcity:Consensus protocol optimization and Byzantine fault tolerance engineering skills concentrate in Zurich, Singapore, and Palo Alto hiring pools.
- Cloud infrastructure concentration:Validator node hosting relies on three hyperscale providers, creating single-point-of-failure exposure for geographically distributed networks.
- Regulatory fragmentation:Divergent custody mandates from the US SEC, EU EBA, and Singapore MAS force service providers to maintain jurisdiction-specific architecture variants.
Strategic Opportunities
- Tokenized real-world assets:Private credit funds and real estate investment trusts are piloting on-chain fractionalization, creating demand for compliant issuance infrastructure.
- Multi-party computation vaults:Institutional cryptocurrency custody is shifting from cold storage to distributed key generation protocols, opening managed security service revenue pools.
- EU Markets in Crypto-Assets framework:MiCA's reserve-auditing and disclosure mandates are creating compliance-as-a-service opportunities for infrastructure providers serving European clients.
Industry Challenges
- Smart contract audit talent bottleneck:Formal verification engineers capable of certifying DeFi protocols remain scarce, extending deployment timelines for institutional clients.
- Legacy ERP integration complexity:SAP and Oracle system connectivity requires custom middleware development, inflating implementation costs for hybrid deployment environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Managed Blockchain Services Market |
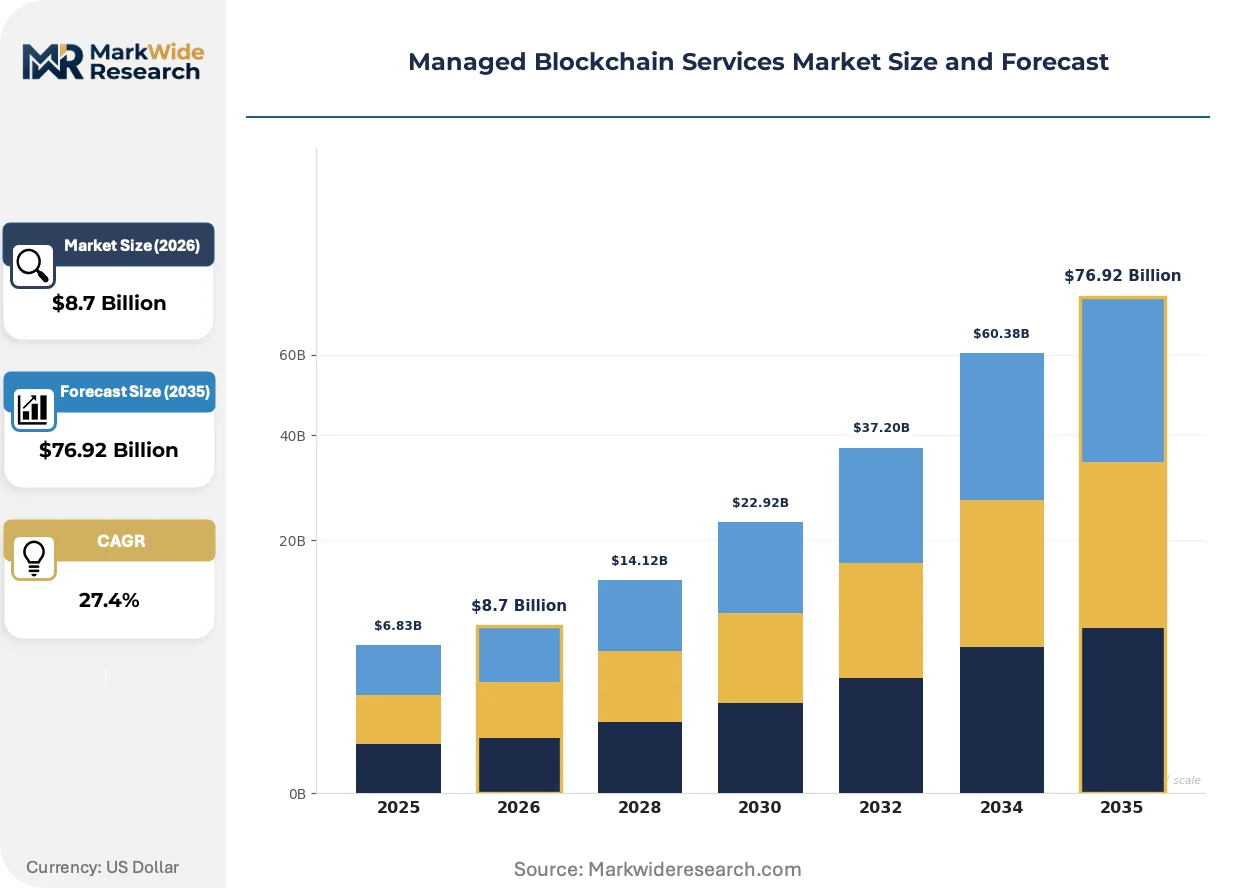
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $76.92 Billion |
| CAGR (2026 – 2036) | 27.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Infrastructure Management, Security Services, Consulting, Integration Services End User: Financial Institutions, Supply Chain Companies, Healthcare Providers, Government Entities Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Application Area: Smart Contracts, Identity Verification, Asset Management, Voting Systems |
| Companies Covered | Amazon Web Services, Microsoft Azure, IBM Blockchain, Google Cloud, Oracle, Accenture, Deloitte, Ernst & Young, Capgemini, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Managed Blockchain Services Market Shifts & Advancements
Managed blockchain infrastructure is converging with confidential computing and zero-knowledge proof systems, enabling privacy-preserving validation without exposing transaction details to node operators.
Zero-knowledge rollup architectures are migrating from experimental deployment to production-grade settlement layers for institutional payment networks. Major commodity exchanges are adopting zk-SNARK-based batch verification to compress on-chain footprint while maintaining auditability. This migration from monolithic chains to modular execution environments is fragmenting infrastructure spend across sequencing, data availability, and proof generation service tiers.
The EU's Markets in Crypto-Assets regulation is mandating segregated custody and reserve transparency for stablecoin issuers operating across member states. Service providers must now maintain real-time attestation infrastructure and cold-wallet segregation protocols that exceed traditional SOC 2 requirements. Asset managers domiciled in Luxembourg and Ireland are restructuring their custody stacks to comply with these reserve-auditing mandates ahead of enforcement deadlines.
Enterprise buyers are consolidating vendor relationships around full-stack infrastructure providers capable of delivering node hosting, key management, and governance tooling through unified APIs. Discrete point solutions for consensus monitoring or validator orchestration are losing procurement share to integrated platforms. This consolidation pattern is most pronounced among Singapore-headquartered financial institutions participating in Project Guardian tokenization pilots.
Managed Blockchain Services Market Segmentation
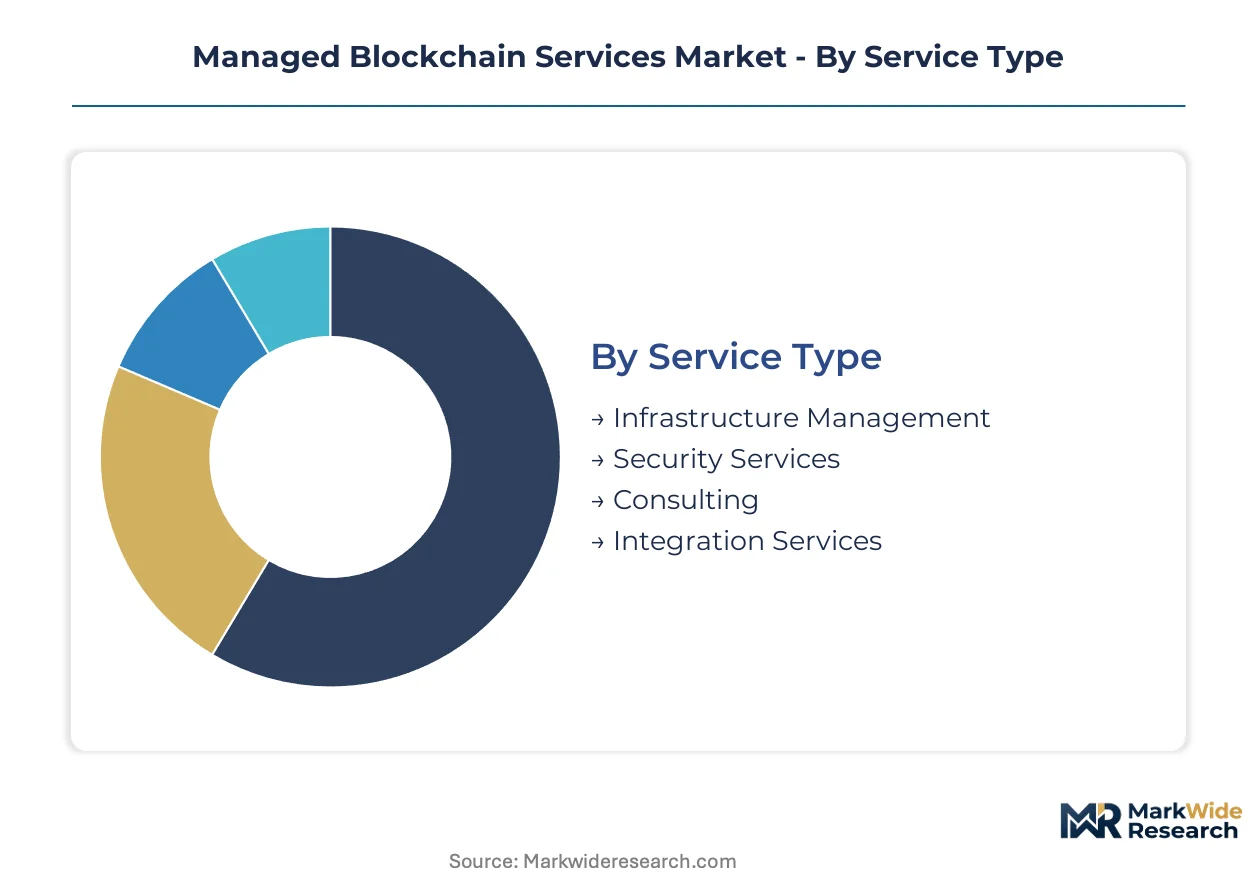
Managed blockchain services fragment across four operational dimensions that determine procurement patterns and margin structures. Service type dictates the technical intensity of vendor relationships, while deployment model choices reflect regulatory exposure and data sovereignty requirements. End user concentration and application specificity shape pricing elasticity and contract duration.
Service Type:
After-sales service intensity varies dramatically across service tiers, with infrastructure management demanding 24/7 operational support while consulting engagements require episodic governance architecture reviews.
- Infrastructure Management:Validator node orchestration, network synchronization, and consensus-layer maintenance delivered through API-accessible platforms with guaranteed uptime thresholds. Demand concentrates among Singapore-headquartered financial institutions participating in tokenization pilots, driven by the operational complexity of geographically dispersed participant coordination. Infrastructure management commands the largest revenue pool among service types.
- Security Services:Multi-party computation vaults, cryptographic key escrow protocols, and quantum-resistant signature schemes. Financial institutions across Luxembourg and Ireland are restructuring custody stacks to comply with EU reserve-auditing mandates, accelerating procurement of HSM-compatible managed security services. Security services are expanding most quickly as institutions race to secure cross-border settlement networks.
- Consulting:Cross-organizational governance framework architecture for consortium chains.
- Integration Services:Middleware development connecting distributed ledgers to SAP and Oracle ERP systems.
Infrastructure management holds the largest share; momentum sits with security services.
End User:
Cost tier stratification separates premium institutional clients with compliance mandates from mid-market adopters prioritizing speed-to-deployment over customization depth.
- Financial Institutions:Banks, asset managers, and commodity traders deploying tokenized settlement infrastructure. Demand clusters in Singapore's wealth management hubs and European private credit funds piloting on-chain fractionalization, constrained by specialized engineering talent scarcity in Zurich, Singapore, and Palo Alto hiring pools.
- Supply Chain Companies:Commodity traders and logistics operators demanding real-time atomic settlement for trade finance.
- Healthcare Providers:Institutions implementing immutable audit trails for pharmaceutical supply chain verification.
- Government Entities:Public sector bodies exploring permissioned networks for identity and record-keeping applications.
Financial institutions dominate current spend; supply chain companies are gaining share fastest as trade finance automation accelerates.
Deployment Model:
Volume concentration favors public cloud configurations for development environments, with production workloads shifting toward hybrid architectures that balance scalability against data residency requirements.
- Public Cloud:Hyperscale-hosted validator nodes and consensus infrastructure. Enterprise buyers are consolidating around full-stack providers capable of delivering unified APIs, with discrete point solutions losing procurement share to integrated platforms.
- Private Cloud:Single-tenant infrastructure for institutions with strict data sovereignty mandates.
- Hybrid Cloud:Split workloads with sensitive operations on-premises and scalability layers in cloud environments. Demand is concentrating among regulated industries requiring HSM-compatible key custody while maintaining elastic compute capacity.
- On-Premises:Self-hosted node clusters for entities with specialized compliance or air-gapped security requirements.
Public cloud retains the largest installed base; hybrid cloud shows the steepest expansion trajectory as regulatory fragmentation forces jurisdiction-specific architecture variants.
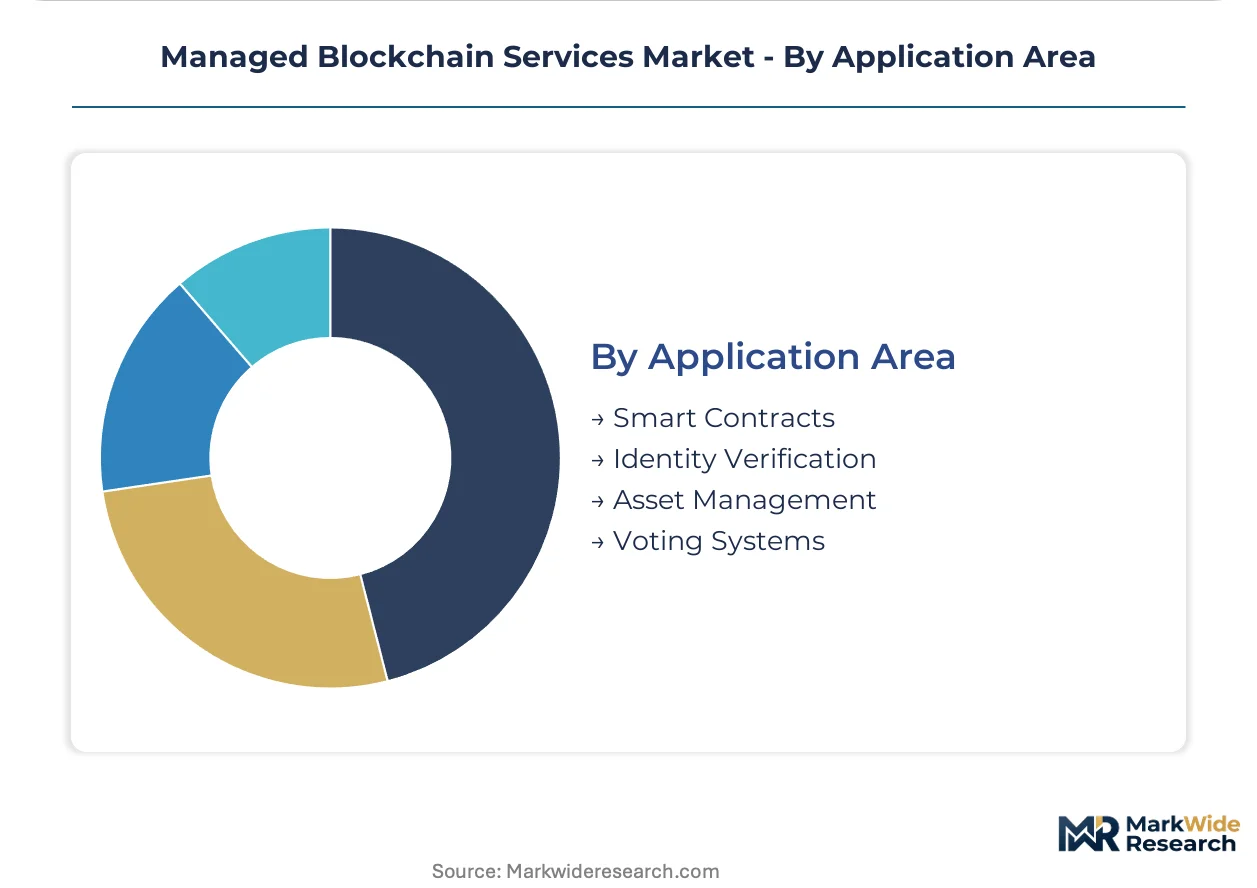
Application Area:
Customer type differentiation separates institutional buyers seeking production-grade settlement infrastructure from experimental adopters testing governance automation.
- Smart Contracts:Self-executing agreements for trade finance and asset settlement. Major commodity exchanges are adopting zk-SNARK-based batch verification to compress on-chain footprint while maintaining auditability.
- Identity Verification:Decentralized credential systems for KYC and access management.
- Asset Management:Tokenized real-world asset infrastructure for private credit and real estate investment trusts. Real estate investment trusts and private credit funds are piloting compliant issuance infrastructure for fractionalized ownership.
- Voting Systems:Immutable record-keeping for corporate governance and organizational decision-making.
Smart contracts anchor current deployment value; asset management is climbing the fastest as tokenization pilots expand across Asia-Pacific wealth hubs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud providers concentrate validator node hosting across three dominant infrastructure stacks, creating single-point-of-failure exposure for geographically distributed networks. Singapore's Project Guardian initiative is accelerating institutional-grade deployment faster than any other jurisdiction. Regulatory divergence between the US SEC, EU EBA, and Singapore MAS forces service providers to maintain jurisdiction-specific architecture variants.
United States
Financial institutions in New York and Palo Alto are racing to secure cross-border settlement networks against quantum decryption threats. The SEC mandates HSM-compatible key custody and reserve-auditing protocols that exceed traditional SOC 2 requirements. Enterprise buyers in Manhattan's wealth management corridor are consolidating vendor relationships around full-stack infrastructure providers.
Singapore
Project Guardian is driving tokenized asset infrastructure deployment across Asia-Pacific wealth management hubs. MAS regulations require real-time attestation infrastructure and cold-wallet segregation for institutional custody operations. The Marina Bay financial district hosts the densest concentration of validator node orchestration talent outside Zurich.
Germany
Asset managers in Frankfurt and Luxembourg are restructuring custody stacks to comply with EU reserve-auditing mandates ahead of enforcement deadlines. The EBA's divergent custody mandates from US and Asian regulators force architecture variants for European clients. Bavaria's industrial clusters are piloting permissioned networks for trade finance automation.
United Kingdom
Commodity traders in London are demanding real-time atomic settlement for trade finance, eliminating correspondent banking delays. The Financial Conduct Authority's disclosure requirements shape compliant issuance infrastructure for tokenized real-world assets. The City of London anchors European demand for multi-party computation vaults and quantum-resistant signature schemes.
Switzerland
Zurich's hiring pools concentrate scarce consensus protocol optimization and Byzantine fault tolerance engineering skills. FINMA guidelines on cryptocurrency custody influence institutional procurement standards across continental Europe. The Zug crypto valley cluster hosts specialized smart contract audit and formal verification engineering capacity.
Managed Blockchain Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in validator orchestration and cryptographic key management. The vendor base separates into three strategic archetypes: hyperscale cloud-native platforms, legacy enterprise integrators with ERP connectivity depth, and boutique security specialists focused on HSM-compatible custody. Consolidation pressure favors full-stack providers capable of unified API delivery. Competitive moves center on strategic partnerships for regulatory coverage and portfolio diversification into quantum-resistant infrastructure.
Within the hyperscale tier, Amazon Web Services and Microsoft Azure exemplify cloud-native dominance in node hosting and consensus-layer management. IBM Blockchain occupies a position anchoring permissioned network configurations for regulated industries through hardware security module compatibility. Among consulting-heavy integrators, Accenture represents the governance architecture specialization required for cross-organizational consortium chains.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| IBM Blockchain |
| Google Cloud |
| Oracle |
| Accenture |
| Deloitte |
| Ernst & Young |
| Capgemini |
| Others |
Supply & Pricing Matrix
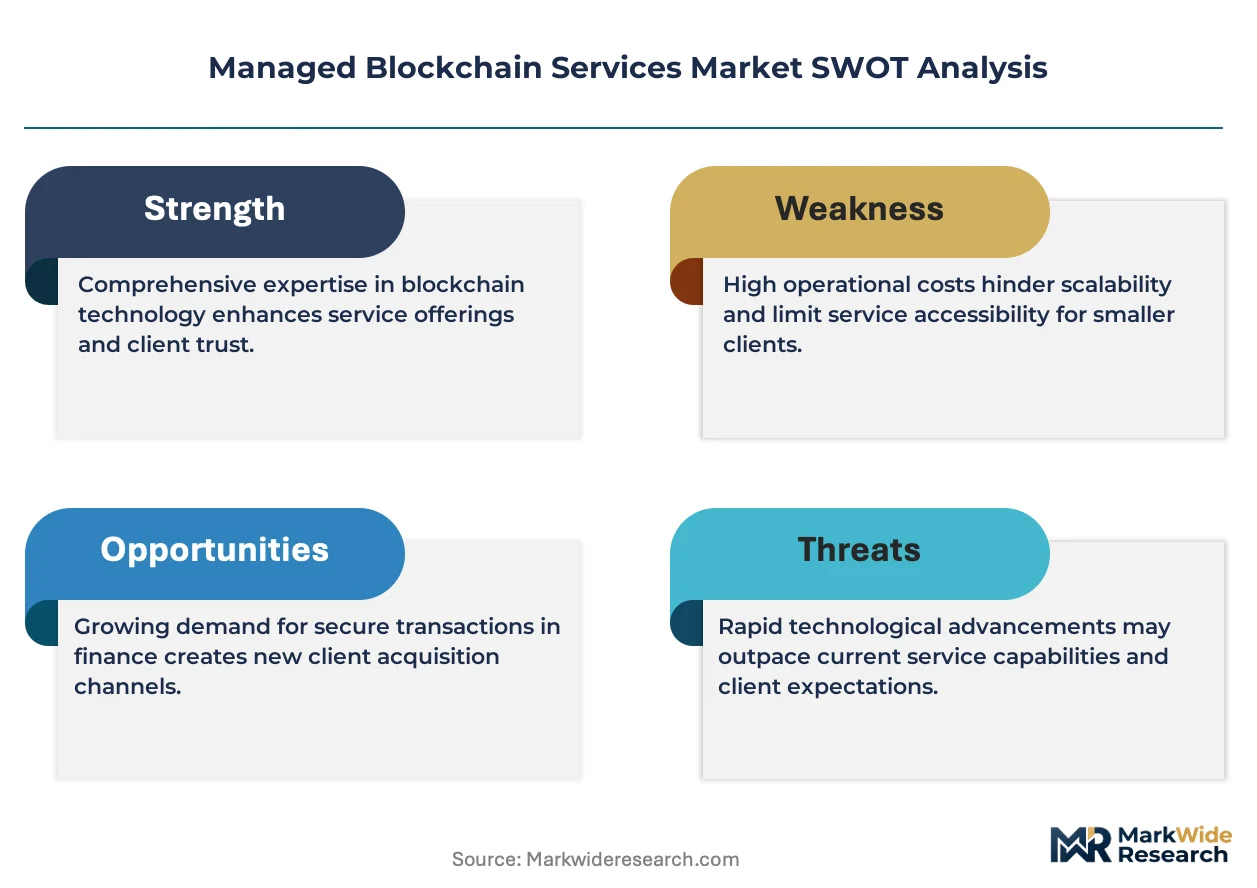
Validator node hosting overcapacity in Northern Virginia and Singapore is compressing infrastructure management margins while simultaneously accelerating procurement of premium security services, creating divergent pricing trajectories across service tiers that reward specialized cryptographic capabilities over commodity compute provisioning.
Pricing Analysis
EU Markets in Crypto-Assets reserve-auditing mandates dictate the pricing tier structure for institutional custody services, with HSM-compatible key management commanding premium positioning above standard API-accessible node hosting. Three-tier pricing structure across premium, standard, and economy levels separates quantum-resistant signature schemes from baseline consensus-layer maintenance from development-environment sandboxes. Cost compression in standard infrastructure tiers is intensifying because hyperscale cloud providers are absorbing validator orchestration into bundled compute contracts. Mid-market supply chain companies piloting trade finance automation exhibit highest price sensitivity, while Singapore-headquartered wealth managers participating in Project Guardian demonstrate lowest elasticity for compliant custody stacks.
Supply Chain Analysis
Upstream cryptographic hardware feeds from Taiwan's semiconductor foundries, Switzerland's precision manufacturing clusters, and China's ASIC fabrication facilities. Managed blockchain services draw from specialized engineering talent concentrated in Zurich, Singapore, and Palo Alto alongside quantum-resistant algorithm libraries developed in academic and national laboratory settings. Single-source vulnerability in HSM chip supply creates concentration risk for regulated custody operations. Distribution runs through direct enterprise sales for institutional clients and API marketplaces for mid-market developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between the US SEC, EU EBA, and Singapore MAS is fragmenting compliance requirements into jurisdiction-specific niches, creating specialized service opportunities for providers architecting modular infrastructure stacks adaptable to multiple regulatory anchors.
For Market Incumbents: Harden competitive positioning through backward integration into quantum-resistant cryptographic hardware development and exclusive partnerships with Zurich-based formal verification engineering pools. Hyperscale cloud providers absorbing validator hosting into commodity compute bundles threaten margin compression in infrastructure management tiers. Capacity addition in Singapore's Marina Bay financial district anchors regional talent acquisition for Project Guardian participation. For New Entrants and Emerging Players: Mid-market commodity traders in London and Frankfurt seeking atomic settlement without full institutional compliance overhead represent the most penetrable entry point. Boutique multi-party computation vault services for European private credit funds restructuring custody stacks ahead of MiCA enforcement deadlines offer second white-space target. Go-to-market positioning as MiCA compliance-as-a-service specialists bypasses direct competition with hyperscale infrastructure incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward boutique security specialists with HSM-compatible custody certifications and established relationships with Luxembourg and Ireland asset managers. Long-term viability hinges on quantum-resistant infrastructure transition timing and regulatory harmonization trajectory across the analysis window. Signal to monitor: bilateral information-sharing agreements narrowing regulatory arbitrage opportunities between US, EU, and Singapore jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Quantum-Resistant Infrastructure Migration | Positions providers ahead of NIST post-quantum cryptographic standards adoption by financial institutions. |
| MiCA Compliance-as-a-Service Buildout | Captures reserve-auditing and real-time attestation demand from European asset managers ahead of enforcement. |
| Project Guardian Partnership | Secures preferred vendor status for Singapore's tokenized asset infrastructure pilots across Asia-Pacific wealth hubs. |
| HSM Hardware Security Integration | Differentiates custody offerings for regulated industries mandating segregated key management protocols. |
| Formal Verification Engineering Acquisition | Addresses smart contract audit talent bottleneck extending institutional deployment timelines. |
Research Methodology
Operator-level perspectives from blockchain infrastructure architects, cryptographic security officers, regulatory compliance leads at asset managers, and consensus protocol engineers anchored the qualitative base. Secondary validation drew from SEC disclosure filings, MAS regulatory circulars, EU EBA technical standards, ISO 27001 certification databases, and hyperscaler capex disclosures. Bottom-up service provider revenue triangulation against top-down enterprise IT spending allocation produced convergent market sizing across the analysis window.
Scenario-bracketing around regulatory harmonization and quantum computing advancement timelines shaped the analytical framework. Segmentation dimensions modeled include service type, deployment architecture, end-user industry vertical, and geographic regulatory cluster. CAGRs were derived from fitted growth curves calibrated to disclosed infrastructure deployment volumes and custody service contract values. Forecast inputs incorporated Project Guardian pilot expansion trajectories and MiCA implementation phase transitions.
Practitioners should monitor bilateral regulatory information-sharing agreement announcements and NIST post-quantum cryptographic standard finalization for early signals necessitating forecast revision. Cross-checking against disclosed hyperscaler blockchain service revenue segments is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Global Blockchain for Non-Profits Market
Blockchain Technology
Blockchain Device Market
Blockchain Technology
Europe Blockchain Market
Blockchain Technology
Blockchain in Manufacturing Market
Blockchain Technology
Blockchain AI Market
Blockchain Technology
Global Blockchain in Energy Market
Blockchain Technology
Smart Contracts on Blockchain Market
Blockchain Technology
Tokenization Market
Blockchain Technology
Aviation Transaction Blockchain Market
Blockchain Technology
Blockchain Messaging Apps Market
Blockchain Technology
Blockchain Game Market
Blockchain Technology
Pharmaceutical Blockchain Market
Blockchain Technology
Blockchain in Aviation Market
Blockchain Technology
Blockchain in Energy Utilities Market
Blockchain Technology
Blockchain Gaming Market
Blockchain Technology
Industrial Blockchain Technology Market