
 Bitcoin Technology Market | 2026-2036
Bitcoin Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Bitcoin Technology Market Analysis
North American mining pool operators is broadening hash rate capacity through Texas-based renewable energy farms. Bitmain Technologies leverages vertical integration into ASIC chip design to sustain manufacturing cost advantages. Canaan Inc. anchors its competitive position through specialized focus on high-efficiency mining equipment. Lightning Labs differentiates by advancing off-chain payment protocol development for enterprise settlement use cases.
Bitcoin technology encompasses the distributed ledger infrastructure, consensus mechanisms, and cryptographic protocols enabling peer-to-peer value transfer without intermediary settlement. The system relies on SHA-256 proof-of-work hashing, block propagation intervals of approximately ten minutes, and a fixed supply cap of twenty-one million units to enforce scarcity and transaction finality. Mining hardware commands concentrated margin pools due to silicon fabrication constraints and energy arbitrage requirements. Payment processing applications attract accelerating institutional interest as settlement latency improves through layer-two protocol adoption. Financial institutions represent the most scrutinized end-user segment as compliance costs reshape platform economics.
The SEC enforces securities registration mandates for staking and yield products, while the CFTC asserts jurisdiction over Bitcoin futures and derivatives markets. FinCEN's Bank Secrecy Act requirements impose know-your-customer obligations on exchanges and custodial wallet providers. The EU's Markets in Crypto-Assets framework introduces uniform licensing standards across member states. Stakeholders must monitor how jurisdictional fragmentation between commodity and securities classifications affects cross-border service provision and capital deployment timelines.
Market Dynamics
Layer-two protocol maturation is compressing settlement latency from ten-minute block confirmations to near-instant finality, forcing infrastructure providers to retool custody and payment stacks around off-chain capability.
Growth Catalysts
- EU Markets in Crypto-Assets (MiCA) framework:Uniform licensing standards across member states reduce regulatory arbitrage costs for cross-border service providers.
- Texas renewable energy clusters:Abundant wind and solar capacity attracts mining hardware deployment through power purchase agreements below grid averages.
- Institutional custody infrastructure:Singaporean banks expanding cold-storage and insurance-backed holding solutions for sovereign wealth and pension fund mandates.
Market Restraints
- Silicon fabrication concentration:TSMC and Samsung foundries in Taiwan and South Korea control advanced ASIC chip production, creating single-source vulnerability.
- SEC registration mandates:Securities registration requirements for staking and yield products impose compliance costs that squeeze retail platform margins.
- Energy input volatility:Natural gas price swings in North American baseload markets directly compress mining operation profitability during winter demand spikes.
Strategic Opportunities
- Lightning Network enterprise settlement:Off-chain payment channels enable micropayment streaming for content platforms and machine-to-machine transactions.
- India's regulatory clarity gap:Absence of comprehensive digital asset legislation creates first-mover positioning for compliant infrastructure buildout before formal frameworks emerge.
- Hash rate financialization instruments:Derivatives contracts pegged to network difficulty and block rewards attract commodity trading desks seeking uncorrelated exposure.
Industry Challenges
- Cryptographic engineering talent scarcity:Shortage of protocol-level developers familiar with elliptic curve cryptography and consensus mechanism design extends product roadmaps.
- Legacy banking system integration:Correspondent banking relationships require expensive middleware development to bridge fiat on-ramps with blockchain settlement layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bitcoin Technology Market |
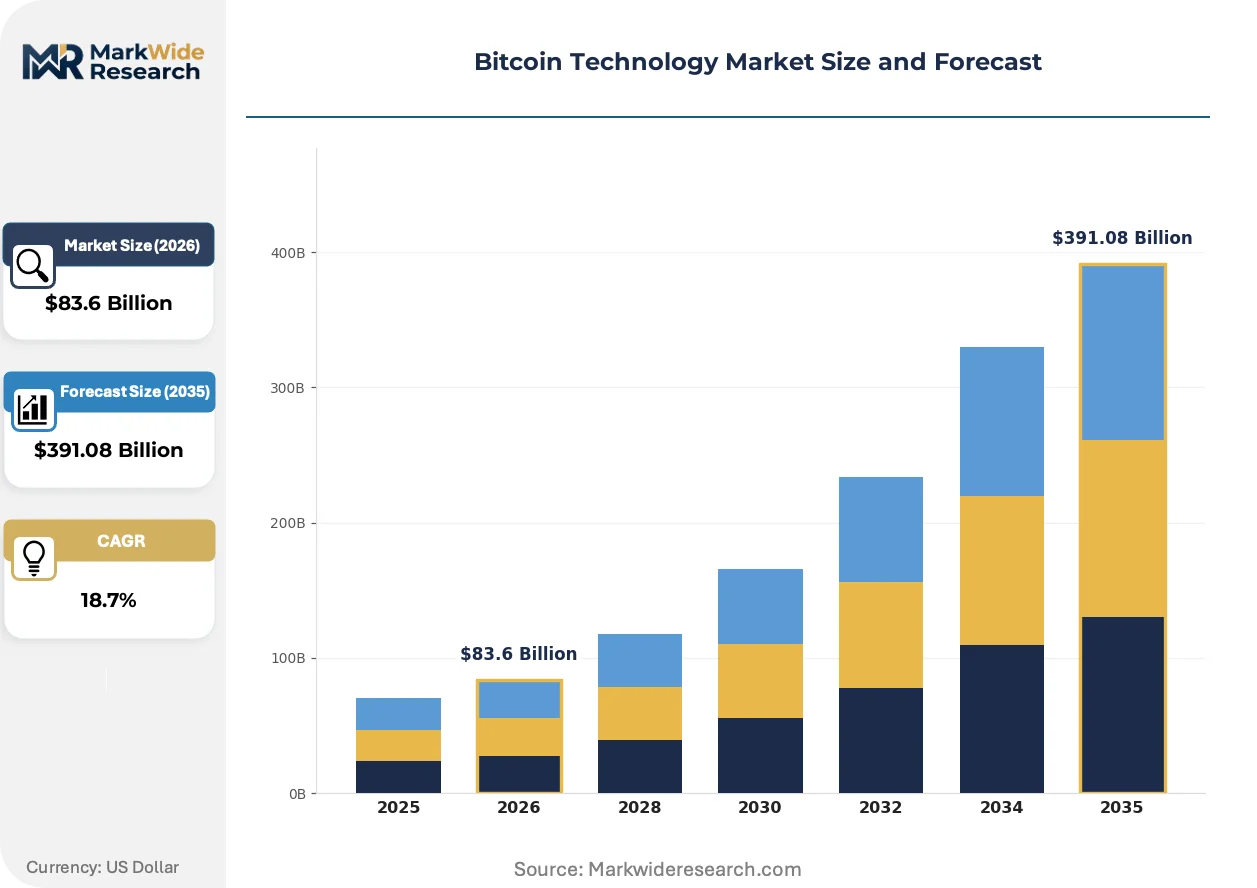
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $391.08 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Blockchain, Smart Contracts, Mining Hardware, Wallets Application: Payment Processing, Asset Management, Trading Platforms, Remittances End User: Financial Institutions, Retail Investors, Merchants, Enterprises Deployment: Cloud, On-Premise, Hybrid, Third-Party Services |
| Companies Covered | Blockstream Corporation, Bitmain Technologies, Canaan Inc., Ebang International Holdings, Lightning Labs, Coinbase Global, Bitstamp, Blockchain Luxembourg SA, BitPay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bitcoin Technology Market Emerging Trajectories
Proof-of-stake migration pressure from adjacent blockchain networks is forcing Bitcoin infrastructure providers to demonstrate energy efficiency and institutional compatibility through hardware and protocol innovation.
Application-specific integrated circuit (ASIC) efficiency gains are expanding into sub-20 joule per terahash performance tiers. Industrial miners in Iceland and Norway are adopting immersion cooling systems to capture waste heat for district heating networks. This thermal recapture model is expanding into Nordic municipal infrastructure planning as a secondary revenue stream.
The SEC's expanded broker-dealer registration requirements for custody services are compressing operational timelines for US-based exchanges. FinCEN's Bank Secrecy Act enforcement has tightened know-your-customer obligations on non-custodial wallet providers above transaction thresholds. European operators are responding by segregating US-facing and EU-facing legal entities to isolate regulatory exposure.
Enterprise treasury allocation to digital assets is rotating procurement authority from chief financial officers to dedicated digital asset committees with mandate-specific risk frameworks. Family offices and endowments are displacing retail-driven exchange volumes through over-the-counter desk relationships with negotiated custody terms. This institutionalization is most visible in Swiss and Liechtenstein private banking channels where fiduciary duty standards require segregated cold-storage architectures.
Bitcoin Technology Market Segmentation
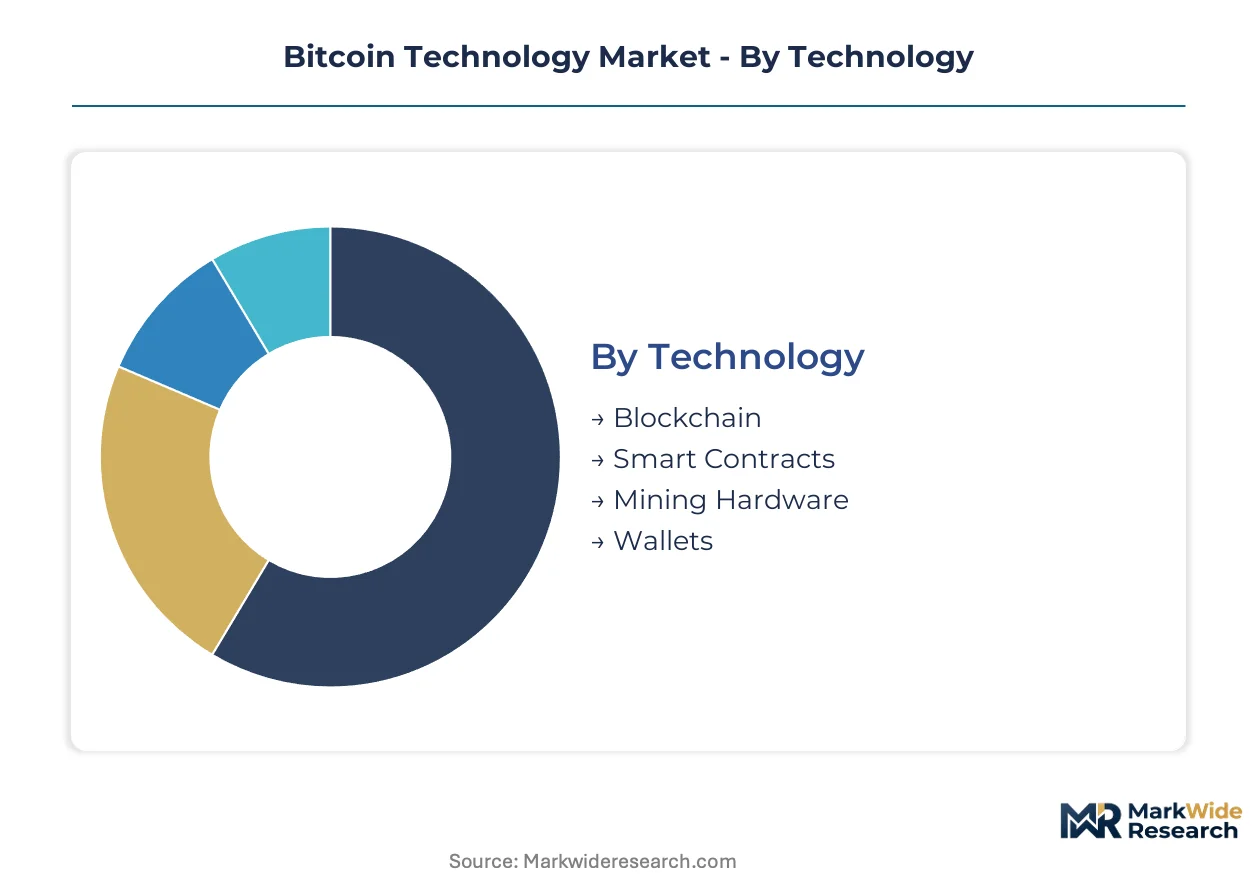
Bitcoin technology segmentation reveals distinct margin profiles across infrastructure layers, with hardware-intensive segments commanding premium pricing while software layers compete on transaction throughput and custody guarantees. Each dimension carries specific upgrade cycles that reshape vendor positioning and procurement authority.
Technology:
Hardware replacement cycles drive vendor lock-in dynamics, with ASIC refresh intervals compressing as efficiency gains accelerate.
- Blockchain:Distributed ledger infrastructure forms the settlement backbone, combining SHA-256 hashing with ten-minute block propagation. Financial institutions in Singapore prioritize enterprise-grade node deployments for sovereign wealth fund mandates.
- Smart Contracts:Programmable transaction logic enables automated escrow and conditional settlement without intermediary enforcement. Demand concentrates in trading platform infrastructure seeking atomic swap capabilities.
- Mining Hardware:ASIC fabrication at sub-20 joule per terahash efficiency tiers anchors industrial-scale operations in Texas renewable energy clusters.
- Wallets:Cold-storage architectures with multi-signature schemes dominate institutional custody procurement from Swiss private banking channels.
Volume placements concentrate in Mining Hardware; the faster expansion belongs to Smart Contracts.
Application:
Cost tier differentiation separates high-frequency retail settlement from bespoke institutional over-the-counter workflows.
- Payment Processing:Layer-two protocol integration compresses finality from ten-minute confirmations to near-instant settlement. Lightning Network channels attract micropayment streaming demand from content platforms.
- Asset Management:Custody and portfolio allocation tools serve family offices and endowments through segregated cold-storage architectures with fiduciary-grade insurance backing.
- Trading Platforms:Order matching engines with deep liquidity pools compete on slippage minimization for retail and institutional order flow.
- Remittances:Cross-border value transfer leverages Bitcoin's 24/7 settlement finality against correspondent banking delays in emerging market corridors.
Asset Management captures the premium pricing tier; Payment Processing is climbing the fastest.
End User:
Customer sophistication determines compliance burden and contract structure, with institutional mandates requiring segregated legal entities.
- Financial Institutions:Banks and asset managers face SEC broker-dealer registration requirements for custody services, compressing operational timelines for US-based deployments.
- Retail Investors:Exchange-based accumulation through mobile applications competes on fee transparency and fiat on-ramp velocity.
- Merchants:Point-of-sale integration demands instant conversion rails to mitigate price volatility exposure on received payments.
- Enterprises:Treasury allocation committees displace CFO-led procurement with mandate-specific risk frameworks for digital asset holdings.
Financial Institutions dominate current procurement volume; Enterprise treasury allocation is gaining share fastest.
Deployment:
Supply concentration in Taiwan and South Korean foundries shapes geographic deployment decisions for hardware-dependent implementations.
- Cloud:Hosted node infrastructure and wallet services reduce capital expenditure for retail-facing platforms. European operators segregate US-facing and EU-facing entities to isolate SEC exposure.
- On-Premise:Self-custody hardware and private node networks serve institutions requiring air-gapped security architectures.
- Hybrid:Split custody models combine hot-wallet liquidity with cold-storage reserves balance accessibility against theft risk.
- Third-Party Services:Specialized custody providers offer insurance-backed holding solutions compliant with FinCEN Bank Secrecy Act obligations.
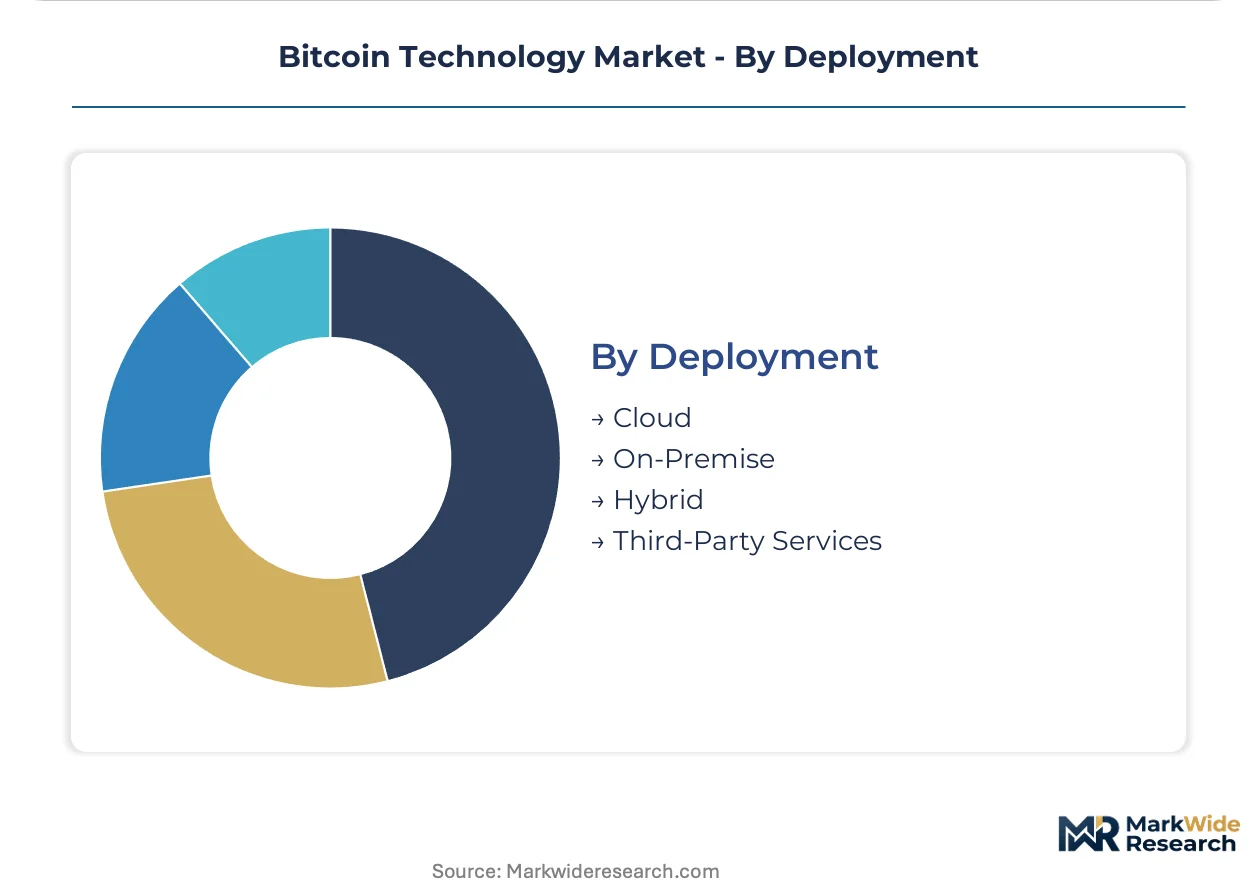
Cloud deployments lead in transaction volume; Hybrid architectures show the steepest expansion trajectory among institutional adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas wind and solar capacity anchors North American mining deployment through sub-grid power purchase agreements. Singaporean banking infrastructure drives institutional custody buildout for sovereign wealth mandates. Nordic hydroelectric reservoirs sustain European thermal recapture operations.
United States
Texas renewable energy clusters attract industrial-scale ASIC deployment through below-average electricity tariffs. The SEC enforces broker-dealer registration mandates for custody services, compressing operational timelines for domestic exchanges. Wyoming and Florida municipal frameworks host specialized banking charters for digital asset firms.
Singapore
Sovereign wealth fund mandates drive demand for insurance-backed cold-storage architectures. The Monetary Authority of Singapore licenses payment institutions under unified digital asset frameworks. Marina Bay financial district concentrates custody infrastructure buildout for regional pension allocations.
Germany
Industrial energy arbitrage opportunities attract mining hardware deployment to Brandenburg lignite transition zones. BaFin licensing requirements impose capital reserve standards on crypto custody providers. Frankfurt banking corridors integrate over-the-counter desk operations with legacy correspondent networks.
Canada
Hydroelectric surplus in Quebec and British Columbia sustains carbon-neutral mining claims for institutional investors. The Canadian Securities Administrators coordinate registration requirements across provincial jurisdictions. Calgary energy sector spinoffs repurpose natural gas flare capture for mobile mining container deployment.
Switzerland
Private banking fiduciary standards mandate segregated cold-storage architectures for family office allocations. FINMA licensing frameworks distinguish between payment tokens, asset tokens, and utility tokens for compliance classification. Zug Crypto Valley concentrates protocol development talent and venture formation activity.
Bitcoin Technology Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized layer-two infrastructure and institutional custody verticals. The vendor base stratifies across silicon fabrication specialists, protocol developers, and regulated financial service providers. Three archetypes dominate: ASIC manufacturers with captive foundry relationships, software-native protocol shops, and compliance-heavy banking infrastructure builders. Capacity expansion and geographic entity segregation represent the dominant competitive moves as operators isolate regulatory exposure across jurisdictions.
Among ASIC fabrication specialists, Bitmain Technologies and Canaan Inc. represent the hardware-centric tier with concentrated manufacturing relationships. Lightning Labs occupies a position within the protocol development archetype, anchoring enterprise settlement infrastructure buildout. Coinbase Global exemplifies the regulated financial services tier, situating its competitive position within compliance-heavy custody and exchange operations.
| Leading Market Players |
|---|
| Blockstream Corporation |
| Bitmain Technologies |
| Canaan Inc. |
| Ebang International Holdings |
| Lightning Labs |
| Coinbase Global |
| Bitstamp |
| Blockchain Luxembourg SA |
| BitPay |
| Others |
Supply Flow & Price Mechanics
Institutional procurement mandates for segregated cold-storage architectures with fiduciary-grade insurance backing are compressing vendor margins and forcing ASIC manufacturers to absorb certification costs or cede share to compliant banking infrastructure builders.
Pricing Analysis
Warranty bundling and after-sales service inclusion separate premium ASIC tiers from stripped-down economy offerings in mining hardware procurement. Three-tier pricing structure across premium, standard, and economy levels tracks efficiency performance, with sub-20 joule per terahash units commanding substantial premiums. Pricing pressure stems from TSMC and Samsung foundry capacity constraints that elevate silicon input costs. Retail-facing exchanges exhibit highest price sensitivity due to fee compression from mobile-first competitors, while sovereign wealth funds demonstrate lowest sensitivity given mandate-driven procurement authority.
Supply Chain Analysis
Semiconductor engineering talent scarcity in Taiwan and South Korea constrains ASIC design throughput and extends product roadmaps for fabrication-dependent vendors. Advanced chip production centers on Taiwan and South Korea, with secondary packaging and testing operations in Malaysia and Vietnam. Raw material dependencies span high-purity silicon wafers, rare earth elements for magnetic components, and specialized cooling fluids for immersion systems. Single-source vulnerability at the 3nm and 5nm process nodes creates supply chain risk. Distribution runs through direct OEM relationships for industrial miners and specialized resellers for retail hardware channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vertically integrated players with captive foundry access, as SEC registration mandates squeeze retail platform margins and force sub-scale operators toward exit or acquisition.
For Market Incumbents: Hedge against foundry concentration risk by diversifying silicon sourcing across Samsung and secondary fabrication partners in Japan. Secure power purchase agreements below grid averages in Texas renewable energy clusters to defend margin position against energy input volatility. Invest in compliance infrastructure to capture institutional custody mandates from Singaporean banking channels.
For New Entrants and Emerging Players: Begin with Lightning Network enterprise settlement infrastructure, where protocol-level expertise scarcity creates white-space opportunity before incumbent retooling completes. Target India's regulatory clarity gap for compliant infrastructure buildout ahead of formal framework emergence. Pursue channel partnerships with content platforms seeking micropayment streaming capabilities as the primary go-to-market angle.
For Investors and Strategic Acquirers: The window for entry favors specialized custody providers with FINMA or MAS licensing already secured, as regulatory moats deepen faster than organic certification timelines permit. Long-term viability hinges on positioning for institutional treasury allocation rotation from retail-driven exchange volumes. Monitor hash rate financialization instrument adoption by commodity trading desks as the inflection signal for infrastructure maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| ASIC Efficiency Roadmap Advancement | Sub-20 joule per terahash performance tiers anchor competitive positioning in Texas renewable clusters. |
| Regulatory Entity Segregation | EU-facing and US-facing legal entity separation isolates SEC broker-dealer registration exposure. |
| Lightning Network Protocol Development | Off-chain payment channel maturation compresses settlement latency for enterprise treasury use cases. |
| Thermal Recapture Infrastructure Partnership | Waste heat capture for Nordic district heating networks creates secondary revenue streams in Iceland and Norway. |
| Institutional Custody Certification Investment | FINMA and MAS licensing frameworks enable fiduciary-grade cold-storage procurement from Swiss and Singaporean banking channels. |
Methodological Framework
SEC filings, EIA power market data, and MAS regulatory guidance documents formed the secondary backbone for market sizing and policy trajectory assessment. Primary interviews with ASIC procurement directors at industrial mining operations, protocol engineers at layer-two infrastructure shops, compliance officers at Singaporean banking channels, and custody architects at Swiss private banks validated demand assumptions and pricing dynamics. Bottom-up unit economics modeling triangulated against top-down addressable market calculations across hardware, software, and services revenue pools.
Historical trendline analysis of ASIC deployment cycles, energy arbitrage spreads, and institutional adoption curves informed the projection framework across the analysis window. Segmentation dimensions modeled include technology layer, application use case, end-user sophistication tier, and deployment architecture. CAGRs derived from fitted growth curves adjusted for regulatory inflection points and foundry capacity expansion schedules. Hash rate difficulty adjustments and block reward halving schedules served as Bitcoin-specific forecast inputs.
Underlying measurement precision varies by segment; mining hardware shipments carry tighter precision than protocol development revenue given disclosed foundry relationships. Forecasts reflect assumptions around MiCA implementation timelines, SEC enforcement continuity, and renewable energy cluster development pace. Material deviation in hashrate migration patterns, foundry geopolitical access, or institutional custody mandate acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Global Blockchain in Telecom Market
Blockchain Technology
Bitcoin Project Incubator Service Market
Blockchain Technology
Automotive Blockchain Market
Blockchain Technology
Blockchain Technology in Healthcare Market
Blockchain Technology
Decentralized Identity Market
Blockchain Technology
Tokenization Market
Blockchain Technology
Blockchain Technology in Energy Market
Blockchain Technology
Blockchain in Energy Utilities Market
Blockchain Technology
Global Blockchain Government Market
Blockchain Technology
Blockchain in Mining Market
Blockchain Technology
Blockchain Identity Management Market
Blockchain Technology
Global Blockchain in Agriculture and Food Supply Chain Market
Blockchain Technology
Web 3.0 Blockchain Market
Blockchain Technology
Managed Blockchain Services Market
Blockchain Technology
Blockchain-As-A-Service (Baas) Market
Blockchain Technology
Web 3.0 Market