
 Blockchain Device Market | 2026-2036
Blockchain Device Market Size, Share, and Industry Trends Forecast 2026-2036
Blockchain Device Market Outlook
Chinese semiconductor foundries is pivoting toward secure element production for hardware wallets. Ledger leverages proprietary chip architecture to sustain its position in cold storage. General Bytes competes across ATM hardware while Tangem differentiates through card-based form factors.
A blockchain device is a dedicated hardware or software system incorporating secure cryptographic processors, tamper-resistant enclosures, or trusted execution environments to generate, store, and manage private keys for distributed ledger transactions. These devices execute elliptic curve cryptography to sign transactions without exposing key material to host systems. Hardware wallets occupy the highest-margin tier due to physical security premiums. Enterprise deployments within the end-user dimension are expanding fastest as treasury departments seek self-custody infrastructure. Payment applications dominate current use-case volume while supply chain tracking represents an emerging structural growth vector.
The EU's MiCA framework, SEC custody rules, and Singapore's Payment Services Act collectively reshape product standards and market access for wallet manufacturers. Compliance with these regimes demands hardware-backed key generation and audit trails that favor established producers over software-only entrants. Stakeholders must monitor regulatory divergence between jurisdictions to determine localization strategies for device certification.
Market Dynamics
Regulatory fragmentation across custody jurisdictions is fragmenting certification pathways and forcing manufacturers to maintain parallel hardware variants for different compliance regimes.
Growth Catalysts
- MiCA framework in Europe:The EU's Markets in Crypto-Assets regulation mandates hardware-backed key generation for wallet providers, creating a compliance-driven replacement cycle across the continent.
- Enterprise treasury departments:Corporate finance teams are deploying self-custody infrastructure to reduce counterparty exposure, expanding the addressable base beyond retail consumers.
- Singapore's manufacturing cluster:Concentrated fintech innovation and semiconductor packaging capabilities in Singapore are shortening production lead times for secure element fabrication.
Market Restraints
- Secure element supply concentration:Chinese and Taiwanese foundries control the majority of tamper-resistant chip production, creating single-source vulnerability for hardware wallet manufacturers.
- SEC custody rule friction:The US Securities and Exchange Commission's qualified custodian requirements impose capital reserves and audit burdens that exclude smaller wallet providers from institutional channels.
- Software wallet substitution:Mobile-based key management solutions with biometric authentication are capturing price-sensitive retail segments that hardware wallets cannot reach.
Strategic Opportunities
- Supply chain tracking applications:Integration of blockchain devices with IoT sensors for provenance verification is opening industrial verticals beyond financial services.
- India's digital rupee infrastructure:The Reserve Bank of India's central bank digital currency pilots are creating demand for certified hardware wallets among early adopters and merchants.
- Convergence with biometric authentication:Pairing secure elements with fingerprint and facial recognition modules is enabling passwordless transaction signing for mainstream users.
Industry Challenges
- Cryptographic engineering talent scarcity:The specialized skill set combining secure hardware design with elliptic curve implementation is concentrated among a small pool of practitioners.
- Multi-jurisdiction certification timelines:Obtaining Common Criteria EAL5+ recognition alongside national financial regulator approvals stretches product launch schedules by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blockchain Device Market |
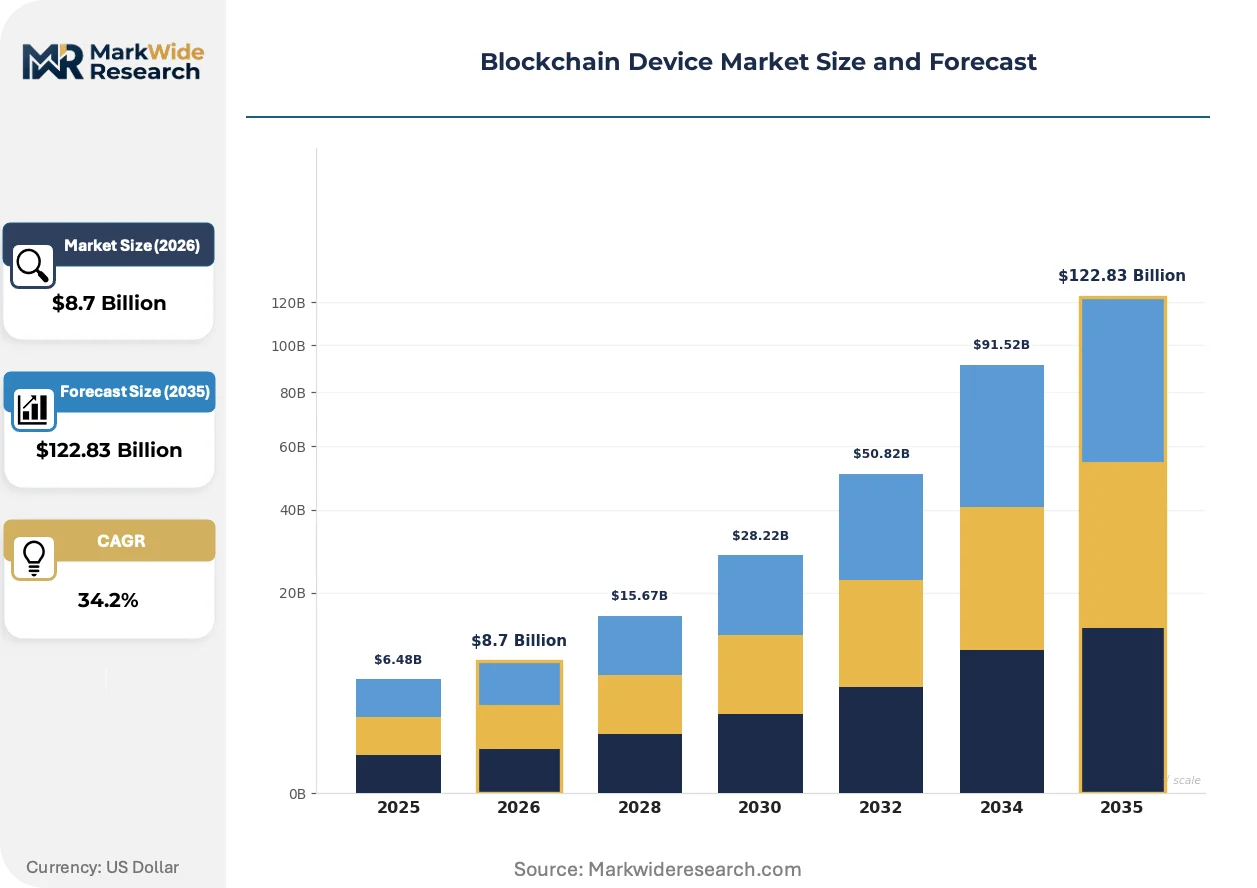
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $122.83 Billion |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Hardware Wallet, Software Wallet, Mobile Wallet, Desktop Wallet Use Case: Payment, Identity Verification, Smart Contracts, Supply Chain Tracking End User: Individuals, Enterprises, Government, Financial Institutions Technology: Cryptographic Algorithms, Consensus Mechanisms, Distributed Ledger, Privacy Protocols |
| Companies Covered | Ledger, General Bytes, Bitaccess, Coinsource, Lamassu Industries, HTC, Avado, Satoshilabs, Tangem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blockchain Device Market Strategic Shifts
Device form factors and security architectures are diverging as manufacturers respond to divergent regulatory requirements and end-use contexts across custody, payments, and industrial verification.
Card-based secure elements with NFC interfaces are overtaking USB-connected hardware wallets in retail deployment scenarios. European payment processors are embedding these modules into corporate expense cards to enable blockchain settlement. This convergence is compressing the distinction between traditional payment instruments and cryptographic key storage.
REACH substance restrictions and EU Green Deal circularity mandates are forcing redesigns of device enclosures and battery systems. Manufacturers must now document material provenance and end-of-life recyclability for hardware wallets sold in Europe. The compliance burden falls most heavily on mid-tier producers lacking in-house environmental testing laboratories.
Direct-to-enterprise sales channels are displacing retail distribution for high-value custody solutions. Institutional buyers in Switzerland and Singapore are negotiating master service agreements that bundle hardware provisioning with key ceremony services. This shift is visible most acutely among family offices and asset managers seeking bespoke security architectures.
Blockchain Device Market Segmentation
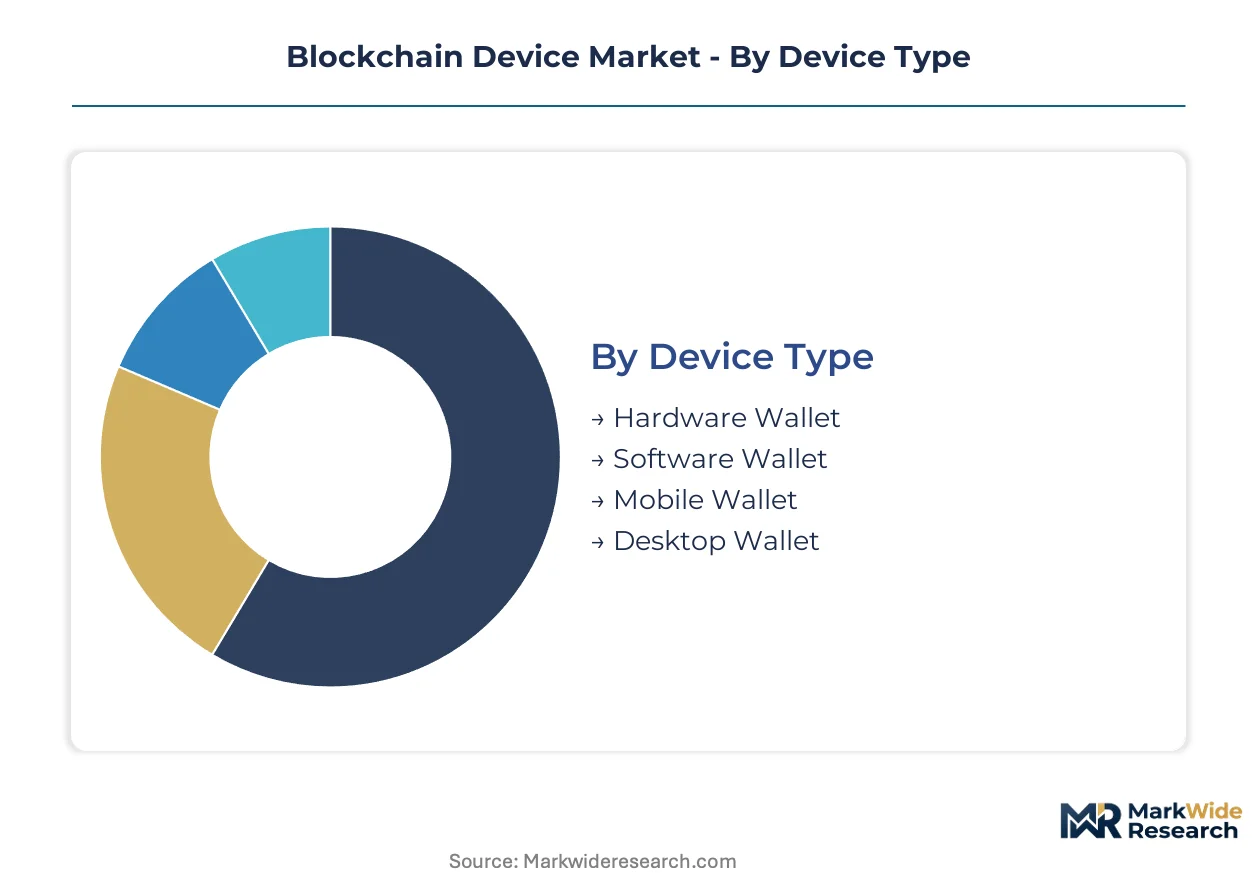
Segmentation in the blockchain device market reveals how security architecture, custody requirements, and transaction volume distribute across distinct hardware and software configurations. Each dimension exposes different margin structures, certification burdens, and supply chain dependencies that shape competitive positioning.
Device Type:
Secure element fabrication concentrates among Chinese and Taiwanese foundries, creating tiered availability that stratifies device categories by security certification and unit economics.
- Hardware Wallet:Dedicated physical devices incorporating tamper-resistant enclosures and secure cryptographic processors to isolate private key material from network-connected systems. Enterprise treasury departments in Switzerland and Singapore are driving demand for Common Criteria EAL5+ certified units despite 18-24 month approval timelines.
- Software Wallet:Applications executing key management on general-purpose computing platforms without dedicated secure hardware. Mobile-based solutions with biometric authentication are capturing price-sensitive retail segments that hardware wallets cannot economically reach.
- Mobile Wallet:Smartphone-integrated applications leveraging device secure enclaves and NFC interfaces for transaction signing. India's central bank digital currency pilots are accelerating merchant adoption for rupee-denominated settlements.
- Desktop Wallet:Personal computer-based key management software typically deployed by advanced users requiring full node verification. European MiCA compliance mandates are forcing migration toward hardware-backed alternatives for institutional custody.
Hardware wallets absorb the bulk of installed capacity; mobile wallets are expanding most quickly.
Use Case:
Application-specific security requirements create divergent cost tiers, with high-assurance custody commanding premium pricing against high-volume transactional deployments.
- Payment:Transaction execution and settlement infrastructure for digital asset transfers, stablecoin remittances, and merchant acceptance. Singapore's Payment Services Act licensing framework is concentrating licensed payment hardware production within its manufacturing cluster.
- Identity Verification:Decentralized credential issuance and authentication using cryptographic key pairs bound to biometric or government-issued identifiers. European digital identity wallet mandates under eIDAS 2.0 are creating demand for certified secure elements.
- Smart Contracts:Automated agreement execution requiring persistent key availability for transaction signing and oracle validation. Enterprise deployments favor hardware security modules over consumer wallet form factors.
- Supply Chain Tracking:Provenance verification through IoT sensor integration and immutable record anchoring. Industrial verticals beyond financial services are emerging as a structural growth vector for ruggedized device deployments.
Payment applications command the largest transaction volume; supply chain tracking is gaining share fastest.
End User:
Customer type determines procurement channel, with direct enterprise sales displacing retail distribution for high-value custody solutions requiring bespoke security architectures.
- Individuals:Retail consumers managing personal digital asset portfolios through consumer-grade hardware or software wallets. Card-based secure elements with NFC interfaces are overtaking USB-connected devices in retail deployment scenarios.
- Enterprises:Corporate entities deploying self-custody infrastructure to reduce counterparty exposure in treasury operations. Family offices and asset managers in Switzerland are negotiating master service agreements bundling hardware with key ceremony services.
- Government:State entities issuing central bank digital currencies, digital identity credentials, or procurement verification systems. India's Reserve Bank is piloting certified hardware wallets for digital rupee distribution.
- Financial Institutions:Banks, exchanges, and custodians meeting qualified custodian requirements under SEC and MiCA frameworks. Capital reserve and audit burdens are excluding smaller wallet providers from institutional channels.
Financial institutions absorb the bulk of premium-tier revenue; enterprises are climbing the fastest.
Technology:
Core technical foundations concentrate specialized engineering talent among limited practitioner pools, extending development timelines for novel cryptographic implementations.
- Cryptographic Algorithms:Elliptic curve and post-quantum implementations for key generation, signing, and verification operations. Ledger's proprietary chip architecture sustains differentiation in cold storage through custom secure element design.
- Consensus Mechanisms:Protocol-layer validation methods including proof-of-work, proof-of-stake, and Byzantine fault tolerance variants. Hardware requirements vary dramatically by network energy and computational demands.
- Distributed Ledger:Underlying blockchain infrastructure for transaction recording and state synchronization. Device compatibility spans public permissionless networks and private enterprise deployments.
- Privacy Protocols:Zero-knowledge proofs, ring signatures, and confidential transaction methods concealing transaction graph analysis. Regulatory scrutiny from FATF travel rule implementation is constraining anonymity-focused hardware.
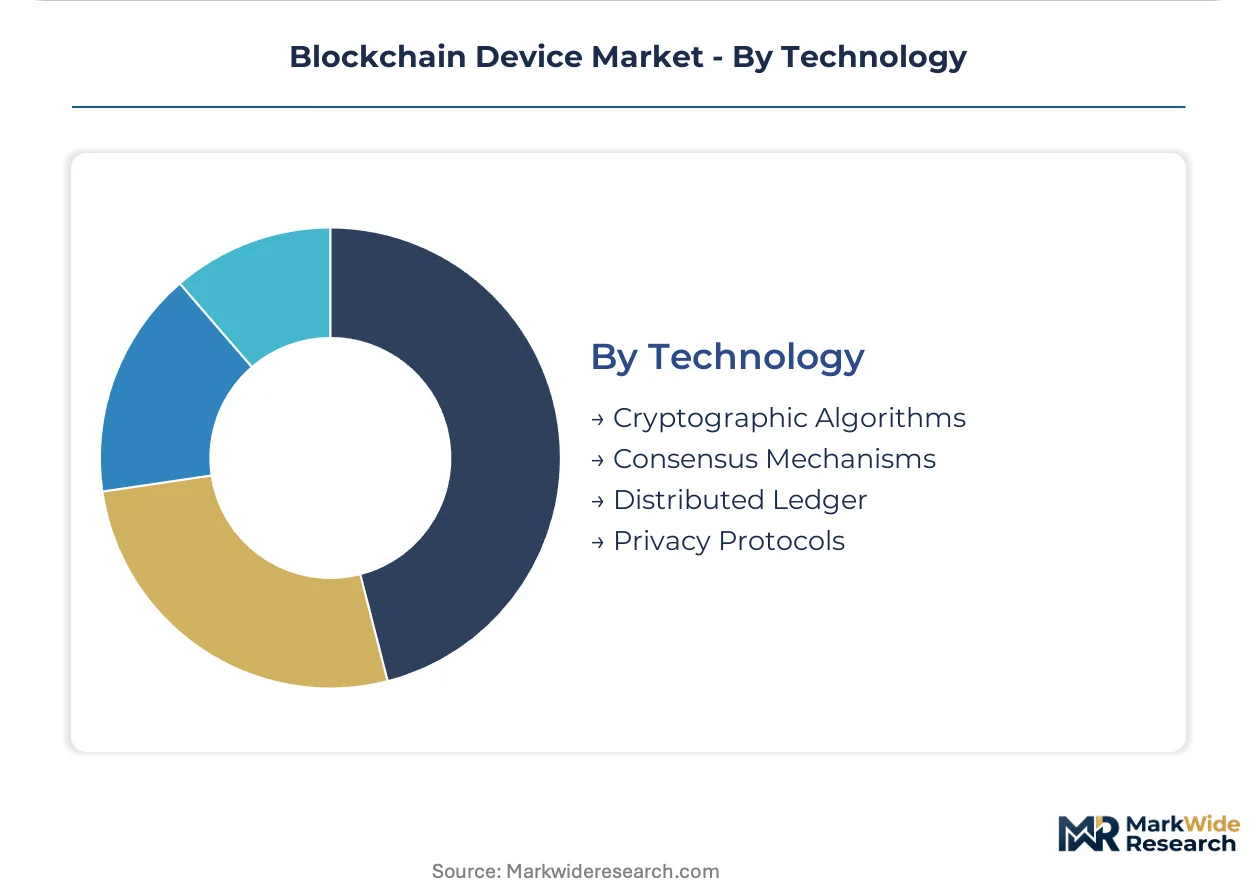
Cryptographic algorithms anchor the bulk of security certification; privacy protocols are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Secure element fabrication concentrates in Chinese and Taiwanese foundries, while Singapore's semiconductor packaging capabilities shorten production lead times for hardware wallet manufacturers. Demand clusters in Switzerland and Singapore reflect institutional treasury requirements for certified custody infrastructure.
United States
Enterprise treasury departments at technology firms and family offices drive hardware wallet procurement for self-custody infrastructure. The SEC's qualified custodian rules impose capital reserve and audit burdens that exclude smaller providers from institutional channels. Austin and Miami host concentrated fintech innovation clusters where custody solution providers negotiate direct enterprise sales.
Singapore
The Payment Services Act licensing framework concentrates licensed payment hardware production within the city-state's manufacturing cluster. The Monetary Authority of Singapore maintains strict operational standards for digital payment token service providers. Semiconductor packaging capabilities in the Jurong Innovation District enable shortened lead times for secure element integration.
Germany
MiCA framework implementation mandates hardware-backed key generation for wallet providers serving European institutional clients. The Federal Financial Supervisory Authority enforces compliance timelines that accelerate replacement cycles for non-certified devices. Berlin and Frankfurt house dedicated engineering teams addressing Common Criteria EAL5+ certification requirements.
Switzerland
Asset managers and family offices in Zurich and Geneva negotiate master service agreements bundling hardware provisioning with key ceremony services. The Swiss Financial Market Supervisory Authority applies banking standards to crypto custody arrangements. Zug's Crypto Valley hosts concentrated blockchain security architecture development for institutional clients.
India
The Reserve Bank of India's central bank digital currency pilots generate certified hardware wallet demand among early adopters and merchants. The central bank mandates specific security standards for digital rupee storage devices. Bangalore and Hyderabad semiconductor design houses are developing indigenous secure element capabilities for domestic wallet production.
Blockchain Device Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue card-based form factors and biometric integration. The vendor base stratifies between secure element designers, hardware wallet assemblers, and ATM hardware specialists. Three archetypes dominate: proprietary chip architects, manufacturing-scale fabricators, and form-factor innovators. Competitive moves center on certification acceleration and direct enterprise channel development.
Within the proprietary architecture tier, Ledger anchors hardware security module development through custom secure element design. General Bytes represents the manufacturing-scale fabricator archetype competing across ATM hardware deployment. Tangem exemplifies form-factor innovation through card-based secure elements with NFC interfaces.
| Leading Market Players |
|---|
| Ledger |
| General Bytes |
| Bitaccess |
| Coinsource |
| Lamassu Industries |
| HTC |
| Avado |
| Satoshilabs |
| Tangem |
| Others |
Value Chain & Pricing Dynamics
Enterprise procurement of Common Criteria EAL5+ certified hardware wallets is forcing manufacturers to absorb 18-24 month certification timelines into upfront pricing, compressing margins on standard-tier devices while premium-tier units capture service-bundling premiums.
Pricing Analysis
Warranty and key-ceremony service bundling separates premium custody offerings from unbundled retail hardware. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales support depth. Cost compression in economy-tier hardware wallets is intensifying because mobile wallet substitution erodes price-sensitive retail demand. Financial institutions exhibit least price sensitivity due to qualified custodian compliance mandates; individual consumers show highest elasticity, migrating toward software alternatives.
Supply Chain Analysis
Dual-sourcing requirements from enterprise buyers are forcing hardware wallet manufacturers to qualify secondary secure element suppliers beyond dominant Chinese and Taiwanese foundries. Supply rests on tamper-resistant chip fabrication, specialized semiconductor packaging, and NFC module integration. Single-source vulnerability in secure element production concentrates risk among limited foundry capacity. Distribution runs through direct enterprise sales channels for institutional custody solutions, while retail flows concentrate through e-commerce and consumer electronics retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as manufacturers pursue captive secure element design capabilities to escape foundry dependency and capture certification-margin premiums.
For Market Incumbents: Anchor market position through proprietary chip architecture investments that create switching costs against commodity secure element suppliers. Accelerate Common Criteria certification pipelines to exploit MiCA-mandated replacement cycles before software wallet biometric solutions erode retail share. Defend against card-based NFC entrants by embedding key-ceremony services into master service agreements with Swiss and Singaporean asset managers. For New Entrants and Emerging Players: Biometric-secure element convergence offers a technology-first wedge into mainstream consumer segments where passwordless transaction signing reduces friction against hardware wallet complexity. Target India's digital rupee pilot infrastructure as the most penetrable government vertical, where indigenous secure element development creates partnership opportunities with Bangalore semiconductor design houses. Pursue direct merchant acquisition through NFC-enabled point-of-sale integration rather than competing for institutional custody contracts. For Investors and Strategic Acquirers: The window for entry favors proprietary chip architects with in-house secure element design capabilities over assembly-dependent hardware wallet producers. Long-term viability hinges on regulatory certification moats that compound across successive compliance regimes. Watch for divergence between SEC qualified custodian rule implementation and MiCA framework harmonization as the inflection indicator for geographic portfolio allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Secure Element Development | Custom chip architecture eliminates foundry dependency and sustains margin premiums against commodity competitors. |
| Common Criteria EAL5+ Certification Acceleration | Expedited approval timelines capture MiCA-driven replacement demand across European institutional clients. |
| Biometric Authentication Integration | Fingerprint and facial recognition modules enable passwordless signing for mainstream consumer adoption. |
| Direct Enterprise Channel Expansion | Master service agreements with Swiss family offices bundle hardware provisioning with key ceremony services. |
| Supply Chain Dual-Sourcing Qualification | Secondary secure element suppliers mitigate concentration risk in Chinese and Taiwanese foundry capacity. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this blockchain device market assessment. Primary interviews with secure element procurement leads at hardware wallet manufacturers, certification auditors at Common Criteria evaluation facilities, and treasury technology officers at asset managers validated demand-side assumptions. SEC disclosure documents, EU MiCA implementation guidance, and Singapore Payment Services Act licensing records supplemented shipment and revenue triangulation across bottom-up and top-down approaches.
Data-stream reconciliation integrated secure element fabrication capacity, certification pipeline durations, and enterprise procurement cycle timing across the projection horizon. Segmentation dimensions modeled include device type, use case, end user, and technology architecture alongside regional regulatory cluster differentiation. CAGRs derived from unit shipment trajectories and average selling price evolution, with specific inputs from hardware wallet replacement cycle analysis and mobile wallet penetration rates by geography.
Several conditions sit outside the modeled scope, including post-quantum cryptographic algorithm standardization timelines and central bank digital currency pilot expansion beyond current Reserve Bank of India parameters. Forecasts reflect assumptions regarding regulatory harmonization between SEC and MiCA custody requirements. Deviation in secure element foundry capacity allocation or cryptographic engineering talent availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Global Blockchain in Energy Market
Blockchain Technology
Blockchain in Manufacturing Market
Blockchain Technology
Blockchain Technology Market
Blockchain Technology
Global Blockchain Market
Blockchain Technology
Blockchain Game Market
Blockchain Technology
Enterprise-Grade DLT Market
Blockchain Technology
Blockchain in Energy Utilities Market
Blockchain Technology
Global Blockchain in Telecom Market
Blockchain Technology
Blockchain Retail Market
Blockchain Technology
Global Blockchain in Healthcare Market
Blockchain Technology
Blockchain in Aviation Market
Blockchain Technology
Decentralized Identity Market
Blockchain Technology
Web 3.0 Blockchain Market
Blockchain Technology
Global Blockchain IoT Market
Blockchain Technology
Global Blockchain in Agriculture and Food Supply Chain Market
Blockchain Technology
Blockchain in Sports Market