
 Global Blockchain in Logistics Market | 2026-2036
Global Blockchain in Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blockchain in Logistics Market Foresight
A shortage of distributed systems engineers fluent in supply chain operations is redrawing competitive boundaries across the logistics technology landscape. IBM Corporation leverages its enterprise blockchain infrastructure to anchor large-scale maritime digitization programs. Maersk sustains platform leadership through integrated container tracking networks spanning multiple port authorities. DHL competes by specializing in last-mile verification protocols that reduce documentation disputes.
Blockchain in logistics refers to cryptographically linked distributed ledgers that record shipment events, custody transfers, and contractual states across immutable time-stamped blocks, typically operating through consensus mechanisms with latency thresholds under ten seconds for high-frequency freight applications. The primary commercial purpose is eliminating information asymmetry between shippers, carriers, and customs authorities while automating compliance through programmable execution. Supply chain transparency solutions dominate current deployment value as enterprises prioritize provenance verification for regulated goods. Permissioned blockchain architectures are capturing the fastest expansion trajectory among technology categories due to their controlled participant governance and data privacy alignment with enterprise risk frameworks. Smart contracts within payment settlement are emerging as a concentrated margin pool where automation directly reduces working capital requirements.
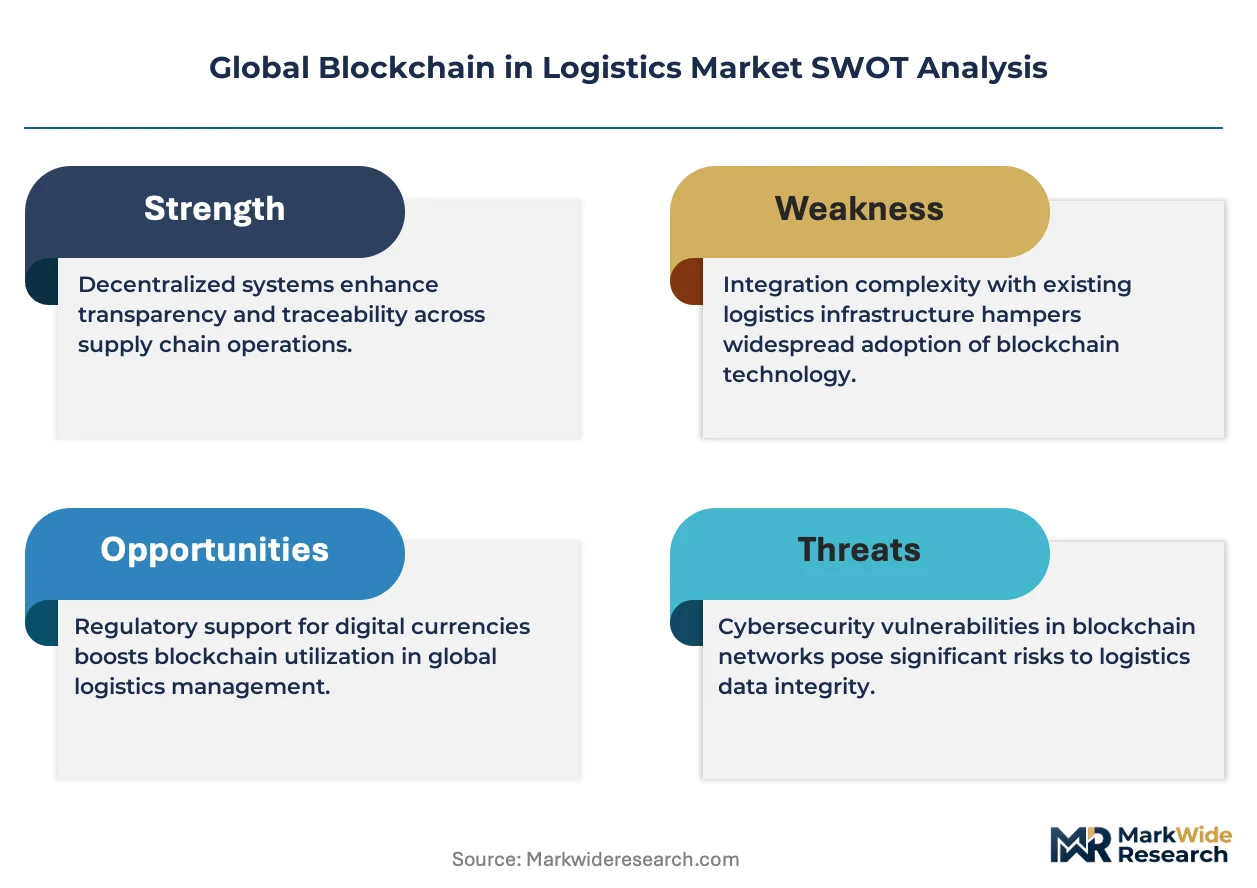
The EU Green Deal's digital product passport mandates, enforced through ECHA compliance frameworks, are compelling logistics providers to adopt traceable ledger architectures for cross-border goods. FDA pharmaceutical track-and-trace requirements under the Drug Supply Chain Security Act are similarly reshaping cold chain blockchain specifications in the United States. ISO blockchain standards for distributed ledger interoperability are establishing baseline technical expectations that determine platform eligibility for multinational tenders. Stakeholders must weigh governance model selection against the regulatory fragmentation emerging from divergent national data localization laws before committing to infrastructure architecture.
Market Dynamics
The EU Green Deal's digital product passport mandates are forcing logistics providers to rebuild data architectures around immutable provenance records, compressing procurement timelines for compliant ledger systems.
Growth Catalysts
- Pharmaceutical serialization:FDA track-and-trace requirements under DSCA are compelling cold chain operators to adopt temperature-logging blockchains for vaccine distribution integrity.
- EU ECHA compliance:Digital product passport frameworks are mandating traceable ledger architectures for cross-border goods circulation through Hamburg and Rotterdam port corridors.
- Consensus mechanism advances:Sub-ten-second latency thresholds in permissioned networks are unlocking high-frequency freight applications previously blocked by throughput constraints.
Market Restraints
- Distributed systems talent scarcity:Engineers fluent in both cryptographic protocols and supply chain operations command premium compensation, inflating implementation costs for mid-tier logistics providers.
- Data localization fragmentation:Divergent national data sovereignty laws in China, Russia, and India are fragmenting cross-border ledger interoperability and forcing redundant infrastructure deployment.
- Legacy ERP integration complexity:Proprietary warehouse management systems from the 2000s lack API architectures compatible with smart contract triggers, extending pilot-to-production timelines.
Strategic Opportunities
- Smart contract settlement automation:Programmable payment execution is compressing working capital cycles for freight forwarders operating across ASEAN manufacturing corridors.
- India's pharmaceutical export expansion:CDSCO compliance alignment with EU MDR standards is creating demand for temperature-verified blockchain documentation in Mumbai-Pune logistics clusters.
- IoT sensor convergence:Integration of GPS-enabled container seals with distributed ledgers is enabling real-time custody verification for high-value electronics shipments.
Industry Challenges
- ISO standardization delays:Pending distributed ledger interoperability specifications are freezing multinational tender eligibility decisions until baseline technical expectations crystallize.
- Permissioned governance design:Consortium formation disputes among competing carriers are stalling network effect accumulation in major trade lanes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blockchain in Logistics Market |
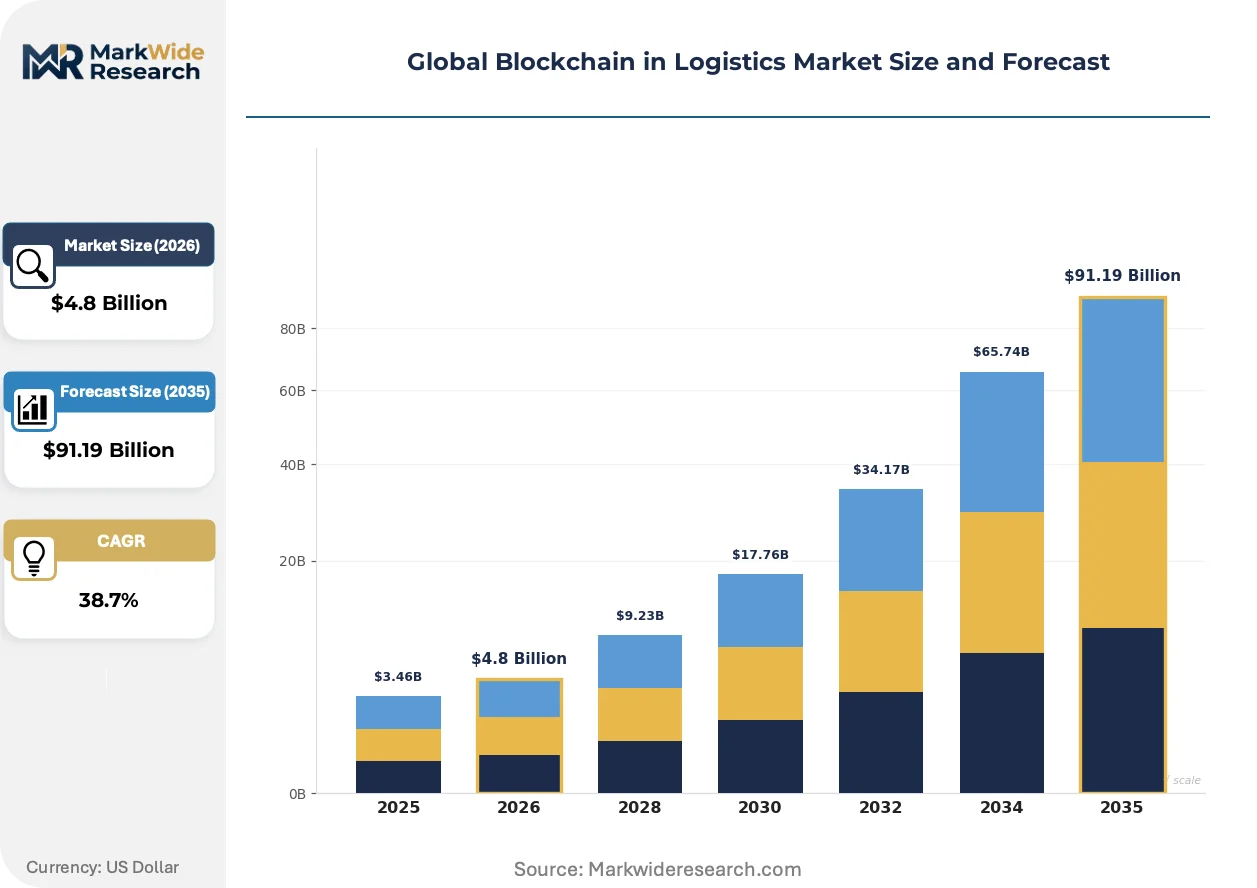
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $91.19 Billion |
| CAGR (2026 – 2036) | 38.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Smart Contracts, Supply Chain Transparency, Freight Tracking, Payment Settlement, Identity Management Application: Shipment Verification, Inventory Management, Customs Clearance, Carrier Management, Route Optimization Technology: Public Blockchain, Permissioned Blockchain, Hybrid Blockchain, Distributed Ledger Technology, Sidechains End User: Third-Party Logistics Providers, Freight Forwarders, Warehousing Operators, Shipping Companies, Courier Services |
| Companies Covered | IBM Corporation, Maersk, Walmart, DHL, DP World, Chronicled, Morpheus.Network, Tradeline, Cubix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blockchain in Logistics Market Shifts & Advancements
Logistics technology procurement is pivoting from pilot programs to production-scale deployments as regulatory deadlines harden, with buyers prioritizing proven interoperability over experimental features.
Permissioned blockchain architectures are fragmenting competitive positioning among enterprise software vendors. Pharmaceutical manufacturers and automotive OEMs are migrating procurement specifications toward controlled-governance ledgers that align with internal risk frameworks. This fragmentation is compressing margins for general-purpose platforms unable to demonstrate sector-specific compliance modules.
ECHA enforcement of EU Green Deal digital product passport requirements is mandating immutable material provenance records for batteries, textiles, and electronics entering European customs zones. German industrial clusters around Hamburg are piloting blockchain-enabled customs corridors to preempt compliance bottlenecks. Third-country exporters are reconfiguring supplier data collection to satisfy ECHA audit trails.
Shippers are unbundling documentation verification from freight contracts, purchasing ledger-based custody confirmation as a standalone service. This disintermediation is compressing margins for traditional forwarders in Asia-Europe trade lanes. Japanese automotive parts suppliers are pioneering the model, demanding timestamped handoff records independent of carrier selection.
Global Blockchain in Logistics Market Segmentation
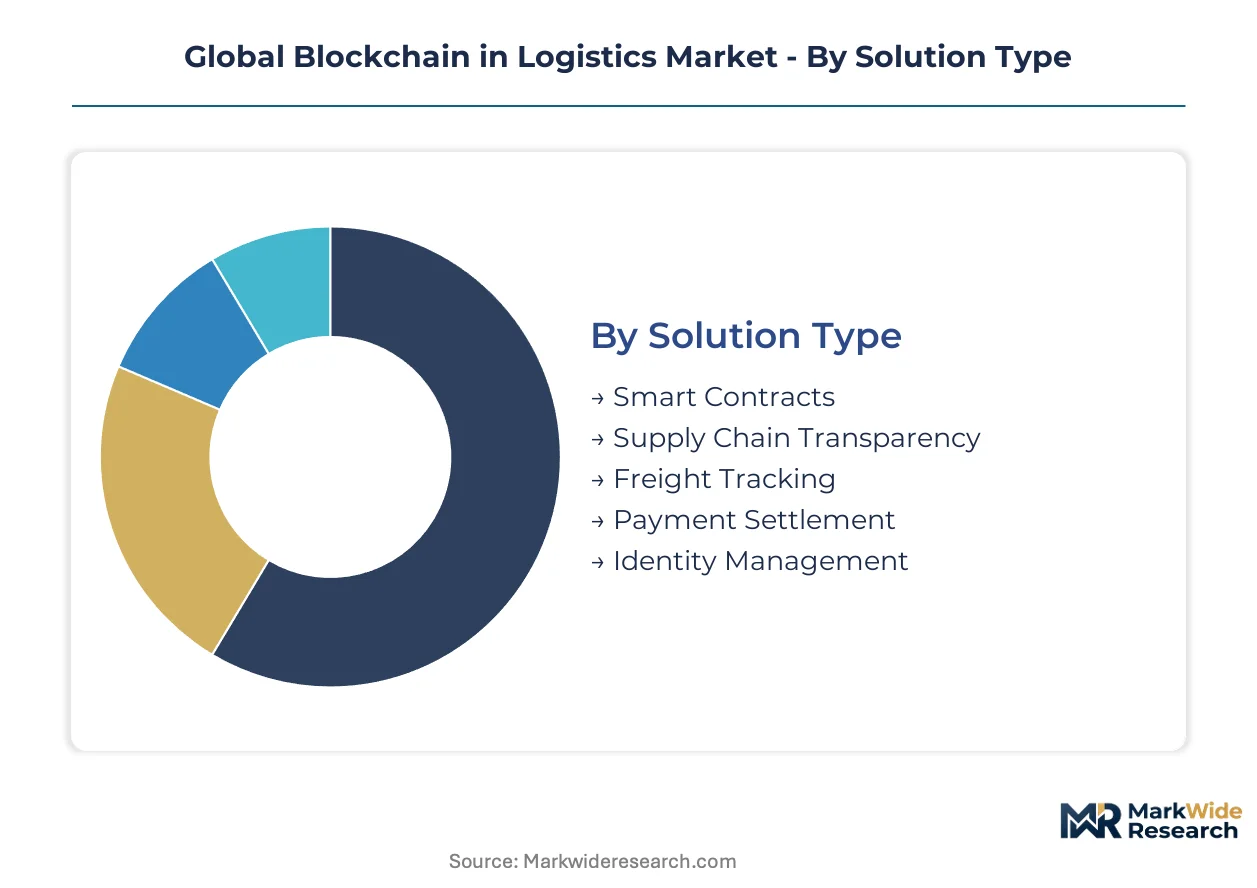
Segmentation in blockchain logistics reveals where procurement budgets concentrate and which use cases justify infrastructure investment. Solution type and technology architecture decisions determine implementation cost structures and regulatory compliance pathways. Application focus shapes interoperability requirements and determines whether platforms serve single enterprises or multi-party networks.
Solution Type:
Margin pools concentrate in automation layers that compress working capital cycles and reduce documentation disputes.
- Smart Contracts:Self-executing protocols encode freight payment terms, customs duties, and insurance triggers into immutable code blocks. Demand clusters among freight forwarders operating across ASEAN manufacturing corridors where programmable settlement directly reduces days sales outstanding. Automotive OEMs in Japan are pioneering standalone procurement of ledger-based custody confirmation independent of carrier selection.
- Supply Chain Transparency:Distributed ledgers record material provenance, custody transfers, and compliance states across timestamped blocks. Pharmaceutical manufacturers under FDA DSCA requirements and EU ECHA digital product passport mandates drive concentrated procurement for temperature-verified documentation. German industrial clusters around Hamburg are piloting blockchain-enabled customs corridors to preempt compliance bottlenecks.
- Freight Tracking:GPS-enabled container seals integrate with distributed ledgers for real-time custody verification of high-value electronics shipments.
- Payment Settlement:Cross-border freight payment automation through programmable execution reduces correspondent banking delays and foreign exchange exposure.
- Identity Management:Cryptographic credential verification for customs authorities, carriers, and shippers streamlines KYC processes across multi-party logistics networks.
The dominant share belongs to Supply Chain Transparency, while Smart Contracts is closing the gap fastest.
Application:
Deployment velocity varies sharply by where regulatory deadlines force procurement decisions versus where efficiency gains alone justify investment.
- Shipment Verification:Immutable timestamp records of cargo condition, seal integrity, and handoff events eliminate documentation disputes between shippers and carriers. Third-party logistics providers in India are expanding temperature-verified blockchain documentation for pharmaceutical exports aligned with EU MDR standards. Mumbai-Pune logistics clusters show concentrated demand for CDSCO-compliant ledger systems.
- Customs Clearance:Pre-validated trade documentation on distributed ledgers accelerates port processing and reduces inspection holds. Rotterdam and Hamburg port authorities are piloting blockchain-enabled customs corridors under EU Green Deal digital product passport frameworks. Third-country exporters are reconfiguring supplier data collection to satisfy ECHA audit trails.
- Inventory Management:Real-time ledger synchronization across warehouse management systems and carrier networks reduces stockout events and safety stock requirements.
- Carrier Management:Smart contract-encoded performance metrics and penalty clauses automate service level agreement enforcement across multi-carrier networks.
- Route Optimization:Consensus-validated traffic, weather, and port congestion data feeds enable dynamic rerouting with immutable audit trails for insurance claims.
Customs Clearance commands the largest implementation budgets, with Shipment Verification expanding most quickly as pharmaceutical serialization mandates harden.
Technology:
Architecture selection determines governance control, data privacy alignment, and eligibility for multinational enterprise tenders.
- Permissioned Blockchain:Controlled participant governance with configurable consensus rules and sub-ten-second latency thresholds. Pharmaceutical manufacturers and automotive OEMs are migrating procurement specifications toward these architectures that align with internal risk frameworks. ISO blockchain standards for distributed ledger interoperability are establishing baseline technical expectations that determine platform eligibility.
- Public Blockchain:Open participation models with cryptographic pseudonymity and token-based incentive mechanisms. Maritime digitization programs requiring neutral infrastructure across competing carriers favor this architecture for its resistance to single-party control.
- Hybrid Blockchain:Selective data exposure combines permissioned transaction processing with public anchoring for notarization purposes.
- Distributed Ledger Technology:Broader architectural category encompassing non-blockchain directed acyclic graph structures optimized for high-throughput freight applications.
- Sidechains:Auxiliary chains processing high-frequency transactions with periodic settlement to main chain for cost efficiency.
Permissioned Blockchain holds the dominant position, while Hybrid Blockchain is gaining share fastest as enterprises seek regulatory compliance without sacrificing interoperability.
End User:
Technology procurement authority varies by where margin pressure is most acute and where regulatory liability concentrates.
- Third-Party Logistics Providers:Full-service operators integrating warehousing, transportation, and customs brokerage face margin compression from documentation disintermediation. These providers are unbundling ledger-based custody confirmation as standalone services to defend revenue streams in Asia-Europe trade lanes.
- Freight Forwarders:Intermediaries specializing in cross-border shipment coordination are adopting smart contract settlement automation to compress working capital cycles. ASEAN corridor operators show concentrated demand for programmable payment execution.
- Warehousing Operators:Facility-based providers integrate IoT sensor networks with distributed ledgers for real-time inventory state verification.
- Shipping Companies:Ocean carriers deploy container-level tracking with immutable custody records to reduce claims disputes and insurance premiums.
- Courier Services:Last-mile specialists implement identity management protocols to reduce failed delivery rates and signature verification costs.
Third-Party Logistics Providers account for the dominant procurement volume, with Freight Forwarders climbing fastest as settlement automation delivers measurable working capital improvements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA enforcement of EU Green Deal digital product passport mandates anchors European procurement gravity, while FDA track-and-trace requirements and CDSCO compliance alignment drive parallel adoption clusters across North America and South Asia.
United States
FDA pharmaceutical serialization requirements under DSCA compel cold chain operators to deploy temperature-logging blockchains for vaccine distribution integrity. Federal mandates for immutable custody records reshape procurement specifications for third-party logistics providers serving pharmaceutical manufacturers. The Boston-Cambridge biotech corridor concentrates pilot deployments linking warehouse management systems to distributed ledgers.
Germany
ECHA compliance frameworks for digital product passports mandate traceable ledger architectures for batteries and electronics entering European customs zones. The EU Green Deal's material provenance requirements compress implementation timelines for Hamburg port authority digitization programs. Industrial clusters around the Port of Hamburg pilot blockchain-enabled customs corridors to preempt inspection bottlenecks.
India
CDSCO regulatory alignment with EU MDR standards creates demand for temperature-verified blockchain documentation among pharmaceutical exporters. The country's pharmaceutical export expansion drives procurement of ledger-based custody confirmation systems. Mumbai-Pune logistics clusters show concentrated adoption of serialization-compliant distributed ledger infrastructure.
China
National data sovereignty laws fragment cross-border ledger interoperability while domestic port digitization programs accelerate permissioned blockchain deployment. SAMR regulatory frameworks for supply chain traceability reshape enterprise procurement specifications for controlled-governance architectures. Yangtze River Delta port authorities pilot distributed ledger integration with customs processing systems.
Japan
METI industrial digitization initiatives promote blockchain adoption for automotive parts provenance tracking across multi-tier supplier networks. PMDA pharmaceutical traceability requirements converge with global serialization standards to reshape cold chain technology procurement. Kanto region automotive OEMs pioneer standalone ledger-based custody confirmation independent of carrier selection.
Global Blockchain in Logistics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with competitive boundaries redrawn by distributed systems engineering scarcity rather than capital scale alone. Enterprise technology conglomerates anchor large-scale maritime digitization programs through infrastructure partnerships with port authorities. Specialized logistics operators defend position through last-mile verification protocols and sector-specific compliance module development. Dominant competitive moves include consortium formation for permissioned network governance and smart contract settlement automation to compress working capital cycles.
Within the integrated infrastructure tier, IBM Corporation and Maersk exemplify archetypes of enterprise blockchain anchoring and platform-led maritime digitization respectively. DHL occupies a position representing specialized last-mile verification capabilities that reduce documentation disputes in high-velocity corridors. These three entities sit within distinct strategic postures: technology infrastructure provision, ocean carrier platform orchestration, and express logistics protocol specialization.
| Leading Market Players |
|---|
| IBM Corporation |
| Maersk |
| Walmart |
| DHL |
| DP World |
| Chronicled |
| Morpheus.Network |
| Tradeline |
| Cubix |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts with Hamburg and Rotterdam port authorities lock in both ledger infrastructure access and predictable implementation pricing for logistics providers navigating ECHA compliance deadlines. These arrangements insulate early movers from spot-market volatility in distributed systems engineering talent while compressing procurement timelines for compliant architectures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade permissioned deployments from mid-tier SaaS subscriptions and open-source implementations. Premium tiers command substantial markups for ISO-certified interoperability modules and sub-ten-second latency guarantees, while price erosion runs through the economy tier as commoditized tooling floods from Asia-Pacific software vendors. Freight forwarders operating across ASEAN corridors exhibit highest price sensitivity due to margin compression from documentation disintermediation, whereas pharmaceutical manufacturers under FDA DSCA mandates demonstrate lowest sensitivity given regulatory liability concentration.
Supply Chain Analysis
Germany and the United States anchor production of enterprise blockchain infrastructure, with India and Singapore emerging as specialized development hubs for smart contract protocols and IoT-ledger integration modules. Critical inputs include cryptographic hardware security modules, consensus algorithm software licenses, and GPS-enabled container seals from Taiwan and South Korea manufacturers. Supply chain risk centers on single-source vulnerability for qualified distributed systems engineers fluent in both cryptographic protocols and supply chain operations. Distribution runs through direct enterprise sales forces for permissioned platforms and cloud marketplace channels for standardized SaaS offerings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent logistics technology providers face substitution pressure from specialized blockchain-native vendors unbundling custody verification as standalone services, demanding defensive architecture investments to preserve platform stickiness.
For Market Incumbents: Compound platform defensibility through backward integration into IoT sensor manufacturing and captive development of sector-specific compliance modules for pharmaceutical and automotive verticals. Prioritize ISO interoperability certification to maintain eligibility for multinational tenders while building consortium governance expertise that stalls network formation by competing carriers.
For New Entrants and Emerging Players: CDSCO-EU MDR alignment fast-tracks create immediate white-space opportunity in Mumbai-Pune pharmaceutical logistics clusters where temperature-verified blockchain documentation demand outstrips qualified provider supply. Target mid-tier freight forwarders in ASEAN manufacturing corridors with programmable settlement automation that delivers measurable working capital compression within single fiscal periods.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists combining proprietary IoT hardware with permissioned ledger software and established port authority relationships. Monitor ECHA enforcement intensity and FDA DSCA implementation timelines as inflection indicators for enterprise procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Consortium Governance Formation | Establishes network effects that preempt competing permissioned ledgers in Hamburg-Rotterdam corridors. |
| Smart Contract Settlement Automation | Compresses days sales outstanding for freight forwarders across ASEAN manufacturing networks. |
| IoT Sensor Hardware Integration | Enables real-time custody verification that differentiates platforms in high-value electronics logistics. |
| ISO Interoperability Certification | Determines platform eligibility for multinational tenders under pending distributed ledger standards. |
| Pharmaceutical Compliance Module Development | Captures procurement budgets from manufacturers under FDA DSCA and EU ECHA serialization mandates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with logistics technology procurement officers, distributed systems engineers, port authority digitization leads, pharmaceutical supply chain directors, and freight forwarder operations managers. Secondary validation drew from ECHA regulatory filings, FDA DSCA guidance documents, ISO blockchain standardization committee outputs, and customs processing modernization disclosures from Hamburg and Rotterdam authorities. Bottom-up deployment estimates triangulated against top-down market sizing from enterprise software procurement databases.
Across the analysis window, the forecasting framework modeled solution type penetration, technology architecture adoption curves, application deployment velocity, and end-user procurement authority shifts. CAGRs derived from segment-level growth trajectories weighted by regulatory deadline proximity and working capital automation ROI evidence. Industry-specific inputs included ECHA digital product passport implementation timelines, FDA pharmaceutical serialization phase requirements, and CDSCO-EU MDR harmonization progress.
Decision-makers should treat outputs as directional under base assumptions of sustained regulatory enforcement and consensus mechanism latency improvements; material deviation in data localization policy fragmentation or distributed systems talent availability would warrant model refresh. Recalibration cycles align with material shifts in ECHA enforcement intensity and ISO standardization completion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Smart Contracts on Blockchain Market
Blockchain Technology
Global Blockchain in Agriculture and Food Supply Chain Market
Blockchain Technology
Blockchain in Pharmaceutics Market
Blockchain Technology
Global Blockchain Market
Blockchain Technology
Blockchain AI Market
Blockchain Technology
Global Blockchain Supply Chain Market
Blockchain Technology
Global Blockchain Software Market
Blockchain Technology
Managed Blockchain Services Market
Blockchain Technology
Europe Blockchain Market
Blockchain Technology
Industrial Blockchain Technology Market
Blockchain Technology
Web 3.0 Blockchain Market
Blockchain Technology
Pharmaceutical Blockchain Market
Blockchain Technology
Blockchain in Mining Market
Blockchain Technology
Blockchain Identity Management Market
Blockchain Technology
Global Blockchain in Healthcare Market
Blockchain Technology
Bitcoin Project Incubator Service Market