
 Marine Blockchain Market | 2026-2036
Marine Blockchain Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Blockchain Market Foresight
The marine blockchain sector is rebalancing between premium enterprise-grade platforms and commodity API-layer services. IBM leverages its Hyperledger expertise to anchor high-assurance supply chain networks for multinational shippers. Maersk sustains platform dominance through TradeLens infrastructure and direct carrier integration. CargoSmart competes on port-community network density across Asian transshipment gateways.
Marine blockchain denotes distributed ledger systems engineered for maritime trade documentation, vessel provenance tracking, and smart-contract automation of freight payments, typically operating on permissioned architectures with throughput exceeding 1,000 transactions per second. These systems eliminate document fraud, reduce demurrage disputes, and enable real-time cargo visibility across multimodal chains. Smart Contracts within the Application layer command the deepest margin pools due to insurance automation and charter-party execution. IoT Integration is expanding fastest as sensor-verified container conditions feed directly into immutable ledgers. Private Blockchain deployments occupy the dominant share among shipping companies prioritizing data sovereignty over open-network interoperability.
The International Maritime Organization (IMO) shapes demand through mandatory digitalization of cargo reporting under its Facilitation Convention amendments. The EU eFTI regulation forces cross-border compliance, while Singapore's Maritime and Port Authority (MPA) mandates electronic bills of lading for port clearance. Stakeholders must monitor which regulatory jurisdiction achieves interoperability standards first, as that geography will dictate platform architecture for the next decade of maritime digitization.
Market Dynamics
Container shipping lines face mounting pressure to digitize bill-of-lading workflows as port authorities in Singapore, Rotterdam, and Shanghai mandate electronic documentation for vessel clearance, compressing adoption timelines across competing maritime digitization hubs.
Growth Catalysts
- EU eFTI Regulation:Cross-border freight operators must deploy interoperable data exchange platforms by regulatory deadline, forcing immediate blockchain infrastructure investment across European container routes.
- Smart Contract Automation:Charter-party execution and marine insurance settlement now execute without manual intervention, reducing demurrage disputes and payment delays for bulk cargo carriers.
- Port Authority Mandates:Singapore's MPA electronic bill-of-lading requirement for port clearance creates compliance-driven demand spikes at transshipment gateways competing for maritime traffic.
Market Restraints
- Permissioned Architecture Costs:Enterprise-grade Hyperledger deployments require substantial infrastructure investment, pricing out smaller regional carriers and freight forwarders.
- Data Sovereignty Fragmentation:Shipping companies prioritize private blockchain networks over open interoperability, creating isolated digital islands that resist cross-platform integration.
- Legacy System Entrenchment:Paper-based customs documentation persists in developing port jurisdictions, delaying end-to-end digitization despite platform availability.
Strategic Opportunities
- IoT-Verified Cargo Conditions:Sensor data feeding directly into immutable ledgers creates new revenue streams for condition-based freight pricing and automated quality disputes.
- Asian Transshipment Gateways:Underpenetrated secondary ports in Vietnam and Indonesia offer first-mover positioning for port-community network density expansion.
- IMO Facilitation Convention:Mandatory digitalization of cargo reporting amendments create regulatory tailwinds for compliant platform providers across signatory nations.
Industry Challenges
- Maritime Blockchain Architecture Expertise:Shortage of developers skilled in permissioned ledger deployment and smart-contract security auditing slows enterprise rollout timelines.
- Multi-Stakeholder Coordination:Carriers, ports, customs authorities, and banks must synchronize platform migration, creating execution risk when any participant delays.
- Interoperability Standard Delays:Absence of unified data formats between competing platforms forces costly duplicate integration work for multi-carrier shippers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Blockchain Market |
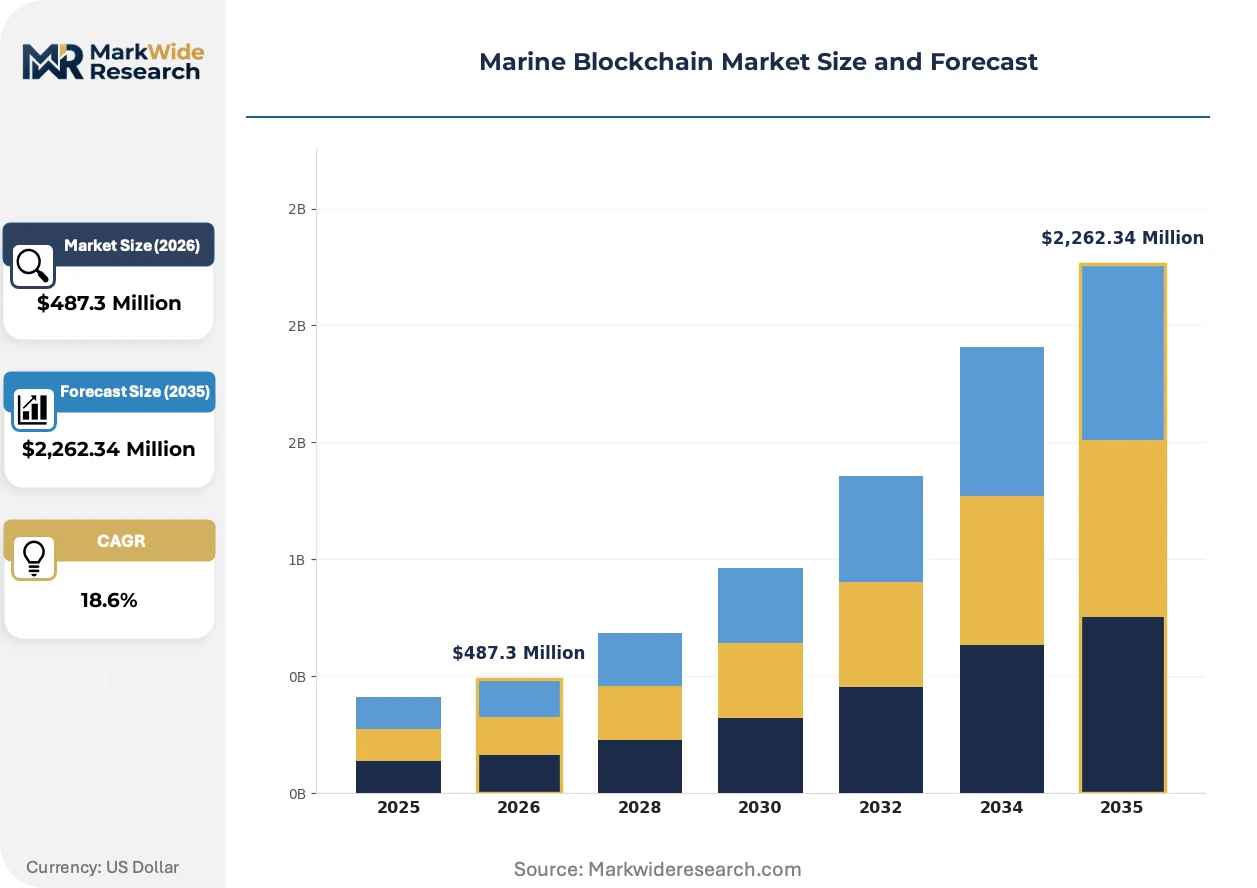
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $2,262.34 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Smart Contracts, Distributed Ledger, IoT Integration, Cloud Computing Application: Supply Chain Management, Asset Tracking, Cargo Management, Maritime Insurance End User: Shipping Companies, Port Authorities, Freight Forwarders, Logistics Providers Deployment: Public Blockchain, Private Blockchain, Hybrid Blockchain, Consortium Blockchain |
| Companies Covered | IBM, Maersk, Oracle, CargoSmart, WAVE BL, DNV, SAP, Microsoft, TradeLens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Blockchain Market Shifts & Advancements
Maritime trade documentation is fragmenting into specialized layer-two solutions as throughput demands exceed base-layer capacity, while sensor integration and regulatory mandates accelerate platform specialization.
Distributed ledger middleware is modularizing around container-level provenance tracking. Bulk grain and refrigerated cargo shippers adopt sensor-verified condition logging at the fastest clip. This architecture is modularizing freight payment workflows into discrete smart-contract components that carriers can mix across trade lanes.
EU Electronic Freight Transport Information regulation forces cross-border compliance architecture into shipping IT roadmaps. Operators must demonstrate real-time data exchange capability with customs authorities in multiple member states. Container lines serving Northern European routes face the steepest compliance investment curves.
Freight procurement is compressing vendor selection cycles as real-time cargo visibility becomes a baseline expectation rather than premium service. Shippers now demand API-accessible container location data before awarding annual contracts. This behavioral shift is most pronounced in Singapore-based commodity trading houses sourcing agricultural and mineral bulk cargoes.
Marine Blockchain Market Segmentation
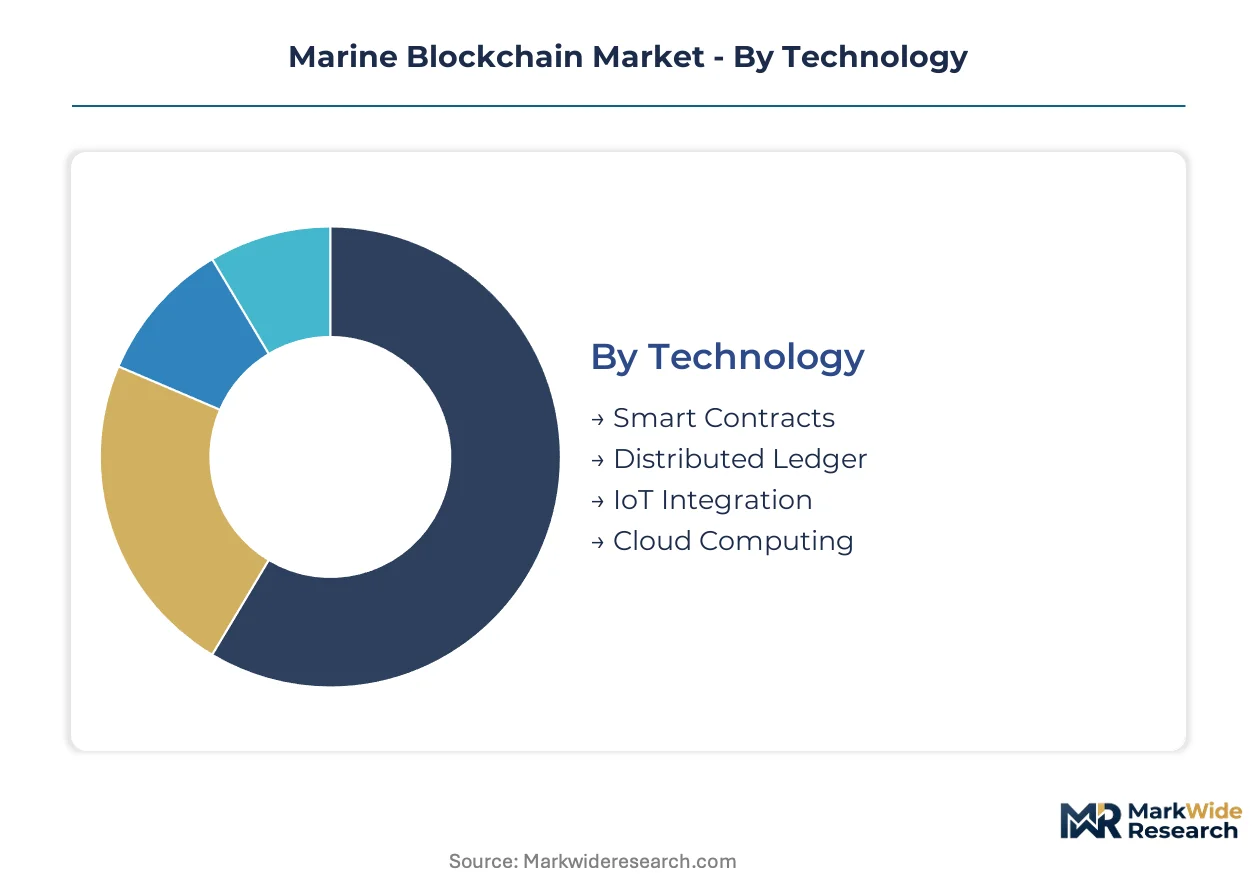
Marine blockchain segmentation reveals how technical architecture, operational use case, and stakeholder configuration determine platform economics. Deployment mode and application layer choices directly shape implementation cost, data sovereignty, and interoperability potential across maritime trade networks.
Technology:
Customization intensity varies sharply across this category, with programmable automation demanding bespoke development while infrastructure layers commoditize toward standardized APIs.
- Smart Contracts:Self-executing code automates charter-party enforcement, demurrage calculations, and marine insurance payouts without intermediary intervention. Demand concentrates among bulk commodity traders in Singapore seeking to eliminate payment delays in grain and mineral shipments.
- Distributed Ledger:Immutable transaction records anchor vessel provenance, cargo custody chains, and customs documentation across multimodal handoffs. Rotterdam-based container lines prioritize this layer for EU eFTI regulatory compliance on North European routes.
- IoT Integration:Sensor-verified container conditions feed temperature, humidity, and shock data directly into on-chain records.
- Cloud Computing:Elastic infrastructure supports permissioned node networks with variable throughput demands.
Leading the category by volume: Distributed Ledger. Growing fastest: IoT Integration.
Application:
Revenue pools align with documentation friction intensity, with insurance automation commanding premium margins while cargo visibility approaches commodity pricing.
- Maritime Insurance:Automated claims processing and parametric risk instruments eliminate manual loss adjustment for hull and cargo underwriters. London-based marine insurers drive adoption to reduce fraud in refrigerated container spoilage disputes.
- Supply Chain Management:End-to-end visibility platforms integrate carrier schedules, port availability, and customs clearance into unified workflow dashboards. Shanghai commodity traders sourcing agricultural bulk demand this capability for contract timing precision.
- Asset Tracking:Vessel and container location verification prevents phantom inventory and detention billing errors.
- Cargo Management:Digital bill-of-lading workflows replace paper documentation for port clearance acceleration.
Volume leadership sits with Supply Chain Management. Maritime Insurance claims the steepest margin expansion trajectory.
End User:
Stakeholder sophistication determines platform complexity, with integrated carriers requiring sovereign infrastructure while freight intermediaries accept multi-tenant SaaS configurations.
- Shipping Companies:Container lines and bulk operators deploy private ledgers to control data exposure while maintaining audit trails for charter-party disputes. Singapore-flagged carriers mandate electronic documentation compatibility for vendor qualification.
- Port Authorities:Harbor masters and terminal operators enforce platform standards for vessel clearance, creating gatekeeper influence over network adoption. Rotterdam's port community system integration requirements shape European deployment patterns.
- Freight Forwarders:Non-vessel-operating intermediaries aggregate cargo across multiple carriers, demanding API interoperability rather than single-platform dependency.
- Logistics Providers:Warehousing and inland transport operators extend chain-of-custody records beyond port gates.
Shipping Companies anchor category volume. Port Authorities are expanding most quickly as regulatory mandates multiply.
Deployment:
Architecture choice reflects the sovereignty-interoperability tradeoff, with closed networks maximizing control while open protocols enable cross-platform settlement.
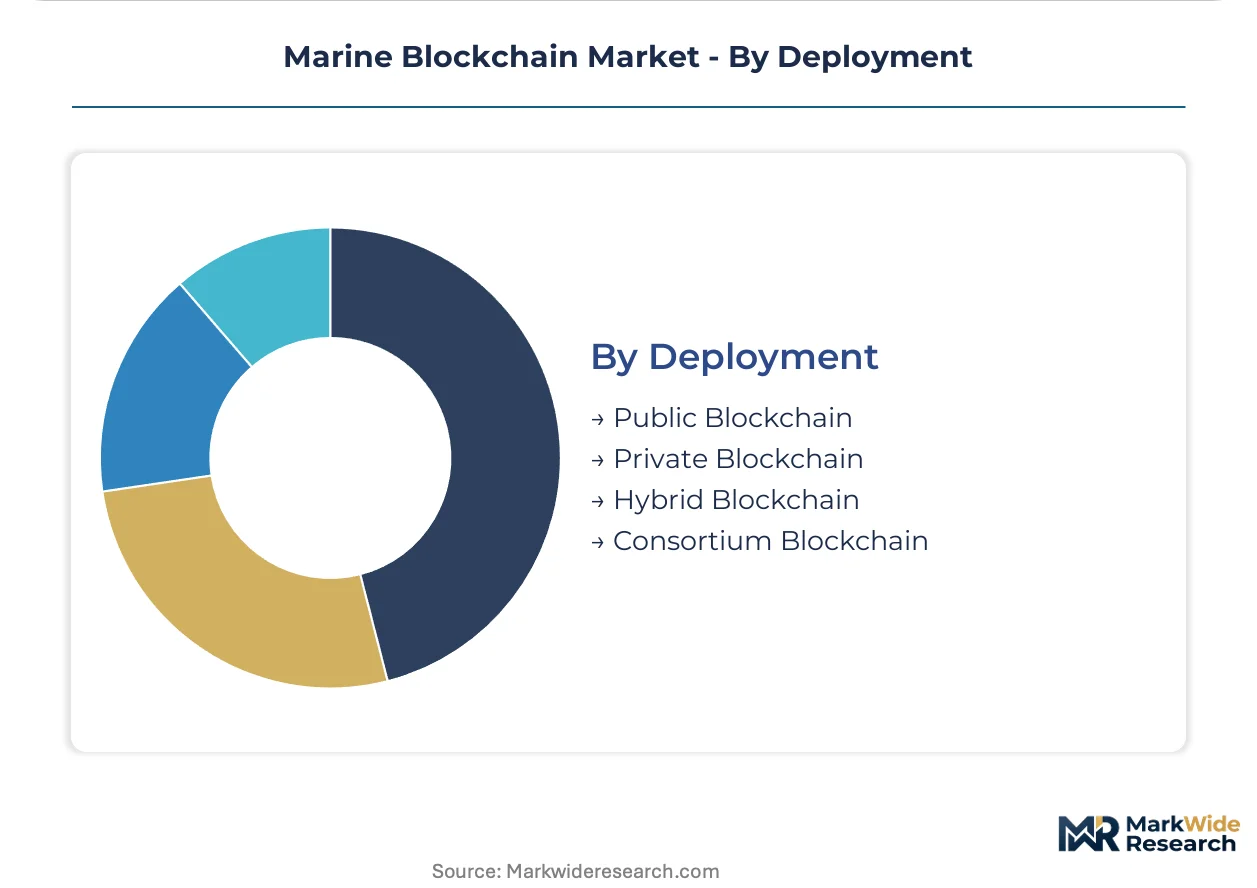
- Private Blockchain:Permissioned infrastructure restricts node participation to pre-validated shipping companies, banks, and port authorities, ensuring data confidentiality in competitive trades. Major container lines favor this model for bill-of-lading digitization to prevent commercial intelligence leakage.
- Consortium Blockchain:Multi-stakeholder governance distributes infrastructure costs across carrier alliances and port communities while maintaining controlled access. Asian transshipment hubs including Singapore and Shanghai organize these networks to align competing terminal operators.
- Public Blockchain:Open participation enables settlement finality without central coordination, though throughput limitations constrain maritime documentation volumes.
- Hybrid Blockchain:Segmented architectures isolate sensitive commercial data on private layers while anchoring verification hashes to public chains for notarization.
Private Blockchain dominates current deployment volume. Consortium Blockchain is gaining share fastest as multi-stakeholder coordination matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore anchors maritime blockchain deployment through its Maritime and Port Authority mandates for electronic documentation at the Port of Singapore, with competing hubs in Rotterdam and Shanghai driving parallel infrastructure investments across three continents.
Singapore
Container lines and commodity traders digitize bill-of-lading workflows under MPA electronic documentation requirements. The Maritime and Port Authority mandates blockchain-verified port clearance for transshipment cargo. The Port of Singapore hosts dense port-community network deployments linking terminal operators with customs authorities.
Netherlands
Rotterdam-based carriers face steep compliance investment curves under EU Electronic Freight Transport Information regulation deadlines. The EU eFTI framework forces real-time data exchange with customs authorities across member states. The Port of Rotterdam integrates distributed ledger infrastructure into its port community system for North European container routes.
China
Shanghai commodity traders demand supply chain visibility platforms for agricultural bulk cargo contract timing. The Ministry of Transport supports smart port initiatives embedding blockchain into cargo reporting systems. The Yangtze River Delta cluster concentrates platform development for multimodal cargo tracking across inland waterway connections.
United States
Los Angeles and Long Beach port complexes pilot blockchain documentation for customs clearance acceleration. The Federal Maritime Commission monitors carrier alliance platform deployments for competition compliance. Pacific Northwest technology corridors supply developer talent for permissioned ledger architecture deployment.
United Kingdom
London marine insurers drive parametric risk instrument automation through distributed ledger settlement. The Financial Conduct Authority oversees blockchain-based trade finance platform compliance. The London insurance market cluster anchors smart-contract development for hull and cargo claims processing.
Marine Blockchain Market Competitive Landscape
Capital-heavy infrastructure providers compete with asset-light software developers for maritime blockchain platform dominance. The market structures around three tiers: enterprise technology conglomerates with Hyperledger expertise, carrier-controlled consortium platforms, and specialized port-community network operators. Strategic moves concentrate on carrier alliance partnerships and regulatory compliance certification rather than standalone technology differentiation.
Within the enterprise technology tier, IBM and Oracle represent archetypal infrastructure providers leveraging existing cloud and middleware relationships with multinational shippers. Maersk occupies a distinct position through its TradeLens carrier consortium model, exemplifying vertical integration into maritime documentation workflows. CargoSmart anchors the port-specialist vector with Asian transshipment gateway density. Microsoft and SAP sit within the enterprise software extension archetype, embedding maritime modules into broader supply chain suites. WAVE BL and DNV represent compliance-focused specialists targeting electronic bill-of-lading standardization.
| Leading Market Players |
|---|
| IBM |
| Maersk |
| Oracle |
| CargoSmart |
| WAVE BL |
| DNV |
| SAP |
| Microsoft |
| TradeLens |
| Others |
Supply & Pricing Matrix
EU Electronic Freight Transport Information regulation compliance gates both qualified platform supply and premium-tier pricing access for maritime blockchain providers, forcing carriers to absorb certification costs or cede market position to pre-compliant competitors.
Pricing Analysis
Throughput-based pricing anchors enterprise marine blockchain contracts, with platform fees scaling to transaction volumes and smart-contract execution frequency. Three-tier pricing structure across premium, standard, and economy levels separates sovereign-grade private deployments from multi-tenant SaaS configurations. Pricing pressure stems from open-source Hyperledger commoditization eroding middleware margins. Regional freight forwarders exhibit highest price sensitivity, while Singapore-flagged container lines prioritize data sovereignty over cost minimization.
Supply Chain Analysis
Single-source vulnerability sits with specialized permissioned ledger developers concentrated in the United States, United Kingdom, and Singapore. Core infrastructure draws from cloud hyperscaler compute, cryptographic hardware security modules, and maritime IoT sensor networks. Supply chain risk centers on regulatory restriction as EU data localization requirements fragment cross-border platform architecture. Distribution runs through carrier alliance procurement committees and port authority technology vendor qualification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine blockchain platform provision is consolidating into a scale-driven oligopoly as EU eFTI compliance deadlines force subscale competitors into exit or acquisition.
For Market Incumbents: Anticipate carrier alliance consolidation by embedding smart-contract automation deeper into charter-party execution workflows. Defensive moves require backward integration into IoT sensor hardware and exclusive port-community network density in Rotterdam and Shanghai. The threat of open-source middleware commoditization demands proprietary data format lock-in through regulatory certification capture. For New Entrants and Emerging Players: Launch via API-layer interoperability services targeting freight forwarder aggregation demand across Vietnam and Indonesia transshipment corridors. White-space targets include condition-based freight pricing algorithms for refrigerated bulk cargo and parametric marine insurance settlement engines. The most penetrable segment sits with secondary Asian port authorities lacking in-house distributed ledger expertise. For Investors and Strategic Acquirers: First carrier alliance platform achieving IMO Facilitation Convention amendment certification is the leading indicator that regulatory capture economics will dominate the next investment cycle. Long-term viability favors vertically integrated providers controlling both infrastructure and compliance certification pathways. Acquisition target archetype: port-community network operators with dense Asian transshipment gateway relationships and pre-certified EU eFTI architecture.| Strategic Initiative | Industry Significance |
|---|---|
| Carrier Alliance Platform Integration | Maersk's TradeLens infrastructure demonstrates how direct carrier integration locks in multimodal documentation workflows. |
| Port-Community Network Expansion | CargoSmart's Asian transshipment density proves gatekeeper influence over competing terminal operator adoption decisions. |
| Smart Contract Automation Development | London marine insurers drive parametric hull and cargo claims processing without manual loss adjustment intervention. |
| Regulatory Certification Capture | IBM's Hyperledger expertise anchors high-assurance supply chain networks for EU eFTI compliance mandates. |
| IoT Sensor Hardware Integration | Sensor-verified container conditions enable automated quality disputes and condition-based freight pricing premiums. |
Research Methodology
IMO Facilitation Convention amendment filings, EU eFTI regulatory impact assessments, and Singapore MPA electronic documentation mandates formed the secondary backbone for demand-side validation. Primary interviews with container line technology procurement officers, port authority harbor masters, marine insurance underwriters, and freight forwarder operations directors combined with secondary sources. Customs documentation databases, carrier alliance platform disclosures, and maritime IoT sensor deployment records anchored supply-side calibration. Bottom-up and top-down triangulation reconciled platform deployment counts with transaction volume estimates.
Bottom-up modeling segmented deployment mode, application layer, and end-user stakeholder configuration across the projection horizon. Technology dimensions included smart-contract automation intensity, distributed ledger throughput specifications, and IoT integration depth. Application segmentation captured maritime insurance settlement, supply chain visibility, asset tracking, and cargo management workflows. End-user archetypes spanned integrated container lines, port authorities, freight forwarders, and logistics providers. CAGRs derived from platform adoption curve analysis and regulatory mandate enforcement timelines.
The model assumes a particular technology adoption path; alternative pathways for public blockchain interoperability would alter the outlook for permissioned architecture dominance. Forecasts reflect assumptions about EU regulatory enforcement consistency and IMO amendment ratification velocity across signatory nations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Blockchain Technology in Energy Market
Blockchain Technology
Smart Contracts on Blockchain Market
Blockchain Technology
Blockchain AI Market
Blockchain Technology
Blockchain in Sports Market
Blockchain Technology
Web 3.0 Market
Blockchain Technology
Blockchain in Pharmaceutics Market
Blockchain Technology
Web 3.0 Blockchain Market
Blockchain Technology
Industrial Blockchain Technology Market
Blockchain Technology
Blockchain Game Market
Blockchain Technology
Enterprise-Grade DLT Market
Blockchain Technology
Aviation Record-Keeping Blockchain Market
Blockchain Technology
Decentralized Identity Market
Blockchain Technology
Tokenization Market
Blockchain Technology
Bitcoin Project Incubator Service Market
Blockchain Technology
Global Blockchain IoT Market
Blockchain Technology
Blockchain Retail Market