
 Blockchain Retail Market | 2026-2036
Blockchain Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Blockchain Retail Market Intelligence
ISO 27001 certification is bifurcating the competitive landscape into enterprise-ready and experimental tiers. IBM leverages its Hyperledger Fabric deployments to anchor high-assurance retail networks. Walmart sustains one of the largest live food traceability implementations, controlling supplier onboarding velocity. Tech Mahindra competes through systems integration depth across APAC retail corridors.
Blockchain retail denotes distributed ledger architectures applied to commerce workflows, typically employing immutable hashing, consensus mechanisms such as Proof of Authority or Practical Byzantine Fault Tolerance, and smart contract automation to verify transactions without intermediary reconciliation. Supply chain transparency solutions lead deployment value, as retailers require end-to-end provenance from farm to shelf. Smart contracts within solution type segments capture expanding margin pools by automating settlement and reducing dispute overhead. Digital wallets are accelerating fastest among solution types, driven by tokenized loyalty and cryptocurrency payment rails.
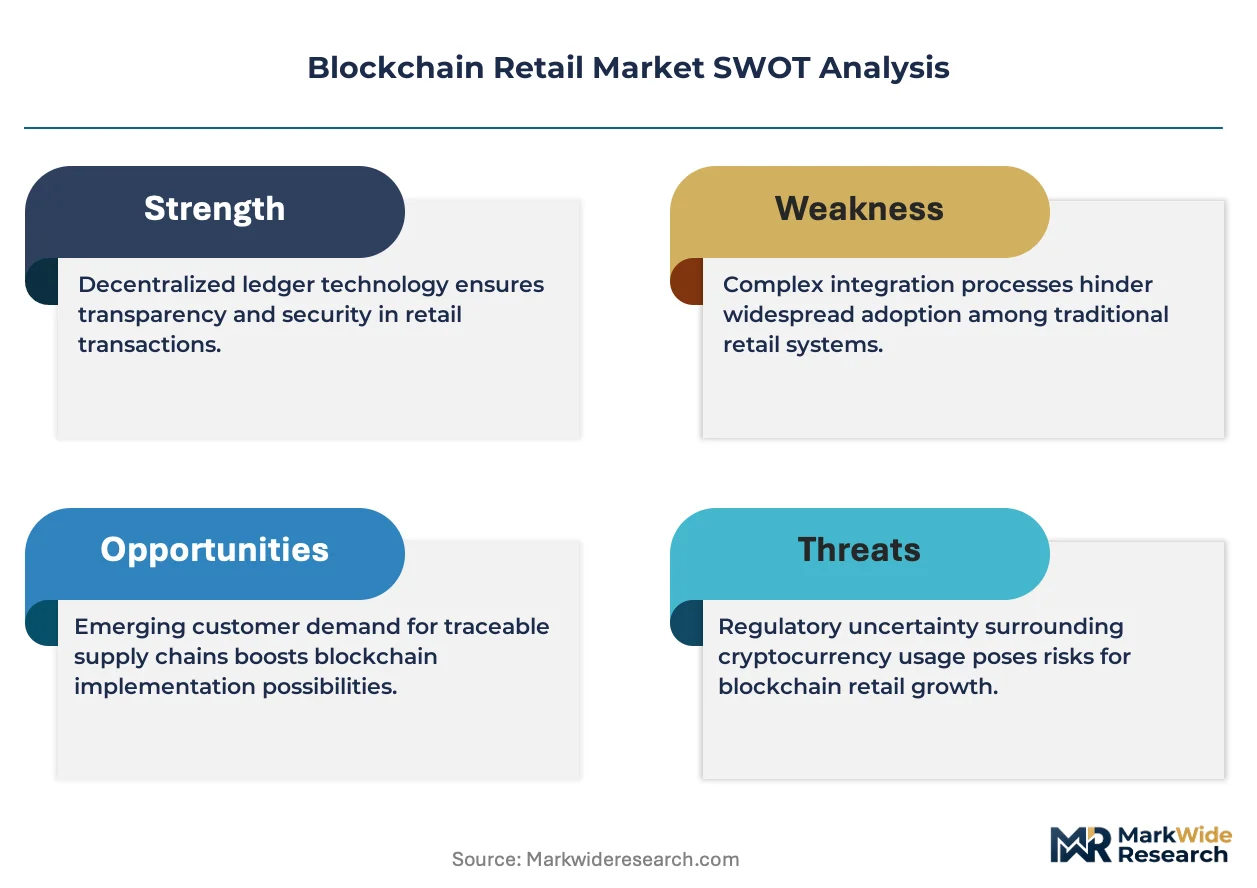
FDA traceability rules under the Food Safety Modernization Act, EU GDPR data residency requirements, and ISO 27001 information security standards collectively shape platform architecture and cross-border data flow permissions. Retailers must architect systems that satisfy FDA record-keeping mandates while enabling GDPR-compliant data minimization across consortium nodes. Stakeholders should monitor how regulatory divergence between jurisdictions affects interoperability investments and vendor selection criteria.
Market Dynamics
Enterprise retailers are consolidating blockchain infrastructure around ISO 27001-certified platforms to satisfy cross-border data governance mandates while reducing supplier reconciliation costs. This certification divide is splitting vendor capabilities into enterprise-grade and experimental tiers.
Growth Catalysts
- EU AI Act compliance requirements:Retailers deploying automated supply chain verification must demonstrate algorithmic transparency and audit trails, accelerating investment in permissioned ledger architectures that embed compliance by design.
- Food Safety Modernization Act traceability mandates:FDA rules for farm-to-fork record-keeping are forcing grocery chains to replace paper-based provenance systems with immutable digital ledgers ahead of enforcement deadlines.
- Tokenized loyalty program expansion:Digital wallet integrations are capturing margin pools by converting points liabilities into programmable assets that interoperate across partner networks.
Market Restraints
- Consortium governance fragmentation:Competing standards bodies and proprietary protocols are preventing network effects from consolidating, leaving retailers exposed to stranded infrastructure investments.
- Specialized talent scarcity:Shortages of smart contract auditors and distributed systems architects are extending deployment timelines and inflating implementation costs for mid-market chains.
- Energy consumption scrutiny:Proof-of-Work consensus mechanisms face mounting pressure from ESG disclosure requirements under CSRD, restricting deployment options for sustainability-conscious brands.
Strategic Opportunities
- India retail corridor digitization:BIS standards for supply chain traceability and DGFT export documentation requirements are creating first-mover advantages for platforms integrating with government digital infrastructure.
- Convergence of IoT sensors and edge computing:Real-time cold chain monitoring combined with local consensus validation is enabling automated quality enforcement without cloud dependency for perishable logistics.
- Second-hand luxury authentication:Resale platforms are adopting NFC-anchored digital product passports to verify provenance, opening new revenue streams in circular fashion and watch markets.
Industry Challenges
- Legacy ERP integration complexity:Retailers with SAP or Oracle backbone systems face multi-year reconfiguration projects to enable bi-directional data flows with distributed ledgers without disrupting daily operations.
- Cross-jurisdictional data residency conflicts:GDPR data minimization requirements clash with FDA record retention mandates, forcing expensive node topology designs that segment sensitive information across geographic boundaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blockchain Retail Market |
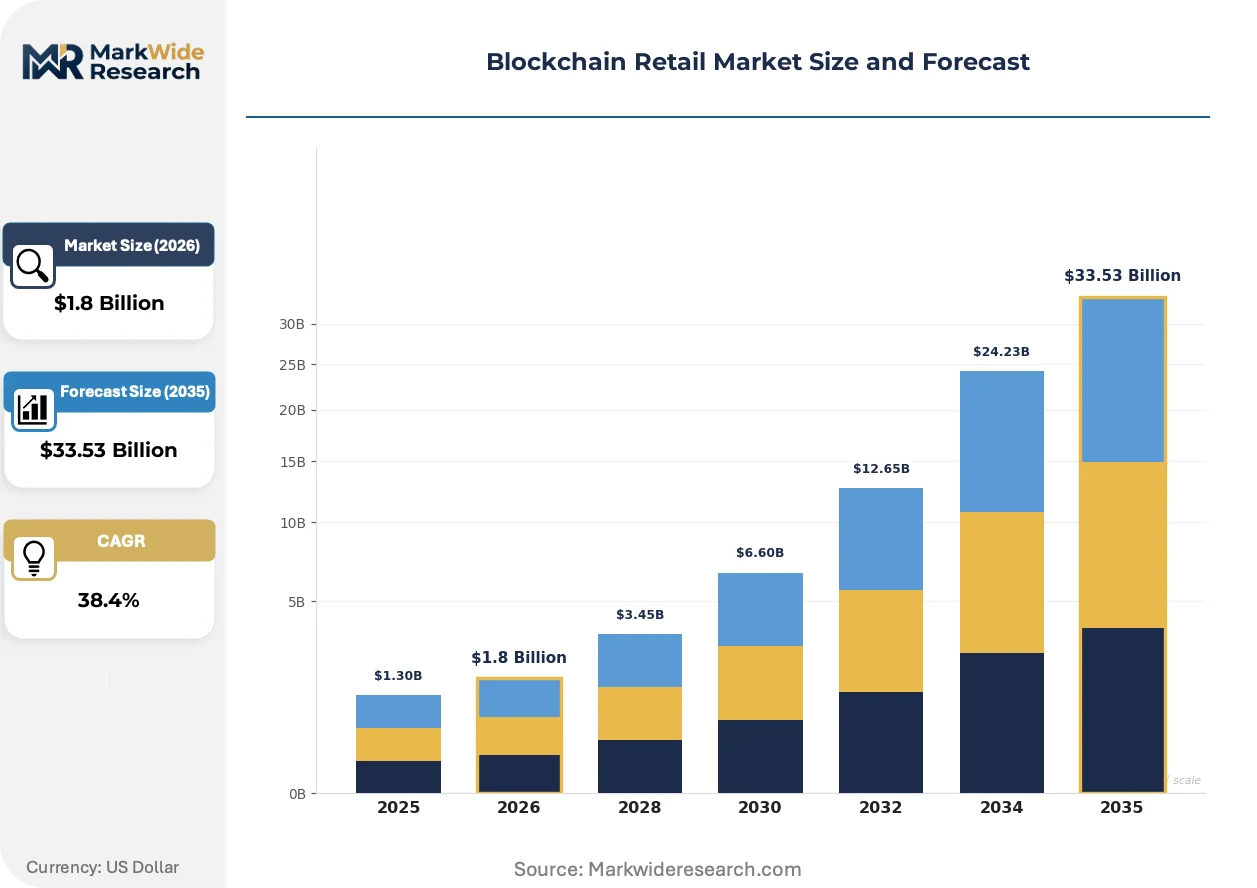
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $33.53 Billion |
| CAGR (2026 – 2036) | 38.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Payment Processing, Supply Chain Transparency, Loyalty Programs, Fraud Detection, Inventory Management Solution Type: Smart Contracts, Digital Wallets, Secure Transactions, Identity Management, Data Analytics Customer Type: Retail Chains, E-commerce Platforms, Specialty Stores, Convenience Outlets, Department Stores Deployment Model: Public Blockchain, Consortium Blockchain, Private Blockchain, Hybrid Blockchain |
| Companies Covered | IBM, Walmart, Binance, Tech Mahindra, Solulab, Peiko, SDLC Corp, RisingMax Inc, Queppelin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blockchain Retail Market Strategic Shifts & Innovations
Distributed ledger architectures are fragmenting across specialized use cases as retailers abandon one-size-fits-all platforms in favor of modular, purpose-built implementations. Three forces are reshaping competitive positioning.
Private permissioned networks are fragmenting the infrastructure layer as retailers reject public chain volatility. Grocery and pharmaceutical buyers are deploying Hyperledger Fabric and R3 Corda instances for supplier onboarding, with consensus limited to vetted counterparties. This fragmentation is compressing vendor margins by eliminating platform rent extraction from transaction fees.
REACH chemical traceability extensions and EU Green Deal carbon accounting rules are mandating immutable emissions documentation for imported goods. Textile and electronics retailers must now attach verified carbon footprints to product records, with German and French regulators auditing chain-of-custody claims. Apparel brands are responding by integrating satellite-verified deforestation monitoring into their ledger architectures.
Retailer procurement teams are demanding outcome-based verification services rather than software licenses. Third-party auditors are displacing in-house blockchain development, with grocers outsourcing farm-to-shelf attestation to specialized logistics technology providers. This shift is most visible in United States produce supply chains, where Walmart-scale buyers have established supplier-funded verification pools.
Blockchain Retail Market Segmentation
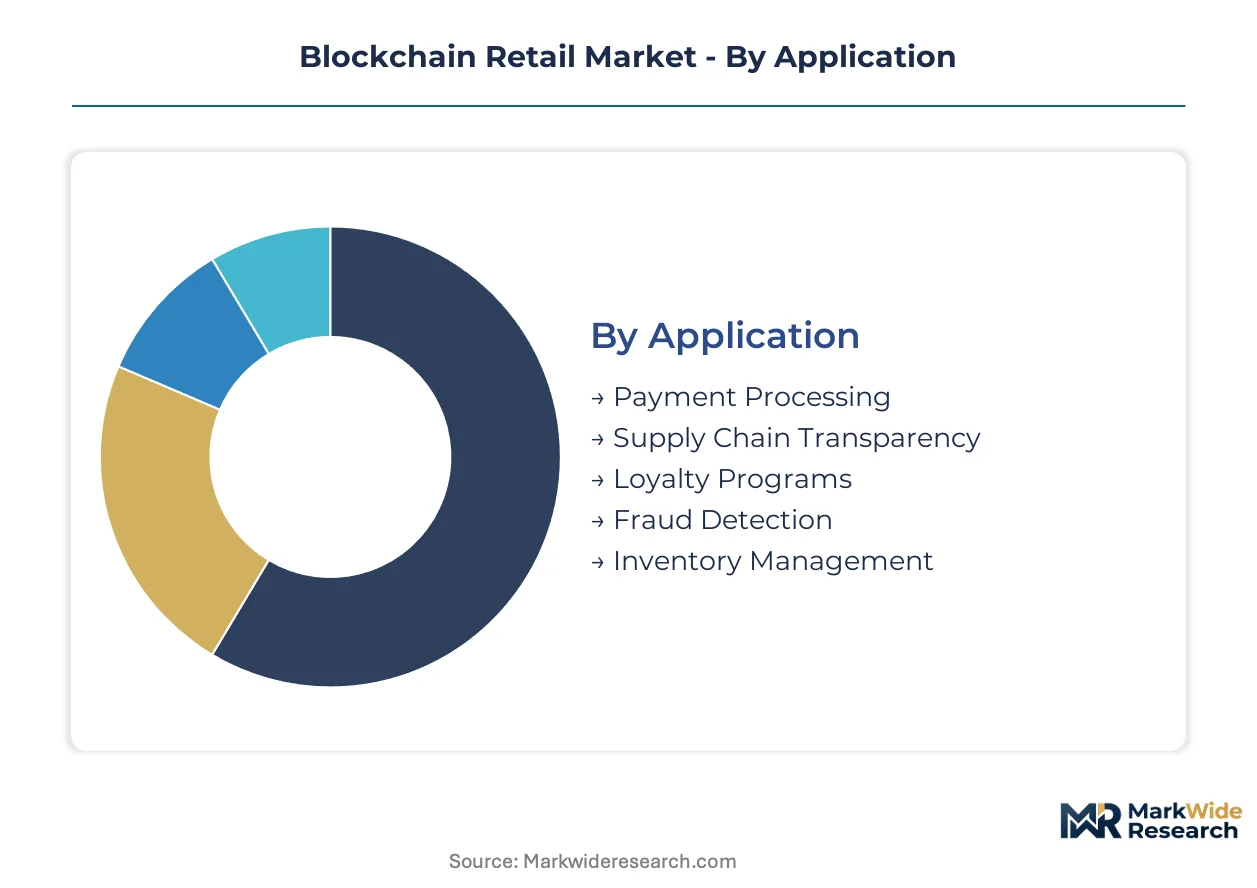
Blockchain retail deployments fragment across functional applications, technical architectures, and buyer categories with divergent compliance requirements. Each segmentation dimension reveals distinct substitution pressures and margin structures that shape vendor positioning and investment prioritization.
Application:
Supply Chain Transparency faces the most acute substitution threat from IoT-native traceability platforms that bypass distributed ledgers entirely.
- Supply Chain Transparency:Immutable provenance tracking from farm origin through retail shelf. Walmart and IBM anchor live implementations across United States grocery networks, driven by FDA Food Safety Modernization Act enforcement deadlines.
- Payment Processing:Cryptocurrency rails and stablecoin settlement layers for cross-border commerce. Demand concentrates in e-commerce corridors with high chargeback rates and correspondent banking friction.
- Loyalty Programs:Tokenized point systems enabling interoperability across partner networks.
- Fraud Detection:Consensus-verified transaction pattern analysis for chargeback prevention.
- Inventory Management:Real-time stock reconciliation across distributed retail locations.
Supply Chain Transparency retains volume leadership; Payment Processing holds the steepest expansion curve.
Solution Type:
Cost tier differentiation separates enterprise-grade certification from experimental deployments.
- Smart Contracts:Self-executing agreement automation with embedded compliance logic. ISO 27001-certified implementations command premium pricing from retail chains with cross-border data governance obligations.
- Digital Wallets:Custodial and non-custodial storage for cryptocurrency and tokenized assets. Expansion accelerates fastest among solution types as loyalty program digitization converts points liabilities into programmable instruments.
- Secure Transactions:Cryptographic verification for high-value retail purchases.
- Identity Management:Decentralized credential verification for customer onboarding.
- Data Analytics:On-chain pattern recognition for demand forecasting.
Smart Contracts capture the largest revenue pool; Digital Wallets gain share fastest.
Customer Type:
Volume concentration follows procurement sophistication and supplier network scale.
- Retail Chains:Multi-location operators with centralized IT governance and ERP backbone requirements. United States grocery and apparel chains drive enterprise platform consolidation around Hyperledger Fabric deployments.
- E-commerce Platforms:Digital-native retailers with API-first architecture and cross-border transaction volumes. Payment processing and fraud detection solutions concentrate here due to chargeback exposure and international settlement complexity.
- Specialty Stores:Niche retailers with curated supplier relationships.
- Convenience Outlets:High-velocity, low-margin operators with limited IT staff.
- Department Stores:Legacy operators with complex legacy system integration requirements.
Retail Chains dominate absolute deployment value; E-commerce Platforms show the most rapid adoption velocity.
Deployment Model:
Margin structures diverge sharply between permissioned control and public network access.
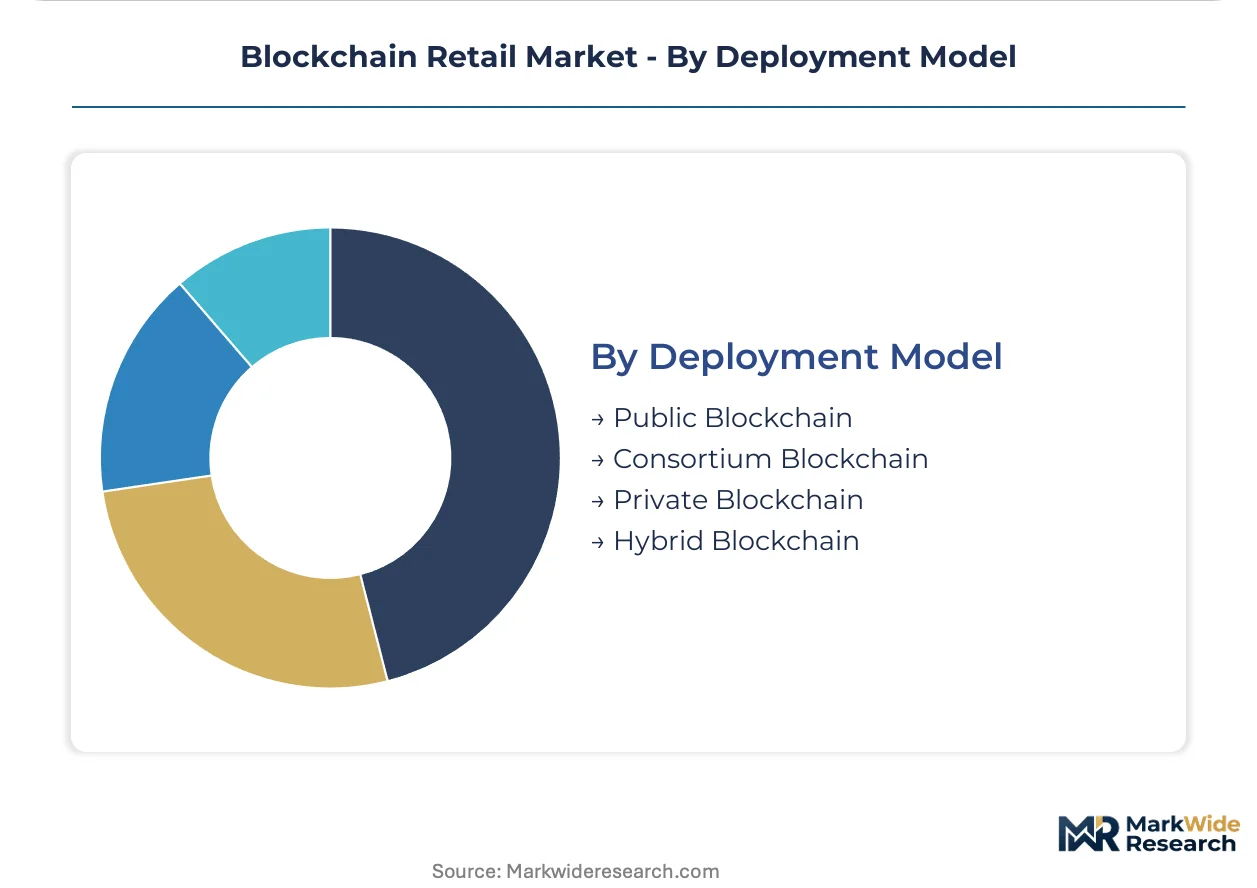
- Consortium Blockchain:Permissioned networks with vetted participant governance. Grocery and pharmaceutical buyers deploy Hyperledger Fabric and R3 Corda instances where FDA traceability mandates and GDPR data residency requirements intersect.
- Private Blockchain:Single-entity controlled ledgers for internal reconciliation. Retail chains with sensitive supplier pricing data favor this architecture to prevent information leakage to competitors.
- Public Blockchain:Open participation with native cryptocurrency settlement.
- Hybrid Blockchain:Segmented visibility with public anchoring and private transaction detail.
Consortium Blockchain holds the dominant installed base; Private Blockchain expands most quickly among risk-averse incumbents.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's blockchain-enabled cargo corridors anchor European supply chain digitization, while Singapore's TradeTrust infrastructure underwrites Asia-Pacific cross-border documentation flows. These physical-digital nodes concentrate deployment capital and regulatory experimentation.
United States
Walmart's live food traceability network and IBM's Hyperledger Fabric deployments drive enterprise adoption. FDA Food Safety Modernization Act enforcement deadlines force grocery chains to replace paper-based provenance systems. Chicago and Bentonville anchor supplier onboarding velocity for retail-scale implementations.
Germany
REACH chemical traceability extensions and EU Green Deal carbon accounting rules mandate immutable emissions documentation for imported textiles and electronics. ECHA compliance audits pressure retailers to attach verified carbon footprints to product records. The Rhine-Ruhr industrial corridor hosts apparel brands integrating satellite-verified deforestation monitoring into ledger architectures.
India
BIS standards for supply chain traceability and DGFT export documentation requirements create first-mover advantages for platforms integrating with government digital infrastructure. Mumbai and Bangalore concentrate systems integration capacity across APAC retail corridors. Tech Mahindra leverages this positioning for enterprise client acquisition.
United Kingdom
FCA stablecoin guidance and BoE retail central bank digital currency exploration accelerate payment processing experimentation. London's fintech cluster drives digital wallet and tokenized loyalty program development. The city's regulatory sandbox environment permits live testing of cryptocurrency settlement rails for e-commerce corridors.
France
CNIL GDPR enforcement and EU AI Act algorithmic transparency requirements push retailers toward permissioned ledger architectures that embed compliance by design. Paris anchors luxury brand experimentation with NFC-anchored digital product passports for second-hand authentication. LVMH-scale buyers are establishing supplier-funded verification pools for circular fashion markets.
Blockchain Retail Market Key Industry Players
Listed leaders compete with private specialists across certification tiers, splitting the vendor base into ISO 27001-certified enterprise platforms and experimental deployments. Consolidation pressures concentrate around Hyperledger Fabric and R3 Corda implementations where FDA traceability mandates intersect with GDPR data residency requirements. Three archetypes dominate: technology conglomerates with systems integration depth, retail chains with captive supplier networks, and blockchain-native specialists with smart contract expertise. Competitive moves center on consortium governance capture and outcome-based verification service outsourcing.
Within the enterprise platform tier, IBM and Tech Mahindra exemplify divergent geographic positioning strategies. IBM leverages its Armonk, New York base to anchor North American grocery network deployments. Tech Mahindra occupies a position emphasizing APAC corridor penetration through Mumbai-headquartered systems integration. Walmart, though operationally a retail chain, sits within the competitive landscape as a demand-side anchor whose supplier onboarding protocols shape vendor selection criteria across the United States market.
| Leading Market Players |
|---|
| IBM |
| Walmart |
| Binance |
| Tech Mahindra |
| Solulab |
| Peiko |
| SDLC Corp |
| RisingMax Inc |
| Queppelin |
| Others |
Cost & Logistics Intelligence
Permissioned ledger architectures replacing public blockchain deployments are redrawing vendor economics and procurement geography simultaneously. Hyperledger Fabric and R3 Corda certifications now command premium positioning as retailers abandon volatile public networks, compressing margins for uncertified providers while concentrating supply around IBM and Tech Mahindra integration hubs.
Pricing Analysis
Certification level creates the primary spread between enterprise-grade and experimental tiers. Three-tier pricing structure across ISO 27001-certified premium, standard compliance, and uncertified economy levels dominates vendor contracts. Cost compression in the economy tier is intensifying because mid-market chains lack procurement leverage for supplier-funded verification pools. E-commerce platforms exhibit highest price sensitivity due to thin margins, while grocery chains with FDA mandates show lowest sensitivity to certification premiums.
Supply Chain Analysis
Port congestion at Rotterdam and Singapore is elevating inbound logistics costs for hardware-dependent edge computing deployments. Software supply chains draw from the United States, India, and Germany for systems integration and compliance architecture. Semiconductor components for IoT sensor anchoring, cryptographic modules, and edge processing units rest on Taiwan and South Korea fabrication. Single-source vulnerability in Hyperledger Fabric enterprise licensing creates concentration risk. Distribution runs through systems integrators with retail vertical expertise rather than direct platform licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from IoT-native traceability platforms that bypass distributed ledgers entirely for supply chain use cases. Defense requires demonstrating irreplaceable compliance automation value.
For Market Incumbents: Shield market position by deepening ISO 27001 certification moats before EU AI Act enforcement deadlines tighten. Prioritize backward integration into smart contract audit capabilities to capture supplier onboarding revenue pools. Counter IoT-native traceability substitutes by embedding FDA and GDPR compliance automation as non-replicable platform features. For New Entrants and Emerging Players: Anchor in India's BIS-compliant retail corridor digitization, where DGFT export documentation requirements create first-mover whitespace with limited incumbent presence. Target second-hand luxury authentication applications in France and United Kingdom markets, where NFC-anchored digital product passports remain underpenetrated. Pursue outcome-based verification service contracts rather than software licensing to bypass capital-intensive platform development. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors systems integration specialists with regulatory compliance depth. Long-term viability hinges on capturing consortium governance roles in grocery and pharmaceutical networks. Monitor FDA Food Safety Modernization Act enforcement velocity as the critical inflection signal for enterprise platform demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 27001 Certification Acceleration | Enterprise retailers require certified platforms to satisfy cross-border GDPR data governance mandates. |
| Smart Contract Audit Capability Buildout | Specialized talent scarcity in distributed systems architecture extends deployment timelines and inflates implementation costs. |
| Consortium Governance Capture | Walmart-scale buyers establish supplier-funded verification pools that shape vendor selection criteria. |
| IoT-Edge Convergence Investment | Real-time cold chain monitoring with local consensus validation enables automated quality enforcement. |
| Outcome-Based Service Transition | Third-party auditors displace in-house blockchain development in United States produce supply chains. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC filings, FDA enforcement documentation, EU regulatory registers, and customs trade data. Interviews with retail chain CTOs, grocery procurement directors, systems integration specialists, and regulatory compliance officers informed demand-side validation. Hyperledger Fabric deployment disclosures and R3 Corda consortium membership records supplied infrastructure-side triangulation. Bottom-up project pipeline analysis and top-down market sizing converged on segment-level estimates.
Segmentation dimensions modeled span application type, solution architecture, customer procurement sophistication, and deployment governance model across the projection horizon. Smart contract automation intensity, digital wallet adoption velocity, and consortium network participation rates served as industry-specific forecast inputs. CAGRs were derived from weighted scenario analysis of regulatory enforcement timelines and supplier onboarding capacity constraints.
Material uncertainties — regulatory divergence between FDA record retention and GDPR data minimization mandates, consortium governance fragmentation, and public blockchain volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions about enforcement consistency and technology standardization velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Blockchain in Smart Home Market
Blockchain Technology
Automotive Blockchain Market
Blockchain Technology
Global Blockchain in Telecom Market
Blockchain Technology
Bitcoin Project Incubator Service Market
Blockchain Technology
Europe Blockchain Market
Blockchain Technology
Enterprise-Grade DLT Market
Blockchain Technology
Blockchain Technology Market
Blockchain Technology
Blockchain Messaging Apps Market
Blockchain Technology
Blockchain-As-A-Service (Baas) Market
Blockchain Technology
Aviation Record-Keeping Blockchain Market
Blockchain Technology
Pharmaceutical Blockchain Market
Blockchain Technology
Marine Blockchain Market
Blockchain Technology
Global Blockchain Market
Blockchain Technology
Blockchain AI Market
Blockchain Technology
Blockchain Game Market
Blockchain Technology
Global Blockchain in Energy Market