
 Blockchain Gaming Market | 2026-2036
Blockchain Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
Blockchain Gaming Market Analytics
ISO 27001 certification for blockchain gaming infrastructure is bifurcating the competitive landscape into audit-ready platforms and unverified entrants. Animoca Brands leverages its portfolio density across licensed IP titles to sustain developer loyalty across Asia-Pacific. Sky Mavis anchors the Ronin sidechain ecosystem with captive transaction throughput for Axie Infinity. Dapper Labs differentiates through Flow blockchain custody architecture that controls NBA Top Shot and NFL All Day marketplaces.
Blockchain gaming denotes interactive entertainment software where cryptographic asset ownership, provable scarcity, and peer-to-peer settlement execute on distributed ledgers rather than centralized databases. Smart contracts automate reward distribution and item provenance verification without intermediary escrow. RPG titles now capture the deepest player retention cycles as character progression ties directly to tradable NFT inventories. Mobile platforms compete for the largest addressable audience, though PC environments retain the highest per-user transaction values through complex DeFi-integrated economies. Play-to-earn monetization has matured into guild-scholarship models where asset owners delegate NFTs to active players for revenue splits.
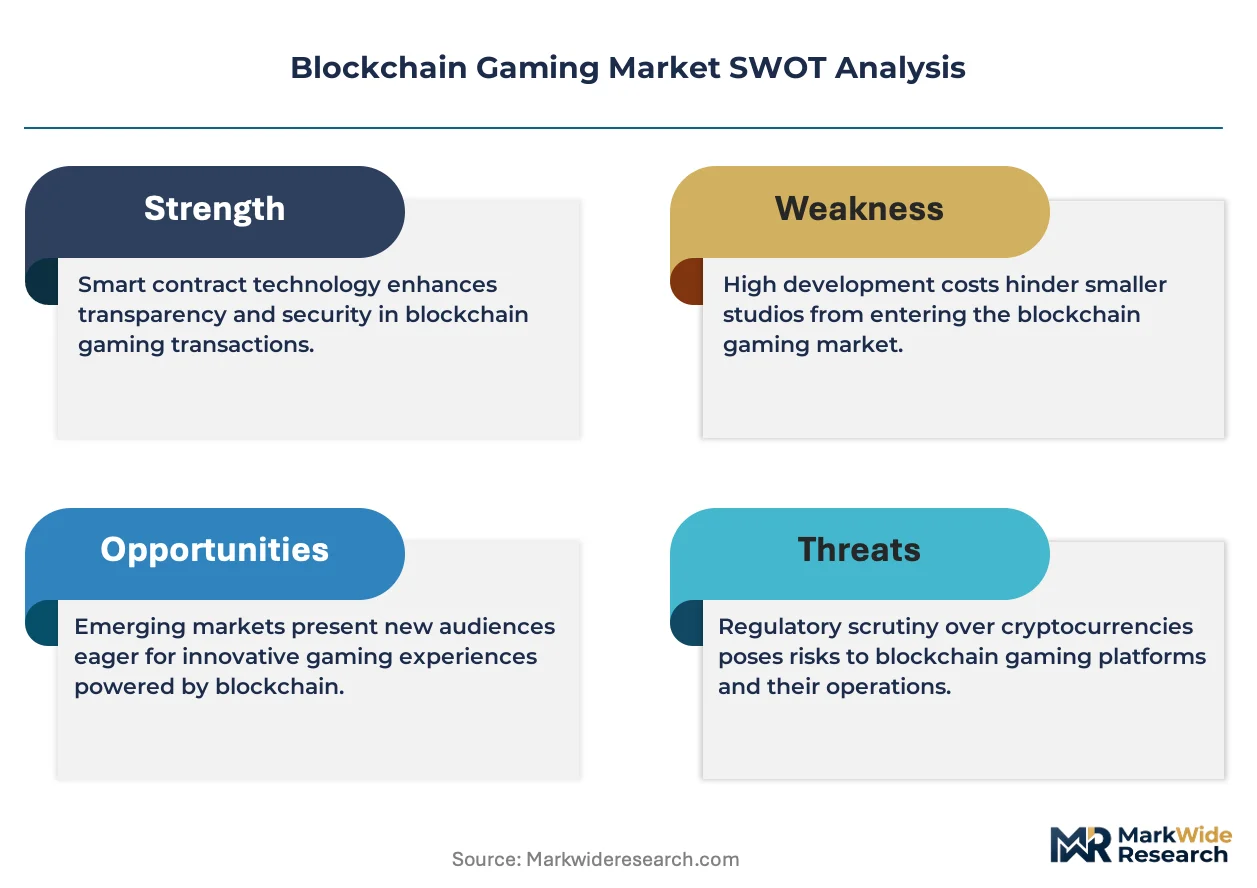
The SEC in the United States scrutinizes token distributions as unregistered securities offerings, forcing studios to restructure reward mechanisms or exclude American participants. MiCA implementation across European Union member states mandates custodial wallet licensing and stablecoin reserve disclosures for any in-game currency with fiat redemption pathways. Developers must now monitor how national financial regulators classify virtual item marketplaces ahead of enforcement waves that could sever payment rails.
Market Dynamics
Layer-2 scaling infrastructure is decomposing the transaction cost barrier that previously confined blockchain gaming to speculative asset trading, enabling persistent gameplay loops comparable to traditional RPG economies.
Growth Catalysts
- MiCA Framework Implementation:The EU's Markets in Crypto-Assets regulation mandates custodial licensing and reserve disclosures, creating compliance clarity that attracts institutional capital into European gaming studios.
- Guild-Sponsorship Models:Asset delegation systems in the Philippines and Vietnam allow NFT owners to rent inventory to active players, expanding addressable user bases beyond crypto-native holders.
- Zero-Knowledge Rollups:zkSync and Polygon zkEVM compress proof verification costs below one cent per transaction, making micro-reward distribution economically viable for mobile-first titles.
Market Restraints
- SEC Securities Scrutiny:The US regulator's enforcement posture against unregistered token distributions forces studios to exclude American participants or restructure reward mechanisms entirely.
- Wallet Onboarding Friction:Self-custody key management creates abandonment rates exceeding seventy percent among first-time players entering mobile blockchain titles.
- Ethereum Base Layer Congestion:Gas price spikes during NFT mint events render mainnet settlement uneconomical for sub-fifty-dollar in-game transactions.
Strategic Opportunities
- India's PLI Scheme Extension:Production-linked incentives for semiconductor and cloud infrastructure reduce datacenter costs for regional gaming servers targeting South Asian markets.
- AI-Generated Asset Pipelines:Procedural NFT generation converges with large language models to produce infinite quest variations without manual artist labor.
- Telegram Mini-Apps Distribution:The messaging platform's embedded wallet and nine-hundred-million user base offers frictionless acquisition channels absent from traditional app stores.
Industry Challenges
- Smart Contract Auditing Bottlenecks:ISO 27001 certification and formal verification processes extend development timelines by four to eight months for security-critical titles.
- Cross-Chain Liquidity Fragmentation:Player assets locked on Ronin cannot migrate to Arbitrum without bridge smart contract risk, diluting network effects across competing layer-2 ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blockchain Gaming Market |
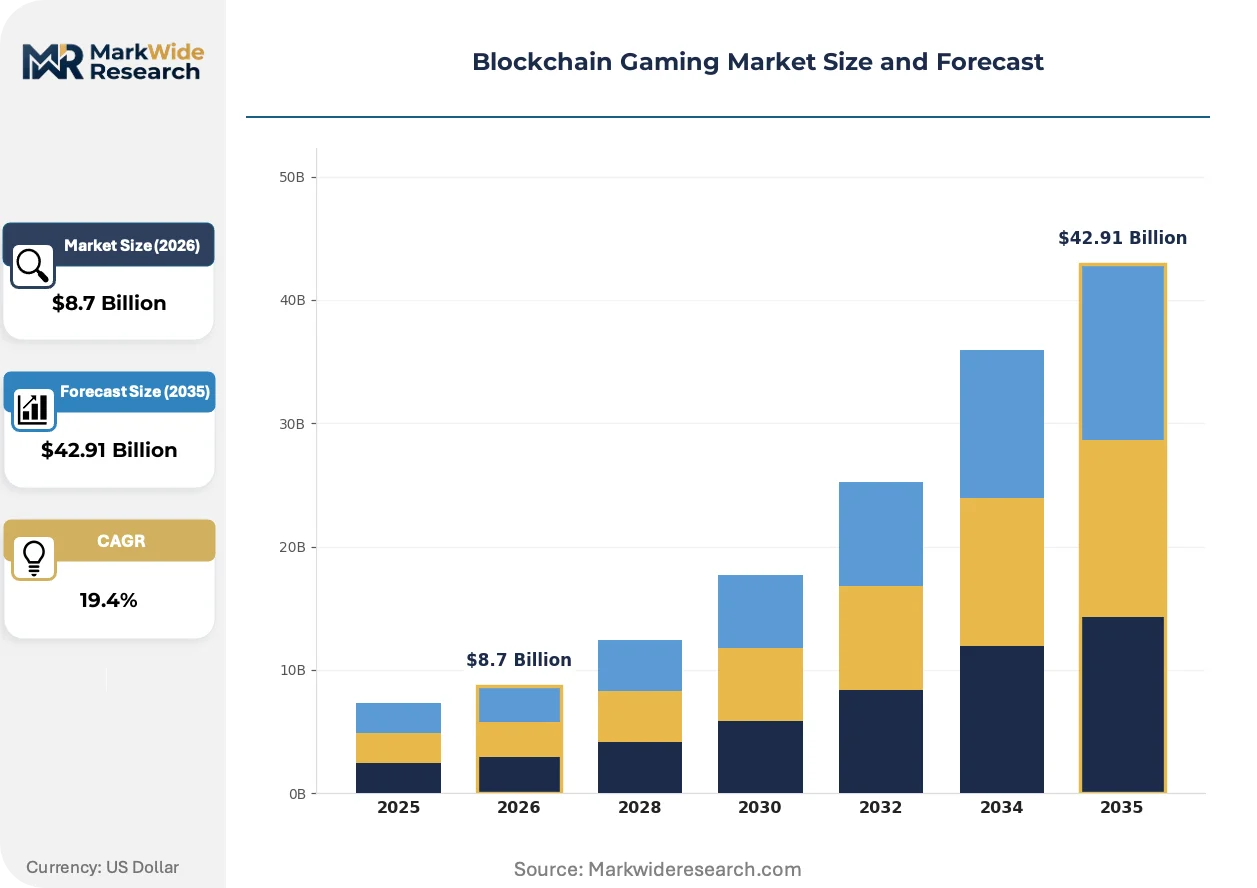
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Action, Strategy, RPG, Card Games Platform: PC, Mobile, Console, Web Monetization Model: Play-to-Earn, Free-to-Play, Subscription, NFT Sales End User: Casual Gamers, Professional Gamers, Investors, Developers |
| Companies Covered | Animoca Brands, Sky Mavis, Dapper Labs, Immutable, Mythical Games, Horizon Blockchain Games, Double Jump.Tokyo, Wemade, Illuvium, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blockchain Gaming Market Evolving Landscape
Modular blockchain architecture is fragmenting the monolithic stack that once forced gaming studios to accept Ethereum's throughput constraints as immutable design parameters.
Account abstraction via ERC-4337 is decomposing the private-key custody model that previously gated mainstream adoption. Mobile RPG studios in Vietnam deploy social recovery wallets and gasless transaction relays, compressing onboarding friction to email-password equivalence. This infrastructure shift enables session-based gameplay where players interact with blockchain backends without conscious wallet management.
Japan's Payment Services Act amendments classify certain in-game tokens as prepaid payment instruments, mandating registration with the Financial Services Agency. Domestic studios now segregate reward currencies from governance tokens to avoid dual classification. The regulatory clarity attracts Korean and Singaporean publishers seeking compliant Asia-Pacific expansion pathways.
Scholarship program managers now bundle asset delegation with performance analytics and automated revenue splits, transforming guild operations from informal Telegram coordination into structured fund-like entities. This professionalization concentrates in the Philippines where Axie Infinity veterans operate multi-thousand-account portfolios. The model displaces direct-to-consumer acquisition for capital-intensive titles requiring substantial NFT inventory deployment.
Blockchain Gaming Market Segmentation
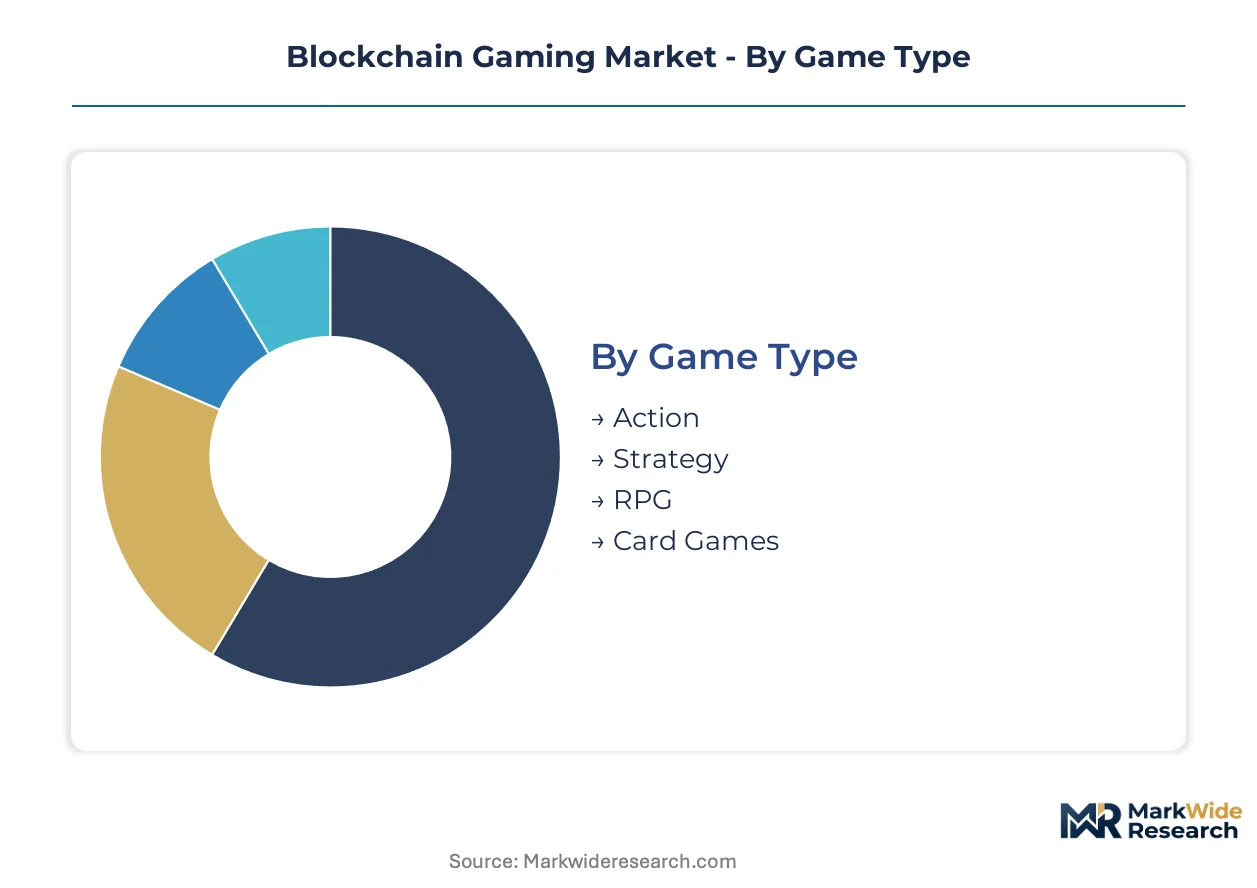
Segmentation in blockchain gaming reveals how value capture concentrates across gameplay mechanics, infrastructure layers, and participant archetypes. Distinct margin profiles emerge between asset-heavy RPG economies and lightweight mobile card games, while platform choice dictates transaction cost exposure and wallet onboarding complexity.
Game Type:
Margin pools concentrate deepest where character progression ties directly to tradable NFT inventories and persistent virtual economies.
- RPG:Open-world character advancement systems embed equipment, land, and cosmetic assets as transferable tokens on layer-2 networks. Guild-scholarship models in the Philippines and Vietnam exploit this inventory depth to scale player bases without direct asset purchase requirements.
- Strategy:Base-building and resource management mechanics generate recurring transaction volume through territorial control and alliance warfare. Demand clusters in South Korea where esports infrastructure supports competitive clan tournaments with tokenized prize pools.
- Action:Real-time combat loops with shorter session durations limit asset attachment depth. These titles prioritize cosmetic NFT drops over functional equipment economies.
- Card Games:Deck construction around provably scarce digital collectibles leverages existing trading card familiarity. Secondary market royalties sustain developer revenue without ongoing content production.
RPG holds installed capacity. Strategy is rotating up the share rankings.
Platform:
Volume concentration follows hardware accessibility curves, with mobile penetration in Southeast Asia contrasting PC transaction value density in North American and European markets.
- Mobile:Smartphone-native distribution captures the largest addressable audience across India, Indonesia, and Nigeria. Embedded wallet solutions and Telegram Mini-Apps distribution reduce onboarding abandonment below self-custody benchmarks.
- PC:Desktop environments sustain the highest per-user transaction values through complex DeFi-integrated economies and multi-window trading interfaces. Complex strategy and RPG titles anchor this segment.
- Web:Browser-based accessibility eliminates download friction for casual experimentation. These implementations sacrifice performance depth for immediate wallet connection.
- Console:Sony and Microsoft platform policies restrict native blockchain integration, limiting this channel to companion apps and external marketplace bridges rather than core gameplay.
Mobile commands player count leadership. PC is climbing the fastest on revenue per user metrics.
Monetization Model:
Revenue stability diverges between upfront NFT sales with secondary royalty streams and recurring subscription frameworks that dampen token price volatility exposure.
- NFT Sales:Primary mint events and peer-to-peer marketplace fees generate concentrated revenue spikes aligned with content drops. Creator royalties embedded in smart contracts sustain long-tail income without active service maintenance.
- Play-to-Earn:Token reward distributions require continuous emission schedule management to prevent inflationary collapse. Guild delegation systems in Vietnam professionalize this model through performance-analytics dashboards.
- Subscription:Recurring fiat or stablecoin payments insulate developers from native token price swings. This model appeals to risk-averse publishers entering from traditional gaming.
- Free-to-Play:Optional cosmetic purchases and battle pass structures lower entry barriers while preserving whale monetization. Blockchain integration typically limits to verified ownership rather than full asset trading.
NFT Sales holds installed capacity. Subscription is rotating up the share rankings.
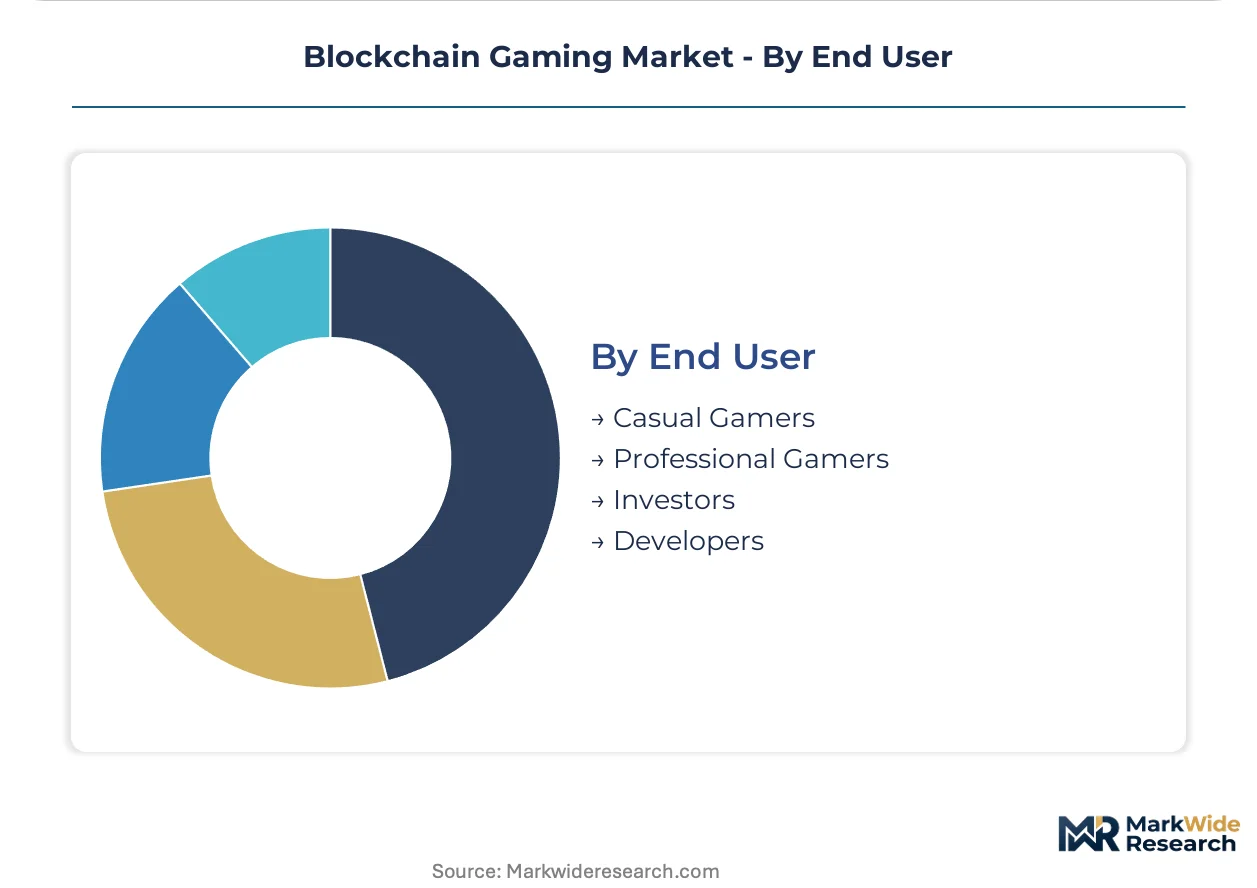
End User:
Customer lifetime value spreads widest between speculative asset holders seeking portfolio diversification and engaged players prioritizing gameplay depth over financial return.
- Investors:Capital deployment focuses on genesis NFT collections and governance token accumulation. This cohort drives floor price volatility and liquidity depth on secondary marketplaces.
- Professional Gamers:Skill-based income optimization through tournament prizes and scholarship revenue splits concentrates in Philippine guild operations with multi-thousand-account portfolios.
- Casual Gamers:Session-based entertainment seekers prioritize low-friction onboarding and minimal wallet management. Account abstraction via ERC-4337 social recovery targets this segment.
- Developers:Infrastructure and tooling purchasers include indie studios licensing middleware for blockchain backend integration rather than native smart contract development.
Investors holds installed capacity. Professional Gamers is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme extension for cloud infrastructure is reducing datacenter costs for regional gaming servers targeting South Asian markets. This incentive architecture is reshaping where blockchain gaming studios deploy backend operations.
Philippines
Play-to-earn guilds operate at scale across Metro Manila and Cebu, with professional gamers driving adoption through scholarship revenue splits. The central bank monitors virtual currency flows for anti-money laundering compliance. Yield Guild Games and similar operators concentrate multi-thousand-account portfolios in the capital region.
Vietnam
Mobile RPG studios deploy account abstraction via ERC-4337 to compress onboarding friction for casual gamers. The government classifies certain crypto assets under existing payment regulations requiring licensing. Ho Chi Minh City anchors the largest concentration of blockchain game developers in Southeast Asia.
United States
The SEC scrutinizes token distributions as unregistered securities offerings, forcing studios to restructure reward mechanisms or exclude American participants. This enforcement posture creates regulatory friction for domestic publishers. San Francisco and Austin retain venture capital concentration despite operational constraints.
Japan
Payment Services Act amendments classify certain in-game tokens as prepaid payment instruments, mandating registration with the Financial Services Agency. Domestic studios segregate reward currencies from governance tokens to avoid dual classification. Tokyo attracts Korean and Singaporean publishers seeking compliant Asia-Pacific expansion pathways.
Germany
MiCA framework implementation mandates custodial wallet licensing and stablecoin reserve disclosures for in-game currencies with fiat redemption pathways. BaFin oversight creates compliance clarity that attracts institutional capital. Berlin's startup ecosystem hosts several audit-ready platform developers.
Blockchain Gaming Market Competitive Landscape
Player mix skews toward vertically integrated platform operators with captive blockchain infrastructure. The competitive landscape bifurcates between audit-ready platforms holding ISO 27001 certification and unverified entrants facing smart contract auditing bottlenecks. Strategic archetypes include layer-2 ecosystem anchors, licensed IP portfolio aggregators, and middleware infrastructure providers. Dominant competitive moves encompass strategic partnerships with telecom distributors and geographic expansion through guild-sponsorship models in Southeast Asia.
Within the licensed IP tier, Animoca Brands and Dapper Labs exemplify portfolio-density strategies that sustain developer loyalty across Asia-Pacific markets. Sky Mavis occupies a position as a layer-2 ecosystem anchor, anchoring transaction throughput through captive sidechain infrastructure. These three entities represent distinct archetypes: the Hong Kong-based portfolio aggregator, the Canadian custody-architecture specialist, and the Vietnamese layer-2 operator.
| Leading Market Players |
|---|
| Animoca Brands |
| Sky Mavis |
| Dapper Labs |
| Immutable |
| Mythical Games |
| Horizon Blockchain Games |
| Double Jump.Tokyo |
| Wemade |
| Illuvium |
| Others |
Value Network & Pricing Analysis
ISO 27001 certification gates both platform qualification and price differentiation in blockchain gaming infrastructure, bifurcating the competitive landscape into audit-ready operators commanding premium licensing fees and unverified entrants competing on raw transaction costs. This regulatory filter simultaneously constrains supply-side capacity and creates tiered pricing power for compliant middleware providers.
Pricing Analysis
Certification level creates the primary spread between audit-ready platform providers and unverified infrastructure operators. Pricing stratifies across ISO 27001-certified middleware, formally verified smart contract tooling, and unaudited open-source alternatives. Cost compression in the unverified tier is intensifying because guild-sponsorship models in the Philippines and Vietnam prioritize transaction cost minimization over security guarantees. Casual gamers and scholarship program managers exhibit highest price sensitivity, while institutional publishers deploying licensed IP titles demonstrate lowest sensitivity to infrastructure premiums.
Supply Chain Analysis
Strategic stockpiling of NFT inventory and layer-2 compute capacity dominates over just-in-time provisioning in guild-scholarship operations. Supply concentrates in Vietnam, the Philippines, and South Korea for mobile RPG development and guild operations. Raw material dependencies encompass Ethereum layer-2 blockspace, zk-rollup proof verification services, and AI-generated asset pipelines. Single-source vulnerability pervades the Ronin sidechain ecosystem where Axie Infinity transaction throughput remains captive to Sky Mavis infrastructure. Distribution runs through Telegram Mini-Apps, embedded wallet SDKs, and direct guild delegation networks rather than traditional app store channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around guild-sponsorship operators in Southeast Asia, with multi-thousand-account portfolios displacing direct-to-consumer acquisition for capital-intensive titles.
For Market Incumbents: Fortify layer-2 ecosystem lock-in through captive transaction throughput and exclusive IP licensing arrangements. Animoca Brands' portfolio density strategy demonstrates how licensed title concentration sustains developer loyalty against emerging middleware competitors. Vertical integration into zk-rollup infrastructure reduces exposure to Polygon and zkSync pricing volatility. For New Entrants and Emerging Players: Anchor in India's PLI-subsidized cloud infrastructure for cost-advantaged backend operations serving South Asian markets. Account abstraction tooling for casual gamers represents the most penetrable white-space segment, with ERC-4337 social recovery wallets compressing onboarding abandonment below self-custody benchmarks. Partner with Vietnamese mobile RPG studios for embedded wallet distribution. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across zero-knowledge proof verification infrastructure and AI-generated asset pipelines. Long-term viability favors platforms with audit-ready certification and guild-sponsorship distribution networks already at scale. Monitor MiCA implementation velocity across European Union member states as the signal for institutional capital allocation into compliant gaming studios.| Strategic Initiative | Industry Significance |
|---|---|
| Layer-2 Ecosystem Expansion | Polygon zkEVM and zkSync adoption reduce transaction costs below one cent for mobile-first titles. |
| Guild-Sponsorship Scaling | Yield Guild Games and Philippine operators professionalize asset delegation into structured fund-like entities. |
| Account Abstraction Deployment | ERC-4337 social recovery wallets compress onboarding friction to email-password equivalence for casual gamers. |
| MiCA Compliance Certification | BaFin oversight in Germany attracts institutional capital through custodial licensing clarity. |
| Telegram Mini-Apps Distribution | Nine-hundred-million user base offers frictionless acquisition absent from Apple and Google platform restrictions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC enforcement filings, MiCA regulatory texts, and layer-2 protocol documentation. Primary interviews encompassed blockchain gaming studio executives, guild-sponsorship program managers, smart contract auditors, and layer-2 infrastructure engineers. Secondary validation drew from BaFin licensing databases, Financial Services Agency registration records, and venture capital transaction disclosures. Bottom-up project economics triangulated against top-down market sizing across the analysis window.
Segmentation dimensions modeled encompass game type, platform, monetization model, and end user archetype alongside regional regulatory framework clusters. CAGRs derived from volume-weighted average of transaction throughput growth, guild account expansion rates, and NFT marketplace velocity. Forecast inputs included zk-rollup cost compression curves and MiCA implementation timelines across European member states.
Material uncertainties — SEC securities classification shifts, layer-2 bridge security incidents, and national payment instrument reclassifications — sit outside the modeled envelope. Forecasts reflect assumptions regarding stablecoin reserve disclosure compliance and guild-sponsorship regulatory tolerance. Practitioners should keep alternative scenarios live as MiCA enforcement patterns and zero-knowledge proof adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Industrial Blockchain Technology Market
Blockchain Technology
Blockchain in Manufacturing Market
Blockchain Technology
Pharmaceutical Blockchain Market
Blockchain Technology
Blockchain in Pharmaceutics Market
Blockchain Technology
Aviation Transaction Blockchain Market
Blockchain Technology
Blockchain Retail Market
Blockchain Technology
Blockchain Technology Market
Blockchain Technology
Europe Blockchain Market
Blockchain Technology
Global Blockchain in Healthcare Market
Blockchain Technology
Bitcoin Project Incubator Service Market
Blockchain Technology
Global Blockchain in Energy Market
Blockchain Technology
Blockchain Game Market
Blockchain Technology
Global Blockchain Government Market
Blockchain Technology
Bitcoin Technology Market
Blockchain Technology
Global Blockchain Software Market
Blockchain Technology
Automotive Blockchain Market